
 HCV Axles Market | 2026-2036
HCV Axles Market Size, Share, and Industry Trends Forecast 2026-2036
HCV Axles Market Outlook
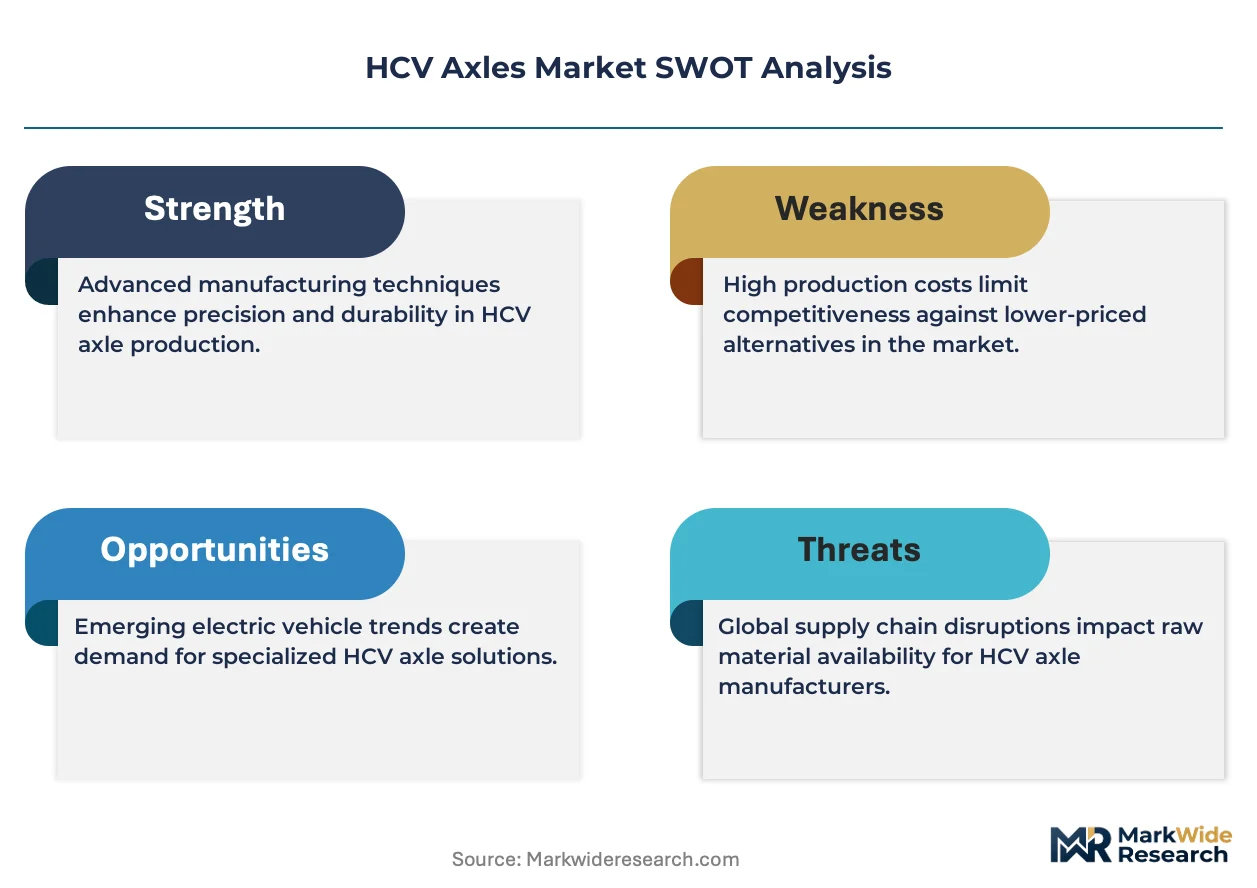
The premium-commodity split in HCV axles is consolidating around load-rating certification and integrated braking architecture. Dana Ltd. leverages in-house forging capacity to anchor its position in North American heavy-freight specifications. Meritor Inc. competes through electronic axle integration programs that merge drivetrain and chassis control. HANDE Axle dominates volume production for China's domestic truck OEMs with cost-optimized tandem configurations.
HCV axles are load-bearing assemblies that transmit torque from the drivetrain to wheels while supporting gross vehicle weights exceeding 16 tonnes, typically manufactured through closed-die forging of alloy steel billets followed by induction hardening of bearing journals. Tandem axle configurations lead unit shipments across long-haul freight applications where weight distribution regulations mandate multi-axle layouts. Aluminum material adoption accelerates in European urban delivery fleets where payload optimization offsets acquisition premiums. Electronic technology segments capture expanding margin pools as axle-integrated torque vectoring and predictive maintenance modules penetrate premium OEM specifications.
EPA Phase 3 greenhouse gas standards and Euro VII emission frameworks are tightening axle efficiency benchmarks, compelling manufacturers to redesign bearing seals and lubrication systems for reduced friction losses. China's MIIT enforces GB-standard axle load limits that directly shape domestic product certification requirements. India's BIS mandates axle testing protocols under automotive component safety regulations that govern market entry for imported assemblies. Stakeholders must monitor divergence between regional brake integration standards and electrification-ready axle architectures as fleet operators evaluate total cost of ownership across powertrain configurations.
Market Dynamics
Electrification mandates across freight logistics are forcing axle manufacturers to redesign load-bearing architectures for battery-electric and hydrogen fuel-cell powertrains, compressing traditional drivetrain integration timelines.
Growth Catalysts
- EPA Phase 3 greenhouse gas standards:US freight operators face tightened axle efficiency benchmarks, accelerating fleet renewal programs for compliant heavy-duty configurations.
- Aluminum forging adoption:European urban delivery fleets prioritize payload optimization, driving material substitution in axle housings for last-mile distribution vehicles.
- China's MIIT electrification mandates:State-backed procurement directives reshape heavy-duty component certification, concentrating demand for electrification-ready tandem assemblies.
Market Restraints
- Alloy steel billet cost volatility:Closed-die forging feedstock prices fluctuate with scrap metal and energy markets, compressing margin stability for volume producers.
- Bearing seal supply concentration:Precision seal manufacturing clusters in Germany and Japan, creating single-source vulnerability for friction-reduction components.
- Euro VII brake integration complexity:The framework mandates electronic axle-chassis coordination that legacy mechanical architectures cannot satisfy without redesign.
Strategic Opportunities
- India's BIS certification gap:Domestic testing protocol capacity lags import demand, opening white space for localized axle assembly facilities serving regional OEMs.
- Predictive maintenance module convergence:Sensor-embedded axle units combining torque monitoring with brake wear analytics command premium positioning in North American long-haul specifications.
- Brazil's ANVISA commercial vehicle safety push:Incoming axle load and braking performance standards create first-mover advantage for certified suppliers in Mercosur freight corridors.
Industry Challenges
- Induction hardening technician scarcity:Precision heat-treatment expertise for bearing journal durability remains concentrated among aging workforce cohorts in mature manufacturing regions.
- Dual-carbon axle architecture capex:Simultaneous development of internal-combustion and electrified load-bearing platforms strains R&D allocation across product generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HCV Axles Market |
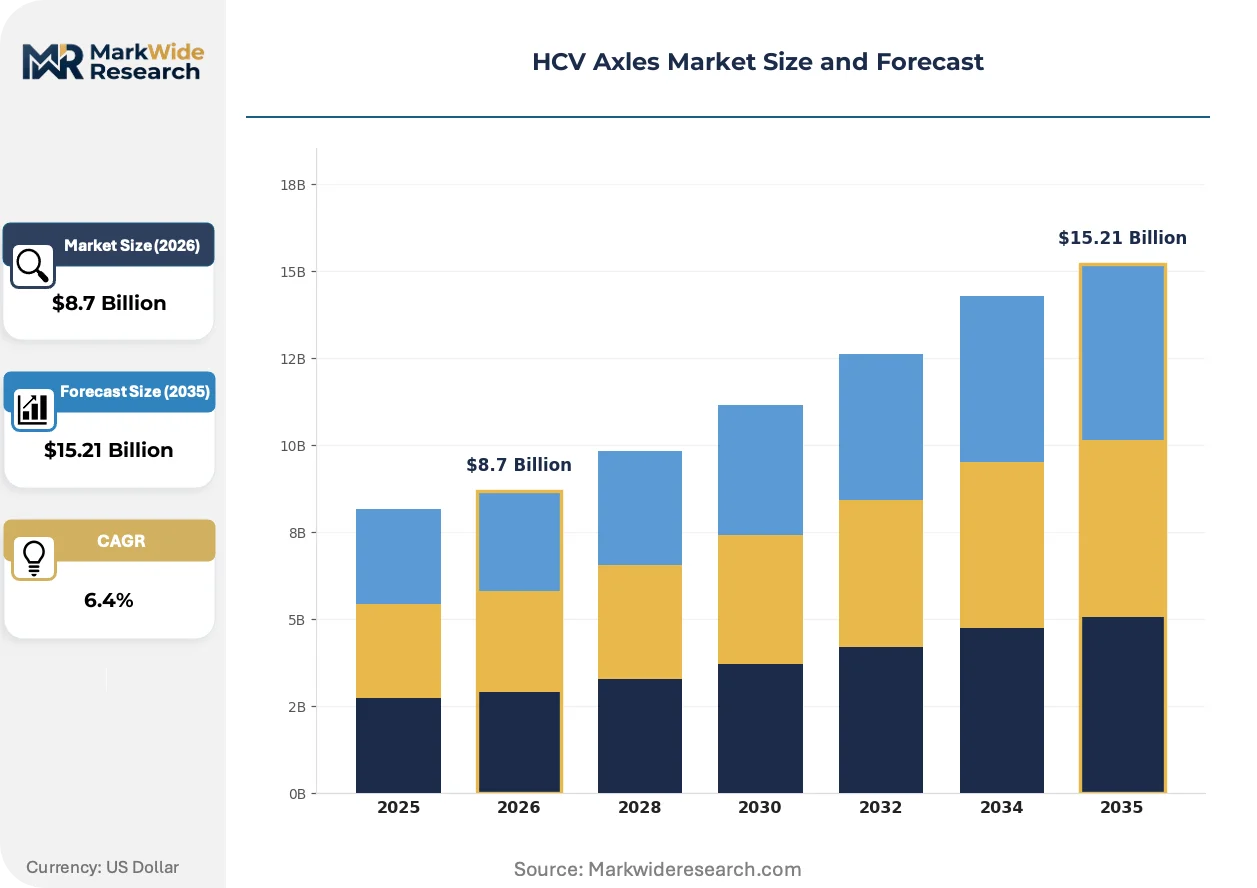
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Axle, Tandem Axle, Tridem Axle, Multi-Axle End User: OEMs, Aftermarket Providers, Fleet Operators, Vehicle Assemblers Material: Steel, Aluminum, Composite, Cast Iron Technology: Hydraulic, Pneumatic, Mechanical, Electronic |
| Companies Covered | American Axle & Manufacturing Inc., Dana Ltd., Meritor Inc., BRIST Axle Systems SRL, PRESS KOGYO, HANDE Axle, Shandong Heavy Industry, Sichuan Jian'an, Hyundai WIA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HCV Axles Market Strategic Shifts
Axle-integrated electronic systems are compressing the traditional separation between drivetrain and chassis control, forcing suppliers to master software-hardware co-development or cede premium tier positioning.
Intelligent axle units with embedded torque vectoring and brake-by-wire capability are unifying previously separate control domains. Premium European OEMs specify these configurations for automated freight corridors. The technology is unifying margin capture around software-enabled predictive maintenance rather than commodity hardware sales.
REACH substance restrictions and F-Gas Regulation amendments are phasing out conventional lubricant formulations in sealed axle assemblies. European suppliers reformulate bearing greases to maintain friction performance without restricted additives. Heavy-haul operators in Germany and Scandinavia face accelerated compliance timelines for fleet-wide retrofit.
Fleet procurement departments now bundle axle specification with total cost-of-ownership analytics spanning fuel efficiency, maintenance intervals, and residual value. Third-party logistics providers in North America displace traditional distributor relationships with direct manufacturer partnerships. This concentration is most visible among US-based refrigerated freight operators managing temperature-controlled axle seal integrity across climate zones.
HCV Axles Market Segmentation
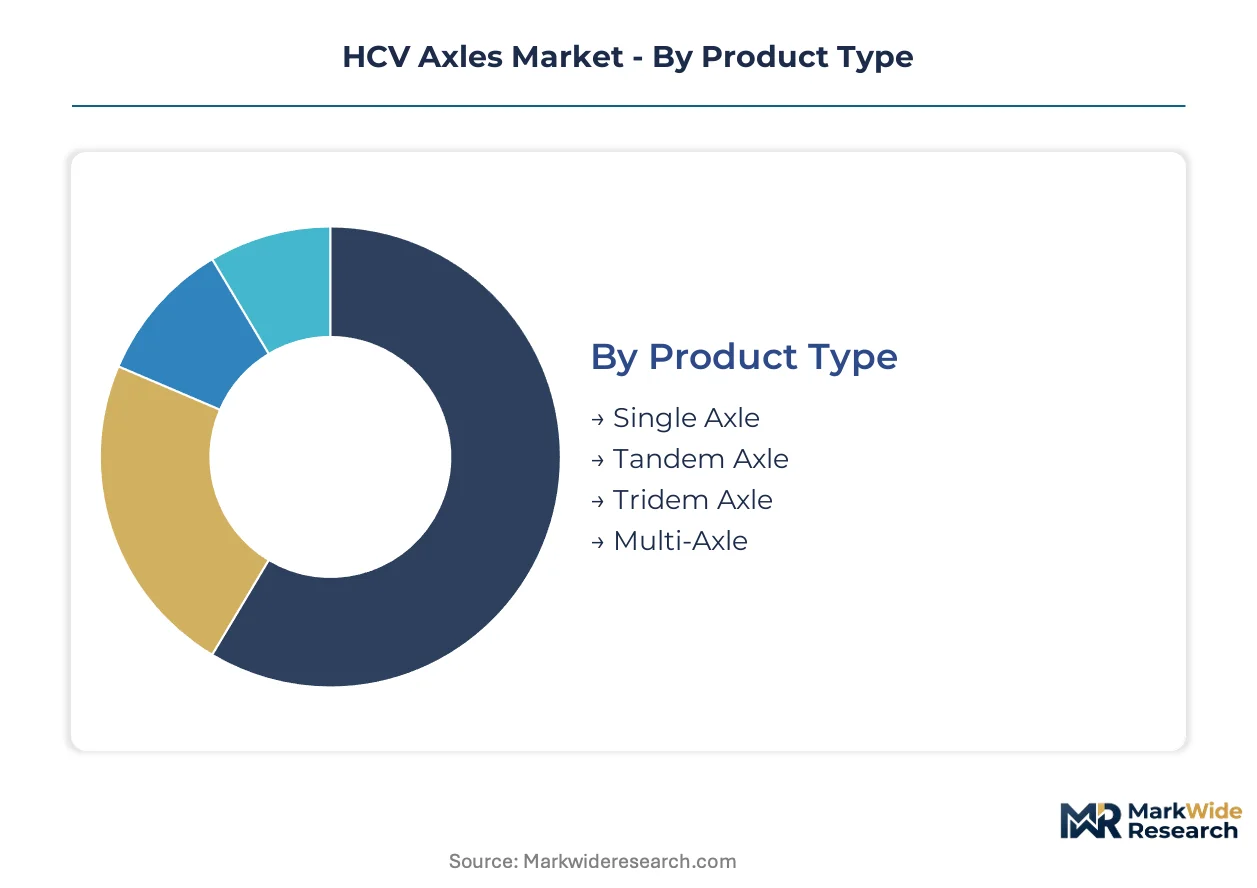
HCV axle procurement splits across customization depth and standardization pressure, with fleet operators demanding application-specific load ratings while OEMs push modular platforms to compress tooling costs. Material and technology choices increasingly bifurcate between efficiency-optimized premium specifications and cost-driven volume production.
Product Type:
Customization intensity varies sharply across axle configurations, with multi-axle layouts requiring chassis-specific engineering while single axle units ship as standardized modules.
- Tandem Axle:Two-axle assemblies connected through a common suspension system distribute gross vehicle weight across dual load-bearing points. Demand concentrates in China's long-haul freight corridor where GB-standard axle load limits mandate weight distribution across multiple contact points. EPA Phase 3 efficiency benchmarks accelerate adoption of friction-optimized tandem configurations in US heavy-freight fleets.
- Single Axle:Independent load-bearing assemblies supporting one wheel pair per unit, manufactured through closed-die forging of alloy steel billets with induction-hardened bearing journals. European urban delivery operators specify these for last-mile distribution vehicles where maneuverability constraints override payload maximization.
- Tridem Axle:Three-axle configurations for specialized heavy-haul applications exceeding standard weight limits.
- Multi-Axle:Four-plus axle assemblies for extreme load mining and construction equipment.
Leading the category by volume: Tandem Axle. Expanding most quickly: Tridem Axle.
End User:
Procurement authority concentrates differently across the value chain, with fleet operators wielding growing specification influence while vehicle assemblers retain design integration control.
- OEMs:Original equipment manufacturers integrate axle assemblies into complete vehicle platforms during initial assembly, specifying load ratings and brake integration architectures. China's state-backed fleet electrification mandates reshape procurement patterns for electrification-ready tandem configurations.
- Fleet Operators:Large logistics providers now specify axle configurations directly through manufacturer partnerships, bypassing traditional distributor relationships. North American refrigerated freight operators lead this shift, managing temperature-controlled seal integrity specifications across climate zones.
- Aftermarket Providers:Independent distributors and service networks handling replacement axle assemblies and repair components.
- Vehicle Assemblers:Final assembly facilities integrating purchased axles into completed commercial vehicles.
Procurement volume leader: OEMs. Gaining share fastest: Fleet Operators.
Material:
Cost-performance tradeoffs define material selection, with weight optimization premiums competing against forged steel durability in total cost-of-ownership calculations.
- Steel:Closed-die forged alloy steel billets dominate heavy-haul specifications where fatigue resistance and impact durability override weight considerations. Scrap metal and energy market volatility compress margin stability for volume producers dependent on steel feedstock.
- Aluminum:Forged aluminum housings reduce unsprung mass for payload optimization in European urban delivery fleets. Euro VII brake integration complexity accelerates specification of aluminum-forged units with electronic chassis coordination.
- Composite:Fiber-reinforced polymer components for specialized lightweight applications.
- Cast Iron:Lower-cost alternative for non-critical load-bearing components in price-sensitive markets.
Steel dominates by installed base. Aluminum posts the steepest expansion trajectory.
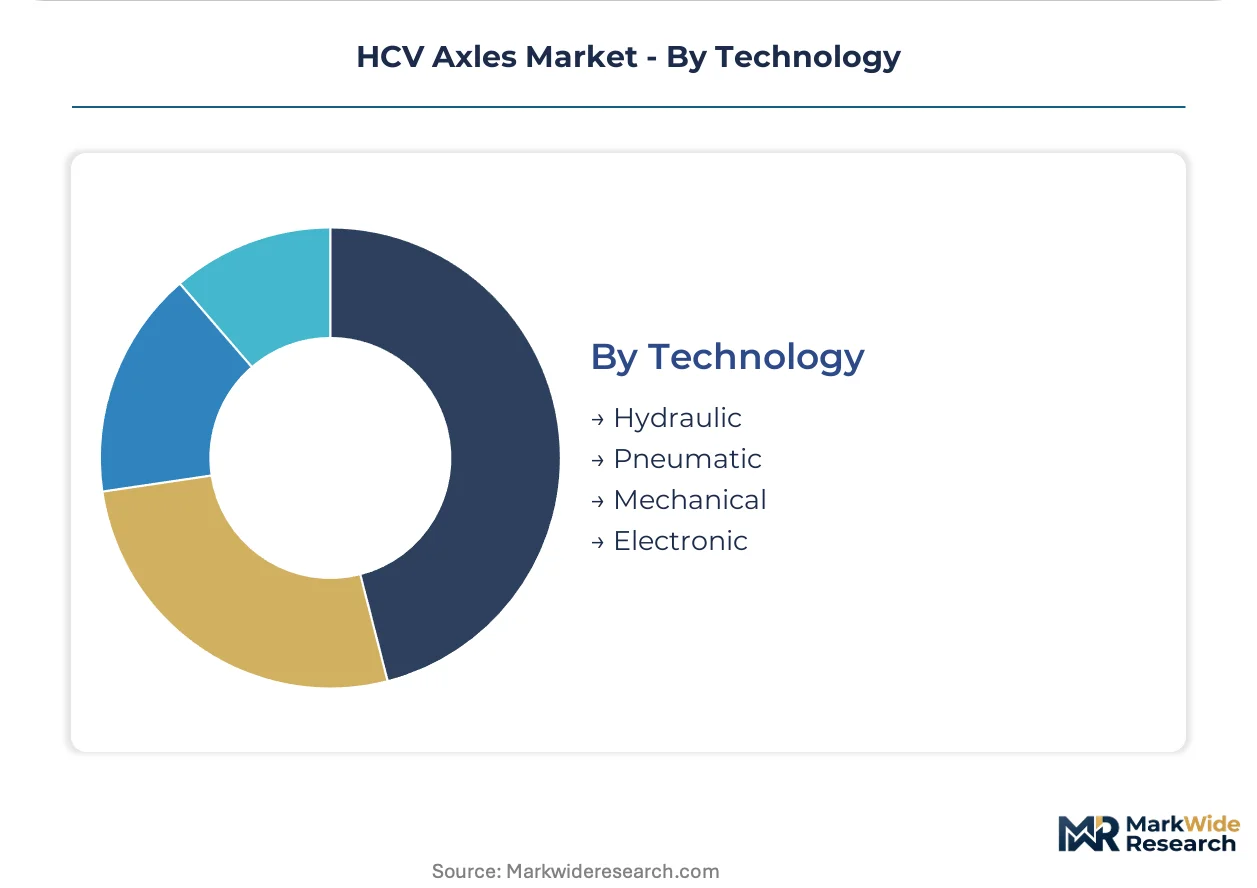
Technology:
Control system architecture determines margin capture, with electronic integration commanding premium positioning while mechanical systems defend commodity volume.
- Electronic:Sensor-embedded axle units with integrated torque vectoring, brake-by-wire capability, and predictive maintenance modules. Premium European OEMs specify these for automated freight corridors, unifying margin capture around software-enabled analytics.
- Hydraulic:Fluid-pressure actuation systems for heavy-load lifting and suspension functions. India's BIS certification protocols govern hydraulic axle entry for imported assemblies serving regional OEMs.
- Pneumatic:Air-spring suspension systems for adjustable load leveling.
- Mechanical:Traditional spring and linkage configurations defending cost-driven segments.
Mechanical systems lead by unit volume. Electronic technology climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jinan anchors the world's densest concentration of heavy commercial vehicle axle fabrication, with the Shandong Heavy Industry cluster supplying domestic OEMs and export markets under China's GB-standard certification regime.
United States
EPA Phase 3 greenhouse gas standards compel freight operators to replace aging tandem configurations with friction-optimized assemblies. The Toledo-Maumee corridor in Ohio hosts Dana Ltd.'s integrated forging and machining operations serving North American heavy-fleet specifications. Refrigerated logistics providers in the Midwest now specify axle configurations directly through manufacturer partnerships rather than distributor networks.
Germany
Euro VII emission frameworks mandate electronic axle-chassis coordination that legacy mechanical architectures cannot satisfy. The KBA enforces brake integration protocols reshaping procurement for automated freight corridors. Stuttgart-based OEMs specify sensor-embedded axle units with predictive maintenance modules for premium long-haul platforms.
China
MIIT electrification mandates concentrate procurement for electrification-ready tandem assemblies in the Yangtze River Delta manufacturing belt. GB-standard axle load limits directly shape domestic product certification requirements. HANDE Axle dominates volume production for state-backed fleet renewal programs targeting battery-electric heavy-duty platforms.
India
BIS mandates axle testing protocols under automotive component safety regulations governing market entry for imported assemblies. Domestic testing capacity lags import demand, opening white space for localized assembly facilities. The Pune-Nashik corridor attracts regional OEMs seeking certified suppliers for heavy-freight configurations.
Brazil
ANVISA commercial vehicle safety standards create first-mover advantage for certified suppliers in Mercosur freight corridors. Incoming axle load and braking performance requirements reshape procurement for long-haul operators. São Paulo-based assemblers evaluate total cost-of-ownership metrics spanning fuel efficiency and maintenance intervals.
HCV Axles Market Competitive Environment
Premium-margin players sit above commodity-margin players across electronic integration and forging capability dimensions. The vendor base stratifies into three tiers: integrated-system suppliers commanding software-enabled positioning, scale-forging specialists defending volume production, and regional fabricators serving price-sensitive procurement. Two strategic archetypes dominate competitive positioning: those mastering closed-die forging with in-house heat treatment, and those developing axle-embedded sensor architectures. Capacity expansion and strategic partnerships represent the dominant competitive moves as electrification timelines compress.
Within the integrated-system tier, Dana Ltd. and Meritor Inc. exemplify premium-tier positioning through electronic axle programs. HANDE Axle anchors the scale-forging archetype for China's domestic OEM base. American Axle & Manufacturing Inc. occupies a position bridging North American heavy-fleet specifications with modular platform supply.
| Leading Market Players |
|---|
| American Axle & Manufacturing Inc. |
| Dana Ltd. |
| Meritor Inc. |
| BRIST Axle Systems SRL |
| PRESS KOGYO |
| HANDE Axle |
| Shandong Heavy Industry |
| Sichuan Jian'an |
| Hyundai WIA |
| Others |
Value Chain & Pricing Dynamics
Fleet electrification mandates from China's MIIT and EPA Phase 3 efficiency benchmarks are forcing axle manufacturers to absorb redesign costs for dual-carbon architectures, compressing margin pools for commodity-grade suppliers while rewarding premium-tier electronics integration. This demand-side specification pressure is reshaping how suppliers allocate forging capacity and where they source alloy steel billets.
Pricing Analysis
Total cost-of-ownership metrics anchor value-based pricing for HCV axles, with fleet operators calculating fuel efficiency gains, maintenance interval extensions, and residual value premiums across contract durations. Pricing stratifies across electronic-integrated premium tiers, friction-optimized standard configurations, and cost-driven mechanical commodity units. Cost compression in steel-forged segments is intensifying because scrap metal and energy market volatility erode volume producer margins. Refrigerated freight operators in North America show least price sensitivity due to temperature-controlled seal integrity requirements, while price-sensitive regional distributors in emerging markets prioritize acquisition cost over lifecycle analytics.
Supply Chain Analysis
Remanufacturing flows for bearing journals and axle housings are expanding as fleet operators extend service intervals under total cost-of-ownership contracts, creating reverse-logistics revenue streams for OEM service networks. Supply concentrates in China, Germany, and the United States, with Jinan's Shandong Heavy Industry cluster, Stuttgart's precision forging corridor, and Ohio's Toledo-Maumee manufacturing belt anchoring regional production. The supply chain draws from alloy steel billets, precision bearing seals, and induction hardening equipment. Single-source vulnerability in German and Japanese seal manufacturing creates structural risk for friction-reduction component availability. Distribution runs through direct manufacturer partnerships with large fleet operators, displacing traditional aftermarket distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HCV axles market is executing a technology-transition phase as electronic axle-chassis coordination architectures displace legacy mechanical systems under Euro VII and EPA Phase 3 mandates.
For Market Incumbents: Extend software-hardware co-development capabilities to defend premium positioning against emerging electronics specialists, while anchoring forging capacity in China's Yangtze River Delta and North American heavy-freight corridors to capture fleet renewal volume. Threat from battery-electric platform specialists with clean-sheet axle designs demands accelerated R&D allocation toward predictive maintenance modules. For New Entrants and Emerging Players: Fleet operator direct procurement partnerships offer the most penetrable channel structure, bypassing entrenched OEM supply relationships that dominate traditional distributor networks. Target India's BIS certification gap where domestic testing capacity lags import demand, opening white space for localized assembly facilities serving Pune-Nashik corridor OEMs. For Investors and Strategic Acquirers: The window for entry favors mid-scale forging operations with captive heat-treatment expertise and emerging electronics integration capabilities. Long-term viability over the next decade hinges on dual-carbon platform readiness. Signal to monitor: divergence between regional brake integration standards and electrification-ready axle architectures as fleet operators evaluate powertrain configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forging Capacity | Dana Ltd.'s in-house closed-die forging anchors North American heavy-freight specification compliance. |
| Electronic Axle-Chassis Integration | Meritor's sensor-embedded programs capture premium positioning in automated freight corridors. |
| Localized Assembly Facility Deployment | India's BIS certification gap creates first-mover advantage for regional OEM supply contracts. |
| Predictive Maintenance Module Development | Torque monitoring with brake wear analytics commands premium pricing in North American long-haul specifications. |
| Aluminum Forging Scale-Up | European urban delivery fleets specify lightweight housings for payload optimization under Euro VII. |
Study Parameters
Trade databases, automotive component regulatory filings, and vehicle production statistics formed the secondary backbone for this analysis, supplemented by customs records from major manufacturing corridors. Primary interviews with OEM procurement directors, fleet maintenance managers, axle forging plant engineers, and aftermarket distribution heads validated demand assumptions. Bottom-up triangulation across product type, material grade, and technology tier converged with top-down macroeconomic modeling.
Historical trendline analysis of axle unit shipments and value flows established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include axle configuration, end-user procurement authority, material composition, and control system architecture, with electrification readiness treated as a cross-cutting attribute. CAGRs were derived from regression analysis against fleet renewal cycles, regulatory phase-in schedules, and powertrain transition timelines.
Caveats apply where alloy steel billet cost volatility, bearing seal supply concentration, or divergence between regional brake integration standards could materially shift the outlook. Practitioners should monitor EPA Phase 3 implementation pace, Euro VII brake coordination requirements, and China's GB-standard axle load enforcement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Trailer Axle Market
Vehicle Components
Bicycle Front Hub Market
Vehicle Components
Automotive Wheel Speed Sensor Market
Vehicle Components
Engine Components Market
Vehicle Components
Italy Automotive Glass Fiber Composites Market
Vehicle Components
Child Seats Market
Vehicle Components
Cross Roller Bearings Market
Vehicle Components
Towing Equipment Market
Vehicle Components
Thrust Bearings Market
Vehicle Components
Navigation Light Market
Vehicle Components
Garbage Collection Vehicle Market
Vehicle Components
Argentina Automotive Carbon Fiber Composites Market
Vehicle Components
Chassis Leveling Valves Market
Vehicle Components
Mining Vehicle AC Kits Market
Vehicle Components
Driveline Systems for Electric Vehicle Market
Vehicle Components
Autonomous Trains Components Market