
 Advanced Suspension Control System Market | 2026-2036
Advanced Suspension Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Suspension Control System Market Intelligence
Electromechanical engineering talent scarcity is unwinding production timelines for next-generation damper valves and sensor-integrated strut assemblies. ZF Friedrichshafen AG leverages its integrated actuator manufacturing footprint to anchor European OEM supply chains. Tenneco Inc. competes through specialized monotube and twin-tube damper portfolios scaled across passenger and commercial vehicle platforms. Continental AG differentiates via embedded software competencies that link suspension modules to broader vehicle dynamics controllers.
Advanced suspension control systems comprise electronically governed damper units, sensor arrays, and control modules that modulate damping force in real time based on road conditions and driver inputs, with response latencies typically below 10 milliseconds for premium electromechanical configurations. These systems primarily serve to optimize ride comfort, vehicle stability, and tire contact patch consistency across variable driving surfaces. Semi-active systems occupy the largest installed base due to their cost-positioning balance between passive hardware and fully active architectures with hydraulic pump demands. Electronic control technology captures expanding design-in activity as automakers integrate suspension logic with central compute platforms and ADAS sensor fusion. Electromechanical actuation leads growth trajectory among technology categories, displacing legacy pneumatic layouts in heavy commercial applications where energy efficiency and maintenance intervals have become decisive procurement criteria.
NHTSA crashworthiness protocols and EPA fuel economy standards shape U.S. product development roadmaps by incentivizing mass reduction and real-time load-adaptive damping. ECE R13 braking stability requirements and EU type-approval frameworks under UNECE WP.29 mandate functional safety validation for electronic chassis control systems entering European vehicle platforms. Stakeholders must monitor divergence between U.S. FMVSS self-certification and EU third-party conformity assessment pathways, as this regulatory asymmetry threatens to fragment validation budgets and platform commonality strategies.
Market Dynamics
Electromechanical actuator architectures are compressing development cycles for damper-integrated sensor modules while simultaneously intensifying competition among valve suppliers and control software developers.
Growth Catalysts
- EPA Fuel Economy Standards:U.S. light-duty vehicle efficiency mandates push automakers toward mass-optimized chassis systems with real-time load-adaptive damping.
- ADAS Integration:Suspension control modules now feed data into central vehicle dynamics computers, creating pull for multi-axis accelerometer arrays.
- German Premium Production Clusters:Stuttgart and Munich anchor concentrated OEM demand for semi-active and active damper configurations.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium price swings destabilize electromechanical actuator cost models.
- Valve Supplier Concentration:Precision solenoid manufacturing concentrates among a handful of European and Japanese component specialists.
- Active System Energy Draw:Hydraulic pump architectures face efficiency ceilings that limit adoption in battery-electric vehicle platforms.
Strategic Opportunities
- India Commercial Vehicle Fleet Modernization:Heavy-duty truck operators seek retrofit-compatible electronic damping to reduce cargo damage and tire wear.
- EU Green Deal Procurement Incentives:Public fleet tenders now weight lifecycle carbon footprint, favoring lightweight electromechanical over pneumatic systems.
- Sensor-Fusion Convergence:Lidar and camera data streams enable predictive road-surface detection that pre-conditions damper response.
Industry Challenges
- Embedded Software Talent Scarcity:Control algorithm development for real-time damping force modulation competes with autonomous driving teams for firmware engineers.
- UNECE WP.29 Type-Approval Complexity:Functional safety validation for electronic chassis systems stretches certification timelines across European platforms.
- Legacy Platform Integration Friction:CAN bus bandwidth limitations complicate retrofit of intelligent suspension modules onto existing vehicle architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Suspension Control System Market |
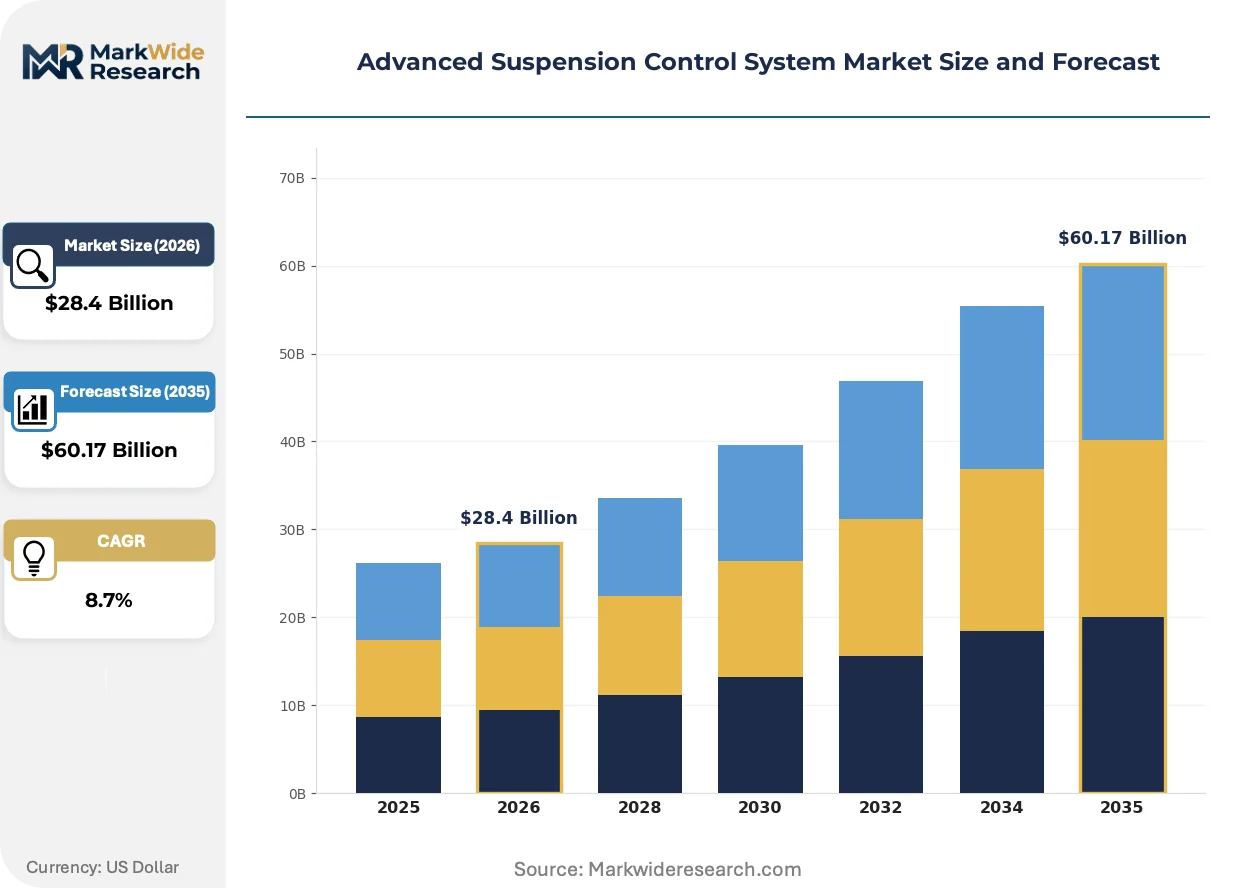
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $60.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Systems, Passive Systems, Semi-Active Systems, Adaptive Systems Technology: Electromechanical, Hydraulic, Pneumatic, Electronic Control End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Application: Passenger Vehicles, Commercial Vehicles, Off-Road Vehicles, Luxury Vehicles |
| Companies Covered | KYB Corporation, Benteler International AG, ZF Friedrichshafen AG, Mando Corporation, Hitachi Automotive Systems Ltd., Tenneco Inc., Thyssenkrupp AG, BWI Group, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Suspension Control System Market Strategic Shifts & Innovations
Digital twin methodologies and over-the-air update capabilities are redefining how suspension calibration data moves between development labs and production vehicles.
Electromagnetic valve technologies with sub-millisecond response latencies are fragmenting the traditional hydraulic damper market. Premium passenger vehicle programs adopt these actuators for frequency-selective damping. The technology is fragmenting supplier hierarchies by enabling software-centric entrants to compete with legacy hardware manufacturers.
EU Green Deal carbon-border adjustments and EPA tailpipe standards are tightening in parallel, forcing chassis system suppliers to document embedded emissions across steel, aluminum, and rare earth supply chains. Component producers must now submit lifecycle assessments alongside technical specifications. European heavy commercial platforms face the steepest compliance cost escalation.
Fleet operators now specify total cost of ownership metrics that unbundle hardware procurement from predictive maintenance subscriptions. Leasing companies and logistics aggregators drive this shift. North American long-haul trucking corridors exhibit the fastest adoption of usage-based damping service contracts.
Advanced Suspension Control System Market Segmentation
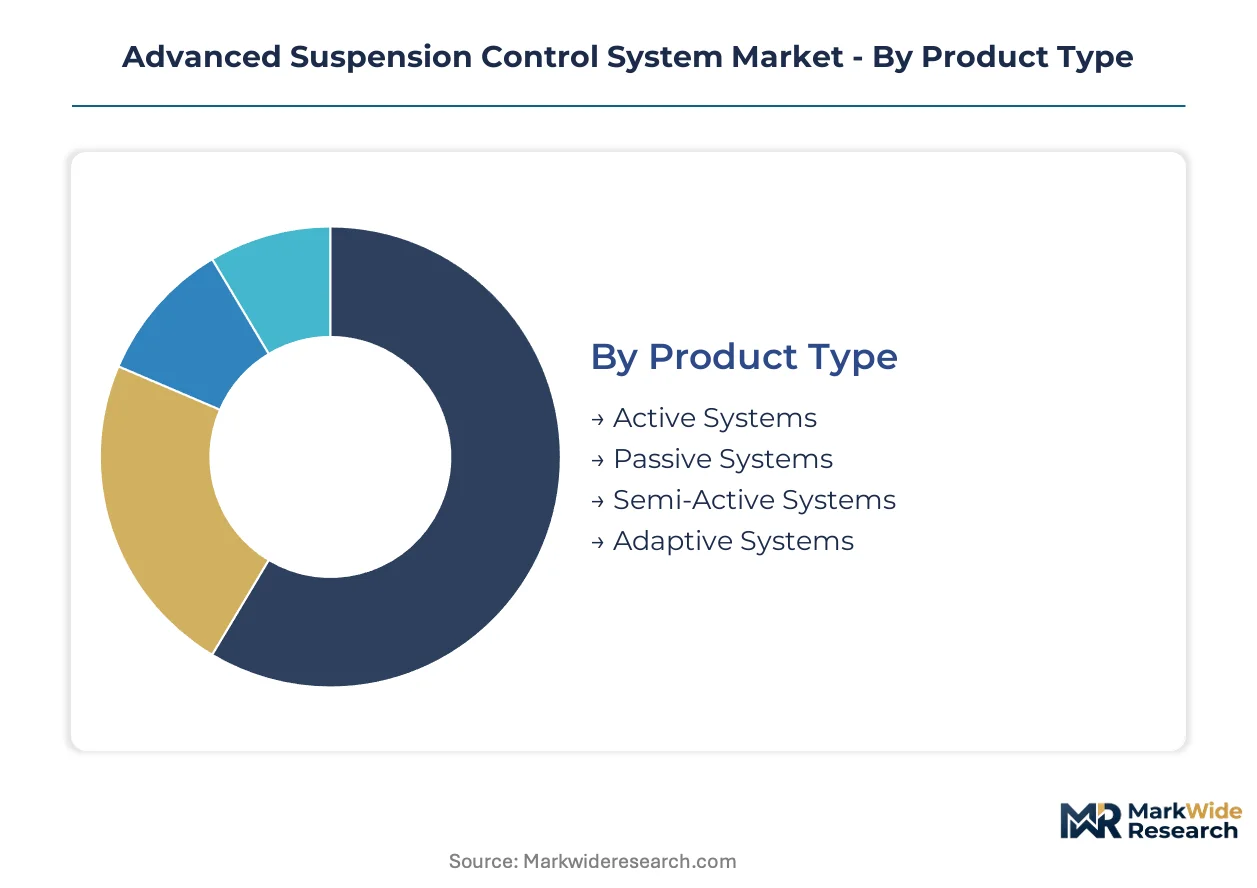
Segmentation in advanced suspension control systems reveals how regulatory pressure and vehicle electrification reshape procurement priorities across hardware architectures and supply chain tiers. Distinct compliance burdens and performance thresholds drive divergence in technology adoption patterns.
Product Type:
EPA fuel economy standards and ECE R13 braking stability requirements create divergent certification pathways that favor certain damping architectures over others.
- Semi-Active Systems:Electronically governed dampers modulate damping force through solenoid valves without external power input, delivering cost-positioned performance between passive and active alternatives. German premium production clusters in Stuttgart and Munich anchor concentrated OEM demand where real-time load-adaptive damping meets mass reduction targets.
- Active Systems:Hydraulic pump-fed architectures deliver continuous force generation with sub-10 millisecond response latencies for full vehicle dynamics control. Energy draw limitations constrain adoption in battery-electric platforms despite superior ride isolation capabilities.
- Passive Systems:Fixed-rate mechanical dampers dominate emerging market commercial fleets where procurement prioritizes acquisition cost over adaptive performance.
- Adaptive Systems:Self-adjusting mechanical valving responds to displacement velocity without electronic intervention, serving retrofit markets with limited CAN bus infrastructure.
Semi-Active Systems handles the majority of throughput; Active Systems is expanding most quickly on share.
Technology:
Cost tier stratification separates premium electromechanical configurations from legacy pneumatic installations in heavy commercial applications.
- Electromechanical:Rare earth magnet actuators with sub-millisecond response latencies displace hydraulic layouts in energy-sensitive platforms. EU Green Deal procurement incentives now weight lifecycle carbon footprint, accelerating displacement of pneumatic systems in public fleet tenders.
- Electronic Control:Embedded software modules integrate suspension logic with central compute platforms and ADAS sensor fusion, creating pull for multi-axis accelerometer arrays. NHTSA crashworthiness protocols shape U.S. development roadmaps by mandating functional safety validation.
- Hydraulic:Pressurized fluid architectures maintain installed base in high-load commercial applications where force density requirements exceed electromechanical limits.
- Pneumatic:Air-spring systems face efficiency ceilings and maintenance interval disadvantages that drive replacement in long-haul trucking corridors.
Electronic Control commands the largest installed base; Electromechanical is gaining share fastest.
End User:
Volume concentration among vehicle assemblers creates procurement leverage that reshapes Tier-1 supplier margin structures.
- OEMs:Brand-holding manufacturers specify damper performance matrices and control software architectures that cascade through supply contracts. UNECE WP.29 type-approval complexity stretches validation timelines and concentrates sourcing among vertically integrated chassis specialists.
- Tier-1 Suppliers:System integrators combine valve manufacturing, sensor assembly, and control module production under single-source responsibility. Embedded software talent scarcity compresses development cycles for damper-integrated modules.
- Vehicle Assemblers:Contract manufacturing operations execute platform builds with limited design authority over suspension specifications.
- Aftermarket Providers:Independent distributors serve retrofit demand from fleet operators seeking cargo damage reduction through electronic damping upgrades.
OEMs handle the majority of throughput; Tier-1 Suppliers is the fastest mover on share.
Application:
Customer type differentiation separates premium passenger specifications from total cost of ownership metrics that govern commercial fleet procurement.
- Luxury Vehicles:Frequency-selective damping with predictive road-surface detection commands design-in priority from Stuttgart and Munich engineering centers. Lidar and camera data streams enable pre-conditioning of damper response before wheel contact.
- Commercial Vehicles:Heavy-duty truck operators in North American long-haul corridors adopt usage-based damping service contracts that unbundle hardware from predictive maintenance subscriptions.
- Passenger Vehicles:Mass-market platforms integrate semi-active configurations as optional equipment where platform commonality strategies span multiple regulatory jurisdictions.
- Off-Road Vehicles:Mining and construction applications prioritize durability over response latency, sustaining demand for robust hydraulic architectures.
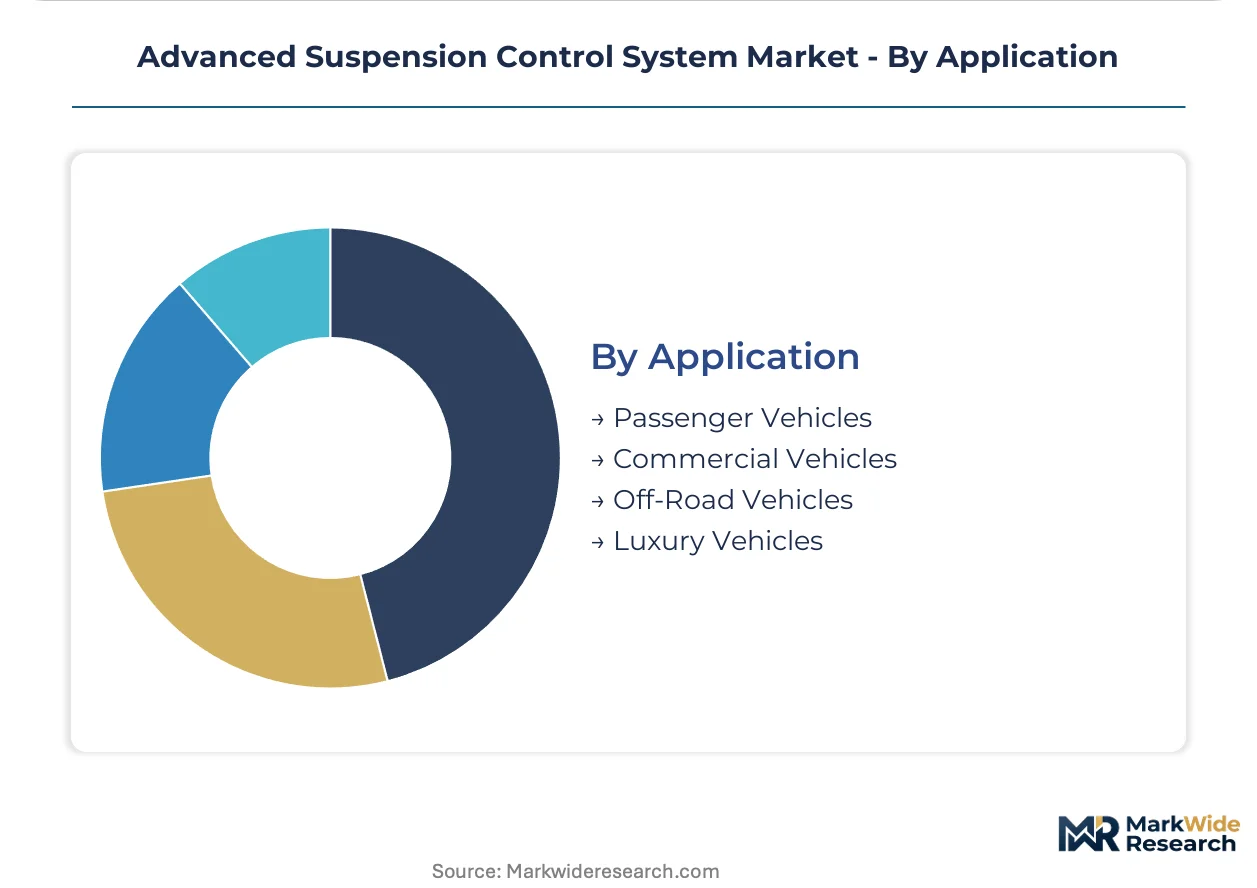
Commercial Vehicles handles the majority of throughput; Luxury Vehicles is the fastest mover on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. German and Japanese OEMs prioritize predictive road-surface detection and sub-10 millisecond response latencies for luxury platforms, while Indian and North American commercial fleets emphasize total cost of ownership metrics and retrofit compatibility for cargo damage reduction.
Germany
Stuttgart and Munich engineering centers anchor concentrated demand for semi-active and active damper configurations in premium passenger vehicles. EU Green Deal procurement incentives now weight lifecycle carbon footprint in public fleet tenders, favoring electromechanical over pneumatic architectures. The Baden-Württemberg automotive cluster drives integration of suspension modules with central vehicle dynamics controllers.
United States
North American long-haul trucking corridors exhibit the fastest adoption of usage-based damping service contracts that unbundle hardware from predictive maintenance subscriptions. EPA fuel economy standards and NHTSA crashworthiness protocols shape development roadmaps by mandating mass reduction and functional safety validation. Detroit-area OEMs specify real-time load-adaptive damping for light-duty platform efficiency targets.
Japan
Precision solenoid manufacturing concentrates among component specialists serving both domestic OEMs and export markets. METI industrial policy supports electromechanical actuator development to reduce rare earth magnet dependency. The Nagoya-Toyota industrial corridor maintains dense supplier networks for sensor-integrated strut assemblies.
India
Heavy-duty truck operators seek retrofit-compatible electronic damping to reduce cargo damage and tire wear in commercial fleet modernization programs. BIS certification requirements and DGFT import regulations shape component sourcing strategies for Tier-1 suppliers. The Chennai-Bangalore automotive belt concentrates assembly operations for domestic and export platforms.
China
MIIT new energy vehicle mandates accelerate displacement of hydraulic pump architectures in battery-electric platforms where energy draw limitations constrain active system adoption. Dual carbon goals pressure chassis suppliers to document embedded emissions across steel and aluminum supply chains. The Yangtze River Delta hosts the densest concentration of electromechanical actuator manufacturing for both domestic OEMs and export markets.
Advanced Suspension Control System Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the advanced suspension control system market. Vertically integrated chassis specialists combine valve manufacturing, sensor assembly, and control module production under single-source responsibility, while software-centric entrants compete through embedded competencies linking suspension logic to ADAS platforms. Dominant competitive moves include strategic partnerships for sensor-fusion convergence and backward integration into rare earth magnet supply chains to stabilize actuator cost models.
Among German-based integrated suppliers, ZF Friedrichshafen AG and Continental AG exemplify the vertically integrated archetype with captive manufacturing footprints anchoring European OEM supply chains. Tenneco Inc. represents the North American specialist tier with scaled damper portfolios across passenger and commercial platforms. KYB Corporation and Hitachi Automotive Systems Ltd. occupy positions within the Japanese precision component cluster serving global OEM demand for solenoid valve and sensor module supply.
| Leading Market Players |
|---|
| KYB Corporation |
| Benteler International AG |
| ZF Friedrichshafen AG |
| Mando Corporation |
| Hitachi Automotive Systems Ltd. |
| Tenneco Inc. |
| Thyssenkrupp AG |
| BWI Group |
| Continental AG |
| Others |
Cost & Logistics Intelligence
Electromechanical actuator displacement of hydraulic architectures in heavy commercial platforms simultaneously redraws procurement geography toward rare earth magnet supply zones and compresses pricing power for legacy pneumatic system suppliers facing EU carbon-border compliance costs.
Pricing Analysis
Long-term offtake contracts dominate procurement between German OEMs and Tier 1 damper suppliers, insulating volume commitments from neodymium spot volatility while spot purchasing persists for aftermarket retrofit channels. Price differentiation rests on certification grade (UNECE WP.29 functional safety validation) and volume scale, with fleet operators commanding steepest discounts through predictive maintenance bundling. Cost compression in semi-active damper tiers is intensifying because embedded software talent scarcity stretches development timelines. Aftermarket providers exhibit highest price sensitivity; luxury vehicle OEMs demonstrate lowest.
Supply Chain Analysis
Inventory buffers for precision solenoid valves stretch lead times when Japanese component specialists face order surges from Stuttgart and Munich engineering centers. Manufacturing concentrates in Germany, Japan, and China, with the Yangtze River Delta hosting densest electromechanical actuator production. Supply chains draw from rare earth magnet feedstock, high-grade steel forgings, and multi-axis accelerometer arrays. Single-source vulnerability concentrates in European precision solenoid manufacturing. Distribution runs through captive Tier 1 supplier networks into OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware engineering talent gaps for real-time damping force modulation are compressing development cycles and forcing automakers to compete with autonomous driving teams for embedded software competencies, reshaping competitive positioning around in-house control algorithm capabilities.
For Market Incumbents: Fortify captive valve manufacturing footprints through backward integration into rare earth magnet supply chains to stabilize actuator cost models against price volatility. Deepen embedded software competencies linking suspension modules to ADAS sensor fusion before software-centric entrants capture design-in activity. Prioritize UNECE WP.29 pre-certification investment to accelerate European platform validation timelines. For New Entrants and Emerging Players: Anchor in Indian commercial vehicle fleet modernization programs where retrofit-compatible electronic damping demand outpaces established supplier coverage. Target heavy-duty truck operators seeking cargo damage reduction through usage-based service contracts rather than capital-intensive hardware sales. Pursue predictive road-surface detection partnerships with lidar and camera system developers as primary go-to-market channel. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Tier 1 damper specialists lacking embedded software integration capabilities but holding captive OEM supply relationships. Five-to-ten year viability hinges on electromechanical transition completion before hydraulic architectures face battery-electric platform exclusion. Monitor MIIT new energy vehicle mandate acceleration as inflection signal for active system demand collapse.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Fusion Partnership | Lidar and camera data integration enables predictive damper pre-conditioning for German luxury OEMs. |
| Rare Earth Supply Agreement | Long-term neodymium offtake stabilizes electromechanical actuator cost models against commodity volatility. |
| Embedded Software Acquisition | Control algorithm talent acquisition accelerates real-time damping module development timelines. |
| UNECE WP.29 Pre-Certification | Functional safety validation investment compresses European platform approval cycles. |
| Retrofit Channel Development | Aftermarket electronic damping distribution captures Indian commercial fleet modernization demand. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, vehicle production databases, and trade flow records. Interviews with OEM platform engineers, Tier 1 damper procurement leads, aftermarket distribution heads, and embedded software development directors inform demand-side validation. Secondary sources include NHTSA crashworthiness protocols, EPA fuel economy standard disclosures, UNECE WP.29 type-approval documentation, and IHS Markit vehicle registration data. Bottom-up damper unit shipment estimates triangulate against top-down chassis system spend analysis.
Segmentation dimensions modeled span product type (semi-active, active, passive, adaptive), technology (electromechanical, electronic control, hydraulic, pneumatic), end user (OEMs, Tier-1 suppliers, vehicle assemblers, aftermarket providers), and application (luxury vehicles, commercial vehicles, passenger vehicles, off-road vehicles) across the analysis window. CAGRs derive from regression against historical adoption curves and scenario-weighted regulatory compliance timelines. Forecast inputs incorporate EPA tailpipe standard stringency trajectories and EU Green Deal procurement incentive phase-ins.
Material uncertainties — rare earth magnet price volatility, electromechanical engineering talent availability, and regulatory divergence between FMVSS self-certification and EU third-party conformity assessment — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Global Automotive Terrain Response System Market
Automotive Safety and Security Systems
Latin America Airbag Systems Market
Automotive Safety and Security Systems
Global Electronic Brake Force Distribution System Market
Automotive Safety and Security Systems
Remote Vehicle Shutdown System Market
Automotive Safety and Security Systems
Anti-Lock Braking System (ABS) Market
Automotive Safety and Security Systems
Global Automotive Backup Camera Market
Automotive Safety and Security Systems
Global Automotive Electronic Stability Control Systems Market
Automotive Safety and Security Systems
Middle East and Africa Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Stolen Vehicle Tracking System Market
Automotive Safety and Security Systems
Automotive Front-End Collision Warning System Market
Automotive Safety and Security Systems
Smart Airbag Coats Market
Automotive Safety and Security Systems
Motorcycle Stability Control Market
Automotive Safety and Security Systems
Europe Pedestrian Detection Systems Market
Automotive Safety and Security Systems
Driving Helmet Market
Automotive Safety and Security Systems
Germany Traffic Sign Recognition Market
Automotive Safety and Security Systems
Automotive Start-Stop System Market