
 Global Bicycle Wheels Market | 2026-2036
Global Bicycle Wheels Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bicycle Wheels Market Analysis
Market Context
Taiwanese rim and hub producers is expanding carbon fiber layup capacity to serve premium OEM contracts across Europe and North America. DT Swiss leverages in-house spoke manufacturing and Swiss engineering heritage to sustain pricing power in the performance tier. Shimano dominates integrated wheel-drivetrain bundles through its dealer network density, while Zipp (SRAM) competes on aerodynamic rim profiles developed in its Indianapolis wind tunnel facility.
Technical Definition and Segment Structure
Bicycle wheels are rotating assemblies comprising hubs, spokes, and rims that transmit rider power to the road surface while maintaining directional stability and load bearing capacity; modern variants employ carbon fiber pre-preg layups achieving rim weights below 450 grams with brake track temperatures rated to 240 degrees Celsius. Carbon fiber wheels command the highest margin pool in the product type dimension as professional cyclists and elite amateurs absorb four-figure price points for rotational weight reduction. Tubeless technology leads the technology dimension by eliminating inner tubes and reducing puncture frequency, though clincher configurations retain volume dominance in the commuter and touring applications where repair simplicity outweighs performance gain.
Regulatory Frame and Outlook
The EU Green Deal and REACH chemical compliance frameworks shape material selection and end-of-life recyclability obligations for European market access, while the FDA exercises indirect influence through ISO 10993 biocompatibility standards applied to cycling-related medical devices and protective equipment ecosystems. Japan's METI energy efficiency guidelines and JIS standards for component durability create additional certification layers for wheels distributed through Japanese OEM channels. Stakeholders must monitor evolving national subsidy regimes and material traceability mandates to align capacity planning with jurisdiction-specific compliance timelines.
Market Dynamics
Carbon fiber rim manufacturing is consolidating among Taiwanese suppliers with captive pre-preg autoclave capacity, compressing lead times for European OEMs while squeezing margin pools for second-tier assemblers lacking backward integration into spoke and hub production.
Growth Catalysts
- EU Green Deal cycling infrastructure mandates:Federal subsidies for commuter bicycles in Germany, France, and the Netherlands are redirecting municipal procurement toward premium wheel sets with tubeless compatibility and disc brake integration.
- Road cycling performance tier expansion:Elite amateur racing categories are absorbing carbon fiber wheel technology originally developed for professional peloton use, extending addressable demand beyond OEM factory-team supply.
- Tubeless technology maturation:Hookless rim bed designs and tire bead interface standardization are eliminating historical compatibility friction that constrained aftermarket upgrade cycles.
Market Restraints
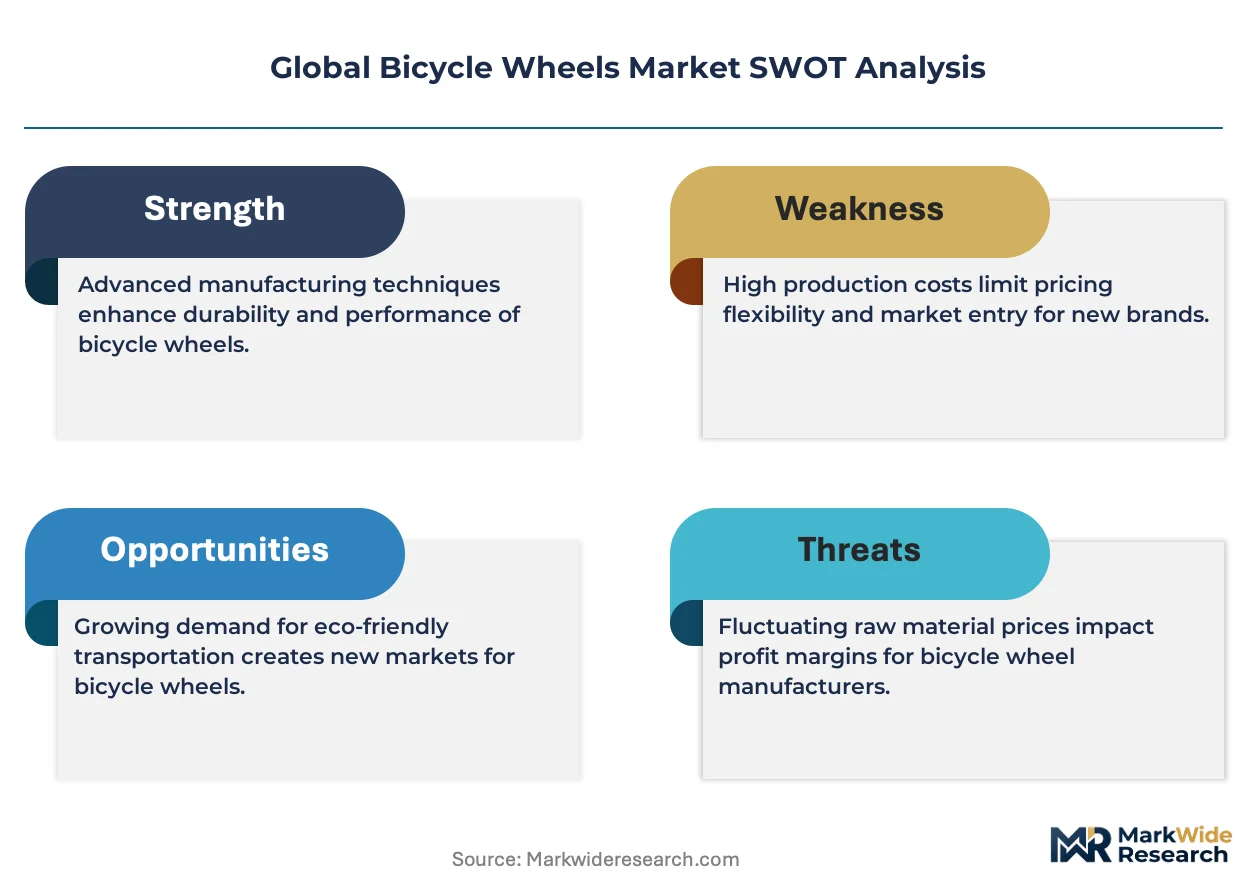
- Carbon fiber precursor cost volatility:Acrylonitrile and petroleum-based pitch feedstock prices fluctuate with energy markets, compressing margin stability for rim manufacturers without long-term polymer supply contracts.
- Taiwanese supply concentration:Over seventy percent of premium carbon rim layup capacity concentrates in Taichung and Kaohsiung industrial zones, creating geographic risk exposure from seismic events and trade route disruption.
- REACH chemical compliance burden:ECHA substance of very high concern listings for epoxy resin hardeners and solvent-based mold release agents are forcing reformulation cycles that extend R&D timelines by twelve to eighteen months.
Strategic Opportunities
- Indian commuter market underpenetration:Tier-two and tier-three cities lack organized retail for premium wheel components, creating first-mover advantage for brands establishing local assembly partnerships under the PLI scheme.
- E-bike motor-integrated hub convergence:Mid-drive motor systems from Bosch and Shimano are creating specification pull-through for reinforced hub shells and larger spoke flange diameters in urban mobility applications.
- Japan METI durability certification:JIS B 9415 wheel strength standards are becoming de facto quality benchmarks for Asian export markets, enabling premium positioning for manufacturers achieving third-party validation.
Industry Challenges
- Composite repair technician scarcity:Carbon fiber rim damage assessment and localized layup restoration require specialized training that outpaces vocational program output in European and North American service networks.
- Wind tunnel validation capex intensity:Aerodynamic rim profile development demands sustained access to rolling-road facilities or computational fluid dynamics clusters that mid-cap wheel brands cannot self-fund.
- Disc brake interface standardization delays:Through-axle diameter and rotor mount specifications remain fragmented across 12mm, 15mm, and flat-mount versus post-mount configurations, complicating inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bicycle Wheels Market |
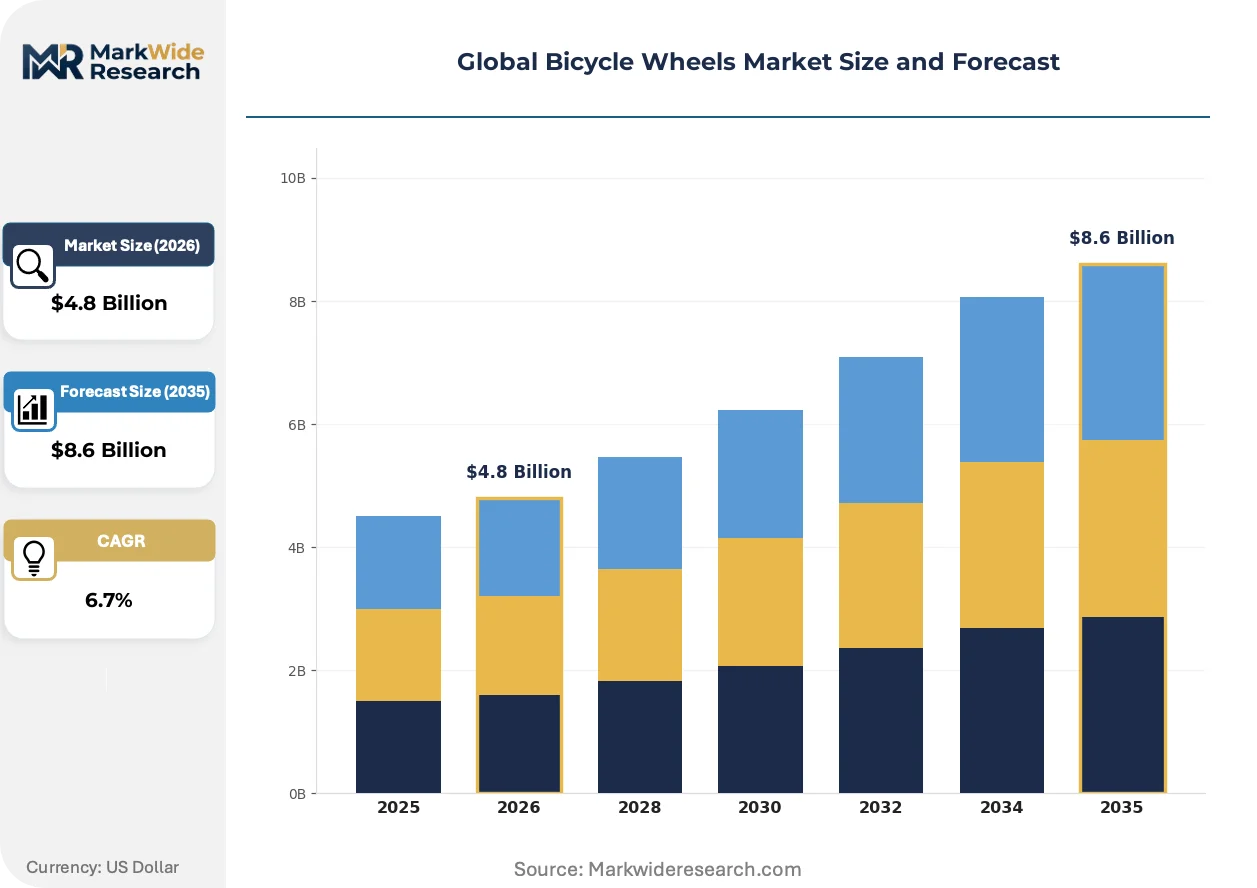
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alloy Wheels, Carbon Fiber Wheels, Steel Wheels, Aluminum Wheels, Magnesium Wheels Technology: Tubeless, Clincher, Tubular, Spoked, Disc, Solid Application: Road Cycling, Mountain Biking, Touring, BMX, Commuting, Track Racing Customer Type: OEM Manufacturers, Aftermarket Retailers, Bicycle Rental Services, Professional Cyclists |
| Companies Covered | Shimano, Campagnolo, DT Swiss, Fulcrum Wheels, Zipp (SRAM), Mavic, ENVE, Hunt Bike Wheels, Easton Cycling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bicycle Wheels Market Emerging Trajectories
Automated fiber placement and robotic nipple tensioning are compressing unit labor content in wheel assembly while enabling geometric tolerances unachievable through manual layup and truing processes.
Robotic spoke tensioning systems are automating the final truing stage that historically consumed skilled labor hours in wheel assembly facilities. High-volume OEM suppliers in Taiwan are deploying six-axis arms with torque-feedback controllers to achieve sub-0.1 millimeter lateral runout specifications. This automation is compressing per-unit labor costs while reducing warranty claims related to tension imbalance and fatigue failure.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing rim brake track coating reformulations across European distribution channels. Manufacturers are migrating from PTFE-based friction modifiers to ceramic particle-impregnated resins that maintain wet-weather performance without SVHC classification. Road racing wheel lines with rim brake compatibility face the steepest compliance timelines as existing inventory clears distribution.
Direct-to-consumer channel expansion is disintermediating traditional bike shop wheel build services for enthusiast segments with mechanical competency. Brands are shipping pre-tensioned wheel sets with tubeless tape and valve stems installed, capturing margin previously allocated to dealer assembly fees. This pattern is most visible in North American and Australian markets where online purchase comfort and home workshop tool penetration exceed European levels.
Global Bicycle Wheels Market Segmentation
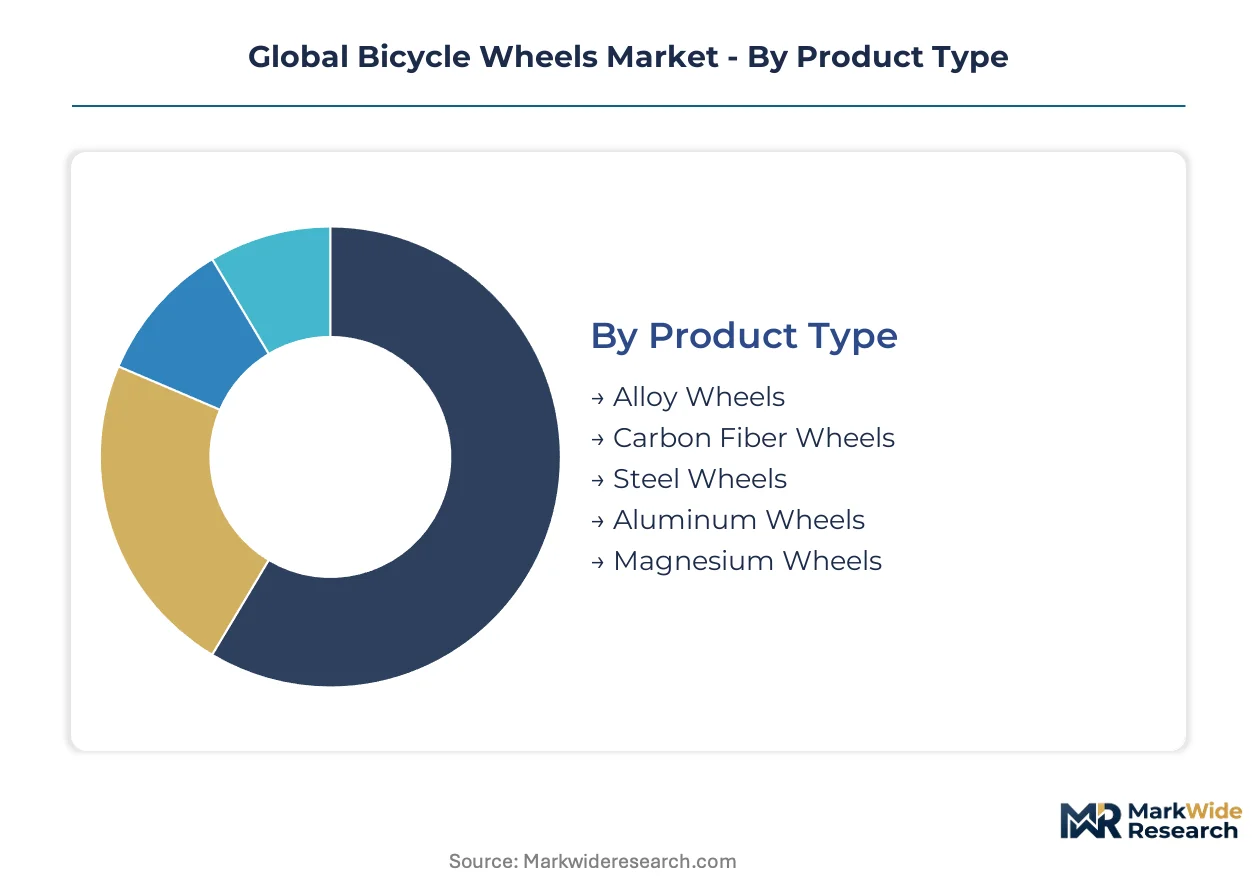
Bicycle wheel segmentation reflects divergent engineering priorities across performance tiers and use cases. Material selection and interface standards determine compatibility with drivetrain ecosystems and brake systems, while application-specific durability requirements shape spoke count and rim depth specifications.
Product Type:
Customization intensity spans from mass-produced alloy variants to bespoke carbon fiber layups with rider-specific stiffness tuning.
- Alloy Wheels:Extruded aluminum rim profiles with welded or sleeved joints dominate commuter and entry-level road segments. Procurement concentrates in Vietnamese and Indonesian foundries serving European OEMs facing REACH compliance deadlines for surface anodization processes.
- Carbon Fiber Wheels:Pre-preg layup rims with variable modulus fiber orientation achieve sub-450 gram weights for climbing-specific applications. Demand clusters in Germany and California where elite amateur racing categories absorb professional-grade rotational inertia reduction.
- Steel Wheels:Chromoly rim constructions with reinforced spoke eyelets persist in cargo bicycle and heavy touring niches requiring load ratings above 180 kilograms.
- Aluminum Wheels:Heat-treated 6061-T6 variants with tubeless-ready bead hooks capture mid-tier mountain bike OEM specifications.
- Magnesium Wheels:Thixomolded rim castings with protective ceramic coatings serve BMX racing applications where impact resistance outweighs corrosion sensitivity.
Leading the category by volume: Alloy Wheels. Expanding most quickly: Carbon Fiber Wheels.
Technology:
Interface standardization maturity separates established formats from emerging configurations still resolving specification fragmentation.
- Tubeless:Hookless rim bed designs with standardized bead seat diameters eliminate inner tubes through liquid sealant integration. German and Dutch municipal procurement now mandates tubeless compatibility for fleet bicycles under EU Green Deal maintenance cost reduction targets.
- Clincher:Traditional bead-retention rims with separate inner tubes retain dominance in touring and developing market segments where roadside repair simplicity outweighs performance optimization.
- Tubular:Glued-on tire constructions with sewn-in inner tubes persist in professional road racing where catastrophic failure modes must not compromise handling.
- Spoked:Tensioned wire spoke lacing patterns with adjustable nipples enable field serviceability across expedition touring and bikepacking applications.
- Disc:Rotor-mount compatible hubs with through-axle interfaces command premium positioning as hydraulic brake adoption accelerates in gravel and cyclocross categories.
- Solid:Polyurethane or airless polymer constructions eliminate puncture risk for dockless shared mobility fleets in urban environments.
Clincher configurations retain installed base dominance. Tubeless systems gain share fastest through OEM specification pull-through.
Application:
Risk exposure and performance intensity vary dramatically across terrain and competitive contexts.
- Road Cycling:Shallow to deep-section rim profiles optimized for aerodynamic drag reduction at sustained speeds above 40 kilometers per hour. German federal commuter subsidies and French corporate cycle-to-work schemes sustain premium wheel replacement cycles.
- Mountain Biking:Wide internal rim widths with reinforced spoke beds accommodate high-volume tires and impact loading from technical descents. Demand concentrates in Colorado and British Columbia trail networks where enduro racing formats drive annual equipment refresh.
- Touring:36-spoke builds with triple-cross lacing patterns prioritize load capacity and field repairability over weight minimization.
- BMX:Compact 20-inch rim diameters with 36-hole drilling patterns withstand repetitive impact from skatepark and dirt jump environments.
- Commuting:Dynamo hub integration and full fender compatibility specifications dominate European urban mobility procurement.
- Track Racing:Fixed-gear specific hub threading with high-flange designs optimized for acceleration out of banked velodrome corners.
Road Cycling generates highest unit value. Mountain Biking demonstrates steepest technology upgrade frequency.
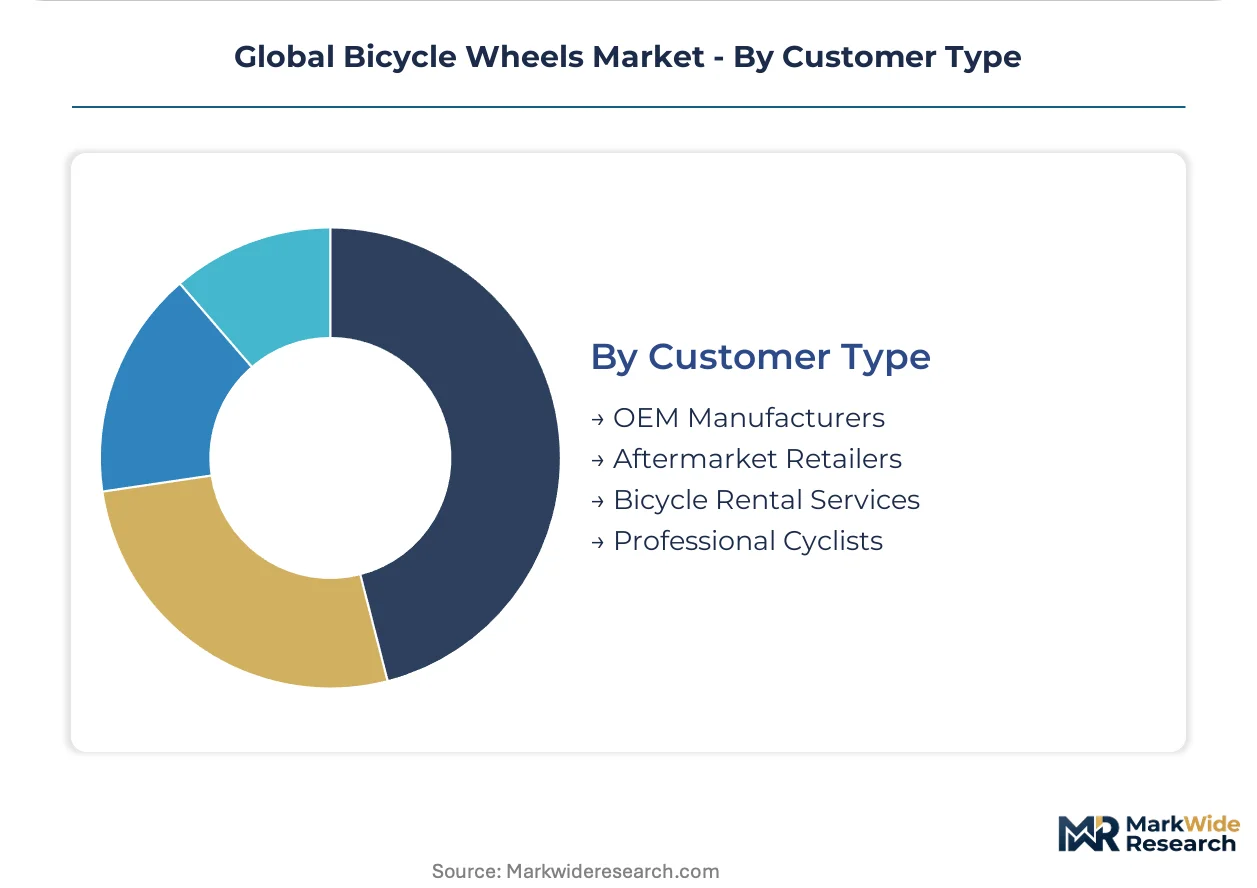
Customer Type:
Purchasing authority and specification control sit at different supply chain nodes across these channels.
- OEM Manufacturers:Frame and complete bicycle assemblers specify wheel sets at bill-of-materials stage, capturing margin through bundled component sourcing. Taiwan-based hub and rim suppliers maintain captive relationships with European and North American bicycle brands.
- Aftermarket Retailers:Independent bike shops and direct-to-consumer platforms serve upgrade cycles and crash replacement demand. North American online penetration exceeds European levels where mechanical service bundling retains importance.
- Bicycle Rental Services:Docked and dockless fleet operators prioritize solid or airless configurations minimizing field maintenance requirements.
- Professional Cyclists:Factory team and sponsored athlete allocations drive halo effect marketing through UCI WorldTour visibility.
OEM Manufacturers command procurement volume leadership. Aftermarket Retailers deliver fastest margin expansion through direct-to-consumer channel growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon fiber precursor feedstock availability in Japan and South Korea underpins rim manufacturing economics across East Asian supply chains. European demand centers on German and Dutch municipal procurement cycles, while North American consumption clusters around Colorado and California trail networks.
Germany
Federal subsidies for commuter bicycles under the National Cycling Plan 3.0 sustain premium wheel replacement cycles in urban mobility fleets. The EU Green Deal mandates tubeless-compatible specifications for municipal bike-share procurements exceeding 500 units. Manufacturing activity concentrates in Baden-Württemberg, where Stuttgart-area engineering firms supply hub dynamo integration systems for trekking and touring wheel builds.
United States
Elite amateur racing categories in Colorado and California absorb carbon fiber wheel technology originally developed for professional peloton use. The EPA exercises indirect influence through TSCA chemical reporting requirements for epoxy resin formulations in domestically distributed rims. Industrial capacity clusters around Indianapolis, where wind tunnel facilities enable aerodynamic profile validation for performance-tier rim development.
Japan
METI energy efficiency guidelines and JIS B 9415 durability standards create certification layers for wheels distributed through domestic OEM channels. The country's national cycling regulator enforces component traceability mandates aligning with circular economy roadmaps. Production gravity sits in Osaka and Nagoya industrial corridors, where precision machining heritage supports high-flange hub shell manufacturing for track and road racing applications.
China
Domestic consumption for e-bike integrated hub systems expands through MIIT industrial standardization programs promoting mid-drive motor compatibility. The national environmental regulator enforces dual carbon goals compliance across carbon fiber precursor manufacturing facilities in Jiangsu and Zhejiang provinces. Layup capacity concentrates in the Yangtze River Delta, where Taicang and Kunshan industrial parks host captive autoclave operations serving European OEM contracts.
Taiwan
Over seventy percent of premium carbon rim layup capacity resides in Taichung and Kaohsiung industrial zones, creating geographic concentration risk for global supply chains. The Bureau of Standards, Metrology and Inspection enforces CNS certification for wheel strength testing protocols. Taichung's precision manufacturing cluster integrates rim molding, hub assembly, and robotic spoke tensioning within vertically coordinated supplier parks serving North American and European bicycle brands.
Global Bicycle Wheels Market Vendor Landscape
Global majors compete with regional champions across material specialization and distribution channel density. The vendor base organizes into three tiers: integrated drivetrain-wheel bundlers, standalone wheel specialists with captive spoke and hub production, and rim-focused fabricators dependent on outsourced assembly. Structural consolidation is accelerating among Taiwanese rim manufacturers with captive pre-preg autoclave capacity, while European and North American brands defend positioning through aerodynamic validation assets and direct-to-consumer channel control.
Within the integrated component tier, Shimano and Campagnolo exemplify bundling strategies that capture margin through dealer network density and drivetrain-wheel compatibility ecosystems. DT Swiss occupies a position among standalone specialists, leveraging geographic origin signaling and in-house spoke manufacturing to sustain pricing power in performance segments. Zipp (SRAM) represents aerodynamic-focused positioning developed through captive wind tunnel access and professional racing visibility.
| Leading Market Players |
|---|
| Shimano |
| Campagnolo |
| DT Swiss |
| Fulcrum Wheels |
| Zipp (SRAM) |
| Mavic |
| ENVE |
| Hunt Bike Wheels |
| Easton Cycling |
| Others |
Supply Flow & Price Mechanics
Robotic spoke tensioning and automated fiber placement are compressing unit labor costs while concentrating production among Taiwanese suppliers with captive autoclave capacity, simultaneously lowering per-unit manufacturing expenses and narrowing the supplier base that controls premium rim output.
Pricing Analysis
Warranty and service bundling separates premium carbon fiber wheel positioning from economy alloy variants, with high-tier suppliers including crash replacement programs and field service networks in their pricing while value-tier offerings strip these protections to hit entry points. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification grade and brand heritage, with JIS B 9415 validation and wind tunnel pedigree commanding substantial markups. Cost compression in the mid-tier is intensifying because REACH compliance reformulation cycles extend R&D timelines without corresponding price recovery. OEM manufacturers exhibit lowest price sensitivity due to bundled component sourcing power, while independent bike shops and direct-to-consumer buyers in North America demonstrate highest elasticity.
Supply Chain Analysis
Containerized freight rates and air cargo premiums from Taichung and Kaohsiung industrial zones to European and North American distribution centers directly impact landed costs for carbon fiber rim sets. Manufacturing gravity draws from Taiwan, China, and Japan, with pre-preg carbon fiber, acrylonitrile feedstock, and precision hub bearings as critical input dependencies. Single-source vulnerability concentrates in Taiwanese autoclave capacity exceeding seventy percent of global premium rim layup, exposing OEMs to seismic disruption and trade route congestion. Distribution runs through vertically coordinated supplier parks in Taichung feeding European bicycle brands, complemented by direct-to-consumer fulfillment centers in North American and Australian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bicycle wheels market sits in a technology-transition phase as tubeless and hookless rim bed designs displace legacy clincher configurations, with EU Green Deal procurement mandates accelerating specification turnover in municipal fleets.
For Market Incumbents: Lock in spoke and hub production through backward integration or long-term supply agreements, defending margin pools against Taiwanese rim manufacturers expanding downstream assembly capabilities. Prioritize REACH-compliant epoxy resin formulation investments to preempt twelve-to-eighteen-month R&D delays that second-tier assemblers cannot absorb. Channel control through dealer network density remains essential as direct-to-consumer platforms disintermediate traditional bike shop wheel build services. For New Entrants and Emerging Players: Direct-to-consumer digital channels enable first-mover positioning in India's tier-two and tier-three cities, where organized retail for premium wheel components remains underdeveloped. E-bike motor-integrated hub convergence in European urban mobility applications offers specification pull-through for reinforced hub shells and larger spoke flange diameters. Partner with local assembly operations under India's PLI scheme to circumvent tariff exposure and establish brand presence before incumbent distribution networks consolidate. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated drivetrain-wheel bundlers seeking aerodynamic validation assets or direct-to-consumer channel control. Long-term viability favors manufacturers with captive wind tunnel access or JIS certification leverage in Asian export markets. Monitor ECHA substance of very high concern listings for epoxy resin hardeners as an inflection indicator for compliance-driven consolidation among mid-cap rim fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spoke Manufacturing | DT Swiss leverages in-house production to sustain pricing power in performance segments. |
| Direct-to-Consumer Channel Expansion | Pre-tensioned wheel sets with tubeless tape installed capture margin from dealer assembly fees. |
| Wind Tunnel Validation Investment | Zipp's Indianapolis facility enables aerodynamic rim profile development unattainable by mid-cap competitors. |
| REACH Compliance Reformulation | Ceramic particle-impregnated resins replace PTFE-based friction modifiers to maintain European market access. |
| JIS B 9415 Certification Achievement | Third-party validation becomes de facto quality benchmark for premium positioning in Asian export markets. |
Methodological Framework
Multi-period observation of carbon fiber precursor pricing, municipal procurement cycles in Germany and the Netherlands, and tubeless technology adoption rates anchored the trend analysis, supplemented by interviews with hub and rim manufacturing executives, OEM procurement directors at European bicycle brands, independent bike shop owners, and fleet operators at dockless mobility services. Secondary validation drew from EU Green Deal implementation documents, ECHA substance registry filings, JIS B 9415 testing protocols, and customs trade data for carbon fiber bicycle components. Bottom-up segment sizing triangulated against top-down macroeconomic indicators for cycling equipment expenditure.
Input-output matrices mapped carbon fiber rim manufacturing cost structures against end-use demand elasticity across road cycling, mountain biking, and urban mobility applications. Segmentation dimensions modeled include material type, technology format, application context, and customer channel, with CAGRs derived from regression analysis of historical procurement volumes and forward projection of regulatory-driven specification shifts. Forecast inputs incorporated MIIT industrial standardization programs for e-bike hub integration and METI durability certification timelines.
The model holds under stable REACH compliance timelines and continued EU Green Deal funding continuity; deviation in ECHA SVHC listing acceleration or Taiwan seismic disruption would shift capacity planning assumptions. Stakeholders should weight assumptions against their own operating context and geographic exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Ambulance Vehicles Market
Vehicle Components
Two Wheeler Footrest Market
Vehicle Components
Locomotive Pantographs Market
Vehicle Components
Trailer Axle Market
Vehicle Components
Refrigerated Trailer Hinges Market
Vehicle Components
Driveline Systems for Electric Vehicle Market
Vehicle Components
Forklift Seats Market
Vehicle Components
Exhaust Manifolds and Downpipes Market
Vehicle Components
Oil Filter Elements Market
Vehicle Components
Car Sunshade Market
Vehicle Components
Truck Axle Market
Vehicle Components
Engine Valve Market
Vehicle Components
Towing Equipment Market
Vehicle Components
Fuel Sensor Market
Vehicle Components
Steering Stabilizers Market
Vehicle Components
Global Car Accessories Market