
 Motor Winding Repair Service Market | 2026-2036
Motor Winding Repair Service Market Size, Share, and Industry Trends Forecast 2026-2036
Motor Winding Repair Service Market Outlook
The capability gap between capital-heavy integrated repair networks and regional independents is rotating competitive dynamics across the Motor Winding Repair Service landscape. Integrated Power Services leverages its nationwide footprint and in-house coil manufacturing to control turnaround times on large industrial jobs. ABB Ltd. anchors its service portfolio with digital diagnostics and predictive maintenance platforms that extend client equipment life. Siemens AG differentiates through OEM-authorized rewind protocols that preserve original efficiency certifications.
Motor winding repair service encompasses the diagnostic disassembly, insulation replacement, coil rewinding, and reassembly of electric motors to restore electromagnetic performance and thermal integrity. The process typically involves class F or H insulation systems rated for 155°C or 180°C operating temperatures, with vacuum pressure impregnation ensuring void-free varnish penetration for extended winding life. Complete overhaul and preventive maintenance services command the deepest margin pools as industrial clients prioritize uptime guarantees and scheduled downtime over reactive emergency repairs. AC motor repair dominates volume given the prevalence of induction motors across manufacturing and HVAC systems, while servo motor repair represents a faster-growing niche driven by precision automation in robotics applications.
The US Department of Energy enforces minimum efficiency standards under 10 CFR 431 that effectively prohibit rewinds degrading motor performance below NEMA Premium thresholds. The EU Ecodesign Directive and accompanying CE marking requirements mandate efficiency class documentation for rewound motors re-entering industrial service. Germany's KBA and France's national energy regulator both audit motor repair facilities for compliance with extended producer responsibility frameworks. Stakeholders must monitor how evolving efficiency thresholds reshape the economic calculus between repair and replacement across their installed base portfolios.
Market Dynamics
Industrial motor fleets are aging past design life as capital discipline freezes replacement budgets, forcing maintenance departments to prioritize rewind quality over speed while efficiency regulations tighten the technical window for acceptable repairs.
Growth Catalysts
- EU Ecodesign Directive:Mandatory efficiency class documentation for rewound motors creates certified repair demand that locks out informal competitors and elevates pricing power for compliant service providers.
- Automotive OEM in-house fleets:Germany's precision engineering and vehicle manufacturing clusters maintain extensive motor populations requiring scheduled overhaul cycles rather than reactive failure response.
- Vacuum pressure impregnation:Advanced varnish penetration systems rated for class H insulation at 180°C operating temperatures extend winding life and justify premium service pricing over basic rewinds.
Market Restraints
- Copper price volatility:Coil rewinding consumes substantial copper conductor stock, and commodity swings compress margin predictability for fixed-price service contracts.
- Regional supplier concentration:Germany's industrial belt hosts dense repair network coverage, while peripheral European markets face thinner qualified capacity and extended logistics lead times.
- NEMA Premium floor effects:US Department of Energy regulations under 10 CFR 431 prohibit rewinds degrading motor performance below efficiency thresholds, eliminating low-cost repair options for older equipment.
Strategic Opportunities
- Servo motor precision automation:Robotics applications in automotive and electronics manufacturing generate faster-growing repair demand than conventional AC induction motor volumes.
- Predictive maintenance convergence:Digital diagnostics platforms integrating vibration analysis and thermal monitoring enable condition-based rewind scheduling that captures margin from uptime guarantees.
- France's extended producer responsibility:National energy regulator audits create compliance-driven repair volume as industrial clients document lifecycle extension to meet environmental accountability frameworks.
Industry Challenges
- Skilled winding technician scarcity:Manual coil forming and insulation placement require years of apprenticeship, and retirement waves in Germany's repair workforce outpace training pipeline output.
- OEM-authorized certification timelines:Siemens AG and ABB Ltd. protocols demand facility audits and equipment verification that delay independent shops from accessing premium rewind contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motor Winding Repair Service Market |
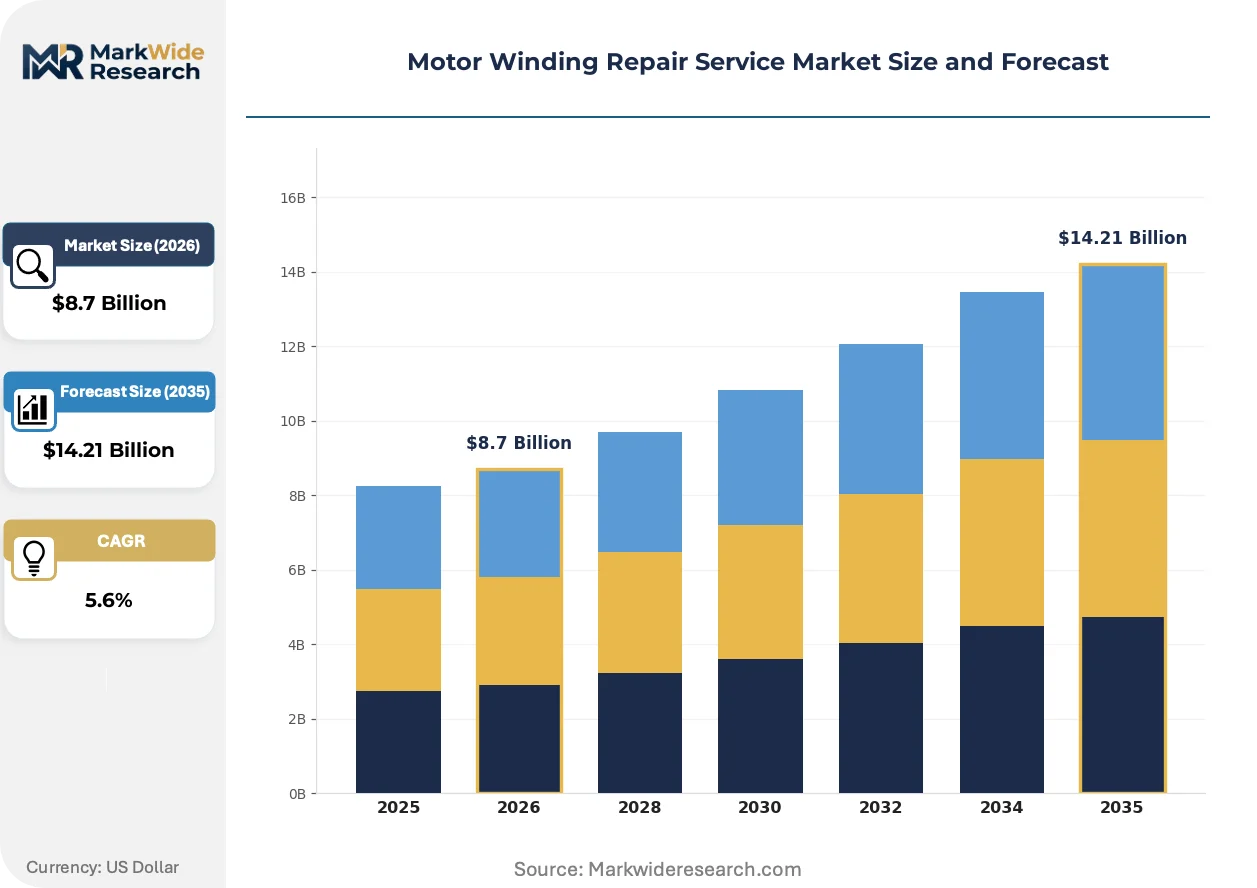
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Complete Overhaul, Partial Repair, Preventive Maintenance, Emergency Service End User: Manufacturing, Energy, Automotive, Marine Motor Type: AC Motors, DC Motors, Stepper Motors, Servo Motors Application: Industrial Machinery, HVAC Systems, Pump Systems, Robotics |
| Companies Covered | Integrated Power Services, Siemens AG, ABB Ltd., Schneider Electric, Regal Rexnord Corporation, Sulzer Ltd., WEG Electric Corporation, General Electric, TECO-Westinghouse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motor Winding Repair Service Market Strategic Shifts
Digital instrumentation is penetrating diagnostic workflows, thermal management materials are advancing rated operating temperatures, and procurement patterns are fragmenting as plant maintenance teams unbundle overhaul services from traditional bundled contracts.
Additive manufacturing is decomposing conventional coil production economics. Selective laser sintering of copper-alloy conductors enables complex winding geometries impossible with drawn wire. Automotive stamping plants in Stuttgart and Wolfsburg are piloting printed coils for servo motor rebuilds. The technology is decomposing inventory-heavy supply chains by producing coils on-demand from digital motor specifications rather than maintaining SKU-dense conductor stock.
REACH chemical restrictions are reshaping insulation material portfolios. ECHA substance of very high concern listings target legacy varnish solvents and resin hardeners common in class F systems. German repair facilities are reformulating toward water-based impregnation chemistries. The regulatory pressure is compressing formulation diversity and consolidating supplier relationships around compliant material platforms.
Maintenance departments are unbundling preventive overhaul from emergency repair contracts. Industrial buyers in France and the Benelux region now specify scheduled downtime windows with uptime penalty clauses rather than time-and-material billing. This behavioral shift is elevating service providers with captive coil manufacturing and guaranteed turnaround commitments over regional independents dependent on external supplier lead times.
Motor Winding Repair Service Market Segmentation
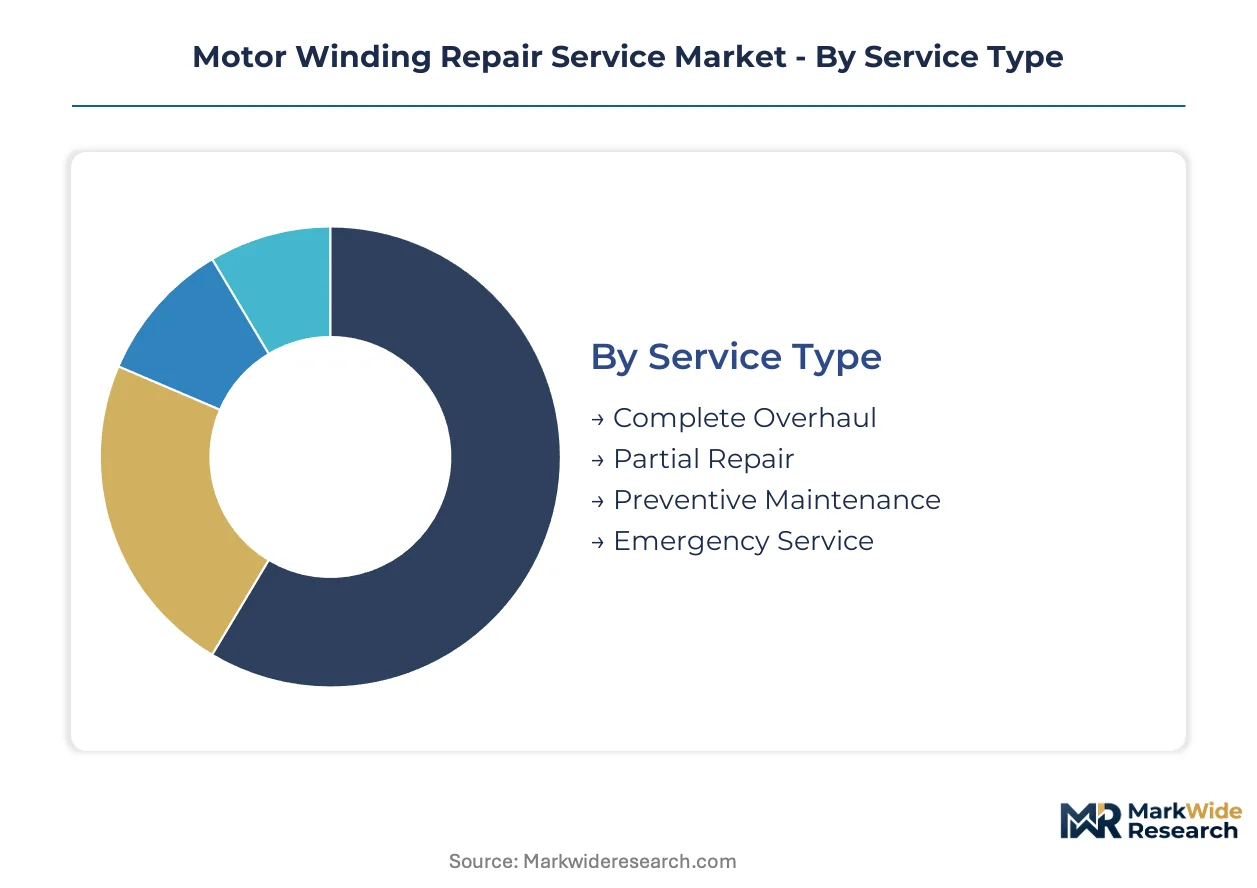
Motor winding repair service segmentation reveals divergent margin structures across service intensities and equipment categories. Technical complexity and regulatory compliance requirements fragment pricing power unevenly across the four primary dimensions.
Service Type:
Complete overhaul and preventive maintenance concentrate in Germany's automotive belt and export-oriented manufacturing clusters, while emergency service remains domestically anchored to regional repair networks.
- Complete Overhaul:Vacuum pressure impregnation with class H insulation systems rated for 180°C operating temperatures restores electromagnetic performance and thermal integrity. Demand clusters at Stuttgart and Wolfsburg automotive stamping plants where scheduled downtime windows carry uptime penalty clauses.
- Preventive Maintenance:Condition-based rewind scheduling integrates digital diagnostics platforms with vibration analysis and thermal monitoring. France's national energy regulator audits drive compliance documentation requirements as industrial clients extend equipment life cycles under extended producer responsibility frameworks.
- Partial Repair:Coil section replacement and insulation spot repairs address localized winding failures without full disassembly.
- Emergency Service:Reactive failure response dominates port cities and remote industrial sites lacking captive maintenance capacity.
Complete overhaul holds the largest share; momentum sits with preventive maintenance as uptime guarantees displace time-and-material billing.
End User:
Cost tier stratification separates capital-intensive in-house fleets from outsourced maintenance dependencies across four verticals.
- Manufacturing:Precision engineering facilities in Germany's industrial belt maintain extensive motor populations requiring OEM-authorized rewind protocols. The EU Ecodesign Directive mandates efficiency class documentation that locks out informal competitors from certified repair contracts.
- Automotive:Robotics applications in electronics manufacturing and vehicle assembly generate expanding servo motor repair demand. Stuttgart OEMs pilot additive-manufactured copper-alloy coils for complex winding geometries impossible with drawn wire.
- Energy:Pump systems and compressor motors in generation and distribution infrastructure operate under FERC efficiency scrutiny in the US.
- Marine:Salt-corrosion exposure and classification society rules drive specialized insulation specifications for propulsion and auxiliary systems.
Manufacturing dominates revenue concentration; automotive climbs fastest on precision automation expansion.
Motor Type:
Volume scale separates mature AC induction technology from emerging precision motor categories with steeper technical barriers.
- AC Motors:Induction motor prevalence across manufacturing and HVAC systems sustains the deepest repair volume pools. NEMA Premium floor effects under US Department of Energy regulations eliminate low-cost rewind options for older equipment.
- Servo Motors:High-resolution feedback systems and compact winding geometries demand specialized technician training. Robotics applications in automotive and electronics manufacturing generate repair demand expanding most quickly than conventional AC volumes.
- DC Motors:Commutator maintenance and brush replacement retain niche demand in legacy industrial equipment.
- Stepper Motors:Positioning accuracy requirements in CNC and 3D printing equipment drive precision rewind specifications.
AC motors anchor volume leadership; servo motors capture the steepest expansion trajectory on automation intensity.
Application:
Customer type fragmentation separates bundled maintenance contracts from unbundled procurement patterns across four equipment categories.
- Industrial Machinery:Extended producer responsibility frameworks in France and Germany require lifecycle extension documentation. REACH chemical restrictions force reformulation toward water-based impregnation chemistries, compressing formulation diversity around compliant material platforms.
- Robotics:Six-axis and collaborative robot joints operate servo motors through continuous duty cycles with minimal maintenance windows. Additive manufacturing of copper-alloy conductors decomposes inventory-heavy supply chains by producing coils on-demand from digital specifications.
- HVAC Systems:Fan and blower motor fleets in commercial buildings face seasonal demand spikes and energy efficiency retrofits.
- Pump Systems:Submersible and process pump motors in water treatment and chemical processing require moisture-resistant insulation systems.
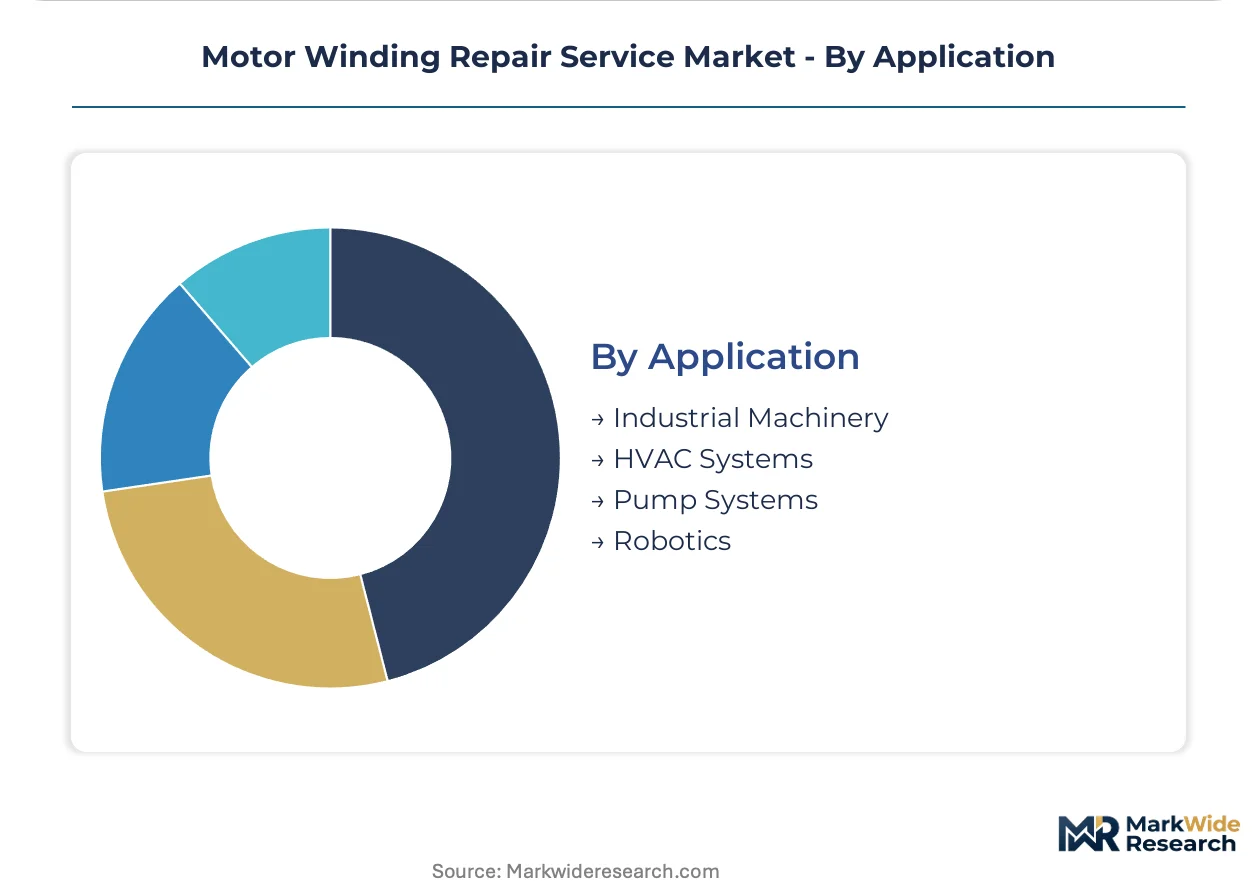
Industrial machinery commands the deepest margin pools; robotics gains share fastest on precision automation penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's automotive belt while peripheral European markets absorb extended logistics lead times and thinner qualified capacity. This asymmetry reflects the density of precision engineering clusters and the regulatory burden of EU Ecodesign Directive compliance documentation.
Germany
Automotive OEM in-house fleets and precision engineering facilities sustain the deepest certified repair demand pools. KBA audits enforce extended producer responsibility frameworks that lock out informal competitors from documented lifecycle extension contracts. Stuttgart and Wolfsburg stamping plants pilot additive-manufactured copper-alloy coils for servo motor rebuilds.
United States
Industrial manufacturing facilities extending equipment life cycles generate steady overhaul volume amid frozen capital budgets. FERC efficiency scrutiny and Department of Energy regulations under 10 CFR 431 prohibit rewinds degrading motor performance below NEMA Premium thresholds. Midwestern automotive and steel belt clusters concentrate demand for integrated repair networks with captive coil manufacturing.
France
National energy regulator audits drive compliance documentation requirements under extended producer responsibility frameworks. Manufacturing clients unbundle preventive overhaul from emergency repair contracts and specify scheduled downtime windows with uptime penalty clauses. Lyon and Grenoble precision engineering clusters prioritize vacuum pressure impregnation services rated for class H insulation systems.
China
Industrial motor fleet expansion and automation intensity generate volume demand across manufacturing and robotics applications. MIIT efficiency standards and GB certification requirements reshape the economic calculus between repair and replacement for older equipment. Yangtze River Delta electronics manufacturing clusters drive servo motor repair demand faster than conventional AC induction volumes.
Japan
High-resolution servo motor populations in robotics and precision automation sustain technical-barrier repair demand. METI industrial efficiency programs and JIS standards documentation requirements elevate certified service provider pricing power over informal competitors. Nagoya automotive and Osaka electronics manufacturing belts concentrate OEM-authorized rewind protocol demand.
Motor Winding Repair Service Market Competitive Environment
Concentration sits with integrated repair networks possessing captive coil manufacturing and nationwide logistics footprints. Regional independents compete on emergency response speed but surrender margin to compliant service providers with documented efficiency certification capabilities. Three archetypes dominate: capital-heavy integrated networks controlling turnaround times, OEM-authorized specialists preserving original efficiency certifications, and digital diagnostics platforms enabling predictive maintenance convergence. Dominant competitive moves include strategic partnerships with automotive OEMs for in-house fleet contracts and backward integration into insulation material supply chains.
Among Germany-based industrial conglomerates, Siemens AG anchors OEM-authorized rewind protocol demand. Swiss-Swedish multinational ABB Ltd. exemplifies digital diagnostics platform integration. US-based Integrated Power Services occupies a position within the capital-heavy integrated network tier. These three represent the archetype spectrum spanning certification authority, predictive technology deployment, and logistics scale.
| Leading Market Players |
|---|
| Integrated Power Services |
| Siemens AG |
| ABB Ltd. |
| Schneider Electric |
| Regal Rexnord Corporation |
| Sulzer Ltd. |
| WEG Electric Corporation |
| General Electric |
| TECO-Westinghouse |
| Others |
Value Chain & Pricing Dynamics
Twenty-one-day coil procurement lead times for class H insulation systems concentrate pricing power with German facilities maintaining captive varnish impregnation lines, while regional independents absorb margin compression from external supplier dependencies. This inventory-velocity asymmetry rewards integrated networks with guaranteed turnaround commitments over time-and-material competitors.
Pricing Analysis
Configured-to-order vacuum pressure impregnation services command 40-60% premiums over standard rewinds without thermal class upgrades. Three-tier pricing structure across OEM-authorized, certified-compliant, and informal service levels segments buyer willingness-to-pay by documentation requirements. Cost compression in the informal tier intensifies as REACH chemical restrictions eliminate legacy varnish formulations. Automotive OEM in-house fleets show lowest price sensitivity due to uptime penalty clauses, while port-city emergency service buyers drive hardest bargaining.
Supply Chain Analysis
Germany and China anchor copper-alloy conductor and insulation varnish production for motor winding repair networks. Coil manufacturing draws from electrolytic copper cathodes, epoxy-novolac resin systems, and mica-based slot insulation materials. Single-source vulnerability concentrates in class H varnish formulations facing ECHA substance-of-very-high-concern listings. Distribution runs through integrated repair networks with regional stocking points, supplemented by independent shops dependent on distributor-held inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial capital expenditure cycles are recovering from trough conditions as manufacturing facilities extend equipment life cycles rather than replacing motor systems. This replacement-deferral dynamic sustains rewind demand through the cyclical upswing.
For Market Incumbents: Consolidate regional independent repair shops to capture certified technician pools and KBA-compliant facility footprints. Backward integration into water-based impregnation chemistry supply secures REACH-compliant material access against formulation consolidation. OEM-authorized protocol investments defend margin position against digital diagnostics platforms eroding time-based service premiums. For New Entrants and Emerging Players: Anchor in France's extended producer responsibility audit pipeline where compliance documentation requirements outpace qualified service provider supply. Robotics servo motor repair offers the most penetrable white-space with steeper technical barriers limiting incumbent density. Digital diagnostics platform partnerships provide go-to-market acceleration without captive coil manufacturing capital requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across predictive maintenance convergence capabilities requiring vibration analysis and thermal monitoring infrastructure deployment. Five-to-ten-year viability favors integrated networks with documented efficiency certification capabilities over regional independents facing technician retirement waves. Watch skilled winding technician training pipeline output as inflection indicator for service capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Insulation Chemistry | REACH-compliant varnish formulation control secures material access against ECHA restriction expansion. |
| Predictive Maintenance Platform Deployment | Digital diagnostics integration with vibration analysis enables condition-based rewind scheduling. |
| OEM-Authorized Certification Investment | Siemens and ABB protocol compliance preserves original efficiency certifications for premium contracts. |
| Additive Manufacturing Coil Production | Selective laser sintering of copper-alloy conductors decomposes inventory-heavy supply chains. |
| Automotive In-House Fleet Partnerships | Stuttgart and Wolfsburg stamping plant contracts anchor scheduled overhaul volume with uptime guarantees. |
Study Parameters
Desk research of customs trade data for copper conductor and insulation material flows, SEC filings from industrial conglomerates, and KBA facility audit records preceded structured interviews with maintenance directors at automotive OEMs, plant engineers at precision engineering facilities, procurement leads at integrated repair networks, and aftermarket service heads at motor manufacturers. Primary fieldwork with winding technicians and facility managers combined with secondary validation against ECHA substance restriction databases and EU Ecodesign Directive implementation reports. Bottom-up service volume estimates triangulated against top-down industrial motor fleet data.
Variance decomposition across service type, end-user vertical, motor technology, and geographic regulatory cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include complete overhaul versus preventive maintenance intensity, manufacturing versus automotive end-use concentration, AC induction versus servo motor technology mix, and Germany versus peripheral European market development stage. CAGRs derived from regression analysis of historical repair volume against industrial production indices and capital expenditure cycles, with explicit modeling of EU Ecodesign Directive compliance threshold effects and REACH chemical restriction timeline impacts.
Material uncertainties — copper price volatility, technician training pipeline disruptions, and ECHA substance restriction scope expansion — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory enforcement consistency and industrial capital discipline persistence. Recalibration cycles align with material shifts in motor efficiency standard thresholds and extended producer responsibility framework adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Antimicrobial Car Care Products Market
Vehicle Maintenance & Aftermarket
Stolen Vehicle Recovery Market
Vehicle Maintenance & Aftermarket
Highway Maintenance Market
Vehicle Maintenance & Aftermarket
E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
US Car Care Products Market
Vehicle Maintenance & Aftermarket
APEJ Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Europe E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Portable Leather Polishing Machine Market
Vehicle Maintenance & Aftermarket
Road Maintenance Service Market
Vehicle Maintenance & Aftermarket
Car and Truck Wash Market
Vehicle Maintenance & Aftermarket
Body Repair Tools Market
Vehicle Maintenance & Aftermarket
Catenary Maintenance Vehicle Market
Vehicle Maintenance & Aftermarket
Car Wash Ancillary Products Market
Vehicle Maintenance & Aftermarket
Global Integrated Vehicle Health Management Market
Vehicle Maintenance & Aftermarket
Car Polisher Market
Vehicle Maintenance & Aftermarket
Europe Automotive Exhaust Aftertreatment Systems Market