
 Ceramic Matrix Composite Disc Brakes (CMC Brake Disc) Market | 2026-2036
Ceramic Matrix Composite Disc Brakes (CMC Brake Disc) Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Matrix Composite Disc Brakes (CMC Brake Disc) Market Insights
High-performance racing teams and military vehicle operators are redrawing procurement priorities for CMC brake discs as thermal durability requirements intensify. Brembo leverages its Italian manufacturing heritage to anchor premium motorsport supply relationships. SGL Carbon sustains carbon-ceramic fiber leadership through captive precursor production. Golden Mountain Ceramic Composites specializes in cost-optimized formulations for expanding Asian aftermarket channels.
Ceramic Matrix Composite Disc Brakes combine silicon carbide or carbon fibers embedded within a ceramic matrix, typically densified through chemical vapor infiltration or melt infiltration to achieve operating temperatures exceeding 1,500°C with minimal thermal fade. The primary purpose is to deliver consistent friction performance under extreme thermal and mechanical stress where conventional cast iron discs deform or degrade. Passenger vehicles and aerospace applications command the dominant value pools, with vacuum infusion and resin transfer molding technologies capturing scale advantages as production volumes climb. Aftermarket providers face margin compression from OEM captive service networks, while military vehicle applications maintain premium pricing through specialized certification requirements.
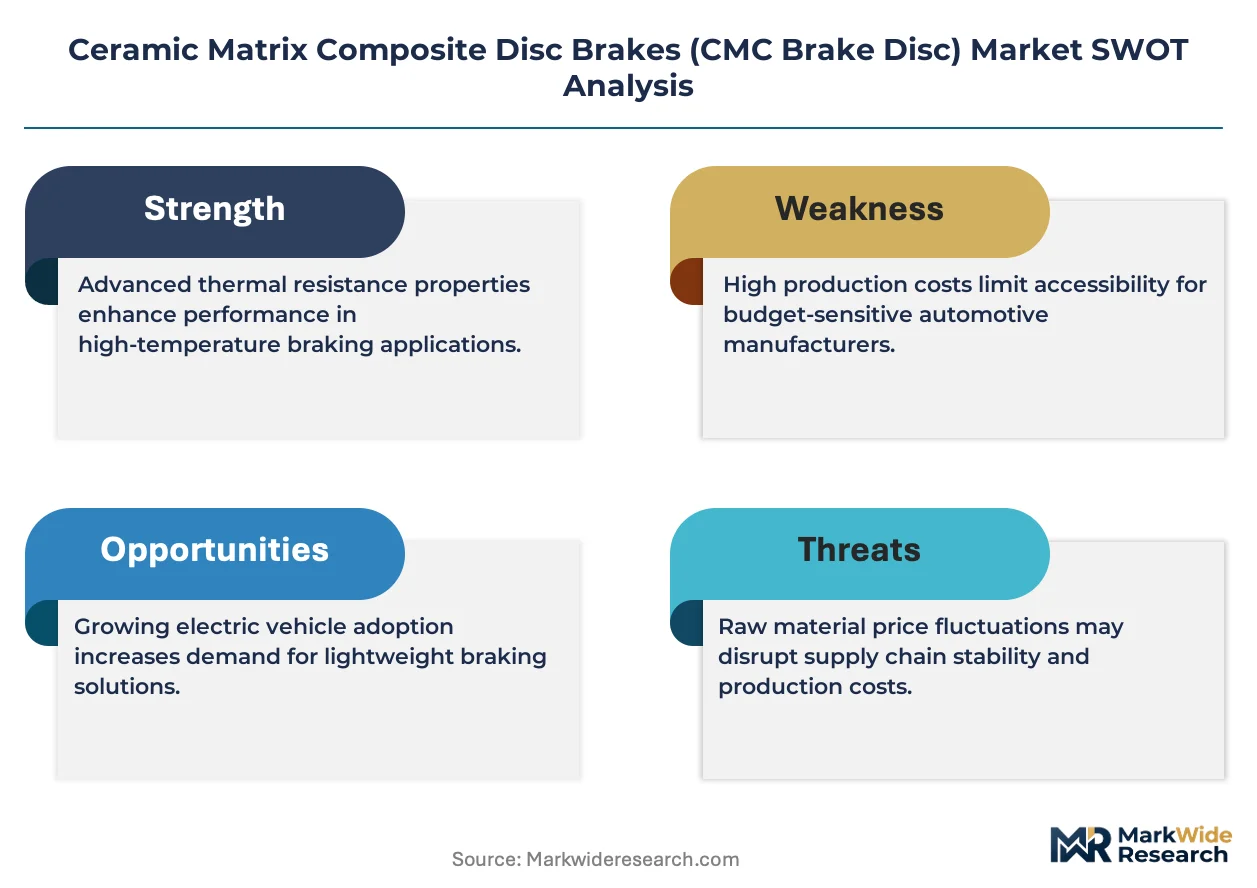
FAA airworthiness standards and Europe's REACH chemical restrictions jointly elevate barrier-to-entry for new CMC brake disc suppliers serving regulated transport sectors. Germany's KBA enforces stringent homologation protocols for automotive braking systems that directly shape product development roadmaps. Stakeholders must monitor evolving military specification harmonization between NATO members and the trajectory of 3D printing qualification standards for flight-critical brake components.
Market Dynamics
Aerospace landing system thermal requirements and Europe's F-Gas Regulation are jointly compressing acceptable material specifications for high-temperature braking components. Suppliers must now validate ceramic matrix composites across wider temperature bands while demonstrating fluorinated gas reduction in densification processes.
Growth Catalysts
- Next-Generation Landing Systems:Commercial aerospace programs are mandating CMC brake discs for nose and main landing gear assemblies to meet extended service intervals and reduced maintenance downtime targets.
- REACH Chemical Restrictions:Europe's tightening substance restrictions on hexavalent chromium coatings are eliminating competing surface treatments and accelerating CMC adoption where ceramic matrices bypass coating requirements entirely.
- Stuttgart-Munich Manufacturing Clusters:Germany's concentrated automotive and aerospace supply chains enable co-located testing, rapid prototyping, and shared R&D infrastructure for brake system validation.
Market Restraints
- Silicon Carbide Precursor Volatility:Petrochemical-derived polycarbosilane prices fluctuate with ethylene and methanol feedstock markets, compressing margin predictability for chemical vapor infiltration processors.
- Japanese Carbon Fiber Concentration:Toray, Mitsubishi Chemical, and Toho Tenax control over seventy percent of aerospace-grade PAN precursor supply, creating single-source vulnerability for CMC fiber reinforcement.
- Cast Iron Thermal Mass Advantage:Conventional gray iron discs retain cost-performance competitiveness in sub-800°C operating envelopes, limiting CMC penetration in mass-market passenger vehicles.
Strategic Opportunities
- Indian Defense Modernization:The country's PLI scheme for specialty materials and indigenous armored vehicle programs create first-mover positioning for CMC brake suppliers qualifying under DGFT defense procurement protocols.
- 3D Printing Qualification:Additive manufacturing of silicon carbide preforms combined with melt infiltration finishing is collapsing lead times for low-volume aerospace brake disc prototypes.
- Aftermarket Channel Digitization:Direct-to-fleet e-procurement platforms for commercial aviation MRO operators are disintermediating traditional distributor networks and capturing higher-margin replacement schedules.
Industry Challenges
- CVI Technician Scarcity:Chemical vapor infiltration furnace operation and pyrolytic carbon deposition control require specialized expertise that outpaces vocational training program output in Germany and the United States.
- FAA TSO-C135 Certification Timelines:Brake disc airworthiness qualification for transport category aircraft extends thirty-six to forty-eight months, locking working capital in pre-revenue development programs.
- Legacy Fleet Retrofit Integration:CMC disc geometry and thermal expansion coefficients mismatch existing cast iron caliper and hub assemblies, requiring complete corner module redesign rather than drop-in replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Matrix Composite Disc Brakes (CMC Brake Disc) Market |
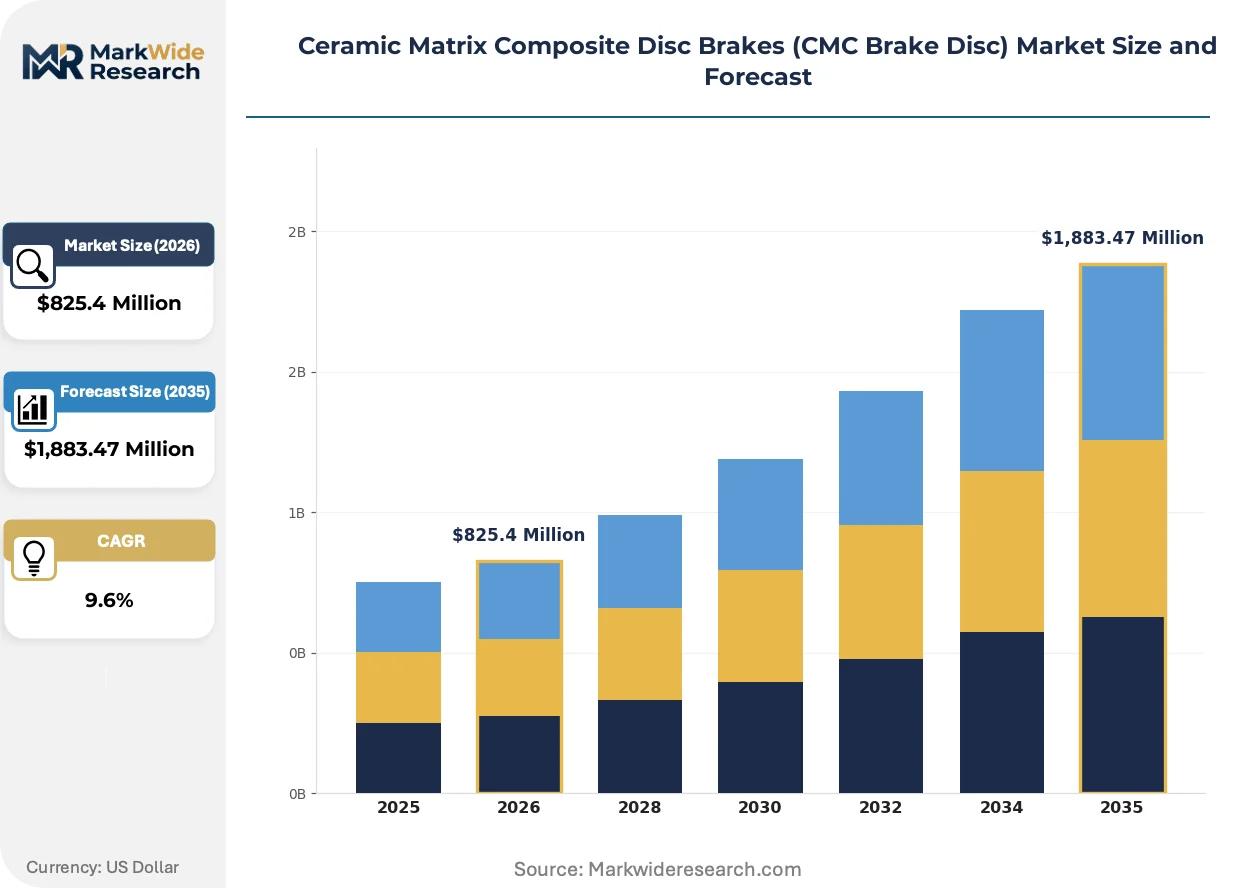
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,883.47 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Vehicles, Commercial Vehicles, Motorcycles, Aerospace Applications End User: OEMs, Aftermarket Providers, Aircraft Manufacturers, Automotive Repair Shops Technology: Vacuum Infusion, Resin Transfer Molding, 3D Printing, Hand Lay-Up Application: High-Performance Racing, Military Vehicles, Industrial Equipment, Public Transport |
| Companies Covered | FERODO, EBC Brakes, Brembo, Golden Mountain Ceramic Composites, CMCMAT, Aisin Seiki, AC Delco, TIANYISHANGJIA, SGL Carbon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Matrix Composite Disc Brakes (CMC Brake Disc) Market Trends and Innovations
Manufacturing process intensification and regulatory chemistry restrictions are actively restructuring how ceramic matrix brake discs achieve density, durability, and cost targets. Three converging developments are compressing incumbent process economics while opening qualification pathways for novel material architectures.
Melt infiltration of silicon into porous carbon-carbon preforms is supplanting multi-cycle chemical vapor infiltration as the dominant densification route for automotive-scale CMC brake production. Tier-1 suppliers in Germany and Italy are retrofitting furnaces for liquid silicon infiltration to cut processing cycles from weeks to days. This compression is enabling price parity with coated carbon-carbon discs in premium passenger vehicle segments while maintaining the thermal stability that disqualifies conventional iron rotors.
Europe's F-Gas Regulation phase-down schedules are forcing brake disc manufacturers to eliminate sulfur hexafluoride and perfluorocarbon process gases from densification and surface treatment operations. Suppliers serving EASA-regulated aerospace programs are validating nitrogen trifluoride alternatives and plasma-enhanced chemical vapor deposition chambers. The regulatory pressure is most acute for French and German facilities supplying Airbus landing system integrators, where 2027 compliance deadlines are accelerating capital deployment into gas abatement infrastructure.
Fleet operators are unbundling brake disc replacement from full landing gear overhaul contracts and negotiating standalone component procurement with direct CMC suppliers. This disintermediation of OEM captive service networks is compressing aftermarket margins but expanding addressable market volume for independent MRO providers. The shift is most visible in North American and Middle Eastern commercial aviation hubs where airline consolidation has concentrated purchasing power and standardized technical specifications across mixed aircraft fleets.
Ceramic Matrix Composite Disc Brakes (CMC Brake Disc) Market Segmentation
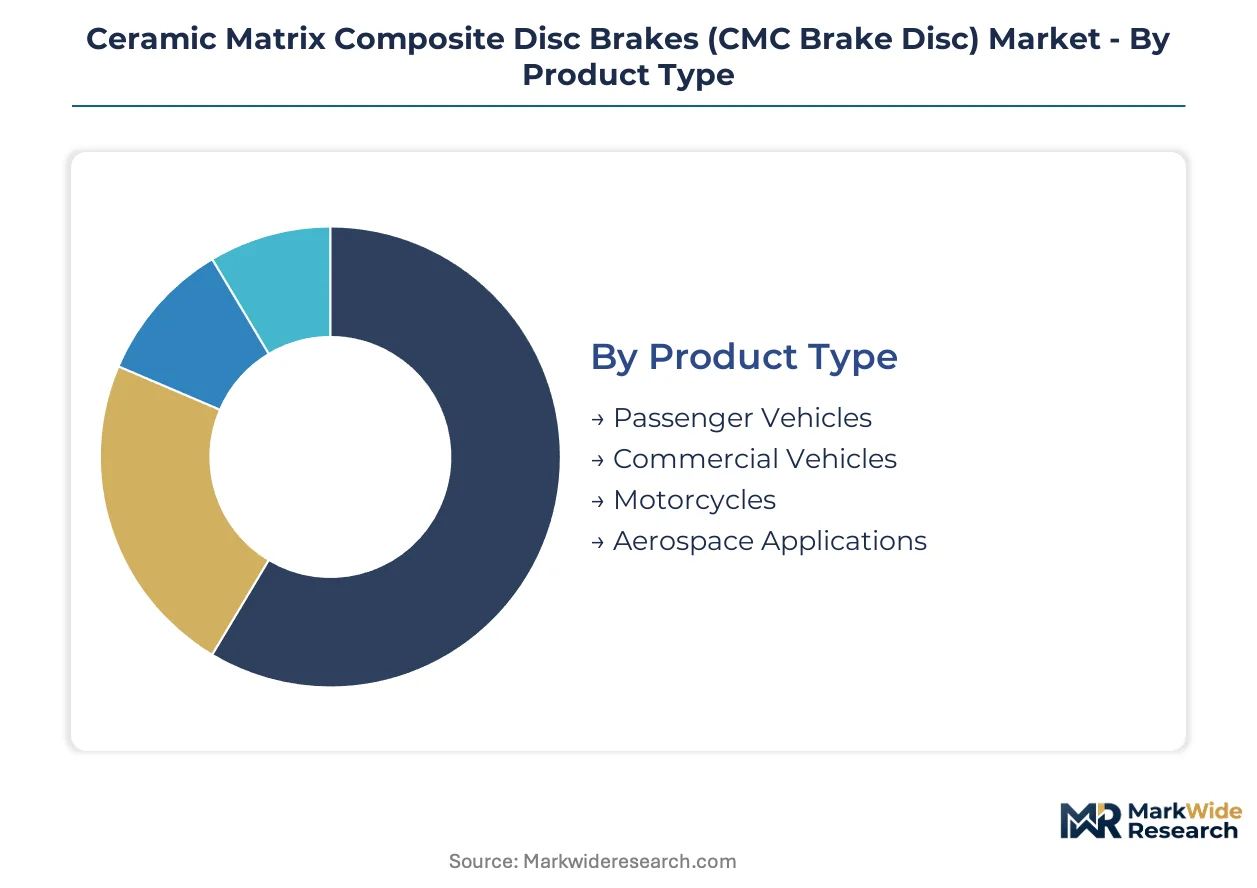
CMC brake disc procurement channels diverge sharply by segment, with aerospace programs routing through airframe integrators while automotive aftermarket flows via distributor networks. Understanding these pathway distinctions shapes pricing power and margin capture across the value chain.
Product Type:
Automotive OEMs dominate volume procurement through Stuttgart and Munich engineering centers, while aerospace channels concentrate in Toulouse and Hamburg landing system integrators.
- Passenger Vehicles:Carbon-fiber-reinforced silicon carbide discs densified through melt infiltration achieve price parity with coated carbon-carbon in premium segments above 400kW thermal loads. German luxury manufacturers anchor specification-setting through KBA homologation protocols.
- Aerospace Applications:Chemical vapor infiltration produces nose and main landing gear discs certified to FAA TSO-C135, with chemical vapor infiltration cycles extending three to four weeks for full densification. Airbus and Boeing landing system mandates concentrate demand in French and German supply bases.
- Commercial Vehicles:Fleet operators spec CMC drums for urban bus regeneration braking above 1,000°C peak temperatures.
- Motorcycles:Supersport and MotoGP categories drive gram-optimized disc development through Brembo Italian supply relationships.
By volume, Passenger Vehicles leads. By growth pace, Aerospace Applications is expanding most quickly.
End User:
Cost tiers separate captive OEM supply from fragmented aftermarket pricing, with military procurement occupying a premium certification tier above commercial aviation.
- OEMs:Automotive and airframe manufacturers lock in multi-year supply agreements with pyrolytic carbon deposition specifications tailored to platform thermal envelopes. Porsche and Ferrari anchor European CMC disc adoption through motorsport technology transfer programs.
- Aircraft Manufacturers:Landing gear integrators at Safran and Collins Aerospace specify disc-stack architectures requiring matched thermal expansion coefficients across carbon-ceramic and steel torque tube interfaces. EASA type certification timelines extend supplier qualification to forty-eight months.
- Aftermarket Providers:Independent MRO operators in Dubai and Singapore challenge OEM captive service networks through direct-to-fleet e-procurement platforms.
- Automotive Repair Shops:High-performance specialist installers handle corner module retrofit rather than drop-in disc replacement.
Revenue concentration favors OEMs. Margin capture is climbing fastest among Aircraft Manufacturers consolidating procurement.
Technology:
Production maturity separates furnace-intensive densification methods from emerging additive routes, with automation levels determining labor cost exposure.
- Melt Infiltration:Liquid silicon wicking into porous carbon-carbon preforms collapses processing from weeks to days, enabling automotive scale economics at German Tier-1 suppliers. The method bypasses perfluorocarbon process gases targeted by F-Gas Regulation phase-down schedules.
- 3D Printing:Additive manufacturing of silicon carbide preforms combined with melt infiltration finishing reduces aerospace prototype lead times from months to weeks. German Fraunhofer institutes and Italian research consortia anchor qualification pathways.
- Vacuum Infusion:Resin transfer molding under reduced pressure achieves fiber volume fractions above 50% for motorsport disc production.
- Hand Lay-Up:Artisan carbon fiber placement persists in low-volume racing and heritage vehicle restoration.
By installed capacity, Melt Infiltration dominates. By investment velocity, 3D Printing is gaining share fastest.
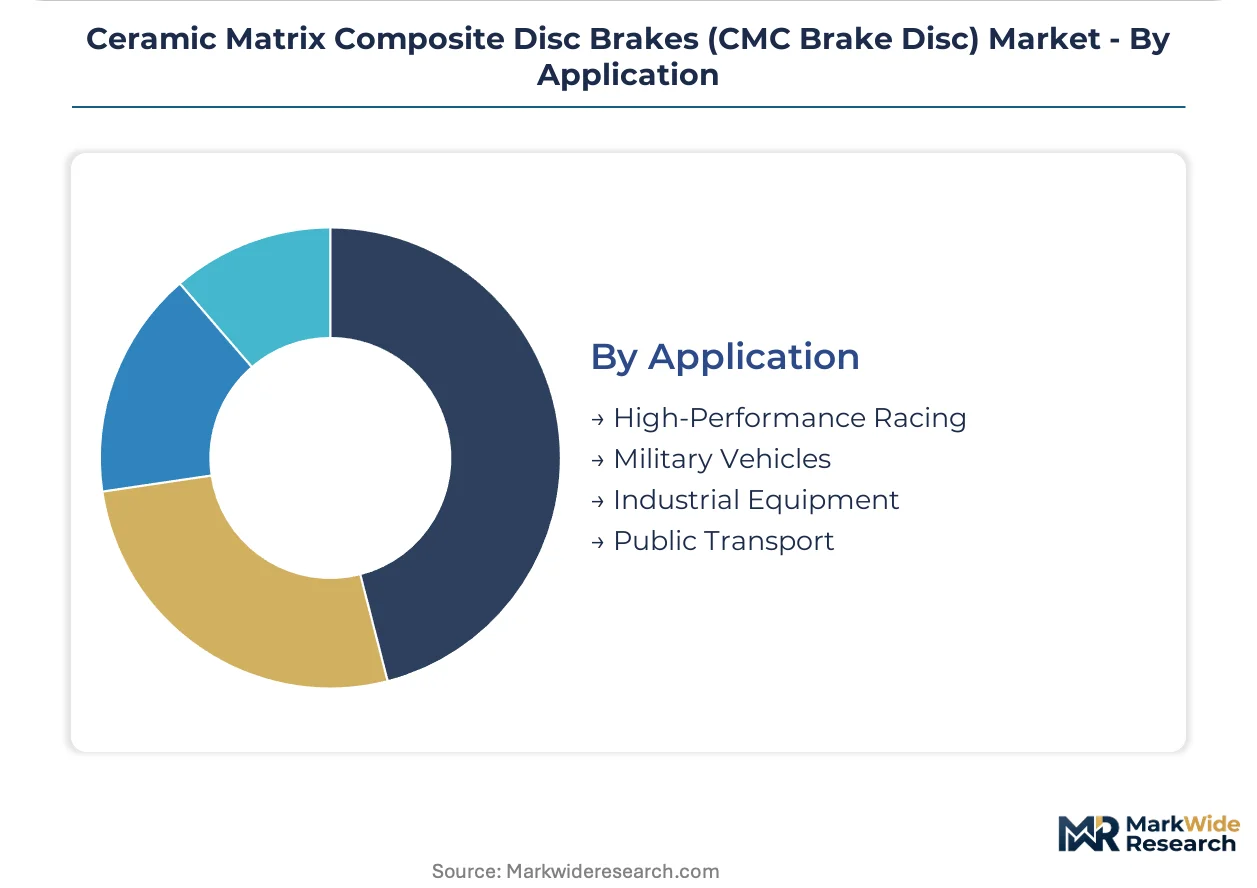
Application:
Customer type fragmentation creates divergent certification burdens, with military specifications demanding NATO harmonization while racing categories prioritize thermal fade resistance.
- High-Performance Racing:Formula 1 and WEC endurance categories mandate CMC discs for brake-by-wire energy recovery systems operating above 1,000°C sustained temperatures. Brembo supplies eight of ten F1 grid teams from its Italian motorsport center.
- Military Vehicles:Armored vehicle programs in India and NATO members require CMC discs for desert and arctic deployment envelopes beyond cast iron thermal limits. DGFT defense procurement protocols in India create qualification pathways for indigenous suppliers.
- Public Transport:Metro and intercity rail operators specify CMC composite brake pads for regenerative braking integration.
- Industrial Equipment:Mining haul trucks and wind turbine yaw brakes expose discs to abrasive contamination cycles.
Unit economics favor High-Performance Racing. Strategic priority is shifting fastest toward Military Vehicles under defense modernization budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports CMC brake disc components to aerospace integrators in France and Italy, while Japan supplies carbon fiber precursors to densification facilities across North America and Europe. Trade corridors concentrate high-value ceramic matrix composites within NATO defense procurement networks and premium automotive supply chains.
Germany
Automotive OEMs and landing gear integrators anchor CMC brake disc procurement through Stuttgart and Munich engineering clusters. KBA homologation protocols enforce stringent validation timelines for automotive braking systems. Chemical vapor infiltration specialists in Bavaria retrofit furnaces for F-Gas Regulation compliance ahead of 2027 deadlines.
United States
FAA airworthiness certification drives demand for transport-category aircraft brake discs, with military vehicle programs adding desert-deployment thermal requirements. FAA TSO-C135 qualification timelines extend thirty-six to forty-eight months for new suppliers. Dallas-Fort Worth and Seattle aerospace hubs concentrate MRO operators unbundling disc replacement from full landing gear overhauls.
France
Airbus landing system mandates concentrate chemical vapor infiltration demand in Toulouse and Le Havre supply bases. EASA type certification requirements shape product development roadmaps for nose and main gear assemblies. French facilities face acute F-Gas Regulation pressure to eliminate sulfur hexafluoride from densification processes by 2027.
Italy
Brembo anchors premium motorsport supply relationships from its Italian manufacturing heritage, serving Formula 1 and WEC endurance categories. Motorsport thermal fade requirements exceed 1,000°C sustained operating temperatures. Emilia-Romagna research consortia validate additive manufacturing pathways for silicon carbide preform production.
India
Defense modernization programs under DGFT procurement protocols create qualification pathways for indigenous CMC brake suppliers. PLI scheme incentives for specialty materials attract first-mover positioning in armored vehicle brake systems. Tamil Nadu and Maharashtra manufacturing corridors develop testing infrastructure for desert and arctic deployment envelopes.
Ceramic Matrix Composite Disc Brakes (CMC Brake Disc) Market Competitive Landscape
Player mix skews toward diversified automotive suppliers and specialized carbon-ceramic fabricators. Market structure concentrates around three tiers: integrated aerospace-landing-system suppliers, premium automotive Tier-1s, and regional aftermarket specialists. Strategic archetypes include captive precursor producers, motorsport-heritage brands, and cost-optimized Asian formulators. Competitive moves center on furnace retrofitting for F-Gas compliance and direct-to-fleet e-procurement platform development.
Among European-integrated suppliers, Brembo and SGL Carbon exemplify divergent archetype positioning. Brembo occupies a motorsport-heritage tier leveraging Italian manufacturing relationships for premium pricing power. SGL Carbon represents captive precursor production with backward integration into carbon fiber supply. Golden Mountain Ceramic Composites anchors cost-optimized formulation development for Asian aftermarket expansion. These three illustrate how geographic specialization and supply chain control separate premium from volume positioning.
| Leading Market Players |
|---|
| FERODO |
| EBC Brakes |
| Brembo |
| Golden Mountain Ceramic Composites |
| CMCMAT |
| Aisin Seiki |
| AC Delco |
| TIANYISHANGJIA |
| SGL Carbon |
| Others |
Pricing and Supply Chain Analysis
Melt infiltration's displacement of multi-cycle chemical vapor infiltration is redrawing supply geography toward Germany and Italy while collapsing price premiums for automotive-grade CMC brake discs. This substitution simultaneously concentrates densification capacity in European Tier-1 clusters and erodes the cost barrier that protected legacy CVI processors in aerospace segments.
Pricing Analysis
Current-generation melt infiltration discs trade at 40-60% below prior-generation CVI aerospace components, while next-generation 3D-printed preforms command prototyping premiums. Three-tier pricing structure separates FAA-certified aerospace grades, KBA-homologated automotive tiers, and unregulated aftermarket segments. Pricing pressure stems from Indian defense procurement mandating indigenous supply at cost-plus benchmarks. Fleet operators in commercial aviation exhibit highest price sensitivity through unbundled disc-only contracts, whereas motorsport teams absorb premiums for gram-optimized thermal performance.
Supply Chain Analysis
Just-in-time silicon carbide precursor delivery dominates German automotive supply chains, while aerospace programs maintain strategic stockpiles of Toray and Mitsubishi carbon fiber to hedge Japanese supplier concentration. Raw material dependencies center on petrochemical-derived polycarbosilane, aerospace-grade PAN precursor, and high-purity silicon metal. Single-source vulnerability in Japanese carbon fiber supply creates structural risk for CMC fiber reinforcement. Distribution runs through Stuttgart-Munich engineering clusters for automotive OEMs and Toulouse-Hamburg landing gear integrators for aerospace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat story where FAA TSO-C135 and EASA type certification timelines create switching costs that lock airframe integrators into qualified supplier relationships. The thirty-six to forty-eight month qualification window erects barriers that compound incumbent advantages.
For Market Incumbents: Compound captive precursor production through backward integration into carbon fiber supply, mirroring SGL Carbon's pyrolytic carbon deposition control. Expand melt infiltration furnace capacity in Bavaria to capture automotive scale economics before 2027 F-Gas Regulation deadlines eliminate sulfur hexafluoride-dependent competitors. Defend against Indian PLI scheme entrants by accelerating DGFT defense qualification partnerships. For New Entrants and Emerging Players: Lead with additive manufacturing qualification for low-volume aerospace prototypes, exploiting collapsed lead times that bypass incumbent CVI cycle advantages. Target Indian armored vehicle programs under DGFT protocols where indigenous supply mandates override incumbent relationships. Pursue direct-to-fleet e-procurement platform partnerships with Dubai and Singapore MRO operators to disintermediate OEM captive service networks. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors furnace-asset owners with F-Gas compliance headroom over legacy CVI operators facing stranded equipment. Long-term viability centers on suppliers controlling both precursor supply and densification technology. Acquisition targets should display captive silicon carbide fiber capability or qualified aerospace brake disc architectures. Watch Indian defense procurement award timelines as inflection indicator for geographic demand shift.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Retrofitting for F-Gas Compliance | German and French facilities eliminate sulfur hexafluoride ahead of 2027 EASA deadlines. |
| Captive Precursor Production Expansion | SGL Carbon's pyrolytic carbon deposition control reduces silicon carbide fiber cost volatility. |
| Direct-to-Fleet E-Procurement Platform | Dubai and Singapore MRO operators unbundle disc replacement from landing gear overhauls. |
| 3D Printing Qualification Investment | Fraunhofer institutes validate additive silicon carbide preform pathways for aerospace prototypes. |
| Indian Defense Procurement Qualification | DGFT protocols under PLI scheme create first-mover positioning in armored vehicle brakes. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with brake system procurement managers at Stuttgart OEMs, landing gear integrators at Toulouse and Hamburg, chemical vapor infiltration furnace operators in Bavaria, and aftermarket MRO directors in Dubai and Singapore. Secondary validation drew from FAA TSO-C135 certification databases, EASA type certificate records, KBA homologation filings, and customs trade data for silicon carbide precursor flows. Bottom-up segment sizing triangulated against top-down aerospace and automotive production forecasts.
Across the analysis window, volume and value outputs reflect segmentation by product type, end user, technology, and application with regional production cluster differentiation. CAGRs were derived from fitted growth curves calibrated to aerospace program delivery schedules and automotive platform refresh cycles. Industry-specific inputs included chemical vapor infiltration furnace capacity utilization rates and melt infiltration adoption curves among German Tier-1 suppliers.
Forecasts assume regulatory continuity in FAA, EASA, and KBA regimes; material policy shifts would require re-modeling qualification timelines and F-Gas Regulation enforcement intensity. Specific risks include Japanese carbon fiber supply disruption, Indian PLI scheme eligibility revisions, and 3D printing qualification standard acceleration. Revision becomes warranted when melt infiltration cost parity thresholds cross premium passenger vehicle adoption tipping points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
France Automotive Parts Aluminium Die Casting Market
Automotive Parts
Global Automotive Hydraulic Brake Market
Automotive Parts
North America Automotive Parts Die Casting Market
Automotive Parts
Thin-Section Ball Bearings Market
Automotive Parts
Global Automotive Muffler Tip Market
Automotive Parts
Gasoline Direct Injection Market
Automotive Parts
Passenger Car Wiper Blade Market
Automotive Parts
North America Gear Market
Automotive Parts
Automotive Brake Shims Market
Automotive Parts
Center and Drag Link Market
Automotive Parts
Automotive Brake Friction Materials Market
Automotive Parts
Wiper Blade Market
Automotive Parts
Variable Valve Timing (VVT) Market
Automotive Parts
X-Arm Type Window Regulator Market
Automotive Parts
Automotive Engine Oil Coolant Market
Automotive Parts
Aluminum Parts Gravity Die Casting Market