
 Fuel Injection Cleaning Machine Market | 2026-2036
Fuel Injection Cleaning Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Injection Cleaning Machine Market Analytics
ISO 9001 quality management certification is unwinding the competitive landscape for fuel injection cleaning equipment manufacturers. Chevron Corporation leverages its petrochemical supply chain to control additive-compatible cleaning chemistry. BASF SE anchors its position through specialized detergent formulations that integrate with ultrasonic systems. 3M Company differentiates via filtration media co-developed with OEM service programs.
A fuel injection cleaning machine restores injector spray patterns by dissolving carbon deposits, varnish, and particulate contamination through pressurized solvent circulation or ultrasonic cavitation at frequencies typically between 25–40 kHz. The equipment serves commercial workshops seeking to resolve rough idle, elevated emissions, and fuel economy degradation without component replacement. Stationary machines dominate installed base among high-volume service centers, while portable units capture fastest growth from mobile repair operators and rural dealerships. Ultrasonic cleaning technology commands premium positioning due to precision restoration of piezoelectric injector nozzles, whereas chemical cleaning retains cost-sensitive fleet maintenance contracts.
EPA emissions standards and California Air Resources Board (CARB) protocols shape product specifications by mandating closed-loop solvent recovery and volatile organic compound containment. The EU F-Gas Regulation and REACH chemical restrictions constrain formulation choices for equipment sold in Europe. ISO 14001 environmental management certification increasingly gates distributor relationships with multinational service chains. Stakeholders must weigh regulatory compliance investments against the margin compression from commodity chemical cleaning alternatives.
Market Dynamics
EPA emissions enforcement and CARB protocols are tightening solvent containment requirements, forcing service centers to retire open-loop chemical systems and adopt closed-loop ultrasonic platforms with volatile organic compound recovery. This regulatory compression is restructuring equipment procurement priorities across commercial automotive workshops.
Growth Catalysts
- Ultrasonic cavitation technology:Piezoelectric nozzle restoration at 25–40 kHz frequencies enables precision cleaning of direct-injection components that chemical baths cannot reach. High-volume service centers in the United States are mandating this capability for fleet maintenance contracts.
- REACH chemical restrictions:The EU F-Gas Regulation and ECHA substance controls are eliminating perchloroethylene-based formulations, creating replacement demand for aqueous and bio-based cleaning systems certified to ISO 14001 environmental management standards.
- Mobile repair operators:Rural dealerships and on-site fleet technicians are driving portable unit adoption, expanding addressable workshop base beyond fixed-bay installations into agricultural and construction equipment servicing.
Market Restraints
- Specialized detergent supply concentration:Additive-compatible cleaning chemistry relies on petrochemical feedstocks controlled by integrated energy majors, exposing independent equipment manufacturers to input cost volatility and formulation licensing constraints.
- Technical limitation of legacy port injection:Older manifold injection systems lack the precision nozzle geometries that justify ultrasonic investment, capping replacement demand in aging vehicle parc segments.
- Substitution by component replacement:Declining injector unit costs in aftermarket channels enable swap-out economics that bypass cleaning protocols entirely for cost-sensitive repair categories.
Strategic Opportunities
- Underpenetrated independent workshops:Germany's Kfz-Innungen network and comparable national garage associations across Southern Europe lack certified cleaning infrastructure, creating distributor expansion targets for ISO 9001-certified equipment lines.
- Hybrid powertrain servicing:Dual-fuel and plug-in hybrid injectors accumulate unique carbon deposition patterns from intermittent combustion cycles, opening specialized application segments beyond conventional gasoline direct injection.
- Outcome-based service contracts:Fleet operators are negotiating emissions-guarantee maintenance agreements that bundle cleaning equipment with performance verification, shifting revenue from capital sale to recurring service annuity.
Industry Challenges
- Ultrasonic technician certification gaps:Cavitation parameter optimization requires training in frequency-power-chemistry interaction that standard automotive curricula omit, constraining effective deployment.
- Closed-loop solvent recovery capex:CARB-compliant containment and distillation systems add fixed cost layers that compress margins for mid-volume service centers.
- OEM service program integration complexity:Filtration media and detergent formulations must validate against proprietary injector warranties, extending certification timelines for aftermarket equipment entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Injection Cleaning Machine Market |
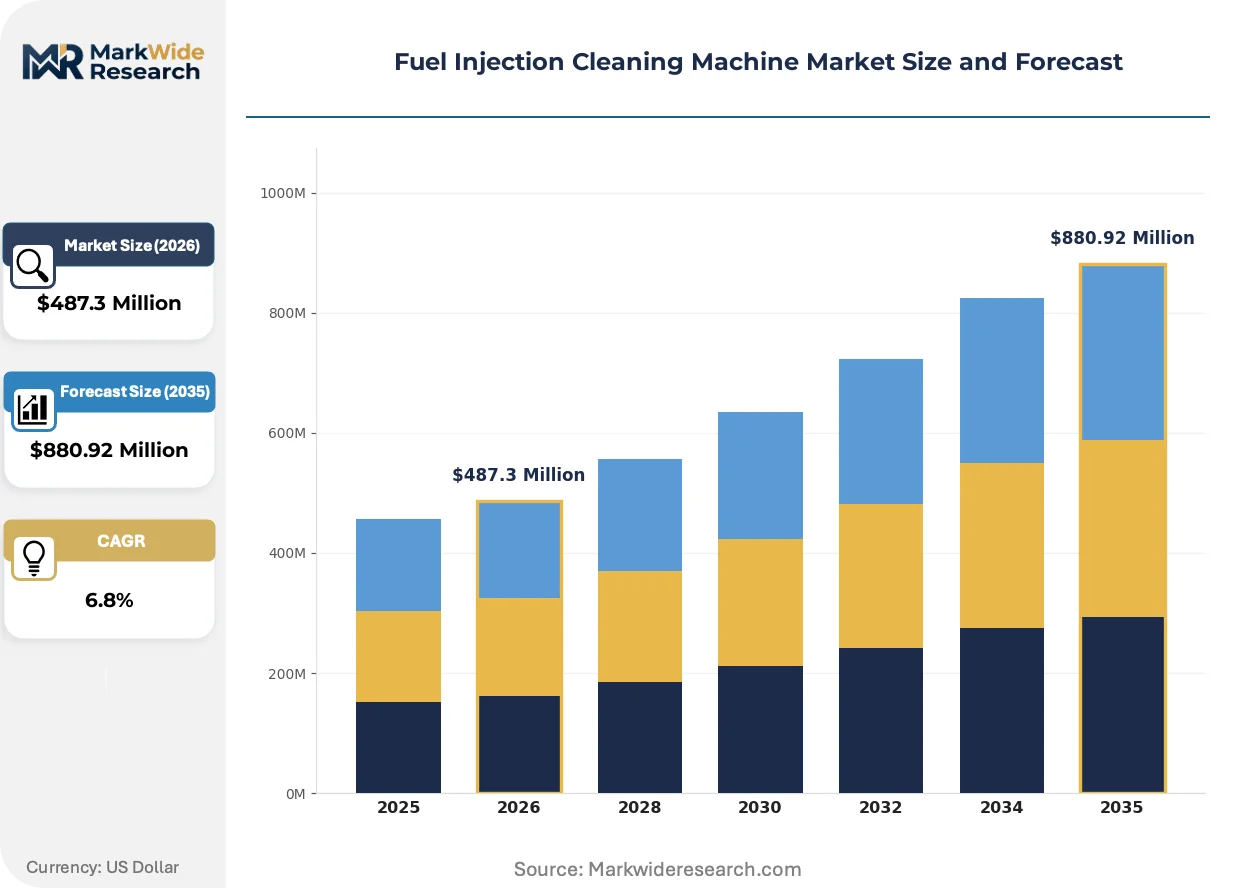
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Stationary Machines, Automated Systems, Manual Cleaners End User: Automotive Repair Shops, Dealerships, Service Centers, Fleet Operators Technology: Ultrasonic Cleaning, Chemical Cleaning, Steam Cleaning, Mechanical Cleaning Capacity: Low Capacity, Medium Capacity, High Capacity, Custom Units |
| Companies Covered | Chevron Corporation, BASF SE, 3M Company, MRCARTOOL, AUTOOL, Liqui Moly, BG Products, Lucas Oil, Royal Purple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Injection Cleaning Machine Market Evolving Landscape
Equipment architecture is pivoting from chemical dependency toward precision mechanical restoration, with digital process control and closed-loop solvent management becoming baseline specifications rather than premium upgrades.
Ultrasonic cleaning platforms operating at variable frequency modulation are supplanting static-pressure chemical circulation as the default restoration method for gasoline direct-injection nozzles. Tier-one automotive service chains in the United States are mandating cavitation-based systems for piezoelectric injector warranty work. This displacement is compressing the addressable market for conventional solvent-recirculation machines to cost-optimized fleet maintenance segments.
California Air Resources Board protocols and EPA National Emission Standards for Hazardous Air Pollutants are mandating zero-discharge solvent containment and volatile organic compound capture above 95% efficiency. Equipment manufacturers must engineer closed-loop distillation and carbon adsorption modules as standard features. The regulatory burden falls heaviest on independent workshops in emissions-nonattainment zones, accelerating consolidation toward certified service networks.
Buyer preference is gravitating toward equipment-as-a-service arrangements that bundle consumables, technical training, and emissions compliance documentation into per-procedure fees. Distributor relationships are displacing direct equipment sales as the primary commercial channel. This reconfiguration is most advanced in United States fleet maintenance contracts, where procurement departments prioritize operational expenditure predictability over capital asset ownership.
Fuel Injection Cleaning Machine Market Segmentation
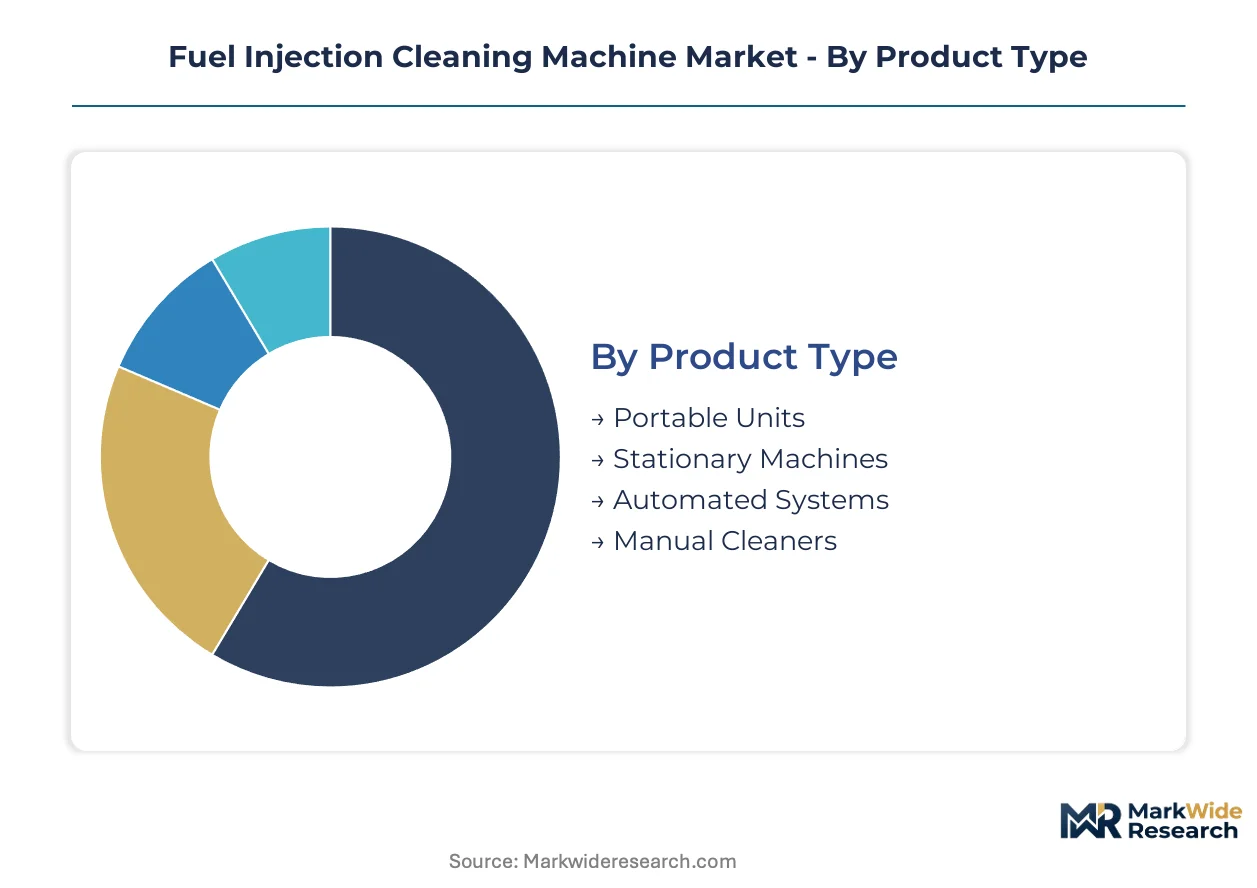
Segmentation in fuel injection cleaning equipment reveals how procurement priorities diverge between high-volume service centers and mobile operators. Margin pools concentrate where regulatory compliance intersects with precision restoration requirements.
Product Type:
Margin concentration sits with equipment that bundles closed-loop solvent recovery and emissions documentation capabilities.
- Stationary Machines:Fixed-bay installations integrate ultrasonic cavitation at 25–40 kHz with automated solvent distillation. United States fleet maintenance contracts mandate these systems for piezoelectric injector warranty work, locking in premium pricing for CARB-compliant configurations.
- Portable Units:Mobile platforms weighing under 50 kilograms enable on-site servicing for agricultural and construction equipment. Rural dealerships in the United States are rotating procurement toward these systems as mobile repair operators expand service territories.
- Automated Systems:Robotic handling and programmable cleaning cycles serve high-throughput environments with minimal technician intervention.
- Manual Cleaners:Entry-level pressure-circulation units retain position in cost-optimized developing markets with limited emissions enforcement.
Stationary machines hold installed capacity. Portable units are rotating up the share rankings.
End User:
Volume concentration follows fleet operator procurement centralization and dealership network consolidation patterns.
- Automotive Repair Shops:Independent workshops in Germany's Kfz-Innungen network lack certified cleaning infrastructure, creating distributor expansion targets for ISO 9001-certified equipment lines with bundled training programs.
- Fleet Operators:Commercial vehicle managers negotiate emissions-guarantee maintenance agreements that shift revenue from capital sale to recurring service annuity, prioritizing per-procedure pricing predictability.
- Dealerships:OEM-affiliated service centers require equipment validation against proprietary injector warranties, extending certification timelines.
- Service Centers:High-volume chains mandate cavitation-based systems as baseline specifications rather than premium upgrades.
Automotive repair shops hold installed capacity. Fleet operators are climbing the fastest.
Technology:
Application differentiation centers on precision requirements for direct-injection nozzle geometries versus legacy port injection systems.
- Ultrasonic Cleaning:Variable frequency modulation at 25–40 kHz enables precision restoration of piezoelectric injector nozzles that chemical baths cannot reach. Tier-one United States automotive service chains mandate this capability for warranty work.
- Chemical Cleaning:Pressurized solvent circulation retains cost-sensitive fleet maintenance contracts where component replacement economics do not justify ultrasonic investment.
- Steam Cleaning:Aqueous-based systems gain position where REACH chemical restrictions eliminate perchloroethylene formulations.
- Mechanical Cleaning:Abrasive and brush-based methods serve heavy-duty diesel injector segments with tolerant nozzle geometries.
Chemical cleaning holds installed capacity. Ultrasonic cleaning is gaining share fastest.
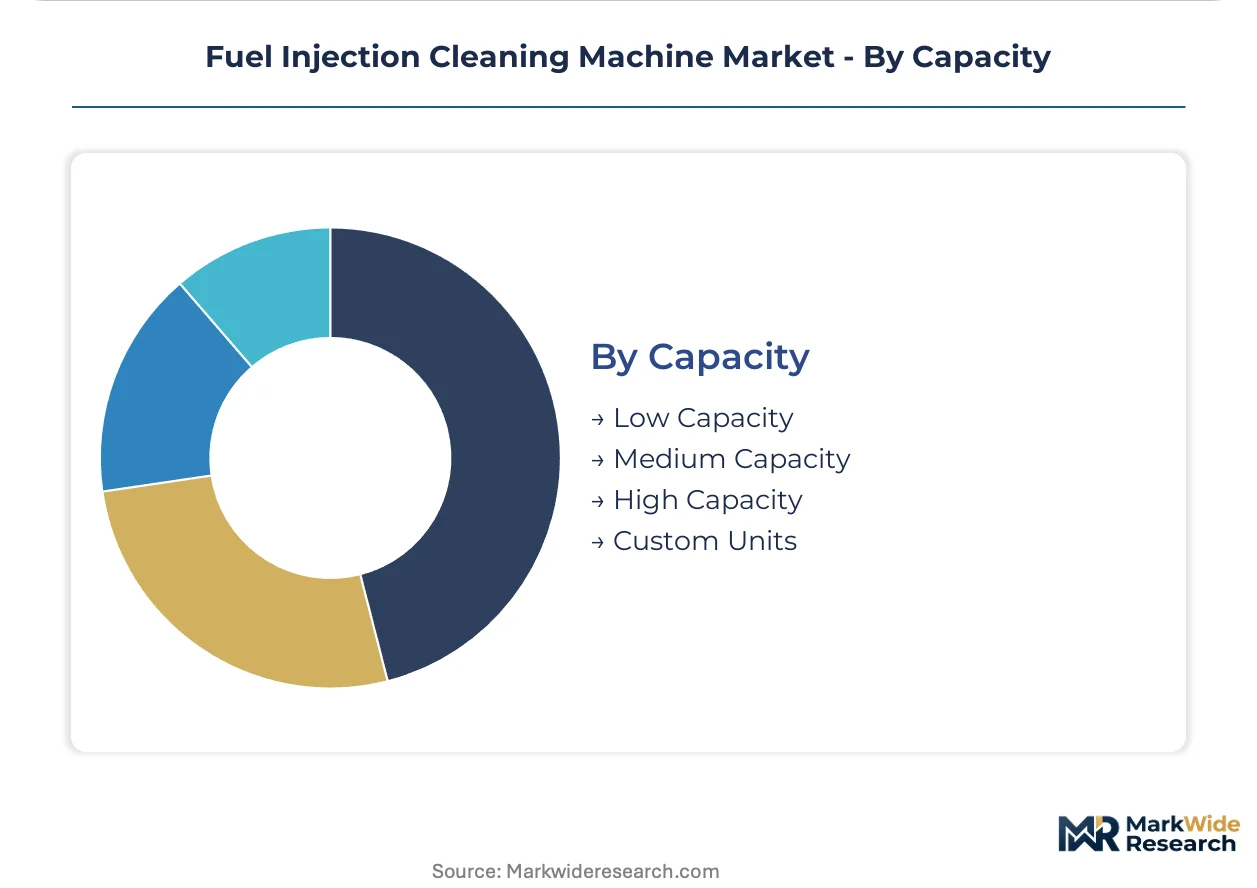
Capacity:
Customer type and throughput requirements determine equipment sizing, with mid-volume installations facing margin compression from regulatory capex burdens.
- High Capacity:Multi-injector parallel processing serves commercial truck fleets and high-volume service centers with continuous throughput requirements.
- Medium Capacity:Single-to-dual injector systems balance throughput with floor space constraints in independent workshops.
- Low Capacity:Entry-level units target mobile operators and rural dealerships with intermittent service demand.
- Custom Units:Specialized configurations address hybrid powertrain injectors with unique carbon deposition patterns from intermittent combustion cycles.
Medium capacity holds installed capacity. Custom units are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement of National Emission Standards for Hazardous Air Pollutants is accelerating equipment turnover across automotive service networks. CARB protocols in California mandate closed-loop solvent containment above 95% efficiency. Fleet operators in emissions-nonattainment zones face procurement pressure to upgrade cleaning infrastructure.
United States
Commercial vehicle fleet managers negotiate emissions-guarantee maintenance agreements that bundle cleaning equipment with performance verification. EPA National Emission Standards for Hazardous Air Pollutants require zero-discharge solvent containment in nonattainment zones. Tier-one automotive service chains in Detroit and Chicago mandate ultrasonic cavitation systems for piezoelectric injector warranty work.
Germany
Independent workshops in the Kfz-Innungen network lack certified cleaning infrastructure, creating distributor expansion targets for ISO 9001-certified equipment lines. REACH chemical restrictions and the EU F-Gas Regulation eliminate perchloroethylene-based formulations. Stuttgart's automotive supplier cluster drives demand for precision restoration systems compatible with direct-injection nozzle geometries.
China
Domestic vehicle parc expansion and tightening MIIT emissions standards create aftermarket service demand. GB standards for volatile organic compound containment shape equipment specifications. Shanghai and Guangzhou service centers prioritize automated cleaning platforms to handle high-throughput direct-injection maintenance.
Japan
METI industrial efficiency programs incentivize precision maintenance equipment adoption across commercial workshops. JIS standards for automotive service equipment establish baseline certification requirements. Nagoya's manufacturing belt concentrates demand for ultrasonic systems serving hybrid powertrain injector servicing.
India
Central Pollution Control Board enforcement of BS-VI emissions standards expands addressable market for certified cleaning protocols. PLI scheme incentives for automotive component manufacturing raise quality expectations for maintenance infrastructure. Maharashtra and Gujarat dealership networks rotate procurement toward portable units for rural service territory expansion.
Fuel Injection Cleaning Machine Market Competitive Landscape
Listed leaders compete with private specialists across formulation control and equipment integration dimensions. The vendor base separates into three tiers: integrated petrochemical majors with captive additive supply, diversified industrial conglomerates with filtration media expertise, and focused equipment fabricators with regional service networks. Dominant competitive moves include backward integration into detergent chemistry and strategic partnerships with OEM service program administrators.
Among diversified industrial conglomerates, 3M Company and BASF SE exemplify archetypes that anchor competitive positioning through materials science capabilities. Chevron Corporation occupies a position representing petrochemical majors that leverage upstream feedstock control. Within the equipment-specialist tier, MRCARTOOL and AUTOOL represent focused fabricators targeting mobile operator and independent workshop segments with portable platform configurations.
| Leading Market Players |
|---|
| Chevron Corporation |
| BASF SE |
| 3M Company |
| MRCARTOOL |
| AUTOOL |
| Liqui Moly |
| BG Products |
| Lucas Oil |
| Royal Purple |
| Others |
Value Network & Pricing Analysis
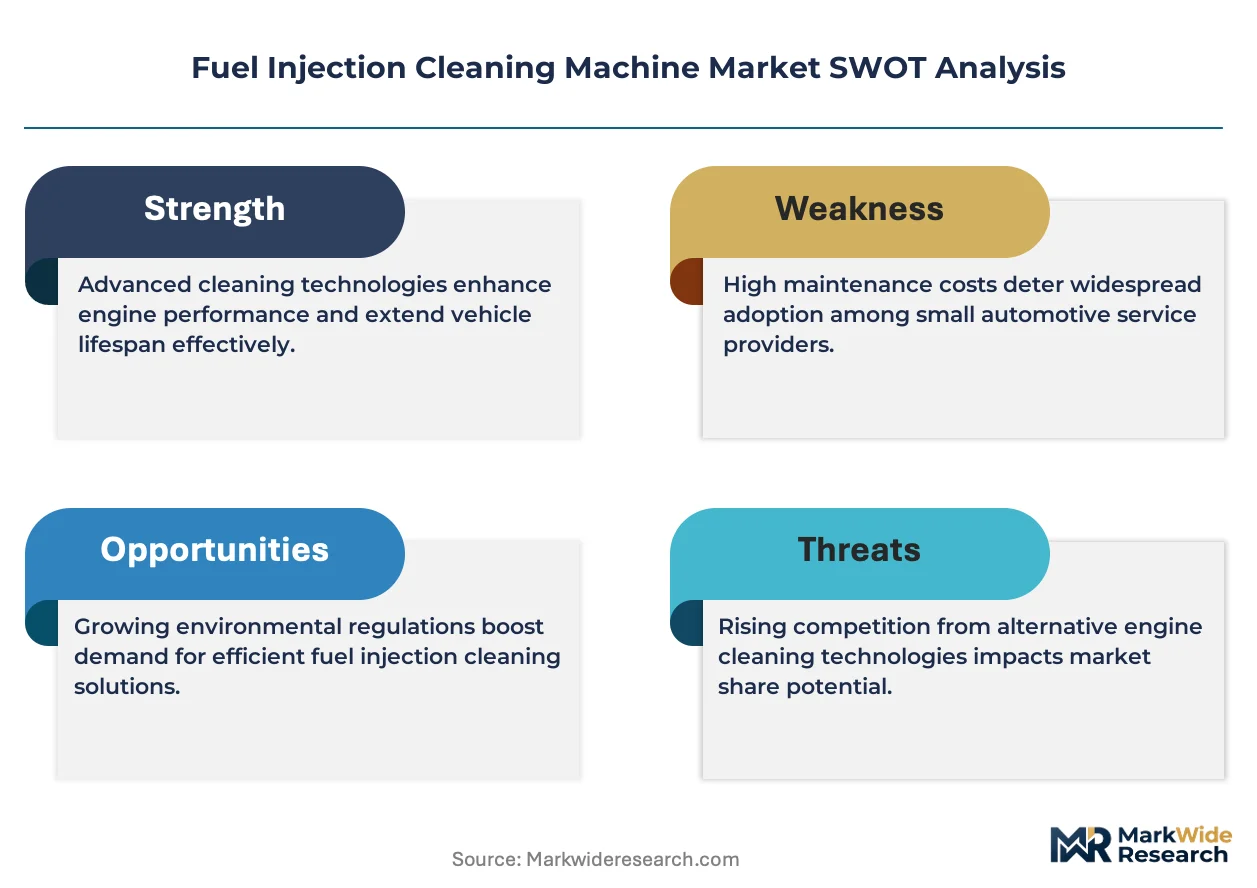
ISO 14001 environmental management certification gates both supplier qualification and price differentiation in fuel injection cleaning equipment, forcing mid-volume service centers to absorb premium positioning for closed-loop solvent recovery systems or exit to commodity chemical alternatives.
Pricing Analysis
Certification level creates the primary spread across equipment tiers, with CARB-compliant ultrasonic platforms commanding premium positioning against open-loop chemical units. Three-tier pricing structure separates ISO 9001-validated systems with bundled training from CE-marked standard configurations and uncertified economy units. Cost compression in the chemical cleaning segment is intensifying because declining aftermarket injector prices enable direct replacement economics. Fleet operators demonstrate highest price sensitivity, while OEM-affiliated dealerships prioritize warranty-compliant specifications over unit cost.
Supply Chain Analysis
Petrochemical feedstock concentration in the United States, Germany, and China anchors detergent formulation supply for ultrasonic cleaning chemistry. Precision piezoelectric transducers and corrosion-resistant tank alloys draw from Japanese and South Korean component specialists. Single-source vulnerability in specialized surfactant chemistry exposes equipment fabricators to input cost volatility. Distribution runs through authorized distributor networks that bundle installation certification and ongoing consumable supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around EPA emissions enforcement and CARB protocols creates durable switching costs for certified equipment installed bases, insulating incumbents from price-based displacement.
For Market Incumbents: Fortify installed base retention by embedding outcome-based service contracts that bundle equipment, consumables, and emissions documentation into per-procedure fees. Deepen captive supply of additive-compatible cleaning chemistry through backward integration into petrochemical feedstocks. Independent equipment manufacturers without formulation control face margin compression from integrated energy majors. For New Entrants and Emerging Players: Anchor in Germany's Kfz-Innungen independent workshop network, where certified cleaning infrastructure penetration remains below comparable Western European markets. Target portable ultrasonic platforms for mobile repair operators expanding into agricultural and construction equipment servicing. Pursue distributor partnerships that bundle ISO 9001 certification support with equipment placement. For Investors and Strategic Acquirers: EPA National Emission Standards for Hazardous Air Pollutants enforcement reshapes the acquisition landscape toward equipment-as-a-service platforms with recurring revenue visibility. Prioritize targets with validated OEM service program integration and established fleet operator relationships. Monitor CARB protocol expansion into additional state jurisdictions as the signal for accelerated equipment replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detergent Chemistry | Chevron Corporation's petrochemical supply chain control demonstrates formulation licensing leverage against independent fabricators. |
| Equipment-as-a-Service Platform Launch | United States fleet maintenance contracts prioritize operational expenditure predictability over capital asset ownership. |
| OEM Service Program Certification | Validation against proprietary injector warranties extends competitive moats for tier-one automotive service chains. |
| Portable Unit Geographic Expansion | Rural dealerships in India and the United States rotate procurement toward mobile platforms for territory coverage. |
| Hybrid Powertrain Application Development | Dual-fuel and plug-in hybrid injectors require specialized cleaning protocols for intermittent combustion carbon deposits. |
Research Methodology
A spread of perspectives from equipment manufacturing executives, automotive service center operators, fleet maintenance procurement managers, and petrochemical formulation specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against EPA enforcement documentation, CARB protocol filings, EU REACH substance restriction updates, and customs trade data for ultrasonic component flows. Bottom-up demand modeling from service center installation counts triangulated against top-down equipment production estimates.
Segmentation dimensions modeled include product architecture, technology type, end-user category, and regional regulatory cluster across the projection horizon. CAGRs derived from equipment shipment trajectories, consumable attach rates, and service contract renewal patterns. Industry-specific forecast inputs incorporated vehicle parc age distributions and direct-injection penetration rates by regional market.
Decision-makers should treat outputs as directional under steady-state regulatory enforcement assumptions; material deviation in EPA or CARB stringency would warrant model refresh. Practitioners should keep alternative scenarios live as REACH chemical restriction timelines and hybrid powertrain adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Japan Automotive Hydraulic Actuators Market
Automotive Parts
Bearing Steel Balls for New Energy Vehicles Market
Automotive Parts
Needle Roller Bearings Market
Automotive Parts
Global Fuel and Oil Filters Market
Automotive Parts
Windshield Lifters Market
Automotive Parts
Automotive Brake Wheel Cylinder Market
Automotive Parts
Electric Coolant Pump Market
Automotive Parts
Automotive Mechanical Control Cable Market
Automotive Parts
Motorcycle Top Box Market
Automotive Parts
Middle East Automotive Lubricants Market
Automotive Parts
Automotive Tire Molds Market
Automotive Parts
Colombia Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Hydraulic Brake Market
Automotive Parts
Car Phone Holder Market
Automotive Parts
Gasoline Direct Injection Market
Automotive Parts
High Level Brake Lamp Market