
 Chassis Sensors Market | 2026-2036
Chassis Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Chassis Sensors Market Outlook
ASIL-D functional safety certification is collapsing into a baseline requirement for chassis sensor procurement across premium and mass-market vehicle platforms. Robert Bosch GmbH leverages captive semiconductor fabrication to control sensor module cost structures from wafer to assembly. Continental AG anchors European OEM supply agreements through integrated braking and suspension sensor portfolios. Sensata Technologies specializes in high-temperature pressure transducers for commercial vehicle air suspension systems.
Chassis sensors are electromechanical transducers that convert mechanical variables—wheel rotation, strut displacement, brake fluid pressure, or steering torque—into electrical signals with millisecond latency for real-time vehicle dynamics control. These devices typically operate across temperature ranges from minus forty to one hundred fifty degrees Celsius and must maintain calibration through vibration profiles exceeding twenty grams RMS. Wheel speed sensors command the largest installed base due to mandatory anti-lock braking and electronic stability control fitment, while optical position sensing captures the fastest expansion as steer-by-wire architectures replace mechanical linkages. Magnetoresistive technology dominates current production volumes, though capacitive sensing gains traction in suspension height measurement where immunity to magnetic interference proves critical.
NHTSA mandates automatic emergency braking on all light vehicles, forcing sensor redundancy and fusion requirements that inflate per-vehicle sensor counts. EPA fuel economy standards and the EU Green Deal's CO2 fleet targets indirectly stimulate chassis sensor demand by accelerating lightweight suspension designs dependent on precise electronic control. ECE R79 steering system regulations in Europe enforce fault-tolerant sensor architectures for lane-keeping and automated parking functions. Stakeholders must monitor how ISO 26262 functional safety revisions and emerging cybersecurity standards reshape qualification timelines and supplier liability exposure.
Market Dynamics
ASIL-D functional safety certification is collapsing into a baseline procurement requirement across premium and mass-market vehicle platforms, compressing supplier qualification timelines and reshaping competitive positioning among chassis sensor vendors.
Growth Catalysts
- NHTSA Automatic Emergency Braking Mandate:The U.S. regulation forces sensor redundancy and fusion architectures that inflate per-vehicle sensor counts across light vehicle programs.
- Steer-by-Wire Architectures:Optical position sensing captures rapid expansion as mechanical steering linkages give way to electronic control systems requiring sub-millisecond latency.
- EU Green Deal CO2 Fleet Targets:The framework indirectly stimulates chassis sensor demand by accelerating lightweight suspension designs dependent on precise electronic control.
Market Restraints
- Semiconductor Supply Concentration:Captive wafer fabrication at dominant suppliers creates barriers for second-tier module assemblers seeking cost parity.
- Raw Material Volatility:Rare earth magnet price fluctuations for magnetoresistive sensing elements compress margin buffers at non-integrated manufacturers.
- Functional Safety Certification Burden:ISO 26262 revision cycles extend product qualification timelines, freezing new entrants from active program bids.
Strategic Opportunities
- Commercial Vehicle Air Suspension:High-temperature pressure transducer demand intensifies as fleet operators retrofit electronic ride height control.
- China Dual Carbon Goals:The national policy framework accelerates electric commercial vehicle production, expanding chassis sensor procurement for regenerative braking systems.
- Cybersecurity Standard Convergence:Emerging ISO/SAE 21434 requirements create service revenue streams for sensor suppliers offering secure over-the-air calibration.
Industry Challenges
- Functional Safety Engineering Talent Scarcity:ASIL-D certified firmware developers command premium compensation, constraining R&D scaling at mid-cap suppliers.
- Legacy Platform Integration Friction:Mechanical-to-electronic sensor interface standards lack harmonization, forcing custom engineering for each OEM architecture.
- Certification Timeline Compression:NHTSA and ECE R79 implementation deadlines outpace traditional 18-month validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chassis Sensors Market |
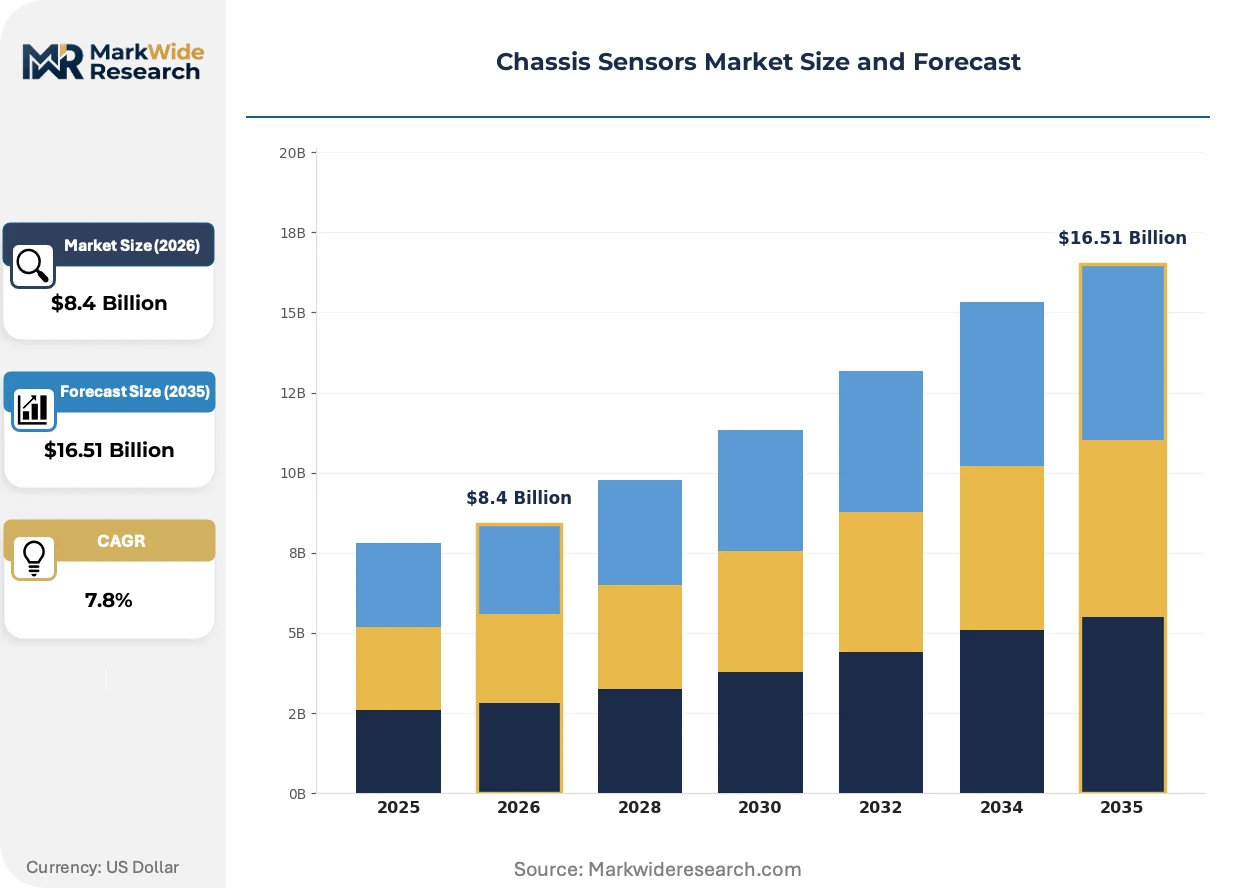
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheel Speed Sensors, Pressure Sensors, Temperature Sensors, Position Sensors Technology: Magnetoresistive, Capacitive, Optical, Ultrasonic End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Application: Safety Systems, Suspension Control, Traction Control, Stability Control |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, Infineon Technologies AG, NXP Semiconductors, Delphi Technologies, Amphenol Corp., Sensata Technologies, Analog Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chassis Sensors Market Strategic Shifts
Capacitive sensing architectures are gaining traction in suspension height measurement where magnetic immunity proves critical, while optical encoders displace Hall-effect devices in next-generation steering systems. Regulatory mandates across multiple geographies are accelerating fault-tolerant sensor designs.
Magnetoresistive wheel speed sensing is displacing variable reluctance technologies in anti-lock braking modules as OEMs pursue higher resolution at equivalent cost structures. Tier-1 braking system suppliers have completed platform transitions on 2024-model-year vehicles. The displacement is compressing royalty revenue streams for legacy inductive sensor patent holders.
ECE R79 steering system regulations in Europe enforce fault-tolerant architectures for lane-keeping and automated parking functions. The mandate requires redundant torque and angle sensing on all new type approvals. German OEMs have advanced compliance deadlines by six months to secure homologation buffer.
Fleet procurement contracts now specify total-cost-of-ownership metrics rather than unit pricing, forcing sensor suppliers to warranty calibration stability across million-kilometer duty cycles. Heavy-truck operators in North America have adopted this model fastest. The shift is disintermediating traditional aftermarket distributors from high-volume commercial vehicle accounts.
Chassis Sensors Market Segmentation
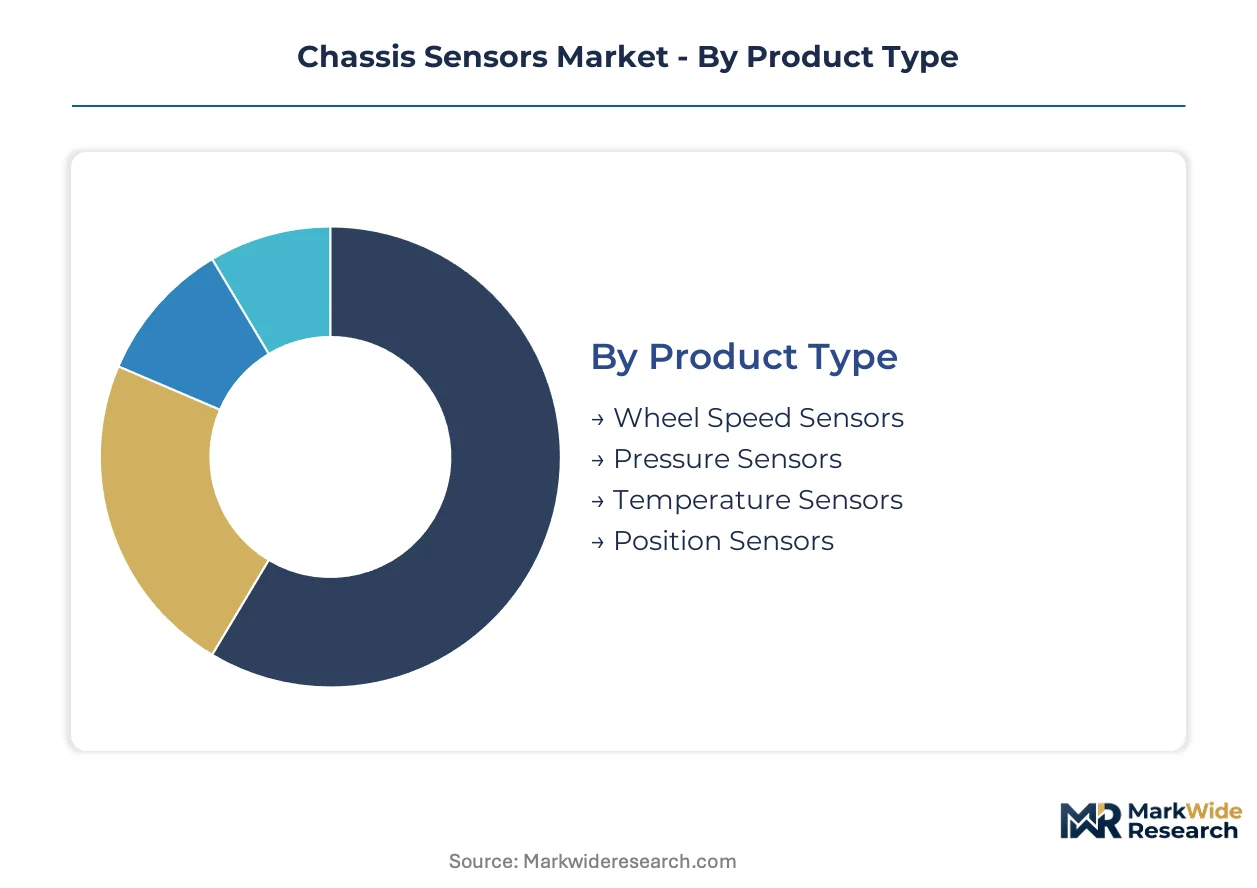
Chassis sensor procurement channels diverge sharply between high-volume OEM contracts and fragmented aftermarket distribution. Understanding these flow patterns reveals where margin compression concentrates and where technical differentiation commands pricing power.
Product Type:
Wheel speed and pressure sensors flow predominantly through captive OEM supply agreements, while position and temperature variants see heavier aftermarket penetration due to calibration service requirements.
- Wheel Speed Sensors:Magnetoresistive transducers measuring rotational velocity with microsecond latency for anti-lock braking modules. Demand concentrates in Germany and China where NHTSA and ECE R79 mandates force redundant fitment on every axle. OEMs bundle these into braking system platforms, freezing out independent distributors.
- Pressure Sensors:Piezoresistive or capacitive elements translating brake fluid, air suspension, or hydraulic line pressure into voltage signals. Fleet operators in the United States specify million-kilometer calibration stability, shifting procurement toward direct Tier-1 contracts with warranty-backed performance guarantees.
- Temperature Sensors:Thermistor-based probes monitoring brake disc, motor winding, or battery thermal states. Commercial vehicle retrofit channels in China absorb rising volumes as dual carbon goals accelerate electric truck deployment.
- Position Sensors:Optical and Hall-effect devices tracking steering angle, suspension travel, or pedal displacement. Steer-by-wire architectures in European premium platforms are displacing mechanical linkages, concentrating demand among integrated chassis system suppliers.
By volume, wheel speed sensors lead. By growth pace, position sensors are expanding most quickly.
Technology:
Cost tiers separate magnetoresistive dominance in mass-market braking from optical and capacitive premiums in next-generation steering and suspension architectures.
- Magnetoresistive:Thin-film magnetic field sensors exploiting anisotropic magnetoresistance for wheel speed detection. Foundry capacity at captive semiconductor suppliers in Germany and Japan constrains second-tier module assemblers seeking cost parity.
- Capacitive:Electrode-based displacement measurement immune to magnetic interference, critical for suspension height sensing near high-current electric drivetrains. China’s electric commercial vehicle production is absorbing capacity from domestic MEMS foundries.
- Optical:Encoded light-beam position detection achieving sub-arcminute precision for steer-by-wire torque and angle feedback. ASIL-D certification requirements extend qualification timelines, favoring incumbent suppliers with existing functional safety portfolios.
- Ultrasonic:Time-of-flight distance measurement for ride height and obstacle proximity, primarily in commercial vehicle air suspension retrofits. North American fleet specifications emphasize million-cycle durability over precision metrics.
Magnetoresistive devices dominate installed base. Optical architectures claim the steepest expansion trajectory as mechanical steering linkages disappear.
End User:
Customer type determines contract structure: OEMs demand system-level integration, while fleet operators increasingly specify total-cost-of-ownership metrics with embedded calibration services.
- OEMs:Vehicle manufacturers procuring sensor modules as subcomponents of integrated braking, steering, or suspension systems. Long-term supply agreements with German and Japanese Tier-1s lock in volume commitments through platform life cycles.
- Aftermarket Providers:Independent distributors and service chains supplying replacement sensors for wear-item replacement. Margin pressure intensifies as fleet operators bypass traditional channels for direct supplier relationships.
- Vehicle Assemblers:Contract manufacturers and regional build-to-order operations requiring configurable sensor kits. Procurement flexibility demands standardized electrical interfaces, which ISO 26262 revision cycles are slowing.
- Fleet Operators:Heavy-truck and bus operators specifying performance-based contracts with uptime guarantees. United States-based logistics companies have adopted this model fastest, disintermediating aftermarket distributors from high-volume accounts.
OEMs command the largest revenue share. Fleet operators are gaining share fastest as procurement centralizes around total-cost metrics.
Application:
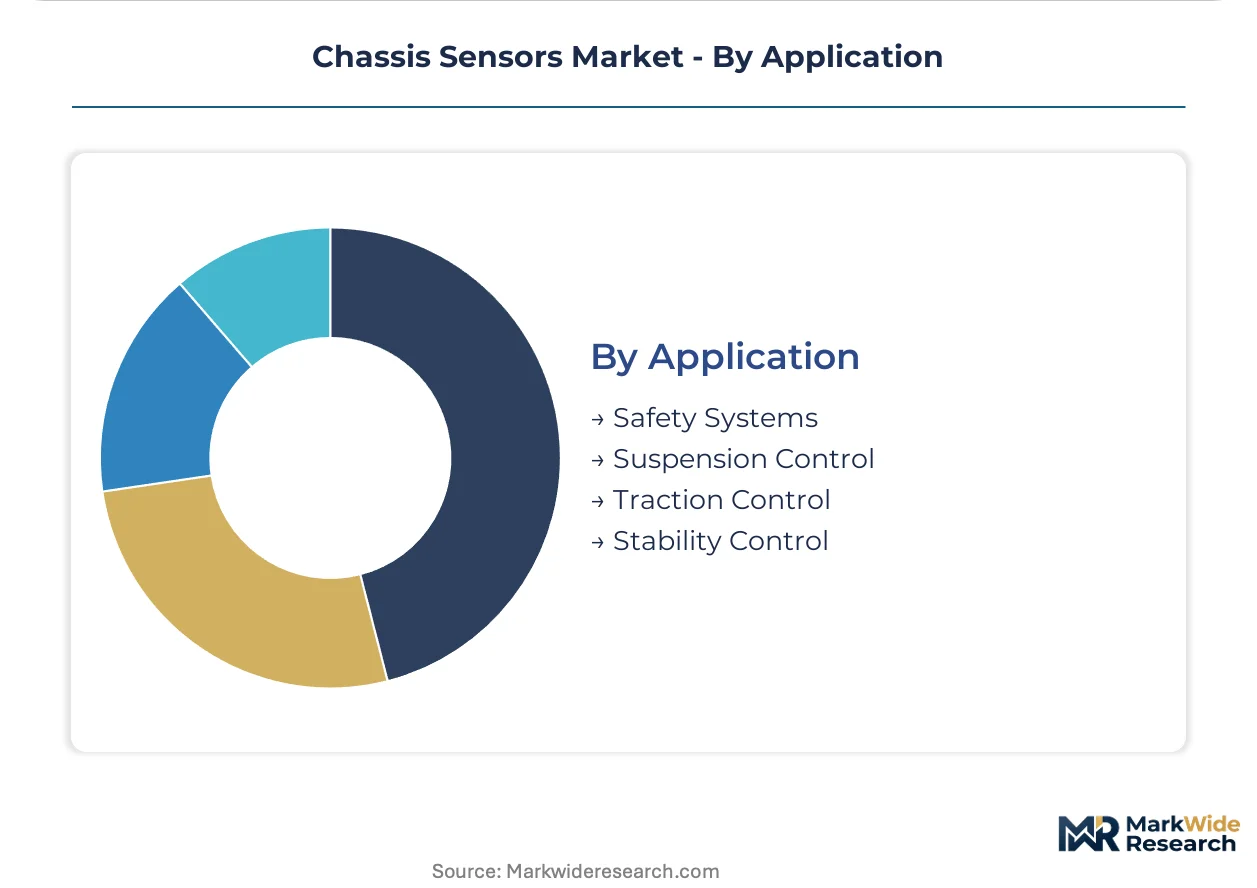
Maturity gradients separate mandated safety systems from discretionary suspension upgrades, with traction and stability control occupying intermediate positions shaped by regional regulatory timelines.
- Safety Systems:Automatic emergency braking, collision avoidance, and pedestrian detection sensor arrays. NHTSA mandates force fitment on all light vehicles in the United States, inflating per-vehicle sensor counts through redundant fusion architectures.
- Suspension Control:Adaptive damping and air ride height systems dependent on continuous position and pressure feedback. EU Green Deal CO2 targets stimulate lightweight suspension designs that trade mechanical complexity for electronic precision.
- Traction Control:Wheel slip detection and torque vectoring support requiring high-resolution speed sensing. Integration with electric drivetrain regenerative braking in China is expanding sensor specification complexity.
- Stability Control:Yaw rate and lateral acceleration monitoring for electronic stability programs. ECE R79 regulations in Europe mandate fault-tolerant sensor redundancy, compressing supplier qualification timelines.
Safety systems lead by unit volume. Suspension control is climbing the fastest as lightweight chassis designs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for magnetic field sensors concentrates in Germany and Japan, constraining second-tier module assemblers in other geographies. China’s electric commercial vehicle build-out is absorbing domestic MEMS capacity for capacitive suspension sensing. United States fleet operators are bypassing aftermarket channels for direct supplier relationships.
United States
NHTSA mandates automatic emergency braking on all light vehicles, forcing redundant sensor fusion architectures that inflate per-vehicle counts. Fleet operators specify million-kilometer calibration stability, shifting procurement toward direct Tier-1 contracts with warranty-backed guarantees. Detroit-based braking system suppliers have locked in long-term supply agreements through platform life cycles.
Germany
ECE R79 steering regulations enforce fault-tolerant torque and angle sensing on all new type approvals, compressing supplier qualification timelines. German OEMs advanced compliance deadlines by six months to secure homologation buffer. Stuttgart and Munich anchor integrated chassis system development, with Tier-1s controlling captive semiconductor fabrication for cost parity.
China
Dual carbon goals accelerate electric commercial vehicle production, expanding chassis sensor procurement for regenerative braking systems. Domestic MEMS foundries supply capacitive sensing elements for suspension height measurement near high-current electric drivetrains. Yangtze River Delta clusters concentrate module assembly for both domestic OEMs and export programs.
Japan
METI industrial policy supports precision sensor manufacturing for steer-by-wire architectures requiring sub-millisecond latency. Chubu and Kansai regions host magnetoresistive thin-film production lines serving global anti-lock braking module demand. Japanese Tier-1s leverage captive wafer fabrication to control sensor module cost structures from substrate to assembly.
South Korea
Seoul Capital Area suppliers specialize in high-temperature pressure transducers for commercial vehicle air suspension retrofits. Domestic OEMs integrate chassis sensors with electric drivetrain regenerative braking systems for export markets. Busan-Ulsan industrial corridors concentrate on optical encoder production for next-generation steering systems.
Chassis Sensors Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with integrated system suppliers controlling premium tiers and specialized component vendors competing on scale. The vendor base separates into three strategic archetypes: captive semiconductor fabricators with backward integration into wafer production, integrated chassis system suppliers bundling sensor modules with braking or steering platforms, and focused component specialists serving aftermarket calibration services. Dominant competitive moves include strategic partnerships for functional safety certification acceleration and geographic expansion into China’s electric commercial vehicle supply chain.
Among German-integrated system suppliers, Robert Bosch GmbH and Continental AG exemplify the captive-fabrication archetype, while Sensata Technologies occupies a position within the high-temperature pressure sensing specialization tier. These three anchors represent distinct competitive vectors: wafer-to-module cost control, integrated platform bundling, and commercial vehicle aftermarket specification leadership.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Infineon Technologies AG |
| NXP Semiconductors |
| Delphi Technologies |
| Amphenol Corp. |
| Sensata Technologies |
| Analog Devices |
| Others |
Value Chain & Pricing Dynamics
Long-term supply agreements with brake system platform suppliers lock in wafer allocation and cost visibility across the forecast window. NHTSA mandates and ECE R79 compliance deadlines compress negotiation cycles, forcing OEMs to trade price flexibility for guaranteed magnetoresistive sensor volumes from captive foundries in Germany and Japan.
Pricing Analysis
NHTSA automatic emergency braking mandates dictate the pricing tier structure across chassis sensor procurement. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified optical encoders from Hall-effect mid-tier units and variable reluctance legacy devices. Price differentiation centers on functional safety certification grade and volume scale commitments. Cost compression in standard-tier magnetoresistive wheel speed sensors is intensifying because captive semiconductor fabrication at Bosch and Continental creates asymmetric margin pressure on non-integrated assemblers. Fleet operators in the United States demonstrate the highest price sensitivity due to total-cost-of-ownership procurement models, while German premium OEMs remain least sensitive given homologation buffer requirements.
Supply Chain Analysis
Germany and Japan anchor magnetoresistive thin-film wafer fabrication for anti-lock braking modules. Taiwan and South Korea supply MEMS foundry capacity for capacitive suspension height sensors. China draws from domestic Yangtze River Delta clusters for electric commercial vehicle sensor assembly. Raw material dependencies include rare earth magnets for anisotropic magnetoresistance elements, silicon substrates for MEMS electrodes, and specialized glass for optical encoder housings. Single-source vulnerability concentrates in German captive semiconductor lines serving European OEM platform programs. Distribution runs through Tier-1 braking and steering system suppliers who bundle sensor modules into integrated chassis platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates durable defensive moats in chassis sensors, as ASIL-D certification timelines and OEM platform lock-in cycles extend beyond typical automotive procurement windows.
For Market Incumbents: Fortify captive wafer fabrication capacity in Germany and Japan to maintain cost parity against emerging Chinese MEMS foundries. Deepen backward integration into rare earth magnet processing to buffer margin pressure from commodity volatility. Prioritize ASIL-D certification portfolio expansion ahead of ISO 26262 revision cycles to freeze out new entrants from 2026-model-year platform bids. For New Entrants and Emerging Players: Anchor in Chinese electric commercial vehicle air suspension retrofits where domestic dual carbon policy accelerates fleet electrification and foreign incumbent presence remains limited. Target high-temperature pressure transducer segments for regenerative braking systems where Sensata's specialization leaves whitespace below their premium positioning. Pursue direct fleet operator relationships bypassing traditional aftermarket distribution channels. For Investors and Strategic Acquirers: Capital is best deployed toward component specialists with existing functional safety portfolios and established Tier-2 relationships to brake system suppliers. The long-term viability window favors suppliers who can bridge mechanical-to-electronic sensor transitions as steer-by-wire architectures displace legacy linkages. Watch for inflection signals in Chinese OEM export program qualification timelines where domestic sensor suppliers gain homologation traction.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Acceleration | Compresses qualification timelines ahead of NHTSA and ECE R79 implementation deadlines. |
| Captive Semiconductor Expansion | Locks in wafer-to-module cost control against rare earth magnet price volatility. |
| Direct Fleet Operator Contracts | Disintermediates aftermarket distributors through million-kilometer calibration guarantees. |
| China Electric Commercial Vehicle Supply Chain Integration | Captures dual carbon policy-driven demand for regenerative braking sensor modules. |
| Optical Encoder Platform Transition | Positions suppliers for steer-by-wire architectures replacing mechanical steering linkages. |
Study Parameters
Initial hypotheses were tested against primary input from Tier-1 braking system procurement managers, OEM platform engineers, aftermarket distributor operations heads, and fleet maintenance directors, then refined through secondary validation. Data synthesis combined regulatory filing analysis from NHTSA and ECE R79 type approval databases, vehicle production registration data, SEC 10-K disclosures from listed sensor suppliers, and customs trade records for rare earth magnet flows. Bottom-up sensor unit demand estimates and top-down chassis electronics spending triangulation converged on market sizing across the analysis window.
Variance decomposition across vehicle class, propulsion architecture, sensor technology type, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level unit economics and content-per-vehicle trajectories modeled throughout the forecast period. Electric commercial vehicle penetration rates in China, steer-by-wire platform rollout schedules in Germany, and NHTSA mandate compliance timelines served as industry-specific forecast inputs.
Material uncertainties — semiconductor foundry capacity constraints, rare earth supply disruptions, and ISO 26262 revision scope changes — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation adherence and OEM platform lifecycle stability. Recalibration cycles align with material shifts in homologation deadlines and electric vehicle production trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Wheel Spindle Market
Vehicle Components
Electric Vehicles Component Market
Vehicle Components
Global Automotive Battery Sensor Market
Vehicle Components
Trailer Brake Controllers Market
Vehicle Components
Wheel Loaders Market
Vehicle Components
Airport Ground Support Vehicle Market
Vehicle Components
High Precision Heavy Load Bearings Market
Vehicle Components
Automotive Wheel Speed Sensor Market
Vehicle Components
Global Undercarriage Components Market
Vehicle Components
South Africa Automotive Carbon Fiber Composites Market
Vehicle Components
Steering Knuckle Market
Vehicle Components
Steering Tie Rod Market
Vehicle Components
Europe Trailer Axle Market
Vehicle Components
China Automotive Carbon Fiber Composites Market
Vehicle Components
Locomotive Drive Shaft Market
Vehicle Components
Electric Wheelbarrow Market