
 Europe Automotive Lightweight Car Market | 2026-2036
Europe Automotive Lightweight Car Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Lightweight Car Market Foresight
OEM direct sourcing channels is reshaping how lightweight materials reach European assembly lines. BMW AG leverages captive supply partnerships for carbon fiber reinforced plastic to secure aerospace-grade material streams. Porsche AG anchors its Zuffenhausen operations with in-house aluminum casting competence. Audi AG competes through multi-material body shops that weld steel, aluminum, and composites within single platforms.
The Europe Automotive Lightweight Car comprises passenger vehicles engineered with reduced mass through advanced material selection and structural optimization, typically achieving 15-30% weight reduction versus conventional steel-intensive architectures to improve energy efficiency and handling dynamics. Aluminum dominates current production volume across European SUVs and sedans due to mature recycling infrastructure and crashworthiness certification. Carbon fiber leads growth within coupe and high-performance hatchback segments where unit economics tolerate premium material costs. Composites capture expanding share in electric vehicle architectures seeking battery mass offset.
EMA vehicle-type approval frameworks and EU Green Deal carbon budgeting enforce fleet-average emissions ceilings that directly mandate lightweighting investment across European OEM product planning. REACH chemical restrictions and CE marking protocols for novel composites govern material qualification timelines and supplier market access. Stakeholders must track how ECHA substance evaluations and evolving end-of-life recycling mandates alter material cost structures and design freedom.
Market Dynamics
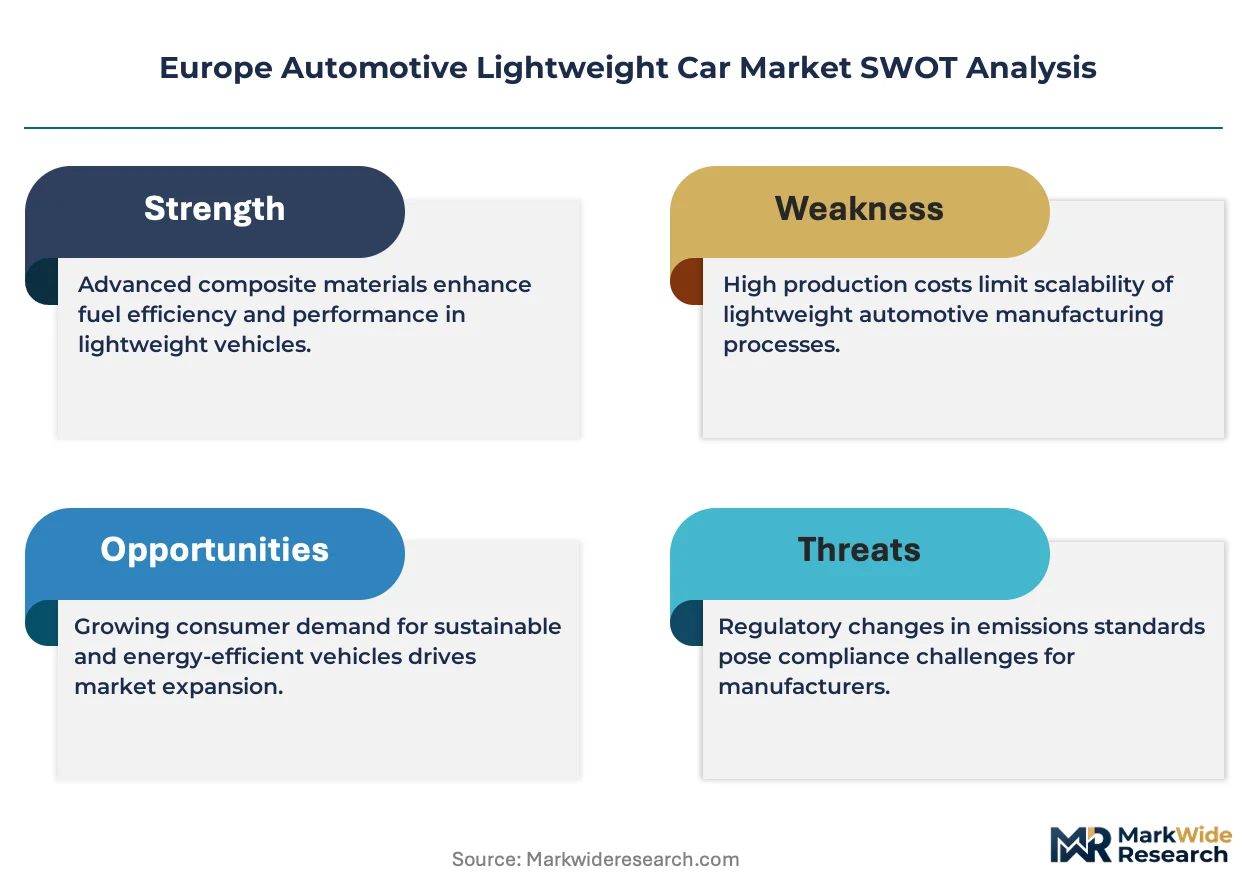
EMA fleet CO₂ enforcement and EU Green Deal carbon budgeting are compressing European OEM product cycles, forcing material substitution decisions upstream into design phases where aluminum and composite architectures displace steel-intensive platforms.
Growth Catalysts
- EMA Fleet Emissions Ceilings:Binding CO₂ targets for 2025 and 2030 compel OEMs to lightweight electric SUVs and sedans to extend range without battery cost escalation.
- Aluminum Recycling Infrastructure:Mature closed-loop systems across Germany and France reduce virgin material dependency and qualify platforms for EU circular economy credits.
- Electric SUV Platform Expansion:Battery mass offset requirements in premium electric architectures drive carbon fiber and multi-material body shop adoption.
Market Restraints
- Carbon Fiber Input Concentration:Aerospace-grade precursor supply concentrates among Japanese and US chemical conglomerates, exposing European OEMs to currency and allocation risk.
- REACH Substance Evaluation Timelines:ECHA scrutiny of novel resin systems and additives extends qualification cycles by 18-24 months, delaying composite platform launches.
- Steel Cost Volatility:Scrap and hot-rolled coil price swings distort total cost of ownership calculations for mixed-material architectures still incorporating high-strength steel.
Strategic Opportunities
- Italian Supplier Ecosystem Expansion:Underdeveloped composite stamping capacity in Turin-Milan corridor offers acquisition and partnership white space for Tier 1 integrators.
- EU Battery Regulation Material Passports:Digital traceability mandates create service revenue streams for lightweight material suppliers able to document carbon intensity and recyclability.
- Thermoplastic Composite Welding Convergence:Laser and ultrasonic joining of carbon fiber-reinforced thermoplastics enables single-platform multi-material construction at cycle times competitive with aluminum stamping.
Industry Challenges
- Multi-Material Joining Skill Scarcity:Shortage of technicians qualified in friction stir welding, adhesive bonding, and rivet-bond hybrid assembly constrains body shop throughput.
- End-of-Life Dismantling Certification:EU ELV directive recyclability targets require new qualification protocols for aluminum-composite joints, complicating platform architecture decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Lightweight Car Market |
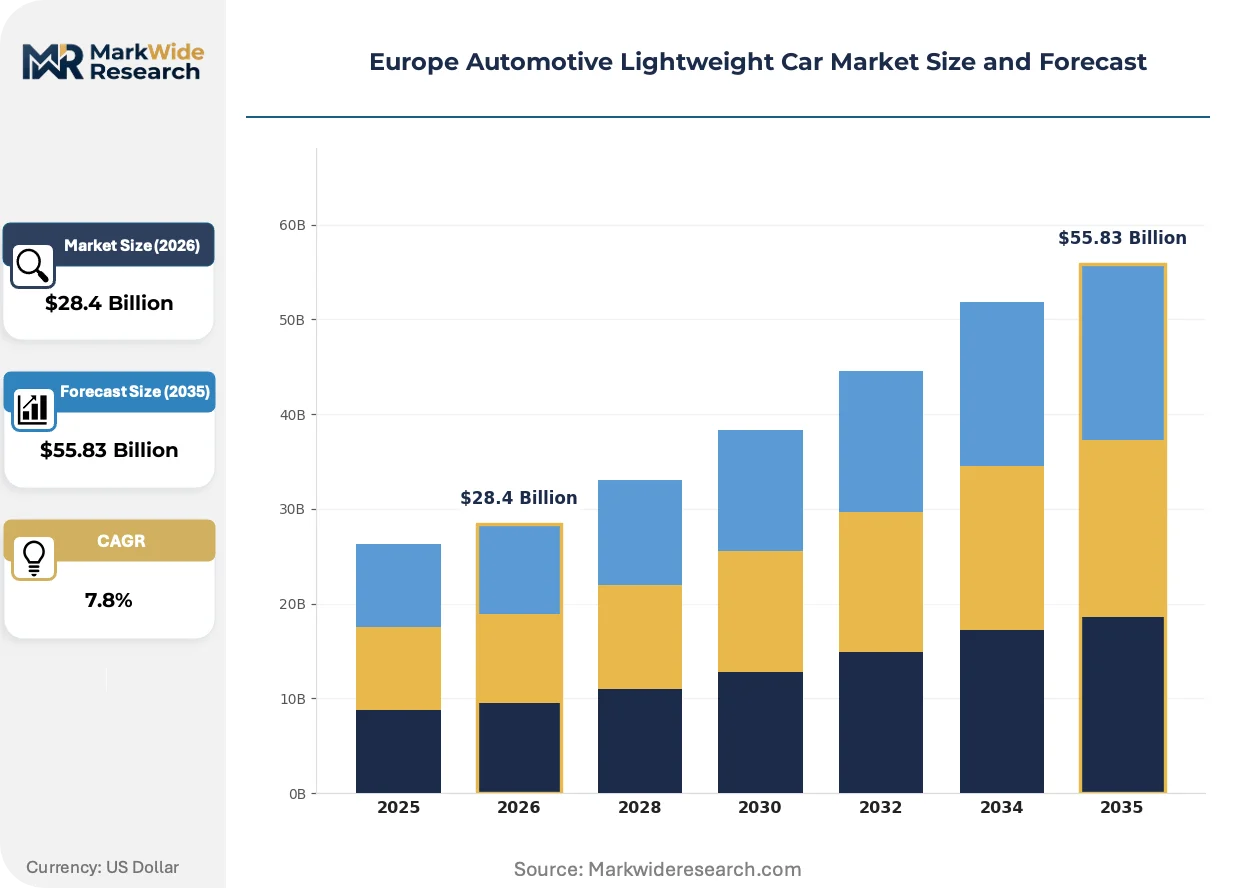
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $55.83 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Aluminum, Carbon Fiber, High-Strength Steel, Composites Vehicle Type: SUVs, Sedans, Hatchbacks, Coupes Production Stage: Design, Manufacturing, Assembly, Quality Control Technology: Advanced Manufacturing, Lightweight Design, Alternative Materials, Automation |
| Companies Covered | Audi AG, Ferrari SpA, Volkswagen AG, Renault Group, Automobili Lamborghini S p A, BMW AG, Porsche AG, Volvo Car Corporation, Daimler AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Lightweight Car Market Shifts & Advancements
European OEM engineering departments are resequencing their material roadmaps around thermoplastic processability and digital twin validation, compressing traditional metal-stamping development cycles.
Continuous fiber-reinforced thermoplastic (CFRTP) tapes enable automated fiber placement in structural battery enclosures and floor pans. BMW and Porsche assembly lines in Germany are adopting these systems for electric platform variants. Conventional thermoset autoclave curing is rendering obsolete for high-volume structural components where cycle time determines line economics.
EU Green Deal carbon border adjustment mechanisms and the CSRD corporate sustainability reporting directive now mandate Scope 3 emissions disclosure across automotive supply chains. Material suppliers must document cradle-to-gate carbon intensity or face exclusion from OEM approved vendor lists. Battery electric vehicle architectures face the steepest compliance burden due to aluminum and lithium supply chain complexity.
Fleet procurement departments at European rental and corporate mobility providers are unbundling residual value guarantees from vehicle acquisition contracts. Lightweight material content and documented recyclability now determine lease rate calculations and secondary market liquidity. German and French fleet operators weight aluminum-intensive platforms more favorably in total cost of ownership models.
Europe Automotive Lightweight Car Market Segmentation
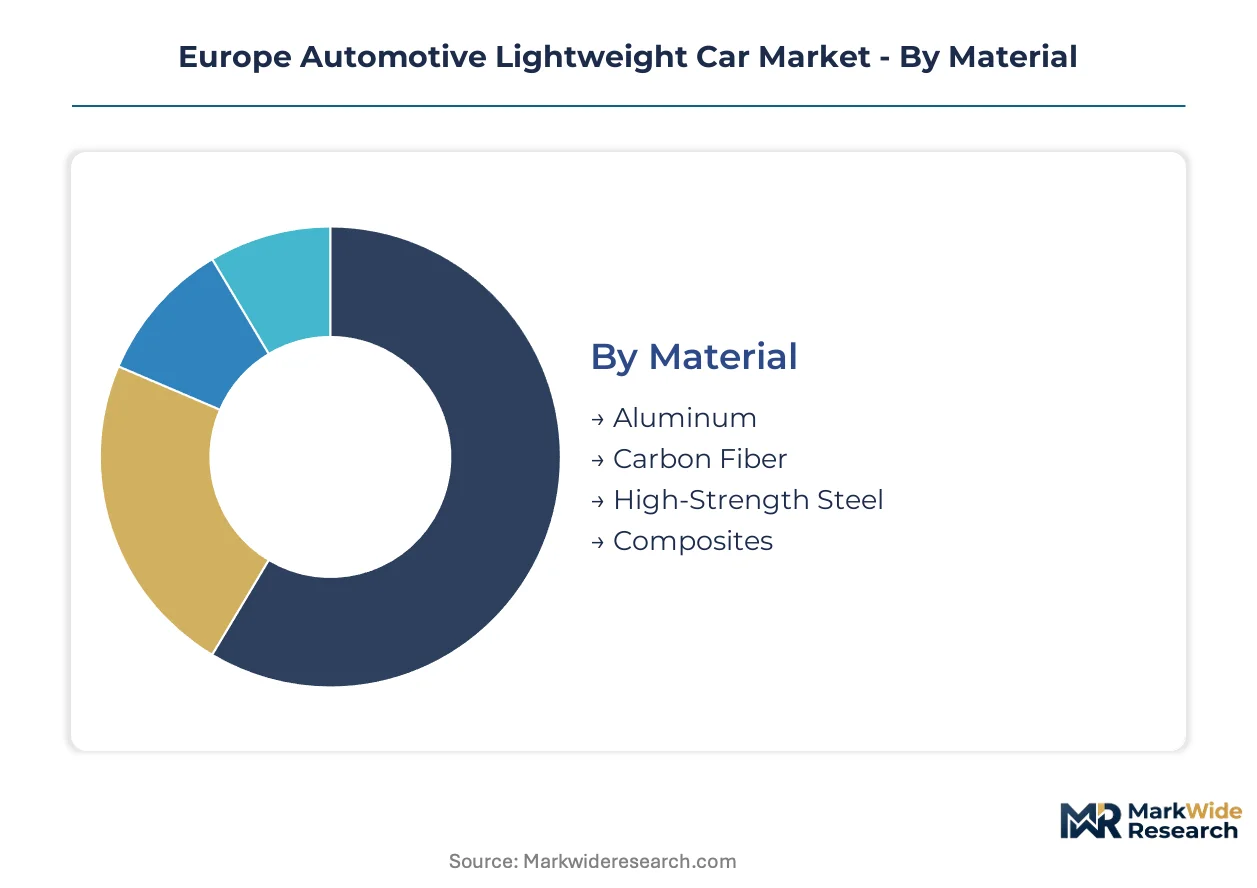
Material selection cycles in European automotive lightweighting compress from seven-year platform horizons toward three-year technology refresh windows. Vehicle type and production stage segmentation reveals divergent investment timelines across OEM engineering budgets and supplier tooling commitments.
Material:
Aluminum turns over fastest in procurement cycles at 18-24 months, while carbon fiber qualification extends across multi-year aerospace-grade precursor agreements.
- Aluminum:Closed-loop recycling infrastructure across Germany and France enables rapid specification changes without virgin material bottlenecks. BMW, Audi, and Porsche anchor demand through multi-material body shops seeking crashworthiness certification under EMA protocols.
- Carbon Fiber:Aerospace-grade precursor dependence on Japanese and US chemical conglomerates stretches procurement timelines and exposes European OEMs to currency allocation risk. High-performance electric SUV architectures absorb premium material costs to offset battery mass.
- High-Strength Steel:Mature stamping infrastructure retains cost advantage in A-segment and B-segment platforms where weight reduction targets remain modest.
- Composites:Thermoplastic matrix systems enable cycle times competitive with metal stamping, accelerating adoption in structural battery enclosures.
Aluminum anchors the volume base while carbon fiber gains share at the steepest rate.
Vehicle Type:
Platform economics concentrate engineering investment where battery mass penalties demand maximum lightweighting return.
- SUVs:Premium electric architectures dominate aluminum and carbon fiber consumption as range extension without battery cost escalation becomes the priority design constraint. German assembly plants in Stuttgart, Munich, and Ingolstadt concentrate flagship SUV production.
- Sedans:Fleet procurement contracts from French and German corporate mobility providers favor aluminum-intensive platforms for residual value guarantees.
- Hatchbacks:A-segment and B-segment applications retain steel-intensive construction where cost floors prevent material substitution.
- Coupes:Low-volume specialty production tolerates thermoset autoclave curing cycles and hand-layup composite fabrication.
SUVs concentrate the technology investment while sedans deliver the steadiest procurement volumes.
Production Stage:
Digital twin validation is compressing traditional design-to-assembly timelines across European OEM engineering departments.
- Design:Multi-material topology optimization now precedes platform commitment, locking aluminum-composite-steel ratios before tooling investment. EMA fleet CO₂ enforcement forces material substitution decisions upstream.
- Manufacturing:Thermoplastic composite welding convergence enables single-platform construction at cycle times matching aluminum stamping.
- Assembly:Friction stir welding and adhesive bonding skill scarcity constrains body shop throughput across German and Italian plants.
- Quality Control:Non-destructive testing protocols for aluminum-composite joints require new qualification standards under evolving EU ELV directive recyclability targets.
Design captures the earliest capital commitment while manufacturing offers the steepest efficiency gains.
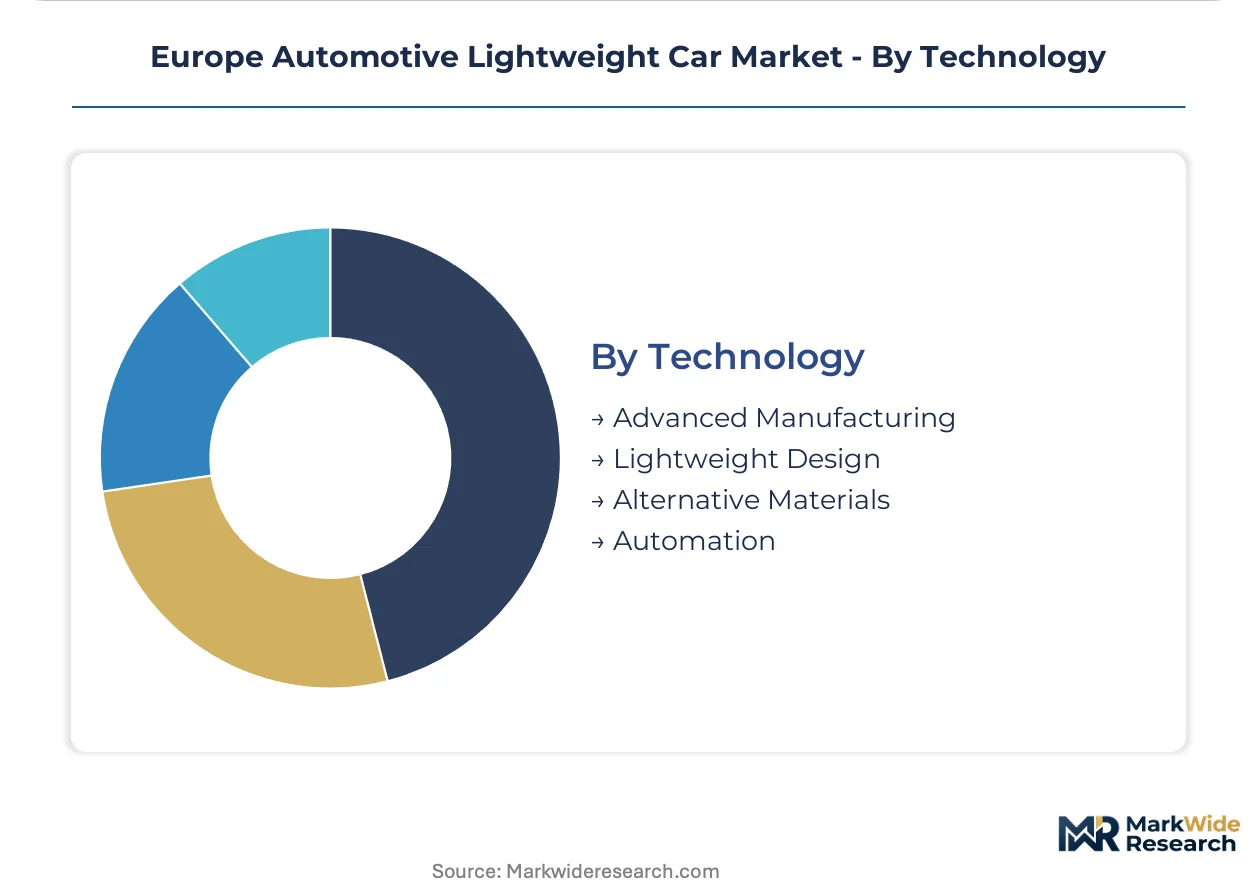
Technology:
Process innovation cycles outpace material science breakthroughs in current European OEM roadmaps.
- Advanced Manufacturing:Continuous fiber-reinforced thermoplastic tape placement systems automate structural battery enclosure production at BMW and Porsche German assembly lines.
- Lightweight Design:Topology optimization software integrates EMA emissions constraints directly into generative design algorithms.
- Alternative Materials:Bio-based resin systems face REACH substance evaluation timelines extending qualification cycles.
- Automation:Robotic rivet-bond hybrid assembly addresses technician scarcity in multi-material joining operations.
Advanced manufacturing commands the capital allocation while lightweight design delivers the broadest platform applicability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEMs command premium pricing for aluminum-intensive platforms while Italian specialists extract margin from low-volume carbon fiber coachbuilding. This pricing-power asymmetry reflects divergent industrial bases and regulatory exposure across the continent.
Germany
BMW, Porsche, and Audi anchor European demand through multi-material body shops in Munich, Stuttgart, and Ingolstadt. The KBA enforces fleet CO₂ compliance that accelerates aluminum and composite substitution in electric SUV architectures. Stuttgart-Zuffenhausen concentrates captive aluminum casting competence and carbon fiber reinforced plastic supply partnerships.
France
Renault Group drives mass-market aluminum adoption through its ElectriCity manufacturing cluster in northern France. The EU Green Deal carbon budgeting and national low-emission vehicle incentives compress product cycles toward material substitution. Paris-Saclay automotive research corridors advance thermoplastic composite welding for battery enclosures.
Italy
Ferrari and Lamborghini sustain carbon fiber demand for high-performance architectures where unit economics tolerate aerospace-grade precursor costs. REACH substance evaluations through ECHA extend novel resin system qualification timelines. The Turin-Milan corridor hosts underdeveloped composite stamping capacity offering partnership white space.
United Kingdom
Jaguar Land Rover and Aston Martin anchor aluminum-intensive platform engineering for premium SUVs and grand tourers. Post-Brexit UKCA marking protocols run parallel to CE marking for composite structural components. West Midlands manufacturing clusters concentrate friction stir welding expertise and adhesive bonding qualification.
Sweden
Volvo Car Corporation advances steel-aluminum multi-material construction for electric SUV safety architectures. The Swedish Transport Agency aligns national type approval with EMA fleet emissions frameworks. Gothenburg-Torslanda assembly operations integrate closed-loop aluminum recycling with renewable energy supply.
Europe Automotive Lightweight Car Market Competitive Landscape
Premium OEMs and mass-market manufacturers split the market along material sophistication lines. The competitive structure consolidates around captive supply control and multi-material body shop competence. Three archetypes dominate: vertically integrated premium specialists, aluminum-focused volume producers, and composite-centric low-volume coachbuilders. Capacity expansion in thermoplastic processing and strategic partnerships for precursor supply constitute the dominant competitive moves.
Among German premium OEMs, BMW AG, Porsche AG, and Audi AG exemplify the vertically integrated archetype through captive carbon fiber supply partnerships and in-house aluminum casting operations. These companies occupy positions where aerospace-grade material streams and multi-material welding competence determine platform economics. Ferrari SpA and Automobili Lamborghini S p A sit within the composite-centric tier, sustaining margin structures that tolerate thermoset autoclave cycles and hand-layup fabrication. Volkswagen AG and Renault Group represent scale-driven aluminum adoption, leveraging closed-loop recycling infrastructure across German and French manufacturing clusters.
| Leading Market Players |
|---|
| Audi AG |
| Ferrari SpA |
| Volkswagen AG |
| Renault Group |
| Automobili Lamborghini S p A |
| BMW AG |
| Porsche AG |
| Volvo Car Corporation |
| Daimler AG |
| Others |
Supply & Pricing Matrix
Aerospace-grade carbon fiber precursor concentration among Japanese and US chemical conglomerates determines both tiered pricing spreads and supply chain configuration across European OEM procurement offices. Currency exposure and allocation risk compress margins for composite-intensive platforms while amplifying premium capture for aluminum suppliers with closed-loop recycling infrastructure in Germany and France.
Pricing Analysis
Configured-to-order carbon fiber architectures command substantial premiums over standard aluminum-intensive platforms due to aerospace-grade precursor certification and multi-year supply agreements. Pricing stratifies across premium, standard, and economy tiers based on material certification grade and volume scale commitments, with fleet procurement contracts from German and French corporate mobility providers driving standard-tier volume. Cost compression in aluminum-intensive segments is intensifying because mature recycling infrastructure enables rapid specification changes without virgin material bottlenecks. Mass-market B-segment platforms exhibit the highest price sensitivity, while low-volume Italian coachbuilders demonstrate minimal elasticity due to unit economics that tolerate thermoset autoclave cycles.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities now structure relationships between European OEMs and Tier 1 integrators facing qualification timeline pressures. Raw material sourcing draws from Japan and the United States for carbon fiber precursors, Germany and France for aluminum smelting and recycling, and China for rare earth elements in composite additives. Single-source vulnerability concentrates in aerospace-grade precursor supply, exposing European assembly lines to allocation rationing during aerospace demand surges. Distribution runs through captive supply partnerships for premium OEMs and spot-market procurement for mass-market manufacturers lacking backward integration into material streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe Automotive Lightweight Car Market dynamics favor incumbents with regulatory entrenchment moats, as REACH substance evaluation timelines and EMA fleet CO₂ enforcement create qualification barriers that compound over successive platform cycles.
For Market Incumbents: Build captive supply moats through exclusive carbon fiber precursor partnerships and in-house aluminum casting competence to defend against emerging Asian composite suppliers and margin pressure from steel cost volatility. Secure multi-material welding technician pipelines through apprenticeship programs in Stuttgart-Zuffenhausen and Ingolstadt clusters. Prioritize certification investment in thermoplastic composite welding to accelerate cycle times beyond autoclave constraints. For New Entrants and Emerging Players: Underdeveloped composite stamping capacity in the Turin-Milan corridor represents the most penetrable entry point for Tier 1 integrators seeking partnership white space with Italian OEMs. Thermoplastic matrix system qualification for structural battery enclosures offers a second avenue, leveraging Paris-Saclay research corridors for technology validation. A go-to-market angle centered on EU Battery Regulation material passport compliance services captures digital traceability revenue streams. For Investors and Strategic Acquirers: EU Green Deal carbon border adjustment mechanism implementation reshapes the acquisition landscape toward suppliers with documented Scope 3 emissions disclosure and cradle-to-gate carbon intensity certification. Long-term viability favors vertically integrated specialists with captive precursor relationships and multi-material body shop competence. Watch ECHA substance evaluation acceleration as the signal for composite platform launch timelines compressing or extending.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Material Body Shop Investment | Audi and Porsche welding competence enables single-platform steel-aluminum-composite construction under EMA protocols. |
| Captive Carbon Fiber Supply Partnership | BMW aerospace-grade material stream partnerships reduce currency allocation risk from Japanese precursor suppliers. |
| Thermoplastic Composite Welding Convergence | Laser joining of CFRTP tapes at BMW and Porsche lines matches aluminum stamping cycle economics. |
| Closed-Loop Aluminum Recycling Infrastructure | German and French closed-loop systems qualify platforms for EU circular economy credits and reduce virgin dependency. |
| Material Passport Compliance Services | Digital traceability documentation for EU Battery Regulation creates service revenue from carbon intensity verification. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, composite material R&D directors, and aftermarket distribution specialists. Secondary validation drew from EMA fleet CO₂ compliance filings, ECHA REACH substance evaluation databases, vehicle production registries, and customs trade data for aluminum and carbon fiber precursor flows. Bottom-up segment sizing triangulated against top-down OEM production planning disclosures across the analysis window.
Calibration approaches anchored volume and value outputs to disclosed OEM platform commitments and supplier tooling investment announcements throughout the forecast period. Segmentation dimensions modeled include vehicle class, propulsion architecture, material content per vehicle, and regional production cluster concentration. CAGRs were derived from regression analysis of historical material substitution rates and OEM engineering budget allocations, with electric SUV platform expansion and battery mass offset requirements serving as primary demand drivers.
Macroeconomic conditions sit as an overlay; deviation in euro-yen exchange rates, aerospace demand cycles, or scrap aluminum pricing would shift the trajectory. Forecasts reflect documented assumptions around EMA enforcement timelines and ECHA qualification durations. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Motor Monitoring Market
Vehicle Components
Vehicle Trailer Hitch Market
Vehicle Components
Latin America Automotive Connectors Market
Vehicle Components
Snowplows Market
Vehicle Components
Trailer Surge Brake Market
Vehicle Components
Vehicle Exhaust Hose Market
Vehicle Components
Global Automotive Battery Sensor Market
Vehicle Components
CV Brake Controls Market
Vehicle Components
Automotive Position Sensor Market
Vehicle Components
Europe Automotive Connectors Market
Vehicle Components
Railway Air Filter Market
Vehicle Components
Global Undercarriage Components Market
Vehicle Components
Refrigerated Trailer Hinges Market
Vehicle Components
Ambulance Vehicles Market
Vehicle Components
Self Loading Trailer Market
Vehicle Components
South Africa Automotive Carbon Fiber Composites Market