
 Vehicle Radiator Market | 2026-2036
Vehicle Radiator Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Radiator Market Analysis
Software-defined thermal calibration is realigning what vehicle radiator suppliers monetize beyond hardware shipments. Denso Corporation leverages its sensor-to-actuator integration to bundle predictive maintenance modules with radiator assemblies. MAHLE GmbH anchors European aftermarket channels with remanufactured aluminum core programs that extend service revenue streams. Valeo SA competes on electrification-ready cooling architectures that position radiators within broader battery thermal management systems.
A vehicle radiator is a heat exchanger comprising fin-and-tube or plate-core constructions, typically manufactured from aluminum alloys or copper-brass composites, designed to dissipate thermal energy from engine coolant or transmission fluid into ambient air. Aluminum product type dominates OEM fitments due to weight reduction imperatives and brazing process efficiencies that lower unit costs. Liquid-cooled systems sustain the largest installed base across passenger vehicles and commercial fleets, though hybrid cooling configurations are capturing share in electrified powertrains where battery and cabin thermal loads converge. Passenger vehicles occupy the volume center, while heavy-duty trucks concentrate margin pools through specialized core designs and extended warranty terms.
EPA tailpipe rules and Euro 7 emissions frameworks are forcing tighter engine thermal management, directly elevating radiator performance specifications for combustion platforms. NHTSA fuel economy standards and China's MIIT dual carbon goals further shape material selection and manufacturing location decisions for suppliers serving multiple regulatory jurisdictions. Stakeholders must monitor how battery electric vehicle thermal architectures evolve cooling load requirements and whether radiator suppliers retool for integrated heat pump modules or cede position to thermal system integrators.
Market Dynamics
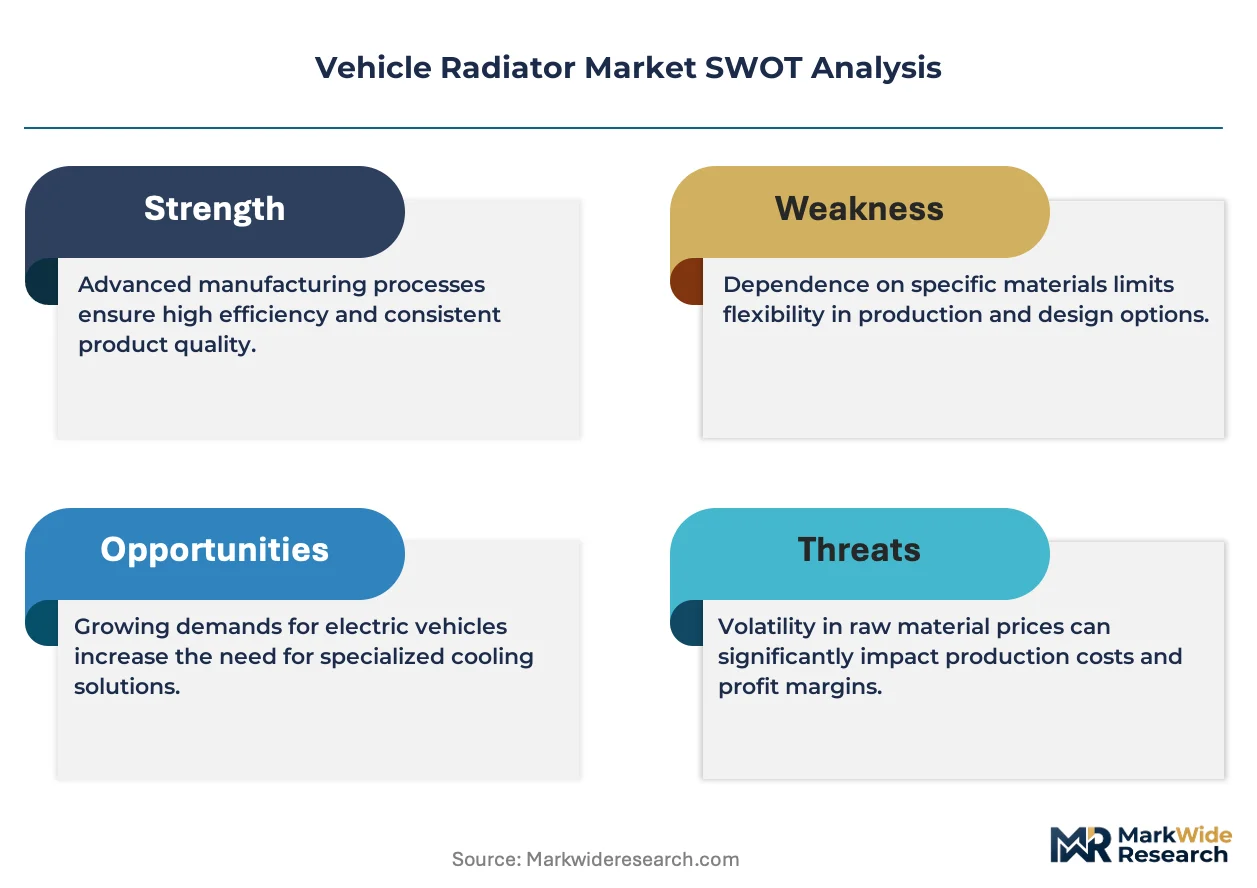
EPA tailpipe rules and Euro 7 emissions frameworks are compressing thermal management tolerances for combustion engines, forcing radiator suppliers to engineer higher-performance cores while simultaneously retooling for battery electric vehicle heat pump integration.
Growth Catalysts
- Euro 7 Emissions Framework:Tighter thermal efficiency mandates for internal combustion engines are elevating radiator performance specifications across European OEM platforms, expanding addressable content per vehicle.
- NEV Thermal Load Convergence:Battery and cabin thermal management requirements in electrified powertrains are diversifying radiator applications beyond traditional engine cooling into integrated thermal modules.
- China MIIT Dual Carbon Goals:Domestic OEM production scaling and lightweighting imperatives are concentrating demand for aluminum brazed radiator cores in the world's largest automotive manufacturing cluster.
Market Restraints
- Aluminum Alloy Price Volatility:Raw material input costs for brazing sheet and fin stock fluctuate with energy prices, compressing margin stability for stamped-core manufacturers.
- Heat Pump Module Substitution:Integrated thermal management systems in battery electric vehicles threaten to displace discrete radiator assemblies with multi-function heat exchanger packages.
- Tooling Amortization Burden:High-volume brazing furnace investments require sustained OEM platform volumes that electrification transition timelines may not guarantee.
Strategic Opportunities
- Commercial Fleet Electrification:Heavy-duty truck thermal architectures for electric drivetrains present unmet cooling load specifications in North American and European logistics corridors.
- Remanufactured Core Programs:Circular economy mandates under EU Green Deal and extended producer responsibility frameworks are legitimizing aftermarket revenue streams for aluminum core refurbishment.
- Sensor-Actuator Integration:Predictive thermal calibration software bundled with hardware shipments is automating service interval optimization for fleet operators.
Industry Challenges
- Brazing Process Expertise Scarcity:Controlled atmosphere furnace operation and flux-free brazing techniques require specialized technicians that automotive supplier workforces lack in sufficient depth.
- Multi-Platform Certification Timelines:Simultaneous validation for combustion, hybrid, and battery electric thermal architectures strains engineering bandwidth and prolongs time-to-revenue.
- Legacy Cooling System Integration:Electrified powertrain thermal modules must interface with existing vehicle architectures, creating packaging and control protocol compatibility friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Radiator Market |
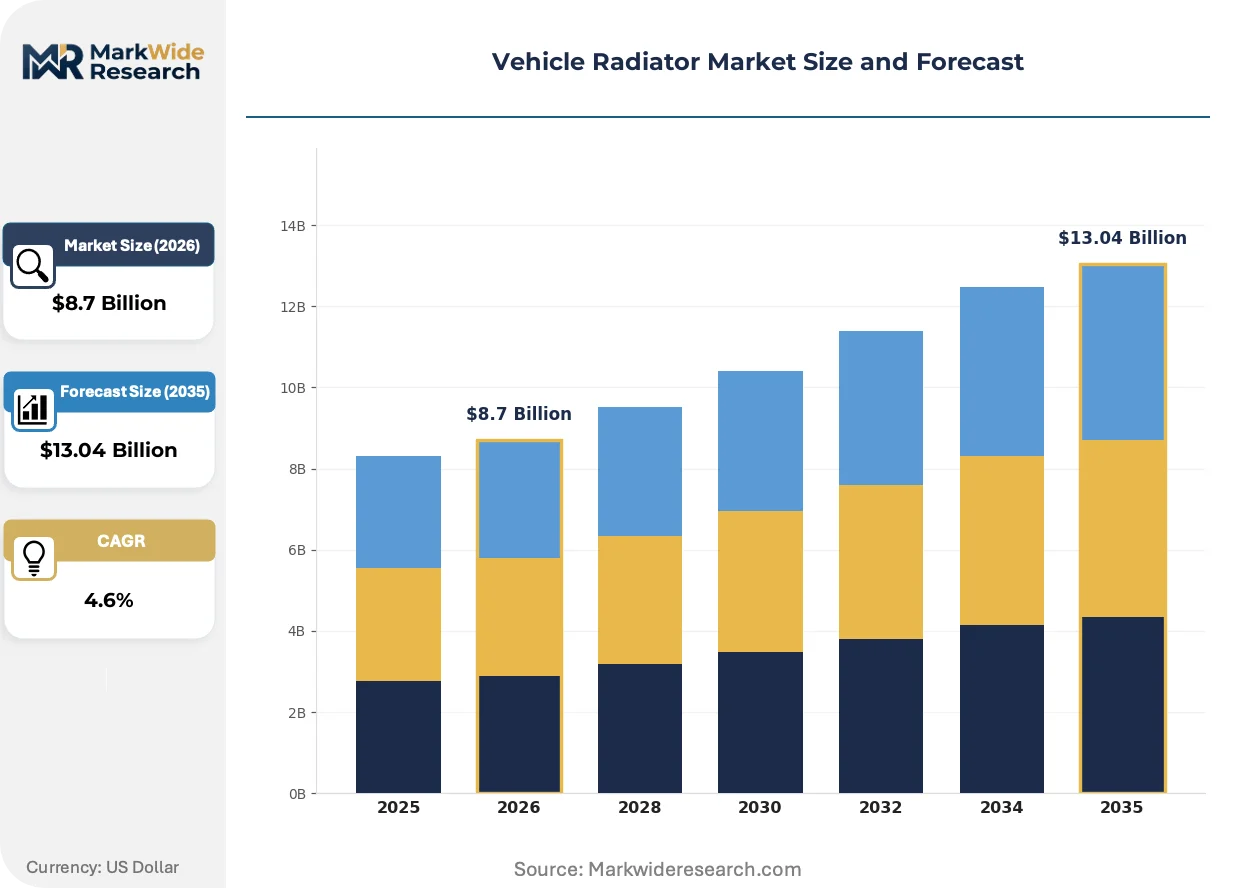
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Copper, Plastic, Steel Cooling Method: Air-Cooled, Liquid-Cooled, Oil-Cooled, Hybrid End User: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Motorcycles Distribution Channel: Online Retail, Auto Parts Stores, Dealerships, Wholesale |
| Companies Covered | Denso Corporation, MAHLE GmbH, Visteon Corporation, Modine Manufacturing Company, Valeo SA, Marelli Corporation, KOYORAD Co., Ltd., Hanon Systems, T.RAD Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Radiator Market Emerging Trajectories
Software-defined thermal management is displacing hardware-centric value capture, while regulatory tightening and electrification convergence reshape what radiator suppliers must engineer and monetize.
Microchannel aluminum tube technology is automating heat transfer efficiency gains through reduced refrigerant charge and enhanced surface-area-to-volume ratios. Tier 1 suppliers are adopting these cores for hybrid vehicle battery cooling circuits where space constraints dominate. The technology is automating the compression of traditional round-tube designs into obsolescence across premium electrified platforms.
EPA greenhouse gas standards for model year 2027-2032 are mandating tighter engine thermal control, directly elevating radiator duty cycles and core density requirements for light-duty trucks. OEMs are responding with split-flow cooling circuits and variable-speed fan modules that increase system complexity. Heavy-duty applications face parallel pressure from NHTSA fuel economy rules, accelerating adoption of advanced fin geometries.
Fleet procurement patterns are consolidating around total-cost-of-ownership metrics that weight thermal system durability and predictive maintenance capability above unit price. Large commercial operators are unbundling service contracts from initial equipment purchases, creating aftermarket revenue concentration for suppliers with diagnostic-integrated hardware. This shift is most pronounced in North American long-haul trucking and European intermodal logistics fleets.
Vehicle Radiator Market Segmentation
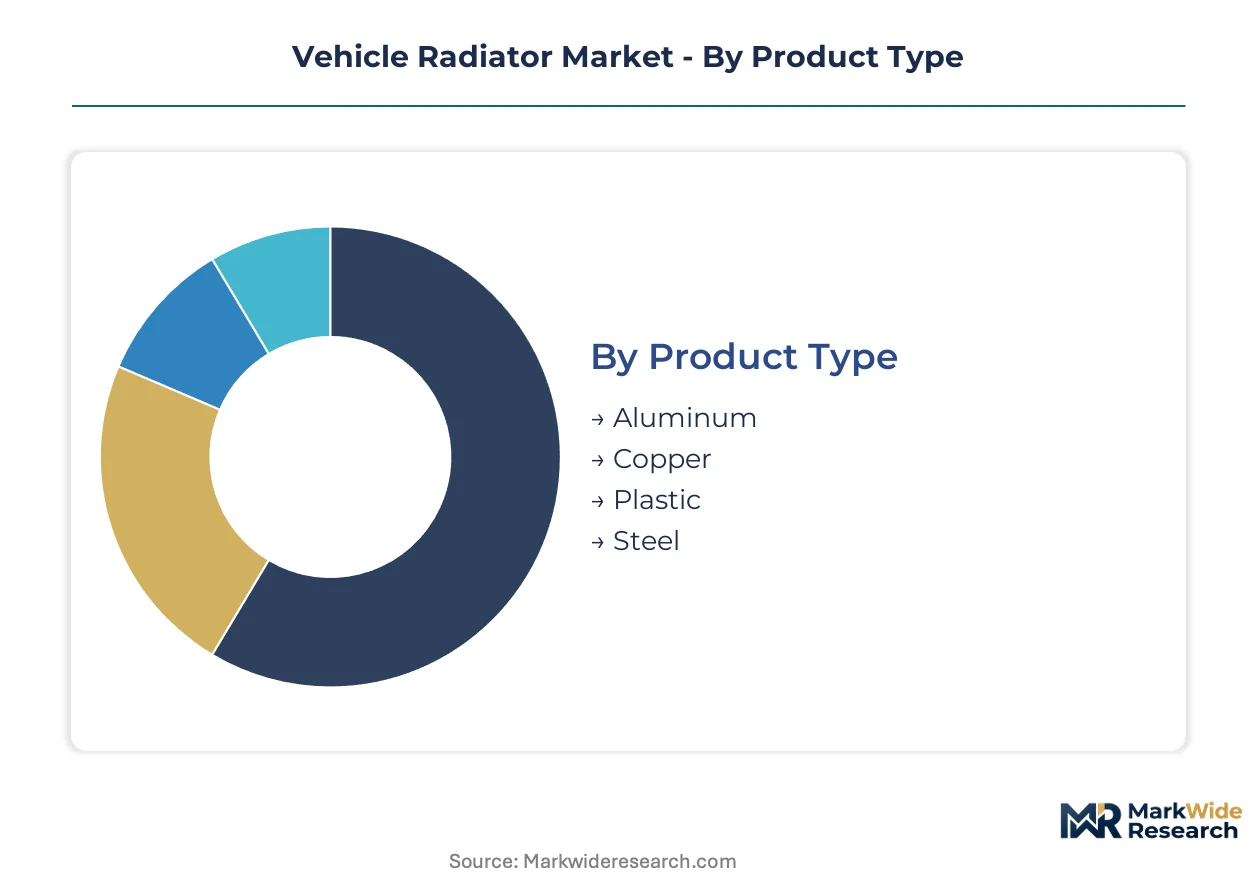
Radiator procurement decisions hinge on thermal load specifications, weight constraints, and regulatory compliance requirements that vary dramatically across powertrain architectures. Understanding how these technical and commercial dimensions fragment the addressable market reveals where suppliers must concentrate engineering investment and channel development.
Product Type:
Material selection directly determines thermal conductivity performance, manufacturing cost structure, and recyclability credentials that OEMs weigh against platform weight targets.
- Aluminum:Brazed aluminum cores dominate OEM fitments through superior heat-to-weight ratios and automated furnace production that compresses unit economics. Passenger vehicle manufacturers in China and Germany specify aluminum for MIIT dual carbon compliance and EU fleet CO2 targets.
- Copper:Traditional copper-brass constructions retain aftermarket loyalty for repairability and corrosion resistance in demanding operating environments. Demand concentrates in commercial fleet refurbishment programs where service life extension outweighs first-cost premiums.
- Plastic:Polymer-based tanks and end caps reduce galvanic corrosion risk while enabling complex geometries for packaging-constrained engine bays. End-tank plasticization is accelerating across Asian OEM platforms seeking cost reduction without core performance sacrifice.
- Steel:Steel components persist in heavy-duty applications requiring mechanical robustness against vibration and stone damage. Mining and construction equipment specifications favor steel-reinforced structures for field durability.
Volume sits with Aluminum; growth tilts toward Plastic as hybrid thermal architectures proliferate.
Cooling Method:
Thermal management architecture choices reflect powertrain heat rejection profiles, with electrification forcing convergence between previously discrete cooling circuits.
- Liquid-Cooled:Engine coolant circulation through fin-and-tube cores remains the dominant thermal rejection pathway for combustion and hybrid powertrains. European OEMs are elevating coolant flow rates under Euro 7 thermal efficiency mandates.
- Air-Cooled:Direct ambient convection systems persist in small-displacement motorcycles and legacy industrial equipment where simplicity trumps thermal precision. Regulatory pressure on emissions is compressing air-cooled share in on-road applications.
- Oil-Cooled:Dedicated transmission and differential oil cooling circuits address lubricant thermal degradation in high-torque commercial drivetrains. North American heavy-duty truck specifications are expanding oil cooler content per vehicle.
- Hybrid:Integrated circuits managing battery, cabin, and power electronics thermal loads are capturing share fastest as electrified platforms consolidate cooling infrastructure. Heat pump integration is displacing discrete radiators in premium battery electric architectures.
Installed base concentrates in Liquid-Cooled; expansion is steepest in Hybrid configurations.
End User:
Vehicle category determines thermal load magnitude, duty cycle severity, and service interval expectations that shape radiator specification and aftermarket opportunity.
- Passenger Vehicles:High-volume OEM production scales reward aluminum brazing automation and standardized core geometries across multiple nameplates. China's domestic brand expansion is concentrating global passenger radiator demand in Yangtze River Delta manufacturing clusters.
- Commercial Vehicles:Fleet procurement patterns prioritize total-cost-of-ownership metrics that weight thermal durability and predictive maintenance capability. North American logistics operators are unbundling service contracts from initial equipment purchases.
- Heavy-Duty Trucks:Specialized core designs with extended fin pitch and reinforced headers address continuous high-load operation. NHTSA fuel economy standards are forcing adoption of variable-speed fan modules and advanced fin geometries.
- Motorcycles:Compact packaging constraints and weight minimization drive microchannel tube adoption in premium displacement categories. Asian motorcycle manufacturing hubs specify low-cost aluminum cores for high-volume commuter segments.
Unit economics favor Passenger Vehicles; margin pools concentrate in Heavy-Duty Trucks.
Distribution Channel:
Channel selection reflects purchase urgency, technical support requirements, and fleet procurement centralization trends that reshape how radiator suppliers reach end users.
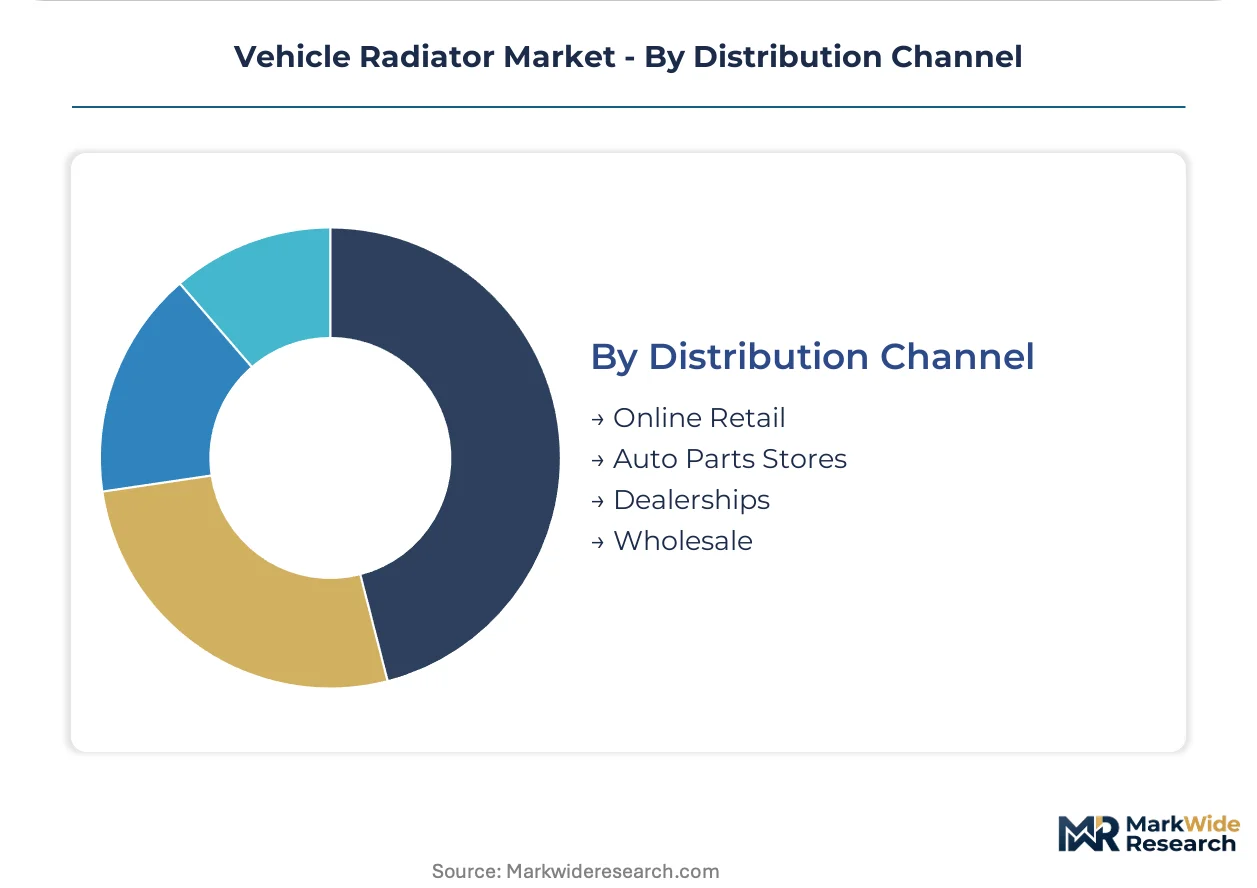
- Auto Parts Stores:Counter sales and same-day availability dominate independent repair shop procurement for collision replacement and preventive maintenance. Store networks in the US and Germany anchor aftermarket volume.
- Dealerships:OEM-captive channels capture warranty service and brand-loyal replacement demand with genuine parts authentication. Dealer management system integration is automating inventory replenishment.
- Online Retail:E-commerce platforms are gaining share in DIY enthusiast and small fleet segments where price transparency and specification lookup tools reduce purchase friction. Amazon and specialized auto parts marketplaces are consolidating digital demand.
- Wholesale:Direct-to-fleet and direct-to-installer contracts bypass retail markups for high-volume commercial operators. Procurement centralization at national logistics companies is compressing distributor tier count.
Transaction volume flows through Auto Parts Stores; digital expansion is accelerating fastest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration in China exceeds regional consumption, creating export dependency for aluminum brazed cores. European and North American markets rely on imports for volume segments while retaining domestic capacity for heavy-duty specifications.
China
Domestic OEM production scaling under MIIT dual carbon goals is concentrating aluminum radiator demand in Yangtze River Delta manufacturing clusters. MIIT fuel consumption regulations are forcing lightweighting specifications that favor brazed aluminum construction. Shanghai and Jiangsu Province host the densest supplier ecosystems, with foundries automating furnace lines for export and domestic fitment simultaneously.
Germany
Euro 7 emissions proposals are elevating thermal efficiency mandates for combustion platforms across German OEM supply chains. KBA type-approval processes are extending validation timelines for multi-platform thermal architectures. Baden-Württemberg and Bavaria anchor precision stamping and brazing operations serving premium vehicle manufacturers and commercial drivetrain specialists.
United States
NHTSA fuel economy standards for model years 2027-2032 are compressing thermal management tolerances for light-duty trucks and heavy-duty applications. EPA greenhouse gas rules are mandating split-flow cooling circuits that increase system complexity. Michigan and Ohio manufacturing corridors retain stamping and assembly capacity, though aluminum sheet sourcing increasingly relies on Canadian and Mexican upstream supply.
Japan
METI carbon neutrality roadmaps are accelerating hybrid thermal system development that converges battery and engine cooling circuits. JIS standards for automotive heat exchangers are being revised to accommodate heat pump integration requirements. Aichi and Kanagawa prefectures concentrate precision tube forming and microchannel technology development for domestic and Southeast Asian export markets.
India
Bureau of Indian Energy Efficiency standards for commercial vehicles are expanding radiator content per vehicle as thermal load specifications tighten. PLI scheme incentives for automotive component manufacturing are attracting brazing furnace investments in Tamil Nadu and Gujarat. Chennai and Ahmedabad industrial belts are scaling aluminum core production for domestic OEM fitment and regional export to Middle Eastern and African markets.
Vehicle Radiator Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across brazing furnace ownership versus core specification development. The supplier base exhibits moderate consolidation, with integrated thermal system specialists absorbing discrete radiator manufacturers. Three archetypes dominate: full-system integrators bundling sensors and software, aluminum specialists controlling brazing process expertise, and remanufacturing operators capturing circular economy mandates. Capacity expansion and strategic partnerships represent the dominant competitive vectors, with furnace investments requiring sustained platform volumes and technology licensing addressing electrification transition risks.
Within the integrated-system tier, Denso Corporation and Valeo SA exemplify sensor-to-actuator bundling strategies that extend value capture beyond hardware shipments. MAHLE GmbH anchors the European aftermarket through remanufacturing archetypes that align with EU Green Deal extended producer responsibility frameworks. These three entities represent divergent responses to electrification pressure: predictive maintenance modules, circular core programs, and electrification-ready cooling architectures respectively.
| Leading Market Players |
|---|
| Denso Corporation |
| MAHLE GmbH |
| Visteon Corporation |
| Modine Manufacturing Company |
| Valeo SA |
| Marelli Corporation |
| KOYORAD Co., Ltd. |
| Hanon Systems |
| T.RAD Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Flux-free brazing furnace automation is compressing unit economics for aluminum core manufacturers while simultaneously concentrating supply among capital-intensive operators capable of sustained platform volumes. This production-method transition elevates fixed-cost barriers for stamped-core specialists and reshapes pricing power toward furnace owners in China's Yangtze River Delta and Germany's Baden-Württemberg corridor.
Pricing Analysis
Cost-down pressure on aftermarket copper-brass cores accelerates because fleet operators unbundle service contracts and weight total-cost-of-ownership metrics above first-cost premiums. Three-tier pricing structure across premium OEM-fitment, standard independent aftermarket, and economy remanufactured tiers separates Denso's sensor-integrated modules from MAHLE's refurbished aluminum programs. Price differentiation hinges on brazing process certification grade and predictive maintenance software bundling. Commercial fleet procurement teams exhibit highest price sensitivity; premium electrification-ready cooling architectures command lowest elasticity.
Supply Chain Analysis
Aluminum brazing sheet supply rests on Chinese and German rolling mill capacity, with fin stock sourcing concentrated in South Korean and Japanese specialty metal producers. Raw material dependencies include brazing alloy formulations, controlled-atmosphere furnace gases, and precision stamping dies. Single-source vulnerability persists for flux-free brazing chemical treatments subject to EU REACH regulatory restrictions. Distribution runs through Tier 1 thermal system integrators consolidating discrete radiator assemblies into vehicle platform contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazing furnace capacity scarcity props pricing for incumbent operators while electrification transition timelines threaten sustained platform volumes. Supply constraints in controlled-atmosphere equipment installation create defensive moats for capital-deployed producers.
For Market Incumbents: To counter heat pump module substitution from integrated thermal system specialists, Denso and Valeo should deepen backward integration into sensor-actuator calibration software while MAHLE expands remanufacturing capacity in EU Green Deal-aligned circular economy hubs. Certification investment in multi-platform validation protocols addresses Euro 7 and EPA emissions convergence timelines. For New Entrants and Emerging Players: Begin with commercial fleet electrification cooling loads in North American long-haul corridors where unmet thermal specifications outpace incumbent R&D bandwidth. Target heavy-duty electric truck battery thermal management as the most penetrable segment, leveraging direct-to-fleet wholesale contracts bypassing established distributor tiers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by full-system integrators seeking brazing process expertise. Long-term viability favors furnace-owning operators with hybrid thermal architecture certification spanning combustion and battery electric platforms. Watch NHTSA fuel economy standard implementation pace as inflection indicator for heavy-duty content-per-vehicle expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Flux-Free Brazing Process Investment | Controlled-atmosphere furnace ownership secures margin pools as Euro 7 thermal efficiency mandates tighten. |
| Predictive Maintenance Software Bundling | Sensor-to-actuator integration extends revenue per vehicle beyond hardware shipment for fleet operators. |
| Remanufactured Core Program Expansion | EU Green Deal extended producer responsibility frameworks legitimize circular aftermarket revenue streams. |
| Heat Pump Module Integration | Multi-function thermal packages capture battery electric vehicle cooling load convergence. |
| MIIT Dual Carbon Compliance Positioning | Lightweight aluminum brazing expertise aligns with China's domestic OEM production scaling. |
Methodological Framework
OEM platform engineering databases, vehicle production registration records, and SEC filings from listed thermal system suppliers formed the secondary backbone. Primary interviews with Tier 1 supplier procurement leads, aftermarket distributor operations heads, and commercial fleet maintenance directors validated demand assumptions. Customs trade data and aluminum alloy pricing indices anchored cost structure modeling. Bottom-up unit economics triangulated against top-down regional production forecasts.
Historical trendline analysis across installed base replacement cycles and electrification penetration curves informed projection parameters. Segmentation modeling spanned product type, cooling method, vehicle class, and regional regulatory cluster dimensions. CAGRs derived from weighted average of OEM platform volume commitments and aftermarket service interval compression. Battery thermal load specifications and heat pump adoption curves served as electrification-transition forecast inputs.
Underlying measurement precision varies by segment; aluminum brazed OEM fitment data carries tighter precision than emerging hybrid cooling architecture estimates. Forecasts reflect assumptions around EPA and Euro 7 implementation timelines, aluminum alloy price stability, and commercial fleet electrification pace. A small set of regulatory enforcement triggers and commodity volatility indicators warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Passenger Car Sensors Market
Vehicle Components
Rolling Stock LED Lights Market
Vehicle Components
Wheel Studs Market
Vehicle Components
Trailer Terminal Tractor Market
Vehicle Components
North America Forklift Rental Market
Vehicle Components
Europe Trailer Axle Market
Vehicle Components
Trailer Stabilizer Market
Vehicle Components
UK Automotive Carbon Fiber Composites Market
Vehicle Components
Rear-Wheel Steering Actuator Systems for SUVs Market
Vehicle Components
Global Truck and Trailer Landing Gear Market
Vehicle Components
Italy Automotive Glass Fiber Composites Market
Vehicle Components
Driveline Systems for Electric Vehicle Market
Vehicle Components
Aircraft and Marine Turbochargers Market
Vehicle Components
HCV Suspension System Market
Vehicle Components
Wheel Chocks Market
Vehicle Components
United Kingdom Vacuum Truck Market