
 Trailer Spindles Market | 2026-2036
Trailer Spindles Market Size, Share, and Industry Trends Forecast 2026-2036
Trailer Spindles Market Analytics
Aftermarket service revenue is narrowing toward spindle replacement and brake-integrated upgrade kits as fleet operators extend trailer lifecycles. Dexter Axle Company leverages vertical integration across forging and heat-treatment operations to control cost positions. AL-KO Vehicle Technology anchors European supply through specialized tapered spindle designs for boat trailers. BPW Bergische Achsen KG dominates heavy-duty disc brake spindle architectures for cargo haulers in Germany.
A trailer spindle is a machined rotating shaft that supports wheel hub assemblies, typically forged from alloy steel with induction-hardened bearing journals and specified runout tolerances below 0.002 inches, serving to transfer radial and thrust loads from the trailer chassis to the rolling elements. Heavy-duty spindles lead material throughput owing to sustained loads in construction and agriculture logistics. Composite spindles represent the fastest-growing material category as weight-sensitive RV and boat trailer builders pursue payload optimization. Standard steel spindles remain the mature volume base across utility trailer production lines.
The National Highway Traffic Safety Administration enforces Federal Motor Vehicle Safety Standard 121 governing trailer braking performance, directly mandating spindle-integrated disc brake compatibility for new heavy trailers. The EPA's Phase 2 greenhouse gas regulations for medium- and heavy-duty vehicles indirectly pressure spindle weight reduction through downstream trailer aerodynamics and mass targets. Stakeholders must monitor how pending updates to FMVSS brake testing protocols reshape spindle load rating certifications and aftermarket replacement specifications.
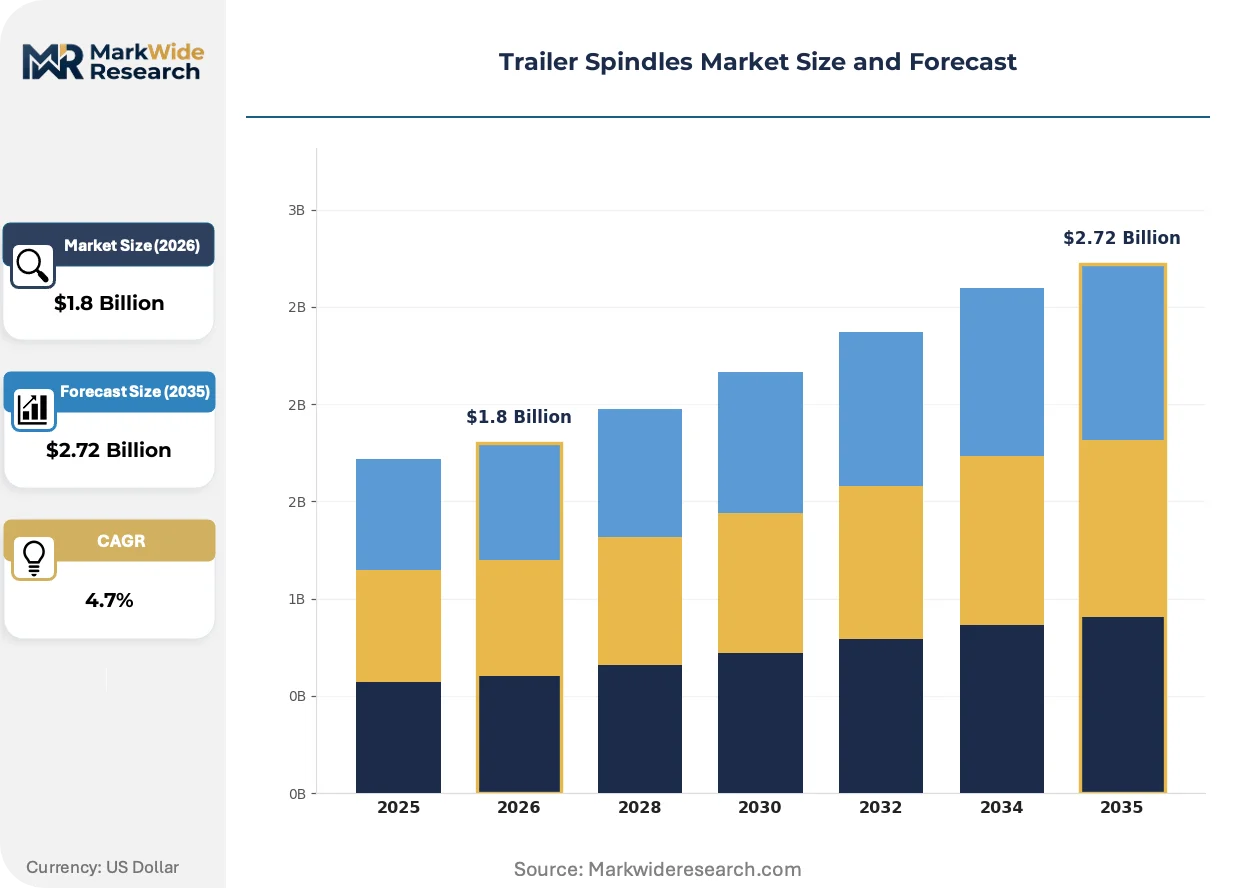
Market Dynamics
Fleet operators across North America are compressing replacement cycles for brake-integrated spindle assemblies as NHTSA enforcement of Federal Motor Vehicle Safety Standard 121 intensifies roadside inspection protocols. This regulatory pressure is restructuring procurement priorities toward certified disc-brake-compatible architectures.
Growth Catalysts
- Federal Motor Vehicle Safety Standard 121:NHTSA mandates for enhanced trailer braking performance are accelerating spindle replacement programs among commercial fleet operators seeking compliance certification.
- Composite materials:Weight-sensitive RV and boat trailer manufacturers are specifying carbon-fiber-reinforced spindle designs to optimize payload capacity under EPA Phase 2 mass reduction targets.
- Indiana-Michigan manufacturing cluster:Concentrated utility trailer production in these states generates sustained demand for standard steel spindle volumes and localized forging capacity.
Market Restraints
- Alloy steel price volatility:Input cost swings for 4140 and 4340-grade steels compress forging margins and destabilize long-term supply agreements with tier-two axle assemblers.
- Heat-treatment capacity concentration:Induction-hardening infrastructure clusters in the upper Midwest, creating geographic single-point-of-failure exposure for just-in-time spindle delivery.
- Bearing journal tolerance limits:Runout specifications below 0.002 inches require precision grinding investments that exclude smaller machine shops from qualified supplier pools.
Strategic Opportunities
- Boat trailer specialization:Tapered spindle architectures for marine applications remain underpenetrated outside European supply channels, opening white space for corrosion-resistant coating technologies.
- Aftermarket service bundling:Fleet maintenance providers are unbundling spindle replacement from full axle swaps, creating direct-to-operator e-commerce channels for brake-integrated upgrade kits.
- Inflation Reduction Act commercial vehicle incentives:Tax credits for medium- and heavy-duty fleet modernization are redirecting capital toward trailer brake system overhauls including spindle-integrated disc configurations.
Industry Challenges
- Precision grinding technician shortage:Bearing journal finishing requires specialized CNC operator skills that vocational programs have not scaled to match replacement demand velocity.
- FMVSS certification timeline compression:Accelerated brake testing protocol updates are forcing spindle manufacturers to parallel-track design validation with production ramp-up, straining quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trailer Spindles Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Spindles, Heavy-Duty Spindles, Tapered Spindles, Disc Brake Spindles Material: Steel, Aluminum, Cast Iron, Composite Application: Utility Trailers, Boat Trailers, RV Trailers, Cargo Trailers End User: Manufacturers, Distributors, Retailers, Aftermarket Providers |
| Companies Covered | Dexter Axle Company, AL-KO Vehicle Technology, Rockwell American, DexKo Global Inc., Meritor Inc., BPW Bergische Achsen KG, JOST Werke AG, SAF-Holland S.A., ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trailer Spindles Market Evolving Landscape
Material science advances and regulatory compliance automation are restructuring how spindle specifications propagate from OEM engineering desks to fleet procurement systems. These forces are compressing traditional design-to-delivery timelines.
Composite spindle architectures are migrating from specialty RV applications toward mainstream utility trailer production. Boat and recreational vehicle manufacturers pioneered carbon-fiber-reinforced designs for weight-critical payloads. Standard trailer builders in Indiana and Michigan are now qualifying hybrid steel-composite spindles for mid-duty ratings to satisfy EPA-implicit mass targets without sacrificing load capacity.
NHTSA's pending updates to Federal Motor Vehicle Safety Standard 121 brake testing protocols are forcing spindle-integrated disc brake compatibility into heavy trailer specifications. The regulation eliminates drum-brake-only architectures for new commercial trailers above specified gross vehicle weight ratings. German cargo hauler specifications through KBA type-approval requirements are converging with US mandates, pressuring multinational axle suppliers to unify disc-brake spindle platforms across Atlantic markets.
Fleet procurement departments are consolidating spindle sourcing through direct manufacturer relationships, disintermediating traditional distributor networks. Large operators in Michigan and Ohio are negotiating multi-year brake system overhaul contracts that bundle spindle replacement with disc upgrade kits. This concentration of buying power is compressing price realization for standard steel spindles while elevating premium positioning for certified disc-compatible architectures.
Trailer Spindles Market Segmentation
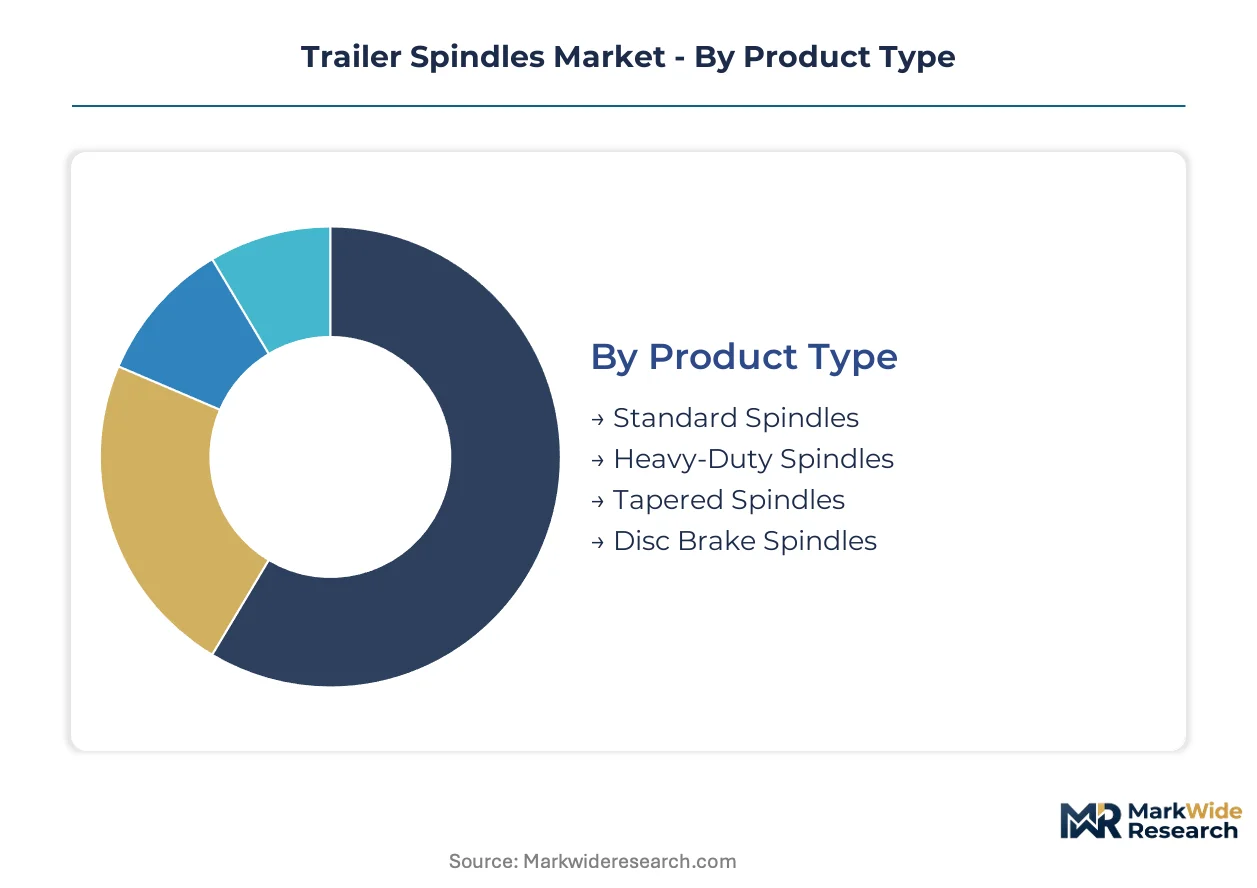
Spindle specification diversity reflects divergent duty cycles across trailer applications. Replacement velocity and procurement economics vary sharply by segment, creating distinct margin architectures for suppliers.
Product Type:
Replacement cycles stretch from seasonal wear parts to decade-long structural components depending on load severity and duty classification.
- Heavy-Duty Spindles:Forged from 4140-grade alloy steel with induction-hardened bearing journals rated for sustained construction and agriculture loads. Fleet operators in Michigan and Ohio compress replacement intervals amid NHTSA roadside inspection intensity.
- Disc Brake Spindles:Integrated hub-spindle architectures engineered for direct caliper mounting with runout tolerances below 0.002 inches. Demand concentrates among commercial cargo haulers retrofitting drum-brake trailers to meet Federal Motor Vehicle Safety Standard 121 mandates.
- Standard Spindles:Utility trailer production lines in Indiana specify these forged steel shafts for light-duty ratings with conventional bearing configurations.
- Tapered Spindles:Marine applications favor these corrosion-resistant designs with specialized seal geometries for saltwater immersion cycles.
Standard spindles dominate installed base. Disc brake spindles are where expansion concentrates.
Material:
Cost tiers stratify sharply between commodity steel and engineered composites, with procurement patterns diverging by trailer builder scale and payload sensitivity.
- Steel:Standard 1045 and alloy grades anchor utility trailer production through established forging infrastructure in the upper Midwest.
- Composite:Carbon-fiber-reinforced architectures pioneered by RV and boat trailer manufacturers for weight-critical payloads now penetrate mid-duty ratings as EPA-implicit mass targets tighten.
- Aluminum:Corrosion-resistant extrusions serve saltwater marine applications where galvanic isolation from steel chassis matters.
- Cast Iron:Ductile iron variants occupy niche agricultural implement trailers requiring vibration damping at lower cost points than forged alternatives.
Steel commands volume throughput. Composite formulations are climbing the fastest.
Application:
End-use specialization dictates spindle geometry, corrosion protection, and bearing interface standards with minimal cross-application standardization.
- Utility Trailers:Light-duty spindles with sealed bearing cartridges serve landscaping and residential hauling demand concentrated in Indiana-Michigan manufacturing clusters.
- Cargo Trailers:Heavy-duty disc-compatible architectures dominate commercial fleet specifications as brake compliance deadlines approach.
- Boat Trailers:Tapered spindle geometries with specialized marine seals address saltwater corrosion cycles through Gulf Coast and Great Lakes distribution channels.
- RV Trailers:Weight-optimized spindle specifications prioritize payload capacity for towable recreational vehicles targeting state park and campground access.
Cargo trailers drive certified spindle demand. Boat trailers present underpenetrated coating technology opportunities.
End User:
Channel structure fragments between direct OEM supply and fragmented aftermarket service networks with diverging technical support requirements.
- Manufacturers:Axle assemblers and trailer builders procure spindles through multi-year forging contracts with heat-treatment capacity guarantees.
- Aftermarket Providers:Fleet maintenance shops and mobile service operators source brake-integrated upgrade kits through direct manufacturer relationships disintermediating traditional distribution.
- Distributors:Regional warehousing operations stock standard steel spindles for emergency replacement cycles in agricultural and construction markets.
- Retailers:Consumer-facing channels serve DIY trailer builders and small utility trailer owners through limited technical specification ranges.
Manufacturers anchor procurement volume. Aftermarket providers are capturing margin from unbundled spindle replacement services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Fleet operators in Germany absorb premium pricing for certified disc-brake architectures without volume contraction. Buyers in India and Southeast Asia resist alloy steel cost pass-through, forcing suppliers into localized forging partnerships.
United States
Commercial fleet operators in Michigan and Ohio compress replacement cycles for brake-integrated spindle assemblies. NHTSA enforcement of Federal Motor Vehicle Safety Standard 121 intensifies roadside inspection protocols across interstate corridors. The Indiana-Michigan manufacturing cluster sustains demand for standard steel spindle volumes through concentrated utility trailer production lines.
Germany
Heavy-duty cargo haulers through BPW Bergische Achsen KG specifications drive disc-brake spindle adoption. KBA type-approval requirements for trailer braking systems converge with US FMVSS mandates, pressuring multinational suppliers to unify platforms. The Bergisches Land region anchors forging and heat-treatment infrastructure for axle assemblies serving Atlantic markets.
China
Domestic trailer builders source standard steel spindles through localized forging networks serving construction and agriculture logistics. MIIT fuel efficiency standards for commercial vehicles indirectly pressure spindle weight reduction targets. The Yangtze River Delta manufacturing belt concentrates axle assembly capacity for export-oriented utility trailer producers.
India
Agricultural implement trailer manufacturers specify ductile iron spindle variants for cost-sensitive vibration damping applications. BIS certification requirements for automotive components create compliance barriers for unorganized forging suppliers. The Gujarat industrial corridor hosts emerging axle assembly operations targeting domestic replacement demand.
Canada
Recreational vehicle and boat trailer manufacturers in Ontario and Quebec specify corrosion-resistant spindle architectures for freshwater and saltwater exposure cycles. Transport Canada vehicle safety regulations align with NHTSA brake performance standards for cross-border fleet compatibility. The Great Lakes distribution channel connects Canadian marine trailer builders with US Midwest forging capacity.
Trailer Spindles Market Competitive Landscape
Capability concentration sits with heat-treatment and precision grinding specialists; scale advantage sits with integrated axle assemblers commanding multi-year OEM contracts. The market structures around three tiers: vertically integrated forging-to-assembly operators, specialized spindle manufacturers with captive heat-treatment, and regional machine shops serving aftermarket replacement. Strategic moves center on backward integration into alloy steel sourcing and geographic expansion through distributor acquisition.
Within the integrated tier, Dexter Axle Company and DexKo Global Inc. occupy positions spanning North American OEM supply. AL-KO Vehicle Technology anchors European demand through specialized marine and RV spindle architectures. BPW Bergische Achsen KG exemplifies the heavy-duty disc-brake specification tier serving commercial cargo haulers across German and export markets.
| Leading Market Players |
|---|
| Dexter Axle Company |
| AL-KO Vehicle Technology |
| Rockwell American |
| DexKo Global Inc. |
| Meritor Inc. |
| BPW Bergische Achsen KG |
| JOST Werke AG |
| SAF-Holland S.A. |
| ZF Friedrichshafen AG |
| Others |
Value Network & Pricing Analysis
Heat-treatment capacity utilization above 85% in the upper Midwest is compressing supplier lead times and elevating price premiums for certified disc-brake-compatible spindles. This tightness propagates through forging contracts as fleet operators accelerate replacement programs to meet NHTSA roadside inspection protocols.
Pricing Analysis
Aftermarket service revenue from spindle replacement and brake-integrated upgrade kits now drives lifetime value beyond initial hardware sales. Pricing stratifies across certified disc-brake architectures, standard forged steel shafts, and economy-grade ductile iron variants based on NHTSA compliance tier and heat-treatment specification. Cost compression in standard steel spindles is intensifying because fleet procurement consolidation disintermediates traditional distributors. Small utility trailer builders and DIY operators exhibit highest price sensitivity, while commercial cargo haulers absorb premiums for FMVSS 121-certified configurations.
Supply Chain Analysis
Alloy steel feedstock draws from integrated mills in the United States, Germany, and China with 4140 and 4340 grades anchoring heavy-duty forging specifications. Raw material dependencies center on scrap steel pricing, induction-hardening equipment, and precision grinding consumables. Single-source vulnerability concentrates in upper Midwest heat-treatment infrastructure serving Indiana-Michigan trailer production clusters. Distribution runs through direct manufacturer relationships with fleet operators, bypassing regional warehousing for brake-integrated upgrade kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spindle replacement services and disc-brake upgrade kits are expanding faster than raw forging throughput, reframing hardware margins as entry points to recurring aftermarket revenue streams.
For Market Incumbents: Insulate forging margins by securing captive heat-treatment capacity in the upper Midwest against geographic concentration risk. Deepen backward integration into alloy steel sourcing to buffer 4140-grade price volatility. Certification investment in FMVSS 121 testing protocols defends positioning against emerging composite spindle entrants targeting RV payload optimization. For New Entrants and Emerging Players: Establish a beachhead in marine trailer tapered spindle architectures through corrosion-resistant coating technologies underpenetrated outside European supply channels. Target boat trailer builders along Gulf Coast and Great Lakes distribution corridors with saltwater-immersion-qualified seal geometries. A direct-to-operator e-commerce channel for brake-integrated upgrade kits bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision grinding and induction-hardening infrastructure as runout tolerances tighten below 0.002 inches. Acquisition candidates with captive heat-treatment and certified disc-brake spindle portfolios offer defensive positioning through regulatory compliance mandates. Monitor NHTSA FMVSS 121 protocol update timing as inflection signal for replacement demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Steel Sourcing | Mitigates 4140-grade price volatility compressing forging margins across upper Midwest capacity. |
| Heat-Treatment Capacity Expansion | Addresses geographic single-point-of-failure exposure threatening just-in-time spindle delivery. |
| Disc-Brake Spindle Certification Investment | Secures FMVSS 121 compliance positioning as NHTSA roadside inspection protocols intensify. |
| Marine Coating Technology Development | Captures underpenetrated boat trailer demand through saltwater corrosion-resistant architectures. |
| Direct-to-Operator E-Commerce Channel | Disintermediates traditional distribution for aftermarket brake-integrated upgrade kit sales. |
Research Methodology
Operator-level perspectives from fleet maintenance directors, axle assembler procurement teams, heat-treatment facility managers, and trailer OEM engineering leads anchored the qualitative base. These primary insights combined with secondary validation from NHTSA regulatory filings, EPA Phase 2 greenhouse gas documentation, SEC 10-K disclosures from listed axle suppliers, and customs trade data for alloy steel imports. Bottom-up spindle volume estimates triangulated against top-down trailer production forecasts across utility, cargo, marine, and RV segments.
Scenario-bracketing framed demand projections across baseline, accelerated regulatory enforcement, and composite material substitution pathways. Segmentation dimensions modeled include product type tier, material grade, application duty cycle, and end-user channel structure. CAGRs derived from regression against historical replacement velocity correlated with NHTSA inspection intensity indices and fleet age demographics. Forecast inputs incorporated EPA-implicit mass reduction targets and KBA type-approval convergence patterns.
Macroeconomic conditions sit as an overlay; deviation in alloy steel scrap pricing, commercial fleet capital expenditure cycles, or NHTSA enforcement staffing levels would shift the trajectory. Forecasts reflect documented assumptions about regulatory timeline adherence and composite material qualification rates. Cross-checking against trailer registration databases and axle assembly production indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Global Air Spring Components Market
Vehicle Components
Italy Automotive Composites Market
Vehicle Components
Trailers and Semi-Trailers Market
Vehicle Components
Mobility Aids and Transportation Equipment Market
Vehicle Components
Bicycle Frames Market
Vehicle Components
Europe Trailer Axle Market
Vehicle Components
Passenger Car Sensors Market
Vehicle Components
Intelligent Rubber Tracks Market
Vehicle Components
Air Suspension Market
Vehicle Components
Vehicle Exhaust Hose Market
Vehicle Components
Crash Lock Box Market
Vehicle Components
Electric Wheelbarrow Market
Vehicle Components
Italy Automotive Glass Fiber Composites Market
Vehicle Components
Trailer Brake Controllers Market
Vehicle Components
Vehicle Radiator Market
Vehicle Components
4x4 Vehicle Parts and Accessories Market