
 Commercial Vehicles LED Bar Lights Market | 2026-2036
Commercial Vehicles LED Bar Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Vehicles LED Bar Lights Market Outlook
Fleet procurement is pivoting from fragmented owner-operator purchases toward consolidated enterprise contracts. Grote Industries leverages its OEM relationships with major truck manufacturers to sustain long-term supply agreements. Federal Signal competes across emergency and utility segments, while Hella anchors European commercial vehicle platforms with integrated lighting architectures.
Commercial vehicles LED bar lights are linear arrays of high-intensity LEDs housed in aluminum extrusions with IP67 or higher ingress protection, typically operating between 9 and 32 volts DC for universal compatibility with heavy-duty electrical systems. Straight LED bars dominate volume sales for grille and bumper mounting on highway trucks, while combo light bars capture premium positioning by integrating spot and flood beam patterns for off-road and construction applications. Work light bars serve the fastest-growing segment in agricultural machinery, where 24V systems align with modern tractor electrical architectures.
NHTSA and FMVSS 108 govern photometric output and mounting geometry for US commercial vehicles, while ECE R10 and R48 regulate electromagnetic compatibility and installation in Europe. Compliance with these frameworks shapes product development timelines and determines aftermarket access for non-certified suppliers. Stakeholders must monitor pending revisions to glare limits and connected-vehicle lighting protocols that could redefine design requirements.
Market Dynamics
Fleet consolidation across North American long-haul trucking is compressing procurement cycles and forcing LED bar suppliers to reconfigure distribution networks around enterprise contract structures rather than fragmented aftermarket channels.
Growth Catalysts
- FMVSS 108 Compliance Mandates:NHTSA photometric thresholds for auxiliary lighting on Class 8 trucks are accelerating OEM-specified LED bar adoption as manufacturers pre-certify configurations to avoid aftermarket liability exposure.
- Agricultural Machinery Electrification:Modern tractor 24V electrical architectures are creating dedicated demand for work light bars engineered to integrate with CAN bus control systems in John Deere and Case IH platforms.
- Collision Avoidance Prioritization:Fleet safety departments at Schneider National and J.B. Hunt are mandating supplemental forward lighting to reduce nighttime incident rates and insurance premium exposure.
Market Restraints
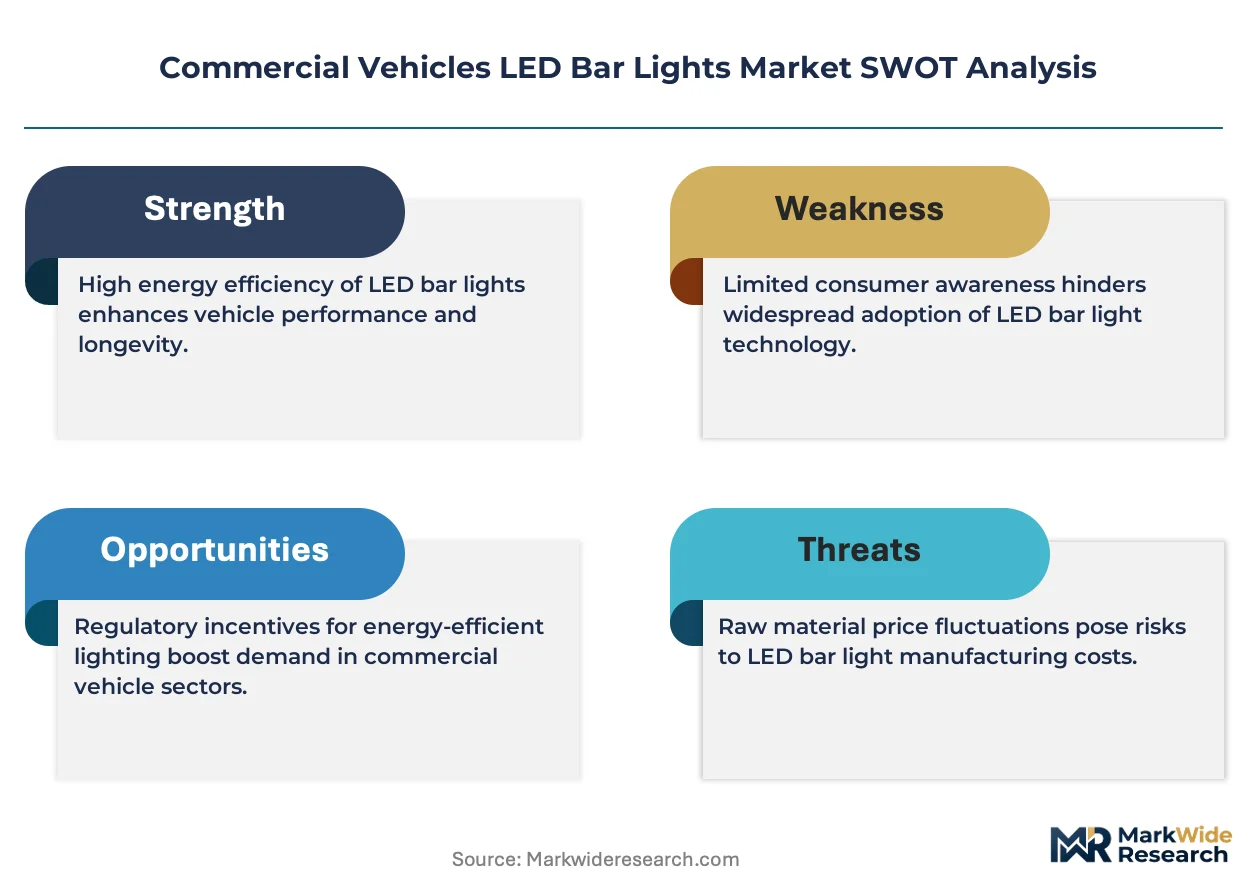
- Aluminum Extrusion Cost Volatility:Housing material costs fluctuate with London Metal Exchange pricing, compressing margin stability for mid-tier suppliers without long-term smelter contracts.
- Asian LED Chip Concentration:Epistar and Sanan Optoelectronics dominate high-intensity diode supply, creating single-source vulnerability for North American assemblers during shipping disruptions.
- IP67 Sealing Technical Ceiling:Ingress protection ratings above IP67 require specialized potting compounds and gasket engineering that extend validation timelines by 8-12 months.
Strategic Opportunities
- Connected Vehicle Lighting Protocols:SAE J3077 standards development is creating white space for LED bars with integrated telematics feedback loops that report operational status to fleet management systems.
- Canadian Prairie Agricultural Expansion:Saskatchewan and Alberta grain operators are retrofitting combines with 40-inch curved light bars for 24-hour harvest windows during narrow weather windows.
- Utility-Scale Solar Construction:EPC contractors at First Solar and NextEra projects are specifying combo beam LED bars for nighttime equipment positioning across Mojave and Texas installations.
Industry Challenges
- Photometric Engineering Talent Scarcity:Specialized optical designers capable of tuning spot-flood distributions for FMVSS compliance command premium salaries that strain mid-cap R&D budgets.
- Legacy 12V System Integration:Owner-operator retrofits on pre-2010 Freightliner and Peterbilt chassis require voltage step-down converters that introduce failure points and warranty complexity.
- ECE R10 EMC Certification Timelines:European electromagnetic compatibility testing for aftermarket suppliers creates 14-18 month market entry delays versus domestic OEM channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Vehicles LED Bar Lights Market |
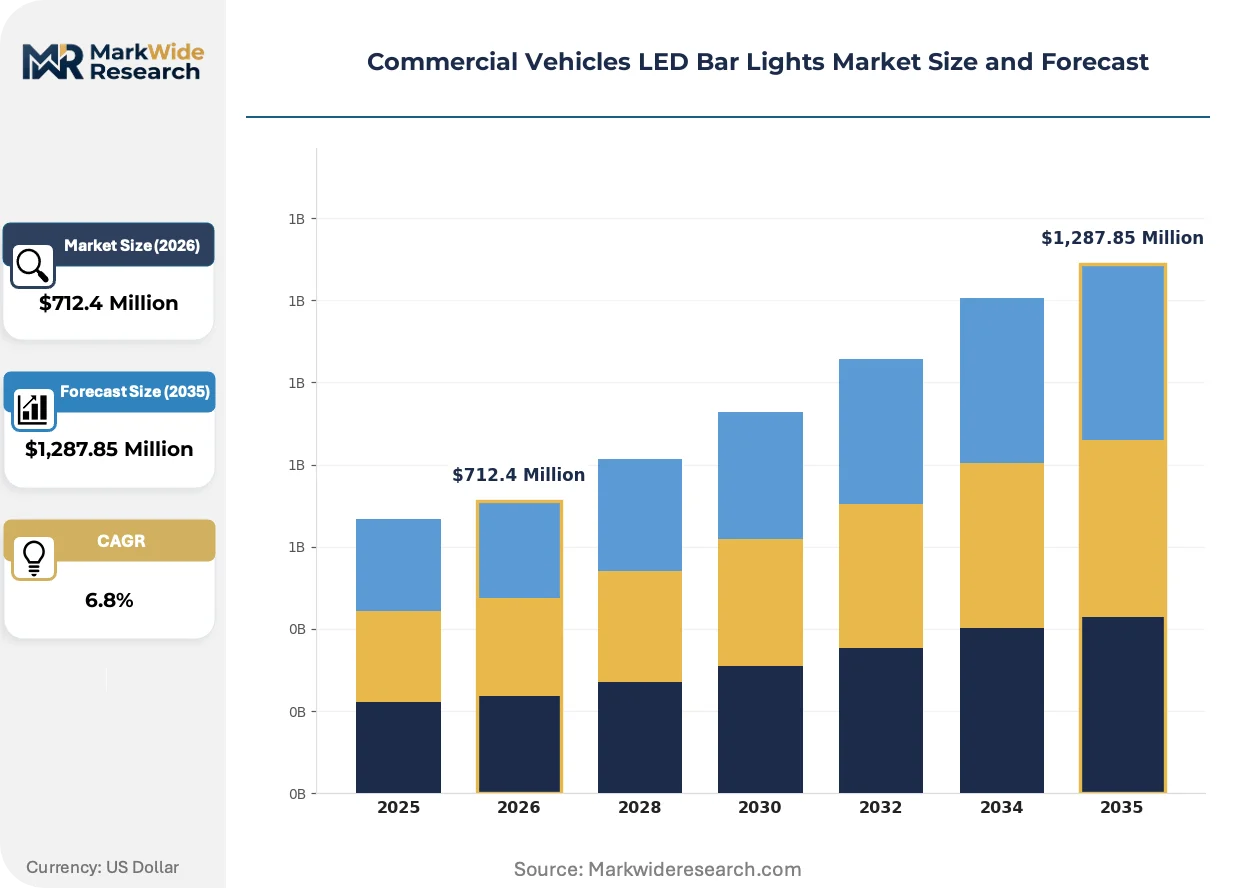
| Market Size in 2026 | $712.4 Million |
| Market Size in 2035 | $1,287.85 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Straight LED Bars, Curved LED Bars, Work Light Bars, Combo Light Bars Application: Off-Road Vehicles, Emergency Vehicles, Construction Equipment, Agricultural Machinery Installation Type: Surface Mount, Flush Mount, Wireless, Universal Fit Power Source: 12V Systems, 24V Systems, Rechargeable Batteries, Solar |
| Companies Covered | Grote Industries LLC, Federal Signal Corp., Whelen Engineering Inc., KC HiLiTES Inc., Clarience Technologies, Hella GmbH & Co. KGaA, OSRAM GmbH, Lumileds Holding B.V., Cree LED, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Vehicles LED Bar Lights Market Strategic Shifts
Active matrix LED control is displacing static binning approaches across commercial vehicle lighting, enabling real-time thermal management and beam pattern adjustment that was previously restricted to luxury automotive applications.
Adaptive thermal feedback circuitry is converging with aluminum nitride substrates to maintain consistent lumen output across ambient temperature swings from -40°F to 140°F. Grote Industries and Hella are embedding these modules in 2024 OEM programs for Freightliner Cascadia and Volvo VNL platforms. The technology is converging with predictive maintenance algorithms that flag degradation before photometric thresholds fail, compressing warranty exposure for fleet operators.
EPA SmartWay verification requirements for auxiliary lighting efficiency are tightening allowable watt-per-lumen thresholds for equipment qualifying under the program. This regulatory pressure is forcing suppliers to abandon legacy halogen-hybrid designs entirely. Long-haul carriers pursuing SmartWay certification represent the segment most affected, with Werner Enterprises and Knight-Swift specifying exclusively LED-based forward lighting in new tractor orders.
Enterprise fleet procurement departments are consolidating lighting specifications across regional operating divisions that previously maintained independent vendor relationships. This behavioral shift is displacing fragmented owner-operator aftermarket purchases as the dominant demand channel. The disruption is most visible in the United States, where Ryder System and Penske Truck Leasing are negotiating multi-year sole-source agreements with Grote and Federal Signal for standardized LED bar configurations across their rental and lease fleets.
Commercial Vehicles LED Bar Lights Market Segmentation
LED bar segmentation determines certification pathways, voltage compatibility, and thermal engineering requirements. Fleet procurement teams specify by application environment and electrical architecture rather than lumens alone. Each category carries distinct FMVSS 108 or ECE R10 compliance obligations that shape supplier qualification.
Product Type:
FMVSS 108 photometric testing applies differentially across form factors, with straight and combo configurations facing stricter forward-illumination thresholds than curved or work variants.
- Straight LED Bars:Linear aluminum extrusions with fixed beam angles dominate grille and bumper mounting on Class 8 highway tractors. Demand concentrates in US long-haul fleets at Schneider National and J.B. Hunt where forward lighting supplements meet insurance risk reduction mandates.
- Combo Light Bars:Integrated spot-flood architectures require dual-zone optical engineering for mixed terrain visibility. Construction and utility fleets at First Solar projects specify these for nighttime equipment positioning across Mojave installations where beam pattern flexibility reduces setup time.
- Curved LED Bars:Wraparound configurations broaden peripheral illumination for off-road and agricultural applications. Canadian Prairie operators in Saskatchewan retrofit combines with 40-inch curved units for 24-hour harvest windows.
- Work Light Bars:Compact arrays optimized for close-proximity task illumination on machinery arms and cab roofs. John Deere and Case IH integrate these with CAN bus control systems in modern 24V tractor architectures.
Leading the category by volume: Straight LED Bars. Growing fastest: Combo Light Bars.
Application:
End-use environments dictate ingress protection ratings, vibration tolerance, and electromagnetic compatibility requirements under ECE R10.
- Off-Road Vehicles:Mining and oilfield operators in Alberta and Texas specify IP67-plus housings with active thermal management for ambient temperature swings from -40°F to 140°F. EPA SmartWay efficiency verification is tightening watt-per-lumen thresholds for auxiliary lighting in this segment.
- Emergency Vehicles:Federal Signal and Whelen dominate supply to police and fire fleets requiring SAE Class 1 optical performance with integrated flash patterns. NHTSA mounting geometry rules constrain installation locations on ambulance and rescue chassis.
- Construction Equipment:Night shift operations at utility-scale solar EPC projects drive combo beam adoption for equipment positioning. OSHA illumination standards for work zones create minimum lumen density requirements.
- Agricultural Machinery:Modern tractor 24V electrical architectures are displacing legacy 12V systems, creating dedicated demand for voltage-matched work light bars with CAN bus integration.
Dominant by fleet contract value: Emergency Vehicles. Expanding most quickly: Agricultural Machinery.
Installation Type:
Mounting methodology determines warranty exposure and aftermarket access, with surface and flush variants carrying distinct FMVSS 108 liability profiles for OEM versus retrofit channels.
- Surface Mount:Bracket-attached configurations allow field replacement without body panel modification. Owner-operators on pre-2010 Freightliner chassis favor these for retrofit simplicity despite voltage step-down converter requirements.
- Flush Mount:Recessed integration with bumper and grille apertures dominates OEM programs for Freightliner Cascadia and Volvo VNL platforms. Grote Industries anchors long-term supply agreements through pre-certified flush configurations.
- Wireless:Battery-powered and induction-coupled units eliminate harness modification for temporary lighting needs. Utility fleets deploy these for rapid deployment in storm response scenarios.
- Universal Fit:Adjustable bracket systems span multiple chassis generations. Aftermarket distributors stock these for fragmented owner-operator demand outside enterprise procurement networks.
Highest shipment volume: Surface Mount. Steepest expansion trajectory: Flush Mount.
Power Source:
Voltage architecture alignment with host vehicle electrical systems determines thermal design and control interface compatibility.
- 12V Systems:Legacy compatibility for pre-2010 commercial vehicle parc requires step-down converters that introduce failure points. Ryder System and Penske Truck Leasing are phasing these out of standardized fleet specifications.
- 24V Systems:Modern Class 8 and agricultural machinery architectures enable direct integration with CAN bus control. Knight-Swift and Werner Enterprises specify exclusively 24V forward lighting in new tractor orders.
- Rechargeable Batteries:Lithium-ion packs with magnetic docking support portable work lighting for maintenance bays and emergency response. Runtime optimization focuses on 8-hour shift alignment.
- Solar:Photovoltaic-integrated units serve remote agricultural and construction sites lacking auxiliary power take-off. Efficiency constraints limit adoption to supplemental rather than primary illumination roles.
Commanding fleet procurement: 24V Systems. Gaining share fastest: Rechargeable Batteries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum smelter capacity in Quebec and British Columbia supplies housing extrusions for North American LED bar manufacturers. Bauxite refining clusters in the Gulf Coast region feed downstream fabrication for commercial vehicle lighting. This raw material geography shapes regional production footprints and supplier qualification pathways.
United States
Class 8 truck replacement cycles at Schneider National and J.B. Hunt drive enterprise procurement of forward lighting bars. NHTSA FMVSS 108 compliance mandates pre-certification for auxiliary lighting on highway tractors. Detroit-Warren automotive corridor hosts Grote Industries and Federal Signal engineering centers serving OEM supply agreements.
Germany
Commercial vehicle OEMs at MAN Truck and Bus specify integrated LED architectures for European platform compliance. ECE R10 electromagnetic compatibility testing creates 14-18 month certification timelines for aftermarket suppliers. Stuttgart industrial cluster anchors Hella GmbH development programs for Volvo and Daimler Truck platforms.
China
Epistar and Sanan Optoelectronics concentrate high-intensity LED chip supply for global bar light assemblers. GB standards for automotive lighting guide domestic commercial vehicle specifications. Yangtze River Delta manufacturing bases export aluminum extrusion housings to North American tier-one suppliers.
Canada
Saskatchewan and Alberta grain operators retrofit combines with curved light bars for 24-hour harvest operations. Transport Canada CMVSS 108 alignment with US standards enables cross-border product certification reciprocity. Toronto-Waterloo corridor hosts Clarience Technologies engineering for fleet telematics-integrated lighting systems.
Japan
Isuzu and Hino Motors integrate compact work light bars in medium-duty commercial platforms for ASEAN export markets. METI energy efficiency guidelines pressure auxiliary lighting watt-per-lumen performance thresholds. Nagoya industrial cluster supplies precision optical components for spot-flood beam pattern engineering.
Commercial Vehicles LED Bar Lights Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue connected-vehicle lighting protocols and predictive maintenance integration. The supplier base stratifies across three tiers: OEM-anchored incumbents with pre-certified configurations, mid-cap specialists serving fragmented aftermarket demand, and technology-focused entrants targeting SAE J3077 telematics standards. Consolidation pressures favor scale-driven procurement contracts over distributed owner-operator channels. Competitive moves center on enterprise sole-source agreements and active matrix LED control licensing.
Among North American lighting specialists, Grote Industries LLC and Federal Signal Corp. represent the OEM-anchored archetype with long-term supply agreements. Hella GmbH & Co. KGaA exemplifies European platform integration specialists serving integrated lighting architectures. Whelen Engineering Inc. occupies a position within emergency vehicle optical performance tiers requiring SAE Class 1 certification. These three anchors illustrate the geographic and functional segmentation shaping competitive positioning across fleet procurement channels.
| Leading Market Players |
|---|
| Grote Industries LLC |
| Federal Signal Corp. |
| Whelen Engineering Inc. |
| KC HiLiTES Inc. |
| Clarience Technologies |
| Hella GmbH & Co. KGaA |
| OSRAM GmbH |
| Lumileds Holding B.V. |
| Cree LED |
| Others |
Value Chain & Pricing Dynamics
Enterprise fleet consolidation at Ryder System and Penske Truck Leasing is compressing procurement into multi-year sole-source agreements, forcing suppliers to absorb aluminum extrusion cost volatility and extend warranty terms to secure contract renewals.
Pricing Analysis
Warranty bundling separates OEM-certified configurations from aftermarket alternatives, with flush-mount systems commanding premium positioning due to pre-certified FMVSS 108 compliance and predictive maintenance integration. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment tiers. Cost compression in mid-tier segments is intensifying because London Metal Exchange aluminum pricing volatility erodes margin stability for suppliers lacking long-term smelter contracts. Owner-operators on pre-2010 chassis exhibit highest price sensitivity due to voltage converter add-on costs, while enterprise procurement departments prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Photometric engineering talent scarcity in Detroit-Warren and Stuttgart automotive corridors constrains R&D scaling for active matrix LED control development. Aluminum extrusion supply concentrates in Quebec, British Columbia, and Yangtze River Delta manufacturing bases. High-intensity LED chip supply draws from Taiwan and mainland China, creating single-source vulnerability during shipping disruptions. Tariff exposure on semiconductor inputs represents the dominant structural risk. Distribution runs through tier-one automotive suppliers and specialized aftermarket distributors serving fragmented owner-operator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into aluminum smelter relationships and captive LED chip supply agreements is becoming the decisive competitive moat as procurement consolidation rewards scale and penalizes fragmented sourcing.
For Market Incumbents: To counter mid-tier margin compression from London Metal Exchange volatility, Grote Industries and Federal Signal should lock long-term aluminum offtake agreements with Quebec smelters and embed predictive maintenance algorithms to extend warranty value propositions. Certification investment in pending SAE J3077 connected-vehicle protocols will preempt emerging entrant disruption in fleet telematics integration. For New Entrants and Emerging Players: Canadian Prairie agricultural operators retrofitting combines for 24-hour harvest windows represent an underserved buyer archetype with limited incumbent presence. Saskatchewan and Alberta grain operators need curved light bars with CAN bus integration for modern 24V tractor architectures. Direct distribution partnerships with agricultural equipment dealers bypass entrenched automotive tier-one channels. For Investors and Strategic Acquirers: The window for entry favors technology-focused entrants with SAE J3077 protocol development capabilities and active matrix LED control IP. Long-term viability hinges on consolidation plays that combine photometric engineering talent pools with enterprise fleet contract access. Watch for EPA SmartWay efficiency threshold revisions as the inflection signal that accelerates halogen-hybrid displacement and rewards pure-LED suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Aluminum Supply Agreement | Quebec smelter contracts insulate margin stability against London Metal Exchange volatility for tier-one assemblers. |
| SAE J3077 Protocol Certification | Preemptive compliance with connected-vehicle lighting standards secures fleet telematics integration contracts. |
| Active Matrix LED Control Licensing | Thermal feedback circuitry IP licensing generates recurring revenue from OEM platform standardization programs. |
| Agricultural Dealer Channel Partnership | Direct access to John Deere and Case IH retrofit demand bypasses fragmented automotive aftermarket distribution. |
| Predictive Maintenance Algorithm Development | Photometric degradation flagging compresses warranty exposure for Knight-Swift and Werner Enterprises fleet contracts. |
Study Parameters
Multi-period observation of Class 8 truck replacement cycles, fleet safety department procurement mandates, and aluminum smelter capacity utilization anchored the trend analysis, supplemented by interviews with OEM platform engineers, aftermarket distributor procurement heads, fleet safety directors at Schneider National and J.B. Hunt, and agricultural equipment dealer principals. Secondary validation drew from NHTSA FMVSS 108 regulatory filings, EPA SmartWay verification databases, SEC 10-K disclosures from listed automotive suppliers, and vehicle production data from IHS Markit. Bottom-up channel volume estimates and top-down fleet spending allocation models were cross-referenced for triangulation.
Input-output matrices mapped LED chip supply from Epistar and Sanan Optoelectronics through North American assembly operations to end-use segmentation across highway trucking, agricultural machinery, and construction equipment. The analytical framework modeled product type, application environment, voltage architecture, and installation methodology across the projection horizon. CAGRs were derived from fleet replacement rate projections and retrofit penetration assumptions. Forecast inputs incorporated pending NHTSA glare limit revisions and ECE R10 EMC certification timeline impacts on aftermarket supplier market entry.
Revisions become necessary when NHTSA finalizes connected-vehicle lighting protocol amendments, aluminum tariff structures shift, or shipping disruptions alter LED chip supply availability from Asian foundries. Material deviation in these triggers warrants pause and re-evaluation of volume and value trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Nigeria Automotive Lubricants Market
Automotive Parts
Automotive Screenwash Products Market
Automotive Parts
Friction Pads Market
Automotive Parts
Global Automotive Cup Holder Market
Automotive Parts
Europe Ball Bearings Market
Automotive Parts
Wiper Systems Market
Automotive Parts
Racing Motor Bike Seat Unit Market
Automotive Parts
Passenger Car Motor Oil Market
Automotive Parts
Electric Parking Brake Actuator Components Market
Automotive Parts
Canada Automotive Parts Die Casting Market
Automotive Parts
Global Inductive Loop Vehicle Detector Market
Automotive Parts
Global Automotive Motor Oil Market
Automotive Parts
Brazil Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Surface Coated Brake Market
Automotive Parts
Automotive Tire Molds Market
Automotive Parts
Automotive Roller Bearing Market