
 Automotive Pyrofuse Market | 2026-2036
Automotive Pyrofuse Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Pyrofuse Market Insights
The EU Green Deal is pivoting automotive electrical safety requirements toward mandatory high-voltage circuit protection in all new electrified platforms. Daicel Corporation leverages its explosives chemistry heritage to dominate precision initiation systems for pyrofuse applications. Autoliv anchors its position through vertical integration into airbag and seatbelt pretensioner channels where pyrofuses serve as critical actuation elements. Littelfuse competes by extending its broad circuit protection portfolio into automotive-specific pyrofuse variants engineered for 800-volt battery architectures.
An automotive pyrofuse is a single-use, explosively actuated circuit interrupter that severs high-current conductors within milliseconds using a pyrotechnic charge and shaped cutter mechanism, primarily protecting battery packs and passenger restraint systems from thermal runaway or crash-induced electrical faults. High-speed pyrofuse variants occupy the dominant revenue share due to their deployment in lithium-ion battery disconnect circuits where microsecond-level interruption prevents cascade failures. Battery protection systems represent the fastest-growing application segment as 800-volt EV platforms from vehicle assemblers and Tier-1 suppliers multiply the per-vehicle unit count and functional redundancy requirements.
The EU AI Act and MDR frameworks, alongside China's GB standards and NMPA automotive safety directives, collectively mandate traceable, certifiable pyrotechnic components with documented failure-mode reliability across temperature extremes. EPA and NHTSA in the United States enforce comparable crashworthiness and environmental compliance thresholds that shape product qualification timelines and supplier qualification burdens. Stakeholders must monitor how divergent certification regimes between EMA-aligned European markets and MIIT-governed Chinese protocols influence modular platform strategies and regional manufacturing footprints.
Market Dynamics
The migration toward 800-volt EV architectures is compressing pyrofuse qualification timelines and multiplying per-vehicle unit counts, forcing suppliers to scale precision initiation manufacturing while maintaining explosives-handling certifications across divergent regulatory regimes.
Growth Catalysts
- EU Green Deal vehicle electrification mandates:Mandatory high-voltage circuit protection requirements in all new electrified platforms are creating installed-base demand for pyrofuse systems across German, French, and Italian OEM supply chains.
- Lithium-ion battery thermal runaway protection:Battery protection systems in electric vehicles require microsecond-level circuit interruption to prevent cascade failures, positioning high-speed pyrofuse variants as non-substitutable safety components.
- China MIIT dual carbon goals:Domestic EV production quotas and NMPA automotive safety directives are accelerating local certification of pyrotechnic components for high-voltage battery architectures.
Market Restraints
- Explosives precursor supply concentration:Specialty initiator chemicals and precision-machined cutter mechanisms concentrate among Japanese and South Korean chemical processors, creating input cost volatility and single-source vulnerability.
- Cross-regional certification friction:EMA-aligned European traceability requirements under EU AI Act and MDR frameworks diverge from MIIT-governed Chinese GB standards, forcing redundant qualification expenditures and platform fragmentation.
- Electromechanical fuse substitution:Solid-state circuit breakers and hybrid electromechanical interrupters are capturing lower-current segments in auxiliary EV systems, compressing addressable volume for pyrotechnic solutions below 400-amp thresholds.
Strategic Opportunities
- India PLI scheme for advanced automotive electronics:Domestic manufacturing incentives and BIS certification pathways for pyrotechnic safety components are opening localized supply opportunities as Indian OEMs electrify commercial vehicle platforms.
- Passenger restraint system convergence:Pyrofuse integration into seatbelt pretensioner and airbag initiation channels creates dual-use manufacturing economies for suppliers with explosives chemistry heritage.
- ISO 26262 functional safety certification:ASIL-D rated pyrofuse architectures for autonomous vehicle battery management systems command premium positioning in next-generation EV architectures from German and Japanese vehicle assemblers.
Industry Challenges
- Pyrotechnic chemist talent scarcity:Specialized explosives formulation expertise and precision initiation engineering skills concentrate among aging workforces in Japan and Germany, constraining R&D throughput and technology transfer.
- Multi-regional manufacturing footprint capex:EMA, NMPA, and EPA explosives-handling facility certifications each require dedicated cleanroom infrastructure and segregated production lines, amplifying capital intensity for geographic diversification.
- Legacy 400-volt platform integration complexity:Retrofitting pyrofuse protection into existing EV architectures originally designed for electromechanical fuses demands custom housing geometries and control system recalibration, extending program timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Pyrofuse Market |
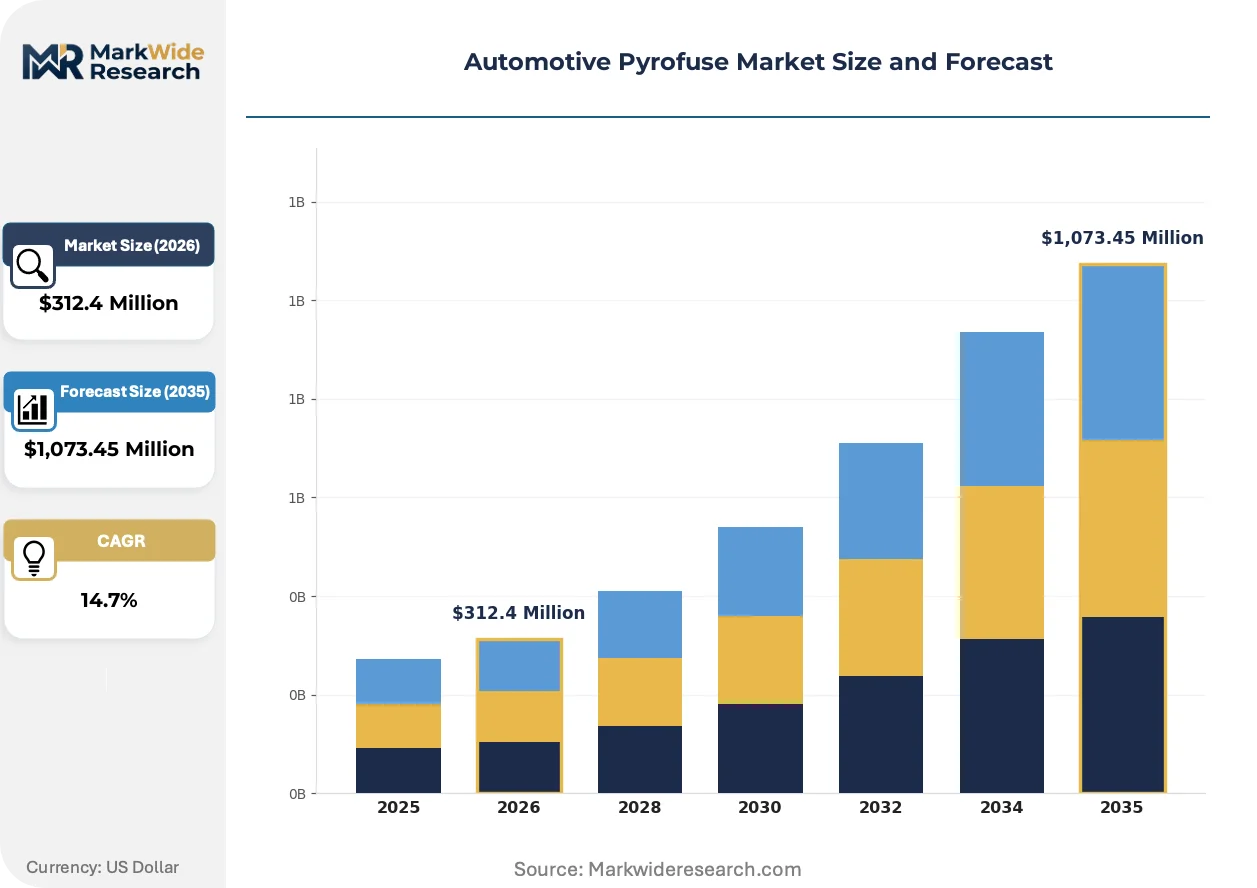
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,073.45 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Speed Pyrofuse, Time-Delay Pyrofuse, Automotive-specific Pyrofuse, Ultra-Fast Pyrofuse Technology: Thermal Activation, Explosive Initiation, Electrical Actuation, Chemical Ignition Application: Airbag Systems, Seatbelt Pretensioners, Engine Control Units, Battery Protection Systems End User: Vehicle Assemblers, Tier-1 Suppliers, Aftermarket Service Providers, Automotive Dealerships |
| Companies Covered | Daicel Corporation, Autoliv, Littelfuse, Mersen, Eaton, Pacific Engineering Corporation, MTA Group, Schaltbau, Xi’an Sinofuse Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Pyrofuse Market Trends and Innovations
Automotive electrical safety is pivoting from passive protection toward active, software-coordinated pyrotechnic interruption systems that integrate with battery management and crash-sensing networks in real time.
Smart pyrofuse architectures with integrated current sensing and predictive triggering algorithms are converging with 800-volt silicon carbide power electronics to enable sub-millisecond fault isolation before thermal propagation begins. Korean and German battery pack assemblers are qualifying these systems for premium EV platforms launching through 2027. The technology is converging with distributed battery management topologies, compressing the addressable market for standalone mechanical fuses in high-voltage zones.
REACH authorization requirements for lead-based initiator compounds are forcing reformulation of primary explosives toward nitrogen-rich energetic materials with equivalent initiation reliability across temperature extremes. This regulatory pressure is reshaping supplier qualification criteria and raw material sourcing patterns. European pyrofuse manufacturers are responding by verticalizing into in-house initiator synthesis to secure supply chain control over next-generation chemistries.
Fleet operators and vehicle leasing companies are unbundling pyrofuse replacement liability from traditional warranty structures, creating aftermarket service contracts indexed to battery cycle counts rather than calendar time. This consumption-pattern shift is disrupting OEM-captive parts distribution and opening independent service channels in Germany, Japan, and California. Commercial EV verticals with intensive duty cycles are driving this transition fastest, compressing replacement intervals and expanding addressable aftermarket volume.
Automotive Pyrofuse Market Segmentation
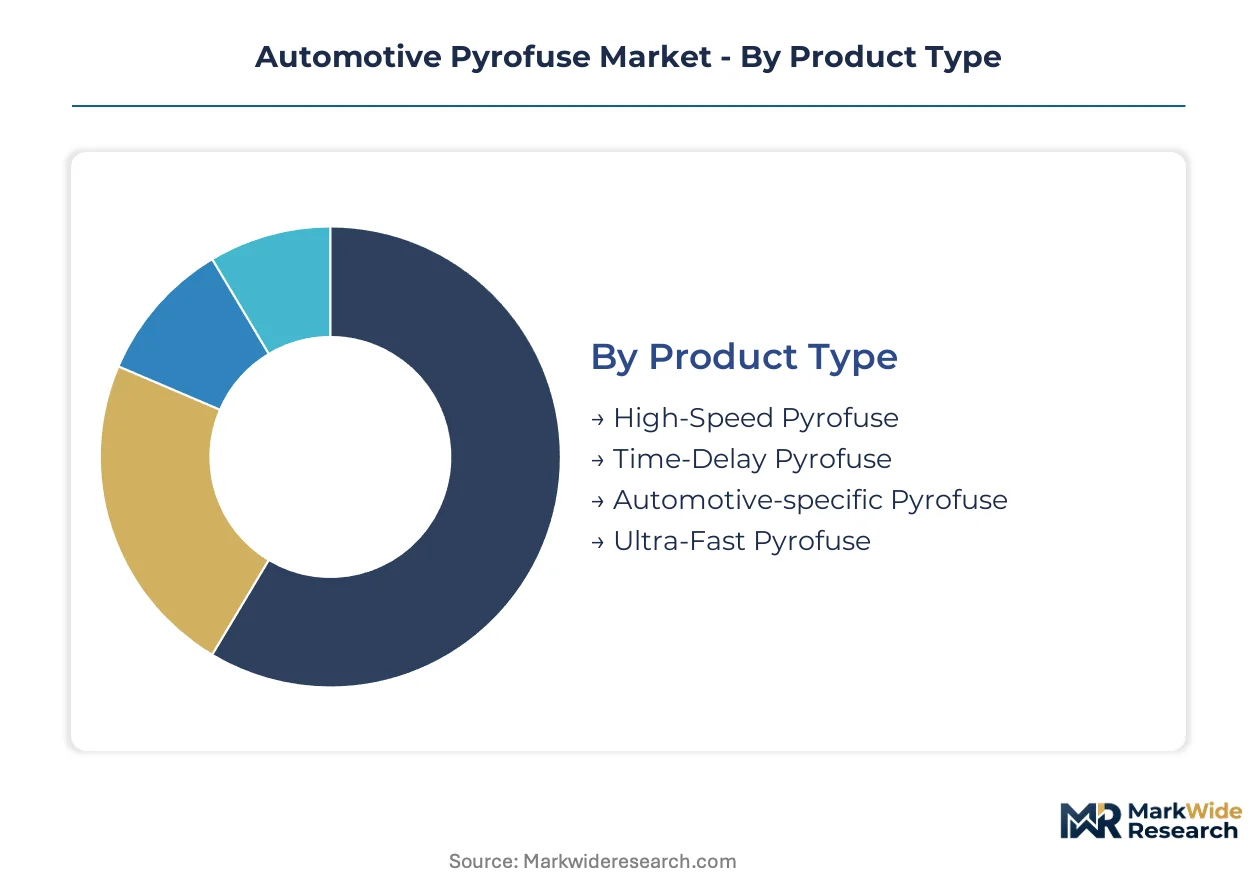
Pyrofuse segmentation reveals how interruption speed requirements and activation mechanisms fragment manufacturing capabilities across suppliers. Technical differentiation in initiation systems and application-specific certification burdens create distinct competitive arenas with divergent margin structures.
Product Type:
Volume concentration favors standard-speed variants, while premium positioning attaches to specialized architectures engineered for next-generation battery platforms.
- High-Speed Pyrofuse:Microsecond-level interruption capability using precision-machined copper cutters and primary explosive charges. Demand concentrates in German and South Korean battery pack architectures where 800-volt platforms require cascade failure prevention.
- Time-Delay Pyrofuse:Engineered intentional latency permits transient current spikes while maintaining protection against sustained faults. Japanese OEMs specify these for airbag deployment circuits where timing synchronization with crash sensors is critical.
- Automotive-specific Pyrofuse:Housings and terminals conform to AEC-Q200 qualification and ISO 26262 functional safety ratings.
- Ultra-Fast Pyrofuse:Sub-millisecond severing using advanced shaped-charge geometries for silicon carbide power electronics protection.
Mature deployment sits with High-Speed Pyrofuse. Newer deployment is concentrated in Ultra-Fast Pyrofuse.
Technology:
Activation mechanism selection traces directly to application safety integrity level requirements and thermal environmental specifications.
- Explosive Initiation:Primary explosives (lead azide, diazodinitrophenol) drive precision cutters through busbar conductors. Daicel Corporation and South Korean chemical processors dominate initiator supply for battery disconnect applications.
- Thermal Activation:Shape-memory alloy or fusible link triggers enable passive, current-independent actuation. Seatbelt pretensioner channels favor these for crash-pulse-agnostic reliability.
- Electrical Actuation:Squib-based systems integrate with vehicle crash sensing networks for commanded interruption. German OEMs mandate these for autonomous vehicle battery management architectures requiring predictive fault isolation.
- Chemical Ignition:Gas-generating pyrotechnic compositions produce pressure-driven contact separation. Limited deployment in legacy engine compartment applications.
Established qualification pathways favor Explosive Initiation. Expanding most quickly is Electrical Actuation.
Application:
Passenger restraint convergence with battery protection is compressing the addressable market for standalone mechanical fuses in high-voltage zones.
- Battery Protection Systems:Cell-to-pack architectures multiply per-vehicle unit counts as 800-volt platforms demand redundant disconnect circuits. Chinese MIIT certification requirements and EU Green Deal mandates are accelerating specification.
- Airbag Systems:Pyrofuse actuation of inflator squibs remains the dominant volume application. Deployment concentrates with Japanese and German Tier-1 suppliers maintaining captive pyrotechnic manufacturing.
- Seatbelt Pretensioners:Micro-gas generator integration requires compact initiation systems with millisecond response.
- Engine Control Units:Legacy 12-volt circuit protection with limited growth trajectory.
Volume concentration sits with Airbag Systems. Steepest expansion trajectory is Battery Protection Systems.
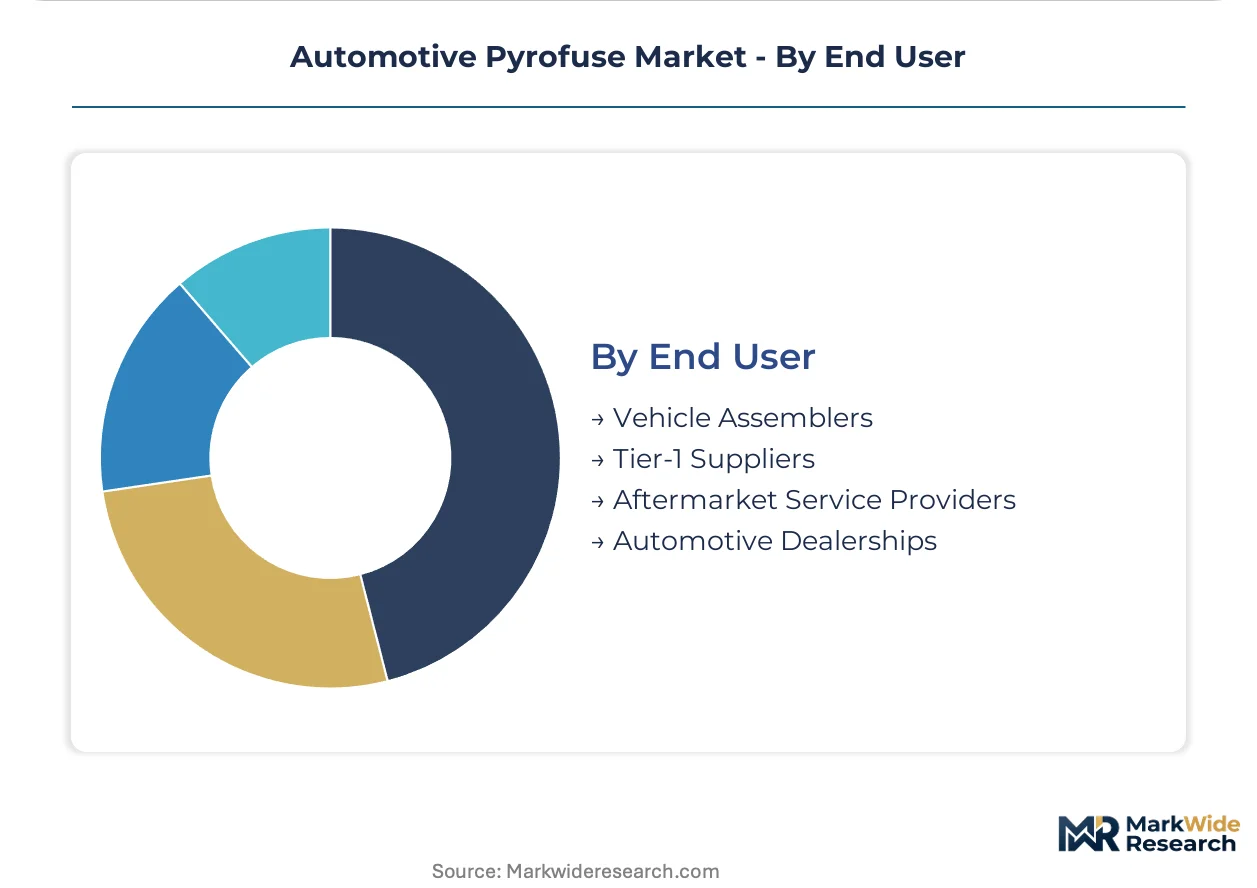
End User:
Procurement authority patterns split between OEM-captive integration and independent aftermarket channels.
- Tier-1 Suppliers:Autoliv, ZF, and Hyundai Mobis consolidate pyrofuse specification authority through seatbelt and airbag system integration. These suppliers qualify dual-use manufacturing for restraint and battery protection applications.
- Vehicle Assemblers:German and South Korean OEMs increasingly specify pyrofuse architectures directly for battery pack platforms, bypassing Tier-1 mediation in high-voltage domains.
- Aftermarket Service Providers:Fleet operators in California and Germany are unbundling replacement liability from warranty structures.
- Automotive Dealerships:Limited technical capability constrains participation to referral and logistics roles.
Specification authority concentrates with Tier-1 Suppliers. Direct OEM procurement is gaining share fastest in Vehicle Assemblers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors pyrofuse specification authority through German OEM battery platform engineering, while regulatory mandates across multiple jurisdictions reshape manufacturing footprints and certification requirements.
Germany
Bavarian and Baden-Württemberg battery pack assemblers specify pyrofuse architectures directly for 800-volt platforms from BMW and Porsche. KBA enforces UN ECE R100 compliance for high-voltage safety components. The Stuttgart industrial corridor concentrates Tier-1 supplier engineering centers where pyrofuse qualification timelines compress.
China
CATL and BYD scale cell-to-pack architectures multiplying per-vehicle pyrofuse unit counts. MIIT dual carbon goals and NMPA automotive safety directives mandate certifiable pyrotechnic components with documented failure-mode reliability. The Yangtze River Delta clusters domestic initiator synthesis facilities responding to GB standard reformulation pressures.
Japan
Toyota and Honda integrate pyrofuses into hybrid and solid-state battery prototypes requiring precision initiation systems. METI oversees explosives-handling facility certifications constraining geographic diversification. The Nagoya industrial zone concentrates Daicel Corporation manufacturing leveraging explosives chemistry heritage.
South Korea
Hyundai Mobis and LG Energy Solution qualify high-speed variants for E-GMP platform battery disconnect circuits. MFDS aligns with UN ECE frameworks while maintaining distinct national certification pathways. The Busan-Ulsan corridor hosts precision-machined cutter mechanism production serving domestic and export demand.
United States
Tesla and Rivian specify pyrofuse protection for Cybertruck and R1 platforms with silicon carbide power electronics integration. NHTSA crashworthiness standards and EPA environmental compliance shape qualification timelines. The California Bay Area clusters autonomous vehicle battery management system development demanding ASIL-D rated architectures.
Automotive Pyrofuse Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification burden and initiation system precision. The vendor base concentrates among explosives chemistry specialists and diversified circuit protection conglomerates. Three archetypes dominate: Japanese chemical processors with heritage initiator synthesis, European automotive safety integrators with restraint system channels, and North American electrical protection specialists extending into automotive variants. Capacity expansion and strategic partnerships constitute the dominant competitive moves as 800-volt platform qualification timelines compress.
Among Japanese chemical specialists, Daicel Corporation exemplifies explosives heritage positioning. Autoliv represents European automotive safety integration archetypes. Littelfuse occupies a position bridging electrical protection breadth with automotive-specific variant development. These three anchors illustrate how supplier qualification burdens and regional certification fragmentation stratify competitive positioning across the pyrofuse value chain.
| Leading Market Players |
|---|
| Daicel Corporation |
| Autoliv |
| Littelfuse |
| Mersen |
| Eaton |
| Pacific Engineering Corporation |
| MTA Group |
| Schaltbau |
| Xi'an Sinofuse Electric |
| Others |
Pricing and Supply Chain Analysis
Captive initiator synthesis among Japanese and South Korean chemical processors anchors both supply security and premium pricing power for high-speed pyrofuse variants serving 800-volt battery architectures. This backward integration into primary explosives manufacturing insulates qualified suppliers from raw material volatility while commanding ASIL-D certification premiums.
Pricing Analysis
Outcome-based pricing tied to thermal-runaway prevention reliability dominates battery protection contracts, with German OEMs paying premiums for documented microsecond-level interruption performance. Price differentiation separates ISO 26262 ASIL-D certified architectures from standard AEC-Q200 qualified units, while volume scale discounts compress margins for airbag-system pyrofuses. Pricing pressure intensifies in auxiliary circuits below 400 amps where solid-state circuit breakers displace pyrotechnic solutions. Fleet operators exhibit highest price sensitivity through unbundled aftermarket service contracts, whereas autonomous vehicle battery management programs show lowest sensitivity due to liability exposure.
Supply Chain Analysis
Specialized freight handling for explosives-classified initiator chemicals elevates logistics costs disproportionately for cross-regional shipments from Japan and South Korea to European battery pack assembly plants. Primary explosives supply concentrates in Nagoya industrial zone facilities and Busan-Ulsan corridor chemical processors, with precision-machined copper cutter mechanisms sourced from German toolmakers. Single-source vulnerability in lead azide and diazodinitrophenol feedstocks creates exposure to REACH authorization disruptions for legacy initiator compounds. Distribution runs through Tier-1 supplier consolidation points where Autoliv and Hyundai Mobis qualify dual-use manufacturing for restraint and battery protection channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive pyrofuse sector is accelerating into a vertical-integration race as 800-volt platform qualification timelines compress, with upstream control over initiator synthesis emerging as the decisive margin lever.
For Market Incumbents: Deepen backward integration into nitrogen-rich energetic material synthesis to secure supply chain control over next-generation initiator chemistries forced by REACH lead-compound restrictions. Expand cleanroom explosives-handling capacity in the Yangtze River Delta to capture China MIIT certification volume for domestic EV production quotas. Electromechanical fuse substitution in sub-400-amp auxiliary circuits demands defensive positioning through ASIL-D functional safety certification investments. For New Entrants and Emerging Players: Capture aftermarket service contract opportunities in California and Germany where fleet operators unbundle pyrofuse replacement liability from OEM warranty structures. India's PLI scheme for advanced automotive electronics offers the most penetrable geographic entry point through BIS certification pathways for commercial vehicle electrification. A go-to-market angle targeting independent battery pack assemblers bypasses Tier-1 supplier consolidation. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified circuit protection conglomerates seeking automotive-specific pyrotechnic capabilities. Long-term viability hinges on explosives-handling facility certifications across EMA, NMPA, and EPA jurisdictions, favoring targets with existing multi-regional cleanroom infrastructure. Watch for inflection signals in silicon carbide power electronics adoption rates that multiply ultra-fast pyrofuse unit counts per vehicle.| Strategic Initiative | Industry Significance |
|---|---|
| Initiator Synthesis Verticalization | REACH-compliant nitrogen-rich energetic materials secure supply chain control against lead-azide authorization risks. |
| Multi-Regional Cleanroom Expansion | EMA, NMPA, and EPA explosives-handling certifications enable platform qualification across German, Chinese, and US OEM supply chains. |
| ASIL-D Functional Safety Certification | Autonomous vehicle battery management architectures from German and Japanese assemblers command premium positioning. |
| Aftermarket Service Contract Development | Fleet operators in California and Germany unbundle replacement liability from traditional OEM warranty structures. |
| Smart Pyrofuse Architecture R&D | Integrated current sensing and predictive triggering algorithms converge with 800-volt silicon carbide power electronics. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, explosives-handling facility operators, and battery pack assembly technical leads. UN ECE R100 compliance documentation, MIIT automotive safety directives, NHTSA crashworthiness standards, and EPA environmental filings provided regulatory traceability. Vehicle production databases and IHS Markit registration data supplied volume benchmarks. Bottom-up unit economics triangulated against top-down market sizing from automotive safety component trade flows.
Reconciliation of production volume data, content-per-vehicle assumptions, and regional electrification trajectories shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include interruption speed tier, activation mechanism, application channel, and end-user procurement authority. CAGRs derived from fitted growth curves applied to battery protection system adoption rates and passenger restraint system convergence patterns. Pyrotechnic chemist workforce constraints and multi-regional certification capex requirements informed capacity expansion assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state circuit breaker substitution rates, REACH authorization timelines for lead-based initiators, and divergent EU-China certification regime alignment. Forecasts reflect documented assumptions about 800-volt platform penetration and explosives-handling facility certification throughput. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
LAMEA Vehicle Exhaust Hose Market
Vehicle Components
UK Automotive Carbon Fiber Composites Market
Vehicle Components
Locomotive Lighting Batteries Market
Vehicle Components
Global Automotive Carbon Fiber Composites Market
Vehicle Components
Trailers and Semi-Trailers Market
Vehicle Components
Global Undercarriage Components Market
Vehicle Components
Argentina Automotive Carbon Fiber Composites Market
Vehicle Components
Automotive Sensors Market
Vehicle Components
Two Wheeler Footrest Market
Vehicle Components
Grille Guard Market
Vehicle Components
Bicycle Components Aftermarket Market
Vehicle Components
Crash Lock Box Market
Vehicle Components
Global Automotive Wheel Bearings Market
Vehicle Components
Automotive Brake Valves Market
Vehicle Components
Global Fuel Tank and Delivery System Market
Vehicle Components
Charge Air Coolers Market