
 Global Automotive Aluminum Market | 2026-2036
Global Automotive Aluminum Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Aluminum Market Intelligence
The trend of supplying modular, pre-fabricated aluminum sub-assemblies instead of raw material forms is realigning OEM procurement strategies. This shift favors suppliers with advanced fabrication and joining capabilities. Novelis specializes in high-recycled-content aluminum sheet for body panels, meeting sustainability targets for automakers. Constellium leverages its expertise in complex extrusions for crash management systems and battery enclosures. Norsk Hydro ASA differentiates through its supply of low-carbon primary aluminum, appealing to brands focused on lifecycle emissions.
Automotive aluminum refers to specific alloys, primarily from the 5000 and 6000 series, engineered for high strength-to-weight ratios, corrosion resistance, and formability. These materials are essential for lightweighting vehicles to improve fuel efficiency or extend electric vehicle range. Rolled aluminum products command a significant share, forming the basis for most body panels supplied directly to OEMs. Within applications, the use in engine components is mature, while adoption for complete body-in-white structures represents a primary growth frontier.
Regulatory frameworks are a principal catalyst for aluminum adoption in vehicles. The US EPA’s stringent corporate average fuel economy (CAFE) standards incentivize mass reduction. In Europe, the End-of-Life Vehicles (ELV) Directive and the EU Green Deal encourage the use of highly recyclable materials like aluminum. China's dual carbon goals similarly push its vast automotive industry toward lighter and more sustainable material inputs. The critical decision for market participants involves balancing investments in recycling capacity against securing long-term contracts for low-carbon primary metal.
Market Dynamics
The central dynamic in the automotive aluminum market is the structural substitution of steel, driven by a confluence of stringent global emissions regulations and the specific technical requirements of battery electric vehicles for mass reduction and structural rigidity.
Growth Catalysts
- Regulatory Mandates:The US EPA's CAFE standards and the EU Green Deal directly compel automakers to improve fleet efficiency, making aluminum's lightweighting properties a primary compliance tool for reducing vehicle mass and lowering emissions.
- Electric Vehicle Architecture:The demand for large, complex aluminum battery enclosures to protect cells and manage thermal loads represents a significant, high-value application that is expanding rapidly with the global transition to electric mobility.
- Geographic Demand Concentration:China's state-supported expansion of its domestic EV manufacturing ecosystem provides a massive and sustained demand signal for all forms of automotive aluminum, from body sheet to structural extrusions.
Market Restraints
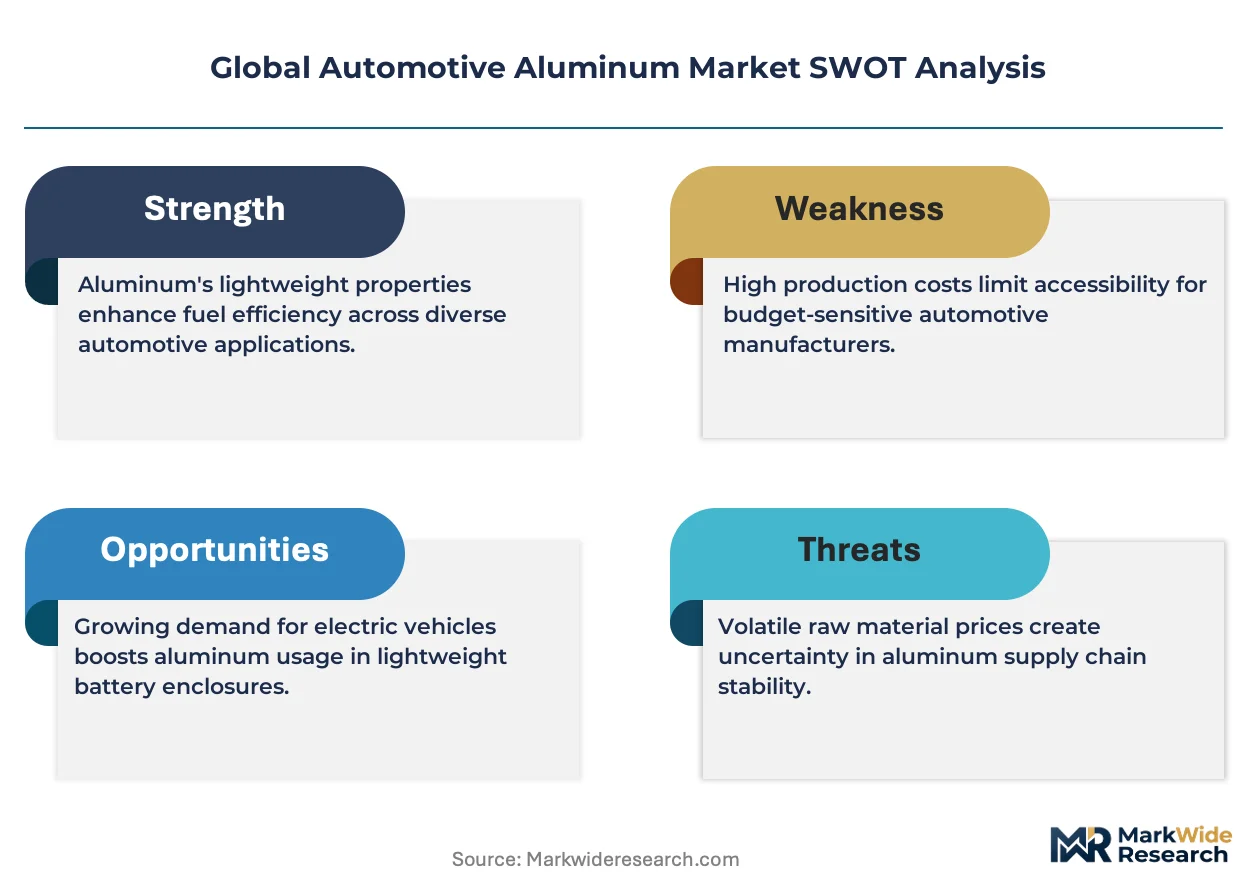
- Input Cost Volatility:The production of primary aluminum is exceptionally energy-intensive, exposing its price to fluctuations in global electricity and energy markets, creating cost uncertainty for automakers compared to more stable steel pricing.
- Multi-Material Joining Complexity:Integrating aluminum components with existing steel-based vehicle platforms requires specialized, costly joining technologies like self-piercing rivets and flow-drill screws, posing a technical and investment barrier for some OEMs.
- Substitution from Composites:In high-performance and luxury vehicle segments, advanced carbon fiber composites present a substitution threat for specific applications like body panels and structural reinforcements, competing on ultimate weight savings.
Strategic Opportunities
- Closed-Loop Recycling Systems:Establishing dedicated, closed-loop recycling partnerships with automotive OEMs to re-melt production scrap into certified, high-recycled-content aluminum sheet creates a sustainable and cost-advantaged supply chain.
- Advanced Alloy Development:There is significant opportunity in commercializing new 6000 and 7000 series alloys with enhanced strength and crash-worthiness, enabling further lightweighting in critical safety structures like B-pillars and roof rails.
- Modular Sub-Assembly Supply:Shifting from selling raw material to providing complete, pre-fabricated modules like battery trays or front-end structures allows suppliers to capture more value and simplify OEM assembly lines.
Industry Challenges
- Capital Investment Intensity:Building new rolling mills, extrusion presses, and casting facilities capable of meeting automotive quality standards and volumes requires substantial, long-term capital investment with extended payback periods.
- Skilled Labor Scarcity:A shortage of engineers and technicians with expertise in aluminum metallurgy, advanced forming processes, and sophisticated joining techniques hinders the pace of adoption and production ramp-ups at both suppliers and OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Aluminum Market |
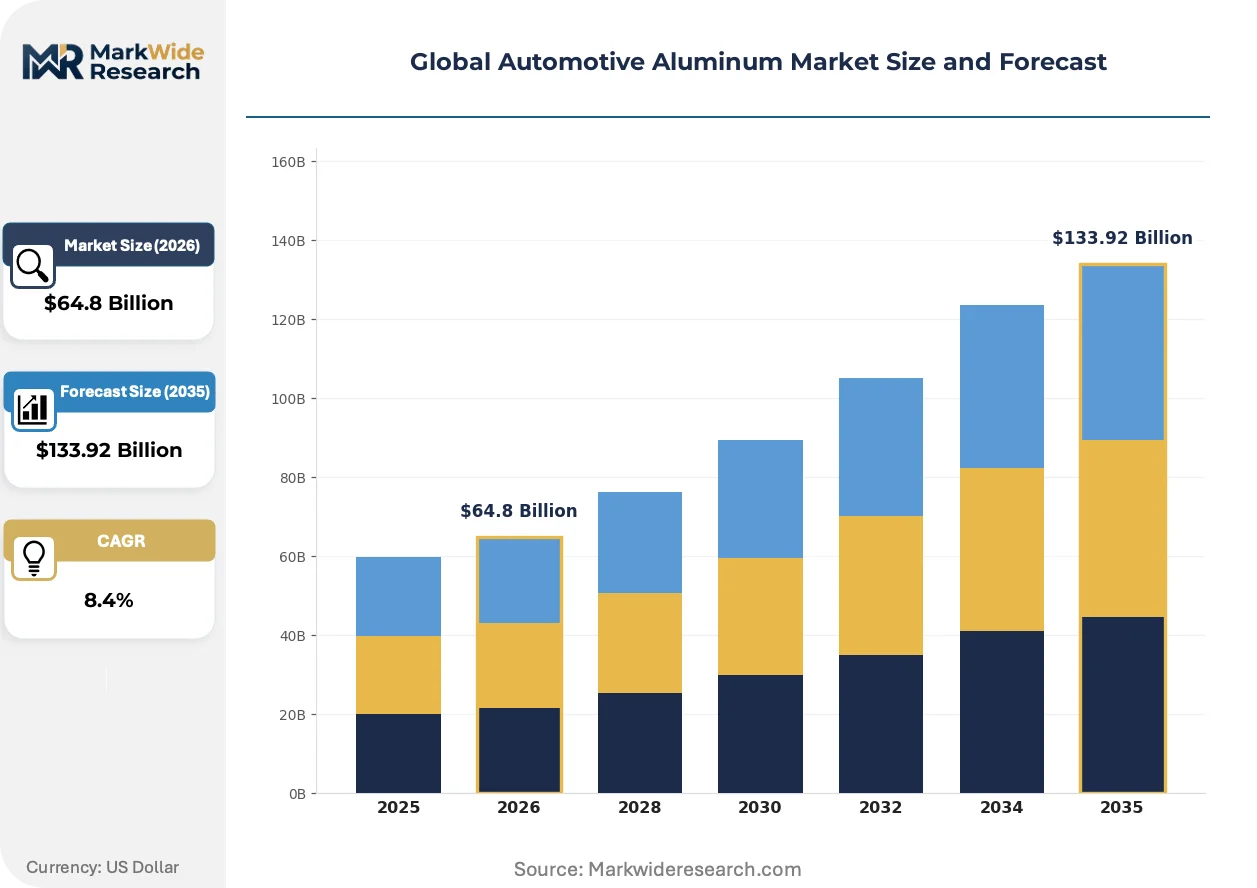
| Market Size in 2026 | $64.8 Billion |
| Market Size in 2035 | $133.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Sheet, Aluminum Extrusion, Aluminum Alloy, Aluminum Foil, Aluminum Plate Application: Body Panels, Engine Components, Heat Exchangers, Suspension Systems, Wheels End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers Form: Cast Aluminum, Rolled Aluminum, Forged Aluminum, Machined Aluminum |
| Companies Covered | Alcoa Corporation, Novelis, Norsk Hydro ASA, Constellium, Rio Tinto Group, ArcelorMittal, Arconic, UACJ Corporation, Kaiser Aluminum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Aluminum Market Strategic Shifts & Innovations
The convergence of advanced manufacturing processes with circular economy principles is defining the next evolution of aluminum use in vehicle design. This shift prioritizes not just mass reduction but also lifecycle emissions and production efficiency, creating new value streams and competitive differentiators for material suppliers.
Giga-casting, the use of massive die-casting machines to produce large, single-piece vehicle structures, is a transformative manufacturing technology. Automakers, particularly in the electric vehicle space, are rapidly adopting this method to drastically reduce part count and simplify body-in-white assembly. This process is absorbing the function of dozens of individual stamped and extruded parts into a single, complex aluminum casting, fundamentally altering vehicle architecture.
The European Union's End-of-Life Vehicles (ELV) Directive is a critical regulatory force. It establishes targets for reuse, recycling, and recovery, directly incentivizing the use of highly recyclable materials like aluminum over less recoverable alternatives. The body-in-white and closures segment is most affected, as designers must now account for disassembly and material separation at the end of the vehicle's life.
Automaker purchasing behavior is moving away from transactional buys of raw material coils and toward strategic partnerships for integrated systems. This disrupts the traditional tiered supplier model, as OEMs now prefer to source complete, functional sub-assemblies like a fully assembled battery housing directly from a single aluminum specialist. This trend is most visible in the North American EV market, where supply chain simplification is a key priority.
Global Automotive Aluminum Market Segmentation
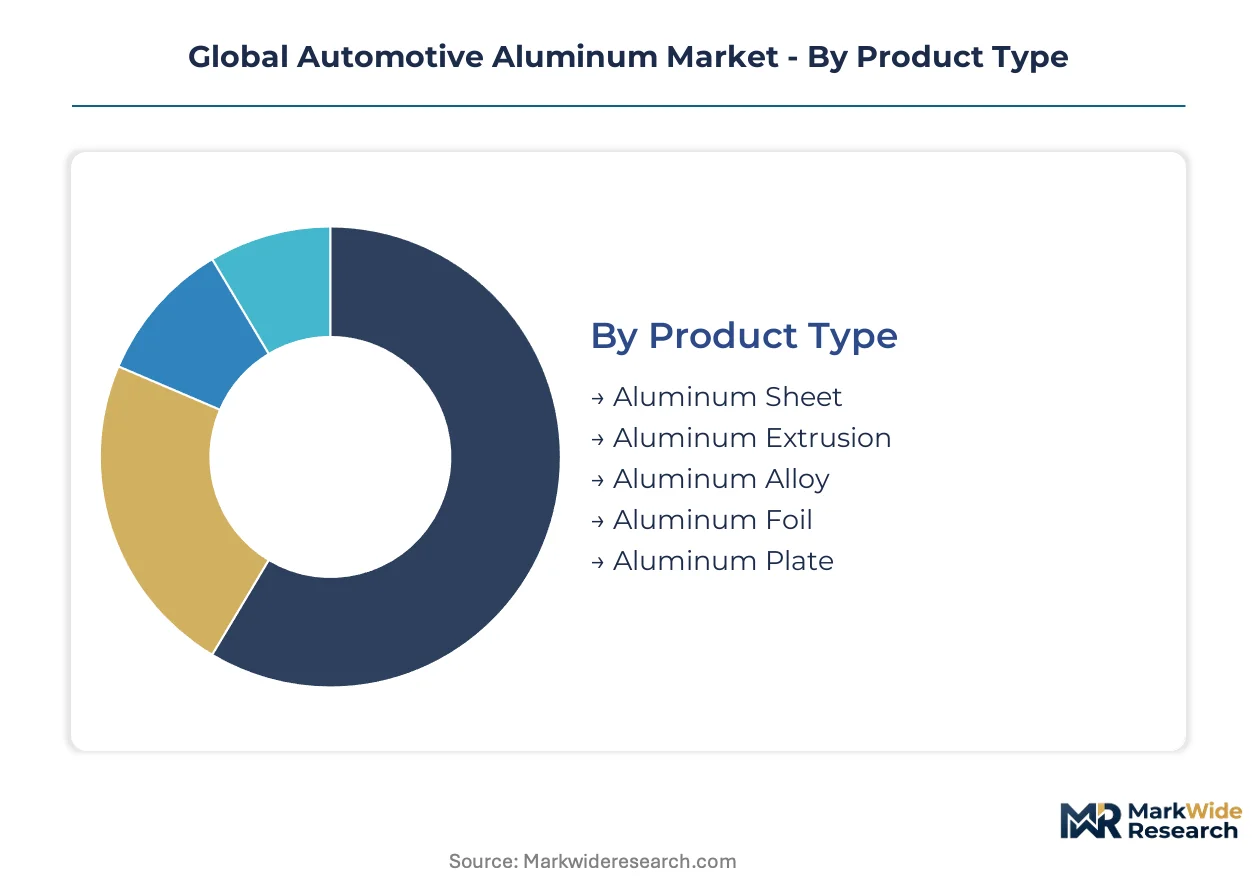
The global automotive aluminum market is precisely segmented to reflect the diverse material requirements and strategic procurement patterns of vehicle manufacturers. Understanding these segments clarifies where value is created and how material innovations are being adopted across the industry.
Product Type:
Automakers differentiate their material procurement for product types based on specific manufacturing processes and performance requirements.
- Aluminum Sheet:This refers to thin, flat aluminum material primarily derived from 5000 and 6000 series alloys, engineered for formability and strength. It is essential for body panels and closures, driven by stringent vehicle lightweighting regulations like the EU Green Deal.
- Aluminum Extrusion:Aluminum material formed by pushing through a die, creating complex cross-sections with consistent profiles. Extrusions are critical for crash management systems and battery enclosures, expanding with electric vehicle architecture demands.
- Aluminum Alloy:Specialized metallic mixtures designed for enhanced strength, corrosion resistance, or specific thermal properties in automotive structures.
- Aluminum Foil:Thin gauge aluminum often utilized in thermal management applications, particularly within battery cell components and insulation systems.
- Aluminum Plate:Thicker aluminum material employed for structural components requiring high rigidity, impact resistance, and robust load-bearing capabilities.
Volume sits with Aluminum Sheet; growth tilts toward Aluminum Extrusion.
Application:
Application areas define material specifications and design priorities for vehicle manufacturers.
- Body Panels:These are the outer vehicle surfaces, typically formed from rolled aluminum sheets to reduce mass and improve fuel efficiency. They are critical for mass reduction and aesthetic design, driven by consumer preference for fuel-efficient vehicles.
- Suspension Systems:Components connecting the vehicle to its wheels, often utilizing forged or cast aluminum for strength and weight reduction. Reducing unsprung mass improves vehicle handling and ride comfort, particularly in performance vehicles.
- Engine Components:This represents a mature application for cast aluminum parts like engine blocks, cylinder heads, and intake manifolds.
- Heat Exchangers:Utilize aluminum's high thermal conductivity for efficient heat transfer in radiators, intercoolers, and air conditioning systems.
- Wheels:Primarily cast or forged aluminum, contributing significantly to vehicle aesthetics, unsprung weight reduction, and improved performance.
Specific application requirements dictate the choice of aluminum form and alloy.
End User:
Purchasing patterns vary significantly among end-user categories based on their role in the automotive supply chain.
- OEMs (Original Equipment Manufacturers):Direct manufacturers of complete vehicles, dictating material specifications and integration strategies. OEMs seek modular sub-assemblies and long-term supply contracts, driven by supply chain simplification goals in North America.
- Tier-1 Suppliers:Provide sub-systems and complex components directly to OEMs, often fabricating aluminum into advanced parts. These suppliers require advanced fabrication and joining capabilities, responding to OEM demands for pre-fabricated units.
- Vehicle Assemblers:Focus on the efficient integration of pre-fabricated components and modules into final vehicle structures.
- Aftermarket Providers:Supply replacement parts and accessories for vehicle maintenance and customization, requiring durable and readily available aluminum components.
Supply chain integration strategies are reshaping procurement dynamics for these end users.
Form:
The physical form of aluminum determines its suitability for specific manufacturing processes and structural performance.
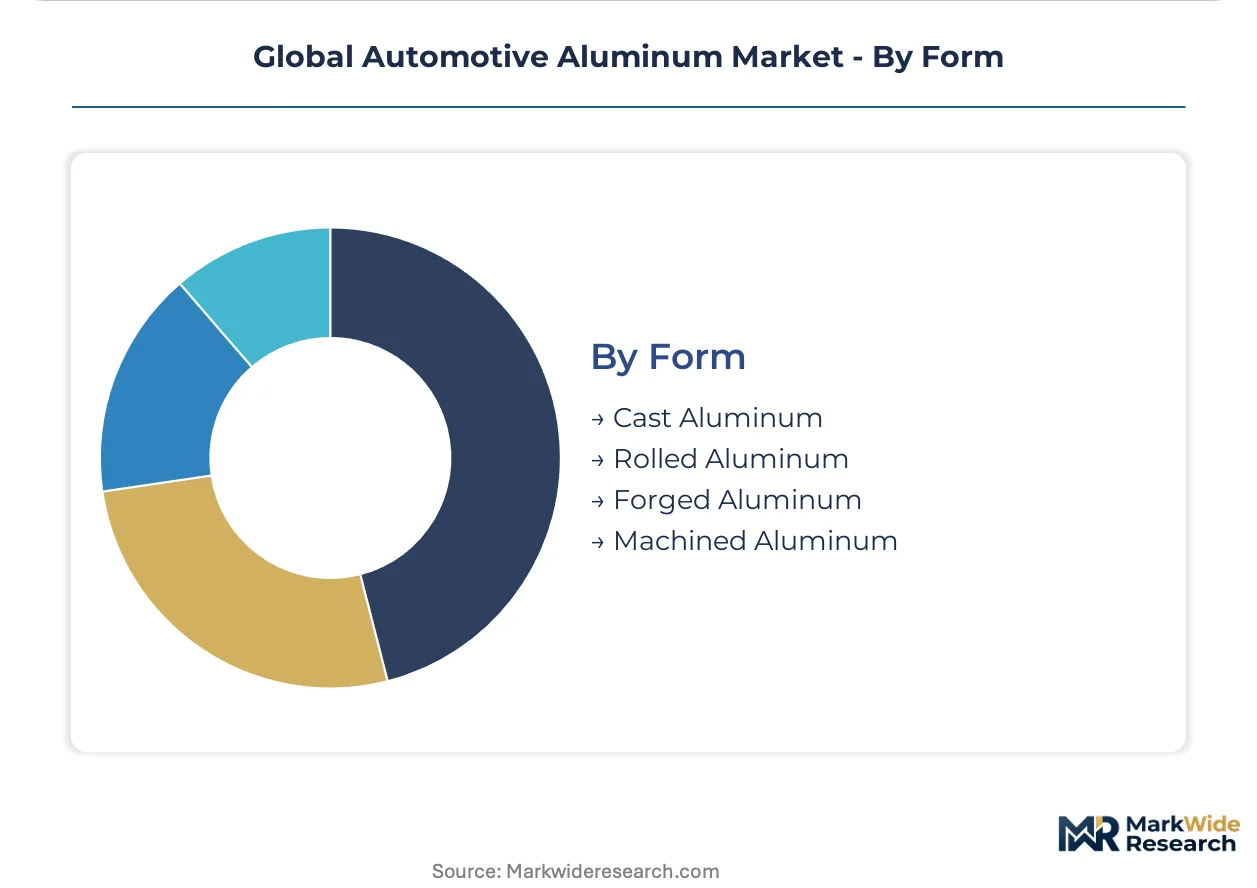
- Cast Aluminum:Aluminum shaped by pouring molten metal into a mold, suitable for creating complex geometries and large integrated parts. Giga-casting adoption for large, single-piece vehicle structures is reducing part count and simplifying assembly.
- Rolled Aluminum:Aluminum processed through rollers to reduce thickness and improve surface finish, forming sheets or plates. Rolled aluminum commands a significant share for body panels, meeting sustainability targets with high-recycled-content material.
- Forged Aluminum:Formed by compressive forces, yielding high strength, ductility, and fatigue resistance for critical load-bearing parts.
- Machined Aluminum:Precision-cut or shaped from solid aluminum blocks, used for components requiring tight tolerances and intricate details.
Process innovation, like giga-casting, is significantly expanding the application scope for specific aluminum forms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production and consumption dynamics for automotive aluminum vary significantly across major global economies. While certain regions lead in primary aluminum production, demand for finished automotive components concentrates where vehicle manufacturing thrives. This creates distinct supply chain challenges and opportunities.
China
China's state-supported EV manufacturing ecosystem drives substantial demand for automotive aluminum, especially for structural extrusions and battery enclosures. The country's dual carbon goals directly incentivize lighter vehicle architectures. In the Yangtze River Delta region, automakers are rapidly adopting giga-casting technologies to simplify body-in-white assembly.
United States
United States demand for automotive aluminum is propelled by stringent vehicle lightweighting requirements and the expanding electric vehicle market. The US EPA’s CAFE standards compel automakers to improve fleet efficiency. Michigan's automotive corridor sees significant investment in advanced joining technologies and aluminum fabrication to meet OEM demand.
Germany
Germany's premium automotive sector and commitment to sustainability generate strong demand for advanced aluminum alloys and high-recycled-content materials. The EU Green Deal and ELV Directive encourage highly recyclable materials. Bavaria's automotive clusters are advancing closed-loop recycling systems, fostering partnerships between aluminum suppliers and OEMs.
Japan
Japanese automakers prioritize lightweighting and performance, creating consistent demand for advanced aluminum sheet and high-strength extrusions. METI initiatives support material innovation and sustainable manufacturing practices. The Nagoya region remains a hub for advanced aluminum sheet applications, focusing on formability and finish.
India
India's expanding domestic automotive production and emerging electric vehicle market are increasing the uptake of aluminum components. The PLI scheme for advanced automotive components incentivizes local manufacturing and material substitution. The Chennai-Bengaluru industrial corridor is attracting significant investments in aluminum fabrication.
Global Automotive Aluminum Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the automotive aluminum market, influencing material supply and component integration. The market exhibits a tiered structure, with primary metal producers at one end and advanced fabricators at the other, each addressing different points in the value chain. Strategic archetypes include integrated material suppliers, specialized component manufacturers offering pre-fabricated modules, and regional niche players serving specific OEM needs. Capacity expansion, particularly in recycling infrastructure, and strategic partnerships for closed-loop systems represent dominant competitive moves.
Within the advanced fabrication tier, Novelis exemplifies a specialist in high-recycled-content aluminum sheet for body panels, meeting critical sustainability targets for global automakers. Constellium occupies a position as a provider of complex extrusions for crash management systems and battery enclosures, leveraging its expertise in demanding structural applications. Norsk Hydro ASA, a Norwegian-based entity, anchors the low-carbon primary aluminum segment, appealing to brands focused on lifecycle emissions and environmental stewardship across their supply chains.
| Leading Market Players |
|---|
| Alcoa Corporation |
| Novelis |
| Norsk Hydro ASA |
| Constellium |
| Rio Tinto Group |
| ArcelorMittal |
| Arconic |
| UACJ Corporation |
| Kaiser Aluminum |
| Others |
Cost & Logistics Intelligence
The LME aluminum price, a global commodity benchmark, cascades through the automotive aluminum supply chain, influencing component pricing tiers for OEMs and sub-assembly suppliers. This volatility in raw material costs creates procurement challenges across the value chain, demanding strategic hedging and long-term contracts.
Pricing Analysis
Cost-down pressure on automotive aluminum suppliers accelerates because automakers demand lower per-unit costs for high-volume applications and mass-market vehicles. The dominant pricing model is contract-based long-term offtake agreements, often with volume commitments. Price differentiation stems from alloy grade and specific performance certifications required for safety-critical components. Automakers are highly price-sensitive for standard body panels, while premium and performance vehicle segments show less sensitivity for advanced alloys and specialized extrusions.
Supply Chain Analysis
Domestic-content mandates, such as those encouraged by the USMCA agreement, are reshaping sourcing strategies for automotive aluminum, favoring localized production. Geographic supply concentration is notable in China for extrusions, Germany for advanced alloys, and the United States for sheet products. The market depends on primary aluminum, bauxite, and reliable electricity supply for production. A structural supply chain risk is commodity price volatility for primary aluminum. Distribution runs through direct supply relationships between aluminum producers or Tier-1 fabricators and automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive aluminum market is consolidating as stringent regulatory compliance and high capital investment intensity force smaller, less agile players to exit.
For Market Incumbents: Deepen strategic partnerships with major OEMs for closed-loop recycling systems, securing long-term supply contracts and meeting lifecycle emissions targets. Invest in advanced alloy development, particularly 6000 and 7000 series, to counter substitution threats from carbon fiber composites in high-performance and luxury segments. Expand manufacturing capacity in key EV production hubs like the US and China to capitalize on regional demand. Focus R&D on enhancing formability and crash-worthiness for new body-in-white structures.
For New Entrants and Emerging Players: Online B2B marketplaces offer a channel for new entrants to target niche applications like custom prototyping for EV startups, leveraging agile manufacturing processes. Focus on specialized extrusions for complex battery enclosures in emerging EV markets within India, where local manufacturing incentives are strong. A penetrable segment is providing modular sub-assemblies for smaller, regional vehicle assemblers. Develop a go-to-market angle emphasizing rapid prototyping and flexible production volumes for specialized components.
For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated material suppliers in the European market, particularly those with advanced recycling infrastructure and low-carbon primary metal production. Long-term viability hinges on companies capable of supplying advanced sub-assemblies for the electric vehicle transition. Acquisition targets should include specialized fabricators with patented joining technologies or unique giga-casting capabilities. A signal to watch is the successful commercialization of giga-casting for new vehicle platforms, indicating strong demand for specific aluminum forms.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand closed-loop recycling capacity | This initiative secures raw material supply for automakers and reduces lifecycle emissions. |
| Invest in advanced 6000/7000 series alloy R&D | This enhances aluminum's competitive edge against composites in performance applications. |
| Develop modular sub-assembly capabilities | This simplifies OEM assembly lines and captures higher value for suppliers. |
| Target emerging EV manufacturing hubs | This aligns with geographic demand shifts and national industrial policies. |
| Acquire specialized giga-casting expertise | This enables production of large, single-piece vehicle structures for EV platforms. |
Research Approach
Independent corroboration across industry reports, company financial statements, and regulatory filings underwrites the qualitative findings and quantitative projections. The study combined primary interviews with OEM procurement leads, Tier-1 fabrication specialists, and aluminum alloy R&D directors, alongside secondary validation from US EPA data, EU Green Deal documents, and China's MIIT reports. This approach ensured robust bottom-up and top-down triangulation of market insights.
Comparable historical reference periods anchored the forecast window, allowing for robust trend analysis and projection. Segmentation dimensions modeled included product type, application, end user, and form, with an industry-specific focus on vehicle architecture types. Compound annual growth rates were derived from a multi-factor regression model, incorporating electric vehicle production forecasts and raw material cost projections.
The model holds under current regulatory frameworks and anticipated technological adoption rates; deviation in global energy prices or significant shifts in material science would shift market dynamics. Forecasts reflect assumptions regarding economic stability and supply chain resilience. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Cast Iron Cylinder Head Market
Automotive Components
Automotive Solenoid Market
Automotive Components
Drive System Market
Automotive Components
Automotive Fender Market
Automotive Components
Automotive Smart Actuator Market
Automotive Components
Automotive Emblem Market
Automotive Components
Automotive Heater Core Market
Automotive Components
Automotive Lightweighting Market
Automotive Components
Europe Automotive Bearing Market
Automotive Components
Global Automotive Components Forging Market
Automotive Components
Active Suspension Damper Actuator Systems Market
Automotive Components
Automotive Dynamic Spotlight Market
Automotive Components
Automotive Ignition Box Market
Automotive Components
Global Automotive Radiator Market
Automotive Components
Japan Automotive Composites Market
Automotive Components
US Automotive Glass Fiber Composites Market