
 Racing Vehicles Market | 2026-2036
Racing Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Racing Vehicles Market Analysis
Direct-to-team technical partnerships is rewriting how racing vehicle suppliers secure long-term contracts. Ferrari leverages its Scuderia racing division to sustain technology transfer into road-car programs. Mercedes-Benz anchors its competitive position through in-house powertrain integration across Formula and endurance platforms. Red Bull Racing differentiates via its Red Bull Powertrains unit, controlling engine development independent of external manufacturers.
Racing vehicles are purpose-built machines engineered to FIA homologation standards with carbon-fiber monocoque chassis, aerodynamic packages generating targeted downforce coefficients, and powertrains optimized for sustained high-RPM operation across sprint or endurance formats. Open-wheel configurations dominate Formula Racing categories where marginal gains in drag reduction and weight distribution determine championship outcomes. Hybrid engine types are gaining structural share in endurance racing as organizers tighten fuel-flow regulations and mandate kinetic energy recovery systems. The professional market segment captures concentrated margin pools through multi-year constructor agreements and exclusive tire or fuel supply partnerships.
The FIA cost-cap framework and EPA emissions waivers for competition vehicles jointly shape product development priorities and market access conditions for suppliers. EU F-Gas Regulation and REACH chemical compliance add material selection constraints on refrigerants, composites, and coatings used in European series preparation. Stakeholders must monitor how powertrain electrification mandates from the FIA and national motorsport federations redefine capital allocation between internal combustion R&D and battery-thermal management competencies.
Market Dynamics
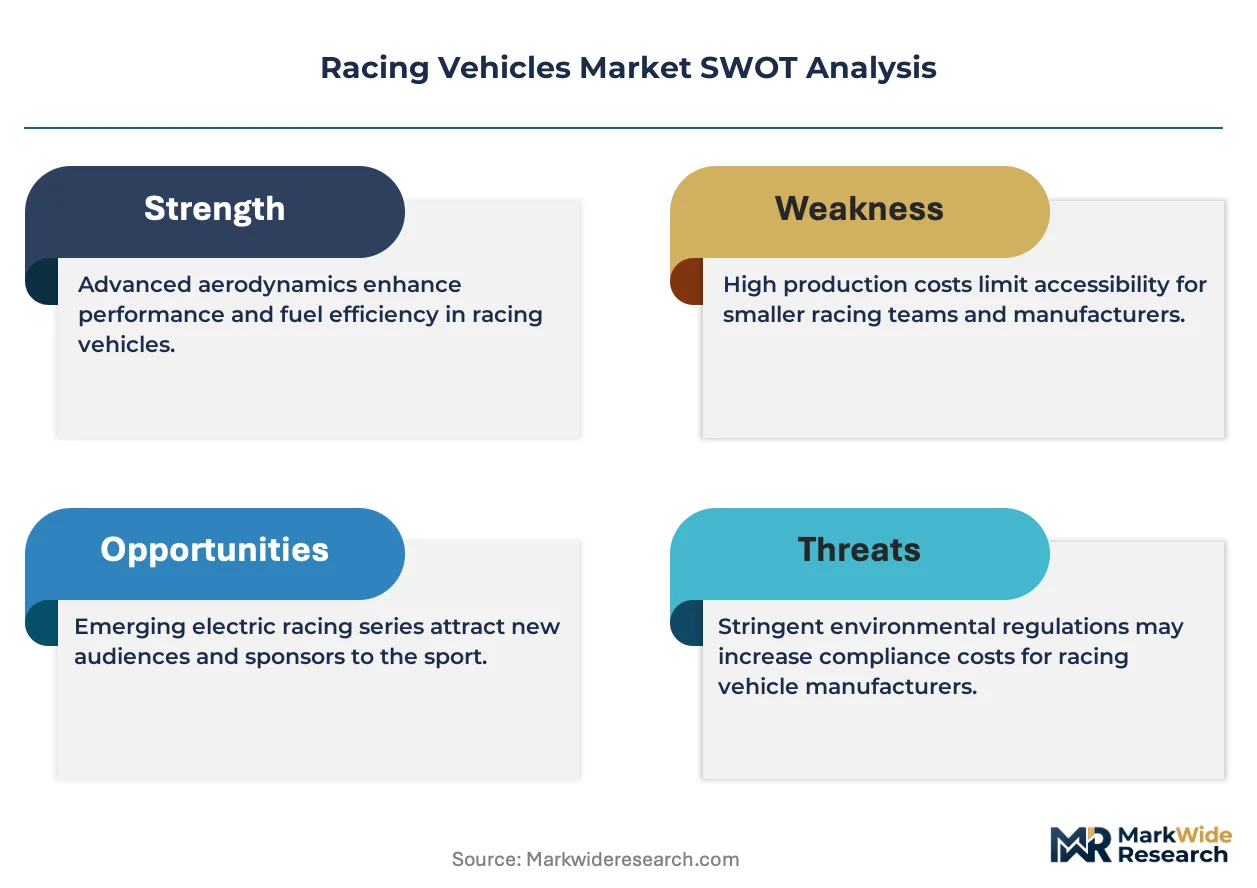
The FIA cost-cap framework and powertrain electrification mandates are compressing development budgets while forcing suppliers to reallocate capital from internal combustion R&D toward battery-thermal management and hybrid system integration.
Growth Catalysts
- Amateur Feeder Program Expansion:Professional motorsport series are building structured talent pipelines that sustain long-term chassis and powertrain demand from entry-level categories through premier divisions.
- F-Gas Regulation Compliance:The EU's tightening refrigerant standards are accelerating material innovation in composite manufacturing and thermal management systems for European series preparation.
- Carbon-Fiber Monocoque Standardization:FIA homologation requirements for chassis safety and weight distribution are cementing advanced composite fabrication as a core supplier competency across Formula and endurance platforms.
Market Restraints
- Development Budget Compression:The FIA cost-cap regulations limit annual expenditure on vehicle design and testing, constraining how much teams can invest in iterative aerodynamic and powertrain improvements.
- Supply Concentration Risk:Carbon-fiber pre-preg and specialized composite resins concentrate among a limited set of Japanese and European suppliers, exposing constructors to input bottlenecks.
- Powertrain Standardization Mandates:Spec-engine rules in multiple series eliminate differentiation opportunities for independent engine developers and reduce addressable market for bespoke powertrain suppliers.
Strategic Opportunities
- Battery-Thermal Convergence:Hybrid endurance formats create white space for suppliers mastering the intersection of kinetic energy recovery systems and sustained high-RPM thermal management.
- Direct-to-Team Technical Partnerships:Long-term constructor agreements and exclusive supply contracts offer stable revenue streams outside volatile spot-market component sales.
- EPA Emissions Waiver Pathways:Competition vehicle exemptions from federal emissions rules preserve internal combustion development channels for US-based series and amateur racing categories.
Industry Challenges
- Multi-Domain Engineering Talent Scarcity:The convergence of mechanical, electrical, and software systems in hybrid powertrains outpaces the supply of engineers competent across all three domains simultaneously.
- Homologation Timeline Compression:FIA certification cycles for new chassis designs and safety systems create cash-flow gaps between development expenditure and competitive deployment.
- IP Licensing Complexity:Proprietary kinetic energy recovery and battery management technologies generate disputes over technology transfer between series-sanctioned suppliers and independent constructors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Racing Vehicles Market |
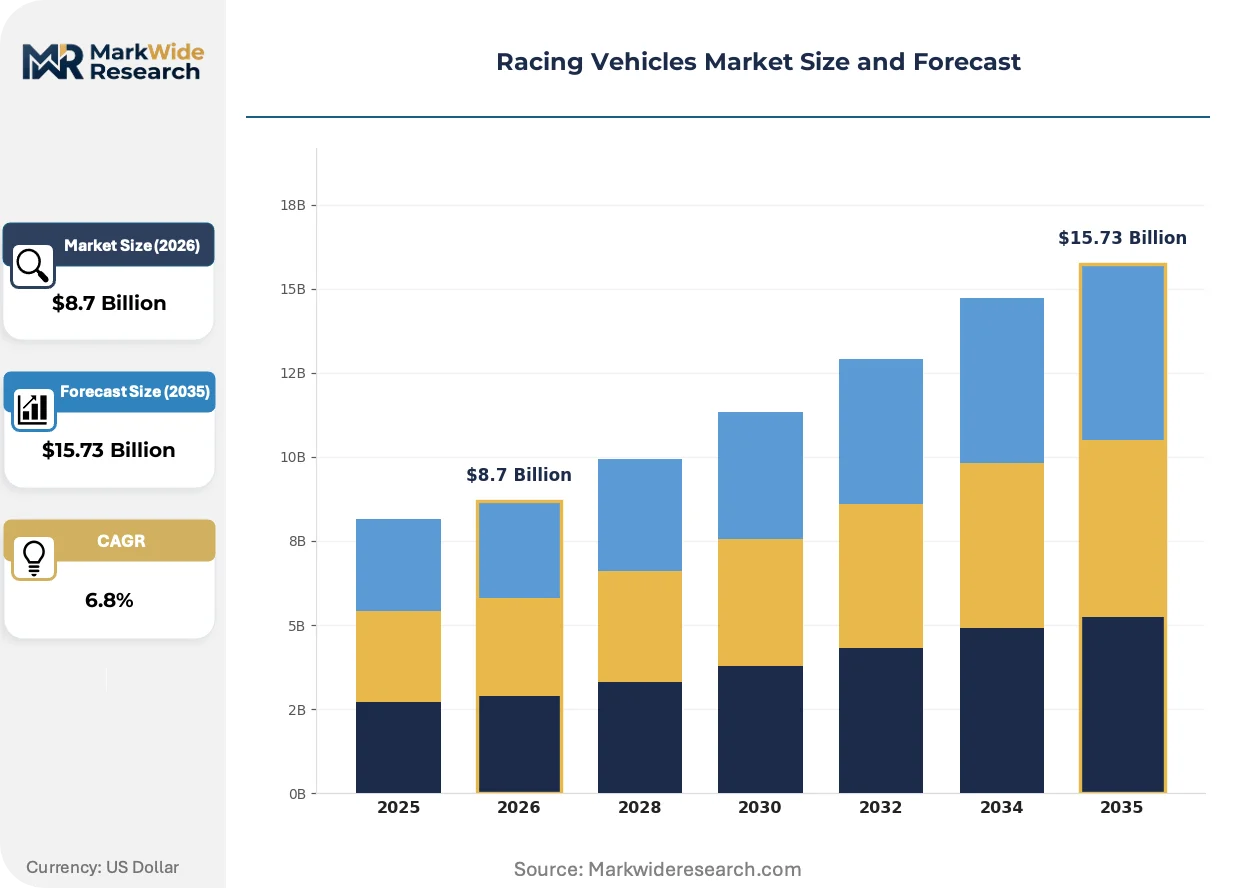
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Open-Wheel, Prototype, Touring Cars, Sports Cars Engine Type: Internal Combustion, Electric, Hybrid, Diesel Race Category: Formula Racing, Endurance Racing, Rally Racing, Drag Racing Market Segment: Amateur, Professional, Karting, Franchise |
| Companies Covered | Ferrari, Mercedes-Benz, McLaren, Red Bull Racing, Porsche, Toyota, Honda, Bmw, Audi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Racing Vehicles Market Emerging Trajectories
Powertrain architecture, aerodynamic simulation methods, and procurement relationships are undergoing simultaneous transformation as electrification mandates and cost-control pressures rewrite how racing vehicles are engineered and sourced.
Computational fluid dynamics coupled with wind tunnel validation is migrating from a late-stage verification tool to an integrated design methodology. Formula constructors now deploy real-time aerodynamic simulation during track sessions, compressing the iteration cycle between computational modeling and physical testing. This capability is migrating from elite factory teams toward mid-tier constructors through cloud-based simulation platforms.
REACH chemical compliance and the EU F-Gas Regulation are reshaping material specifications for composites, coatings, and refrigerants used in European series preparation. Suppliers must reformulate resin systems and thermal fluids to maintain homologation eligibility, adding certification overhead to product development. Endurance racing categories face the steepest adaptation burden due to extended operational duty cycles and thermal load profiles.
Team procurement of powertrain components is consolidating around multi-year technical partnerships rather than annual supplier rotations. Constructors seek captive engineering relationships that embed supplier personnel within team operations, displacing transactional component purchasing. Germany's Nürburgring corridor and the UK's Motorsport Valley cluster exhibit the densest concentration of these embedded partnership models.
Racing Vehicles Market Segmentation
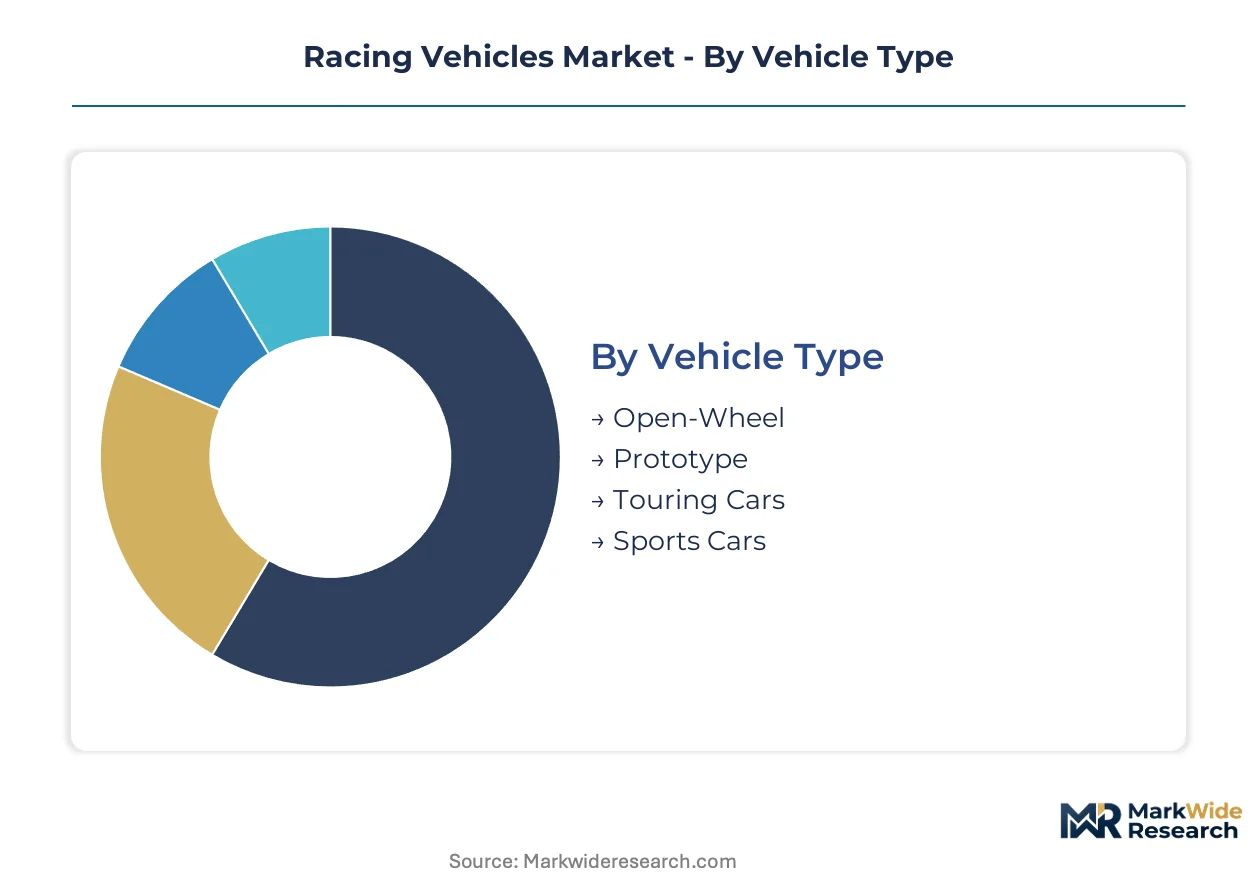
Segmentation in racing vehicles reveals distinct capital intensity profiles and homologation cycles. Open-wheel chassis programs refresh every regulatory cycle while amateur categories sustain longer production runs. Understanding these turnover patterns determines supplier resource allocation and partnership tenure.
Vehicle Type:
Open-wheel platforms command the shortest development cycles as FIA technical regulations reset chassis specifications biennially, whereas sports car and touring car architectures persist across multiple seasons with evolutionary updates.
- Open-Wheel:Single-seat carbon-fiber monocoque chassis engineered to FIA Formula homologation standards with optimized drag coefficients and weight distribution. Demand concentrates in the UK's Motorsport Valley cluster where constructor teams source integrated aerodynamic packages from embedded technical partners.
- Prototype:Closed-cockpit endurance platforms balancing sustained high-RPM thermal management with hybrid energy recovery integration. Le Mans Hypercar and LMDh regulations are driving convergence between factory programs and customer chassis supply in Germany's Nürburgring corridor.
- Touring Cars:Production-derived silhouettes with tube-frame reinforcement and standardized aerodynamic kits.
- Sports Cars:GT-category machinery homologated from road-going platforms with extensive composite bodywork modification.
Open-Wheel anchors the volume base while Prototype gains share at the steepest rate as endurance hybridization mandates expand addressable scope for battery-thermal system suppliers.
Engine Type:
Powertrain segmentation stratifies by thermal management complexity and regulatory waiver pathways, with electrified architectures commanding premium engineering margins against internal combustion's established supply base.
- Internal Combustion:High-RPM naturally aspirated and turbocharged engines optimized for sprint or endurance duty cycles. EPA emissions waivers for competition vehicles preserve development channels for US-based series and amateur racing categories.
- Hybrid:Kinetic energy recovery systems paired with downsized combustion cores for fuel-flow regulated endurance formats. FIA mandates in WEC and IMSA are accelerating supplier investment into battery-thermal convergence competencies.
- Electric:Battery-electric powertrains with thermal management prioritizing sustained output over range optimization.
- Diesel:Compression-ignition endurance powertrains retaining niche application in 24-hour racing categories.
Internal Combustion retains the broadest installed base while Hybrid is expanding most quickly as organizer mandates displace pure combustion entries from premier championships.
Race Category:
Category segmentation reflects divergent procurement models, with formula series emphasizing exclusive constructor agreements and rally programs fragmenting across privateer and factory-supported entries.
- Formula Racing:Open-wheel championships governed by FIA technical regulations with standardized chassis and powertrain supply rules. Cost-cap frameworks are compressing annual expenditure limits and reshaping how teams contract simulation and wind tunnel services.
- Endurance Racing:Multi-hour events mandating hybrid integration and fuel-flow restrictions across prototype and GT divisions. EU F-Gas Regulation compliance adds material selection constraints on refrigerants and composites used in European series preparation.
- Rally Racing:Gravel and tarmac surface competition with production-homologated or purpose-built machinery.
- Drag Racing:Straight-line acceleration formats with minimal regulatory constraint on powertrain architecture.
Endurance Racing anchors professional supplier revenue while Formula Racing shows the steepest budget compression as cost-cap enforcement tightens.
Market Segment:
Customer tier segmentation distinguishes between factory-backed development programs with captive engineering resources and amateur categories served through distributor networks and spec-component supply.
- Professional:Factory and satellite teams competing in FIA-sanctioned world championships with multi-year constructor agreements. Concentrated margin pools flow through exclusive tire, fuel, and telemetry supply partnerships.
- Amateur:Club-level and regional series participants sourcing chassis and powertrain components through feeder program structures. Professional motorsport series are expanding these pipelines to secure long-term talent development.
- Karting:Entry-level single-cylinder categories serving as talent identification and development pathways.
- Franchise:Spec-series operations with standardized machinery and controlled component supply.
Amateur anchors unit volume through feeder program expansion while Professional captures the highest per-unit engineering value through embedded technical partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FIA's regulatory authority anchors Europe as the dominant geography, with Germany's Nürburgring corridor and the UK's Motorsport Valley engineering cluster anchoring professional supply chains. National motorsport federations across multiple jurisdictions are tightening powertrain electrification mandates that reshape capital allocation for constructors.
Germany
Factory endurance programs and customer chassis supply drive demand concentration along the Nürburgring corridor. The KBA enforces EU F-Gas Regulation compliance for refrigerants and thermal fluids used in series preparation. Stuttgart and Munich host embedded technical partnerships where supplier personnel integrate directly with constructor operations.
United Kingdom
Formula constructor teams and aerodynamic package suppliers cluster in Motorsport Valley between Oxfordshire and Northamptonshire. REACH chemical compliance mandates reformulate resin systems for composite fabrication. Silverstone and Milton Keynes anchor the densest concentration of direct-to-team technical partnerships in open-wheel categories.
Italy
Historic motorsport heritage sustains demand for high-RPM powertrain development and carbon-fiber monocoque production. The national motorsport federation aligns with FIA cost-cap frameworks that compress annual expenditure limits. Maranello and Modena host integrated racing divisions that sustain technology transfer into road-car programs.
Japan
Carbon-fiber pre-preg and specialized composite resin suppliers concentrate manufacturing capacity for export to European and North American constructors. METI oversees industrial standards that align with FIA homologation requirements for chassis safety. Tokyo and Nagoya anchor supply relationships that expose constructors to input bottlenecks during demand surges.
United States
EPA emissions waivers for competition vehicles preserve internal combustion development channels for amateur racing categories and domestic series. The exemption framework sustains demand for high-RPM naturally aspirated and turbocharged engines. Indianapolis and Charlotte host feeder program structures that secure long-term talent pipelines from entry-level categories.
Racing Vehicles Market Vendor Landscape
Factory-integrated constructors and independent powertrain developers split the market between captive technology transfer and external supply relationships. The vendor base concentrates around multi-year technical partnerships rather than transactional component purchasing. Three archetypes dominate: racing divisions of automotive OEMs, standalone constructor teams with embedded supplier networks, and specialized powertrain units controlling independent engine development. Competitive moves center on backward integration into composite fabrication and strategic partnerships for battery-thermal system convergence.
Within the factory-integrated tier, Ferrari and Mercedes-Benz exemplify archetypes that sustain technology transfer between racing programs and road-car divisions. Red Bull Racing occupies a distinct position through its powertrains unit, representing the standalone constructor model that controls engine development independent of external manufacturers. These three entities anchor the competitive structure that other participants must navigate through technical partnership proposals or niche specialization.
| Leading Market Players |
|---|
| Ferrari |
| Mercedes-Benz |
| McLaren |
| Red Bull Racing |
| Porsche |
| Toyota |
| Honda |
| Bmw |
| Audi |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Japanese carbon-fiber pre-preg suppliers determines both the widening spread between configured-to-order chassis pricing and standard component tiers and the geographic clustering of constructor operations around embedded technical partnerships in Germany's Nürburgring corridor and the UK's Motorsport Valley.
Pricing Analysis
The customization-premium spread separates FIA-homologated carbon-fiber monocoque chassis with tailored aerodynamic packages from spec-component supply to amateur feeder programs. Price differentiation hinges on certification grade for FIA safety standards and the depth of embedded engineering support, with factory teams showing minimal sensitivity while club-level entrants face acute pressure from compressed development budgets under cost-cap enforcement.
Supply Chain Analysis
Tariff exposure between Japan and European constructor clusters dominates supply chain risk planning for composite fabricators. Carbon-fiber pre-preg and specialized epoxy resins draw from Japanese and German chemical suppliers, with distribution running through just-in-time logistics to constructor facilities in Stuttgart, Milton Keynes, and Maranello, exposing teams to input bottlenecks during demand surges for new regulatory-cycle chassis.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineers competent across mechanical, electrical, and software domains simultaneously are the scarcest asset in racing vehicle development, constraining how quickly suppliers can execute battery-thermal convergence strategies.
For Market Incumbents: Entrench multi-year technical partnerships by embedding supplier personnel within constructor operations in Motorsport Valley and the Nürburgring corridor, while backward integration into composite fabrication mitigates carbon-fiber pre-preg supply concentration risk from Japanese sources. For New Entrants and Emerging Players: Establish a beachhead in amateur feeder program chassis supply where professional series expansion creates sustained demand, leveraging cloud-based aerodynamic simulation platforms to bypass wind tunnel capital requirements and serve mid-tier constructors with iterative design services. For Investors and Strategic Acquirers: FIA powertrain electrification mandates reshape the acquisition landscape toward suppliers mastering battery-thermal management competencies. Long-term viability favors targets with captive hybrid system integration capabilities, with the signal to watch being homologation timeline compression for new endurance chassis designs.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Thermal System Convergence | Captures margin pools in WEC and IMSA hybrid mandates where FIA regulations enforce kinetic energy recovery integration. |
| Embedded Technical Partnership | Locks multi-year revenue streams with Ferrari, Mercedes-Benz, and Red Bull Racing through captive engineering relationships. |
| Carbon-Fiber Pre-Preg Backward Integration | Reduces exposure to Japanese supply concentration risk that constrains constructor production timelines. |
| Cloud-Based Aerodynamic Simulation | Democratizes CFD capability from elite factory teams to mid-tier constructors via subscription platforms. |
| Amateur Feeder Program Expansion | Secures long-term talent pipelines that sustain chassis demand from karting through premier formula divisions. |
Methodological Framework
Initial hypotheses were tested against primary input from chassis design engineers, powertrain integration specialists, FIA technical delegates, and constructor procurement directors and refined through secondary validation against FIA homologation databases, EU REACH chemical compliance filings, EPA emissions waiver records, and carbon-fiber trade flow data, with bottom-up chassis production estimates triangulated against top-down series entry counts.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, modeling segmentation dimensions spanning vehicle type, engine architecture, race category, and market segment tier, with CAGRs derived from regression analysis of historical constructor expenditure patterns and forward-looking regulatory mandate timelines for powertrain electrification and cost-cap enforcement.
Stress conditions across carbon-fiber input pricing, FIA regulatory cycle timing, and hybrid system adoption curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from supply concentration events or accelerated electrification mandates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Wiping Systems Market
Automotive Parts
Japan Ceramic Ball Bearings Market
Automotive Parts
High Speed Rolling Bearings Market
Automotive Parts
Automotive Brake Caliper Market
Automotive Parts
Mexico Automotive Parts Aluminum Die Casting Market
Automotive Parts
Automotive Forging Market
Automotive Parts
Global Intelligent Steering System Market
Automotive Parts
Engine Bearings Market
Automotive Parts
UK Automotive Parts Zinc Die Casting Market
Automotive Parts
Japan Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Fuel Rail Market
Automotive Parts
UK Automotive Parts Magnesium Die Casting Market
Automotive Parts
Needle Roller Bearings Market
Automotive Parts
Automotive Hinges Market
Automotive Parts
Uae Passenger Vehicles Lubricants Market
Automotive Parts
AC Electromagnetic Brakes Market