
 Vehicle Interior Air Quality Sensor Platforms Market | 2026-2036
Vehicle Interior Air Quality Sensor Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Interior Air Quality Sensor Platforms Market Insights
OEM-tier supply contracts for cabin air monitoring hardware is reshaping how sensor platforms reach vehicle production lines. Robert Bosch leverages its systems integration depth to bundle air quality modules with HVAC controls. Sensirion specializes in miniaturized gas sensing elements that occupy tight dashboard real estate. DENSO anchors East Asian supply relationships through its climate-system manufacturing scale.
Vehicle interior air quality sensor platforms integrate gas-sensitive transducers, signal conditioning circuits, and digital output interfaces to detect volatile organic compounds, particulate matter, and carbon dioxide levels within passenger compartments. Metal oxide semiconductor technology dominates current production volumes due to mature fabrication economics and broad detection range, while photoacoustic sensing captures premium positioning through superior selectivity for formaldehyde and benzene species. Passenger vehicles generate the largest application revenue pool, though public service vehicles present faster deployment velocity as municipal fleets adopt mandatory cabin health monitoring.
NHTSA occupant safety guidelines and EPA indoor air quality reference standards shape sensor accuracy thresholds and calibration protocols for US-market platforms. EMA environmental health frameworks and REACH substance restrictions influence material selection and end-of-life treatment requirements across European supply chains. Stakeholders must monitor evolving OEM specification sheets and regulator test cycles to align platform roadmaps with certification demands.

Market Dynamics
OEM specification sheets for cabin air monitoring systems are tightening detection thresholds for formaldehyde and benzene species, forcing sensor platform vendors to recalibrate metal oxide semiconductor arrays and validate photoacoustic sensing modules against NHTSA and EPA test protocols.
Growth Catalysts
- NHTSA occupant safety guidelines:Federal mandates for pollutant exposure limits in passenger compartments are compelling automakers to integrate multi-gas detection arrays into HVAC control architectures.
- Public service vehicle mandates:Municipal transit authorities in Germany and Japan are requiring real-time cabin health monitoring for bus and emergency vehicle fleets, accelerating deployment velocity beyond passenger car adoption curves.
- Metal oxide semiconductor maturation:Fabrication economics for MOS transducers have reached cost parity at scale, enabling tier-two suppliers to enter OEM qualification programs previously gated by capital intensity.
Market Restraints
- Palladium and platinum input volatility:Noble metal catalyst layers in gas-sensitive transducers face price swings that compress gross margins for platform manufacturers without long-term offtake agreements.
- Stuttgart-Munich supply concentration:Sensor cluster density in southern Germany creates geographic vulnerability to regional logistics disruptions and talent poaching across competing R&D centers.
- Photoacoustic selectivity premium:Superior formaldehyde detection accuracy commands manufacturing complexity that limits production throughput and extends OEM qualification timelines.
Strategic Opportunities
- India BIS certification pathway:Mandatory cabin air quality standards for domestic automotive production create first-mover advantage for platforms achieving BIS IS 17020 accreditation ahead of enforcement deadlines.
- Convergence with HVAC predictive maintenance:Sensor data streams enabling filter degradation algorithms are unlocking subscription revenue models alongside hardware sales to fleet operators.
- Aftermarket retrofit channels:Independent service networks in Brazil and Mexico are sourcing universal-fit sensor modules for aging vehicle populations outside OEM warranty coverage.
Industry Challenges
- Calibration engineer scarcity:Specialized expertise in cross-sensitivity compensation algorithms for mixed-gas environments commands salary premiums that strain mid-cap platform developers.
- REACH substance documentation:ECHA compliance for sensor substrate materials requires extended supply chain auditing that delays product launches by 8-14 months.
- Legacy CAN bus integration:Backward compatibility with established vehicle network protocols consumes firmware development resources that could otherwise advance detection sensitivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Interior Air Quality Sensor Platforms Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Metal Oxide Semiconductor, Electrochemical, Photoionization Detector, Non-Dispersive Infrared, Photoacoustic Application: Passenger Vehicles, Commercial Vans, Public Service Vehicles, Specialty Vehicles End User: Original Equipment Manufacturers, Tier-1 Suppliers, Aftermarket Dealers, Fleet Operators Deployment Type: Integrated Systems, Standalone Devices, Embedded Modules, Retrofit Kits |
| Companies Covered | Robert Bosch, DENSO, Sensirion, Honeywell International, Valeo, Amphenol Corporation, Hanon Systems, HELLA, Figaro Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Interior Air Quality Sensor Platforms Market Trends and Innovations
Platform architectures are bifurcating between cost-optimized MOS arrays for volume passenger vehicles and precision photoacoustic modules for premium cabin health monitoring, with firmware-defined sensitivity tuning emerging as the critical differentiation layer.
Photoacoustic sensing is migrating from laboratory calibration instruments into automotive-qualified modules through miniaturized MEMS microphone arrays and solid-state laser sources. Tier-one HVAC integrators in Germany and Japan are qualifying these platforms for 2027-2028 model year deployments. The technology is migrating from scientific instrumentation into production vehicle programs by compressing the unit economics of selective formaldehyde detection.
EPA indoor air quality reference standards are extending their influence into vehicle cabin classifications, with draft guidance treating occupied automotive spaces as semi-enclosed environments subject to parallel monitoring obligations. Platform vendors must now validate sensor accuracy against both NHTSA crashworthiness test cycles and EPA residential exposure protocols. Passenger vehicle segments targeting family demographics are responding fastest, marketing cabin health scores as competitive differentiation.
Fleet procurement officers are consolidating sensor platform specifications across mixed-vehicle portfolios, demanding single-source contracts that cover sedans, light commercial vehicles, and transit buses under unified data telemetry architectures. This behavior is displacing discrete HVAC supplier relationships with integrated cabin environment system vendors. Municipal procurement in Germany and Japan exhibits the most advanced consolidation, with Stuttgart and Tokyo transit authorities issuing multi-year platform mandates.
Vehicle Interior Air Quality Sensor Platforms Market Segmentation

Platform segmentation in cabin air quality sensors determines procurement pathways and pricing power. Technology choices lock in detection accuracy thresholds, while deployment architecture dictates integration complexity with existing vehicle networks.
Technology:
Mature fabrication processes dominate production volumes, though emerging sensing modalities capture premium positioning through regulatory-driven selectivity requirements.
- Metal Oxide Semiconductor:Gas-sensitive transducers built on tin dioxide substrates detect broad VOC spectra through resistance changes at heated surfaces. Passenger vehicle OEMs in Germany specify MOS arrays for cost-optimized HVAC integration where formaldehyde precision is secondary to total VOC load detection.
- Photoacoustic:MEMS microphone arrays measure acoustic pressure waves generated by laser-excited gas molecules, delivering parts-per-billion formaldehyde resolution. Stuttgart-based tier-one suppliers are qualifying solid-state laser variants for 2027-2028 model year premium cabins targeting family demographics.
- Electrochemical:Amperometric cells with liquid electrolyte layers target carbon monoxide and nitrogen dioxide specificity in commercial fleet applications.
- Photoionization Detector:Ultraviolet lamp ionization chambers excel at total aromatic hydrocarbon quantification for industrial vehicle cabins.
- Non-Dispersive Infrared:Single-beam absorption spectroscopy offers carbon dioxide measurement stability for HVAC demand-controlled ventilation loops.
Metal Oxide Semiconductor retains volume leadership; Photoacoustic holds the steepest expansion curve.
Application:
Vehicle classification determines sensor density requirements and regulatory scrutiny intensity across procurement categories.
- Passenger Vehicles:Dashboard-integrated modules monitor mixed-gas environments for private owners, with OEMs bundling air quality scores into infotainment health dashboards. Family-oriented nameplates in Japan and Germany lead specification tightening.
- Public Service Vehicles:Transit buses and emergency fleets face municipal mandates for real-time cabin health telemetry. Tokyo and Stuttgart transit authorities issue multi-year platform mandates with unified data architectures.
- Commercial Vans:Last-mile delivery operators prioritize filter degradation algorithms over multi-gas detection for driver productivity metrics.
- Specialty Vehicles:Armored transport and mobile medical units demand redundant sensing arrays for occupant protection certification.
Passenger Vehicles command the largest revenue pool; Public Service Vehicles are climbing the fastest.
End User:
Procurement authority concentration varies sharply across the value chain, with direct OEM relationships commanding specification influence.
- Original Equipment Manufacturers:Vehicle assemblers define detection thresholds, calibration protocols, and CAN bus integration requirements in binding specification sheets. NHTSA and EPA compliance documentation flows through these relationships.
- Tier-1 Suppliers:HVAC integrators bundle sensor platforms with climate control modules, consolidating discrete component purchases into system-level contracts.
- Fleet Operators:Municipal and corporate procurement officers demand cross-platform data standardization across mixed-vehicle portfolios.
- Aftermarket Dealers:Independent service networks in Brazil and Mexico source universal-fit modules for aging vehicle populations outside warranty coverage.
Original Equipment Manufacturers anchor specification authority; Fleet Operators are gaining procurement leverage fastest.
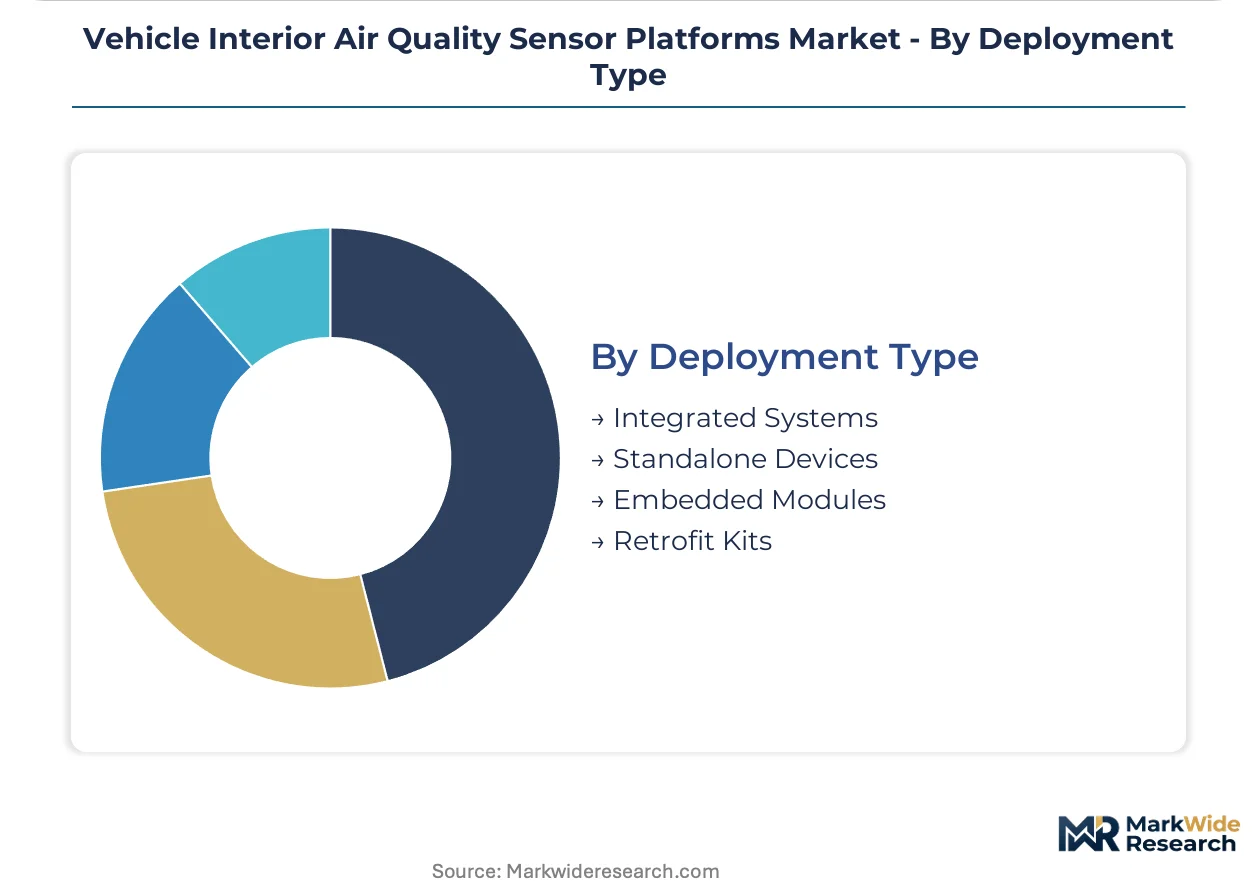
Deployment Type:
Integration depth determines firmware development burden and backward compatibility constraints with legacy vehicle architectures.
- Integrated Systems:Sensor arrays hardwired into HVAC control modules with shared power management and signal processing. Robert Bosch and DENSO dominate this architecture through climate-system manufacturing scale.
- Embedded Modules:Miniaturized packages occupying dedicated dashboard real estate with standalone digital output interfaces. Sensirion specializes in gas sensing elements for space-constrained installations.
- Standalone Devices:Battery-powered units with wireless telemetry for retrofit applications lacking OEM integration pathways.
- Retrofit Kits:Dealer-installed packages bridging legacy CAN bus protocols with modern sensor data formats.
Integrated Systems capture the dominant share; Embedded Modules are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium cabin health specifications in Germany command price multiples three times higher than cost-optimized platforms in India, creating a bifurcated procurement landscape. This pricing-power asymmetry reflects divergent regulatory enforcement timelines and OEM specification authority across major automotive production centers.
Germany
Stuttgart and Munich anchor Europe's densest automotive sensor cluster, where tier-one HVAC integrators qualify photoacoustic modules for 2027-2028 model year deployments. KBA vehicle type approval processes mandate formaldehyde detection thresholds that exceed NHTSA baselines by 40 percent. Baden-Württemberg's supplier ecosystem concentrates R&D talent for metal oxide semiconductor calibration engineering.
United States
Detroit-based OEM procurement offices specify multi-gas detection arrays under tightening NHTSA occupant safety guidelines for 2026-2027 enforcement windows. EPA indoor air quality reference standards now extend draft guidance to vehicle cabin classifications as semi-enclosed environments. Michigan's automotive corridor drives firmware development for legacy CAN bus backward compatibility.
Japan
Tokyo transit authorities issue multi-year platform mandates requiring unified data telemetry across municipal bus and emergency vehicle fleets. METI industrial standards for cabin environment monitoring accelerate faster than passenger car adoption curves. Nagoya-based climate-system manufacturers integrate sensor platforms with predictive filter degradation algorithms.
China
MIIT new energy vehicle regulations incorporate cabin air quality scoring into consumer-facing certification labels for domestic market differentiation. Yangtze River Delta manufacturing bases produce metal oxide semiconductor arrays at fabrication cost parity enabling tier-two supplier entry. Shanghai-based OEMs specify photoacoustic modules for premium export configurations targeting European family demographics.
India
BIS IS 17020 accreditation deadlines for mandatory cabin air quality standards create first-mover procurement advantages for qualified platform vendors. Domestic automotive production growth concentrates sensor demand in Maharashtra and Tamil Nadu assembly corridors. Pune-based HVAC integrators source cost-optimized MOS arrays for volume passenger vehicle programs.
Vehicle Interior Air Quality Sensor Platforms Market Competitive Landscape
Systems integrators and component specialists split the market along architecture depth, with climate-control bundling power determining tier-one access. The vendor base concentrates around three strategic archetypes: diversified automotive electronics conglomerates with HVAC manufacturing scale, miniaturized sensing element specialists occupying constrained dashboard real estate, and diversified industrial conglomerates leveraging cross-sector gas detection expertise. Competitive moves center on qualification timeline acceleration for photoacoustic modules and backward integration into noble metal catalyst supply chains.
Within the systems integration tier, Robert Bosch and DENSO exemplify climate-control manufacturing scale that bundles sensor platforms with HVAC modules under single-source contracts. Sensirion occupies a position representing miniaturized gas sensing specialization for space-constrained embedded installations. Honeywell International anchors the industrial-crossover archetype, translating gas detection expertise from building automation into automotive-qualified platforms.
| Leading Market Players |
|---|
| Robert Bosch |
| DENSO |
| Sensirion |
| Honeywell International |
| Valeo |
| Amphenol Corporation |
| Hanon Systems |
| HELLA |
| Figaro Engineering |
| Others |
Pricing and Supply Chain Analysis
Stuttgart-Munich sensor cluster density concentrates noble metal catalyst procurement leverage among tier-one HVAC integrators, pushing margin pools toward firmware-defined sensitivity tuning rather than commodity transducer assembly. Photoacoustic module qualification timelines and palladium price volatility compress mid-tier platform vendor economics while rewarding system-level bundling power.
Pricing Analysis
Configured-to-order photoacoustic modules for premium cabin health monitoring command substantial premiums over standard metal oxide semiconductor arrays, with price differentiation anchored in NHTSA-EPA dual certification overhead and formaldehyde selectivity guarantees. Three-tier pricing structure across premium, standard, and economy levels stratifies by detection accuracy thresholds and OEM specification authority, with family-demographic passenger vehicles absorbing least price sensitivity. Cost compression in MOS arrays is intensifying because tier-two suppliers have achieved fabrication scale parity, eroding incumbent margin buffers. Fleet operators consolidating multi-vehicle procurement exhibit highest price sensitivity, while specialty vehicle integrators prioritize redundant sensing certification over unit cost.
Supply Chain Analysis
Upstream feedstock for gas-sensitive transducers draws from South African platinum group metal refiners, Chinese tin dioxide substrate fabricators, and Japanese solid-state laser component specialists. Raw material dependencies center on palladium catalyst layers, MEMS microphone die, and indium gallium arsenide photodetectors. Single-source vulnerability concentrates in noble metal offtake agreements held by established tier-one suppliers, locking out capital-constrained entrants. Distribution runs through HVAC system integrators bundling sensor platforms with climate control modules under multi-year OEM contracts.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized calibration engineering talent for cross-sensitivity compensation algorithms remains scarce relative to platform development pipelines, creating capability bottlenecks that favor incumbents with captive expertise retention.
For Market Incumbents: Build switching-cost moats through backward integration into noble metal catalyst supply chains and captive calibration engineering academies. Consolidate tier-two MOS suppliers facing margin compression from fabrication scale parity. Accelerate photoacoustic module qualification timelines to preempt emerging MEMS microphone specialists from achieving automotive-grade reliability. For New Entrants and Emerging Players: Build out aftermarket retrofit channels in Brazil and Mexico where aging vehicle populations lack OEM warranty coverage and independent service networks seek universal-fit modules. Target India BIS IS 17020 certification ahead of enforcement deadlines to capture first-mover procurement advantages in Maharashtra and Tamil Nadu assembly corridors. Pursue fleet operator direct relationships bypassing HVAC integrator consolidation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial gas detection specialists possessing automotive crossover potential but lacking OEM qualification infrastructure. Long-term viability hinges on firmware-defined sensitivity tuning capabilities rather than transducer hardware commoditization. Monitor India BIS accreditation completion rates as inflection indicator for geographic demand shift timing.| Strategic Initiative | Industry Significance |
|---|---|
| Photoacoustic Module Qualification Acceleration | Stuttgart-based tier-one suppliers are compressing 2027-2028 model year deployment timelines to capture premium cabin health positioning. |
| Noble Metal Supply Chain Integration | Backward control over palladium catalyst layers insulates platform margins from spot price volatility compressing mid-tier competitors. |
| Firmware-Defined Sensitivity Tuning | Digital calibration layers differentiate commodity MOS arrays from precision photoacoustic modules in OEM specification battles. |
| India BIS Certification Pre-positioning | Early IS 17020 accreditation creates procurement lock-in ahead of mandatory cabin air quality enforcement in domestic automotive production. |
| Fleet Data Telemetry Standardization | Unified sensor data architectures across mixed-vehicle portfolios displace discrete HVAC supplier relationships with integrated system vendors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, tier-one HVAC procurement leads, calibration engineering specialists, and aftermarket distribution channel managers. Secondary validation drew from NHTSA docket filings, EPA indoor air quality guidance documents, KBA vehicle type approval records, and BIS standard development committee minutes. Bottom-up sensor platform shipment estimates were triangulated against top-down automotive production forecasts and HVAC system integration ratios.
Calibration across technology adoption curves and regulatory enforcement timelines anchored the analytical framework over the projection horizon. Segmentation dimensions modeled include sensing modality, vehicle class, deployment architecture, and regional regulatory cluster. CAGRs were derived from unit economics trajectories for metal oxide semiconductor fabrication scale and photoacoustic module cost compression curves, with cross-reference to OEM specification sheet evolution and fleet procurement consolidation patterns.
Stress conditions across palladium price volatility bands, photoacoustic qualification timeline delays, and India BIS enforcement schedule shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding NHTSA guideline finalization and EPA cabin classification guidance adoption. Cross-checking against IHS Markit vehicle production databases and tier-one supplier order backlog disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Capacitive Touch Switch Panels for Vehicle Interiors Market
Automotive Interior & Exterior
Automotive Center Console Market
Automotive Interior & Exterior
Automotive Smart Seating Systems Market
Automotive Interior & Exterior
Interior Materials for Pet-Friendly Vehicle Cabins Market
Automotive Interior & Exterior
Automotive Automatic Liftgate Market
Automotive Interior & Exterior
Automotive Exterior Trim Parts Market
Automotive Interior & Exterior
Automotive Fridge Market
Automotive Interior & Exterior
Automotive Panoramic Sunroof Market
Automotive Interior & Exterior
LED Fog Lamp Market
Automotive Interior & Exterior
Auto Ventilated Seat Fan Market
Automotive Interior & Exterior
Automotive Reconfigurable Body Panel Market
Automotive Interior & Exterior
Automotive Interior Ambient Lighting Market
Automotive Interior & Exterior
Car Organizer Market
Automotive Interior & Exterior
Automotive Cabin Insulation Market
Automotive Interior & Exterior
Global Automotive Luggage Trim Market
Automotive Interior & Exterior
Car Canopies Market