
 Automotive Solenoid Market | 2026-2036
Automotive Solenoid Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Solenoid Market Analysis
East Asian solenoid manufacturing capacity is consolidating around high-volume electromagnetic actuator production for hybrid and battery-electric platforms. Robert Bosch GmbH leverages its integrated semiconductor and actuator divisions to control in-house production of high-pressure fuel solenoids. Denso Corporation anchors thermal management solenoid supply for Japanese and North American OEM transmission programs. Johnson Electric Holding Ltd. competes across low-to-medium power ratings with specialized brushless DC valve actuators for engine cooling circuits.
An automotive solenoid is an electromechanical transducer converting electrical energy into linear mechanical force, typically operating at 12V or 48V with response times under 10 milliseconds for fuel injector and transmission shift applications. Its primary commercial purpose is enabling precise fluid and gas flow control across powertrain, thermal, and chassis systems under electronic control unit command. Electromagnetic solenoids dominate starter motor and fuel system applications where rapid actuation cycles and established cost structures preserve incumbent positions. Electric vehicle solenoid demand is expanding fastest across HVAC refrigerant valve and battery thermal management circuits, where medium power ratings capture expanding margin pools as cooling architectures multiply.
NHTSA safety standards and EPA tailpipe regulations in the United States shape solenoid performance specifications for fuel metering accuracy and evaporative emissions containment. EMA and REACH compliance requirements in Europe restrict certain coil insulation chemistries while mandating durability testing protocols for under-hood thermal exposure. Stakeholders must monitor how 48V mild-hybrid proliferation and solid-state battery thermal architectures alter power rating and response-time specifications across next-generation actuator procurement programs.
Market Dynamics
Powertrain electrification is fragmenting solenoid demand across thermal management and transmission systems as 48V architectures and battery-electric platforms impose divergent actuator specifications on Tier 1 suppliers.
Growth Catalysts
- Euro 7 emissions mandates:European OEMs are deploying precision solenoid-controlled fuel injection and exhaust after-treatment systems to meet nitrogen oxide and particulate limits, expanding high-pressure actuator procurement.
- China EV production scaling:Domestic battery-electric manufacturers are integrating intelligent valve bodies and mechatronic modules into thermal management circuits, concentrating demand for medium-power electromagnetic actuators.
- 48V mild-hybrid proliferation:The voltage architecture shift is creating new specifications for starter-generator and active suspension solenoids across German and Japanese transmission programs.
Market Restraints
- Copper and rare-earth magnet cost volatility:Neodymium and copper coil winding prices fluctuate with mining output from Chinese and African suppliers, compressing margin stability for electromagnetic actuator producers.
- East Asian supply concentration:High-volume solenoid manufacturing clusters in Jiangsu and Guangdong provinces create geographic risk exposure for North American and European OEM procurement strategies.
- Electromechanical actuator substitution:Piezoelectric fuel injectors and brushless DC motors are displacing traditional solenoids in select fuel metering and engine cooling applications.
Strategic Opportunities
- India automotive electrification:The PLI scheme for advanced chemistry cell manufacturing is attracting thermal management solenoid investment for domestic EV battery pack assembly.
- Solid-state battery thermal architectures:Next-generation cooling systems require distributed refrigerant valve networks, opening white space for low-power precision actuators in prototype vehicle programs.
- REACH-compliant coil insulation chemistry:European ECHA restrictions on legacy varnish formulations are creating premium positioning for fluoropolymer and silicone-based insulation suppliers.
Industry Challenges
- Electromagnetic simulation talent scarcity:Finite element analysis expertise for thermal and magnetic field optimization remains concentrated among senior engineers at established Tier 1 suppliers.
- ISO 26262 functional safety certification timelines:Transmission shift and brake solenoid validation for ASIL-D ratings extends development cycles by 12-18 months.
- Legacy 12V system integration friction:Dual-voltage architectures complicate controller software and harness design for platforms spanning internal combustion and electrified variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Solenoid Market |
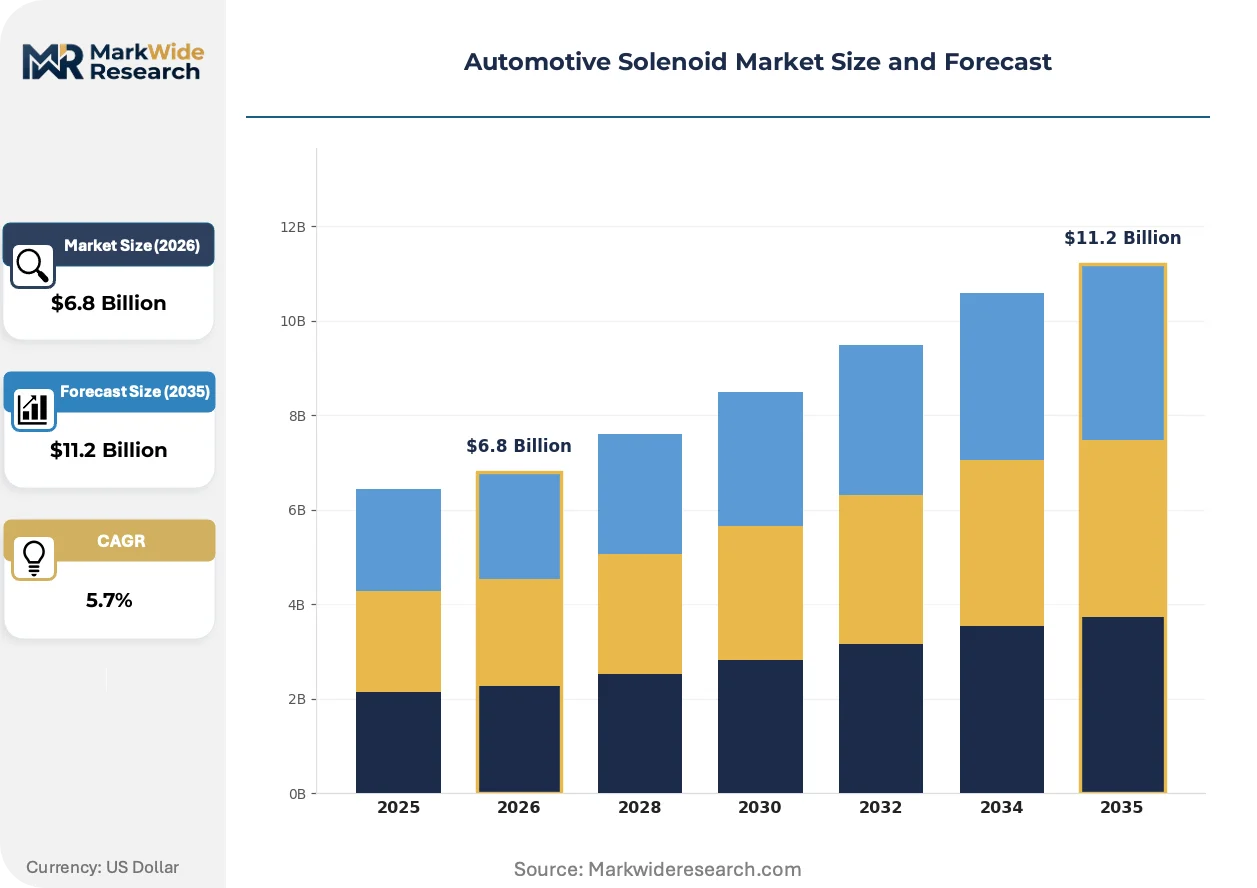
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromagnetic, Pneumatic, Hydraulic, Mechanical Application: Starter Motors, Fuel Systems, Transmission, HVAC Systems Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Electric Vehicles Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, BorgWarner Inc., Mitsubishi Electric Corporation, Hitachi Ltd., Johnson Electric Holding Ltd., Nidec Corporation, ZF Friedrichshafen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Solenoid Market Emerging Trajectories
Actuator architecture is fragmenting as modular thermal management systems and software-defined vehicle platforms redefine how solenoids are specified, procured, and integrated across powertrain domains.
Integrated mechatronic valve modules are consolidating multiple solenoid functions into single electromechanical assemblies with embedded position sensing. Tier 1 thermal system suppliers are adopting these compact units for battery and cabin HVAC circuits. This convergence is modularizing supplier tiers and compressing the traditional separation between valve body manufacturers and coil winding specialists.
EPA tailpipe regulations and NHTSA safety standards are tightening fuel metering accuracy and evaporative emissions containment specifications for internal combustion variants. United States OEMs are responding with redundant solenoid position feedback and enhanced coil thermal endurance testing. The compliance burden falls heaviest on light-duty truck and SUV programs where engine displacement remains elevated.
Fleet procurement of thermal management subsystems is consolidating around vertically integrated module suppliers capable of software calibration and vehicle-level thermal simulation. Traditional component distributors are losing share to direct OEM-Tier 1 engineering relationships. This channel compression is most visible in German and South Korean battery-electric vehicle programs where thermal architecture complexity demands early supplier involvement.
Automotive Solenoid Market Segmentation
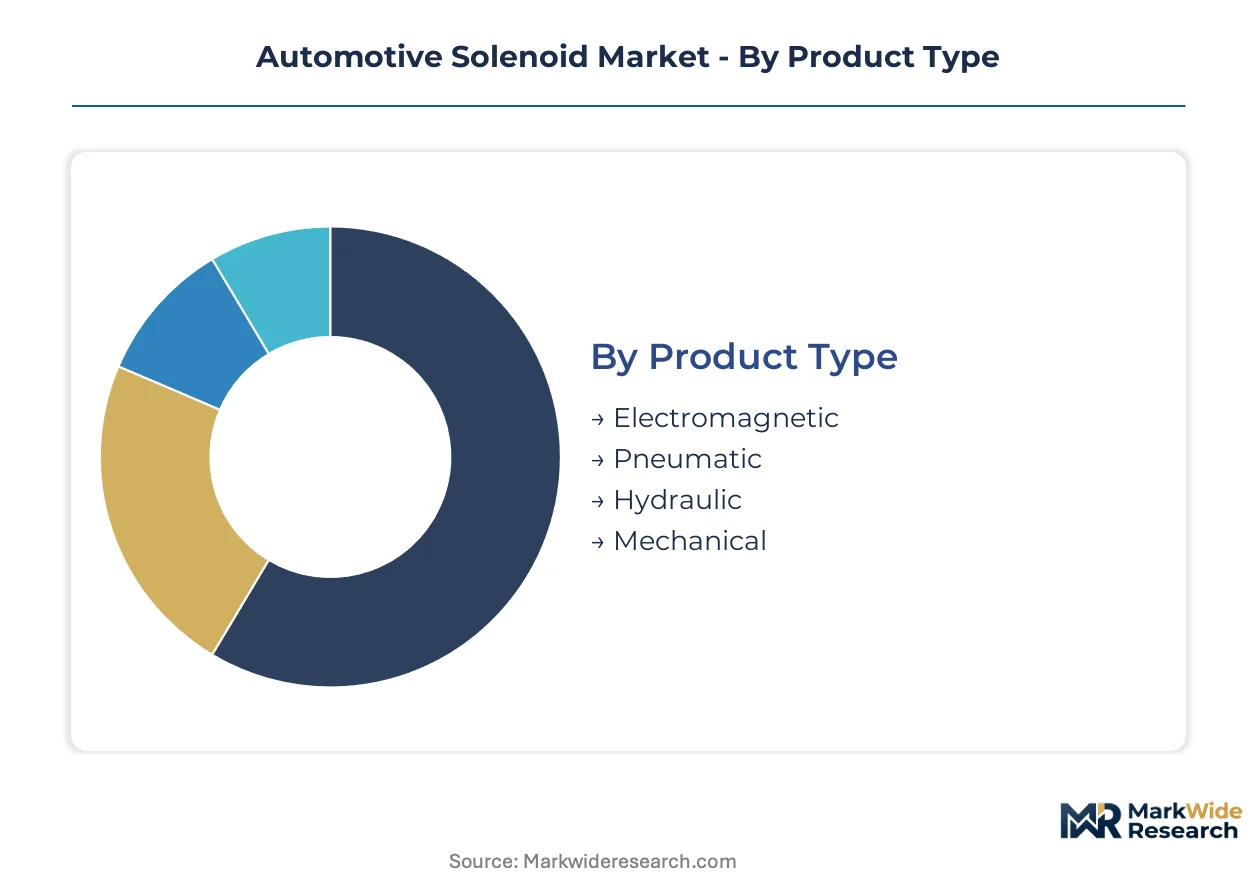
Automotive solenoid procurement patterns diverge sharply across powertrain architectures, with electrification reshaping how Tier 1 suppliers configure actuator portfolios. Understanding segment boundaries reveals where margin pools are concentrating versus commoditizing.
Product Type:
Buyers differentiate primarily by response-time requirements and electromagnetic field precision rather than raw force output.
- Electromagnetic:Coil-wound actuators dominate fuel injector and transmission shift applications where sub-10 millisecond response is mandatory. Demand concentrates in German and Japanese OEM transmission programs facing Euro 7 emissions deadlines, with copper coil specifications tightening under REACH-compliant insulation mandates.
- Pneumatic:Compressed-air actuators serve commercial vehicle air brake and suspension systems where force density requirements exceed electromagnetic limits. Procurement is accelerating in Indian and Brazilian heavy-truck manufacturing hubs as air brake mandates expand.
- Hydraulic:Fluid-pressure solenoids control automatic transmission clutch packs and power steering circuits. Volume remains anchored in legacy internal combustion platforms.
- Mechanical:Spring-return and cam-actuated devices persist in cost-sensitive starter motor applications. Share is eroding as electromagnetic alternatives achieve cost parity.
Electromagnetic solenoids lead volumes today; pneumatic variants are gaining share fastest in commercial vehicle electrification programs.
Application:
Specification intensity varies by thermal exposure cycles and functional safety certification requirements.
- Starter Motors:High-current electromagnetic switches engage pinion gears against flywheel torque. Demand is fragmenting as 48V mild-hybrid systems replace traditional 12V architectures, requiring redesigned coil windings and contact materials.
- Fuel Systems:Precision metering solenoids operate direct injection rails at pressures exceeding 200 bar. EPA tailpipe regulations and Euro 7 nitrogen oxide limits are extending validation cycles for ASIL-rated fuel injector actuators.
- Transmission:Multi-clutch control solenoids manage shift quality in dual-clutch and automatic units. Procurement is concentrating around integrated mechatronic valve modules with embedded position feedback.
- HVAC Systems:Refrigerant valve actuators regulate battery and cabin thermal circuits. Electric vehicle production scaling in China and South Korea is expanding specifications for medium-power actuators with extended temperature ranges.
Transmission applications lead volumes today; HVAC systems are climbing the fastest as battery thermal architectures multiply.
Vehicle Type:
Volume concentration and margin structure diverge by electrification pathway and production scale.
- Passenger Cars:Light-duty platforms consume the broadest solenoid portfolio across powertrain variants. Chinese domestic manufacturers are integrating intelligent valve bodies at scale, compressing supplier margins through direct OEM engineering relationships.
- Commercial Vehicles:Heavy-duty trucks and buses require pneumatic brake solenoids and high-cycle transmission actuators. Indian PLI scheme incentives are attracting thermal management solenoid investment for domestic EV bus assembly.
- Motorcycles:Compact electromagnetic units serve fuel injection and starter circuits. Specifications lag automotive platforms on response-time requirements.
- Electric Vehicles:Battery-electric platforms eliminate fuel system solenoids while multiplying thermal management actuator counts. Solid-state battery prototypes are testing distributed refrigerant valve networks requiring low-power precision actuators.
Passenger cars lead volumes today; electric vehicles are expanding most quickly across HVAC and battery cooling circuits.
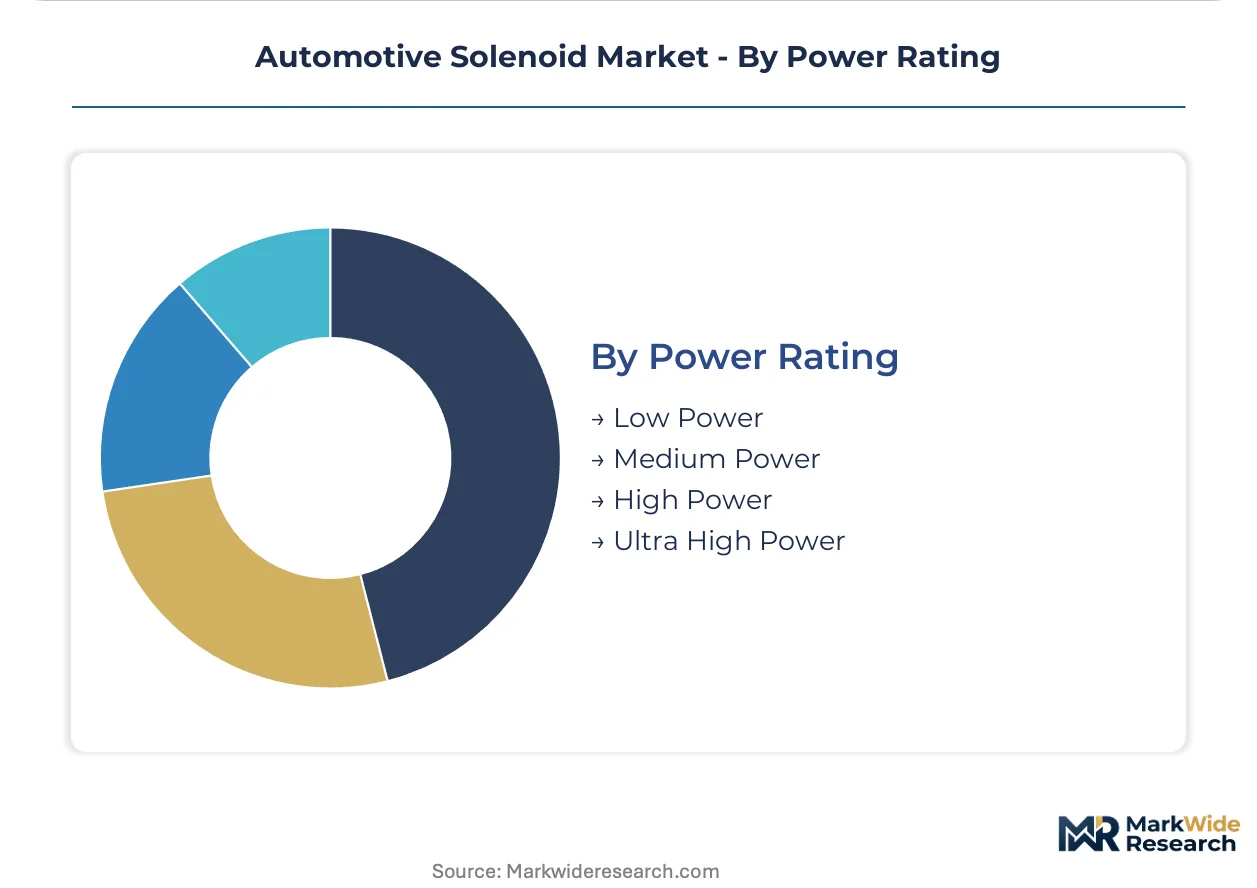
Power Rating:
Procurement economics shift dramatically across voltage architectures and force-density requirements.
- Medium Power:12V to 48V actuators serve transmission shift and thermal management valves where force-to-response balance is critical. This tier captures expanding margin pools as cooling architectures multiply in German and South Korean battery-electric programs.
- High Power:Heavy-current solenoids control starter motors and commercial vehicle air brake systems. Neodymium magnet cost volatility is compressing margin stability for producers serving this tier.
- Low Power:Compact actuators operate evaporative emissions purge valves and auxiliary circuits. Specifications are standardizing as 12V legacy platforms decline.
- Ultra High Power:Specialized electromagnetic units serve racing and military applications with extreme force density. Volume remains negligible in commercial automotive.
Medium power ratings lead volumes today; high power variants face substitution pressure from brushless DC motors in select cooling applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting solenoid manufacturing toward jurisdictions with favorable emissions compliance costs and established automotive clusters. Tier 1 suppliers are relocating coil winding and electromagnetic actuator assembly to exploit gaps between REACH enforcement in Europe and domestic content incentives in Asia.
China
Battery-electric vehicle production scaling drives thermal management solenoid procurement from BYD and CATL supply chains. MIIT dual carbon goals accelerate 48V mild-hybrid adoption across domestic transmission programs. Manufacturing concentrates in Jiangsu province, where Suzhou and Changzhou host high-volume electromagnetic actuator clusters serving German and Japanese OEM joint ventures.
Germany
Euro 7 nitrogen oxide limits compel precision fuel injection solenoid deployment across BMW and Mercedes-Benz engine platforms. KBA type-approval protocols extend validation timelines for ASIL-D rated transmission actuators. Production gravity sits in Baden-Württemberg, where Stuttgart-area suppliers integrate mechatronic valve modules for battery thermal management in Porsche and Audi EV programs.
United States
EPA tailpipe regulations tighten evaporative emissions containment specifications for light-duty truck solenoids. NHTSA safety standards mandate redundant position feedback for brake and transmission shift actuators. Industrial activity clusters in Michigan, where Detroit-area Tier 1s redesign 12V starter motor solenoids for 48V mild-hybrid architectures.
Japan
METI carbon neutrality roadmaps accelerate thermal management solenoid integration into Toyota and Honda battery-electric platforms. JIS durability testing protocols govern under-hood thermal exposure for coil insulation chemistries. Manufacturing concentrates in Aichi prefecture, where Nagoya-area suppliers anchor Denso and Mitsubishi Electric transmission actuator programs.
India
PLI scheme incentives for advanced chemistry cell manufacturing attract thermal management solenoid investment for Tata Motors and Mahindra EV battery packs. BIS certification requirements standardize electromagnetic actuator specifications for domestic commercial vehicle air brake systems. Production emerging in Tamil Nadu, where Chennai-area suppliers scale medium-power actuators for export to Southeast Asian bus manufacturers.
Automotive Solenoid Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue solid-state battery thermal architectures and 48V mild-hybrid specifications. The supplier base concentrates around integrated mechatronic module manufacturers with captive coil winding capabilities. Three archetypes dominate: diversified automotive electronics conglomerates with semiconductor-actuator integration, specialized electromagnetic component manufacturers, and vertically integrated thermal system suppliers. Competitive moves center on backward integration into rare-earth magnet supply chains and strategic partnerships with battery OEMs for thermal management program access.
Within the diversified conglomerate tier, Robert Bosch GmbH and Denso Corporation exemplify integrated production models spanning semiconductor and actuator divisions. Johnson Electric Holding Ltd. occupies a position among specialized electromagnetic component manufacturers with concentrated expertise in brushless DC valve actuation. These three entities anchor distinct competitive vectors: Bosch through in-house high-pressure fuel solenoid production, Denso via thermal management supply relationships with Japanese and North American OEMs, and Johnson Electric through targeted positioning across low-to-medium power ratings for engine cooling circuits.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| BorgWarner Inc. |
| Mitsubishi Electric Corporation |
| Hitachi Ltd. |
| Johnson Electric Holding Ltd. |
| Nidec Corporation |
| ZF Friedrichshafen |
| Others |
Supply Flow & Price Mechanics
Captive coil winding capabilities among integrated mechatronic module manufacturers anchor both supply security and pricing power across electromagnetic actuator procurement. Tier 1 suppliers with in-house semiconductor and actuator divisions command premium positioning against specialized coil winding competitors serving fragmented aftermarket channels.
Pricing Analysis
Distributor margin compression defines the channel economics as direct OEM-Tier 1 engineering relationships displace traditional component distributors. Three-tier pricing structure across ASIL-D certified, ISO 26262 compliant, and standard-grade actuators separates transmission shift solenoids from thermal management valves and auxiliary purge units. Cost compression in medium-power thermal management tiers is intensifying because Chinese domestic EV manufacturers are consolidating procurement around vertically integrated module suppliers. Fleet procurement teams at German and South Korean OEMs exhibit lowest price sensitivity due to thermal architecture complexity demands, while Indian commercial vehicle assemblers remain most price-sensitive in air brake actuator sourcing.
Supply Chain Analysis
Dual-sourcing requirements from NHTSA and KBA type-approval protocols mandate multi-supplier qualification for brake and transmission shift actuators across North American and German OEM programs. Manufacturing concentrates in China, Germany, and Japan, with Jiangsu province, Baden-Württemberg, and Aichi prefecture hosting high-volume electromagnetic clusters. Raw material dependencies center on copper coil windings, neodymium rare-earth magnets, and REACH-compliant fluoropolymer insulation chemistries. Single-source vulnerability persists in rare-earth magnet supply from Chinese mining operations. Distribution runs through direct OEM-Tier 1 contracts rather than aftermarket channels for battery-electric thermal management programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in medium-power thermal management actuators as solid-state battery prototypes multiply cooling circuit complexity and premium-tier ASIL-D certification requirements extend.
For Market Incumbents: Anchor market position through backward integration into rare-earth magnet supply chains and captive coil winding capacity additions in Tamil Nadu to serve Indian PLI scheme battery pack assembly. Piezoelectric fuel injector substitution threatens high-pressure solenoid demand in European direct injection programs. ISO 26262 functional safety certification investment for transmission shift actuators defends margin position against emerging mechatronic module competitors. For New Entrants and Emerging Players: Capture white space in distributed refrigerant valve networks for solid-state battery thermal architectures where established suppliers lack prototype-scale production experience. India's commercial vehicle electrification presents the most penetrable geography given BIS standardization of air brake specifications and PLI scheme capital availability. Partner with domestic battery OEMs for early thermal management program access rather than competing for legacy transmission actuator procurement. For Investors and Strategic Acquirers: Roll-up economics work for specialized electromagnetic component manufacturers because ASIL-D validation timelines and finite element analysis talent scarcity create durable moats against commoditization. Target acquisition archetype: mid-cap coil winding specialists with captive fluoropolymer insulation chemistry expertise and existing Denso or Bosch supply relationships. Watch for inflection in 48V mild-hybrid platform proliferation at German and Japanese OEMs as signal for medium-power actuator demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Neodymium cost volatility from Chinese mining operations threatens margin stability for high-power actuator producers. |
| ASIL-D Functional Safety Certification Investment | KBA and NHTSA protocols extend validation timelines, creating barrier against unqualified competitors in brake and transmission applications. |
| Solid-State Battery Thermal Architecture Partnership | Distributed refrigerant valve networks in prototype programs open premium positioning for low-power precision actuator specialists. |
| India PLI Scheme Manufacturing Footprint | Tamil Nadu emerging as export hub for medium-power actuators serving Southeast Asian commercial vehicle electrification. |
| REACH-Compliant Insulation Chemistry Development | ECHA restrictions on legacy varnish formulations create premium tier for fluoropolymer and silicone-based coil suppliers. |
Methodological Framework
Bottom-up vehicle production modeling reconciled against top-down electromagnetic actuator shipment tracking forms the analytical core of this study. Primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, thermal system R&D leads, and aftermarket distribution channel heads combined with secondary validation from vehicle registration databases, IHS Markit production forecasts, EPA certification filings, and KBA type-approval records. Triangulation between demand-side consumption patterns and supply-side manufacturing capacity ensures consistency across market sizing estimates.
Input-output matrices map solenoid content per vehicle across propulsion architecture, vehicle class, and regional production cluster dimensions. Growth trajectory derivation incorporates battery-electric platform ramp schedules, 48V mild-hybrid adoption curves, and Euro 7 compliance deadlines throughout the projection horizon. Forecast inputs include MIIT dual carbon policy implementation timelines, PLI scheme disbursement patterns, and solid-state battery prototype development milestones across German and South Korean OEM programs.
Underlying measurement precision varies by segment; electric vehicle thermal management and transmission shift applications carry tighter precision than legacy starter motor and mechanical actuator categories due to consolidated procurement data availability. Forecasts reflect assumptions regarding REACH enforcement consistency, rare-earth magnet supply continuity, and OEM platform standardization decisions. Deviation in solid-state battery commercialization timelines or Euro 7 implementation delays would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Carbon Brake Rotor Market
Automotive Components
Torque Vectoring Market
Automotive Components
China Automotive Composites Market
Automotive Components
Automotive Tie Rod Market
Automotive Components
Automotive Braking Component Market
Automotive Components
Automotive Air Intake Manifold Market
Automotive Components
Europe and North Africa Automotive Window Regulator Market
Automotive Components
Automotive Resonator Market
Automotive Components
Automotive Hardware Market
Automotive Components
Europe Automotive Airfilters Market
Automotive Components
Electronic Clutch Actuators Market
Automotive Components
Automotive Spark Plug Market
Automotive Components
Automotive Metal Casting Market
Automotive Components
Automotive Bushing Technologies Market
Automotive Components
Egypt Commercial Vehicles Lubricants Market
Automotive Components
Italy Automotive Sunroof Market