
 Global Automotive Radiator Market | 2026-2036
Global Automotive Radiator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Radiator Market Intelligence
The integration of radiators into complete thermal management modules is rebalancing the value proposition from a standalone component to a system-level solution. Denso Corporation leverages its extensive R&D in thermal systems to offer these integrated solutions for both conventional and electric vehicles. Valeo SA competes on the basis of its broad portfolio covering advanced cooling technologies. Meanwhile, MAHLE GmbH sustains its market position through deep specialization in engine components and filtration systems, anchoring its presence in the OEM segment.
An automotive radiator is a heat exchanger designed to transfer thermal energy from an engine's liquid coolant to the surrounding air. It typically consists of a core with fins and tubes, often constructed from aluminum for its high thermal conductivity and low weight, and tanks on either side. Aluminum radiators dominate the product landscape due to their efficiency and weight advantages, especially within the passenger cars segment. The heavy-duty trucks segment, however, presents a significant market for more durable copper-brass radiator designs, particularly in the aftermarket.
Regulations like the US EPA's vehicle emissions standards and the EU's F-Gas Regulation indirectly influence radiator design by pushing for more efficient engine cooling. In China, directives from the MIIT on vehicle energy consumption and new energy vehicles directly shape component specifications for domestic and export models. Component suppliers must now decide whether to specialize in high-performance radiators for internal combustion engines or pivot towards thermal management systems for electric vehicle batteries.
Market Dynamics
The automotive radiator market is defined by a fundamental technological divergence. Manufacturers face a strategic split between optimizing high-efficiency radiators for advanced internal combustion engines and developing entirely new thermal management systems for the growing electric vehicle segment, a division driven by global emissions regulations.
Growth Catalysts
- Stringent Emissions Regulations:Mandates such as the US EPA's vehicle standards and the EU's F-Gas Regulation compel automakers to adopt more efficient engine cooling, driving demand for lightweight aluminum radiators that improve fuel economy.
- Heavy-Duty Vehicle Demand:The global heavy-duty trucks segment provides a consistent source of demand, particularly in the aftermarket where durable copper-brass radiators remain a preferred option for their repairability and robustness.
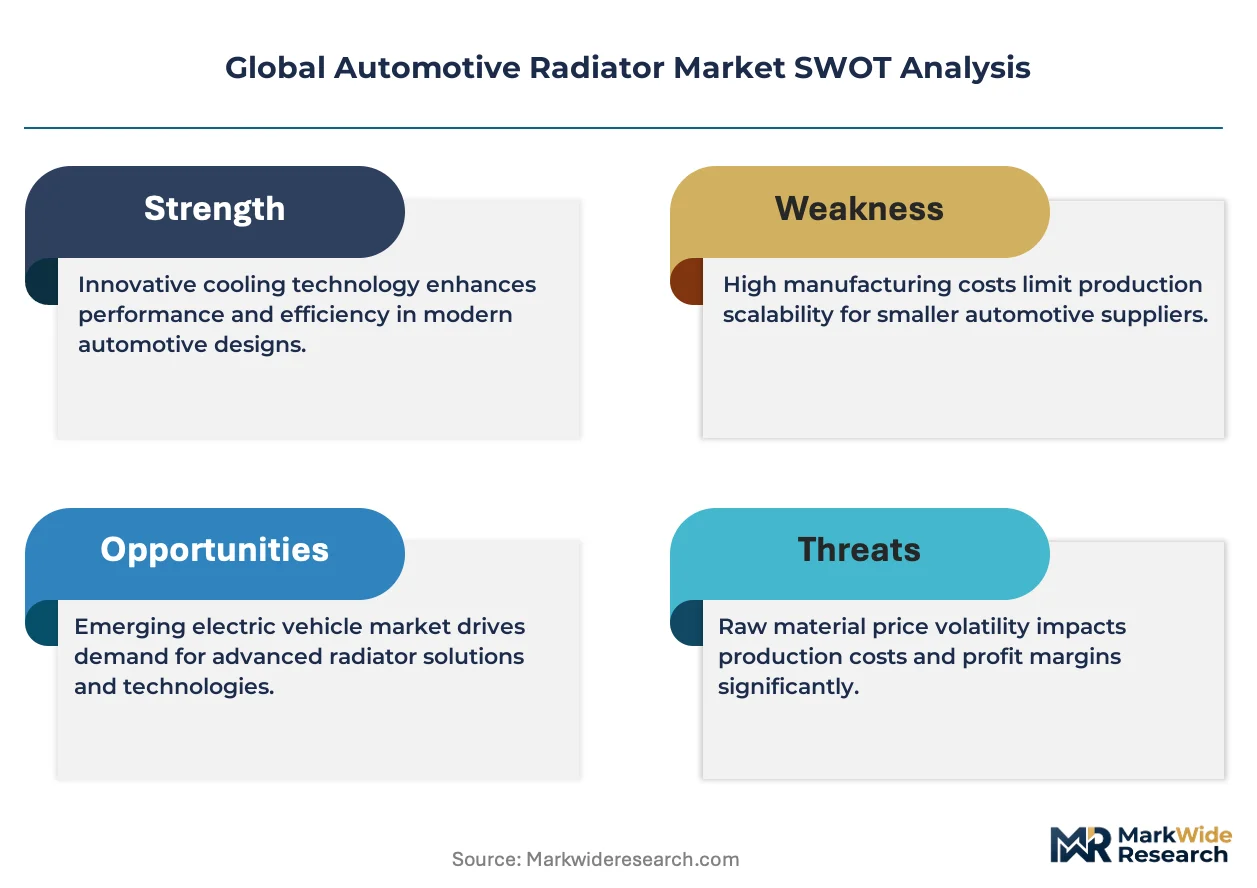
- System Integration:The evolution from standalone radiators to integrated thermal management modules, which include condensers and fans, expands the value proposition and creates opportunities for system-level suppliers.
Market Restraints
- Material Price Volatility:Fluctuations in the global prices of aluminum and copper, the primary raw materials for radiators, create significant cost pressures and margin uncertainty for manufacturers.
- Technological Substitution:The long-term transition to battery electric vehicles presents a substitution threat, as these vehicles do not use traditional engine radiators, requiring different thermal management solutions.
- Aftermarket Competition:The presence of numerous low-cost producers, particularly in China, intensifies price competition in the aftermarket segment, eroding margins for established original equipment suppliers.
Strategic Opportunities
- Electric Vehicle Thermal Management:Developing specialized cooling plates, chillers, and heat pump systems for EV batteries and electronics offers a high-growth pivot away from the traditional ICE radiator market.
- Aftermarket in Emerging Economies:An aging vehicle parc and an expanding middle class in regions like Latin America and Southeast Asia create a growing, sustainable demand for replacement radiators and components.
- Advanced Materials and Manufacturing:The use of novel aluminum alloys and advanced manufacturing processes like controlled atmosphere brazing enables the production of more efficient, compact, and durable radiator designs for high-performance applications.
Industry Challenges
- Complex Compliance Landscape:Manufacturers must navigate a patchwork of regional standards, from China's MIIT directives on energy consumption to European end-of-life vehicle regulations, complicating global product development and certification.
- System Integration Complexity:Ensuring seamless hardware and software interoperability between the radiator module and the vehicle's central electronic control unit (ECU) is a significant engineering challenge for suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Radiator Market |
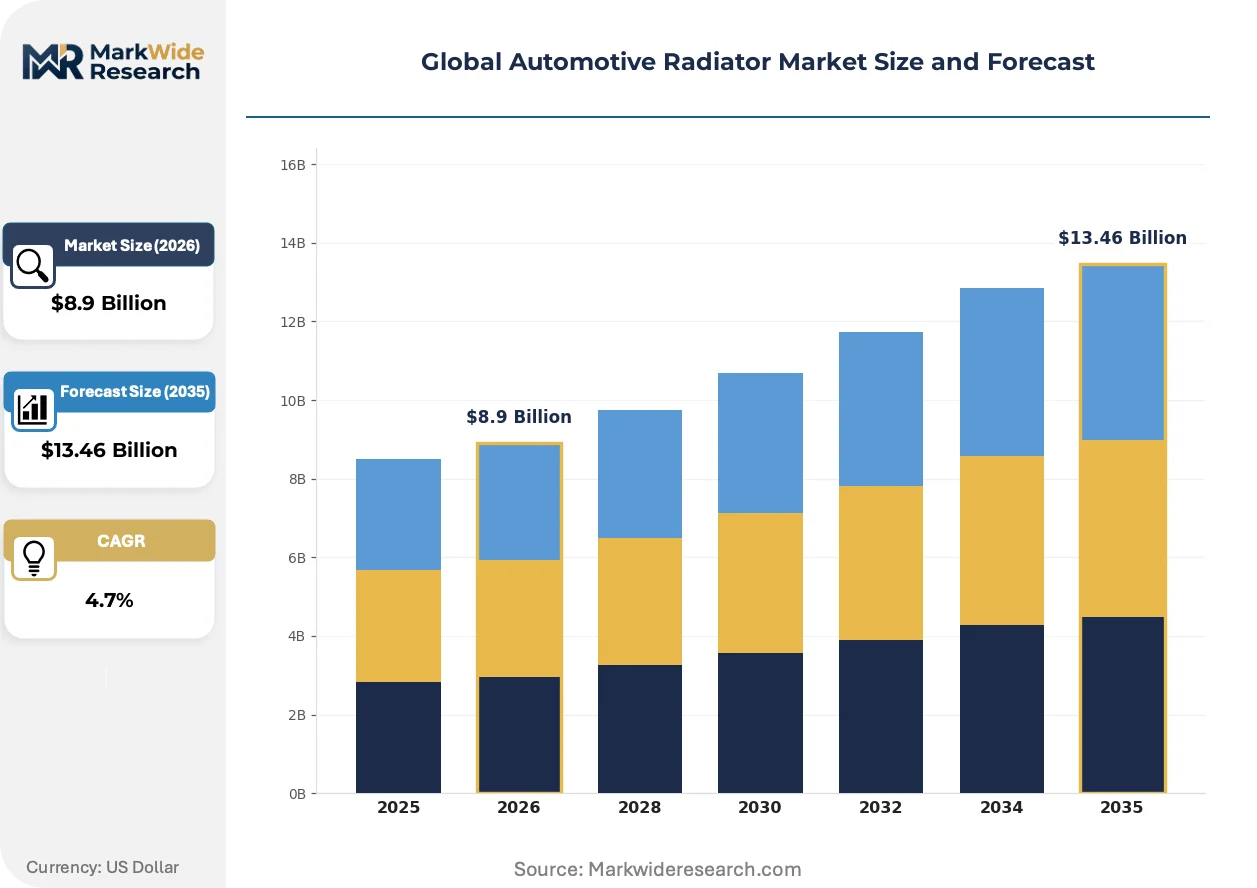
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $13.46 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Radiators, Copper-Brass Radiators, Plastic Composite Radiators, Stainless Steel Radiators Technology: Cross-Flow, Down-Flow, Top-Flow, Dual-Pass Vehicle Type: Passenger Cars, Light Commercial Vehicles, Heavy-Duty Trucks, Motorcycles End User: OEM Manufacturers, Aftermarket Suppliers, Vehicle Assemblers, Tier-1 Component Makers |
| Companies Covered | Denso Corporation, Valeo SA, MAHLE GmbH, Modine Manufacturing Company, Marelli Corporation, Visteon Corporation, Hanon Systems, T.RAD Co., Ltd., Calsonic Kansei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Radiator Market Strategic Shifts & Innovations
A key trend is the bifurcation of product strategy, forcing suppliers to choose between perfecting high-efficiency components for the final generation of internal combustion engines or investing in entirely new thermal architectures for electric mobility. This strategic decision is reshaping R&D priorities and supply chain structures.
Integrated thermal management modules combine the radiator, condenser, fan, and associated electronics into a single, pre-tested unit. Automakers in the passenger vehicle segment are increasingly adopting these systems to streamline vehicle assembly lines and optimize cooling performance. This shift is consolidating the supply base, favoring large Tier 1 suppliers capable of delivering complete, validated systems over manufacturers of standalone components.
Regulations like the US EPA's stringent emissions standards for heavy-duty trucks indirectly drive innovation in radiator technology. These rules push for greater engine efficiency, which in turn requires more effective cooling systems that can operate under higher thermal loads without compromising fuel economy. The heavy-duty segment is therefore seeing increased adoption of advanced, high-performance aluminum radiators previously common only in passenger cars.
A notable change in aftermarket procurement is the rise of direct sourcing by large e-commerce platforms and multi-regional repair shop chains. This model bypasses traditional tiered distribution, putting pressure on regional wholesalers that have historically served independent repair shops. This trend is most pronounced in the North American market for common passenger car replacement models, where logistics and online platforms are highly mature.
Global Automotive Radiator Market Segmentation
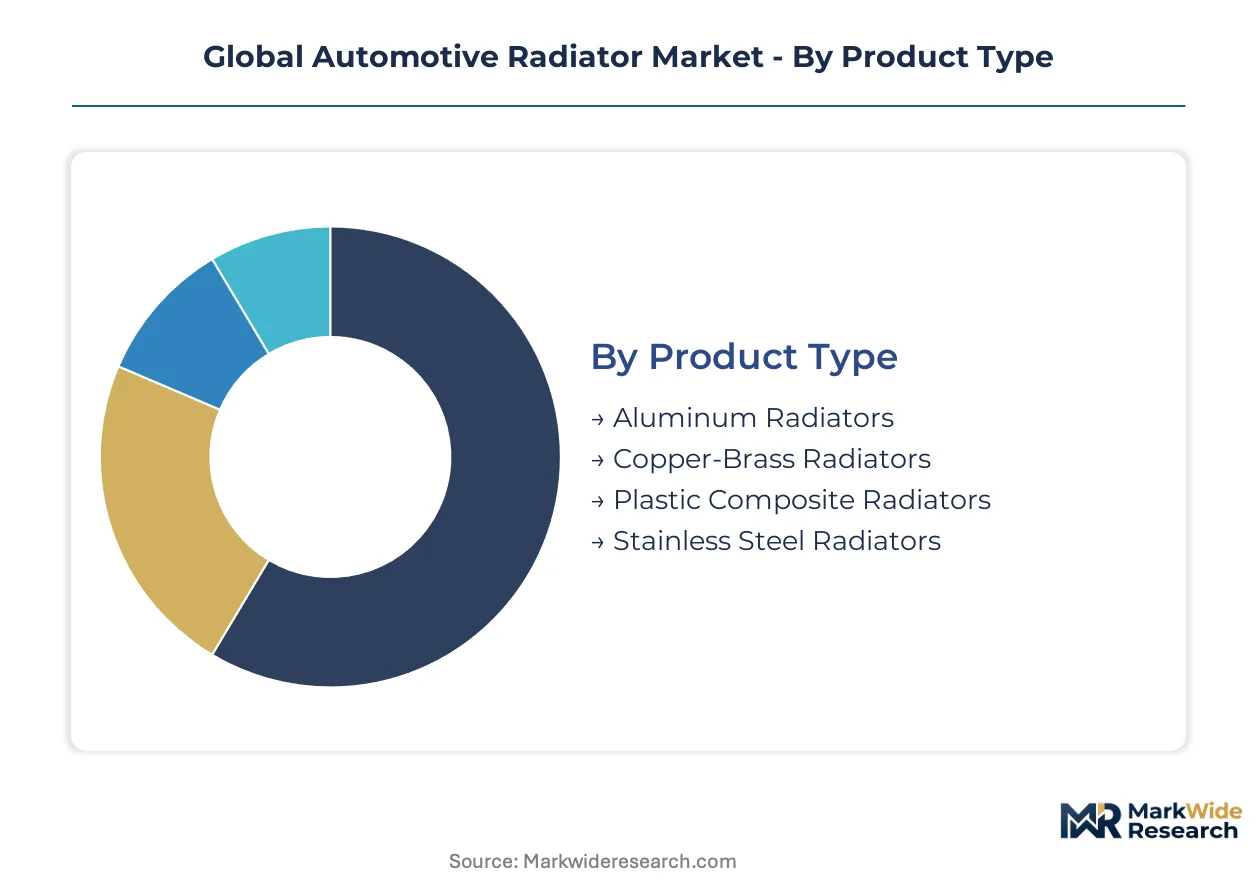
The automotive radiator market's granular segmentation reveals distinct value pools and competitive dynamics across product types, technologies, vehicle applications, and end-user ecosystems. Understanding these divisions helps stakeholders align product development and market strategies with specific demand drivers and regulatory pressures.
Product Type:
Supply concentration in product type for automotive radiators heavily favors aluminum, driven by its lightweight properties and thermal efficiency. Manufacturing capabilities for aluminum radiators are globally distributed, with significant hubs in Asia.
- Aluminum Radiators:These heat exchangers are predominantly constructed from aluminum alloys, offering superior thermal conductivity and reduced weight compared to traditional materials. Demand for aluminum radiators is concentrating in the passenger cars segment, driven by stringent fuel economy regulations and the need for improved vehicle performance.
- Copper-Brass Radiators:Comprising copper tubes and brass fins, these radiators are known for their durability and repairability, making them suitable for demanding applications. The heavy-duty trucks segment provides a consistent market for copper-brass radiators, particularly within the aftermarket, where robustness is prized.
- Plastic Composite Radiators:These radiators often combine aluminum cores with plastic end tanks, balancing cost-effectiveness with adequate performance for certain vehicle types.
- Stainless Steel Radiators:Offering high corrosion resistance and strength, stainless steel radiators find niche applications where extreme durability and chemical inertness are critical.
Today's leader: Aluminum Radiators. Tomorrow's challenger: Stainless Steel Radiators.
Technology:
Radiator technology differentiates primarily by coolant flow path and design, impacting efficiency and packaging within diverse vehicle architectures.
- Cross-Flow:In cross-flow radiators, coolant flows horizontally from one tank to the other, passing through the core. This design is often favored for its lower profile, allowing for more flexible engine bay layouts in modern vehicles.
- Down-Flow:Down-flow radiators feature coolant entering at the top tank and flowing vertically downward to the bottom tank, utilizing gravity to assist coolant movement. This configuration is common in older vehicle designs and some heavy-duty applications.
- Top-Flow:Top-flow designs are a variation where coolant enters and exits from the top, often configured for specific engine cooling requirements.
- Dual-Pass:Dual-pass radiators route coolant through the core twice, enhancing heat transfer efficiency in a more compact design.
The market for cross-flow designs is expanding most quickly, while dual-pass technology offers significant future potential.
Vehicle Type:
Demand for automotive radiators is heavily influenced by vehicle production volumes and specific cooling requirements across different transportation segments.
- Passenger Cars:This segment includes sedans, SUVs, and hatchbacks, requiring compact and highly efficient aluminum radiators to meet fuel economy and emissions standards. Passenger cars represent the largest volume segment, driving innovation in lightweight thermal solutions.
- Heavy-Duty Trucks:These vehicles, including commercial trucks and buses, demand robust and durable radiators capable of dissipating significant heat from powerful engines. The heavy-duty trucks segment provides a consistent source of demand, particularly for copper-brass designs in the aftermarket.
- Light Commercial Vehicles:This category encompasses vans and smaller trucks used for commercial purposes, balancing efficiency with durability in their cooling system needs.
- Motorcycles:Motorcycles utilize smaller, often more specialized radiators designed for compact spaces and specific engine cooling characteristics.
Passenger cars command the largest market share, while heavy-duty trucks maintain a stable, high-value segment.
End User:
The end-user landscape for automotive radiators is bifurcated between original equipment manufacturers and the aftermarket, each with distinct procurement patterns and product requirements.
- OEM Manufacturers:These are the vehicle manufacturers that integrate radiators into new vehicles during assembly, demanding high volumes, stringent quality control, and just-in-time delivery. OEM manufacturers prioritize integrated thermal management modules to streamline vehicle assembly.
- Aftermarket Suppliers:This segment comprises distributors and retailers providing replacement radiators for vehicle repair and maintenance, focusing on product availability, competitive pricing, and broad vehicle compatibility. Aftermarket suppliers cater to an aging vehicle parc in many regions.
- Vehicle Assemblers:These entities assemble vehicles from components, often for smaller production runs or specialized applications, requiring flexible supply chains for radiator procurement.
- Tier-1 Component Makers:These suppliers manufacture and integrate complex systems, including thermal modules, directly for OEMs, often involving extensive R&D and engineering collaboration.
OEM Manufacturers drive initial market volume, while Aftermarket Suppliers ensure long-term product lifecycle support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and China present contrasting demand drivers for automotive radiators, reflecting diverse market maturity and regulatory landscapes. US demand centers on aftermarket replacement and heavy-duty vehicles, while China's market is shaped by new vehicle production and electric mobility mandates. This divergence influences material choices and technological investments across both nations.
United States
Demand for automotive radiators in the United States stems from a large aging vehicle parc and robust heavy-duty truck sales. The US EPA's vehicle emissions standards push for more efficient engine cooling, favoring lightweight aluminum designs. Major automotive manufacturing hubs in Michigan and Ohio concentrate significant OEM and aftermarket supply chain activity.
China
China's automotive radiator market is driven by high vehicle production volumes and aggressive new energy vehicle policies. Directives from the MIIT on vehicle energy consumption and new energy vehicles directly shape component specifications for domestic and export models. OEM manufacturing hubs in provinces like Guangdong and Jiangsu are central to both original equipment and aftermarket supply chains.
Germany
Germany's market for automotive radiators benefits from a strong premium automotive sector and stringent environmental regulations. The EU's F-Gas Regulation indirectly influences radiator design by pushing for more efficient engine cooling and climate control systems. Automotive component suppliers in Baden-Württemberg and Bavaria focus on high-performance and integrated thermal modules.
Japan
Japanese demand for automotive radiators is influenced by advanced vehicle technology and a focus on fuel efficiency in passenger cars. METI's industrial policies support innovation in lightweight materials and compact thermal management solutions. Major automotive component clusters around Toyota City and Yokohama drive R&D and manufacturing for global markets.
India
India's automotive radiator market experiences demand from a rapidly expanding middle class purchasing new vehicles and a significant aftermarket for older models. The country's vehicle emissions norms, aligning with global standards, drive the adoption of more efficient cooling systems. Automotive manufacturing zones in Chennai and Pune are key centers for both domestic and export radiator production.
Global Automotive Radiator Market Key Industry Players
Top-tier vendors anchor the integrated thermal management system market, while specialized component manufacturers target specific segments. The industry structure shows a mix of large, diversified players and niche specialists. Strategic archetypes include global system suppliers, regional aftermarket providers, and emerging EV thermal solution developers. Dominant competitive moves involve portfolio diversification into EV solutions and strategic partnerships for system integration.
Among global thermal system providers, Denso Corporation and Valeo SA exemplify diversified portfolio strategies across conventional and electric vehicle applications. MAHLE GmbH occupies a position as a specialist in engine components, including advanced cooling systems. Modine Manufacturing Company further anchors this segment with its long-standing presence in heat transfer technologies.
| Leading Market Players |
|---|
| Denso Corporation |
| Valeo SA |
| MAHLE GmbH |
| Modine Manufacturing Company |
| Marelli Corporation |
| Visteon Corporation |
| Hanon Systems |
| T.RAD Co., Ltd. |
| Calsonic Kansei Corporation |
| Others |
Cost & Logistics Intelligence
Stringent fuel economy regulations in the US and EU compel automakers to adopt lightweight aluminum radiators. This demand necessitates a supply chain capable of high-volume aluminum component manufacturing, influencing pricing dynamics across the market.
Pricing Analysis
Capacity additions in China are reshaping price floors for aluminum radiators in the aftermarket segment. The dominant pricing model is per-unit transactional, with long-term contracts for OEM manufacturers. Price differentiation stems from quality grade, with OEM-certified parts commanding premiums over generic aftermarket alternatives. Pricing pressure intensifies due to competition from numerous low-cost producers, particularly impacting the aftermarket where buyers are most price-sensitive.
Supply Chain Analysis
OEM manufacturers often mandate dual-sourcing requirements, diversifying risk across the automotive radiator supply chain. Geographic supply concentration centers on China, Japan, and Germany for finished goods. Raw material dependencies include aluminum, copper, and brass. Commodity price volatility for these materials presents a significant supply chain risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global automotive radiator market presents a geographic-arbitrage play, leveraging lower manufacturing costs in Asian hubs like China for export, while meeting stringent regulatory demands in Europe and North America.
For Market Incumbents: Acquire specialized EV thermal management system developers to counter the threat of technological substitution. Invest heavily in advanced materials R&D for lightweight aluminum and novel alloys, maintaining a competitive edge in high-performance ICE applications. Consolidate production capacity in strategic regions to optimize logistics and reduce exposure to raw material price volatility.
For New Entrants and Emerging Players: Launch via online direct-to-consumer channels, targeting the aftermarket segment in emerging economies like Southeast Asia. Focus on specialized cooling plates and chillers for electric vehicle batteries, a high-growth white-space target. Offer cost-effective, durable copper-brass radiator alternatives for heavy-duty trucks where repairability is valued.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists focused on integrated thermal management modules for electric vehicles. These firms offer long-term viability by pivoting away from traditional ICE components. The signal to watch is OEM announcements for dedicated EV platforms and strategic partnerships for thermal system development.
| Strategic Initiative | Industry Significance |
|---|---|
| Diversify into EV Thermal Management | Reduces reliance on internal combustion engine components, securing future revenue streams from electric vehicles. |
| Invest in Advanced Aluminum Alloys | Improves radiator efficiency and reduces weight, meeting stringent fuel economy regulations for passenger cars. |
| Expand Aftermarket Presence in Emerging Economies | Captures demand from aging vehicle fleets and expanding middle-class populations in regions like India. |
| Form Partnerships for System Integration | Enables Tier 1 suppliers to offer complete thermal management modules, streamlining OEM assembly processes. |
| Optimize Manufacturing Footprint in Asia | Leverages cost efficiencies in OEM manufacturing hubs like China, enhancing global competitive pricing. |
Research Approach
Bottom-up passenger car modeling reconciled against top-down OEM manufacturing tracking forms the analytical core. This study combines primary interviews with OEM procurement managers, Tier 1 R&D directors, aftermarket distributors, and heavy-duty truck fleet operators. Secondary validation draws from vehicle production databases, regulatory filings from the US EPA, EU F-Gas Regulation, and China MIIT, alongside industry association reports.
Historical trendline analysis informed the projection of market dynamics across the analysis window. Segmentation dimensions modeled include product type, technology, vehicle application, end-user, and regional regulatory impact. Compound annual growth rates were derived from observed historical performance and projected market shifts. Key industry-specific forecast inputs included electric vehicle penetration rates and raw material price forecasts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid EV transition or raw material price shocks. Forecasts reflect assumptions regarding technological evolution and regulatory enforcement. Deviation in global emissions standards would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Skid Plate Market
Automotive Components
Metal Forming for Automotive Market
Automotive Components
India Passenger Vehicles Lubricants Market
Automotive Components
Automotive Brackets Market
Automotive Components
Automotive Push Rods Market
Automotive Components
Automotive Regenerative Braking System Market
Automotive Components
Beryllium Copper for Automobile Market
Automotive Components
Automotive Engine Bearings Market
Automotive Components
Global Automotive Coupling Market
Automotive Components
Automotive Active Bonnet Market
Automotive Components
Asia Pacific Automotive Bearing Market
Automotive Components
Polyamide in E-Mobility Market
Automotive Components
Automotive Carbon Fiber Composites Parts Market
Automotive Components
Global Automotive Fifth Wheel Coupling Market
Automotive Components
Italy Automotive Sunroof Market
Automotive Components
Global Automotive Active Body Panel Market