
 Vehicle Management System Market | 2026-2036
Vehicle Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Management System Market Insights
Software-defined subscription tiers for predictive maintenance and driver behavior analytics is decoupling hardware sales from recurring revenue streams across the vehicle management system landscape. Geotab leverages its open-platform architecture to sustain ecosystem partnerships with third-party developers. Samsara dominates the cloud-native segment with integrated video telematics and IoT sensor fusion. Verizon Connect anchors enterprise fleet deployments through bundled connectivity and professional services.
A vehicle management system integrates GPS tracking, engine diagnostics, wireless communication modules, and centralized dashboards to monitor fleet location, fuel consumption, driver performance, and maintenance schedules in real time. The primary commercial purpose is to reduce operational expenditures, enforce regulatory compliance, and extend asset utilization rates across dispersed vehicle populations. Fleet management solutions command the largest installed base due to established ROI metrics in logistics and trucking, while data analytics represents the fastest-expanding margin pool as operators shift from raw telemetry storage to predictive decision engines. Cloud-based deployment models are displacing on-premises infrastructure among mid-sized fleets seeking lower capital barriers and faster scalability.
NHTSA, FMCSA, and the EPA collectively shape product requirements through electronic logging device mandates, emissions reporting standards, and safety scoring protocols that determine fleet insurance premiums and operating authority. The EU Green Deal and F-Gas Regulation add compliance layers for European operators managing refrigerated transport and alternative-fuel transitions. Stakeholders must monitor how fragmented national data-privacy rules affect cross-border telematics data flows and platform architecture choices.
Market Dynamics
Software-defined architectures are decoupling hardware from recurring revenue streams, forcing fleet management vendors to restructure pricing around data analytics subscriptions rather than upfront telematics hardware sales.
Growth Catalysts
- FMCSA Hours-of-Service Rules:Electronic logging device mandates in the United States compel fleet operators to replace legacy paper logbooks with connected compliance systems, accelerating hardware refresh cycles across trucking and logistics fleets.
- Last-Mile Delivery Expansion:E-commerce fulfillment networks in Germany and China are deploying real-time route optimization and driver behavior monitoring to meet same-day delivery service-level agreements.
- Predictive Maintenance Algorithms:Machine learning models processing engine diagnostic data are reducing unplanned downtime for refrigerated transport operators managing temperature-sensitive pharmaceutical and food cargo.
Market Restraints
- Semiconductor Supply Concentration:GPS modules and cellular modems depend on concentrated Asian manufacturing, exposing fleet telematics providers to component lead-time volatility and inventory carrying costs.
- GDPR Data Localization:European Union privacy rules fragment cross-border telematics data flows, forcing platform operators to maintain redundant infrastructure across national jurisdictions.
- Legacy Fleet Replacement Inertia:Small owner-operator trucking businesses retain analog maintenance practices, delaying connected system adoption due to perceived complexity and upfront capital requirements.
Strategic Opportunities
- India Commercial Vehicle Digitization:The country's PLI scheme for automotive electronics and expanding national highway freight corridors create entry points for cloud-native fleet platforms targeting mid-sized logistics operators.
- Video Telematics Convergence:Integration of AI-powered dashcams with traditional GPS tracking is opening new insurance partnerships where underwriters price premiums based on verified driver behavior data.
- EU Green Deal Refrigerated Transport:F-Gas Regulation compliance deadlines are driving demand for connected cold-chain monitoring that tracks refrigerant leaks and documents emissions for regulatory reporting.
Industry Challenges
- Embedded Systems Engineering Talent:Vendors struggle to recruit firmware developers capable of optimizing low-power wireless communication protocols for battery-operated trailer tracking devices.
- Multi-Protocol Integration Complexity:Fleet operators demand seamless unification of OEM-installed telematics, aftermarket sensors, and third-party logistics software through standardized APIs that remain inconsistently implemented.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Management System Market |
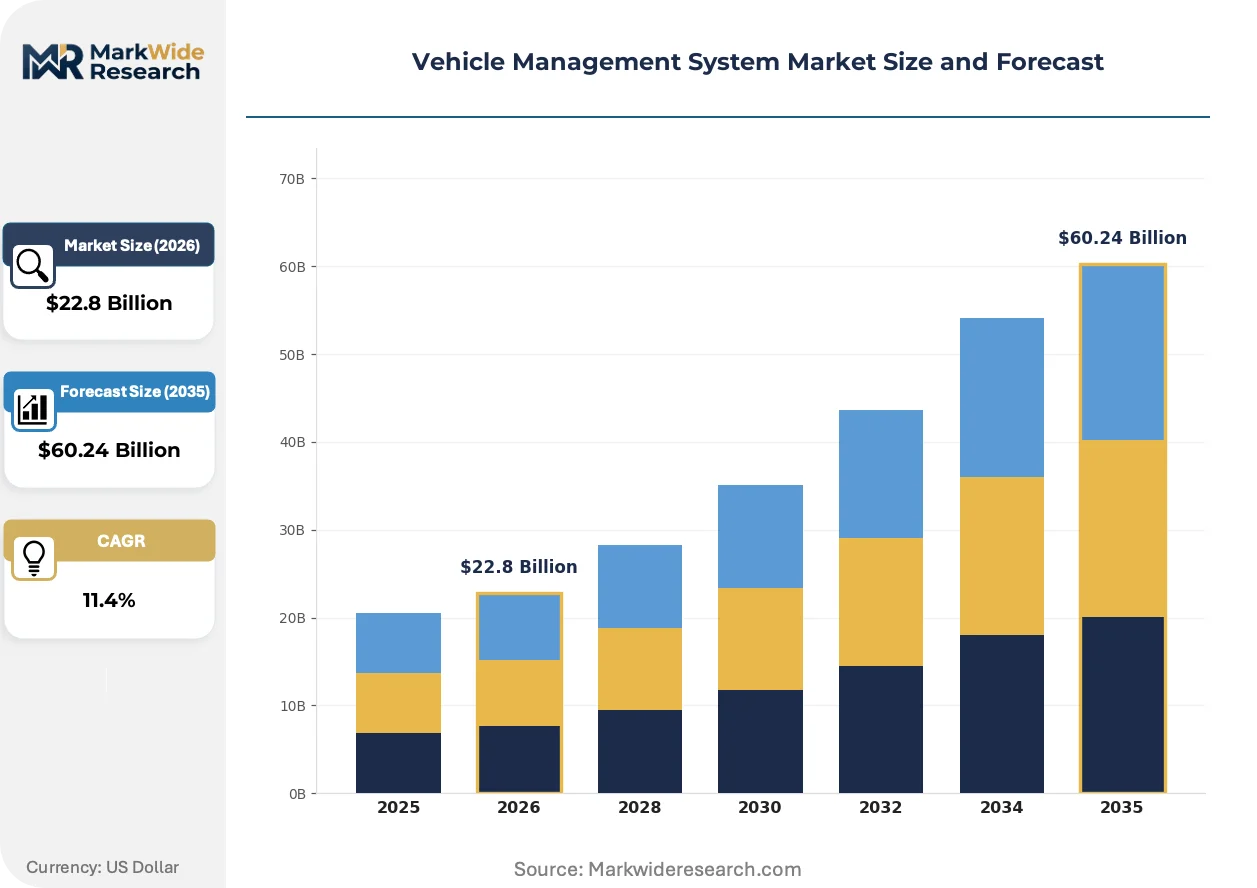
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $60.24 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fleet Management, Telematics, Maintenance Solutions, Driver Management Technology: Cloud-Based, On-Premises, Mobile Applications, Data Analytics End User: Logistics Providers, Car Rental Services, Corporate Fleets, Public Transport Service Type: Consulting, Implementation, Support & Maintenance, Training |
| Companies Covered | Verizon Connect, Geotab, Samsara, Lytx, Teletrac Navman, Azuga, Bosch Automotive Service Solutions, Mobileye, Trimble, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Management System Market Trends and Innovations
Edge computing architectures are redistributing data processing from centralized cloud servers to vehicle-mounted gateways, reducing latency for safety-critical alerts while compressing cellular data transmission costs.
Artificial intelligence inference engines deployed on in-cabin edge processors are automating real-time detection of driver fatigue, distracted behavior, and collision risks without requiring continuous cloud connectivity. Long-haul trucking fleets in the United States are piloting these systems to satisfy insurance carrier requirements and FMCSA safety scoring protocols. The technology is automating incident documentation that previously required manual supervisor review of video footage.
The European Union's CSRD disclosure rules are mandating granular emissions reporting from corporate vehicle fleets, compelling telematics platforms to integrate fuel consumption sensors with automated sustainability audit trails. Logistics operators must now reconcile Scope 1 emissions data across mixed diesel, electric, and alternative-fuel vehicle populations. Heavy-duty freight carriers operating across Germany, France, and the Netherlands face the most compressed compliance timelines.
Subscription-based procurement models are displacing perpetual license purchases among mid-sized fleet operators seeking to convert capital expenditures into predictable operational costs. Third-party fleet management service providers are capturing maintenance and compliance workflows that owner-operators previously managed internally. This shift is most pronounced in United States regional trucking markets where driver shortage pressures force smaller fleets to outsource administrative functions.
Vehicle Management System Market Segmentation
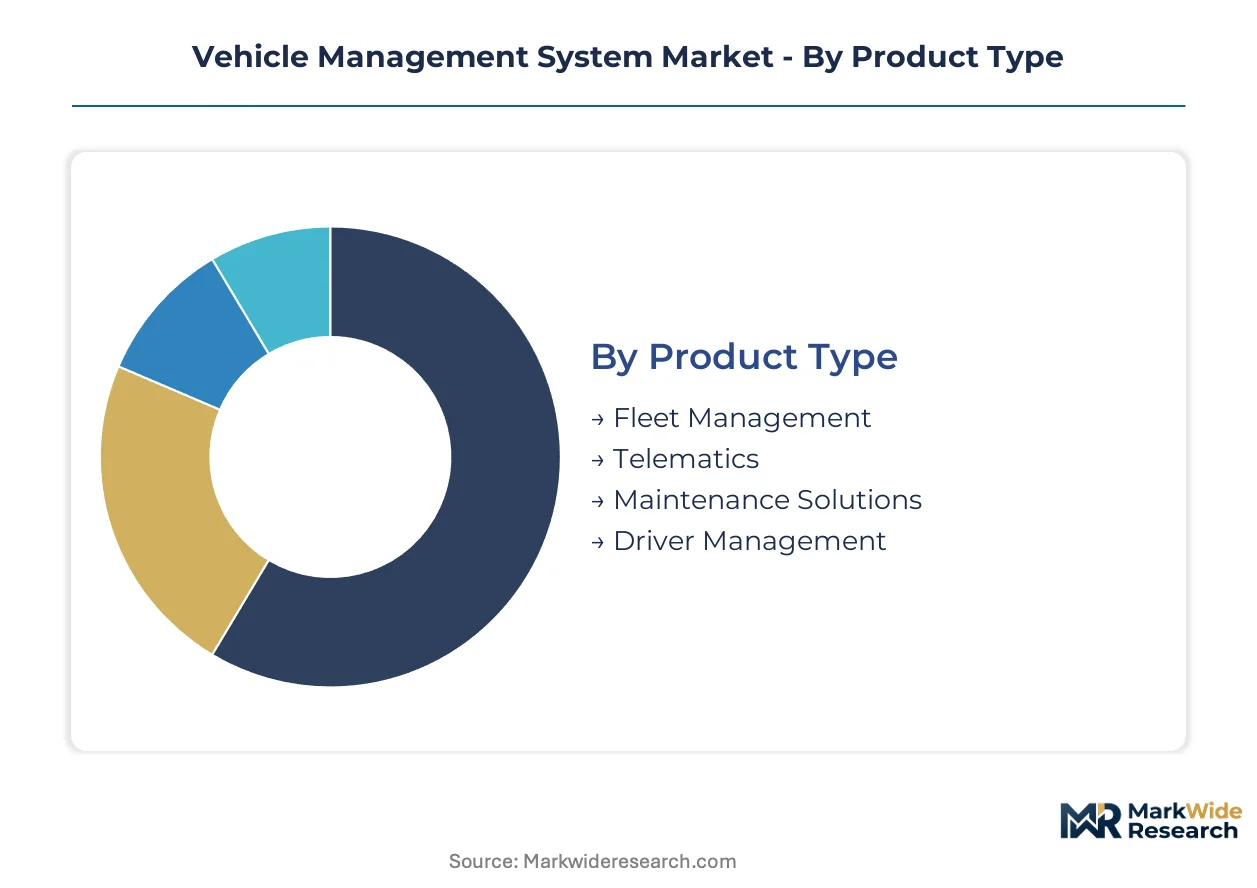
Vehicle management system vendors structure product portfolios around distinct operational workflows, technology delivery modes, and buyer sophistication levels. Segmentation reveals where subscription revenue concentrates versus one-time hardware sales, and which buyer categories drive platform consolidation.
Product Type:
Supply concentration in fleet management software has shifted toward integrated suites that bundle telematics, compliance, and maintenance modules under single vendor relationships.
- Fleet Management:Unified platforms combining GPS tracking, fuel monitoring, route optimization, and regulatory compliance dashboards. Demand concentrates among United States trucking fleets facing FMCSA hours-of-service enforcement and insurance carrier safety scoring requirements.
- Telematics:Hardware-software systems capturing vehicle location, engine diagnostics, and driver behavior through cellular-connected onboard units. German logistics operators deploy these for real-time cold-chain monitoring under EU Green Deal emissions reporting mandates.
- Maintenance Solutions:Predictive algorithms processing engine fault codes and mileage data to schedule service intervals.
- Driver Management:Performance scoring tools linking telematics data to training programs and retention incentives.
Today's leader: Fleet Management. Tomorrow's challenger: Maintenance Solutions.
Technology:
Deployment architecture determines capital expenditure profiles and scalability ceilings for fleet operators across different size tiers.
- Cloud-Based:Multi-tenant SaaS platforms delivering real-time dashboards through web browsers and mobile applications. Mid-sized United States regional trucking fleets favor this model to avoid server infrastructure investments while scaling vehicle counts seasonally.
- On-Premises:Licensed software installed on customer-managed servers with dedicated database instances. Large German automotive manufacturer fleets retain these deployments for data sovereignty and integration with existing ERP systems.
- Mobile Applications:Native iOS and Android tools extending core platform functionality to field supervisors and drivers.
- Data Analytics:Machine learning modules processing aggregated fleet telemetry to generate predictive maintenance alerts and fuel efficiency recommendations.
Cloud-Based commands current procurement volumes. Data Analytics is climbing the fastest as operators shift from storage to predictive decision engines.
End User:
Buyer category dictates feature prioritization, with logistics providers demanding route optimization while corporate fleets emphasize driver safety and sustainability reporting.
- Logistics Providers:Third-party trucking and delivery companies managing dispersed vehicle assets across multiple shipper contracts. China e-commerce fulfillment networks represent the steepest expansion trajectory for real-time visibility platforms supporting same-day delivery SLAs.
- Car Rental Services:Fleet operators tracking vehicle location, utilization rates, and maintenance status across distributed pickup locations.
- Corporate Fleets:Company-owned vehicle pools serving sales, service, and executive transportation needs.
- Public Transport:Municipal bus and rail operators monitoring schedule adherence, passenger loads, and asset condition.
Logistics Providers anchor platform revenue. Corporate Fleets are gaining share fastest through CSRD-mandated emissions disclosure requirements.
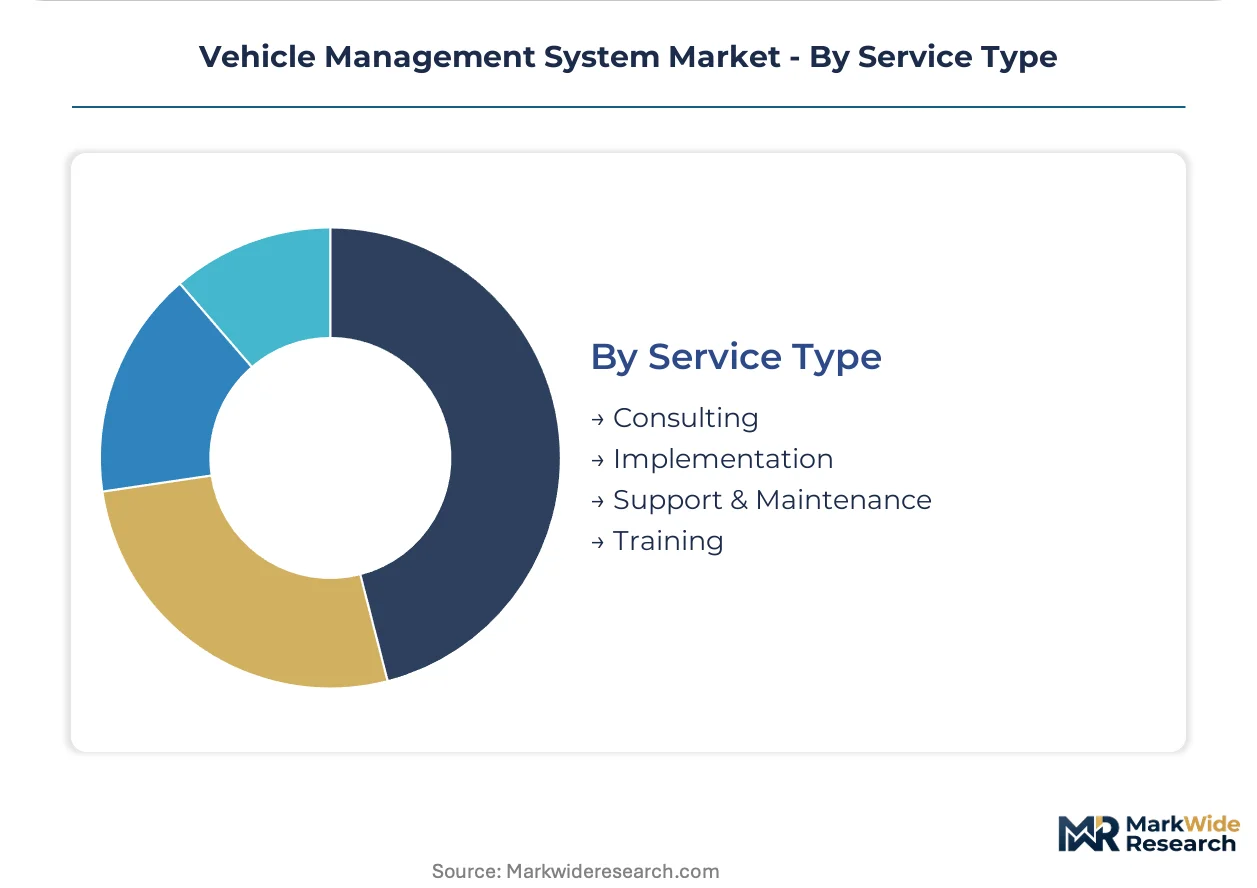
Service Type:
Professional services attach rates vary by buyer digital maturity, with complex implementations commanding multi-year consulting engagements.
- Consulting:Fleet optimization assessments, regulatory compliance roadmaps, and technology selection advisory. United States owner-operator trucking businesses purchase these services to navigate ELD mandate complexity without dedicated IT staff.
- Implementation:System configuration, data migration, and integration with existing dispatch and accounting software.
- Support & Maintenance:Technical helpdesk services, software updates, and hardware warranty management.
- Training:Administrator certification programs and end-user onboarding for drivers and fleet managers.
Support & Maintenance generates recurring revenue stability. Consulting is expanding most quickly as regulatory complexity outpaces in-house fleet expertise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States deploy vehicle management systems at comparable fleet penetration rates, yet regulatory pressure in Europe is compressing compliance timelines faster than North American mandates. China e-commerce fulfillment networks are scaling real-time visibility platforms at the steepest velocity globally. India commercial vehicle digitization is accelerating through targeted government production incentives.
United States
FMCSA hours-of-service enforcement and insurance carrier safety scoring requirements drive fleet management platform procurement among long-haul trucking operators. NHTSA electronic logging device mandates eliminated paper logbook alternatives, forcing hardware refresh cycles across owner-operator and enterprise fleets alike. Dallas-Fort Worth logistics corridors concentrate telematics provider deployment activity supporting cross-border freight flows.
Germany
EU Green Deal emissions disclosure rules and F-Gas Regulation compliance deadlines propel connected cold-chain monitoring adoption among refrigerated transport operators. KBA vehicle type approval processes shape telematics hardware certification requirements for aftermarket installation. Ruhr Valley industrial logistics clusters anchor predictive maintenance solution deployments across mixed diesel and electric vehicle populations.
China
E-commerce same-day delivery service-level agreements mandate real-time route optimization and driver behavior monitoring across last-mile fulfillment networks. MIIT connected vehicle standards and dual carbon goals accelerate telematics integration into commercial vehicle manufacturing specifications. Yangtze River Delta logistics hubs concentrate fleet platform deployment supporting pharmaceutical and fresh food cold-chain distribution.
India
PLI scheme incentives for automotive electronics production lower hardware cost barriers for mid-sized logistics operators digitizing dispersed commercial vehicle assets. DGFT import substitution policies favor domestic telematics module assembly over fully imported systems. Maharashtra national highway freight corridors create concentrated demand for cloud-native fleet management platforms targeting regional trucking consolidation.
Vehicle Management System Market Competitive Landscape
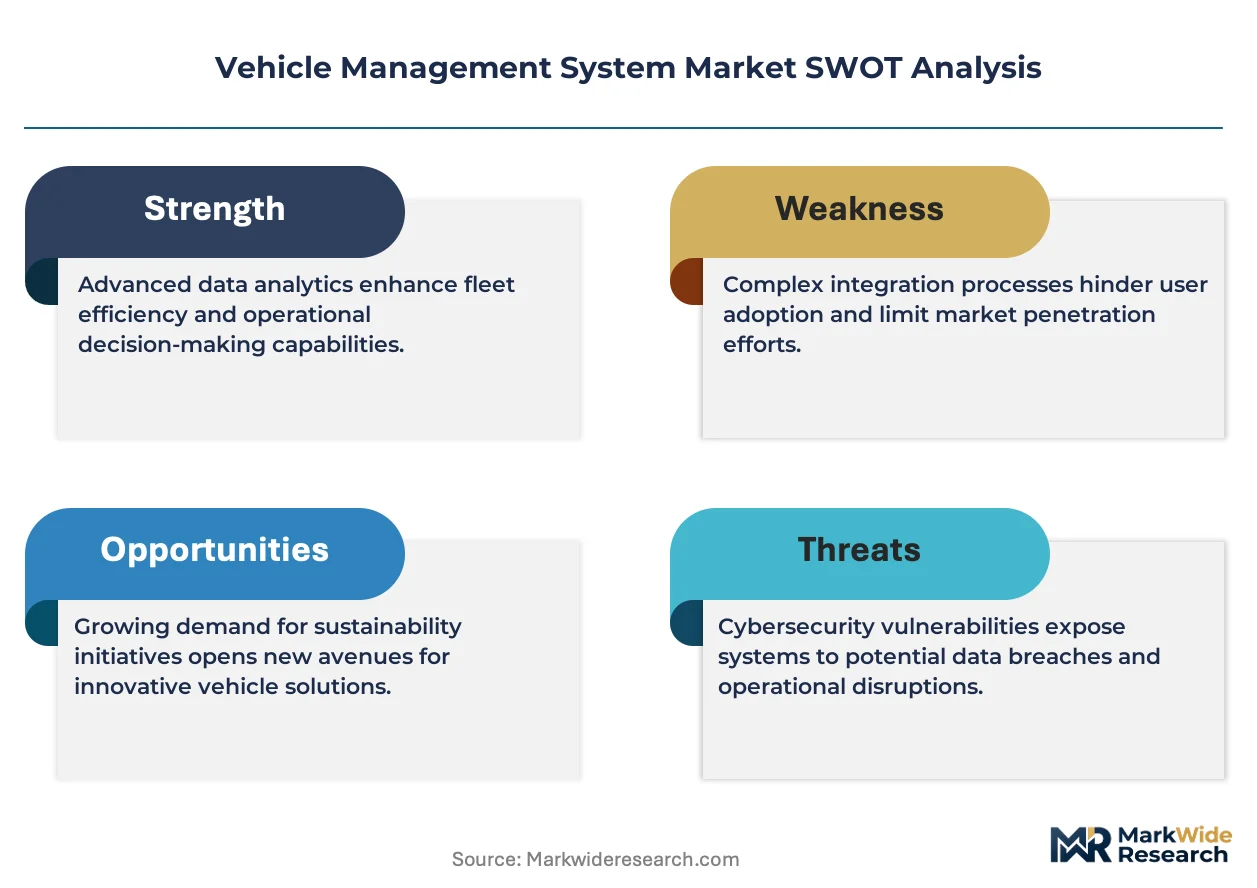
Top-tier vendors anchor enterprise fleet deployments through bundled connectivity and professional services, while mid-market specialists compete on subscription pricing and faster implementation cycles. The vendor base stratifies across three strategic archetypes: open-platform ecosystem orchestrators, cloud-native integrated suite providers, and connectivity-anchored telecom incumbents. Dominant competitive moves include strategic partnerships with third-party developers and portfolio diversification into video telematics and AI-powered driver safety modules.
Among North American platform providers, Verizon Connect, Geotab, and Samsara occupy distinct positioning within the competitive structure. Verizon Connect represents the connectivity-anchored archetype through bundled telecommunication services. Geotab exemplifies open-platform ecosystem strategy with third-party developer relationships. Samsara sits within the cloud-native integrated suite tier, converging video telematics with IoT sensor fusion capabilities.
| Leading Market Players |
|---|
| Verizon Connect |
| Geotab |
| Samsara |
| Lytx |
| Teletrac Navman |
| Azuga |
| Bosch Automotive Service Solutions |
| Mobileye |
| Trimble |
| Others |
Pricing and Supply Chain Analysis
Edge computing migration to vehicle-mounted gateways is compressing hardware bill-of-materials costs while concentrating procurement leverage among semiconductor foundries serving cellular modem and GPS module suppliers. This dual shift simultaneously lowers entry barriers for cloud-native platform providers and amplifies cost volatility for legacy telematics hardware vendors tethered to concentrated Asian component sourcing.
Pricing Analysis
Capacity additions in Vietnam and India are reshaping price floors for cellular modem assembly, forcing incumbent telematics hardware vendors toward subscription-tiered SaaS pricing to preserve margins. Pricing stratifies across premium enterprise suites with bundled professional services, standard mid-market cloud deployments, and economy self-service tiers for small fleets. Cost compression in hardware modules is intensifying because domestic assembly incentives under India's PLI scheme are displacing fully imported systems. Small owner-operator trucking businesses in the United States exhibit the highest price sensitivity, while German refrigerated transport operators show the least due to F-Gas Regulation compliance deadlines.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Ho Chi Minh City, and Dallas-Fort Worth anchor hub-and-spoke fulfillment patterns for telematics hardware, with final configuration occurring near logistics corridor demand clusters. Manufacturing concentrates in China, Vietnam, and Taiwan for GPS modules, cellular modems, and edge processors. Component sourcing draws from concentrated semiconductor foundries, lithium-ion battery cell producers, and precision antenna suppliers. Single-source vulnerability in advanced node chip fabrication poses structural risk to hardware delivery timelines. Distribution runs through direct OEM partnerships, aftermarket installer networks, and third-party fleet management service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vehicle management system market functions as a stable compounder, with regulatory mandates for electronic logging and emissions disclosure generating replacement-driven revenue visibility regardless of macroeconomic cycles.
For Market Incumbents: Deploy API standardization investments to lock in ecosystem partnerships before multi-protocol integration complexity fragments platform architectures. Consolidate around video telematics capabilities to defend against cloud-native entrants attacking the insurance-linked safety scoring segment. Vertical integration into edge processor design mitigates semiconductor supply concentration exposure. For New Entrants and Emerging Players: Small regional trucking fleets in India represent the most penetrable buyer archetype, with PLI-scheme hardware cost reductions and national highway freight corridor expansion creating favorable entry conditions. Target mid-sized logistics operators seeking to outsource compliance workflows without dedicated IT staff. Pursue white-label partnerships with domestic telematics assemblers to bypass import substitution barriers. For Investors and Strategic Acquirers: Roll-up economics work for specialized predictive maintenance algorithm developers because fleet operator procurement is shifting from raw telemetry storage to decision-engine subscriptions, creating valuation arbitrage between data analytics revenue multiples and legacy hardware trading multiples. Acquisition candidates include cold-chain monitoring specialists with EU Green Deal regulatory workflows. Watch for FMCSA enforcement intensity as the inflection signal for United States hardware refresh cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies OEM telematics, aftermarket sensors, and third-party logistics software through standardized APIs. |
| Strategic Partnership | Links AI-powered dashcam deployments with insurance underwriters pricing premiums on verified driver behavior data. |
| Product Launch | Introduces edge computing gateways reducing latency for safety-critical alerts while compressing cellular transmission costs. |
| Acquisition of Specialist Firm | Captures predictive maintenance algorithm teams processing engine fault codes for refrigerated transport operators. |
| Geographic Expansion | Establishes cloud-native deployments across Maharashtra freight corridors targeting regional trucking consolidation. |
Research Methodology
Coverage spans the United States, Germany, China, and India, with primary inputs from each market cluster combining executive interviews with fleet operators, telematics platform engineers, and automotive electronics procurement leads with secondary validation. Primary sources include CTOs at logistics providers, OEM platform integration specialists, and aftermarket installer network managers. Secondary data draws from NHTSA regulatory filings, FMCSA compliance databases, EU CSRD disclosure frameworks, and MIIT connected vehicle standards documentation. Bottom-up vehicle count projections and top-down fleet expenditure surveys undergo cross-triangulation to reconcile segmentation outputs.
Rate-of-change decomposition separates hardware unit growth from subscription revenue expansion across the analysis window. Segmentation dimensions modeled include deployment architecture, fleet size tier, vehicle class, and regulatory compliance intensity. CAGRs derive from fitted growth curves applied to telematics hardware shipments and SaaS subscription attach rates. Industry-specific forecast inputs incorporate FMCSA enforcement timelines, EU F-Gas Regulation phase-out schedules, and India PLI scheme incentive trajectories.
Underlying measurement precision varies by segment; cloud-based deployment and logistics provider end-use carry tighter precision than on-premises installations and small owner-operator categories. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and semiconductor supply normalization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Egypt Ride Hailing Service Market
Transportation Services
ASEAN Taxi Market
Transportation Services
India Taxi Market
Transportation Services
Vacuum Truck Rentals Market
Transportation Services
Peer-To-Peer (P2P) Car-Sharing Market
Transportation Services
Ship Management Software Market
Transportation Services
Corporate Employee Transportation Service Market
Transportation Services
Indonesia Car Rental Market
Transportation Services
Online Bus Ticketing Service Market
Transportation Services
Airline Passenger Service System Market
Transportation Services
Water Truck Rental Market
Transportation Services
MUV Rental Market
Transportation Services
Taxi and Ride-Hailing Services Market
Transportation Services
United Kingdom Car Rental Market
Transportation Services
ASEAN Car Rental Market
Transportation Services
Car Rental Service Market