
 Global Automotive Components Forging Market | 2026-2036
Global Automotive Components Forging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Components Forging Market Analysis
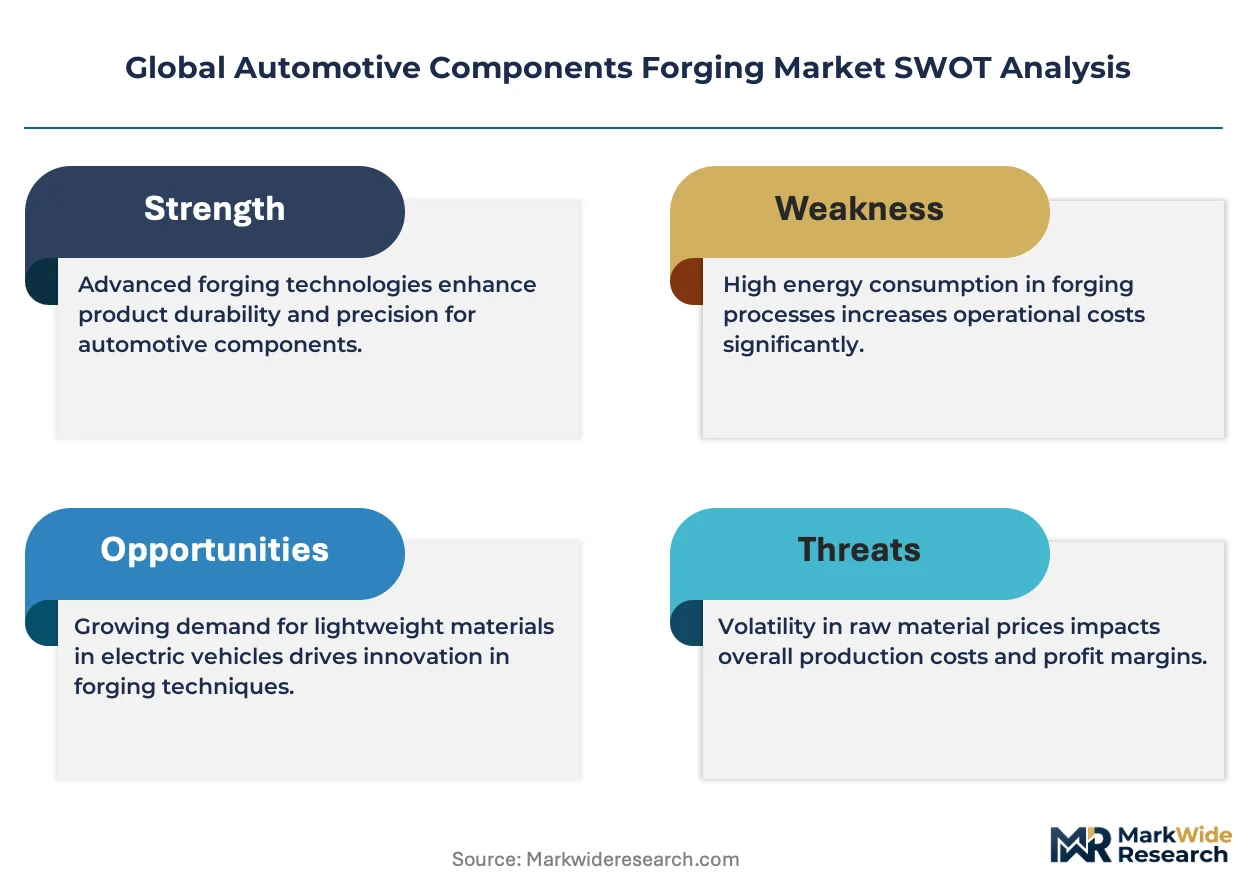
Aluminum is repositioning traditional steel in automotive forging as OEMs pursue mass reduction for battery-electric platforms. Bharat Forge Ltd. leverages its vertical integration across crankshaft and connecting rod production to sustain cost leadership in powertrain forgings. ThyssenKrupp Forged Technologies anchors European supply through specialized closed-die capabilities for high-strength chassis applications.
Automotive components forging encompasses the plastic deformation of metals under compressive force to produce high-strength parts with controlled grain flow, typically achieving tensile strengths exceeding 1,000 MPa in alloy steels. The process serves critical load-bearing functions in vehicles where fatigue resistance and impact absorption determine safety performance. Forged steel continues to dominate engine component and drivetrain applications where thermal and mechanical stress peaks, while forged aluminum captures expanding share in chassis and suspension systems as weight reduction intensifies. Cold forging registers the fastest trajectory among manufacturing stages, driven by near-net-shape precision that minimizes machining waste and energy input relative to hot forging cycles.
The EPA enforces fleet-wide emissions benchmarks that compel OEMs to specify lighter forged materials, while the EU Green Deal's carbon border adjustments threaten non-compliant imports from carbon-intensive forging operations. China's MIIT mandates domestic content ratios for NEV supply chains, redirecting forging investment toward local aluminum and titanium capabilities. Stakeholders must monitor how divergent carbon-accounting rules across Washington, Brussels, and Beijing fragment material certification requirements and reshape supplier qualification timelines.
Market Dynamics
Material substitution pressure from battery-electric vehicle platforms is compressing traditional steel forging volumes while expanding aluminum and titanium capacity requirements across supplier networks. This structural force is reallocating capital from powertrain-dominant facilities toward chassis and structural component specialization.
Growth Catalysts
- EPA Fleet Emissions Benchmarks:United States Corporate Average Fuel Economy standards mandate progressive mass reduction, compelling OEM specifications for lightweight forged aluminum in suspension and structural components.
- Closed-die Precision Advancement:Near-net-shape forming technologies reduce machining waste ratios and energy consumption per unit, improving cost structures for high-volume chassis programs.
- China MIIT Domestic Content Mandates:New energy vehicle supply chain localization requirements redirect forging investment toward captive aluminum and titanium melting capabilities within Chinese industrial clusters.
Market Restraints
- Aluminum Scrap Price Volatility:Primary and secondary aluminum input costs fluctuate with energy pricing and Chinese export policy, compressing margin predictability for independent forgers without backward integration into metal supply.
- Die Development Lead Times:Complex closed-die tooling for chassis components requires 12-18 month design-to-production cycles, creating capacity rigidity against demand spikes.
- Thermal Management Limitations:Forged aluminum tensile strength and fatigue resistance under sustained high-temperature exposure remain inferior to alloy steel, restricting substitution in engine block and turbocharger applications.
Strategic Opportunities
- India PLI Scheme for Auto Components:Production-linked incentive structures for advanced automotive technology manufacturing attract forging capacity expansion for export-oriented chassis component supply.
- Solid-state Battery Enclosure Forging:Next-generation cell architectures require novel aluminum housing geometries with integrated cooling channels, creating first-mover advantage for die-design specialists.
- EU Green Deal Carbon Border Adjustments:Compliance premiums on carbon-intensive imports from non-EU forging operations create pricing umbrella for European producers with renewable energy-integrated melting operations.
Industry Challenges
- Multi-material Welding Certification:Dissimilar metal joining between forged aluminum chassis members and steel body structures requires new technician qualifications and inspection protocols that extend supplier qualification timelines.
- Press Retrofit Capital Intensity:Existing mechanical forging presses lack force distribution precision for complex aluminum die geometries, requiring substantial reinvestment in servo-hydraulic systems or greenfield capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Components Forging Market |
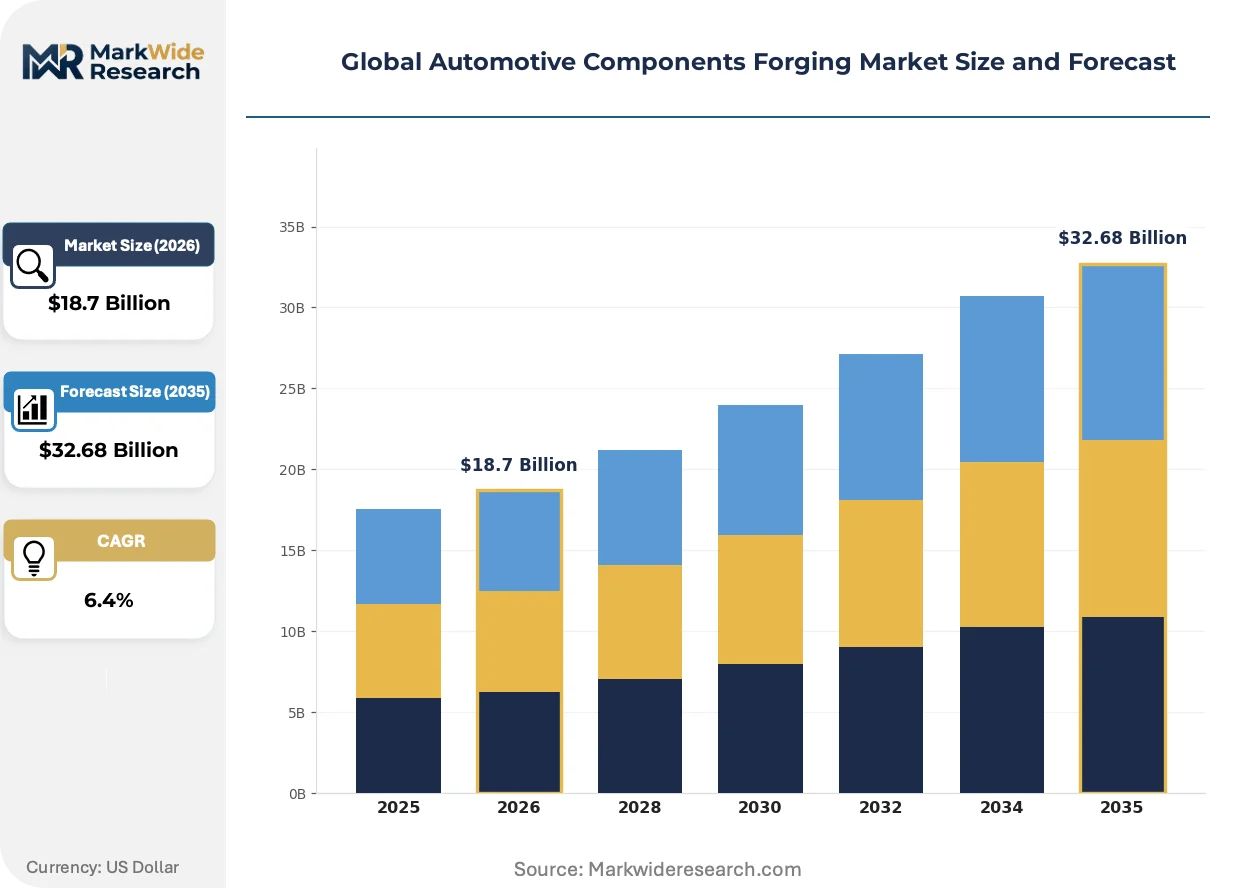
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forged Steel, Forged Aluminum, Forged Iron, Forged Titanium Application: Engine Components, Transmission Parts, Chassis, Drivetrain Customer Type: OEMs, Tier-1 Suppliers, Aftermarket Providers, Dealerships Manufacturing Stage: Hot Forging, Cold Forging, Open Die Forging, Closed Die Forging |
| Companies Covered | American Axle & Manufacturing, Ellwood Group, Bharat Forge Ltd., China First Heavy Industries, Precision Castparts Corp., ThyssenKrupp Forged Technologies, Scot Forge, Japan Casting & Forging Corporation, Aichi Forge USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Components Forging Market Emerging Trajectories
Process digitization and material science convergence are redefining forging economics. Real-time thermal monitoring, predictive die-wear algorithms, and alloy formulation advances are compressing development cycles while expanding performance envelopes for safety-critical automotive applications.
Isothermal forging of aluminum-lithium alloys is electrifying structural component possibilities for electric vehicle platforms. BMW and Tesla procurement teams specify these materials for battery tray rails and crash management systems. The technology is electrifying supplier qualification requirements as traditional steel forgers retool metallurgical expertise.
REACH substance restrictions on hexavalent chromium conversion coatings are forcing conversion to trivalent chrome and zirconium-based surface treatments across European forging supply chains. Surface finishing suppliers face reformulation investments. German and Czech forging clusters absorb the highest compliance costs while accelerating qualification of alternative passivation chemistries.
Consolidated OEM direct-sourcing programs are compressing tier structures in chassis component procurement. Tier-1 module suppliers increasingly specify forgings directly rather than through historical distributor channels. This pattern concentrates most visibly in North American electric vehicle supply chains where Rivian and Lucid bypass traditional forging distributors for aluminum control arm and knuckle contracts.
Global Automotive Components Forging Market Segmentation
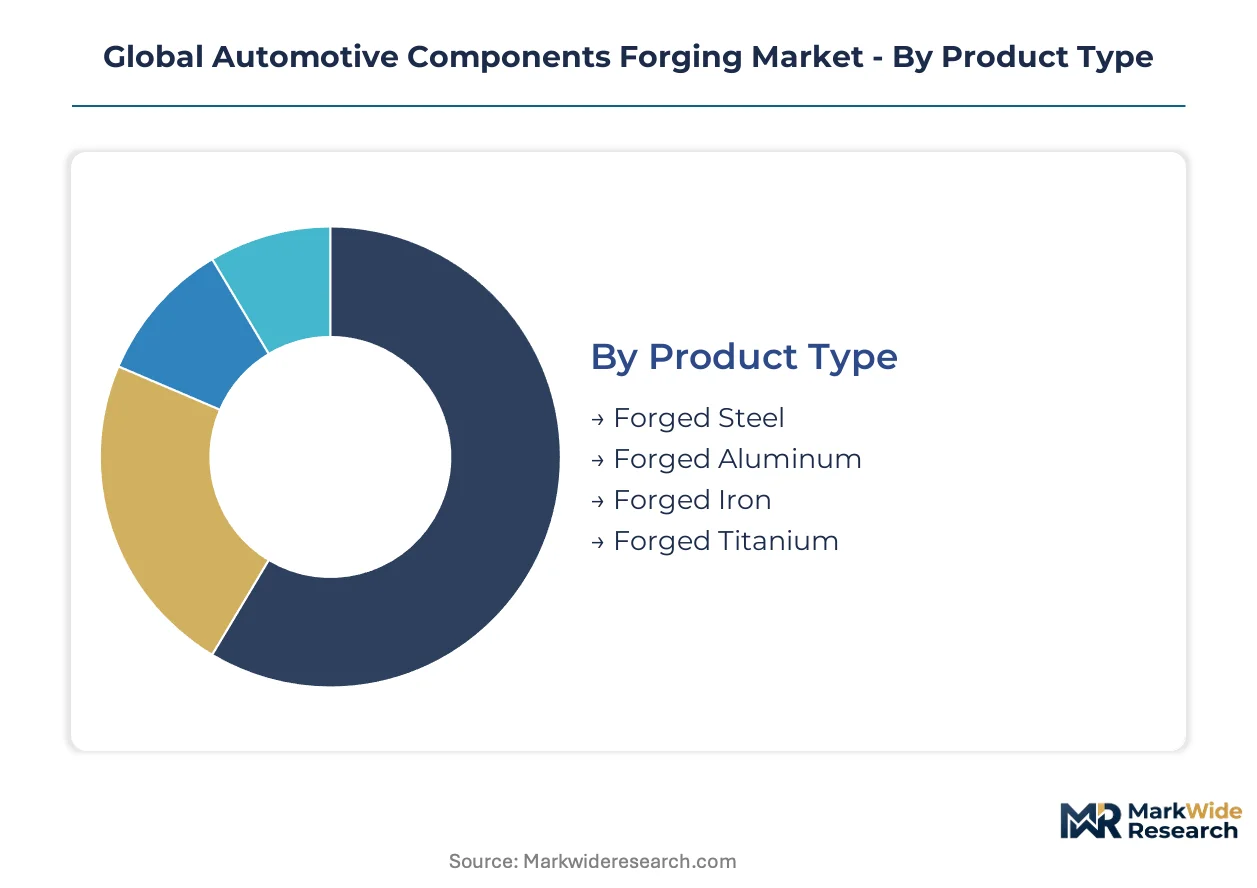
Material substitution dynamics and manufacturing precision requirements create divergent value pools across automotive forging segments. Procurement specifications from electric vehicle programs are fragmenting traditional segment boundaries as chassis and powertrain demands decouple.
Product Type:
Cost tier positioning determines supplier qualification pathways, with premium alloys commanding dedicated melting capacity investments.
- Forged Steel:Alloy formulations achieve tensile strengths exceeding 1,000 MPa with controlled grain flow for fatigue-critical applications. Demand concentrates in German and Japanese engine component supply chains where thermal stress resistance remains non-negotiable.
- Forged Aluminum:Lithium-aluminum alloys enable 40-50% mass reduction versus steel equivalents for battery-electric chassis structures. Tesla and BMW procurement teams specify these materials for crash management systems and battery tray rails in their United States and European assembly programs.
- Forged Iron:Gray and ductile iron variants serve cost-sensitive suspension brackets and steering knuckles in emerging market vehicle platforms.
- Forged Titanium:Ti-6Al-4V grades command aerospace-derived specifications for high-performance connecting rods and valve train components in limited-production internal combustion engines.
Forged steel leads on scale; forged aluminum leads on momentum.
Application:
Volume concentration follows powertrain architecture shifts, with battery-electric platforms eliminating traditional engine component demand while multiplying structural forging requirements.
- Engine Components:Crankshafts, connecting rods, and camshafts require isotropic mechanical properties achievable only through closed-die forging of microalloyed steels. Bharat Forge Ltd. and ThyssenKrupp Forged Technologies anchor supply for European and Indian OEM powertrain programs.
- Chassis:Control arms, steering knuckles, and subframe nodes demand near-net-shape precision to minimize machining waste in high-volume aluminum programs. Rivian and Lucid direct-sourcing contracts bypass traditional distributor channels for these components in North American electric vehicle supply chains.
- Transmission Parts:Gear blanks and synchronizer hubs maintain steel dominance where torque density requirements resist aluminum substitution.
- Drivetrain:Differential gears and axle shafts balance fatigue resistance with cost constraints across light truck and commercial vehicle segments.
Engine components retain volume leadership; chassis applications are expanding most quickly.
Customer Type:
Margin structure varies with technical integration depth, from specification-heavy OEM relationships to price-elastic aftermarket channels.
- OEMs:Direct forging procurement for electric vehicle platforms emphasizes design-for-manufacturing collaboration and carbon-accounting transparency. Volkswagen Group and General Motors qualification timelines extend 18-24 months for new aluminum die designs.
- Tier-1 Suppliers:Module integrators increasingly specify forgings directly rather than through historical distributor networks, compressing supply chain tiers in chassis component procurement.
- Aftermarket Providers:Independent distributors serve replacement demand for wear items in legacy vehicle populations with limited technical specification requirements.
- Dealerships:Captive parts operations handle warranty-related forging replacements under OEM service contracts.
OEMs dominate absolute value capture; Tier-1 suppliers are gaining specification authority fastest.
Manufacturing Stage:
Energy intensity and capital requirements segment competitive positioning across thermal processing alternatives.
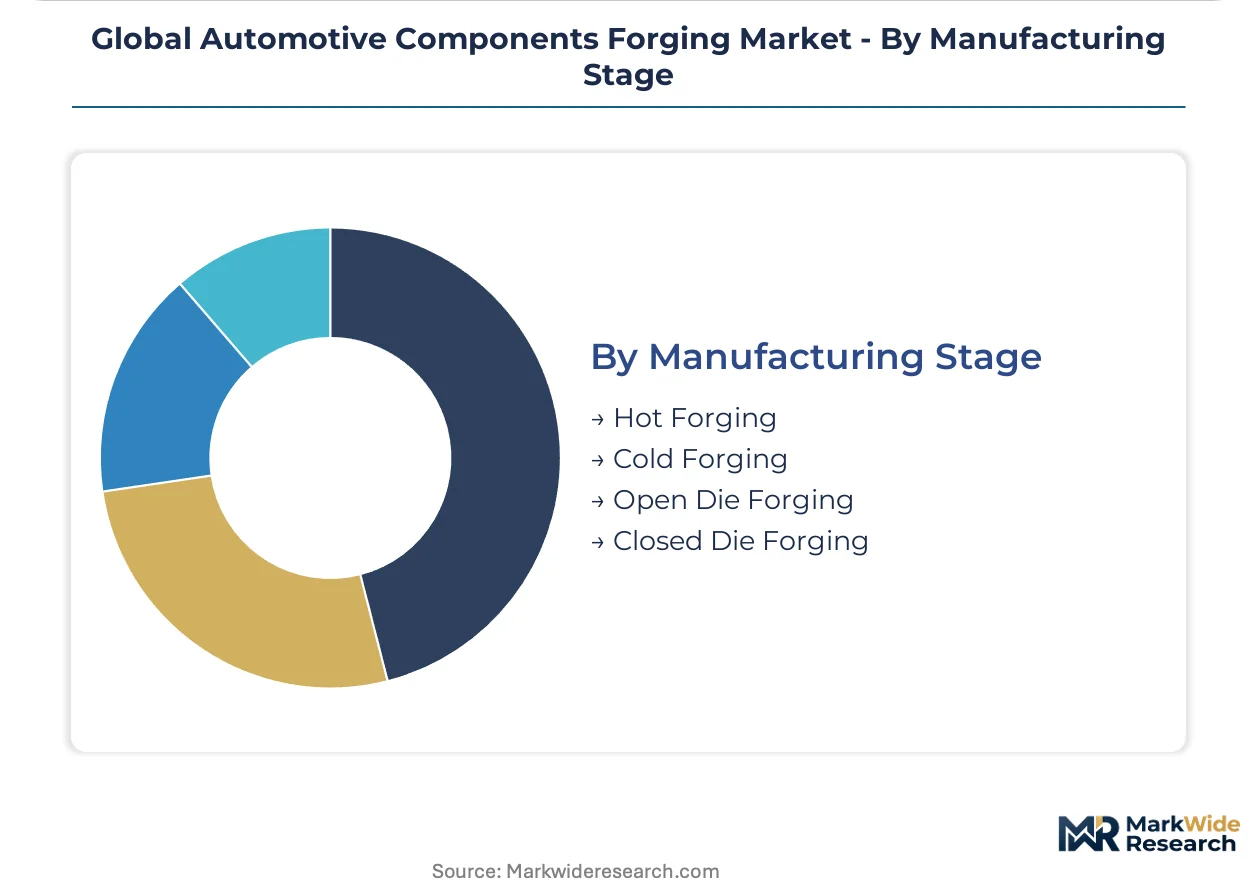
- Cold Forging:Near-net-shape precision at ambient temperatures minimizes machining waste ratios and energy input versus hot forging cycles. German and Czech forging clusters deploy these capabilities for high-volume chassis component programs serving European OEMs.
- Closed Die Forging:Precision cavity tooling produces complex geometries with controlled grain flow for safety-critical applications. Die development lead times of 12-18 months create capacity rigidity against demand spikes in aluminum chassis programs.
- Hot Forging:Elevated-temperature deformation enables large-section reductions for engine crankshafts and connecting rods in alloy steel grades.
- Open Die Forging:Hammers and presses shape ingots without cavity constraints for preform operations and limited-production custom components.
Hot forging retains installed capacity scale; cold forging shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The German automotive forging cluster anchors production gravity for high-strength chassis and powertrain components, with supplier networks concentrated around Stuttgart, Munich, and the Ruhr industrial belt serving BMW, Mercedes-Benz, and Volkswagen Group assembly programs.
United States
Detroit-based OEM procurement teams specify lightweight aluminum forgings for electric vehicle platforms, with Rivian and Lucid direct-sourcing control arms and steering knuckles from domestic suppliers. EPA Corporate Average Fuel Economy standards mandate progressive mass reduction, compelling material transitions in Michigan and Ohio industrial corridors. Cleveland and Pittsburgh forging operations absorb capital reinvestment for servo-hydraulic press upgrades serving North American EV supply chains.
Germany
Stuttgart and Munich industrial zones concentrate closed-die forging capacity for high-strength steel crankshafts and aluminum-lithium chassis structures. EU Green Deal carbon border adjustments threaten imports from carbon-intensive operations, redirecting qualification timelines toward renewable energy-integrated melting facilities. ThyssenKrupp Forged Technologies anchors European supply through specialized capabilities serving BMW and Porsche performance programs.
China
MIIT domestic content mandates for new energy vehicle supply chains redirect forging investment toward captive aluminum and titanium melting capabilities. Shanghai and Yangtze River Delta industrial clusters absorb the majority of greenfield capacity additions for battery tray rail and crash management system forgings. China First Heavy Industries exemplifies state-directed consolidation in heavy forging equipment serving domestic OEM localization requirements.
India
Pune and Chennai industrial corridors leverage production-linked incentive schemes for advanced automotive component manufacturing, attracting export-oriented chassis forging capacity. Bharat Forge Ltd. maintains cost leadership in powertrain forgings through backward integration into crankshaft and connecting rod production. Government PLI structures accelerate qualification timelines for European and North American OEM supplier audits.
Japan
Nagoya and Osaka industrial zones preserve precision forging expertise for hybrid powertrain components and limited-production titanium valve train applications. METI industrial policy supports alloy formulation advances for next-generation thermal management systems. Japan Casting & Forging Corporation occupies a position within the specialist tier serving Toyota and Honda residual internal combustion engine programs.
Global Automotive Components Forging Market Vendor Landscape
Global majors compete with regional champions across material specialization and die-design complexity. The supplier base organizes into three tiers: integrated steel-aluminum dual-capability operators, pure-play aluminum chassis specialists, and legacy powertrain-dominant forgers retooling for electric platforms. Consolidated OEM direct-sourcing programs compress historical distributor channels, concentrating specification authority with Tier-1 module integrators. Dominant competitive moves include captive aluminum melting investments and servo-hydraulic press retrofits for complex die geometries.
Among German-based fabricators, ThyssenKrupp Forged Technologies exemplifies the integrated industrial conglomerate archetype with diversified material capabilities. Bharat Forge Ltd. represents the emerging-market scale champion with demonstrated cost discipline in powertrain applications. American Axle & Manufacturing occupies a position within the North American Tier-1 supplier tier, anchoring regional procurement relationships with Detroit OEMs. These three entities illustrate divergent strategic postures across geographic and capability dimensions.
| Leading Market Players |
|---|
| American Axle & Manufacturing |
| Ellwood Group |
| Bharat Forge Ltd. |
| China First Heavy Industries |
| Precision Castparts Corp. |
| ThyssenKrupp Forged Technologies |
| Scot Forge |
| Japan Casting & Forging Corporation |
| Aichi Forge USA |
| Others |
Supply Flow & Price Mechanics
Tool-and-die engineering talent concentration in Stuttgart and Shanghai industrial clusters anchors labor-cost differentials that widen pricing-tier spreads between European precision-forged chassis components and Chinese volume-production alternatives. These geographic skill premiums interact with EPA fleet-emissions compliance costs and MIIT localization mandates to stratify procurement economics across OEM supplier networks.
Pricing Analysis
Input-cost pass-through from aluminum scrap and primary metal markets drives contract renegotiation cycles for independent forgers lacking captive melting capacity. Pricing stratifies across premium, standard, and economy tiers based on ISO 14001 carbon-accounting certification levels and volume-scale commitments. Cost compression in standard-grade aluminum chassis forgings is intensifying because Chinese state-subsidized capacity expansion floods export markets. Aftermarket distributors exhibit highest price sensitivity due to inventory holding constraints, while OEM direct-sourcing teams prioritize carbon-transparency premiums over unit cost.
Supply Chain Analysis
Certification and qualification gating through 18-24 month OEM die-design approval timelines concentrates supply relationships with incumbent forgers possessing established IATF 16949 track records. Geographic supply concentration centers on Germany, China, and the United States for closed-die chassis and powertrain forging capacity. Raw material dependencies draw from primary aluminum smelters in China and Russia, alloy steel producers in Japan and South Korea, and titanium sponge suppliers in Japan and Kazakhstan. Single-source vulnerability around specialized servo-hydraulic press equipment creates capacity rigidity against demand spikes. Distribution runs through Tier-1 module integrators increasingly bypassing historical forging distributor channels in North American electric vehicle supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where European carbon-border compliance premiums under EU Green Deal regulations create pricing umbrellas for renewable-energy-integrated forgers against carbon-intensive Chinese import competition.
For Market Incumbents: Deepen backward integration into captive aluminum melting to offset scrap-price volatility compressing margin predictability. Secure servo-hydraulic press capacity additions in Michigan and Ohio industrial corridors to defend position against emerging Chinese state-subsidized competitors targeting North American EV supply chains. Prioritize IATF 16949 certification maintenance to sustain OEM qualification timelines against new entrant disruption. For New Entrants and Emerging Players: Begin with solid-state battery enclosure forging for aluminum-lithium alloy housing geometries where die-design specialization creates first-mover advantage before incumbent retooling completes. Target India's PLI scheme corridors around Pune and Chennai for export-oriented chassis component capacity where government incentive structures accelerate European and North American OEM supplier audits. Deploy direct-sourcing relationships with Rivian-class electric vehicle OEMs bypassing traditional distributor channels. For Investors and Strategic Acquirers: Tier-1 automotive module integrators are the most active acquirer in this space as consolidated OEM procurement programs compress supply chain tiers. Long-term viability over the next decade hinges on aluminum-lithium alloy formulation capabilities and renewable-energy-integrated melting assets. Monitor EPA Corporate Average Fuel Economy standard stringency revisions as the critical inflection signal for lightweight forging demand acceleration versus steel retention in hybrid powertrain applications.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Hydraulic Press Retrofit | Enables complex aluminum die geometries required by BMW and Tesla battery tray specifications. |
| Captive Aluminum Melting Investment | Insulates Bharat Forge-class operators from LME scrap volatility threatening independent forgers. |
| Carbon-Border Compliance Certification | Secures EU Green Deal pricing umbrella against carbon-intensive Chinese import competition. |
| Solid-State Battery Enclosure Die Development | Creates first-mover positioning for integrated cooling channel geometries in next-generation cell architectures. |
| India PLI Corridor Capacity Buildout | Captures government incentive structures accelerating European and North American OEM supplier qualification timelines. |
Methodological Framework
Bottom-up automotive platform modeling reconciled against top-down forging capacity tracking forms the analytical core of this study. Primary interviews with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and servo-hydraulic press manufacturers combined with secondary validation from vehicle production databases, IHS Markit registration data, EPA emissions compliance filings, and MIIT NEV supply chain disclosures. This dual-layer approach triangulates demand signals against confirmed capacity investments across German, Chinese, and North American industrial clusters.
Historical trendline analysis of material substitution patterns from steel to aluminum forgings informed projection framework construction across the analysis window. Segmentation dimensions modeled include propulsion architecture, vehicle class, content per vehicle, and regional production cluster. CAGRs derive from regression analysis of OEM procurement specification trajectories and forging press order backlogs. Industry-specific forecast inputs incorporate EPA fleet-emissions benchmark stringency scenarios and MIIT domestic content mandate enforcement timelines.
Several conditions sit outside the modeled scope, including unannounced trade policy shifts affecting aluminum scrap flows, breakthrough solid-state battery commercialization timelines, and sovereign subsidy program modifications. Forecasts reflect documented assumptions regarding OEM platform rollout schedules and forging equipment delivery lead times. A model refresh is warranted upon material change in EPA Corporate Average Fuel Economy standard enforcement or EU Green Deal carbon-border adjustment implementation scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
North America Automotive Hydraulic Actuators Market
Automotive Components
Europe Automotive Bearing Market
Automotive Components
Automotive Key Market
Automotive Components
Asia-Pacific Automotive Upholstery Market
Automotive Components
Global Automotive Selector Lever Market
Automotive Components
India Automotive Heat Exchanger Market
Automotive Components
Europe Automotive Heat Exchanger Market
Automotive Components
Automotive Refrigerant Market
Automotive Components
GCC Automotive Lubrication Services Market
Automotive Components
Automotive Smart Actuator Market
Automotive Components
Automotive Distributor Market
Automotive Components
Automotive Polymer Composites Market
Automotive Components
Automotive Stabilizer Bar Link Market
Automotive Components
Automotive Bushing Technologies Market
Automotive Components
Sheet Molding Compound (SMC) for Automotive Market
Automotive Components
Electric Vehicle Fluid Lubricants Market