
 Europe Automotive Bearing Market | 2026-2036
Europe Automotive Bearing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Bearing Market Foresight
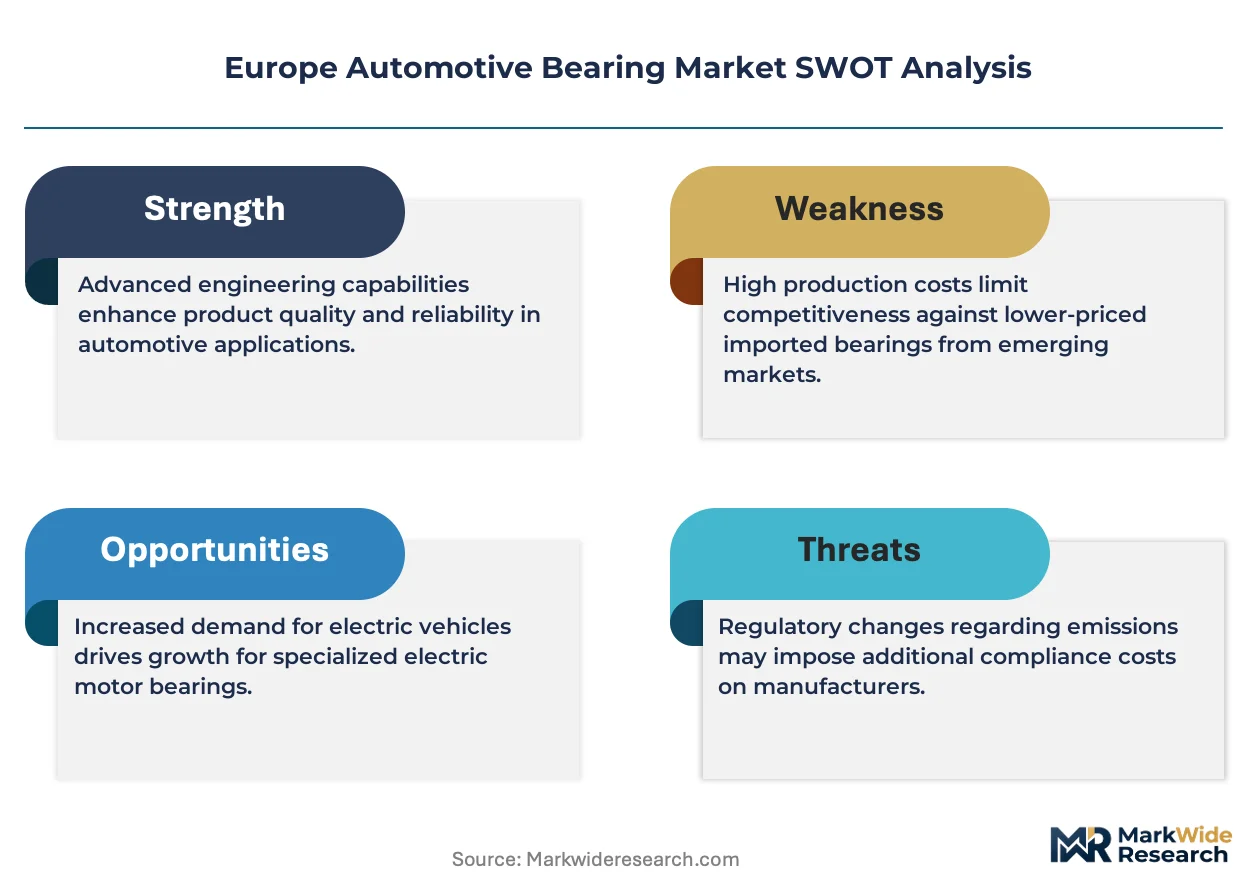
Aftermarket service revenue is tilting toward bearing refurbishment and predictive maintenance contracts as OEMs extend vehicle lifecycles. Schaeffler AG leverages its integrated manufacturing footprint across Germany and Eastern Europe to control input costs for tapered roller assemblies. AB SKF anchors its position through sensor-embedded smart bearing platforms that feed real-time vibration data into fleet management systems. NSK Ltd. competes on ceramic hybrid designs optimized for electric motor shaft speeds.
Automotive bearings are precision-engineered rotational components, typically fabricated from hardened chrome steel or silicon nitride ceramic, with raceway tolerances measured in micrometers to manage radial and axial loads in powertrain and chassis assemblies. Their primary commercial purpose is reducing friction between moving parts while maintaining positional accuracy under thermal and mechanical stress. Roller bearings dominate heavy-load applications in commercial vehicle axles and transmission systems where contact geometry distributes stress across line rather than point contact. Ball bearings lead passenger vehicle accessory drives and electric motor support due to lower friction coefficients at high rotational speeds. Hybrid bearings, combining ceramic rolling elements with steel rings, are gaining share in electric vehicle traction motors where insulation and thermal stability matter.
REACH compliance and the EU Green Deal shape material selection by restricting hazardous substances in bearing coatings and lubricants, while CE marking under the Machinery Directive governs performance validation for aftermarket distribution. ECHA substance evaluations are pushing suppliers toward PFAS-free grease formulations and recyclable cage materials. Stakeholders must monitor how battery-electric platform architectures reshape load paths and thermal envelopes, as these determine which bearing technologies win design-in contracts across European vehicle programs.
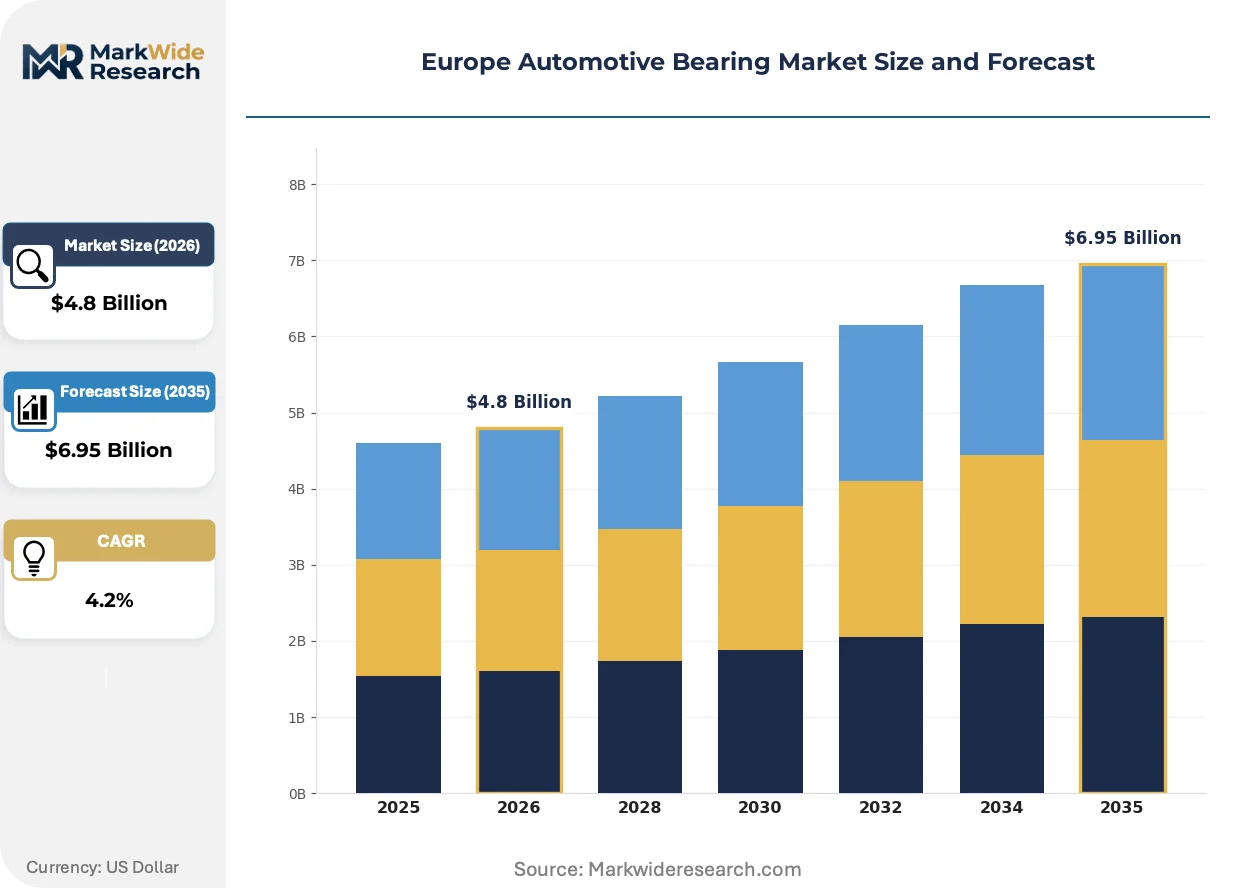
Market Dynamics
Electric vehicle powertrain architectures are compressing bearing count per vehicle while demanding higher load-density specifications from remaining components, forcing suppliers to re-engineer product portfolios around thermal management and electrical insulation requirements.
Growth Catalysts
- EU Green Deal compliance mandates:F-Gas Regulation phase-down is accelerating demand for low-friction bearing designs that reduce HVAC compressor energy draw in electric vehicles.
- Silicon nitride ceramic adoption:Hybrid bearing configurations with ceramic rolling elements are penetrating electric motor shaft applications where thermal stability and electrical insulation prove critical.
- German aftermarket concentration:Fleet operators in Baden-Württemberg and Bavaria are extending vehicle replacement cycles, pulling demand toward predictive maintenance contracts and refurbishment services.
Market Restraints
- Alloy steel input volatility:Chrome steel prices fluctuate with nickel and chromium spot markets, compressing margin visibility for tapered roller assembly producers.
- Eastern European supply concentration:Tier-two cage and seal suppliers cluster in Poland and Romania, creating single-source vulnerability for Western European bearing assemblers.
- REACH substance restrictions:ECHA evaluations of PFAS-containing greases are forcing reformulation timelines that outpace product certification cycles.
Strategic Opportunities
- Italian commercial vehicle retrofit market:Aging heavy-duty fleets in Lombardy and Emilia-Romagna present untapped demand for upgraded axle bearing kits compatible with extended service intervals.
- Sensor-embedded smart bearings:Integration of vibration monitoring chips with steel raceway assemblies enables real-time fleet diagnostics for logistics operators.
- CE marking harmonization:Machinery Directive alignment across EU member states reduces aftermarket distribution friction for replacement bearing kits.
Industry Challenges
- Precision grinding workforce scarcity:Micrometer-tolerance raceway finishing requires specialized machinist training that vocational programs in France and Germany have not scaled to meet.
- Dual certification timelines:Battery-electric platform bearings must simultaneously satisfy OEM performance validation and aftermarket CE marking, stretching engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Bearing Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Bearings, Roller Bearings, Needle Bearings, Thrust Bearings Technology: Plain Bearings, Magnetic Bearings, Hybrid Bearings, Composite Bearings End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Electric Vehicles |
| Companies Covered | AB SKF, Schaeffler AG, NSK Ltd., NTN Corporation, The Timken Company, JTEKT Corporation, RBC Bearings, Inc., Nippon Thompson Co., Ltd., Iljin Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Bearing Market Shifts & Advancements
Digital twin technology is virtualizing how bearing performance gets validated before physical prototyping, compressing development cycles for electric vehicle powertrain applications. This convergence of simulation software with material science is reshaping competitive requirements for supplier engineering capabilities.
Cloud-based bearing simulation platforms are virtualizing traditional physical testing protocols. Tier-one suppliers now model thermal expansion and contact stress digitally before cutting steel. French and German OEM engineering teams are adopting these tools at accelerating rates. The technology is virtualizing capital allocation decisions by reducing prototype iteration counts and compressing time-to-design-in.
REACH and the F-Gas Regulation are tightening material compliance thresholds for bearing coatings and lubricants. ECHA substance evaluations now restrict PFAS-containing greases and mandate recyclable cage materials. Suppliers are reformulating product lines to maintain market access. Aftermarket distributors face the steepest adaptation burden as legacy inventory must clear compliance checkpoints.
Long-term service contracts are displacing transactional component sales for commercial vehicle fleet operators. Logistics providers in Germany and the Netherlands now procure bearing performance by kilometer rather than by unit. Predictive maintenance platforms feed vibration data into fleet management systems. This procurement evolution is most visible in refrigerated transport segments where uptime guarantees dominate supplier selection criteria.
Europe Automotive Bearing Market Segmentation
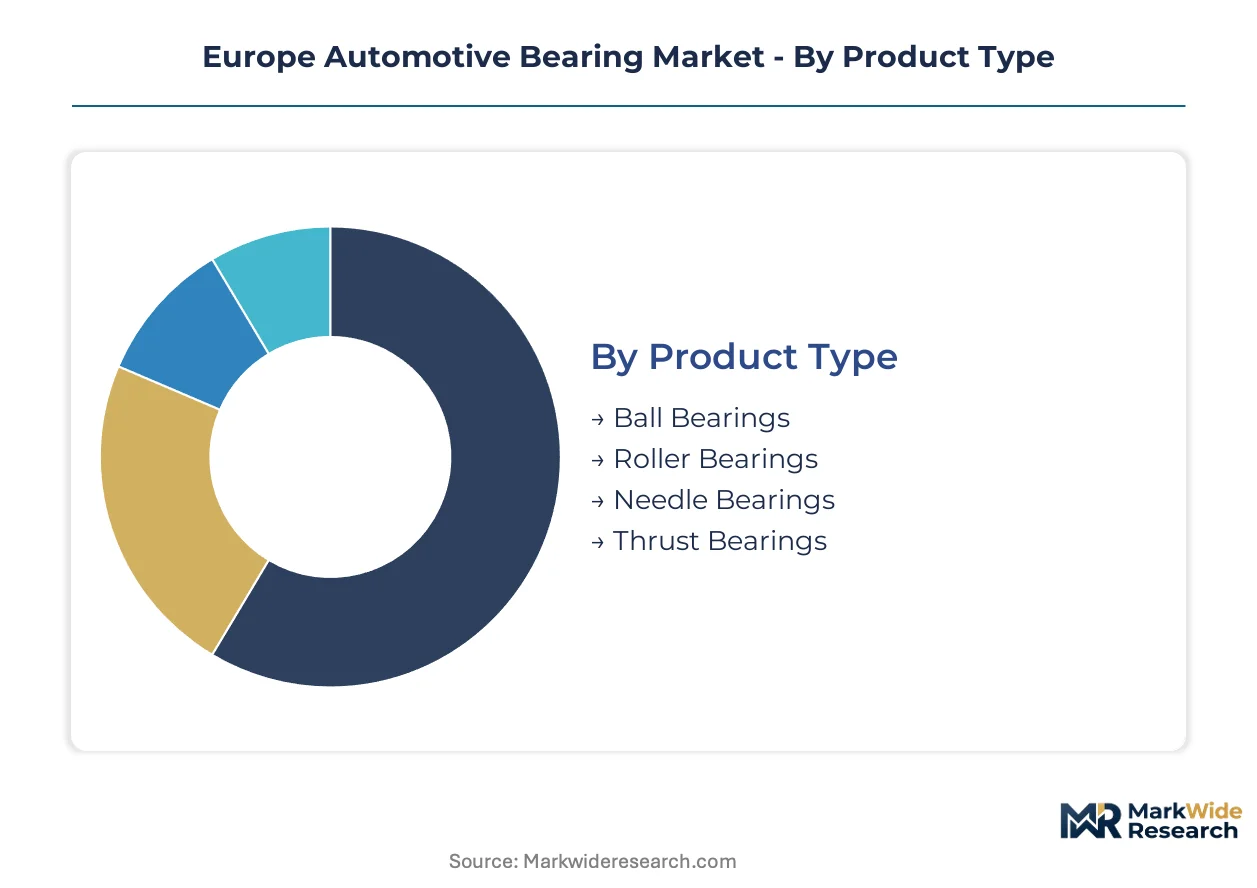
Automotive bearing procurement patterns diverge sharply across product architectures, technology generations, and supply chain tiers. Electric vehicle platforms are compressing traditional segment boundaries while amplifying performance requirements for remaining components.
Product Type:
Use-case spectrum spans low-friction passenger vehicle accessory drives through heavy-load commercial vehicle axles, with each geometry optimizing for distinct load paths and rotational speeds.
- Ball Bearings:Spherical rolling elements maintain point contact with raceways, minimizing friction coefficients for high-speed electric motor shaft support and belt-driven accessory systems. German passenger vehicle OEMs specify these for HVAC compressor and alternator applications where energy efficiency directly impacts range calculations.
- Roller Bearings:Cylindrical or tapered geometries distribute stress across line contact, accommodating radial and axial loads in transmission gearboxes and wheel hub assemblies. French and Italian commercial vehicle manufacturers rely on tapered roller configurations for drive axle differentials subject to sustained torque spikes.
- Needle Bearings:Compact cylindrical rollers with high length-to-diameter ratios fit constrained envelope spaces in planetary gear sets and connecting rod small ends.
- Thrust Bearings:Flat-race designs manage pure axial loads in steering rack pinions and automatic transmission clutch packs.
Established volume favors Roller Bearings; emerging adoption favors Ball Bearings as electric powertrains proliferate.
Technology:
Material science differentiation determines thermal envelope, electrical insulation capability, and maintenance interval expectations across European vehicle programs.
- Hybrid Bearings:Silicon nitride ceramic rolling elements paired with steel rings deliver dielectric isolation and thermal stability for electric motor shaft applications. NSK Ltd. and AB SKF have scaled production of these configurations for battery-electric traction motors operating above 15,000 RPM.
- Plain Bearings:Self-lubricating polymer or sintered metal sleeves eliminate rolling elements entirely, suited for oscillating motion in suspension linkages and steering columns where contamination resistance matters.
- Magnetic Bearings:Electromagnetic levitation eliminates mechanical contact for ultra-high-speed compressor applications in fuel cell systems and advanced thermal management loops.
- Composite Bearings:Reinforced polymer matrices with PTFE liners reduce weight in non-critical chassis attachments where load magnitude permits material substitution.
Hybrid configurations are climbing the fastest as OEMs validate electrical insulation requirements for next-generation electric platforms.
End User:
Procurement authority concentrates differently across new vehicle assembly, system integration, and replacement part distribution channels.
- OEMs:Vehicle manufacturers specify bearing performance criteria during platform development, locking in design-in relationships through multi-year supply agreements. Volkswagen Group and Stellantis maintain direct technical dialogue with Schaeffler AG for powertrain bearing validation.
- Tier-1 Suppliers:System integrators procure bearings for transmission, axle, and motor assembly subcontracts, applying their own quality gates atop OEM requirements.
- Aftermarket Providers:Independent distributors and service networks manage replacement inventory for aging vehicle parc, with German fleet operators increasingly procuring through predictive maintenance contracts.
- Vehicle Assemblers:Contract manufacturers and specialty vehicle builders source bearings through consolidated procurement functions without direct engineering involvement.
Direct OEM relationships command premium positioning; aftermarket channels face margin compression from compliance adaptation costs.
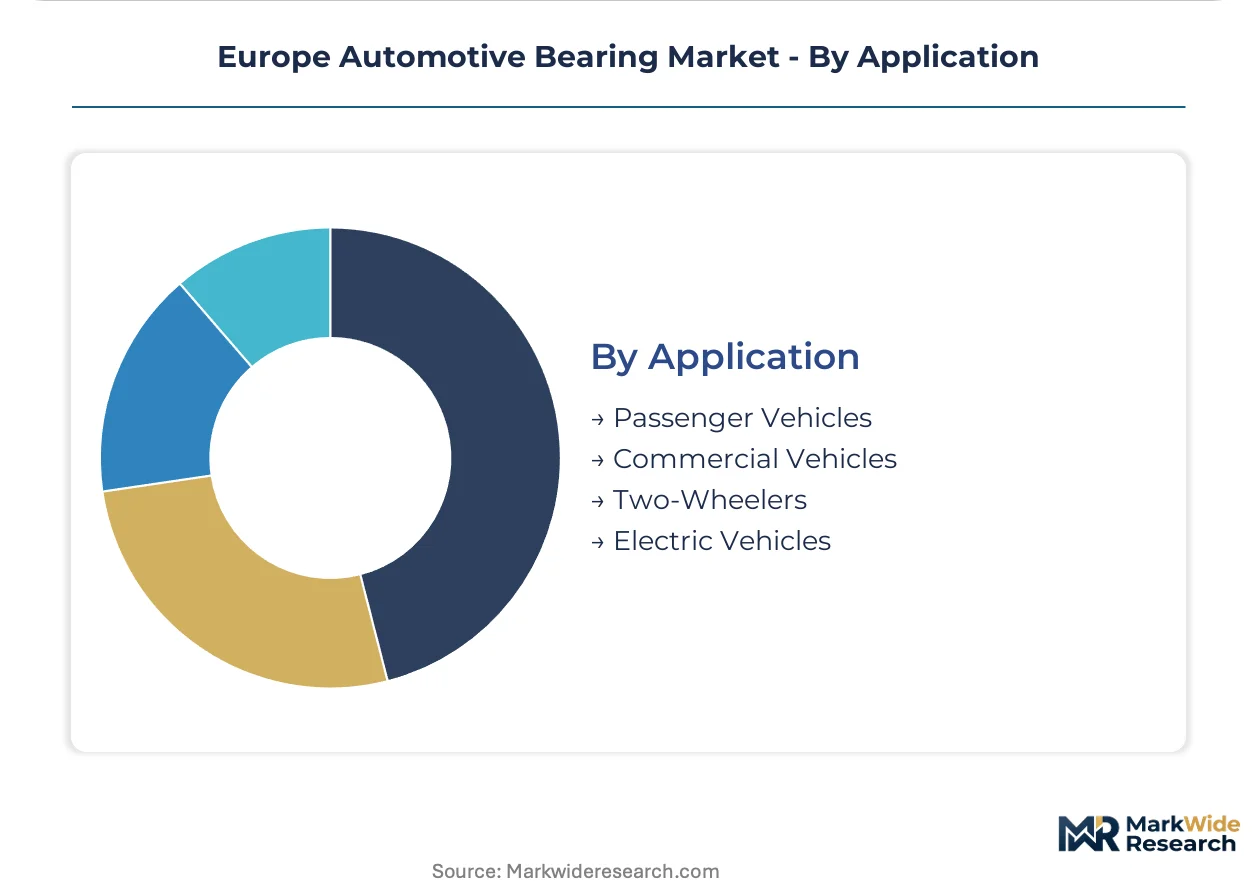
Application:
Vehicle architecture determines load path geometry, thermal environment, and duty cycle severity for bearing specification.
- Electric Vehicles:Traction motor bearings must manage electrical discharge damage, thermal cycling from rapid charging, and sustained high-speed operation. Hybrid ceramic designs with integrated insulation layers are becoming standard for European battery-electric platforms.
- Commercial Vehicles:Heavy-duty axle and transmission bearings endure torque spikes, contamination exposure, and extended service interval demands. Lombardy-based fleet operators in Italy are retrofitting upgraded bearing kits to aging Euro V and Euro VI chassis.
- Passenger Vehicles:Internal combustion powertrains continue generating demand for conventional bearing geometries, though volumes are plateauing as electrification accelerates.
- Two-Wheelers:Compact bearing envelopes for motorcycle engines and transmissions prioritize cost efficiency over advanced material specifications.
Commercial vehicle refurbishment sustains near-term volume; electric vehicle applications are gaining share fastest across supplier engineering priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Eastern European manufacturing clusters concentrate bearing assembly capacity, while Southern European aftermarket demand pulls refurbishment services toward aging commercial vehicle fleets. Regulatory pressure from Brussels reshapes material specifications across all national markets.
Germany
Baden-Württemberg and Bavaria host dense networks of tier-one bearing assemblers serving Volkswagen Group and BMW powertrain programs. KBA vehicle certification requirements enforce strict performance validation for replacement bearing kits entering the German aftermarket. Stuttgart's industrial corridor anchors sensor-embedded smart bearing development for electric vehicle traction motors.
France
Île-de-France engineering centers specify bearing performance criteria for Stellantis electric platforms, driving demand for hybrid ceramic configurations. ANSM and CNIL oversight extends to data-bearing components in connected vehicle systems. Auvergne-Rhône-Alpes machining clusters face precision grinding workforce shortages that constrain raceway finishing capacity.
Italy
Lombardy and Emilia-Romagna fleet operators retrofit upgraded axle bearing kits to extend Euro V and Euro VI chassis service intervals. CE marking harmonization under the Machinery Directive streamlines aftermarket distribution for replacement components. Turin-based commercial vehicle manufacturers source tapered roller assemblies for heavy-duty transmission systems.
Poland
Lower Silesia and Masovia regions concentrate tier-two cage and seal suppliers, creating single-source vulnerability for Western European bearing assemblers. Polish vocational programs scale CNC machining training faster than Western counterparts, attracting subcontractor relocation. Warsaw logistics hubs distribute replacement inventory across Central European aftermarket channels.
Netherlands
Randstad logistics operators procure bearing performance through long-term service contracts rather than transactional component sales. Dutch refrigerated transport fleets demand uptime guarantees that favor predictive maintenance platforms. Rotterdam port infrastructure supports just-in-time delivery of alloy steel inputs for bearing manufacturers serving German OEMs.
Europe Automotive Bearing Market Competitive Landscape
Integrated manufacturing specialists and sensor-technology developers split the market between cost-controlled volume production and premium connected-component positioning. The vendor base concentrates around three strategic archetypes: German-anchored integrated manufacturers, Nordic sensor-technology platforms, and Japanese ceramic-hybrid specialists. Consolidation pressure favors backward integration into steel input streams and cross-border partnerships for Eastern European cage supply security.
Within the integrated-manufacturing tier, Schaeffler AG exemplifies the archetype of geographically concentrated production control. AB SKF anchors the sensor-embedded technology vector through its positioning in real-time diagnostics platforms. NSK Ltd. occupies the ceramic-hybrid specialization niche that electric vehicle powertrain electrification is amplifying.
| Leading Market Players |
|---|
| AB SKF |
| Schaeffler AG |
| NSK Ltd. |
| NTN Corporation |
| The Timken Company |
| JTEKT Corporation |
| RBC Bearings, Inc. |
| Nippon Thompson Co., Ltd. |
| Iljin Group |
| Others |
Supply & Pricing Matrix
Polish and Romanian cage and seal suppliers anchor tier-two input availability, concentrating margin capture with Western European bearing assemblers who control raceway finishing and final assembly. Chrome steel price volatility from nickel and chromium spot markets feeds directly into tapered roller assembly margins, compressing visibility for producers without backward integration into alloy inputs.
Pricing Analysis
Predictive maintenance contracts and refurbishment services now drive lifetime value extraction from commercial vehicle fleets. Three-tier pricing structure across premium sensor-embedded, standard sealed, and economy open-bearing levels separates warranty-backed OEM supply from aftermarket replacement tiers. Cost compression in standard-grade tapered roller assemblies is intensifying because Eastern European metalworking capacity scales faster than Western finishing expertise. Fleet operators in German refrigerated transport segments show least price sensitivity due to uptime guarantee requirements, while Italian independent aftermarket distributors face greatest margin pressure from REACH compliance adaptation costs.
Supply Chain Analysis
EU dual-use export controls on precision grinding equipment limit technology transfer to non-EU machining centers, constraining capacity expansion outside the region. Germany, Poland, and Romania concentrate tier-one assembly and tier-two component supply, with raw material dependencies on Swedish and Turkish alloy steel, Chinese rare-earth elements for ceramic hybrids, and Belgian lubricant formulations. Single-source vulnerability runs through Lower Silesia cage suppliers serving multiple Western assemblers. Distribution runs through Stuttgart engineering corridors for OEM design-in, Rotterdam port logistics for steel input staging, and Warsaw distribution hubs for Central European aftermarket fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe Automotive Bearing Market recovery tracks vehicle production cycles, with electrification capex waves from Stellantis and Volkswagen Group powertrain programs providing the cyclical lift.
For Market Incumbents: Pre-empt ceramic hybrid supply shortages by locking silicon nitride powder contracts ahead of electric vehicle platform ramp-ups. Secure Polish and Romanian cage supplier equity stakes to eliminate single-source exposure for Western European assembly footprints. Precision grinding workforce scarcity in Auvergne-Rhône-Alpes and Baden-Württemberg demands apprenticeship program scaling before competitor talent raids intensify. For New Entrants and Emerging Players: Aging Euro V and Euro VI commercial vehicle fleets in Lombardy and Emilia-Romagna represent the most penetrable entry point for upgraded axle bearing retrofit kits. Sensor-embedded smart bearing platforms for Dutch refrigerated transport logistics operators offer design-in pathways without direct OEM supply agreement barriers. CE marking harmonization under the Machinery Directive enables aftermarket distribution entry without multi-year OEM validation cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed automotive component platforms that consolidated during prior downturn cycles. Five-to-ten year viability hinges on electric vehicle bearing content per vehicle trajectories and thermal management technology transitions. Watch silicon nitride ceramic adoption rates in German traction motor programs as the inflection signal for hybrid bearing demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Steel Supply | Captive chrome steel production insulates Schaeffler AG from nickel spot volatility. |
| Sensor-Embedded Smart Bearing Platform Launch | AB SKF vibration monitoring chips penetrate Dutch refrigerated transport fleet management systems. |
| CE Marking Harmonization Investment | Machinery Directive alignment reduces aftermarket distribution friction for Italian retrofit kits. |
| Precision Grinding Workforce Apprenticeship Scaling | French and German vocational program expansion addresses raceway finishing capacity constraints. |
| PFAS-Free Grease Formulation Certification | ECHA-compliant lubricant lines maintain REACH market access for aftermarket distributors. |
Research Methodology
Desk research of EU regulatory filings, vehicle production databases, and ECHA substance evaluation records preceded structured interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributor operations heads, and precision grinding workforce training coordinators. Secondary validation drew from KBA vehicle certification data, IHS Markit registration statistics, and SEC filings of listed bearing manufacturers. Bottom-up segment sizing triangulated against top-down OEM production forecasts across the analysis window.
Assumptions held electric vehicle penetration rates and REACH substance restriction timelines fixed while varying chrome steel price scenarios and precision grinding workforce availability. Segmentation modeling spanned product geometry, material technology, end-user procurement authority, and vehicle application thermal envelope. CAGRs derived from regression of historical content-per-vehicle trends against projected platform volumes, with electric motor shaft speed requirements and commercial vehicle service interval extensions as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in eurozone industrial production indices or German automotive capex cycles would shift the trajectory. Material shifts in ECHA PFAS restriction enforcement timelines or silicon nitride ceramic supply chain consolidation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Argentina Automotive Electric Actuators Market
Automotive Components
Automotive Lightweighting Market
Automotive Components
Automotive Active Bonnet Market
Automotive Components
Automotive Tailgate Market
Automotive Components
Automotive Mobile Accessories Market
Automotive Components
Automotive Exhaust Headers Market
Automotive Components
Automotive License Plate Light Market
Automotive Components
Automotive Aftermarket for Brake Components Market
Automotive Components
Global Automotive Sun Visor Market
Automotive Components
Automotive Air Deflector Market
Automotive Components
Automotive Refrigerant Market
Automotive Components
Automotive Solenoid Market
Automotive Components
Automotive Solar Control Glass Market
Automotive Components
Automotive Distributor Market
Automotive Components
Japan Automotive Composites Market
Automotive Components
Asia-Pacific Automotive Plastics Market