
 Automotive Heater Core Market | 2026-2036
Automotive Heater Core Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Heater Core Market Analysis
Commercial fleet operators is unwinding the traditional OEM-dominant procurement pattern for heater cores. Denso Corporation leverages its integrated thermal systems portfolio to anchor supply relationships with Japanese and North American automakers. Mahle competes through specialized aluminum brazing expertise that sustains cost advantages in high-volume passenger vehicle programs. Valeo dominates European electric vehicle thermal module integration, extending its position into battery conditioning applications.
An automotive heater core is a heat exchanger component, typically constructed from aluminum or copper tubes with fin arrays, that transfers thermal energy from engine coolant or electric heating elements into cabin air streams. The device operates at coolant temperatures between 80°C and 110°C in conventional architectures, while electric variants employ positive temperature coefficient elements or heat pump integration for cabin warming. Aluminum heater cores lead production volume due to favorable weight-to-conductivity ratios, though copper variants retain niche positions in heavy equipment where corrosion resistance commands priority. Electric technology segments are expanding fastest as battery electric vehicles eliminate waste heat sources and demand active thermal management. Aftermarket providers within the end user dimension concentrate margin pools in regions with aging vehicle parc and limited dealer network penetration.
NHTSA safety standards govern defrosting performance timelines that shape heater core thermal output specifications in the United States. ECHA REACH restrictions on hexavalent chromium coatings are forcing European suppliers toward trivalent alternatives in brazing flux formulations. EPA fuel economy regulations indirectly tighten cabin thermal efficiency requirements, compressing allowable energy draw from propulsion systems. Stakeholders must monitor how Euro 7 implementation timelines and California Air Resources Board zero-emission mandates recalibrate material and technology selection across their product roadmaps.
Market Dynamics
Electric vehicle thermal architectures are dismantling the waste-heat dependency that sustained conventional heater core designs for decades, forcing suppliers to reengineer around positive temperature coefficient elements and heat pump integration.
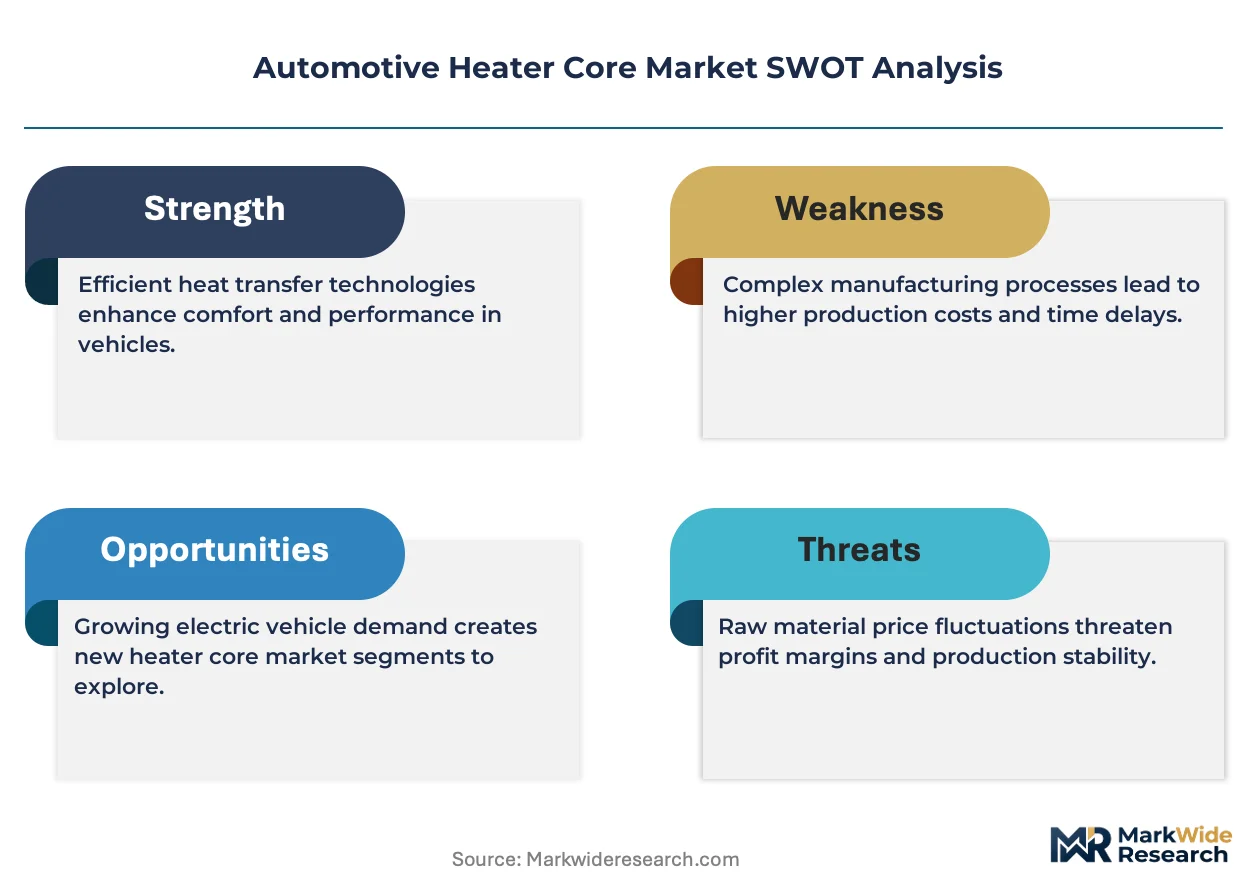
Growth Catalysts
- EPA tailpipe standards:Tightening fuel economy mandates in the United States compress allowable cabin energy draw, accelerating demand for high-efficiency thermal management components that minimize propulsion system parasitic load.
- China's aging vehicle parc:Domestic EV output scaling alongside a swelling base of combustion vehicles past warranty coverage concentrates aftermarket replacement demand in tier-two and tier-three cities.
- Aluminum brazing advances:Improved flux formulations and controlled atmosphere processing enable thinner tube walls without sacrificing pressure integrity, reducing unit weight for electric platforms where thermal mass directly impacts range.
Market Restraints
- Copper price volatility:Heavy equipment segments still specifying copper heater cores face input cost instability that compresses margin predictability for low-volume specialty suppliers.
- European supply concentration:Trivalent chromium conversion capacity for REACH-compliant brazing fluxes clusters in German and Austrian processing facilities, creating geographic chokepoints.
- Heat pump substitution:Integrated thermal management modules in premium electric vehicles increasingly bypass discrete heater cores entirely, threatening component-level demand in high-growth segments.
Strategic Opportunities
- India commercial fleet electrification:Bus rapid transit and last-mile delivery electrification under the Faster Adoption and Manufacturing of Hybrid and Electric Vehicles scheme opens demand for localized thermal module production.
- Battery conditioning convergence:Heater cores repurposed for pack thermal regulation bridge cabin comfort and cell longevity functions, creating dual-revenue component architectures.
- E-commerce aftermarket channels:Direct-to-installer platforms bypass traditional distributor markups in regions with limited OEM dealer penetration, capturing margin pools previously held by wholesale intermediaries.
Industry Challenges
- Multiphysics simulation talent scarcity:Coupled thermal-fluid-electrical modeling for integrated heat pump systems requires skill sets concentrated in aerospace and battery engineering, not legacy HVAC supply bases.
- Dual certification timelines:Simultaneous NHTSA defrosting validation and ECE R122 compliance for global vehicle programs extends development cycles and strains testing capacity.
- Legacy combustion integration:Modular heater core designs must interface with both existing coolant architectures and emerging refrigerant loops, multiplying interface specification complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Heater Core Market |
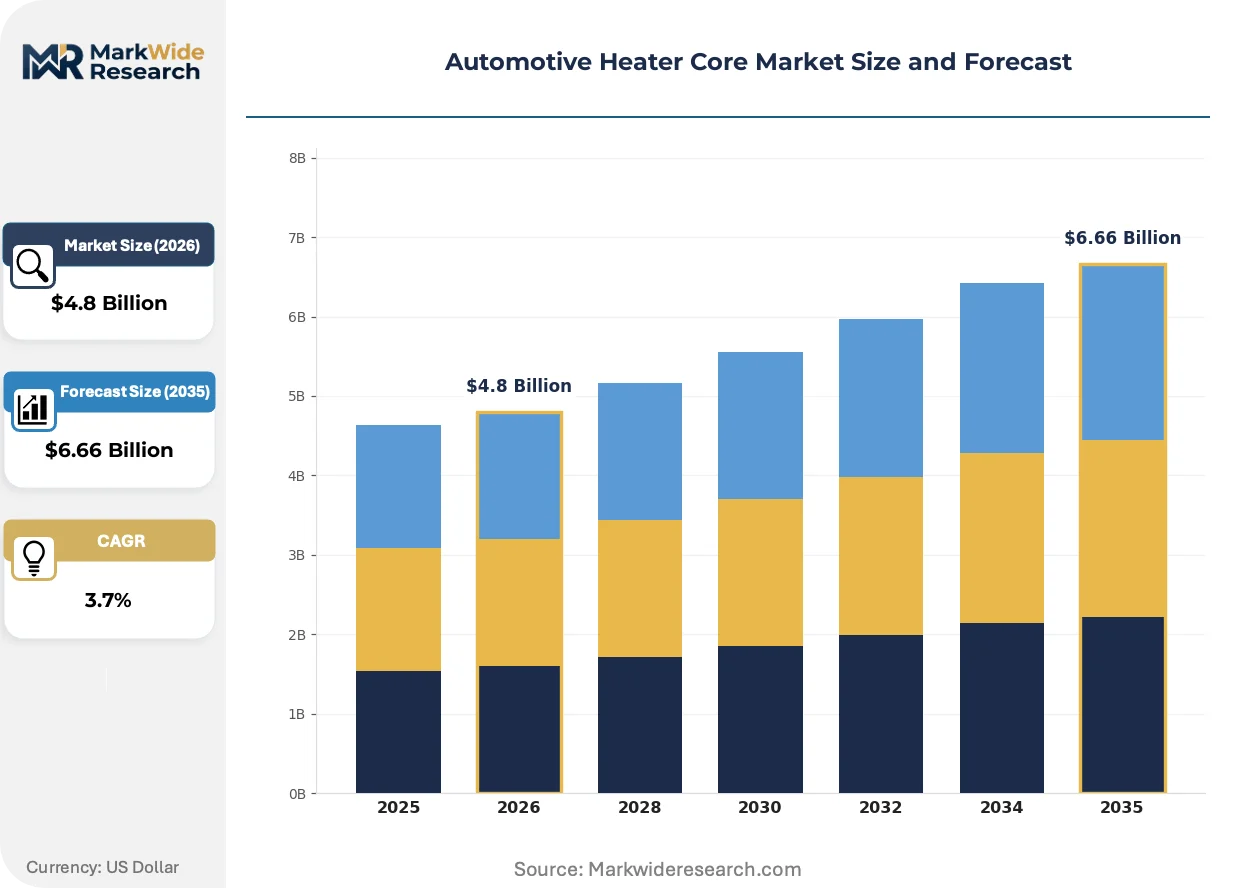
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Plastic, Copper, Composite Application: Passenger Vehicles, Commercial Trucks, HVAC Systems, Heavy Equipment End User: OEMs, Aftermarket Providers, Service Centers, Distributors Technology: Conventional, Electric, Hybrid, Customized Solutions |
| Companies Covered | Denso Corporation, Calsonic Kansei, Delphi Automotive, Hanon Systems, Sanden Holdings, Mahle, Spectra Premium, Modine Manufacturing Company, Valeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Heater Core Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry restrictions are converging to compress heater core form factors while expanding their functional scope beyond cabin heating into full vehicle thermal management.
Positive temperature coefficient ceramic elements are replacing traditional coolant-based heat exchangers in battery electric vehicle architectures. Premium EV platforms from German and Korean automakers specify these solid-state heaters for instantaneous cabin response without coolant loop thermal lag. The technology is miniaturizing packaging envelopes to half the volume of aluminum tube-and-fin equivalents, freeing critical front-end space for battery and power electronics cooling.
ECHA REACH restrictions on hexavalent chromium surface treatments are forcing European suppliers to retool brazing lines toward trivalent formulations. The transition adds process steps and quality verification overhead but eliminates hazardous substance liability exposure. Suppliers serving Volvo, Stellantis, and BMW programs have completed conversion fastest, while smaller tier-two processors lag in capital deployment.
Fleet operators managing commercial vehicle parc are unbundling heater core procurement from full HVAC system contracts. Large logistics and transit authorities in California and Texas now source thermal components separately from compressor and blower assemblies, compressing supplier margins but opening direct relationships previously gated by tier-one integrators. This disintermediation is most visible in school bus and medium-duty delivery segments where total cost of ownership analytics dominate specification decisions.
Automotive Heater Core Market Segmentation
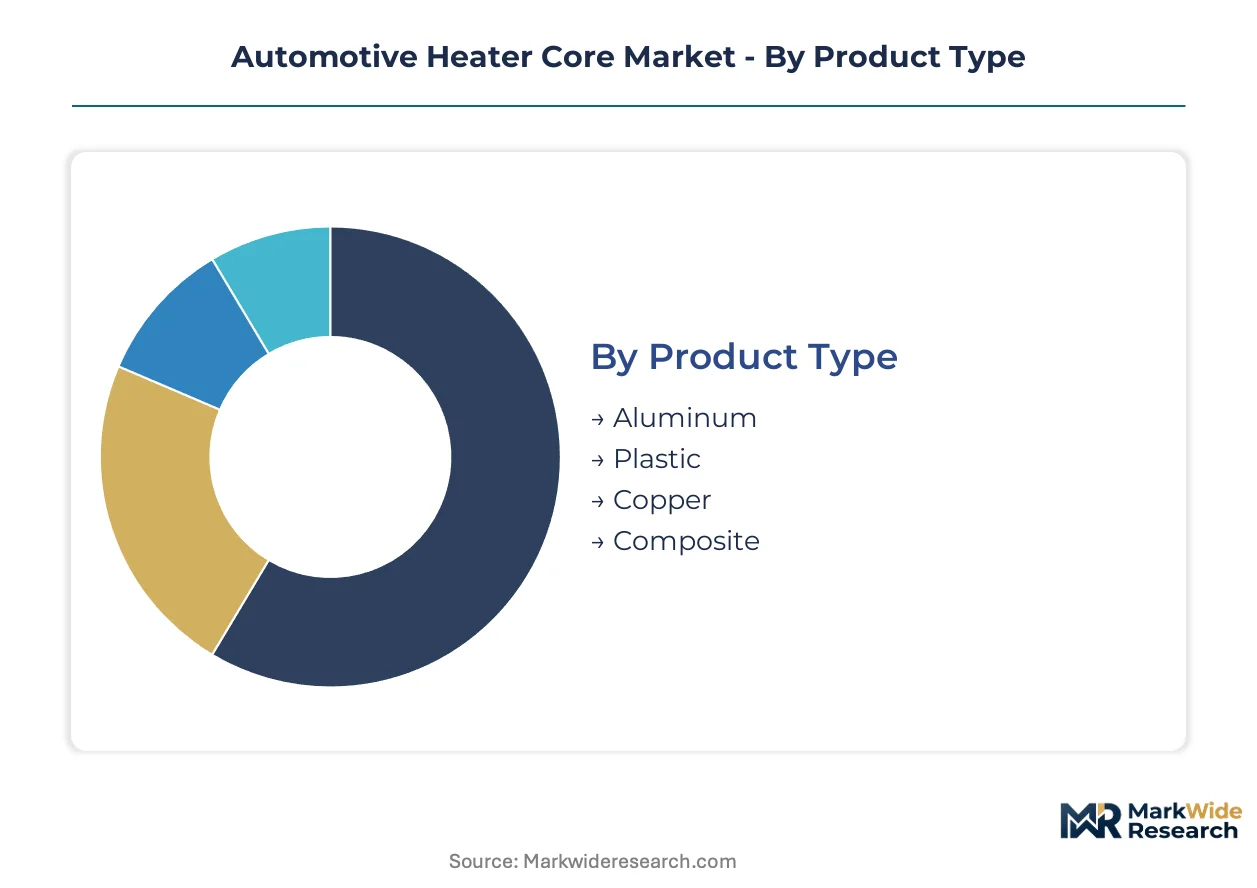
Segmentation in the automotive heater core market exposes how material chemistry, vehicle electrification, and procurement channel shifts create divergent margin pools. Suppliers must align production capabilities across aluminum brazing, electric PTC elements, and legacy copper architectures to capture value as thermal management architectures fragment.
Product Type:
Aluminum dominates export-led supply chains serving North American and European electric vehicle platforms, while copper retains domestic-heavy demand in heavy equipment markets with limited cross-border sourcing.
- Aluminum:Tube-and-fin architectures leverage controlled atmosphere brazing to achieve weight-to-conductivity ratios critical for battery electric range optimization. Demand concentrates in German and Korean OEM electric platforms where thermal mass directly impacts vehicle efficiency metrics.
- Copper:Superior corrosion resistance and pressure tolerance sustain specification in mining equipment, agricultural machinery, and military vehicles operating in abrasive environments. North American heavy equipment manufacturers source domestically to avoid tariff exposure on fabricated thermal components.
- Plastic:Polymer tank housings and end caps reduce unit weight in cost-sensitive passenger vehicle programs.
- Composite:Multi-material bonding combines aluminum conductivity with polymer corrosion barriers in hybrid architectures.
Aluminum holds the largest share; momentum sits with composite solutions bridging thermal performance and electrification packaging constraints.
Application:
Volume concentration varies sharply by customer procurement power, with fleet operators in commercial segments disaggregating specifications that OEMs once bundled.
- Passenger Vehicles:Mass-market and premium electric platforms drive the steepest expansion trajectory as heat pump integration and PTC elements replace coolant-dependent architectures. Japanese and Korean automakers specify integrated thermal modules compressing heater core form factors by half versus conventional designs.
- Commercial Trucks:Long-haul diesel platforms retain coolant-based heater cores for sleeper cab heating, though battery electric transit buses in California and Texas are forcing thermal system redesigns.
- HVAC Systems:Integrated climate control modules bundle heater cores with compressors and blower assemblies in tier-one supplier relationships.
- Heavy Equipment:Construction and mining vehicles specify copper variants for extreme duty cycles and field serviceability.
Passenger vehicles command volume leadership; commercial trucks face the most procurement disruption from fleet electrification mandates.
End User:
Channel structure determines margin capture, with direct relationships replacing distributor intermediation in regions with sparse OEM dealer networks.
- OEMs:Tier-one thermal system integrators specify heater cores within bundled HVAC contracts, though electric vehicle platforms are unbundling components for specialized sourcing. German and Korean automakers maintain the tightest supplier qualification timelines.
- Aftermarket Providers:Independent distributors and e-commerce platforms capture replacement demand in China's tier-two and tier-three cities where vehicle parc aging outpaces dealer network expansion.
- Service Centers:Quick-lube and repair chains source standardized aluminum units for high-turnover installation.
- Distributors:Wholesale intermediaries retain position in European markets with established tier-two supplier relationships.
OEMs dominate value capture; aftermarket channels are climbing fastest as vehicle electrification extends replacement cycles and concentrates demand in aging combustion fleets.
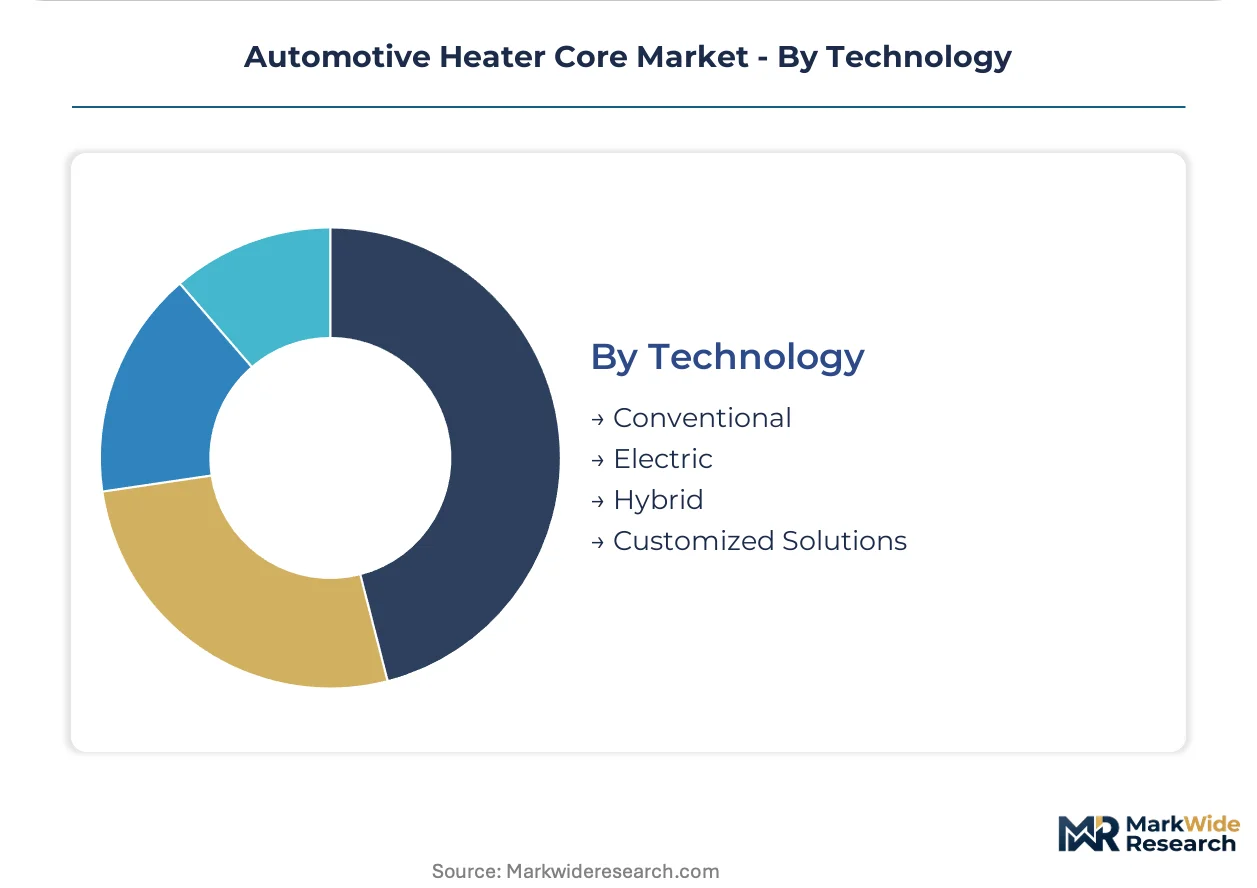
Technology:
Development resource allocation splits between optimizing legacy coolant architectures and engineering solid-state thermal solutions for battery electric platforms.
- Electric:Positive temperature coefficient ceramic elements deliver instantaneous cabin response without coolant loop thermal lag. Korean battery electric platforms specify these for packaging efficiency and reduced front-end thermal mass.
- Conventional:Engine coolant-dependent tube-and-fin designs sustain production volume in hybrid vehicles and markets with limited charging infrastructure.
- Hybrid:Dual-mode systems switch between waste heat recovery and active electric heating based on powertrain operating state.
- Customized Solutions:Specialized form factors serve military, aerospace, and extreme climate applications with non-standard packaging envelopes.
Conventional technology retains volume dominance; electric architectures gain share fastest as battery electric vehicle production scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors Asia-Pacific thermal component flows, handling aluminum brazing materials and finished heater cores for German and Korean electric vehicle platforms. Its throughput capacity underwrites China's position as the dominant export hub for automotive thermal management hardware.
United States
California's fleet electrification mandates and Texas commercial vehicle density drive divergent demand profiles. NHTSA defrosting performance timelines shape heater core thermal specifications for domestic automakers. Detroit's supplier corridor concentrates aluminum brazing capacity serving North American OEM electric platforms.
Germany
Premium electric vehicle thermal module integration commands specialized engineering resources from Stuttgart and Munich automotive clusters. ECHA REACH restrictions on hexavalent chromium coatings force trivalent conversion in brazing flux formulations. Bavarian processing facilities cluster REACH-compliant capacity, creating geographic concentration for European supply.
China
Domestic EV output scaling alongside aging combustion vehicle parc concentrates aftermarket replacement demand. MIIT new energy vehicle production quotas accelerate thermal management component localization. Tier-two and tier-three cities in the Yangtze River Delta absorb independent distributor channels as dealer networks lag vehicle aging.
Japan
Integrated thermal systems portfolios anchor supply relationships with domestic and North American automakers. METI carbon neutrality roadmaps recalibrate material selection for export-oriented production. Nagoya's automotive supplier corridor maintains controlled atmosphere brazing expertise for thin-wall aluminum architectures.
South Korea
Battery electric vehicle platforms specify positive temperature coefficient elements for packaging efficiency and reduced front-end thermal mass. MFDS automotive component standards align with ECE regulations for export market access. Gyeonggi Province's electric vehicle supplier ecosystem concentrates solid-state heater development capacity.
Automotive Heater Core Market Vendor Landscape
Concentration sits with diversified thermal system integrators holding bundled HVAC contracts with major OEMs. The supplier base tiers between full-system integrators, component specialists, and aftermarket distributors. Three archetypes dominate: Japanese conglomerates with integrated portfolios, European specialists in electric vehicle thermal modules, and North American aftermarket-focused fabricators. Competitive moves center on aluminum brazing process refinement for weight reduction and direct fleet operator relationships that bypass traditional tier-one intermediaries.
Among Japanese conglomerates, Denso Corporation exemplifies the integrated systems archetype through its thermal management portfolio breadth. Calsonic Kansei occupies a position within the same tier, representing consolidated supplier relationships with global OEM platforms. Valeo anchors the European specialist vector, with its positioning extending into battery conditioning applications that bridge cabin comfort and cell longevity functions.
| Leading Market Players |
|---|
| Denso Corporation |
| Calsonic Kansei |
| Delphi Automotive |
| Hanon Systems |
| Sanden Holdings |
| Mahle |
| Spectra Premium |
| Modine Manufacturing Company |
| Valeo |
| Others |
Supply Flow & Price Mechanics
Trivalent chromium conversion replacing hexavalent coatings in European brazing flux formulations is redrawing supplier geography toward German and Austrian processing clusters while compressing margin structures for tier-two fabricators unable to fund retooling capital.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies around certification grade and volume scale. OEM direct contracts command premium positioning through NHTSA defrosting validation and ECE R122 dual certification, while aftermarket channels compete on unit economics for aging combustion fleet replacement. Cost compression in aluminum tube-and-fin architectures intensifies as electric vehicle platforms demand thinner-wall specifications without pressure integrity sacrifice. Fleet operators exhibit highest price sensitivity through unbundled procurement, whereas premium EV thermal module integrators prioritize performance over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate OEM thermal module assembly, though aftermarket distributors maintain strategic stockpiles of standardized aluminum units for high-turnover replacement cycles. Controlled atmosphere brazing capacity concentrates in Germany, China, and Japan, with raw material flows drawing from aluminum smelters in the Yangtze River Delta and flux chemical processors in Bavaria. Single-source vulnerability clusters in trivalent chromium conversion capacity for REACH-compliant formulations. Distribution runs through tier-one HVAC integrators for OEM channels, while e-commerce platforms and independent distributors capture aftermarket volume in regions with limited dealer penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle thermal architecture proliferation is accelerating heater core demand toward solid-state and heat pump-integrated solutions, creating early-cycle expansion conditions for suppliers with PTC ceramic and multiphysics simulation capabilities.
For Market Incumbents: Consolidate aluminum brazing expertise through captive supply of thin-wall tube architectures to defend against heat pump substitution threatening discrete heater core demand. Deepen backward integration into trivalent chromium flux processing to eliminate geographic chokepoint exposure from German-Austrian supplier concentration. Secure dual NHTSA-ECE certification capacity to compress development timelines for global vehicle programs.
For New Entrants and Emerging Players: Differentiate on battery conditioning convergence by engineering heater cores repurposed for pack thermal regulation alongside cabin comfort functions. Target India's commercial fleet electrification under FAME scheme incentives for localized thermal module production. Pursue direct fleet operator relationships in California and Texas school bus segments where total cost of ownership analytics unbundle procurement from tier-one integrators.
For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors specialists with electric thermal management capabilities over legacy coolant-dependent fabricators. Long-term viability centers on suppliers bridging cabin comfort and cell longevity functions in integrated architectures. Acquisition candidates should demonstrate PTC element engineering or heat pump integration expertise. Watch for inflection when battery electric vehicle production share crosses thresholds that render conventional waste-heat architectures economically marginal.
| Strategic Initiative | Industry Significance |
|---|---|
| PTC Ceramic Element Scale-Up | Solid-state heating eliminates coolant loop thermal lag for Korean and German EV platforms. |
| Backward Integration into Flux Processing | In-house trivalent chromium capacity removes REACH compliance chokepoint exposure. |
| Battery Conditioning Module Development | Dual-revenue architectures bridge cabin comfort and cell longevity functions. |
| India Manufacturing Footprint Establishment | FAME scheme incentives localize production for bus rapid transit electrification. |
| Direct Fleet Operator Channel Development | California and Texas school bus segments unbundle procurement from tier-one integrators. |
Methodological Framework
Operator-level perspectives from OEM platform engineers, tier-one thermal system procurement leads, aftermarket distributor operations managers, and fleet maintenance directors anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation drawing from vehicle production databases, IHS Markit registration data, EPA fuel economy filings, and ECHA REACH substance restriction updates. Bottom-up segmentation modeling triangulated against top-down market sizing across material chemistry, propulsion architecture, and procurement channel dimensions.
Sensitivity analysis tested forecast robustness across aluminum price volatility scenarios, electric vehicle penetration trajectories, and regulatory implementation timelines over the projection horizon. The analytical framework modeled vehicle class, propulsion architecture, content per vehicle, and regional production cluster segmentation. CAGRs derived from production volume forecasts weighted by thermal system content shifts from conventional coolant architectures toward PTC and heat pump integration. Industry-specific inputs included MIIT new energy vehicle production quotas and NHTSA defrosting performance validation timelines.
Decision-makers should treat outputs as directional under base assumptions of sustained EV production scaling and REACH compliance enforcement; material deviation would warrant model refresh. Forecasts reflect these documented assumptions alongside aluminum commodity price stability and fleet electrification mandate continuity. Revision becomes warranted when heat pump substitution rates in premium EV segments cross thresholds that compress discrete heater core demand beyond modeled parameters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
India Automotive Airfilters Market
Automotive Components
Europe Automotive Bearing Market
Automotive Components
Global Automotive Mats Market
Automotive Components
Automotive Metal Casting Market
Automotive Components
Automotive Bearing Market
Automotive Components
Automotive Glass Fiber Composites Market
Automotive Components
Electronic Clutch Actuators Market
Automotive Components
Brazil Automotive Composites Market
Automotive Components
Automotive Evaporative Emission Control (EVAP) System Market
Automotive Components
Turkey Automotive Plastic Compounding Market
Automotive Components
Global Automotive Window Regulator Market
Automotive Components
Europe Automotive Pneumatic Actuators Market
Automotive Components
Global Automotive Carbon Ceramic Brake Rotors Market
Automotive Components
Automotive Brake System and Components Market
Automotive Components
Automotive Active Grille Shutter Actuator Gear Market
Automotive Components
France Automotive Electric Actuators Market