
 Global Automotive Water Separation Systems Market | 2026-2036
Global Automotive Water Separation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Water Separation Systems Market Intelligence
Production capacity expansion in Eastern European automotive hubs like Poland and the Czech Republic is tilting the supply chain dynamics for filtration components. In this environment, MANN+HUMMEL Group leverages its extensive OEM relationships to secure long-term contracts. Donaldson Company, Inc. specializes in filtration solutions for heavy-duty commercial trucks and off-highway equipment. Meanwhile, MAHLE GmbH competes on the basis of its integrated thermal and engine component expertise.
Automotive water separation systems are filtration devices designed to remove emulsified and free water from fuel, oil, or air, primarily using coalescing filter media to achieve efficiencies above 99%. Their core purpose is to protect sensitive high-pressure common rail injectors and other engine components from corrosion and premature failure. While coalescing filters dominate the technology landscape, the commercial trucks segment accounts for the largest application-based demand due to its stringent uptime requirements.
Regulatory frameworks are a primary market catalyst, with the US EPA's emission standards and Europe's upcoming Euro 7 requirements mandating cleaner engine operation. Concurrently, material compliance under regulations like REACH in Europe and China's GB standards governs the composition of filter media and housing materials. Component suppliers must therefore balance performance improvements against a complex and diverging set of international material and environmental regulations.
Market Dynamics
The imperative to protect advanced high-pressure common rail engine systems from contamination is the central force shaping the market. Stricter global emissions regulations are accelerating the adoption of more efficient filtration, while production capacity for commercial vehicles is concentrating in specific regions.
Growth Catalysts
- Emission Standards:Regulations such as Europe's Euro 7 and mandates from the US EPA require cleaner combustion, driving the need for superior fuel filtration to protect sensitive engine components and minimize harmful emissions.
- Off-Highway Demand:The off-highway equipment sector, including construction and agricultural machinery, demands high-efficiency water separation to ensure operational reliability and uptime in demanding, often remote, environments.
- Engine Technology Advancement:The widespread adoption of high-pressure common rail (HPCR) fuel injection systems, which are highly susceptible to damage from water corrosion and abrasion, necessitates the use of advanced water separators.
Market Restraints
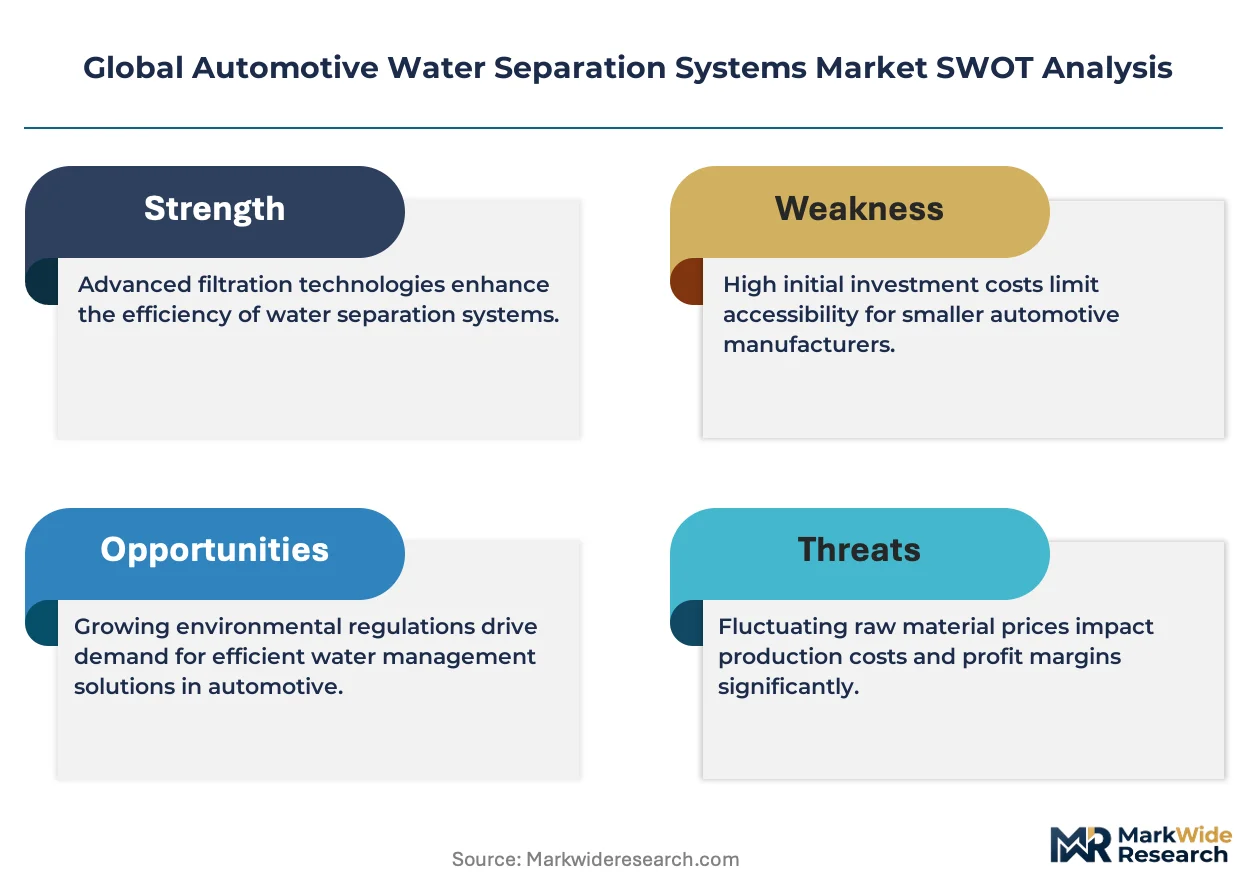
- Material Cost Volatility:The price of specialized synthetic coalescing filter media and high-grade polymers for housings is subject to fluctuations in raw material markets, creating cost pressure for component manufacturers.
- Diverging Regulatory Frameworks:Navigating conflicting material compliance rules, such as Europe's REACH and China's GB standards, complicates global product design and adds significant administrative and testing overhead for suppliers.
- Threat from Integrated Sensors:The development of sophisticated onboard fuel quality monitoring systems presents a long-term substitution risk, potentially allowing for less complex filtration hardware by enabling real-time fuel quality adjustments.
Strategic Opportunities
- Service for Alternative Fuels:Developing specialized water separation systems tailored for emerging powertrains, including hydrogen fuel cells and engines running on synthetic fuels, which have distinct filtration and material compatibility requirements.
- Smart Filtration Systems:Integrating sensors into filter modules to provide real-time data on water saturation and filter lifespan enables predictive maintenance services, creating new revenue streams beyond component sales.
- Geographic Expansion:Targeting the modernizing commercial vehicle fleets in Southeast Asian and Latin American countries provides access to markets with growing filtration needs but less mature local supply chains.
Industry Challenges
- Complex Validation Cycles:The extensive time and capital required to certify new filter media and housing materials against the performance and safety standards of multiple automotive OEMs creates a high barrier to entry.
- Compact Engine Integration:Designing and fitting high-performance water separation systems within the increasingly constrained space of modern engine compartments poses a significant engineering and packaging challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Water Separation Systems Market |
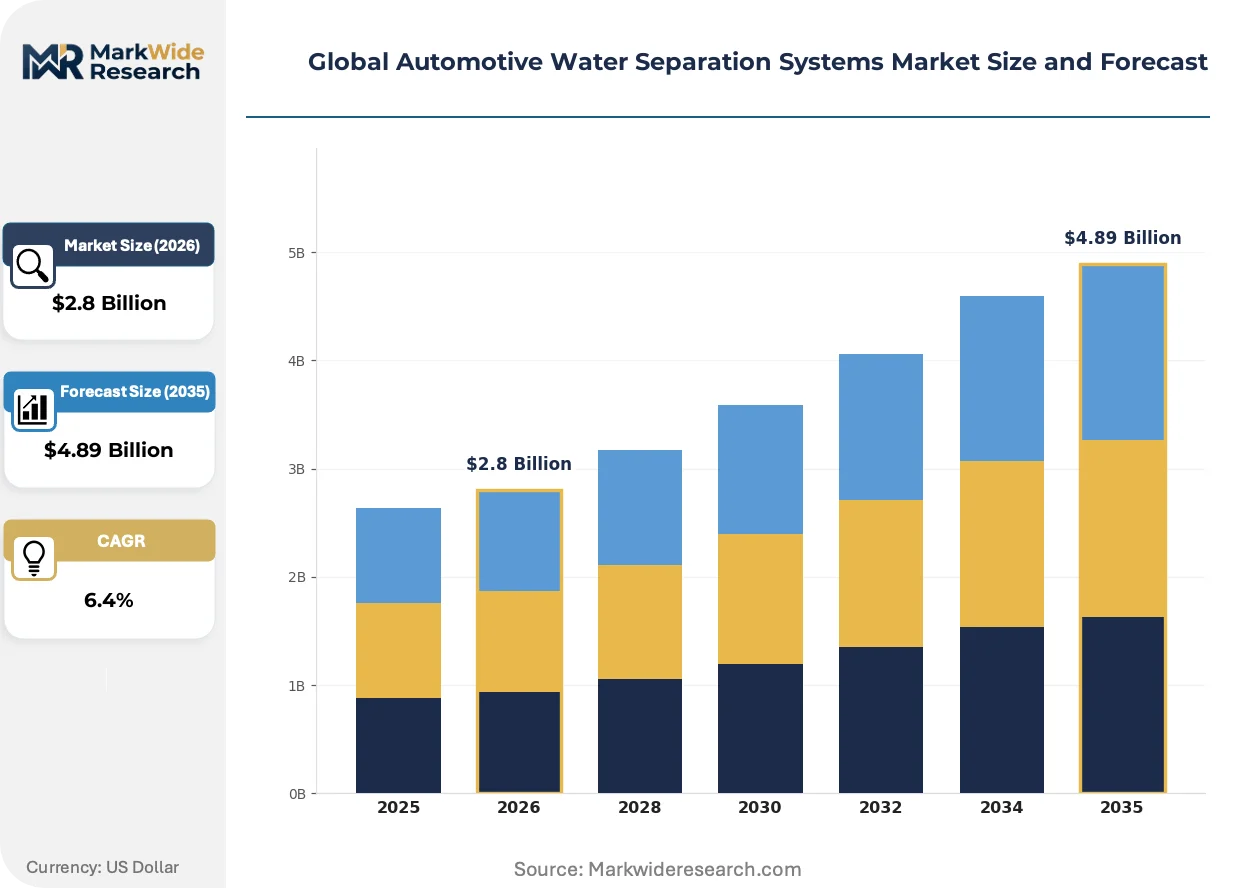
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Water Separators, Oil Water Separators, Air Water Separators, Coolant Water Separators Technology: Coalescing Filters, Centrifugal Separation, Membrane Filtration, Electrostatic Separation Application: Passenger Vehicles, Commercial Trucks, Off-Highway Equipment, Two-Wheelers End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | Parker Hannifin Corporation, Donaldson Company, Inc., MANN+HUMMEL Group, Bosch Group, MAHLE GmbH, Cummins Inc., Hengst SE, UFI Filters, Sogefi SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Water Separation Systems Market Strategic Shifts & Innovations
The convergence of advanced material science and digital sensor technology is redefining filtration performance and maintenance protocols. This shift moves the market from a focus on simple component replacement toward integrated, intelligent systems that actively manage fuel quality and vehicle uptime.
Multi-layer, gradient-density synthetic media combines several filtration functions, such as particulate capture and water coalescing, into a single, compact element. Commercial truck and off-highway equipment manufacturers are adopting this technology to reduce system complexity and extend service intervals. This integration of functions into a single component is collapsing the physical and functional separation between pre-filters, primary filters, and water separators.
Europe’s Euro 7 emission standard imposes stringent new limits on engine pollutants, compelling manufacturers to ensure optimal combustion. This regulation directly increases the need for highly efficient water separation to protect injectors from corrosion and wear, which can degrade fuel atomization and increase emissions. The heavy-duty commercial vehicle segment, which operates under tight uptime and emission controls, is most affected by this legislative pressure.
Fleet operators are modifying procurement patterns, moving from transactional purchases of replacement filters to service agreements that bundle components with predictive analytics. This model disrupts the traditional aftermarket distribution channel by prioritizing total cost of ownership and guaranteed vehicle uptime over individual part costs. The trend is most visible in North American and European logistics fleets where asset utilization is a critical performance metric.
Global Automotive Water Separation Systems Market Segmentation
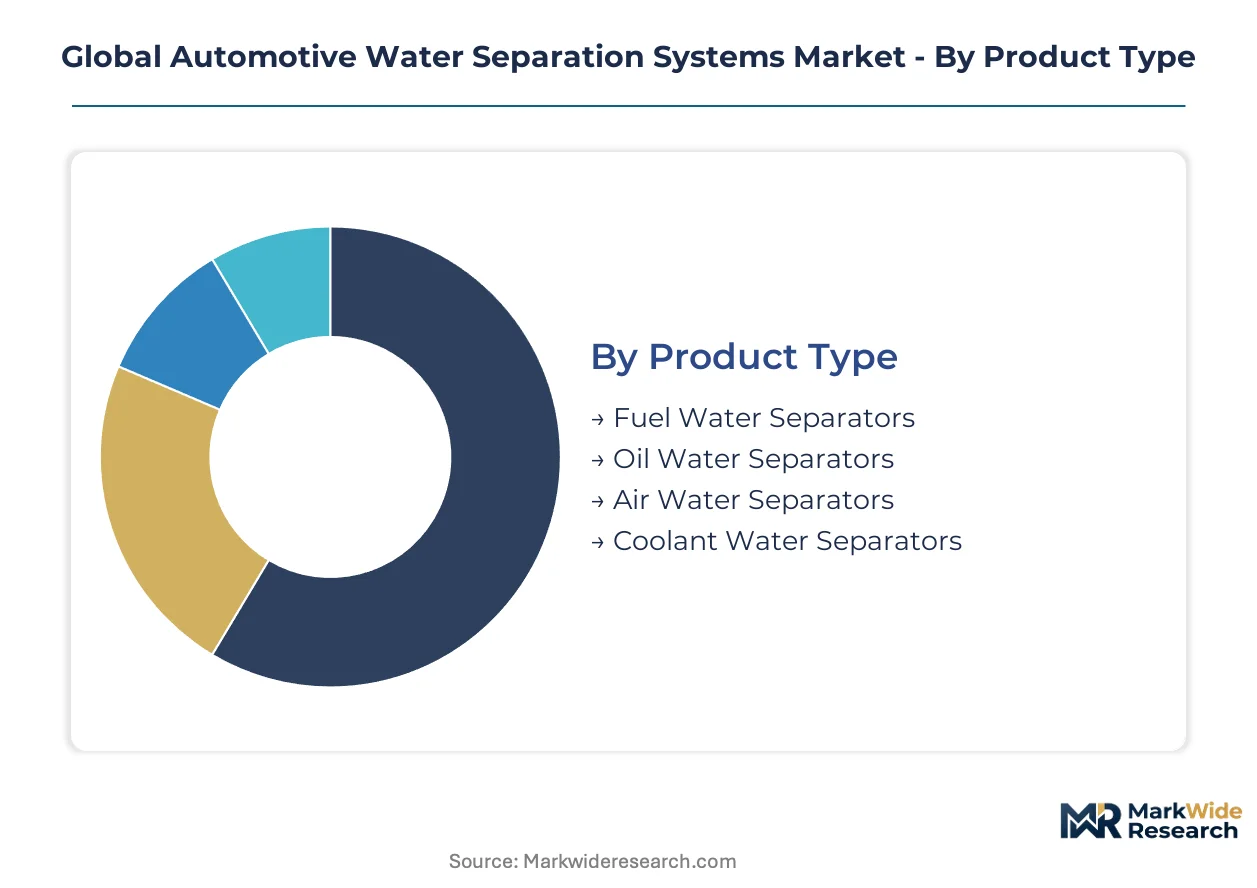
The automotive water separation systems market is structured by distinct product types, underlying technologies, diverse applications, and varied end-user segments. Understanding these classifications reveals the specific demands for engine protection and filtration efficiency across the global automotive industry. This granular view helps identify key growth vectors.
Product Type:
The maturity spectrum of water separation product types highlights established solutions alongside niche applications.
- Fuel Water Separators:These systems remove free and emulsified water from diesel and gasoline, protecting sensitive high-pressure common rail injectors from corrosion and wear. Demand concentrates in commercial trucks and off-highway equipment due to stringent uptime requirements and emission regulations.
- Oil Water Separators:Designed to separate water from engine lubricating oils, these components prevent oil degradation and maintain optimal engine performance. The off-highway equipment sector drives significant demand, where robust engine protection is critical for heavy machinery operation.
- Air Water Separators:These devices extract moisture from compressed air systems, crucial for air brakes and pneumatic controls in heavy-duty vehicles.
- Coolant Water Separators:Specialized units ensure the purity of engine coolant, preventing corrosion and cavitation within the cooling system.
Fuel Water Separators handle the majority of throughput; Oil Water Separators are the fastest mover on share.
Technology:
Supply concentration for water separation technologies reflects the dominance of proven methods alongside the emergence of advanced filtration.
- Coalescing Filters:These filters utilize specialized media to aggregate small water droplets into larger ones, which then separate by gravity from the fuel or oil. This technology dominates the market due to its high efficiency and effectiveness in protecting high-pressure common rail systems.
- Centrifugal Separation:This method employs rotational force to separate water from fuel or oil based on density differences, often used as a pre-filter or in conjunction with other technologies. Commercial trucks utilize these systems for robust primary separation in demanding operational environments.
- Membrane Filtration:Advanced membrane technologies offer ultra-fine separation capabilities, removing even sub-micron water droplets and particulate matter.
- Electrostatic Separation:This technology uses an electrostatic field to coalesce and separate water from non-conductive fluids, finding application in specialized industrial settings.
Coalescing Filters maintain significant market volume; Membrane Filtration exhibits the steepest expansion trajectory.
Application:
The application of automotive water separation systems spans diverse vehicle types, each presenting unique operational demands and regulatory pressures.
- Commercial Trucks:This segment represents the largest application-based demand, driven by stringent uptime requirements and the need to protect advanced diesel engines from fuel contamination. Regulations like Europe's Euro 7 directly impact filtration needs for these heavy-duty vehicles.
- Off-Highway Equipment:Construction, agricultural, and mining machinery require robust water separation systems to ensure reliability and longevity in harsh operating conditions. The demanding environments often necessitate superior filtration performance to prevent costly downtime.
- Passenger Vehicles:Modern passenger cars increasingly incorporate water separation, especially those with diesel engines or advanced gasoline direct injection systems.
- Two-Wheelers:This segment primarily includes motorcycles and scooters, where simpler fuel filtration is typically sufficient, though advanced models may integrate basic water separation.
Commercial Trucks account for the largest demand volume; Off-Highway Equipment is gaining share fastest due to operational intensity.
End User:
Customer type segmentation reveals how water separation systems flow through the automotive value chain, from initial manufacturing to ongoing maintenance.
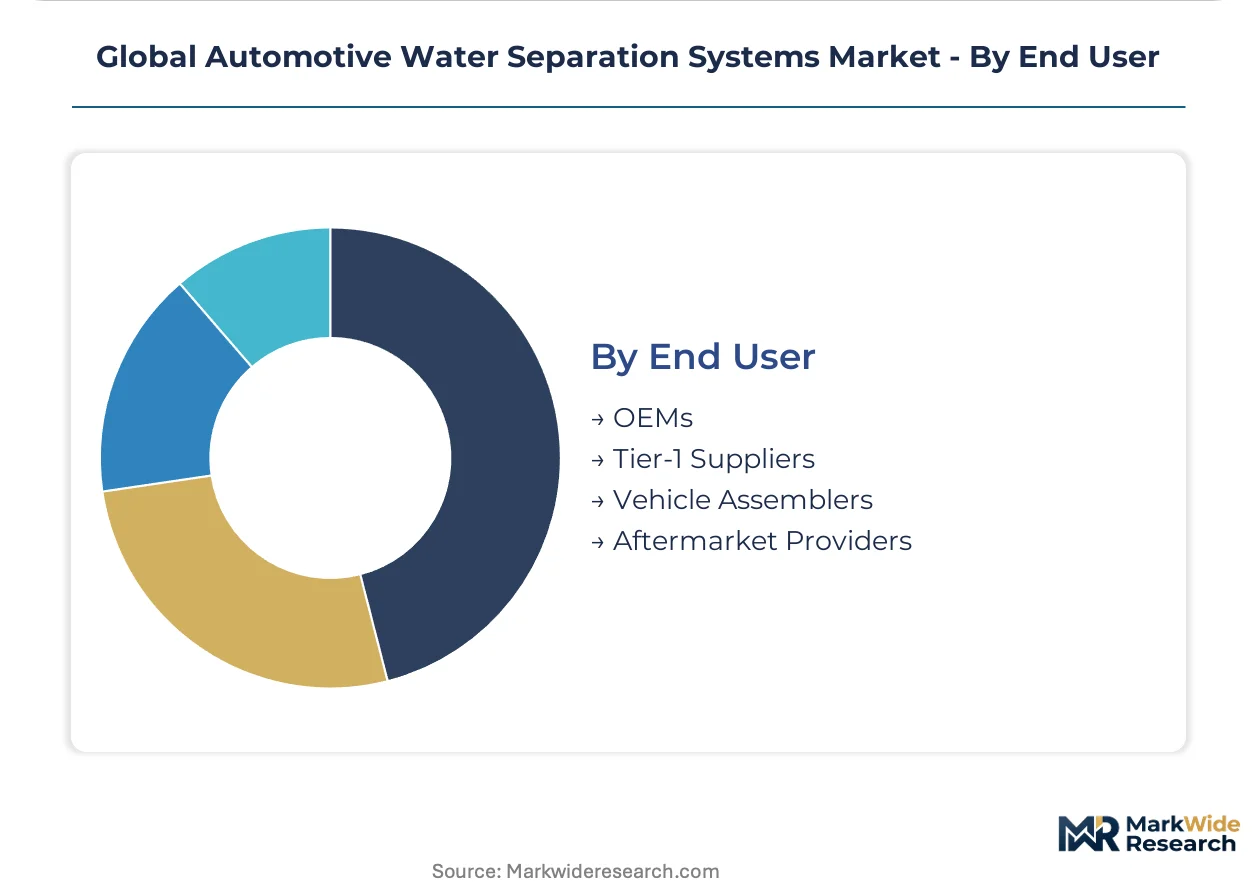
- OEMs:Original Equipment Manufacturers integrate water separation systems directly into new vehicles during the production phase, specifying components that meet their engine design and performance standards. This segment drives initial technology adoption and volume.
- Aftermarket Providers:These entities supply replacement water separation systems and filter media for vehicle maintenance and repair throughout the vehicle's operational lifespan. Fleet operators increasingly engage with aftermarket providers for predictive maintenance services.
- Tier-1 Suppliers:These companies develop and manufacture complex water separation modules and systems, supplying them directly to OEMs for vehicle assembly.
- Vehicle Assemblers:These users primarily focus on the assembly of vehicles, integrating components sourced from various suppliers, including water separation systems.
OEMs dictate initial market specifications; Aftermarket Providers are crucial for sustained component demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The supply-side concentration for automotive water separation systems is shifting, driven by the geographic consolidation of commercial vehicle production. This dynamic creates specific demand patterns for advanced filtration components in key manufacturing hubs. Diverse regulatory landscapes and operational requirements shape regional market evolution for engine protection.
China
China's extensive commercial vehicle manufacturing sector drives substantial demand for water separation systems, ensuring engine longevity in logistics and construction fleets. The country's GB standards for vehicle emissions and materials necessitate compliant and efficient filtration solutions. Major automotive production centers like the Yangtze River Delta and Pearl River Delta are focal points for advanced component integration.
United States
Demand in the United States stems from its large off-highway equipment sector and stringent EPA emission mandates for heavy-duty trucks. These regulations compel the adoption of high-efficiency fuel filtration to protect sensitive engine components. Key industrial regions such as the Midwest and the Gulf Coast exhibit concentrated demand from construction and agricultural machinery operators.
Germany
Germany, a prominent automotive manufacturing hub, experiences demand for water separation systems due to its focus on premium commercial vehicles and forthcoming Euro 7 emission standards. These regulations require sophisticated filtration to maintain engine performance and minimize pollutants. Automotive clusters in Bavaria and Baden-Württemberg are centers for innovation and integration of advanced filtration technologies.
Poland
Poland's expanding role as an Eastern European automotive production hub, particularly for commercial vehicles, creates significant demand for filtration components. The country's integration into the EU regulatory framework, including future Euro 7 compliance, influences local manufacturing specifications. Production facilities in regions like Silesia and Greater Poland are increasing their output of filtration-equipped vehicles.
India
India's modernizing commercial vehicle fleet and evolving emission norms, such as Bharat Stage VI, are accelerating the need for effective water separation systems. The country's diverse operational environments, from urban logistics to rural agriculture, require robust engine protection. Automotive manufacturing zones in Tamil Nadu and Maharashtra are experiencing rising demand for high-performance filtration solutions.
Global Automotive Water Separation Systems Market Key Industry Players
Integrated engine component suppliers and specialized filtration manufacturers split the market for automotive water separation systems. The competitive structure features a mix of established global players and regional specialists. Manufacturers are increasingly engaging in capacity expansion and technology integration to meet evolving regulatory and performance demands.
Global industrial players like Donaldson Company, Inc. occupy a strong position in filtration solutions for heavy-duty commercial trucks and off-highway equipment. MANN+HUMMEL Group exemplifies a major OEM-focused specialist, leveraging extensive relationships to secure long-term supply contracts. MAHLE GmbH, with its integrated thermal and engine component expertise, represents a diversified supplier offering comprehensive engine system solutions.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Donaldson Company, Inc. |
| MANN+HUMMEL Group |
| Bosch Group |
| MAHLE GmbH |
| Cummins Inc. |
| Hengst SE |
| UFI Filters |
| Sogefi SpA |
| Others |
Cost & Logistics Intelligence
The China-Europe rail freight route's fluctuating costs influence component supply concentration and subsequent price differentiation for automotive water separation systems. These transit expenses impact the final product pricing across global markets.
Pricing Analysis
Europe's Euro 7 emission standard dictates the pricing tier structure for advanced automotive water separation systems. Contract-based long-term offtake agreements with OEMs define base pricing, with significant differentiation based on certification level for new engine platforms and volume scale. Cost compression in the aftermarket segment stems from material cost volatility in synthetic media and polymers. Aftermarket providers exhibit the highest price sensitivity, while OEMs prioritize performance and regulatory compliance.
Supply Chain Analysis
The availability of specialized synthetic coalescing filter media and high-grade polymers forms the upstream feedstock angle for water separation systems. Supply concentration for these components centers in China and Germany, with manufacturing hubs in Poland and the Czech Republic assembling final modules. Raw material cost volatility and diverging material compliance rules, like Europe's REACH and China's GB standards, create significant supply chain risk. Distribution runs through direct OEM integration and established aftermarket networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive water separation systems market presents a fragmentation opportunity, driven by the shift towards specialized filtration for alternative fuels. This demand-side evolution creates distinct niches for focused product development.
For Market Incumbents:Pre-empt the substitution risk from sophisticated onboard fuel quality monitoring systems by accelerating smart filtration system development. Consolidate market position through long-term OEM contracts, leveraging existing relationships for next-generation engine platforms. Invest in R&D for specialized water separation systems compatible with hydrogen fuel cells, mitigating threats from alternative powertrain shifts. Expand production capacity in Eastern European automotive hubs to optimize cost structures.
For New Entrants and Emerging Players:Underpenetrated commercial vehicle fleets in Southeast Asia offer a significant market entry point for water separation systems. Target the off-highway equipment segment in Latin American countries, where operational reliability demands robust filtration solutions. A go-to-market angle focused on localized service agreements, bundling components with predictive maintenance, will capture market share. This approach addresses the region's evolving filtration needs and less mature local supply chains.
For Investors and Strategic Acquirers:Europe's Euro 7 emission standards reshape the acquisition landscape for automotive water separation systems. The market demonstrates sustained long-term viability over the next decade, driven by the ongoing need for engine protection and cleaner combustion. Target specialized filtration technology providers with strong intellectual property in advanced coalescing media or integrated sensor systems. OEM adoption rates of hydrogen fuel cell or synthetic fuel powertrains serve as a critical signal to watch for future market shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces manufacturing complexity and cost for OEMs across diverse engine applications. |
| Advanced Media R&D Investment | Develops next-generation coalescing filters for Euro 7 compliance and emerging fuel types. |
| Smart Filtration System Integration | Provides real-time data to fleet operators, enabling predictive maintenance and uptime guarantees. |
| Geographic Manufacturing Footprint Expansion | Establishes local production in Southeast Asia to serve growing commercial vehicle fleets. |
| Long-term OEM Supply Contracts | Secures stable demand for MANN+HUMMEL Group's advanced filtration components from major vehicle manufacturers. |
Research Approach
A spread of perspectives from Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and fleet operators converged on the working assumptions for this analysis. Primary interviews with these industry stakeholders were rigorously cross-referenced with secondary validation from vehicle production databases, IHS Markit registration data, and customs/trade statistics. This approach combined bottom-up market sizing with top-down industry trend analysis.
The demand-supply-balance framing informed the analytical framework across the projection horizon for automotive water separation systems. Volume and value outputs reflected a triangulated approach, modeling segmentation by product type, technology, application, end-user, and regional regulatory cluster. Compound annual growth rates were derived from historical trends and projected adoption rates of high-pressure common rail engines. Emission standard compliance timelines served as a key industry-specific forecast input.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated engine component suppliers or specialized filtration manufacturers would shift outcomes. This analysis reflects assumptions on regulatory stability and material science advancements. Cross-checking against OEM R&D roadmaps is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Solenoid Market
Automotive Components
Torque Vectoring Market
Automotive Components
Automotive Differential Market
Automotive Components
France Automotive Electric Actuators Market
Automotive Components
Automotive Exhaust Emission Control Device Market
Automotive Components
Regenerative Suspension System Market
Automotive Components
Automotive Spark Plug Market
Automotive Components
Automotive Exhaust Silencer Market
Automotive Components
Global Automotive Mats Market
Automotive Components
Global Automotive Brake Components Market
Automotive Components
Automotive Air Intake Manifold Market
Automotive Components
Automotive Key Market
Automotive Components
Saudi Arabia Automotive Actuators Market
Automotive Components
Automotive Axle Market
Automotive Components
Beryllium Copper for Automobile Market
Automotive Components
Global Automotive Components Forging Market