
 Japan Automotive Composites Market | 2026-2036
Japan Automotive Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Automotive Composites Market Foresight
Carbon fiber reinforced polymer manufacturing is fragmenting across multiple process technologies including resin transfer molding, sheet molding compound, and automated fiber placement. Toray Industries anchors Japan's upstream carbon fiber supply through captive precursor production. Mitsubishi Chemical Carbon Fiber and Composites differentiates via integrated compounding capabilities spanning PAN precursor to finished automotive parts. Teijin Limited specializes in thermoplastic composites for high-cycle automotive applications.
Japan automotive composites encompass fiber-reinforced polymer materials engineered for mass reduction in vehicle structures, typically achieving 50-70% weight savings versus steel counterparts while meeting JIS crashworthiness specifications. Carbon fiber products command premium positioning in structural parts and chassis applications where specific strength requirements justify material costs. Glass fiber segments dominate body panels and interior components based on cost-performance balance and established OEM qualification pathways. Hybrid composites represent the fastest-growing product category as Tier-1 Suppliers blend carbon and glass fibers to optimize price-performance for electric vehicle platforms.
METI enforces dual carbon goals through industrial decarbonization roadmaps that mandate recycled carbon fiber content in automotive applications. JIS standards and PMDA material certifications shape product qualification timelines and barrier-to-entry dynamics for new composite formulations. The country's national automotive regulator and METI coordinate on end-of-life vehicle directives affecting composite recyclability requirements. Stakeholders must monitor evolving OEM lightweighting targets against scrap carbon fiber recovery economics to calibrate capacity commitments.
Market Dynamics
Japan's automotive composites sector operates under the structural tension between METI's recycled carbon fiber mandates and the cost economics of virgin material substitution. Tier-1 suppliers face compressed qualification timelines as OEMs accelerate electric vehicle platform rollouts requiring lightweight structural components.
Growth Catalysts
- Electric vehicle platform expansion:Nissan and Toyota are redesigning chassis architectures around carbon fiber reinforced polymer subframes, creating pull-through demand for high-strength lightweight materials in battery enclosure applications.
- METI's industrial decarbonization roadmap:Mandatory recycled carbon fiber content thresholds in automotive applications are forcing material substitution away from conventional metals toward qualified composite formulations.
- Aichi Prefecture manufacturing corridor concentration:Proximity between Toray Industries' precursor facilities and Toyota City's assembly plants reduces logistics friction and accelerates prototype-to-production cycles.
Market Restraints
- Acrylonitrile price volatility:PAN precursor production consumes petroleum-derived feedstocks, exposing carbon fiber manufacturers to input cost swings that compress margin structures at the compounder level.
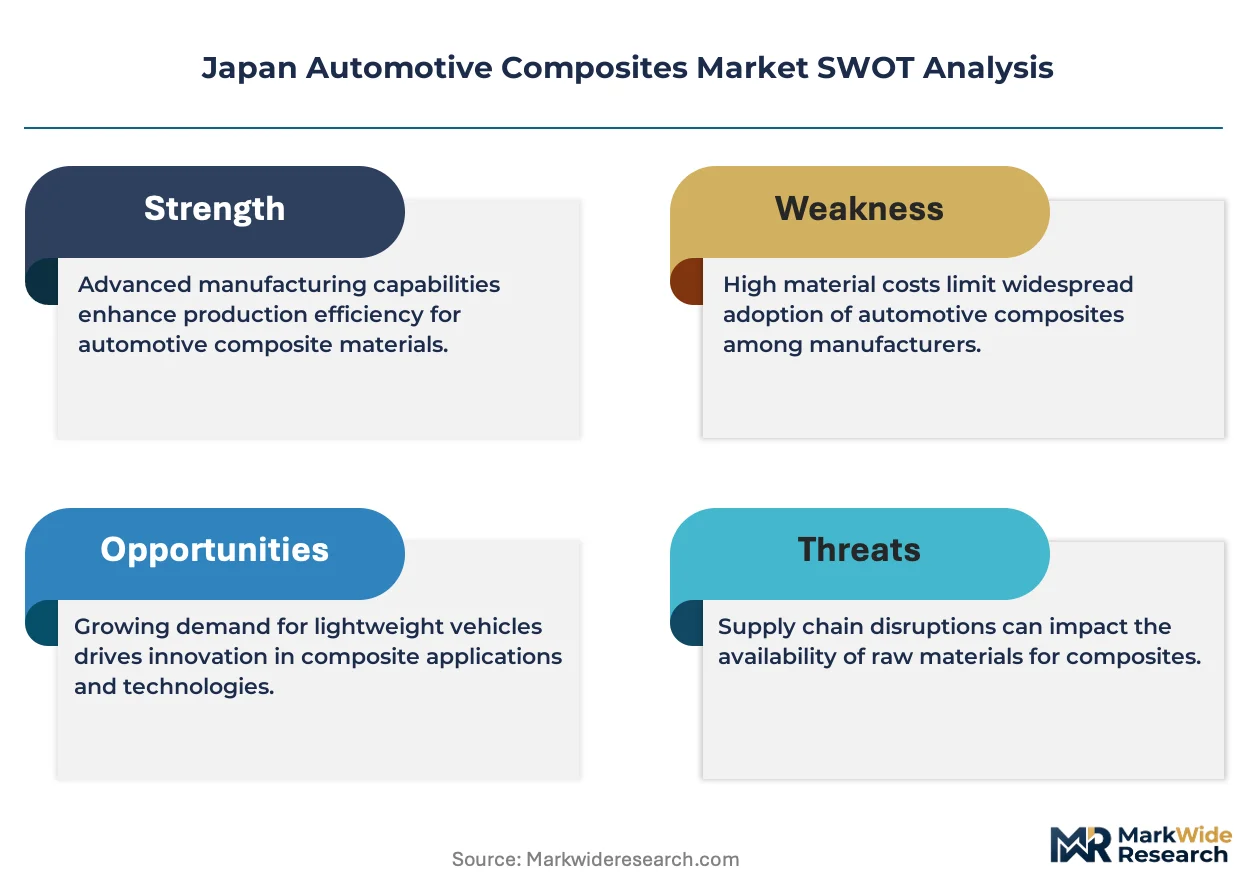
- Single-source precursor dependency:Japan's carbon fiber supply chain concentrates around three domestic precursor producers, creating concentration risk for Tier-1 suppliers qualifying alternative material streams.
- JIS crashworthiness certification timelines:Extended validation protocols for new composite formulations delay OEM adoption decisions and extend payback periods for R&D investments.
Strategic Opportunities
- Kyushu electric vehicle manufacturing hub:Emerging battery and EV assembly investments in Fukuoka and Oita prefectures create geographic white space for composite part suppliers outside the saturated Aichi corridor.
- Thermoplastic composite recycling infrastructure:METI's end-of-life vehicle directives incentivize closed-loop material recovery systems, enabling compounders to capture value from scrap fiber streams.
- Automated fiber placement and resin transfer molding convergence:Hybrid process technologies are reducing cycle times for structural automotive parts, opening mid-volume EV platform opportunities previously reserved for metal stamping.
Industry Challenges
- Composite design engineering talent scarcity:Japanese universities produce insufficient graduates with combined materials science and automotive structural simulation expertise, forcing manufacturers to recruit from aerospace sectors.
- Multi-material joining certification complexity:OEMs require extensive validation of adhesive and mechanical fastening protocols for carbon fiber-to-aluminum and carbon fiber-to-steel interfaces, extending development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Automotive Composites Market |
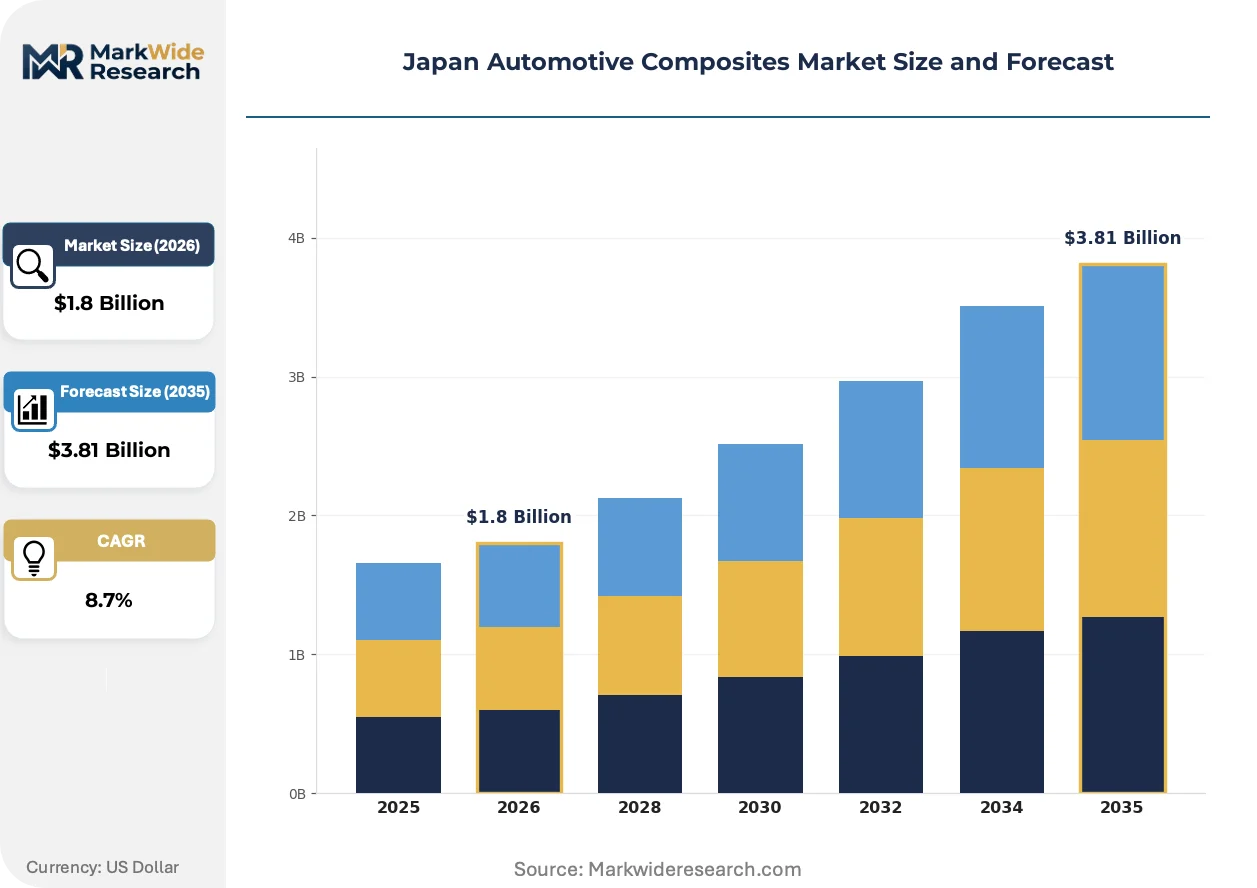
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Fiber, Glass Fiber, Natural Fiber, Hybrid Composites End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Body Panels, Interior Components, Structural Parts, Chassis Manufacturing Stage: Design, Production, Quality Control, Assembly |
| Companies Covered | Toray Industries, Mitsubishi Chemical Carbon Fiber and Composites, SGL Carbon, Teijin Limited, Hexcel Corporation, BASF, Owens Corning, Nippon Electric Glass, Solvay, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Automotive Composites Market Shifts & Advancements
Process automation and material formulation advances are compressing the cost-performance gap between carbon fiber composites and high-strength steel alloys. Japanese suppliers are repositioning around hybrid material strategies that balance structural performance with end-of-life recyclability requirements.
Carbon fiber sheet molding compound technology is hybridizing across multiple automotive applications. Tier-1 suppliers are adopting hybrid carbon-glass fiber formulations for battery enclosures and structural reinforcements. This material convergence is enabling price-performance positioning that captures mid-tier EV platforms previously excluded from carbon fiber qualification.
METI's carbon fiber recycling mandates are reshaping compounder business models toward circular material flows. The regulation requires automotive applications to incorporate specified percentages of recycled fiber content by designated phase-in dates. Hybrid composite suppliers with integrated scrap recovery capabilities are capturing preferential qualification status with cost-sensitive OEM purchasing departments.
Buyer concentration among Japan's domestic OEMs is compressing supplier negotiation leverage and accelerating long-term contract structures. Tier-1 composite part manufacturers are responding by locking in multi-year offtake agreements with precursor producers. This procurement pattern shift is most visible in Aichi Prefecture, where Toyota's purchasing consortium dominates composite component sourcing decisions.
Japan Automotive Composites Market Segmentation
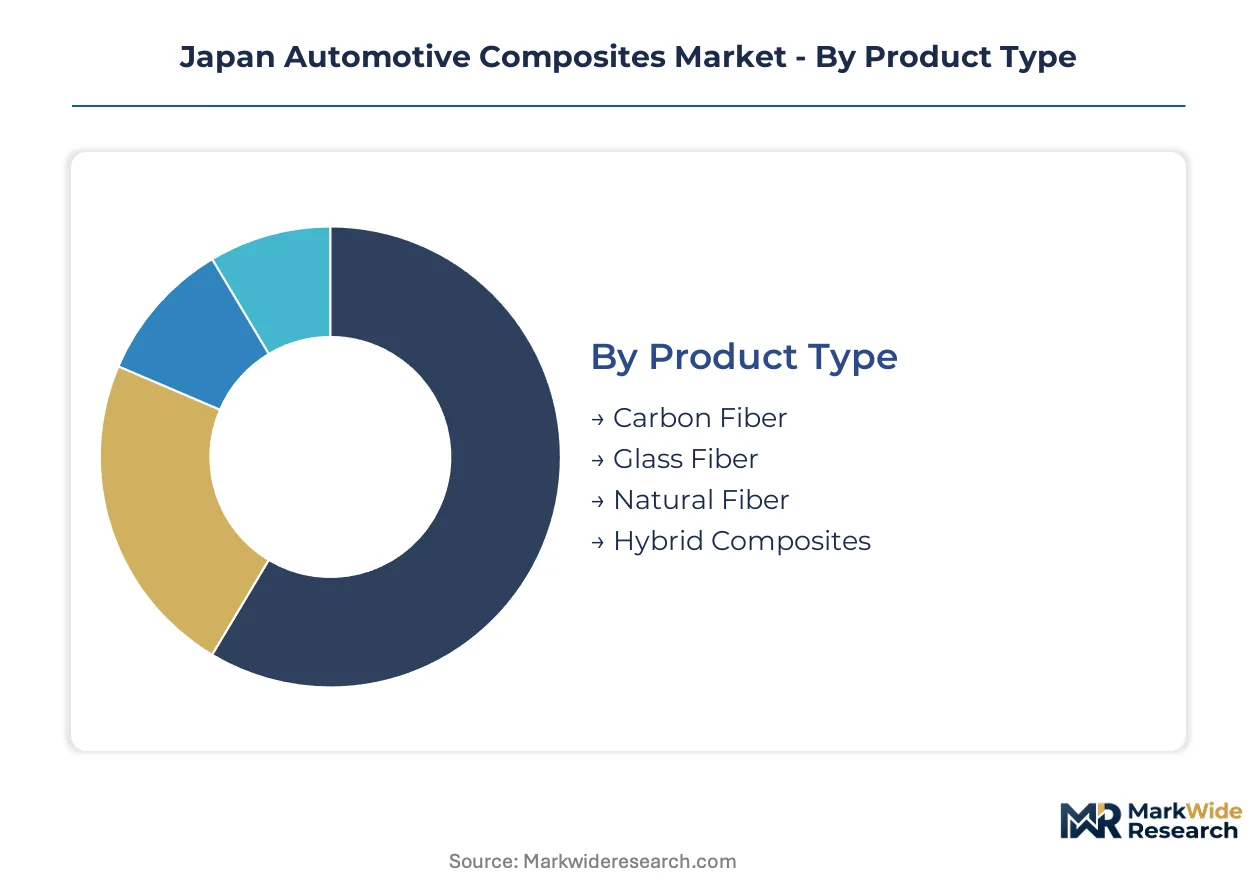
Material selection in Japan's automotive composites sector hinges on balancing JIS crashworthiness mandates against electric vehicle lightweighting economics. Segmentation reveals how suppliers calibrate fiber formulations and manufacturing stages to capture platform-specific qualification pathways.
Product Type:
Cost tier positioning determines fiber selection across battery enclosure and structural applications, with premium grades commanding OEM qualification advantages.
- Carbon Fiber:High-modulus PAN-based reinforcements achieve 50-70% weight reduction versus steel in chassis subframes. Demand concentrates in Toyota and Nissan electric vehicle platforms where specific strength requirements offset virgin material premiums.
- Hybrid Composites:Blended carbon-glass fiber formulations optimize price-performance for mid-tier battery enclosures. The steepest expansion runs through this segment as METI recycling mandates and OEM cost targets converge.
- Glass Fiber:E-glass and S-glass reinforcements dominate body panels and interior components based on established qualification pathways and compounder familiarity.
- Natural Fiber:Flax and hemp-based biocomposites serve non-structural interior applications where sustainability credentials drive specification decisions.
Carbon fiber commands the established base. The steepest expansion runs through hybrid composites.
End User:
Customer type segmentation reflects procurement authority concentration and technical specification control across Japan's tiered automotive supply chain.
- OEMs:Toyota, Nissan, and Honda purchasing consortia directly specify composite formulations for structural platforms, locking in multi-year offtake agreements with Toray and Mitsubishi Chemical.
- Tier-1 Suppliers:Denso, Aisin, and Calsonic Kansei manage subsystem integration, translating OEM targets into resin transfer molding and automated fiber placement process parameters.
- Vehicle Assemblers:Contract manufacturers in Aichi and Kyushu execute final composite-to-metal joining operations under JIS certification protocols.
- Aftermarket Providers:Specialty shops serve restoration and performance modification segments with limited regulatory exposure compared to OEM channels.
OEMs command the established base. The steepest expansion runs through Tier-1 Suppliers.
Application:
Application segmentation tracks how load-bearing requirements and surface finish specifications distribute fiber technologies across vehicle architectures.
- Structural Parts:Carbon fiber reinforced polymer subframes and crash structures absorb impact energy while reducing mass. Demand concentrates in battery electric platforms where range optimization justifies material substitution economics.
- Chassis:Suspension components and underbody shields require fatigue resistance and corrosion immunity that hybrid composites deliver at intermediate cost points.
- Body Panels:Hoods, roofs, and doors utilize glass fiber sheet molding compound for dent resistance and styling flexibility.
- Interior Components:Dashboard carriers, seat structures, and trim panels prioritize acoustic damping and design freedom over structural loading.
Body panels command the established base. The steepest expansion runs through structural parts.
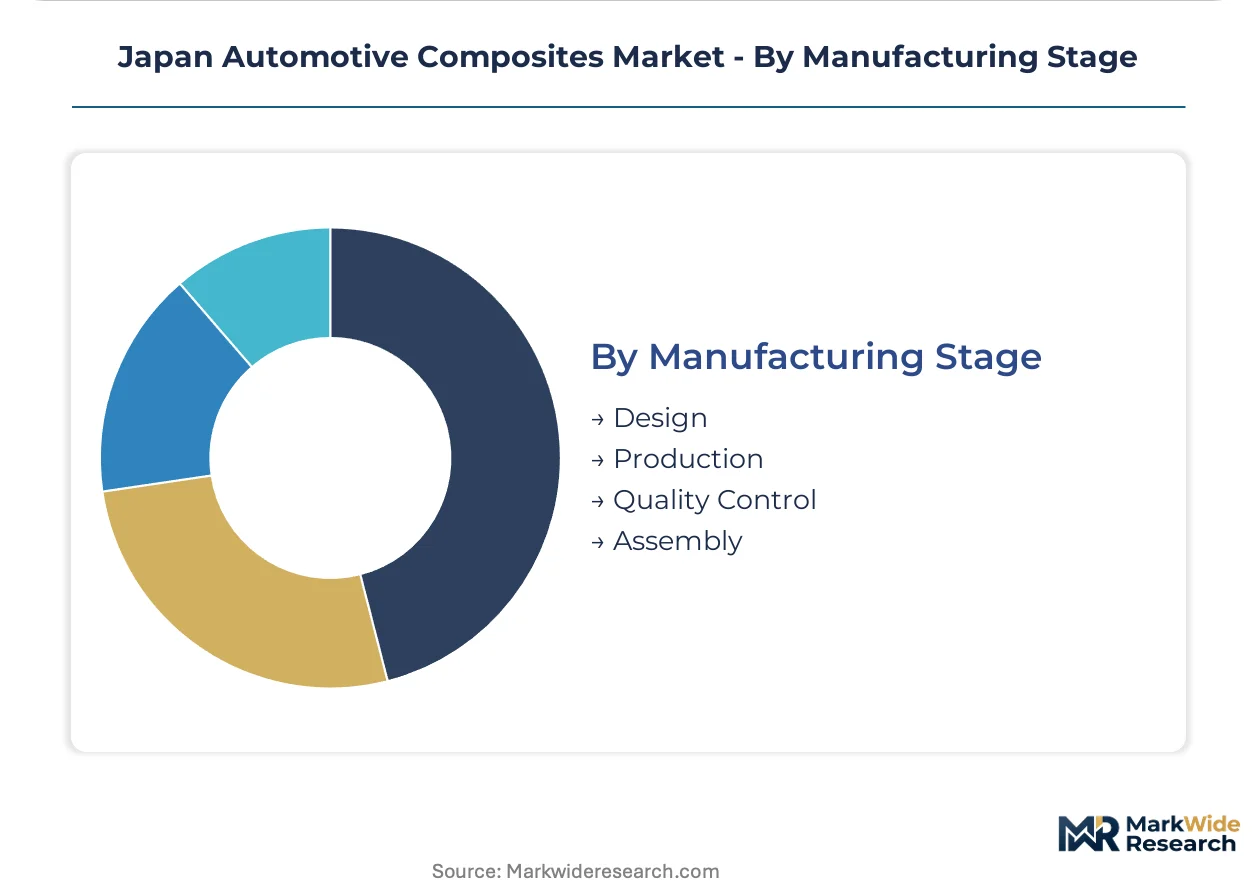
Manufacturing Stage:
Process maturity segmentation distinguishes where Japanese suppliers capture margin through technical differentiation versus commoditized execution.
- Production:Resin transfer molding and automated fiber placement cycles determine throughput economics for high-volume EV platforms. Toray's precursor supply integration with Aichi Prefecture compounders compresses lead times.
- Quality Control:Non-destructive testing and JIS certification validation extend timelines but lock in multi-year supply agreements with risk-averse OEM purchasing departments.
- Design:Topology optimization and multi-material joining simulation require scarce talent combining materials science with automotive structural expertise.
- Assembly:Adhesive bonding and mechanical fastening of composite-to-aluminum interfaces demand process control precision that differentiates qualified Tier-1 suppliers.
Production commands the established base. The steepest expansion runs through quality control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese OEM purchasing consortia concentrate procurement authority among Toyota, Nissan, and Honda, directing composite formulation specifications toward Aichi Prefecture suppliers and reshaping geographic production patterns across domestic manufacturing corridors.
Kanto/Tokyo
Corporate headquarters and R&D centers for Denso and Aisin drive specification-setting for hybrid composite formulations. METI's industrial decarbonization roadmap mandates recycled carbon fiber thresholds that compounders in this region must integrate into product development cycles. Research partnerships between Tokyo Institute of Technology and Toray Industries accelerate thermoplastic composite validation for high-cycle automotive applications.
Chubu/Nagoya
Toyota City's assembly plants and Toray's precursor facilities create the densest automotive composites ecosystem in Japan. JIS crashworthiness certification protocols administered through Nagoya-based testing laboratories compress qualification timelines for Tier-1 suppliers. The manufacturing corridor extending through Aichi Prefecture concentrates resin transfer molding capacity for battery enclosure production.
Kansai/Osaka
Mitsubishi Chemical's integrated compounding operations span PAN precursor through finished automotive parts from Osaka-area facilities. METI recycling mandates incentivize closed-loop scrap recovery systems that compounders in this region are constructing to capture value from end-of-life vehicle directives. Academic collaboration with Osaka University advances automated fiber placement process optimization.
Kyushu
Emerging battery and EV assembly investments in Fukuoka and Oita prefectures create geographic white space for composite part suppliers outside the saturated Aichi corridor. The national automotive regulator coordinates with prefectural authorities on industrial zone designation for carbon fiber recycling infrastructure. Nissan's expanding presence in Kyushu is pulling Tier-1 suppliers to establish satellite compounding operations.
Japan Automotive Composites Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Upstream precursor producers anchor supply security through captive raw material production. Midstream compounders differentiate via process technology integration spanning fiber placement to finished part qualification. Downstream Tier-1 subsystem integrators translate OEM lightweighting targets into manufacturing parameters. Capacity expansion and strategic partnerships represent the dominant competitive moves as electric vehicle platform rollouts compress development timelines.
Among Japanese upstream specialists, Toray Industries and Mitsubishi Chemical Carbon Fiber and Composites occupy positions that exemplify the integrated precursor-to-compound archetype. Teijin Limited represents the thermoplastic composite specialization vector targeting high-cycle automotive applications. These three anchors sit within a structure where backward integration into PAN precursor production determines margin capture and supply security for qualified automotive formulations.
| Leading Market Players |
|---|
| Toray Industries |
| Mitsubishi Chemical Carbon Fiber and Composites |
| SGL Carbon |
| Teijin Limited |
| Hexcel Corporation |
| BASF |
| Owens Corning |
| Nippon Electric Glass |
| Solvay |
| Others |
Supply & Pricing Matrix
Three domestic PAN precursor producers anchor Japan's carbon fiber supply chain, concentrating margin capture upstream while Tier-1 compounders absorb acrylonitrile cost volatility through indexed contract structures. This upstream oligopoly translates into asymmetric pricing power where Toray Industries and Mitsubishi Chemical dictate formulation premiums downstream.
Pricing Analysis
Cost-plus contracts with acrylonitrile indexation dominate procurement between precursor producers and automotive compounders. Price differentiation rests on JIS certification tier and volume scale, with crash-qualified structural grades commanding premiums over interior-grade formulations. Pricing pressure stems from OEM lightweighting mandates compressing Tier-1 margins, while battery enclosure specifications show least price sensitivity due to range-critical performance requirements.
Supply Chain Analysis
Extended payment terms from Toyota's purchasing consortium strain working capital for Aichi Prefecture compounders, accelerating supply-chain finance facility adoption. Raw material flows draw from petroleum-derived acrylonitrile, glass fiber from Nippon Electric Glass, and thermoplastic resins from domestic petrochemical complexes. Single-source precursor vulnerability concentrates risk around three domestic suppliers. Distribution runs through just-in-time delivery networks serving Nagoya and Toyota City assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's automotive composites sector sits in early-cycle expansion as electric vehicle platform rollouts accelerate carbon fiber adoption beyond aerospace heritage applications. METI's recycled content mandates create structural pull-through for qualified suppliers.
For Market Incumbents: Build captive precursor supply moats through backward integration into PAN production or long-term offtake agreements with Toray Industries. Defend qualification advantages by accelerating JIS crashworthiness certification for hybrid thermoplastic formulations before emerging compounders achieve validation. Lock in multi-year supply agreements with Nissan and Toyota purchasing consortia to preempt capacity allocation to new entrants. For New Entrants and Emerging Players: Pursue geographic white space in Kyushu's emerging battery manufacturing corridor where Nissan's expanding footprint lacks established composite supplier density. Target thermoplastic recycling infrastructure as METI's end-of-life vehicle directives create first-mover advantages for closed-loop scrap recovery capabilities. Anchor go-to-market strategy through automated fiber placement process partnerships with Fukuoka prefectural industrial zone authorities. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier compounders holding JIS certifications but lacking precursor integration. Five-to-ten year viability hinges on recycled fiber recovery economics aligning with OEM cost targets. Watch Nissan's Kyushu platform procurement decisions as inflection signal for geographic demand redistribution outside Aichi concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Toray's captive PAN supply secures margin capture and qualification priority with Toyota purchasing. |
| Thermoplastic Composite Recycling Infrastructure | METI's end-of-life directives enable compounders to monetize scrap fiber streams through closed-loop recovery. |
| Automated Fiber Placement Process Partnerships | Hybrid manufacturing technologies compress cycle times for mid-volume EV battery enclosure production. |
| Kyushu Manufacturing Footprint Expansion | Nissan's Fukuoka battery investments create geographic white space outside saturated Aichi supplier corridors. |
| JIS Crashworthiness Certification Acceleration | Extended validation protocols lock in multi-year supply agreements with risk-averse OEM procurement departments. |
Research Methodology
The analysis maps carbon fiber precursor supply, thermoplastic compounding, and automated fiber placement sub-sectors, each validated through procurement directors at Tier-1 suppliers, OEM platform engineers, and METI industrial policy officials. Primary interview findings triangulate against customs trade data for acrylonitrile and carbon fiber imports, vehicle production databases from IHS Markit, and JIS certification registry filings. Bottom-up volume estimates from compounder capacity and top-down demand calibration from OEM lightweighting targets converge through iterative reconciliation.
Forecast assumptions hold METI's recycled carbon fiber phase-in thresholds and Toyota-Nissan EV platform rollout schedules fixed across the projection horizon, while varying acrylonitrile price scenarios and JIS certification timeline compression. Segmentation dimensions span fiber type, manufacturing process, application load-bearing tier, and regional production cluster. CAGRs derive from elasticity modeling against vehicle production forecasts and content-per-vehicle penetration curves for structural composites.
Sensitivities concentrate around acrylonitrile price volatility, JIS certification timeline extensions, and OEM platform cancellation decisions. Forecasts reflect documented assumptions about regulatory enforcement consistency and precursor supply security. Macroeconomic contraction, regulatory delay, or breakthrough metal-alloy lightweighting would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Plastic Bumper Market
Automotive Components
India Passenger Vehicles Lubricants Market
Automotive Components
Australia Automotive Composites Market
Automotive Components
Automotive Skid Plate Market
Automotive Components
Automotive Buffers Market
Automotive Components
Advanced Automotive Materials Market
Automotive Components
South Korea Automotive Sunroof Market
Automotive Components
Automotive Front-End Module (FEM) Market
Automotive Components
Automotive Hubcaps Market
Automotive Components
Automotive Tailgate Market
Automotive Components
Europe Automotive Glass Market
Automotive Components
Automotive Solenoid Market
Automotive Components
Automotive Injector Nozzle Market
Automotive Components
Automotive Glass Market
Automotive Components
Iran Automotive Lubricants Market
Automotive Components
Automotive Polycarbonate Glazing Market