
 Automotive Cast Iron Cylinder Head Market | 2026-2036
Automotive Cast Iron Cylinder Head Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Cast Iron Cylinder Head Market Outlook
Aluminum is repositioning cast iron in passenger vehicle engine bays, yet iron retains cost and thermal fatigue advantages in heavy-duty cycles. Cummins Inc. anchors North American diesel cylinder head production through captive foundry networks. MAHLE GmbH differentiates via precision CNC machining capabilities that tighten combustion chamber tolerances. Nemak S.A.B. de C.V. competes across multiple metallurgy platforms while sustaining geographic diversification across the Americas.
An automotive cast iron cylinder head is a engine component cast from gray or compacted graphite iron alloys, typically featuring integrated valve seats, coolant jackets, and intake or exhaust ports, produced through sand casting or permanent mold processes with subsequent CNC machining to achieve surface finishes below Ra 3.2 micrometers for sealing interfaces. Its primary function is to seal the combustion chamber, support valvetrain components, and manage thermal loads in internal combustion engines. Passenger vehicle applications face substitution pressure from aluminum, while commercial vehicle and heavy machinery segments maintain iron dominance due to higher mechanical loads and longer service intervals. CNC Machining technology commands premium positioning as downstream OEMs tighten geometric dimensioning requirements for emissions-compliant engines.
EPA tailpipe standards and the EU F-Gas Regulation shape material choices and foundry emissions controls, forcing investment in electric melting and fume capture systems. China's MIIT enforces fuel consumption limits that indirectly pressure cylinder head weight reduction, though commercial vehicle exemptions preserve iron's relevance. India's BIS certification mandates metallurgical testing that filters out low-grade imports. Stakeholders must monitor regulatory divergence between passenger and commercial vehicle treatment, as this bifurcation determines which metallurgy platforms receive sustained engineering investment.
Market Dynamics
Commercial vehicle procurement cycles are elongating as fleet operators prioritize total cost of ownership over upfront acquisition cost, cementing cast iron's position in heavy-duty powertrains despite aluminum's encroachment into passenger segments. This divergence between light and heavy-duty material selection is forcing foundries to bifurcate their metallurgical capabilities rather than consolidate around a single alloy platform.
Growth Catalysts
- EU F-Gas Regulation:Stringent fluorinated gas controls are pressuring foundries to upgrade fume capture and electric melting systems, inadvertently favoring larger cast iron producers with capital reserves to absorb compliance costs.
- India's heavy-duty truck sector:BIS certification requirements for metallurgical testing are filtering low-grade imports and consolidating demand around domestic foundries with certified laboratory capabilities.
- Compacted graphite iron formulations:Advanced CGI alloys deliver 75% higher tensile strength than gray iron while retaining thermal fatigue resistance, opening displacement opportunities in high-boost diesel architectures.
Market Restraints
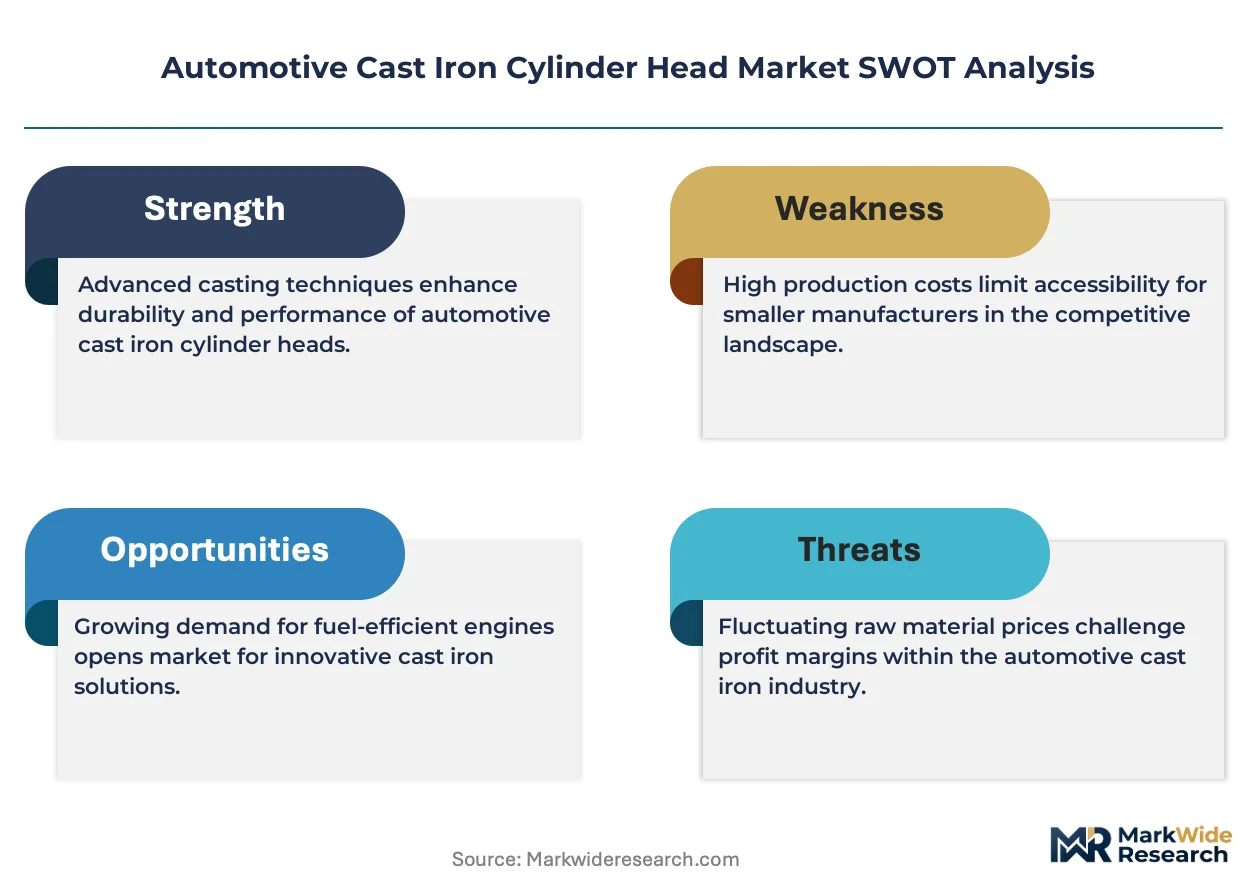
- Scrap iron price volatility:Ferrous scrap input costs swing with construction sector demolition cycles, compressing foundry margins during periods of tight secondary raw material supply.
- Aluminum substitution in passenger vehicles:OEM weight reduction mandates under China's MIIT fuel consumption limits are accelerating aluminum cylinder head adoption in light-duty gasoline engines.
- Foundry concentration in China's Hebei corridor:Environmental compliance crackdowns by MEE periodically shutter unlicensed capacity, creating supply shocks for export-dependent buyers.
Strategic Opportunities
- Aftermarket remanufacturing channels:Extended commercial vehicle service intervals are expanding demand for remanufactured cylinder heads with re-machined valve seats and renewed surface finishes.
- Hybrid powertrain thermal management:Cast iron's thermal mass properties suit range-extender engines in plug-in hybrid commercial vehicles, creating a bridge application during electrification transition.
- Brazil's ANVISA-aligned foundry modernization:Import substitution incentives for heavy machinery production are stimulating local cast iron capacity expansion for agricultural and mining equipment.
Industry Challenges
- CNC programming talent scarcity:Precision machining of complex combustion chamber geometries requires specialized five-axis programming expertise that outpaces vocational training pipeline output.
- Emissions certification timelines:EPA and EU type-approval processes for revised metallurgical formulations extend product development cycles by 18-24 months versus historical baselines.
- Legacy sand casting integration:Foundries must maintain conventional green sand lines for commercial vehicle volume while investing in permanent mold automation for emerging CGI applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Cast Iron Cylinder Head Market |
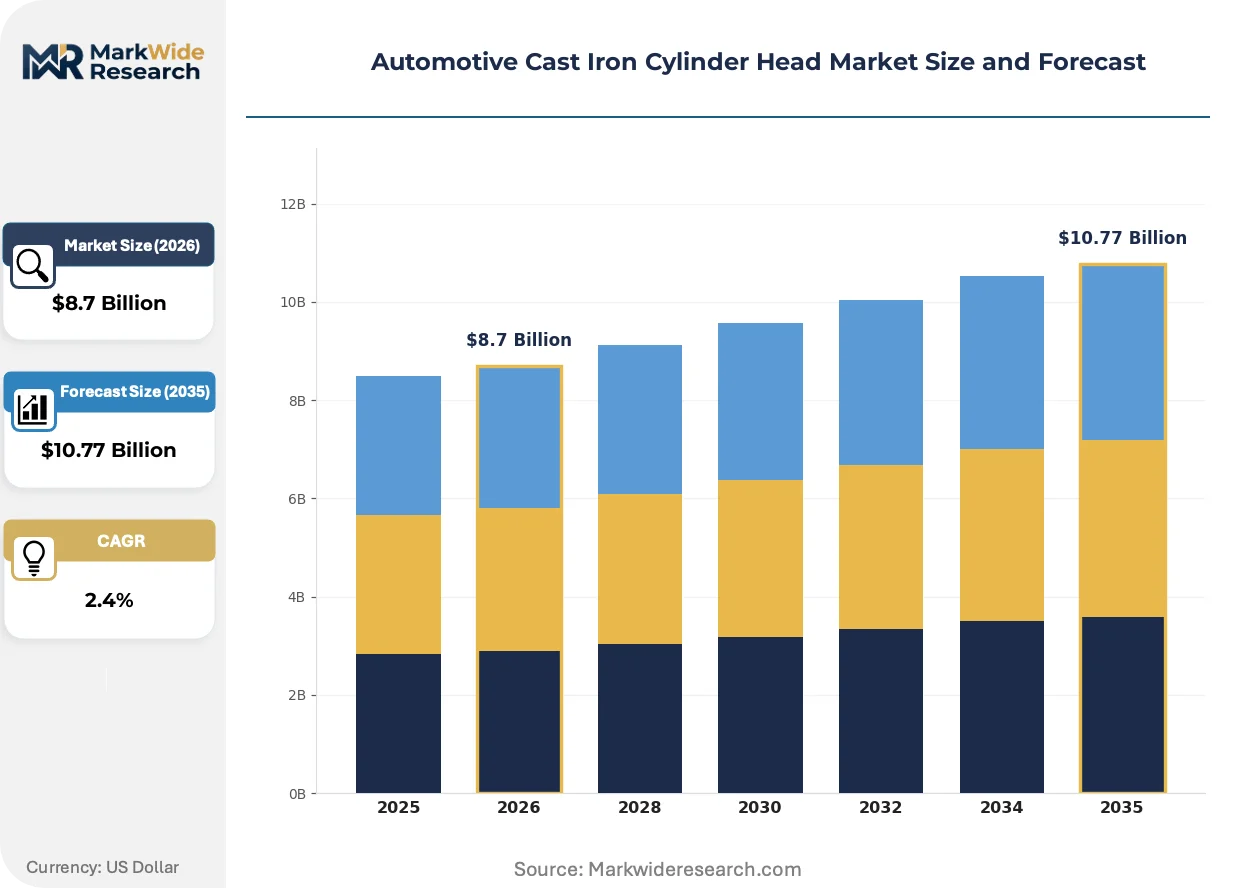
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $10.77 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inline, V-Type, Flathead, OHV Engine Size: Small Block, Big Block, Diesel, Modular Application: Passenger Vehicles, Commercial Vehicles, Heavy Machinery, High-Performance Engines Technology: Casting, CNC Machining, Surface Treatment, Thermal Coating |
| Companies Covered | Nemak S.A.B. de C.V., Linamar Corporation, Toyota Industries Corporation, Yamaha Motor Co., Ltd., Cummins Inc., Sandvik Coromant, MAHLE GmbH, Teksid S.p.A, Edelbrock LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Cast Iron Cylinder Head Market Strategic Shifts
Thermal management demands from downsized boosted engines are accelerating metallurgical innovation cycles, while regulatory pressure on foundry emissions is reshaping capital deployment patterns across the supplier base.
Compacted graphite iron is electrifying heavy-duty diesel thermal strategies by delivering superior strength-to-weight ratios than conventional gray iron while maintaining the fatigue resistance critical for high-peak cylinder pressures. European commercial vehicle OEMs are adopting CGI for their next-generation 13-liter platforms, with procurement volumes accelerating as validation cycles complete. This alloy transition is compressing the addressable market for legacy gray iron formulations in the highest-load applications.
REACH authorization requirements for nickel and cobalt compounds are forcing reformulation of certain high-performance iron alloys used in valve seat inserts and exhaust port reinforcements. Foundries serving EU-registered vehicle programs must document substance volume thresholds and substitution feasibility assessments under extended SCIP database obligations. Passenger vehicle suppliers face the tightest compliance timelines, while commercial vehicle exemptions under Stage V transition provisions offer temporary relief.
Fleet procurement departments are consolidating supplier relationships around foundries offering integrated machining and thermal coating capabilities, displacing pure casting houses from Tier 1 qualification lists. This consolidation concentrates volume among vertically capable suppliers in India's Chennai-Pune corridor and China's Yangtze River manufacturing belt. The shift is most pronounced in long-haul trucking segments where single-source accountability for casting defects and machining dimensional drift reduces warranty exposure.
Automotive Cast Iron Cylinder Head Market Segmentation
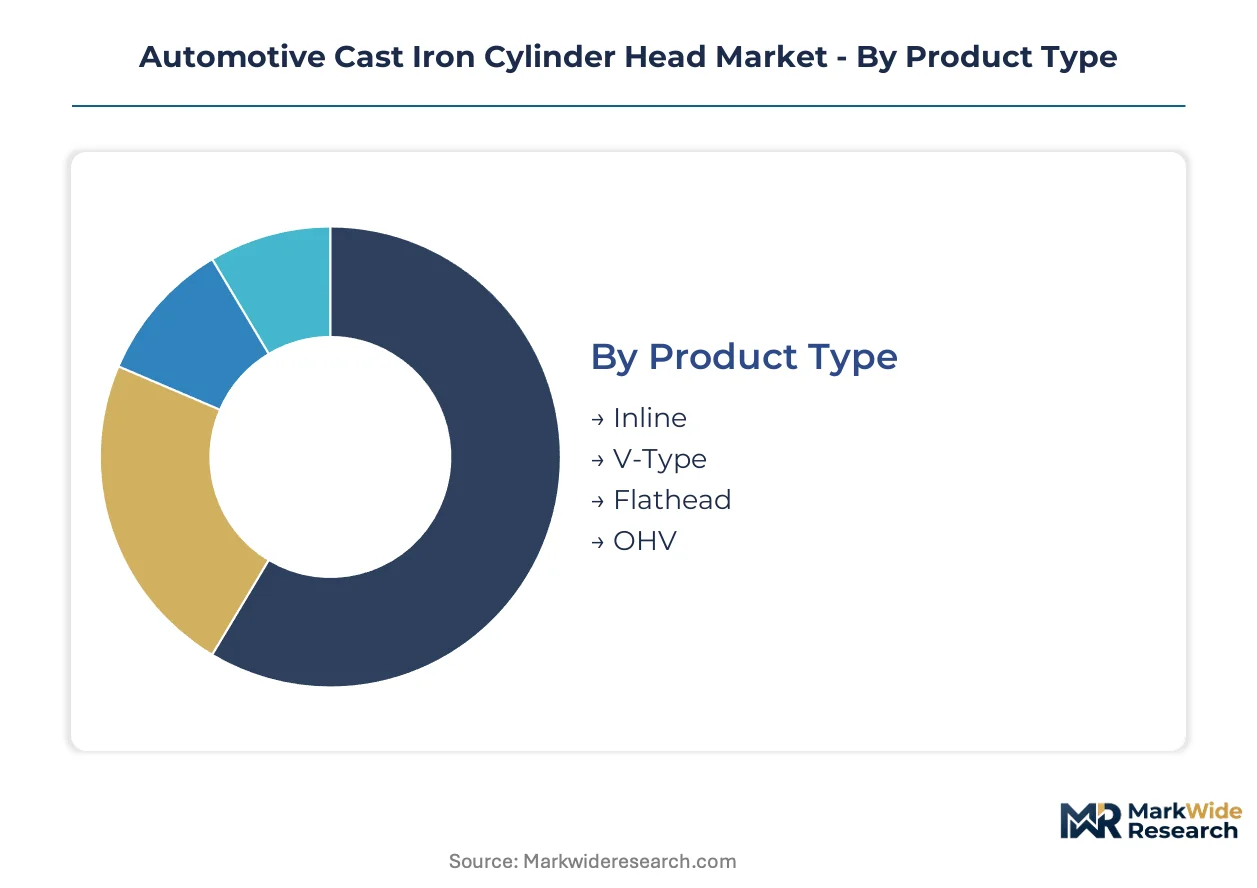
Cast iron cylinder head procurement patterns diverge sharply between replacement cycles and new powertrain architectures. Fleet operators prioritize thermal durability and remanufacturability, while OEMs weigh metallurgical compliance against lightweighting mandates.
Product Type:
Upgrade cycles favor designs that accommodate higher combustion pressures without valvetrain geometry changes.
- Inline:Single-row valve arrangements dominate commercial vehicle diesel architectures up to six cylinders. India's heavy-duty truck sector sources these configurations for their serviceability and lower remanufacturing cost.
- V-Type:Angled cylinder banks accommodate larger displacement in constrained engine bay envelopes. Cummins and Navistar specify V-configurations for their 15-liter platforms where thermal load distribution favors cast iron over aluminum alternatives.
- Flathead:Obsolete for modern emissions-compliant engines but persists in aftermarket remanufacturing channels for legacy agricultural equipment.
- OHV:Pushrod-operated valvetrains retain cost advantage in price-sensitive commercial segments. Brazil's agricultural machinery producers specify OHV heads for their repairability in remote operating environments.
Inline configurations sit at the top of the volume ranking, with V-Type climbing the fastest as European OEMs adopt CGI alloys for high-boost diesel architectures.
Engine Size:
Displacement categories map directly to duty cycle severity and thermal management requirements.
- Small Block:Compact V8 and V6 architectures under 6.0 liters face the steepest aluminum substitution pressure in passenger applications. China's MIIT fuel consumption limits accelerate this displacement in light-duty gasoline engines.
- Big Block:Large-displacement V8 platforms above 6.0 liters retain iron dominance for towing and motorhome applications. North American chassis cab producers specify these heads for their fatigue resistance under sustained high-load operation.
- Diesel:Compression-ignition architectures from 2.0 to 16.0 liters constitute the core revenue base. EPA and EU Stage V emissions compliance drives precision machining investment for combustion chamber sealing.
- Modular:Scalable bore spacing architectures allow foundry flexibility across displacement variants. Nemak and MAHLE have consolidated procurement around modular platforms to amortize tooling investment across multiple OEM programs.
Diesel heads command the highest unit margins, with Modular platforms expanding most quickly as foundries seek volume aggregation.
Application:
End-use segmentation reveals the bifurcation between lightweighting imperatives and total cost of ownership logic.
- Passenger Vehicles:Sedan and SUV gasoline engines face regulatory pressure for mass reduction. China's dual carbon goals and EU fleet CO2 targets accelerate aluminum migration in this segment.
- Commercial Vehicles:Class 4-8 trucks and buses preserve iron's relevance through extended service intervals. Fleet operators in India's Chennai-Pune corridor specify cast iron for its thermal durability under sustained highway cruise conditions.
- Heavy Machinery:Mining and construction equipment subjects cylinder heads to shock loading and contaminated intake air. Brazil's ANVISA-aligned foundry modernization supports local capacity for this severe-duty segment.
- High-Performance Engines:Racing and aftermarket applications demand CNC-machined combustion chambers with surface finishes below Ra 1.6 micrometers. Limited volume but premium pricing sustains specialized foundry operations in Germany's Baden-Württemberg region.
Commercial Vehicles generate the largest absolute volume, with Heavy Machinery gaining share fastest as mining capital expenditure recovers.
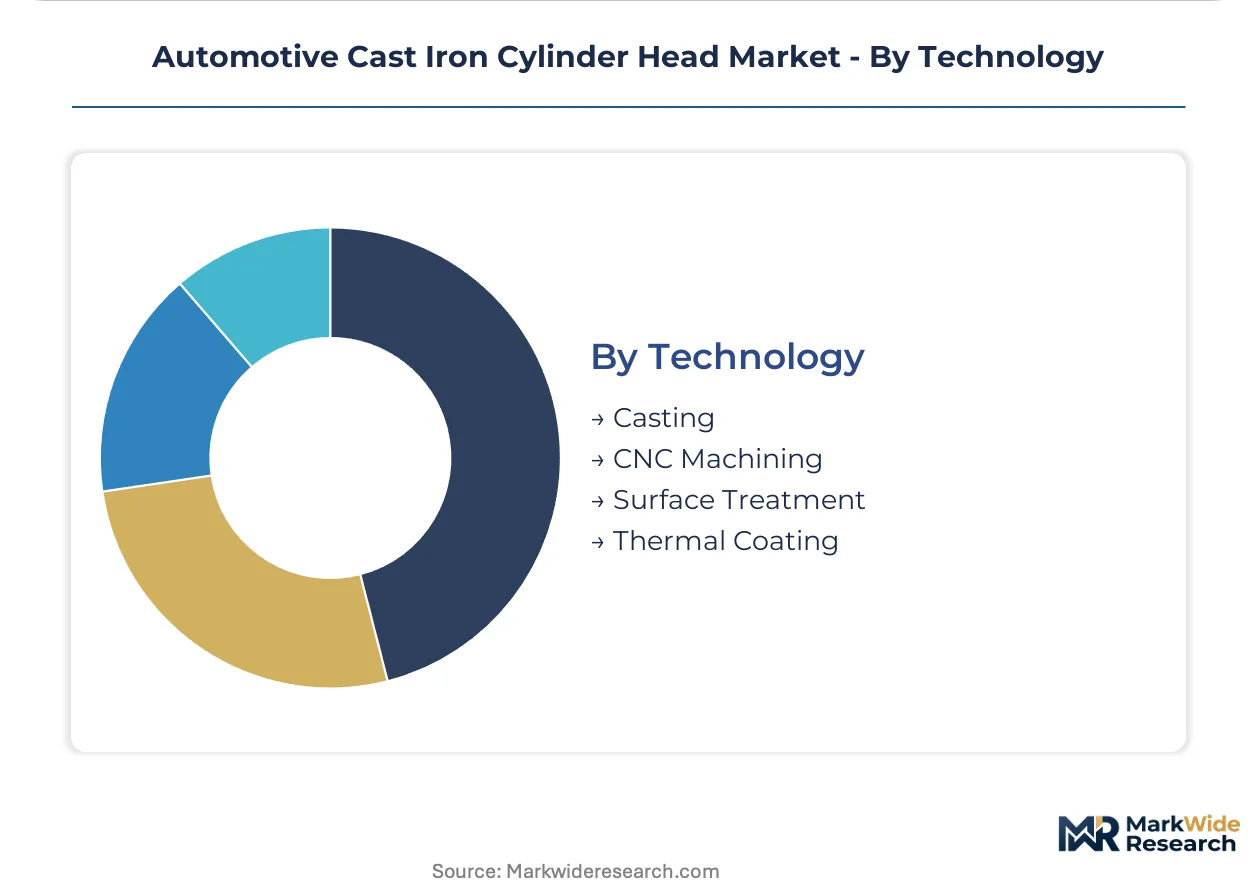
Technology:
Process capabilities determine qualification for Tier 1 supplier lists and emissions-critical applications.
- Casting:Green sand and permanent mold processes remain the foundational production method. Environmental compliance crackdowns by China's MEE in the Hebei corridor periodically constrain export supply.
- CNC Machining:Five-axis precision finishing achieves geometric tolerances required for high-pressure common rail injection. Talent scarcity for CAM programming limits expansion of this capability.
- Surface Treatment:Shot peening and chemical cleaning prepare sealing surfaces for multi-layer steel head gaskets. Foundries integrate these lines to capture value previously outsourced to Tier 2 suppliers.
- Thermal Coating:Plasma-sprayed ceramic barrier coatings extend valve seat life in EGR-heavy combustion strategies. EU F-Gas Regulation compliance adds capital cost to coating line installation.
Casting operations anchor the supply base by volume, with CNC Machining expanding most quickly as geometric dimensioning requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River manufacturing belt concentrates the heaviest foundry capacity for automotive cast iron cylinder heads, with procurement patterns diverging sharply between passenger vehicle lightweighting mandates and commercial vehicle durability requirements.
China
Commercial vehicle OEMs in the Yangtze River Delta sustain demand for gray iron and compacted graphite iron formulations despite MIIT fuel consumption limits pressuring passenger segments. MEE environmental compliance crackdowns in Hebei periodically shutter unlicensed foundry capacity, creating supply volatility for export-dependent buyers. Foundry modernization concentrates in Jiangsu and Zhejiang provinces where state-backed industrial parks absorb electrification transition costs.
United States
Class 8 truck production in Indiana and Ohio anchors demand for heavy-duty diesel cylinder heads with extended thermal fatigue resistance. EPA tailpipe standards and California CARB waivers shape metallurgical compliance timelines, extending product development cycles for revised formulations. Cummins maintains captive foundry networks across the Midwest, insulating procurement from import supply shocks.
Germany
European commercial vehicle OEMs adopt compacted graphite iron for next-generation 13-liter diesel platforms, validating higher-strength alloys for high-boost architectures. EU F-Gas Regulation forces foundry investment in electric melting and fume capture systems, filtering smaller producers from Tier 1 supplier lists. Industrial concentration in Baden-Württemberg and Lower Saxony supports precision machining capabilities for emissions-critical combustion chamber tolerances.
India
Heavy-duty truck fleets in the Chennai-Pune corridor specify cast iron cylinder heads for total cost of ownership advantages over aluminum alternatives in sustained highway cruise conditions. BIS certification mandates metallurgical testing that filters low-grade imports, consolidating demand around domestic foundries with certified laboratory capabilities. Fleet procurement departments prioritize remanufacturability and extended service intervals in material selection.
Brazil
Agricultural and mining equipment manufacturers in São Paulo and Minas Gerais states sustain demand for severe-duty cast iron heads under shock loading and contaminated intake conditions. ANVISA-aligned foundry modernization programs stimulate local capacity expansion for import substitution in heavy machinery segments. OHV pushrod configurations retain preference for repairability in remote operating environments.
Automotive Cast Iron Cylinder Head Market Competitive Environment
Global majors compete with regional champions across metallurgy platforms and machining capabilities, producing a tiered structure where integrated foundry-machining operations capture premium positioning. The supplier base concentrates among vertically capable producers with captive casting and five-axis finishing lines, while pure casting houses face displacement from Tier 1 qualification lists. Three archetypes dominate: captive foundry networks serving single OEM ecosystems, independent multi-client foundries with modular platform flexibility, and precision machining specialists integrating thermal coating capabilities. Competitive dynamics center on portfolio diversification across gray iron, ductile iron, and compacted graphite iron formulations, plus geographic expansion into emerging commercial vehicle manufacturing corridors.
Within the captive foundry tier, Cummins Inc. exemplifies backward integration into in-house cylinder head production for diesel powertrain ecosystems. Among diversified automotive component manufacturers, MAHLE GmbH and Nemak S.A.B. de C.V. occupy positions spanning multiple metallurgy platforms with sustained geographic diversification across the Americas and European manufacturing belts. These three anchors represent distinct strategic postures: single-OEM captive supply, precision machining-led differentiation, and multi-platform volume aggregation.
| Leading Market Players |
|---|
| Nemak S.A.B. de C.V. |
| Linamar Corporation |
| Toyota Industries Corporation |
| Yamaha Motor Co., Ltd. |
| Cummins Inc. |
| Sandvik Coromant |
| MAHLE GmbH |
| Teksid S.p.A |
| Edelbrock LLC |
| Others |
Value Chain & Pricing Dynamics
Compacted graphite iron adoption across European heavy-duty diesel platforms is compressing legacy gray iron margins while concentrating premium pricing power among foundries with certified metallurgical laboratories. This alloy transition simultaneously elevates capital requirements for supply-side participants and reshapes procurement negotiations toward long-term offtake structures.
Pricing Analysis
Ferrous scrap input costs transmit directly into foundry quotations through quarterly contract adjustments, with gray iron formulations absorbing tighter volatility than CGI grades due to lower alloy complexity. Price differentiation hinges on BIS certification tier and five-axis machining capability, with India's domestic foundries commanding premiums over import alternatives. Cost compression in passenger vehicle segments is intensifying because MIIT fuel consumption limits accelerate aluminum substitution, while commercial vehicle buyers show lowest price sensitivity due to total cost of ownership calculations. Fleet procurement departments in heavy-duty trucking prioritize thermal durability over unit cost, insulating diesel-focused suppliers from downstream margin pressure.
Supply Chain Analysis
Ocean freight rate fluctuations from China to North American Midwest assembly plants directly influence landed cost competitiveness for export-dependent foundries. Geographic supply concentration centers on China, India, and Germany, with Hebei corridor environmental crackdowns periodically disrupting export volumes. Raw material dependencies draw from Brazilian pig iron, Australian metallurgical coal, and domestic ferrous scrap streams. Single-source vulnerability concentrates in CNC programming talent pools, where five-axis CAM expertise scarcity constrains capacity expansion. Distribution runs through Tier 1 supplier consolidation toward integrated foundry-machining operations, displacing pure casting houses from OEM qualification lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by commercial vehicle fleet replacement cycles that resist aluminum substitution through extended service interval requirements.
For Market Incumbents: Extend CGI alloy certification coverage to capture displacement opportunities in high-boost diesel architectures, while consolidating machining capacity in India's Chennai-Pune corridor to exploit BIS import filtration. Aluminum encroachment into adjacent passenger segments threatens volume aggregation, making backward integration into thermal coating lines the critical defensive lever for margin preservation. For New Entrants and Emerging Players: Precision five-axis CNC programming capabilities offer the most penetrable wedge against incumbent machining bottlenecks, particularly for aftermarket remanufacturing channels serving Brazil's agricultural equipment sector. Target white-space in hybrid range-extender thermal management applications, where cast iron's thermal mass properties create bridge demand during electrification transition. Go-to-market positioning should emphasize single-source accountability for casting defects and dimensional drift to displace fragmented supplier bases. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap foundry-machining hybrids because customer consolidation around vertically capable suppliers is accelerating exit multiples for integrated operations. Long-term viability frames around commercial vehicle electrification timelines, with CGI formulation expertise serving as the durable moat. Acquisition targets should show certified laboratory capabilities and permanent mold automation lines. The signal to watch is EPA type-approval velocity for revised metallurgical formulations, as extended certification cycles compress valuation windows for technology-transitioning assets.| Strategic Initiative | Industry Significance |
|---|---|
| CGI Alloy Platform Expansion | European OEM validation of 13-liter diesel architectures opens premium displacement opportunities. |
| Integrated Machining Investment | Five-axis CNC capability captures value previously outsourced to Tier 2 precision finishers. |
| Thermal Coating Line Addition | Plasma-sprayed ceramic barriers extend valve seat life under EGR-heavy combustion strategies. |
| Remanufacturing Channel Development | Extended commercial vehicle service intervals expand aftermarket cylinder head renewal demand. |
| Foundry Modernization Compliance | EU F-Gas Regulation alignment filters smaller competitors from Tier 1 supplier qualification lists. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and foundry operations directors with secondary validation from vehicle production databases, IHS Markit registration data, customs trade records, and SEC filings from publicly traded component manufacturers. Bottom-up volume builds across engine displacement categories and top-down macroeconomic anchoring were triangulated to constrain forecast variance.
Comparable-period anchoring linked projection assumptions to historical production cycles across heavy-duty truck and commercial vehicle segments. The analytical framework modeled demand across product type, engine size, application, and technology dimensions over the projection horizon. CAGRs were derived from segment-level growth rate blending weighted by revenue contribution, with foundry capacity utilization rates and emissions certification timelines serving as primary industry-specific forecast inputs.
The model holds under stable regulatory treatment of commercial vehicle segments; deviation in EPA or EU Stage V enforcement intensity would shift volume assumptions. Forecasts reflect documented assumptions regarding aluminum substitution velocity and CGI adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
France Automotive Electric Actuators Market
Automotive Components
Automotive Radiator Grille Market
Automotive Components
Automotive Front-End Module (FEM) Market
Automotive Components
Europe Automotive Electric Actuators Market
Automotive Components
Automotive Carbon Brake Rotor Market
Automotive Components
Global Automotive Plastic Compounding Market
Automotive Components
Global Automotive Chrome Accessories Market
Automotive Components
Automotive Clutch Disc Market
Automotive Components
Global Automotive Brake Components Market
Automotive Components
Automotive Backing Plate Market
Automotive Components
Automotive Heater Core Market
Automotive Components
Germany Automotive Composites Market
Automotive Components
Europe Automotive Airfilters Market
Automotive Components
Automotive Aftermarket for Brake Components Market
Automotive Components
Global Automotive Cigarette Lighters Market
Automotive Components
Automotive Evaporative Emission Control (EVAP) System Market