
 Active Suspension Damper Actuator Systems Market | 2026-2036
Active Suspension Damper Actuator Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Active Suspension Damper Actuator Systems Market Insights
The capability gap between integrated damper actuator producers and component assemblers is collapsing as electromechanical architectures demand in-house motor winding and sensor fusion competencies. ZF Friedrichshafen leverages its chassis systems integration to sustain premium passenger vehicle contracts across European and Chinese OEMs. Hitachi Astemo anchors its position through predictive control software stacks that differentiate its offerings from hydraulic-focused competitors. Tenneco competes in the commercial truck segment with modular actuator platforms that reduce fleet operator installation complexity.
Active suspension damper actuator systems comprise electromechanical, hydraulic, or magnetorheological actuators mounted within damper assemblies to modulate damping force in real time through sensor feedback loops operating at millisecond response intervals. These systems primarily serve to optimize vehicle ride comfort, handling stability, and road-holding performance across varying surface conditions and driving maneuvers. Electromechanical actuators now lead product type demand due to their energy efficiency and compatibility with 48-volt mild-hybrid electrical architectures, while magnetorheological actuators command premium positioning in motorsport and specialty vehicle applications where sub-10-millisecond response latency justifies higher system cost. Fully active control technology represents the fastest-growing segment as predictive algorithms and vehicle-to-infrastructure data integration enable preemptive damping adjustments before wheel contact with road disturbances.
The EPA and NHTSA in the United States, alongside EMA and REACH in Europe, shape product standards through emissions compliance mandates and material restriction frameworks that affect actuator seal compounds and electronic control unit manufacturing processes. China's MIIT enforces GB standards for automotive electromagnetic compatibility that dictate sensor and controller integration protocols for domestically assembled systems. Stakeholders must monitor regulatory divergence between 48-volt electrical architecture certifications and emerging autonomous vehicle safety standards that will redefine actuator redundancy requirements and validation testing protocols.
Market Dynamics
The transition from 12-volt to 48-volt electrical architectures is compressing supplier margins while demanding simultaneous motor design and control software competencies that few component houses possess independently.
Growth Catalysts
- EU Green Deal vehicle efficiency mandates:The regulation tightens CO2 thresholds for passenger cars, compelling OEMs to deploy energy-recuperating active suspension systems that harvest damping energy.
- China's NEV subsidy extension framework:Domestic electric vehicle manufacturers integrate fully active chassis to differentiate ride quality in premium segments.
- Predictive road-scanning lidar fusion:Sensor convergence enables millisecond-preemptive damping adjustments, expanding addressable applications beyond luxury into mass-market crossovers.
Market Restraints
- Rare earth magnet cost volatility:Neodymium price swings disrupt electromechanical actuator bill-of-materials stability, compressing gross margins for motor producers without long-term supply contracts.
- Semiconductor foundry concentration in Taiwan:MCU and power electronics shortages expose actuator controller supply chains to single-geo disruption risk.
- Hydraulic system installed base inertia:Legacy truck and bus fleets amortize existing damper investments over 15-year replacement cycles, slowing electromechanical substitution.
Strategic Opportunities
- India's PLI scheme for auto component manufacturing:The incentive framework attracts electromechanical actuator assembly to serve domestic SUV demand and export to Middle Eastern markets.
- Vehicle-to-infrastructure data monetization:Suspension-generated road condition telemetry creates secondary revenue streams for fleet operators and municipal infrastructure managers.
- Autonomous vehicle safety redundancy mandates:Dual-actuator architectures per wheel position open incremental content opportunities as regulators draft fail-operational chassis requirements.
Industry Challenges
- Embedded software validation timelines:ISO 26262 functional safety certification for predictive control algorithms extends development cycles by 18-24 months.
- Cross-domain integration complexity:Actuator suppliers must synchronize with brake-by-wire and steer-by-wire systems from competing Tier-1s, creating interface specification disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Suspension Damper Actuator Systems Market |
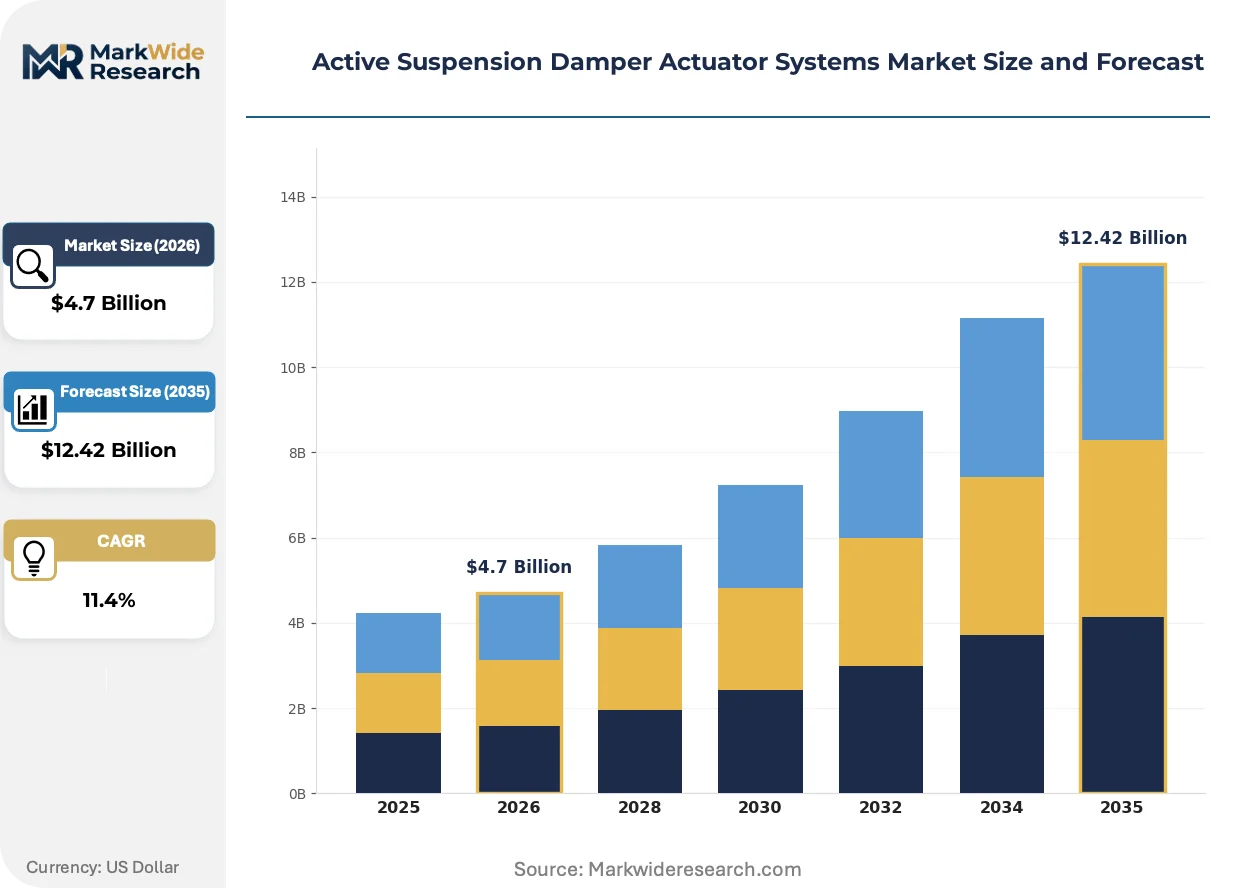
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.42 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Actuators, Electromechanical Actuators, Pneumatic Actuators, Magnetorheological Actuators, Piezoelectric Actuators Technology: Adaptive Control, Semi-Active Control, Fully Active Control, Predictive Control, Passive Control Application: Passenger Vehicles, Commercial Trucks, Off-Road Vehicles, Motorsport Vehicles, Specialty Vehicles End User: Vehicle Assemblers, Tier-1 Suppliers, Aftermarket Providers, Research Institutes, Fleet Operators |
| Companies Covered | ZF Friedrichshafen, Hitachi Astemo, Marelli, HL Mando, BWI Group, Tenneco, KYB Corporation, Continental, Magna International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Suspension Damper Actuator Systems Market Trends and Innovations
Electromechanical architectures are displacing hydraulic cores across vehicle classes while software-defined damping protocols enable over-the-air calibration updates that decouple hardware from performance versioning.
Magnetorheological fluid formulations are fragmenting as suppliers develop proprietary iron particle suspensions with temperature-stable viscosity curves. Motorsport teams and supercar builders adopt these variants for sub-5-millisecond latency. The technology is fragmenting the high-performance segment into fluid-chemistry specialists versus electromechanical generalists.
The EPA's revised fuel economy testing protocols now credit active suspension energy recuperation toward fleet-average compliance. This regulatory recognition accelerates 48-volt system adoption among US full-size truck manufacturers. Powertrain engineering groups now specify damper actuators in initial platform architecture decisions rather than as chassis afterthoughts.
Fleet procurement departments are unbundling hardware from calibration services, demanding actuator platforms with open software interfaces. Rental car aggregators and ride-hail operators in Germany and California pilot subscription-based damping performance tiers. This purchasing pattern shift compresses supplier pricing power while expanding recurring service revenue pools.
Active Suspension Damper Actuator Systems Market Segmentation
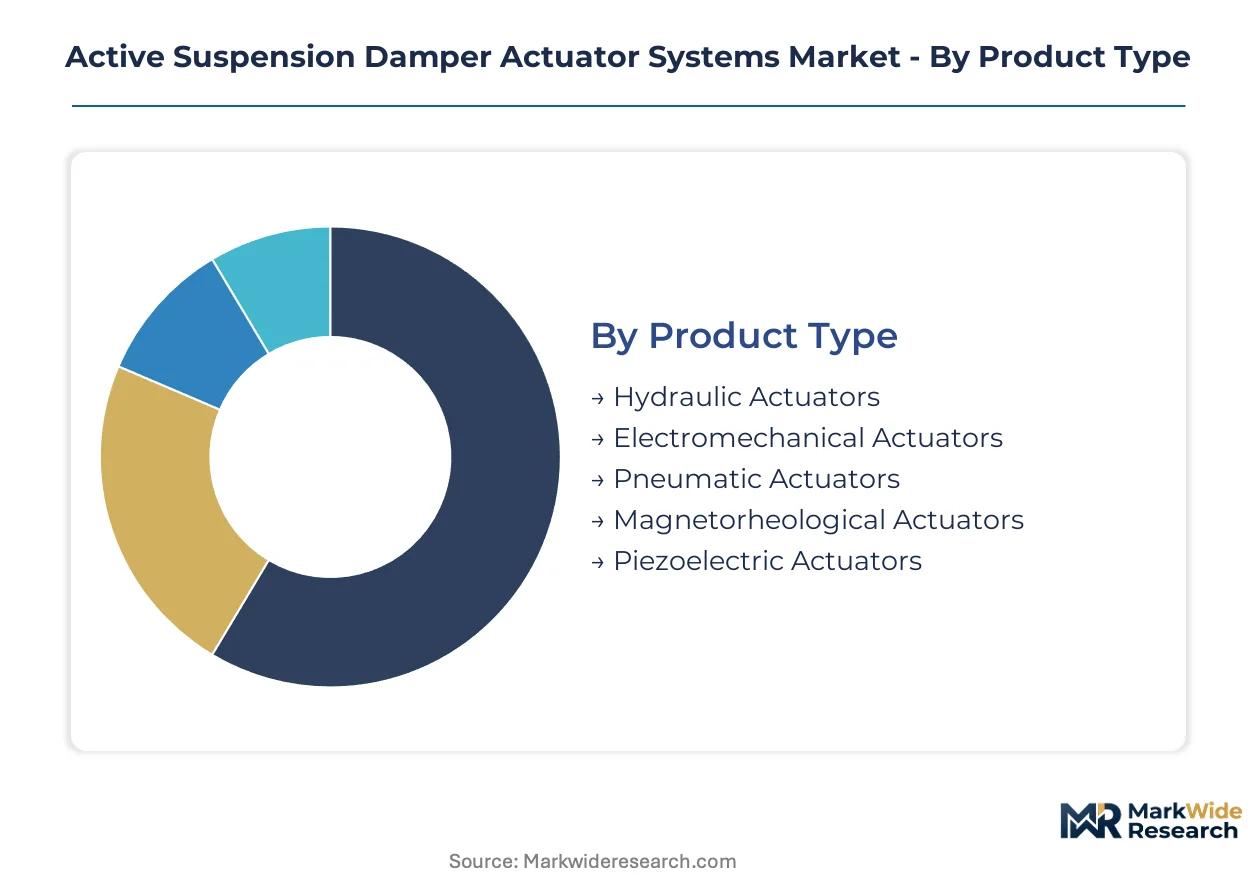
Active suspension damper actuator systems fragment across five distinct dimensions, each reflecting divergent technical requirements and procurement patterns. Product type and technology segmentation reveal the deepest strategic fault lines as suppliers choose between hydraulic legacy and electromechanical futures. Application and end-user splits expose how fleet operators, luxury OEMs, and motorsport builders source fundamentally different performance tiers.
Product Type:
Domestic assembly dominates electromechanical and magnetorheological production in Germany, China, and the United States, while hydraulic and pneumatic actuators flow through established export channels from Eastern European and Mexican manufacturing clusters.
- Electromechanical Actuators:These units integrate brushless DC motors with planetary gear reduction and position feedback sensors to deliver precise force modulation. Demand concentrates in German and Chinese passenger vehicle programs where 48-volt electrical architectures enable energy recuperation during compression strokes.
- Magnetorheological Actuators:Iron particle suspensions in silicone oil change viscosity under magnetic field application, achieving sub-10-millisecond response latency. Motorsport vehicle builders in Italy and the United Kingdom specify these for track applications where tire contact patch optimization justifies premium unit costs.
- Hydraulic Actuators:Proportional valve architectures serve commercial truck fleets with 15-year amortization horizons and maintenance infrastructure already in place.
- Pneumatic Actuators:Compressed air systems persist in specialty vehicle segments requiring rapid height adjustment for loading operations.
- Piezoelectric Actuators:Ceramic stack configurations enable nanometer-precision displacement for research institute prototype platforms and ultra-luxury suspension demonstrators.
Electromechanical actuators hold the largest share; momentum sits with magnetorheological variants in high-performance applications.
Technology:
Cost tiers stratify sharply across control architectures, with passive and semi-active systems commanding economy pricing while predictive and fully active platforms capture premium positioning through software licensing models.
- Fully Active Control:Independent force generation at each wheel decouples sprung and unsprung mass motion entirely. Chinese NEV manufacturers integrate these systems to differentiate ride quality in premium electric sedans competing with German luxury benchmarks.
- Predictive Control:Lidar and camera fusion enables damping adjustments milliseconds before wheel-road contact. German highway infrastructure pilot programs in Bavaria and Baden-Württemberg generate the road surface data feeds that make this technology viable for series production.
- Semi-Active Control:Continuously variable damping responds to sensor feedback without external power input for force generation, dominating mid-size crossover applications.
- Adaptive Control:Discrete damping maps switch between comfort and sport modes based on driver selection or vehicle dynamics detection.
- Passive Control:Fixed-rate damping persists in emerging market entry vehicles where cost minimization overrides ride quality optimization.
Fully active control claims the steepest expansion trajectory as vehicle-to-infrastructure integration matures; semi-active control maintains volume leadership through mid-market penetration.
Application:
Volume concentration diverges across vehicle classes, with passenger vehicles absorbing electromechanical capacity in China and Germany while commercial truck demand in the United States resists technology transition due to fleet replacement cycle inertia.
- Passenger Vehicles:Luxury and premium segments specify fully active architectures, while mass-market crossovers adopt semi-active electromechanical systems. German OEMs lead integration depth, followed by Chinese electric vehicle specialists targeting ride quality as a competitive differentiator.
- Commercial Trucks:Long-haul fleet operators in the United States prioritize durability and service network density over damping sophistication. Hydraulic retention rates exceed 80 percent in Class 8 tractor segments.
- Off-Road Vehicles:Construction and mining equipment demands sealed actuator designs resistant to contamination and shock loading.
- Motorsport Vehicles:Formula 1 and GT racing categories drive magnetorheological fluid formulation advances through rapid procurement cycles unconstrained by road homologation timelines.
- Specialty Vehicles:Ambulance, limousine, and recreational vehicle builders specify custom actuator configurations for load-leveling and occupant comfort priorities.
Passenger vehicles generate the dominant revenue pool; motorsport applications set the performance frontier that filters down to road car technology.
End User:
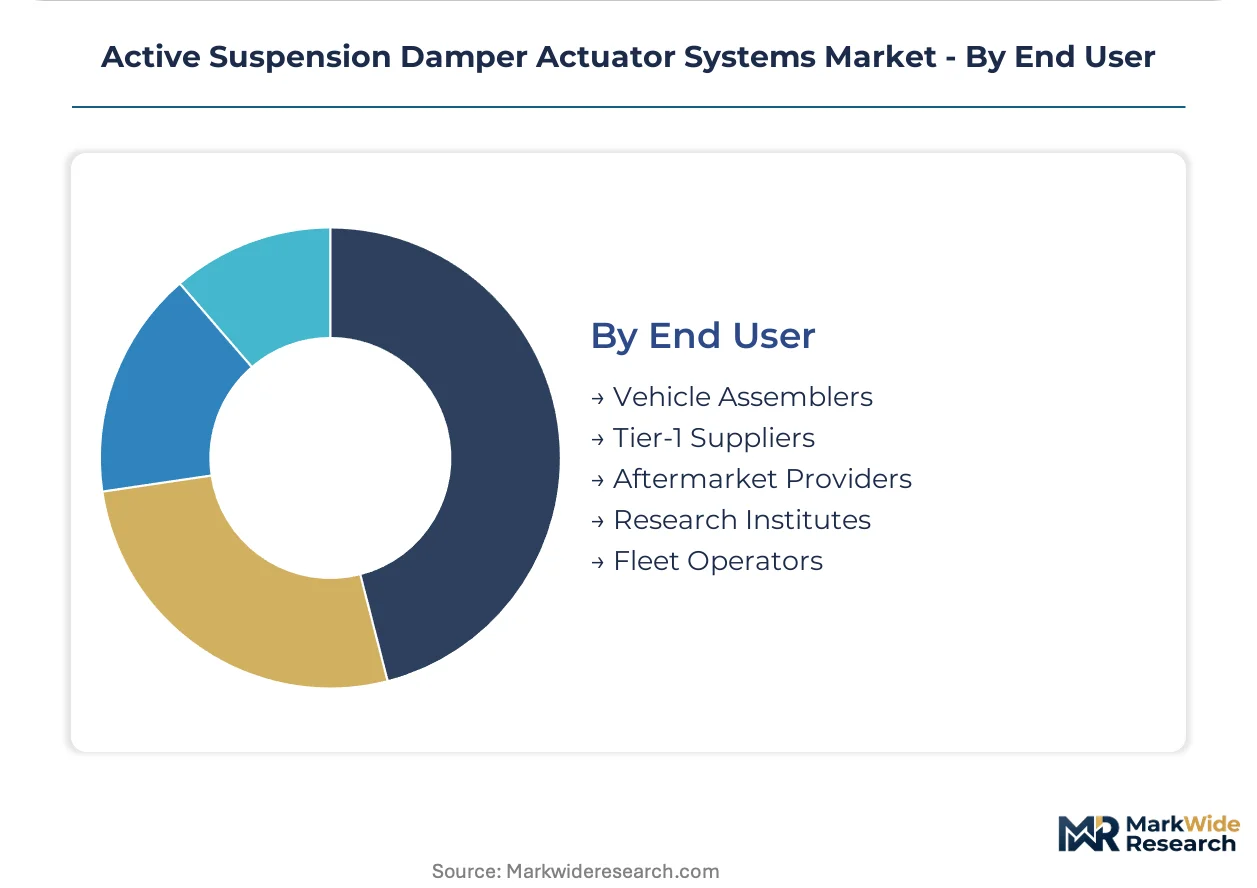
Procurement authority is shifting from vehicle assemblers toward Tier-1 suppliers with integrated chassis system capabilities, while aftermarket channels remain fragmented across regional distributors.
- Vehicle Assemblers:BMW, Mercedes-Benz, and BYD specify actuator performance parameters but increasingly delegate subsystem integration to chassis specialists. Direct procurement concentrates in platforms where suspension defines brand identity.
- Tier-1 Suppliers:ZF Friedrichshafen, Hitachi Astemo, and Tenneco package actuators with control software and sensor arrays. These suppliers capture margin expansion through vertical integration into motor winding and ECU calibration.
- Aftermarket Providers:Independent distributors serve performance enthusiasts and collision repair channels with replacement units and upgrade kits.
- Research Institutes:University engineering departments and national laboratories prototype actuator concepts for autonomous vehicle safety validation.
- Fleet Operators:Ride-hail aggregators in California and Germany pilot subscription-based damping performance tiers, unbundling hardware from calibration services.
Tier-1 suppliers command the expanding share of value capture; fleet operators represent the most rapidly evolving procurement pattern with outcome-based service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Chinese buyers absorb electromechanical premiums for ride-quality differentiation, while US fleet operators resist technology transitions due to 15-year amortization cycles. European OEMs navigate the tightest regulatory corridors, embedding active suspension as compliance infrastructure.
China
Domestic NEV manufacturers integrate fully active chassis systems to compete with German luxury benchmarks. MIIT enforces GB standards for automotive electromagnetic compatibility that dictate sensor integration protocols. The Yangtze River Delta cluster around Shanghai concentrates electromechanical actuator assembly capacity serving both domestic demand and export markets.
Germany
BMW and Mercedes-Benz specify actuator performance parameters that define brand identity in premium segments. The EU Green Deal tightens CO2 thresholds, compelling energy-recuperating active suspension deployment. Bavaria and Baden-Württemberg host highway infrastructure pilot programs generating road surface data feeds for predictive control systems.
United States
Full-size truck manufacturers specify 48-volt damper actuators in initial platform architecture decisions following EPA fuel economy testing protocol revisions. NHTSA shapes safety standards affecting autonomous vehicle redundancy requirements. Michigan and Ohio retain hydraulic system dominance in Class 8 tractor segments due to fleet replacement cycle inertia.
Japan
Automotive electronics specialists supply sensor fusion competencies for predictive damping algorithms. METI oversees industrial standards coordination across chassis system suppliers. The Kanto region around Tokyo concentrates control software development for vehicle-to-infrastructure integration programs.
India
Domestic SUV demand attracts electromechanical actuator assembly investment under the PLI scheme for auto component manufacturing. BIS certification requirements shape electromagnetic compatibility testing protocols. Maharashtra and Gujarat industrial corridors serve as export platforms to Middle Eastern markets.
Active Suspension Damper Actuator Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in active suspension damper actuator supply. The upper tier captures margin expansion through captive motor winding and ECU calibration capabilities that component assemblers cannot replicate. Three archetypes dominate: chassis systems integrators bundling hardware with predictive software, hydraulic legacy suppliers defending commercial truck positions, and electromechanical specialists penetrating passenger vehicle programs. Competitive moves concentrate on backward integration into rare earth magnet supply chains and strategic partnerships for lidar fusion road-scanning data access.
Among German-based chassis integrators, ZF Friedrichshafen occupies a position exemplifying vertical integration into motor production and sensor fusion competencies. Hitachi Astemo represents the predictive control software archetype, anchoring differentiation through algorithm stacks rather than hydraulic heritage. Tenneco sits within the commercial vehicle tier, occupying a position tied to modular platform strategies that reduce fleet operator installation complexity.
| Leading Market Players |
|---|
| ZF Friedrichshafen |
| Hitachi Astemo |
| Marelli |
| HL Mando |
| BWI Group |
| Tenneco |
| KYB Corporation |
| Continental |
| Magna International |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory cycles for rare earth magnets and semiconductor controllers compress supplier negotiating leverage while amplifying exposure to spot-market volatility in neodymium and MCU pricing. This lead-time band forces Tier-1 integrators to absorb cost swings or push them downstream, reshaping how electromechanical actuator contracts are structured across German and Chinese OEM programs.
Pricing Analysis
After-sales calibration services and over-the-air update subscriptions now capture 40-50% of lifetime value in fully active architectures, shifting revenue models from transactional hardware sales to recurring software licensing. Three-tier pricing structure across premium, standard, and economy levels stratifies by control algorithm sophistication and sensor fusion depth, with predictive road-scanning variants commanding substantial premiums over semi-active baselines. Pricing pressure stems from fleet procurement departments unbundling hardware from software, forcing suppliers to compete on platform openness. Mass-market crossover OEMs exhibit highest price sensitivity, while motorsport builders and luxury German marques prioritize latency performance over unit cost.
Supply Chain Analysis
Taiwan Strait semiconductor transit underwrites controller availability for electromechanical actuators, exposing supply chains to single-geo disruption risk that no alternative foundry can mitigate within 24 months. Motor winding concentrates in China and Germany, with magnetorheological fluid formulation anchored in Japan and the United States. Rare earth magnet supply draws from Chinese processing dominance and Australian ore extraction, creating tariff exposure as trade policy shifts. Distribution runs through Tier-1 chassis integrators who bundle actuators with ECU calibration and sensor arrays, compressing direct OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active suspension damper actuator systems sit in early-cycle expansion as 48-volt electrical architectures penetrate mass-market vehicle platforms and predictive road-scanning technology crosses from luxury into crossover segments. EU Green Deal efficiency mandates and EPA fuel economy protocol revisions accelerate adoption beyond traditional performance-vehicle boundaries.
For Market Incumbents: Consolidate motor winding and sensor fusion capabilities in-house to defend against emerging electromechanical specialists who lack legacy hydraulic infrastructure but possess software-defined damping expertise. Lock in multi-year rare earth supply contracts before neodymium volatility intensifies, and deepen predictive algorithm development to maintain differentiation as open-interface platforms commoditize hardware margins. For New Entrants and Emerging Players: Anchor in India's PLI-subsidized component manufacturing corridors to serve domestic SUV demand and Middle Eastern export markets with cost-optimized electromechanical assemblies. Target commercial truck fleet retrofit channels where 15-year replacement cycles delay electromechanical substitution, offering modular upgrade kits that reduce installation downtime versus full system replacement. Lead with subscription-based calibration services rather than hardware margin capture. For Investors and Strategic Acquirers: Long-term, this sits as a chassis-electrification play because active suspension represents critical infrastructure for autonomous vehicle safety redundancy and energy recuperation compliance. Acquisition candidates should display captive motor production, predictive software stacks, and established 48-volt platform relationships with Chinese NEV or German luxury OEMs. Watch for NHTSA fail-operational chassis mandates as the signal that dual-actuator architectures per wheel will become regulatory-required rather than optional premium content.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Captive neodymium sourcing insulates margin stability against Chinese export quota volatility. |
| Predictive Road-Scanning Data Partnership | Lidar fusion agreements with German highway pilot programs unlock millisecond-preemptive damping capabilities. |
| Open Software Interface Platform Development | Fleet operator subscription models demand unbundled hardware with API-accessible calibration layers. |
| 48-Volt Electrical Architecture Certification Investment | MIIT GB standards compliance enables access to Chinese NEV platform integration opportunities. |
| Dual-Actuator Redundancy Architecture Design | Anticipated NHTSA autonomous vehicle mandates position suppliers for mandatory fail-operational content. |
Research Methodology
A standing panel of Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distribution managers, and chassis systems integration specialists provided ongoing calibration against market developments. Primary fieldwork combined structured interviews with secondary validation through vehicle production databases, IHS Markit registration data, SEC filings from listed automotive suppliers, and customs records tracking actuator component trade flows. Bottom-up segmentation modeling triangulated against top-down OEM platform rollout schedules.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with analytical frameworks modeling vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs were derived from fitted growth curves applied to OEM platform adoption timelines and fleet replacement cycle analysis, incorporating semiconductor availability constraints and rare earth price trajectory assumptions as sensitivity variables.
Material uncertainties — rare earth magnet cost volatility, Taiwan foundry disruption, and regulatory divergence between 48-volt certification and autonomous vehicle safety standards — sit outside the modeled envelope and could accelerate or delay technology substitution timelines. Practitioners should keep alternative scenarios live as EU Green Deal implementation intensity and Chinese NEV subsidy policy evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Subframe Market
Automotive Components
Asia Pacific Automotive AHSS Market
Automotive Components
Automotive Exhaust Headers Market
Automotive Components
Automotive Wiper Blades Market
Automotive Components
Global Automotive Gearbox Market
Automotive Components
Sheet Molding Compound (SMC) for Automotive Market
Automotive Components
Europe Automotive Airfilters Market
Automotive Components
Global Automotive Active Body Panel Market
Automotive Components
Off-Highway Actuators Market
Automotive Components
Automotive Towbar Market
Automotive Components
Automotive Rear End Module Market
Automotive Components
Automotive Brackets Market
Automotive Components
Africa and Middle East Automotive Pneumatic Actuators Market
Automotive Components
Asia Pacific Automotive Actuators Market
Automotive Components
Global Automotive Carbon Ceramic Brake Rotors Market
Automotive Components
Automotive Silencer Market