
 Multi-Enterprise Logistics Contract and SLA Performance Management Platforms Market | 2026-2036
Multi-Enterprise Logistics Contract and SLA Performance Management Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Enterprise Logistics Contract and SLA Performance Management Platforms Market Insights
Buyer consolidation among Fortune 500 shippers is repositioning contract leverage toward enterprise procurement teams with centralized logistics operations. SAP leverages deep ERP integration to anchor its position in SLA enforcement workflows. Oracle sustains competitive pressure through database-centric contract analytics that span transportation and warehousing clauses. Sirion specializes in obligation extraction and compliance tracking for complex multi-carrier agreements.
Multi-enterprise logistics contract and SLA performance management platforms are software systems that ingest carrier agreements, parse service-level obligations, and trigger automated penalties or remediation workflows when delivery windows, damage thresholds, or documentation standards are breached. These platforms typically operate through API connections to TMS and WMS layers, enabling real-time event correlation against contractual terms. Cloud-based deployments now lead platform type adoption as freight networks demand elastic compute for seasonal volume spikes. Predictive analytics within feature sets represents the fastest-expanding capability area, though contract repository modules still occupy the largest margin pool due to enterprise data migration complexity.
The EU AI Act and GDPR constrain how European logistics networks deploy automated SLA penalty algorithms, while the US Federal Motor Carrier Safety Administration shapes hours-of-service data integration requirements that feed into carrier compliance tracking. ISO 31000 risk management standards increasingly influence how multinational shippers structure performance guarantees in platform-configured contracts. Stakeholders must decide whether to prioritize real-time event processing investments or contract intelligence layers that reduce manual clause interpretation.
Market Dynamics
Cloud-native API architectures are compressing deployment timelines for logistics contract platforms, forcing incumbent vendors to rearchitect monolithic systems while enterprise shippers demand real-time SLA correlation across multimodal networks.
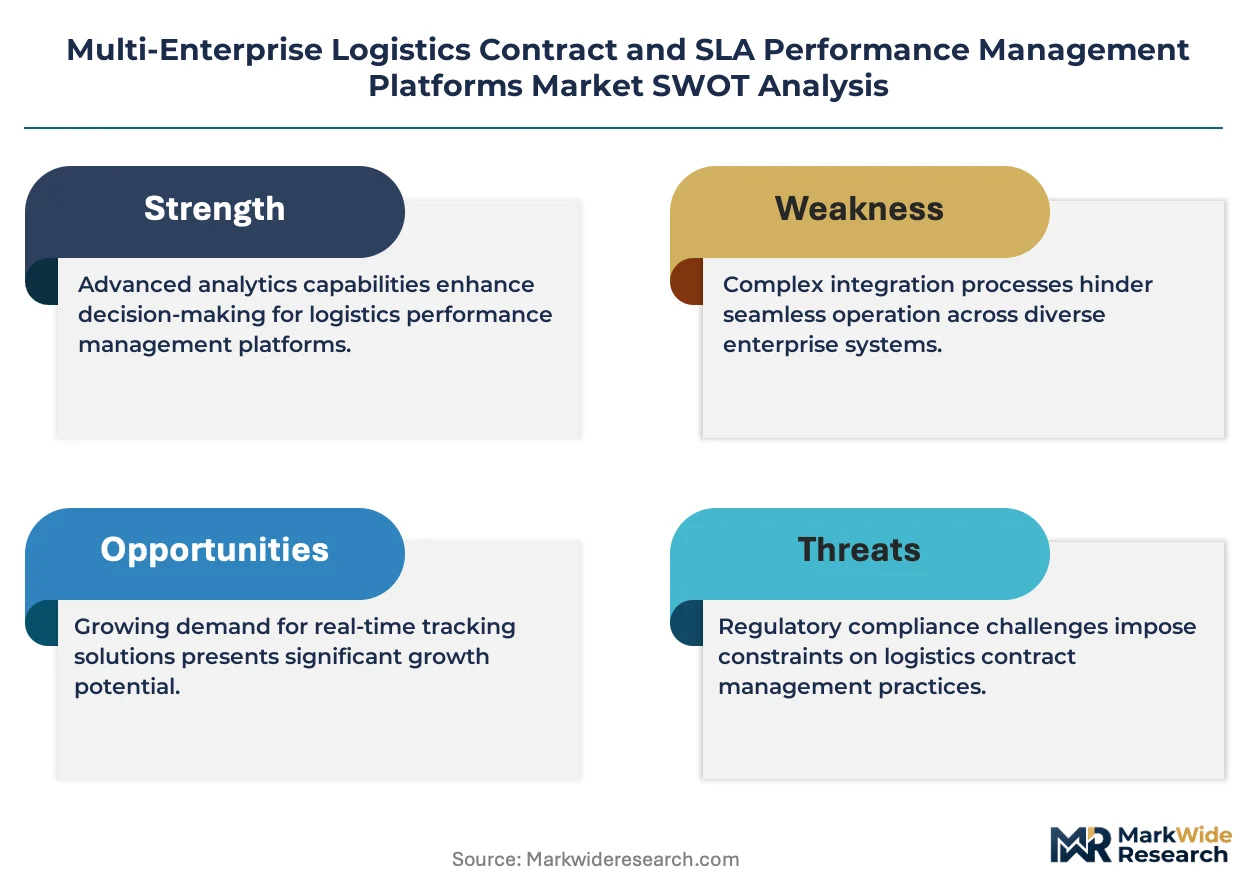
Growth Catalysts
- Federal Motor Carrier Safety Administration mandates:Hours-of-service data integration requirements compel carriers to adopt automated compliance tracking, expanding platform addressable market across US freight networks.
- Predictive analytics modules:Machine learning models trained on historical breach patterns enable preemptive carrier intervention, reducing penalty arbitration costs for enterprise procurement teams.
- Fortune 500 shipper consolidation:Centralized logistics operations at conglomerates like Amazon, Walmart, and Target create procurement leverage that mandates vendor platform standardization.
Market Restraints
- GDPR algorithmic accountability:EU AI Act constraints on automated penalty determination force European deployments to maintain human-in-the-loop review, inflating operational overhead.
- Legacy ERP integration complexity:SAP and Oracle system migrations absorb 60-80% of implementation budgets, delaying ROI realization for mid-market 3PLs.
- Carrier data standardization gaps:Inconsistent EDI and API formats across North American trucking networks require expensive custom mapping layers.
Strategic Opportunities
- Rail-ocean intermodal corridors:Port congestion at Los Angeles and Long Beach accelerates demand for unified SLA tracking across containerized rail and vessel networks.
- ISO 31000 risk frameworks:Multinational shippers embedding performance guarantees into platform-configured contracts create premium pricing tiers for compliance-certified vendors.
- Blockchain-API convergence:Immutable contract repositories combined with real-time event streaming enable dispute-proof penalty automation for high-value pharmaceutical and electronics freight.
Industry Challenges
- Clause extraction expertise scarcity:Natural language processing engineers with logistics domain knowledge command premium compensation, constraining vendor R&D velocity.
- Multimodal event correlation latency:Synchronizing TMS, WMS, and carrier telematics feeds into sub-minute SLA breach detection requires expensive edge computing infrastructure.
- Penalty arbitration workflow design:Configuring automated remediation paths that satisfy both shipper procurement and carrier legal teams demands prolonged pilot programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Enterprise Logistics Contract and SLA Performance Management Platforms Market |
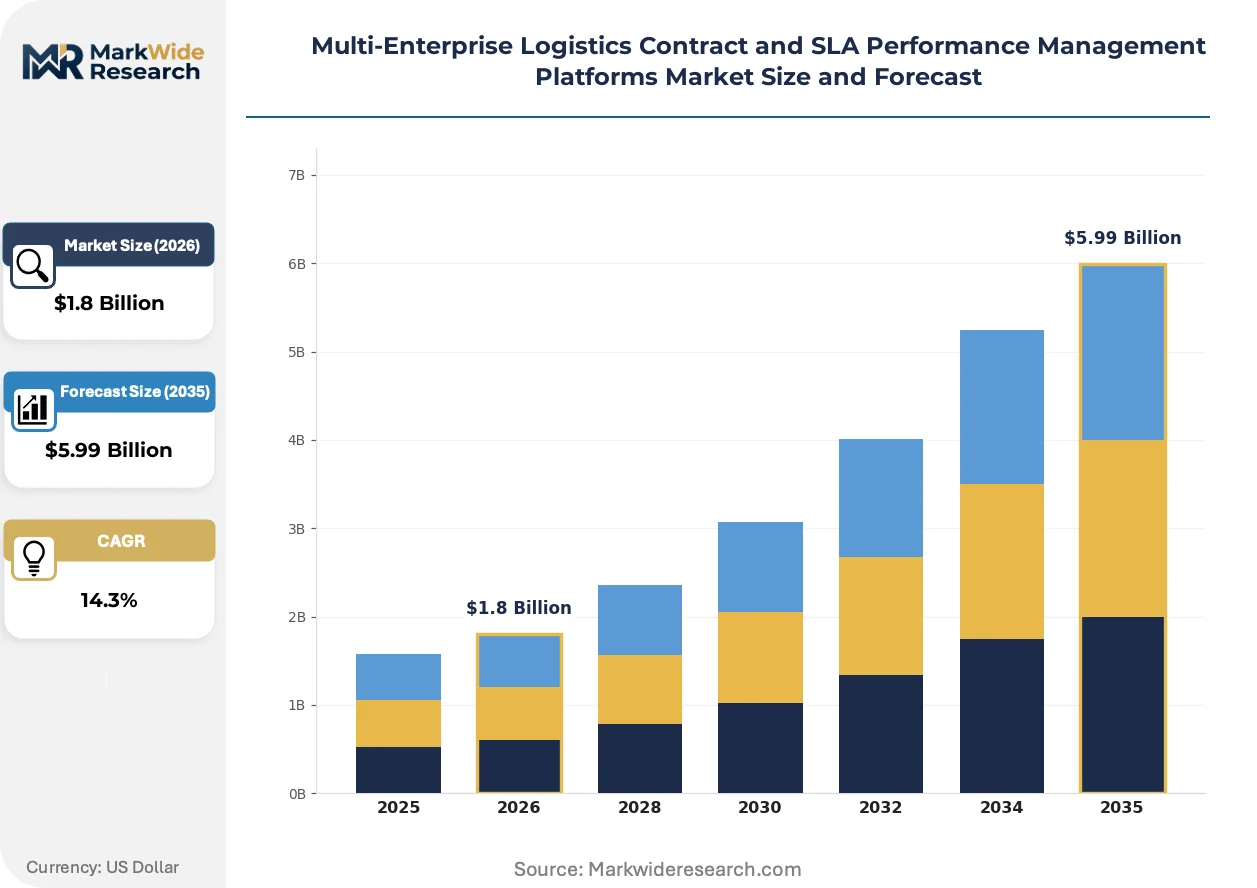
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.99 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Cloud-Based, On-Premises, Hybrid, SaaS, API-Driven Feature Set: Real-Time Monitoring, Predictive Analytics, Automated Reporting, Compliance Tracking, Contract Repository End User Sector: Third-Party Logistics Providers, Freight Forwarders, Distribution Centers, Retail Supply Chains, Wholesale Networks Integration Capability: ERP Systems, Transportation Management, Warehouse Management, Carrier Networks, Billing Systems |
| Companies Covered | Sirion, Oracle, SAP, Coupa Software, Jaggaer, Keelvar, Descartes Systems Group, WiseTech Global, project44, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Enterprise Logistics Contract and SLA Performance Management Platforms Market Trends and Innovations
Real-time event streaming architectures are displacing batch-processed contract analytics, compressing SLA breach detection from hours to seconds and enabling preemptive carrier intervention before delivery windows expire.
Serverless computing infrastructure is overtaking provisioned cloud instances for seasonal freight volume spikes, allowing 3PLs to scale contract processing capacity during peak retail quarters without year-round hardware commitments. Mid-market logistics providers in the United States are adopting this model fastest, drawn by consumption-based pricing that aligns technology costs with shipment volatility. The structural consequence is margin compression for traditional SaaS vendors locked into annual subscription models.
EU AI Act algorithmic transparency requirements are reshaping how European logistics networks deploy automated penalty engines, mandating explainable decision trails for every SLA breach determination. Industrial consequence includes mandatory audit logging and human appeal pathways that inflate platform development costs. German and Dutch freight networks are responding by piloting hybrid systems that reserve full automation for low-value parcel flows while maintaining manual review for high-stakes pharmaceutical and automotive contracts.
Outcome-based logistics procurement is consolidating contract leverage among enterprise shippers with centralized transportation operations, displacing transactional rate negotiations with multi-year performance partnerships. Retail and grocery verticals are leading this shift, embedding inventory availability guarantees directly into carrier agreements. This pattern is most visible in US Midwest distribution corridors where Walmart, Target, and Kroger co-locate fulfillment centers and demand synchronized SLA enforcement across shared carrier pools.
Multi-Enterprise Logistics Contract and SLA Performance Management Platforms Market Segmentation
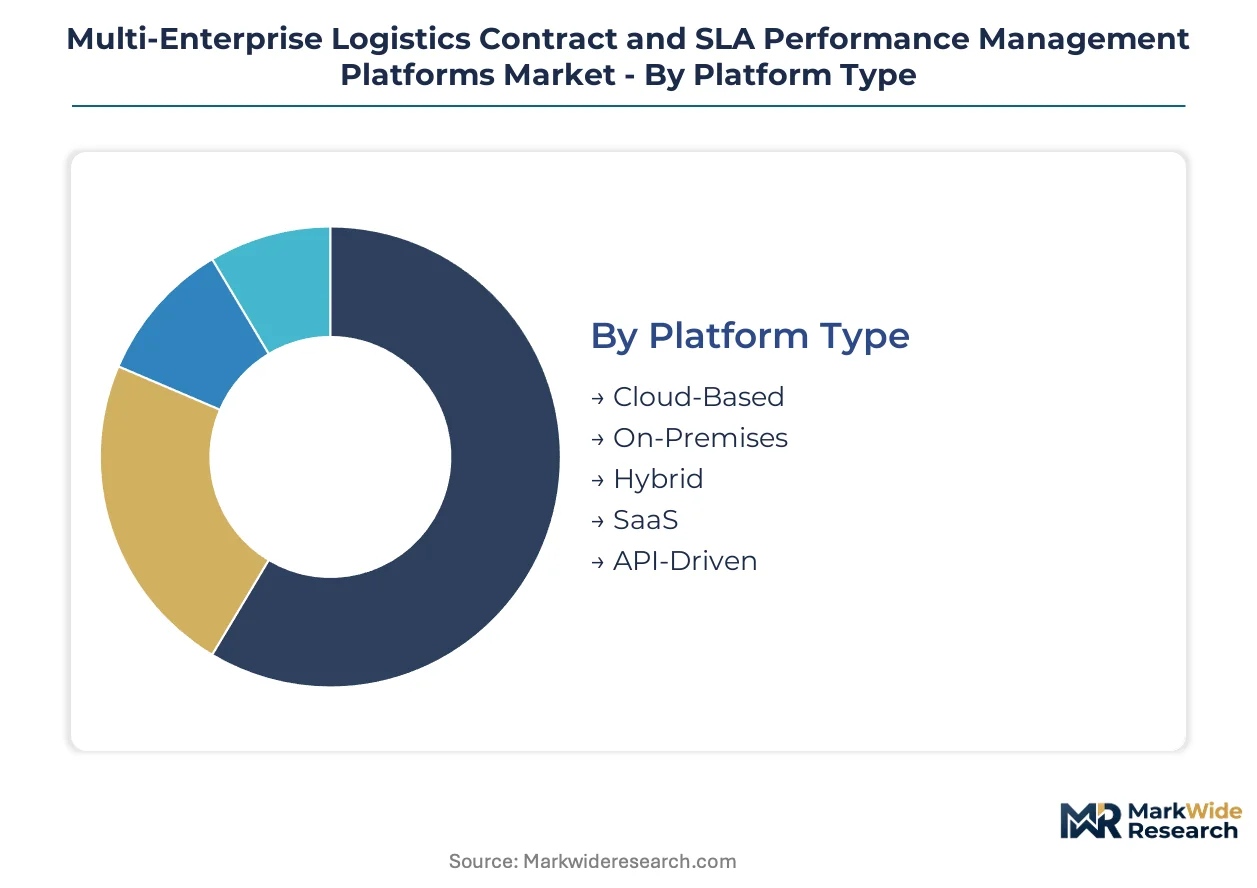
Platform architecture choices determine whether logistics operators deploy standalone contract modules or embed SLA enforcement within existing ERP and TMS stacks. Integration depth directly shapes implementation timelines, data latency, and penalty automation reliability across multimodal freight networks.
Platform Type:
Cloud-native deployments embed directly within distributed carrier networks, while on-premises installations retain data sovereignty for defense and pharmaceutical shippers with classified routing requirements.
- Cloud-Based:Elastic compute pools scale contract processing capacity during peak retail quarters without hardware commitments. United States-based 3PLs favor this model for consumption-based pricing alignment with shipment volatility.
- On-Premises:Air-gapped installations satisfy EU GDPR data residency mandates and defense contractor security protocols. German automotive manufacturers and Dutch pharmaceutical distributors maintain these deployments for algorithmic audit trail control.
- Hybrid:Sensitive contract terms reside on local servers while carrier telematics stream through cloud APIs. This architecture dominates mid-market freight forwarders balancing compliance with connectivity.
- SaaS:Subscription licensing with standardized SLA templates accelerates deployment for regional distribution networks lacking dedicated IT infrastructure.
- API-Driven:Microservices architecture enables real-time event correlation across TMS, WMS, and carrier EDI feeds. This segment climbs fastest as multimodal networks demand sub-minute breach detection.
Volume placements concentrate in Cloud-Based; the faster expansion belongs to API-Driven.
Feature Set:
Functional modules range from passive contract storage to preemptive intervention systems, with procurement teams prioritizing capabilities that reduce manual clause interpretation and arbitration overhead.
- Real-Time Monitoring:Continuous ingestion of carrier telematics, port terminal data, and customs clearance status enables instantaneous SLA status dashboards. Port congestion at Los Angeles and Long Beach accelerates demand for this capability across Pacific Rim container networks.
- Predictive Analytics:Machine learning models trained on historical breach patterns flag at-risk shipments before delivery windows expire. Retail supply chains embed these tools to preempt inventory stockouts during promotional cycles.
- Automated Reporting:Scheduled generation of carrier scorecards and compliance summaries reduces procurement analyst workload. Mid-market 3PLs deploy this feature to standardize client communication without dedicated business intelligence staff.
- Compliance Tracking:Automated mapping of carrier documentation against FMCSA hours-of-service rules and EU driver working time directives.
- Contract Repository:Centralized clause libraries with version control and obligation extraction. This module captures the largest margin pool due to enterprise data migration complexity and NLP engineering scarcity.
Contract Repository anchors current procurement budgets; Predictive Analytics gains share fastest as outcome-based logistics partnerships proliferate.
End User Sector:
Sector-specific workflows dictate whether platforms emphasize carrier network complexity, customs brokerage integration, or inventory synchronization across shared fulfillment infrastructure.
- Third-Party Logistics Providers:Multi-tenant architectures supporting dozens of shipper clients with segregated contract data and penalty workflows. These operators demand white-label reporting and configurable SLA templates.
- Freight Forwarders:Ocean-air-road multimodal coordination with customs brokerage integration. Port-to-door visibility requirements drive adoption of real-time monitoring across NVOCC networks.
- Distribution Centers:Inbound receiving schedules and outbound dispatch windows require WMS-native SLA enforcement. Midwest US grocery consolidation centers embed these platforms to synchronize Kroger, Walmart, and Target shared carrier pools.
- Retail Supply Chains:Inventory availability guarantees and promotional delivery windows dominate contract terms. Seasonal volume spikes necessitate elastic platform scaling.
- Wholesale Networks:Full-truckload and less-than-truckload consolidation with pallet-level tracking requirements. These operators prioritize API-driven carrier connectivity over predictive capabilities.
Third-Party Logistics Providers generate the deepest contract volumes; Retail Supply Chains expand most quickly as inventory availability guarantees displace transactional rate negotiations.
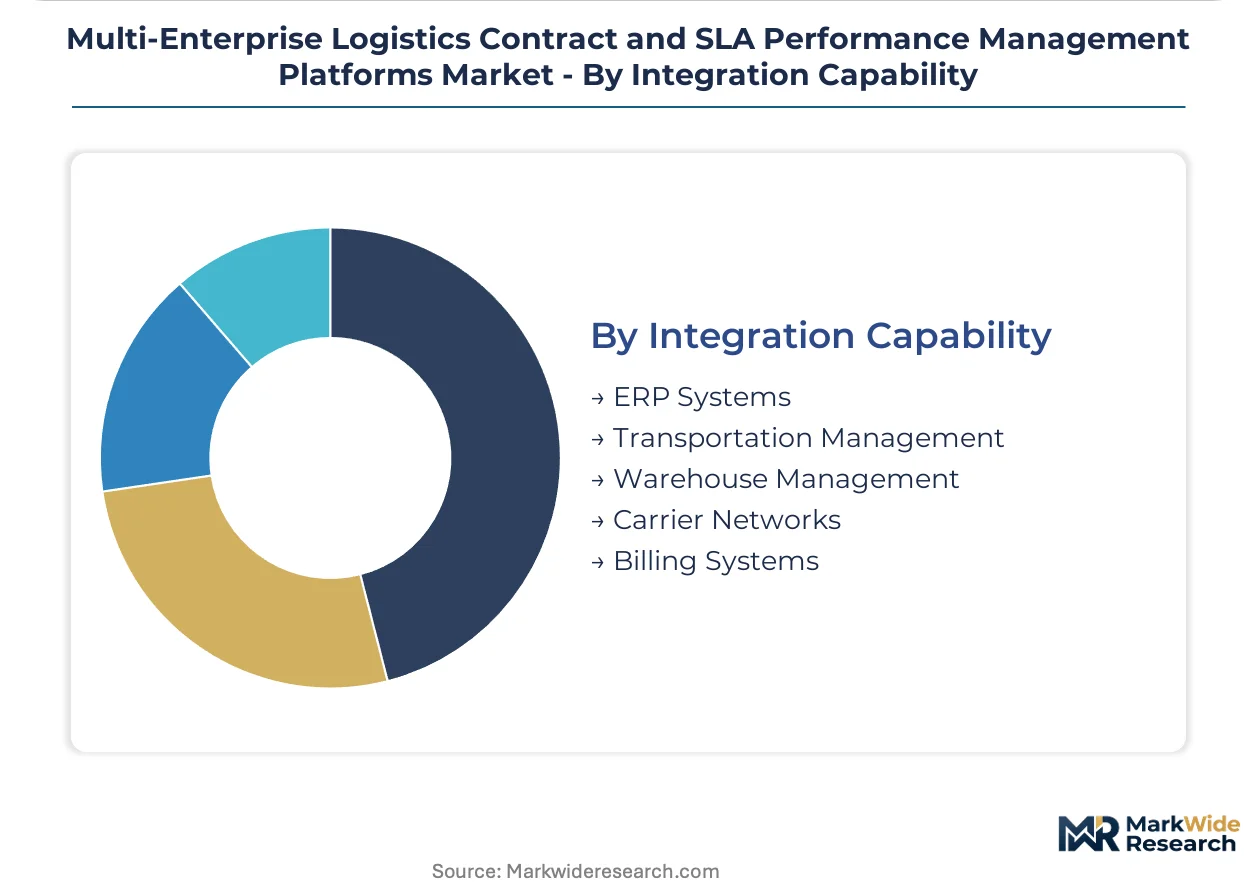
Integration Capability:
System connectivity depth determines whether SLA enforcement operates as a standalone overlay or embedded workflow within operational technology stacks.
- ERP Systems:SAP and Oracle financial modules receive automated penalty accruals and carrier payment holds. These integrations absorb 60-80% of implementation budgets due to legacy data schema complexity.
- Transportation Management:Native TMS embedding enables dispatch-level SLA visibility and proactive carrier intervention. This integration tier dominates enterprise shipper procurement requirements.
- Warehouse Management:Receiving dock scheduling and inventory put-away windows trigger automated breach detection. Distribution centers demand sub-second WMS synchronization for high-velocity fulfillment.
- Carrier Networks:EDI and API standardization layers normalize telematics feeds from heterogeneous trucking fleets. Custom mapping requirements inflate deployment costs for regional carriers.
- Billing Systems:Automated invoice reconciliation against contracted rates and penalty schedules. This capability reduces accounts payable overhead for Fortune 500 procurement teams.
ERP Systems integration commands the largest implementation spend; Transportation Management connectivity shows the steepest adoption curve as centralized logistics operations consolidate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise shipper consolidation concentrates platform demand in the United States, where Fortune 500 retailers mandate automated SLA enforcement across multimodal freight networks. Cloud-native architectures and API standardization are compressing deployment timelines in North American logistics corridors.
United States
Federal Motor Carrier Safety Administration hours-of-service mandates compel carriers to adopt automated compliance tracking, expanding platform addressable market across US freight networks. The FMCSA's electronic logging device requirements feed directly into carrier compliance tracking modules. Chicago and Memphis distribution clusters anchor Midwest logistics automation as Walmart, Target, and Kroger co-locate fulfillment centers and demand synchronized SLA enforcement across shared carrier pools.
Germany
EU AI Act algorithmic transparency requirements reshape how German logistics networks deploy automated penalty engines, mandating explainable decision trails for every SLA breach determination. GDPR data residency mandates and ISO 31000 risk management standards influence how multinational shippers structure performance guarantees. The Rhine-Ruhr industrial corridor hosts automotive manufacturers and pharmaceutical distributors maintaining hybrid deployments where sensitive contract terms reside on local servers while carrier telematics stream through cloud APIs.
Netherlands
Port congestion at Rotterdam accelerates demand for unified SLA tracking across containerized rail and vessel networks serving European distribution networks. EU driver working time directives require automated mapping of carrier documentation against compliance rules. Dutch freight forwarders in the Randstad region pilot blockchain-API convergence for immutable contract repositories combined with real-time event streaming.
United Kingdom
Post-Brexit customs brokerage complexity drives adoption of real-time monitoring across NVOCC networks handling EU-UK freight corridors. UK procurement teams prioritize predictive analytics modules that flag at-risk shipments before delivery windows expire. London and Southeast England concentrate third-party logistics providers demanding multi-tenant architectures supporting dozens of shipper clients with segregated contract data.
China
Yangtze River Delta and Pearl River Delta manufacturing clusters generate contract volumes for platforms managing complex carrier networks across export-oriented supply chains. SAMR data governance requirements and MIIT cloud computing standards shape platform procurement for multinational shippers operating in Chinese logistics markets. Shanghai and Shenzhen anchor demand for API-driven microservices architecture enabling real-time event correlation across TMS, WMS, and carrier EDI feeds.
Multi-Enterprise Logistics Contract and SLA Performance Management Platforms Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue API-native architectures and predictive analytics specialization. The vendor base stratifies across ERP-integrated incumbents, contract intelligence specialists, and logistics visibility platforms extending into SLA enforcement. Three archetypes dominate: database-centric enterprise suites, obligation extraction specialists, and transportation visibility platforms adding contractual layers. Competitive moves concentrate on strategic partnerships with TMS providers and portfolio diversification into predictive intervention capabilities.
Within the ERP-integrated tier, SAP and Oracle anchor positions through deep financial system connectivity that absorbs implementation budgets but locks in enterprise accounts. Sirion occupies the contract intelligence specialist position, exemplifying vendors that parse complex multi-carrier agreements for obligation extraction and compliance tracking. These three represent how competitive positioning depends on whether procurement teams prioritize system integration depth or standalone contract analytics flexibility.
| Leading Market Players |
|---|
| Sirion |
| Oracle |
| SAP |
| Coupa Software |
| Jaggaer |
| Keelvar |
| Descartes Systems Group |
| WiseTech Global |
| project44 |
| Others |
Pricing and Supply Chain Analysis
Cloud compute spot pricing indices cascade through platform vendor cost structures, compressing margins for subscription-based SLA management tools while amplifying pricing power for API-native architectures that meter consumption against freight volume volatility.
Pricing Analysis
Volume placements concentrate in high-margin contract repository modules while predictive analytics capabilities capture expanding share at premium price points. Three-tier pricing structure across enterprise, mid-market, and regional operator levels differentiates by integration depth and NLP engineering access. Pricing pressure stems from serverless infrastructure commoditizing compute costs for seasonal freight spikes. Mid-market 3PLs exhibit highest price sensitivity due to thin technology budgets; Fortune 500 shippers absorb premium tiers for ERP-embedded deployments.
Supply Chain Analysis
Dual-sourcing requirements mandate that enterprise shippers qualify at least two platform vendors per procurement cycle, fragmenting vendor concentration across the United States, Germany, and Netherlands. Software development draws from specialized NLP engineering pools, cloud infrastructure providers, and carrier API standardization consortia. Single-source vulnerability concentrates in contract intelligence talent markets where logistics domain expertise commands scarcity premiums. Distribution runs through direct enterprise sales, TMS vendor partnerships, and systems integrator channels serving regional 3PL networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time event streaming architectures are displacing legacy batch-processed contract analytics, compressing SLA breach detection from hours to seconds and enabling preemptive carrier intervention.
For Market Incumbents: To counter API-native entrants eroding mid-market share, SAP and Oracle must accelerate microservices rearchitecture of monolithic systems while embedding predictive analytics modules directly within TMS partnership ecosystems. Certification investment in ISO 31000 risk framework compliance creates defensible positioning for multinational shipper contracts. For New Entrants and Emerging Players: Capture white-space opportunity in rail-ocean intermodal corridors where port congestion at Los Angeles and Long Beach accelerates demand for unified SLA tracking. European freight networks present penetrable geography given EU AI Act compliance gaps among incumbent vendors. Go-to-market through direct integration with WiseTech Global and Descartes TMS platforms bypasses lengthy procurement cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor contract intelligence specialists with proven NLP extraction engines in German automotive and pharmaceutical verticals. Long-term viability hinges on platform differentiation beyond repository storage toward predictive intervention capabilities. Watch FMCSA enforcement intensity as inflection indicator for carrier compliance tracking module demand.| Strategic Initiative | Industry Significance |
|---|---|
| API-Native Architecture Migration | Serverless microservices enable sub-minute SLA breach detection for multimodal freight networks. |
| Predictive Analytics Module Launch | Machine learning models trained on historical breach patterns reduce penalty arbitration costs for procurement teams. |
| ISO 31000 Certification Investment | Compliance-certified vendors command premium pricing from multinational shippers embedding performance guarantees. |
| TMS Strategic Partnership | Native embedding within transportation management systems dominates enterprise shipper procurement requirements. |
| Blockchain-API Convergence Pilot | Immutable contract repositories combined with real-time streaming enable dispute-proof penalty automation for pharmaceutical freight. |
Research Methodology
Document review covered SEC 10-K filings, FMCSA enforcement databases, and EU regulatory submissions, complemented by interviews with 3PL operations directors, enterprise procurement officers, TMS integration specialists, and carrier compliance managers. Secondary sources included customs trade data, carrier telematics consortium reports, and ISO certification registries. Bottom-up platform deployment estimates triangulated against top-down enterprise technology spending surveys.
Historical deployment trajectories cross-referenced against panel input from logistics technology vendors established analytical boundaries across the projection horizon. Segmentation dimensions modeled encompassed platform architecture, feature set priority, end-user sector workflow, and integration capability tier. CAGRs derived from elasticity-adjusted adoption curves incorporating cloud infrastructure cost trajectories and carrier API standardization momentum.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement evolution and FMCSA hours-of-service rule modifications. Forecasts reflect assumptions around cloud migration velocity and mid-market 3PL consolidation patterns. A model refresh is warranted upon material change in carrier data standardization adoption rates or blockchain-API convergence commercialization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Third-Party Logistics (3PL) Market
Logistics and Shipping
Middle East and Africa Courier Market
Logistics and Shipping
GCC Secure Logistics Market
Logistics and Shipping
South Africa Air Freight Market
Logistics and Shipping
Thailand Courier Express Parcel (CEP) Market
Logistics and Shipping
Malaysia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Peru Freight and Logistics Market
Logistics and Shipping
Asia-Pacific Last Mile Delivery Market
Logistics and Shipping
South Korea Third-Party Logistics (3PL) Market
Logistics and Shipping
North America Freight and Logistics Market
Logistics and Shipping
Retail Logistics Market
Logistics and Shipping
Asia Pacific Freight and Logistics Market
Logistics and Shipping
UAE Contract Logistics Market
Logistics and Shipping
Apparel Logistics Market
Logistics and Shipping
United States Chartered Air Freight Transport Market
Logistics and Shipping
Mexico Freight Forwarding Market