
 Automotive Lightweighting Market | 2026-2036
Automotive Lightweighting Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Lightweighting Market Analysis
ISO 14001 environmental management certification is redrawing supplier qualification tiers across the Automotive Lightweighting Market. BASF SE leverages its polyurethane composite portfolio to anchor European OEM programs for battery enclosure applications. Novelis Inc. competes through closed-loop aluminum recycling, sustaining virgin-grade supply to North American stamping plants. Toray Industries, Inc. dominates carbon fiber prepreg output for structural members, extending its position through dedicated aerospace-to-automotive technology transfer.
Automotive lightweighting encompasses the systematic reduction of vehicle mass through advanced material substitution and structural optimization, typically targeting 20-40% weight savings versus conventional steel assemblies through high-strength aluminum alloys, carbon-fiber-reinforced polymers, or multi-material hybrid designs. The primary purpose is to improve fuel economy and extend electric vehicle range without compromising crashworthiness or cabin stiffness. Aluminum leads material type adoption due to established stamping infrastructure and cost-positioning between steel and carbon fiber, while composites represent the fastest-expanding margin pool as resin transfer molding cycle times compress. Body-in-white applications concentrate the highest value per kilogram saved, though powertrain enclosures are gaining share as battery mass creates offset requirements.
The EPA and NHTSA in the United States enforce Corporate Average Fuel Economy standards that escalate financial penalties for overweight fleets, directly accelerating aluminum and composite procurement. ECHA's REACH framework in Europe restricts certain heavy-metal additives in polymer formulations, forcing reformulation of glass-filled nylon compounds for interior brackets. China's MIIT mandates new-energy vehicle credit quotas that reward range-extended designs, amplifying lightweighting intensity for domestic EV platforms. Stakeholders must monitor how pending revisions to these frameworks alter material qualification timelines and cross-border certification reciprocity.
Market Dynamics
Electric vehicle battery mass is forcing structural redesign across the Automotive Lightweighting Market, as 500-kilogram battery packs demand compensatory mass reduction elsewhere to preserve range targets and chassis dynamics.
Growth Catalysts
- EU Green Deal fleet standards:Binding carbon-intensity targets for 2035 are compelling OEMs to redesign body-in-white architectures around aluminum-intensive platforms.
- MIIT new-energy vehicle credits:China's range-extended credit system rewards kilogram-efficient designs, accelerating composite adoption for domestic EV programs.
- Stuttgart-Munich engineering corridor:Concentrated OEM-Tier-1 co-location in southern Germany compresses prototype-to-production cycles for multi-material assemblies.
Market Restraints
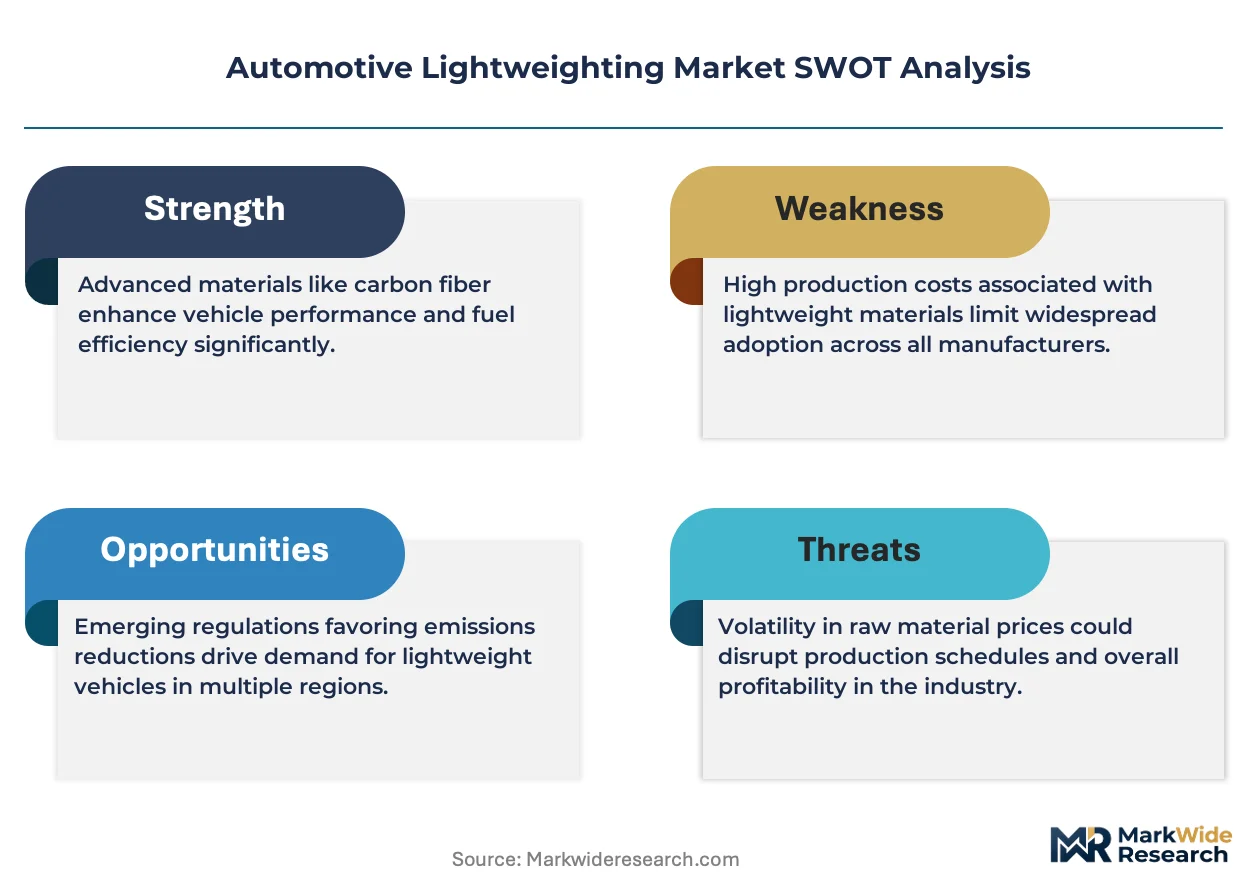
- Primary aluminum price volatility:London Metal Exchange pricing swings above fifteen percent annually destabilize stamping plant cost models.
- Carbon fiber supply concentration:Toray Industries and limited Japanese-Korean precursor manufacturers create single-source vulnerability for structural composite programs.
- ECHA REACH additive restrictions:Phased prohibitions on certain flame retardants force reformulation of glass-filled nylon compounds, extending qualification timelines.
Strategic Opportunities
- Indian PLI scheme for EV components:Production-linked incentives for domestic battery and lightweight structure manufacturing open greenfield capacity.
- Resin transfer molding cycle compression:Sub-three-minute cure chemistries are enabling carbon fiber fender and hood applications previously reserved to aluminum.
- Closed-loop aluminum recycling infrastructure:Novelis-style scrap-to-sheet systems offer virgin-grade material security independent of primary smelter capacity.
Industry Challenges
- Multi-material joining expertise gap:Adhesive selection and corrosion management between aluminum-steel-composite interfaces require specialized process engineering talent scarce in traditional stamping operations.
- Crashworthiness recertification timelines:NCAP protocol updates for electric vehicle platform safety extend validation cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Lightweighting Market |
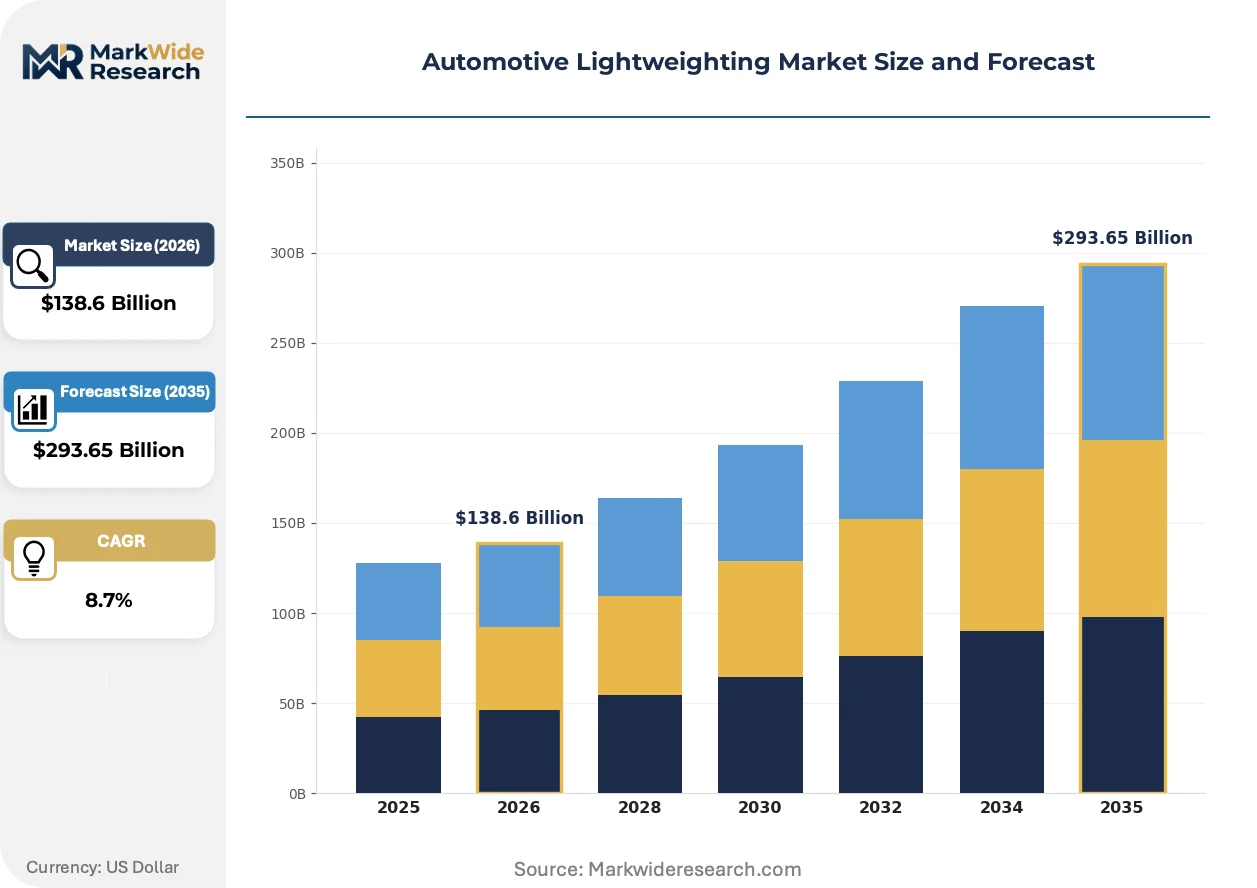
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $293.65 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Carbon Fiber, Steel, Composites Vehicle Type: SUVs, Sedans, Trucks, Hybrids Application: Body, Chassis, Interior, Powertrain Manufacturing Process: Stamping, Casting, Welding, Injection Molding |
| Companies Covered | BASF SE, Toray Industries, Inc., LyondellBasell Industries, Novelis Inc., ArcelorMittal, Alcoa Corporation, Covestro AG, Constellium SE, Thyssenkrupp AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Lightweighting Market Emerging Trajectories
Material substitution velocity is accelerating as battery mass creates hard constraints on vehicle efficiency, compressing the traditional decade-long material transition cycles into three-to-four-year platform redesign windows.
Hot-stamped ultra-high-strength steel grades above 1500 MPa are displacing conventional mild steel in B-pillar and roof rail applications, enabling Porsche and BMW to maintain cabin integrity while shaving twelve to eighteen kilograms from legacy sedan architectures. Tier-1 suppliers are retrofitting existing press lines for die-quenching cycles, preserving capital deployment while capturing performance tier pricing.
NHTSA CAFE penalty escalation is tightening fleet-average weight thresholds, forcing Detroit Three manufacturers to accelerate aluminum door and hood programs originally scheduled for 2028-2030 introduction. The EPA enforcement trajectory is compressing supplier qualification windows, privileging material systems with existing automotive validation histories over novel composite alternatives.
Fleet procurement departments are consolidating lightweighting specifications across vehicle platforms, replacing model-specific material calls with modular aluminum-composite hybrid kits. Tier-1 stamping divisions in Michigan and Ontario are reorganizing around platform-agnostic subassembly cells, reducing tooling changeover friction and capturing scale economics previously reserved to high-volume steel programs.
Automotive Lightweighting Market Segmentation
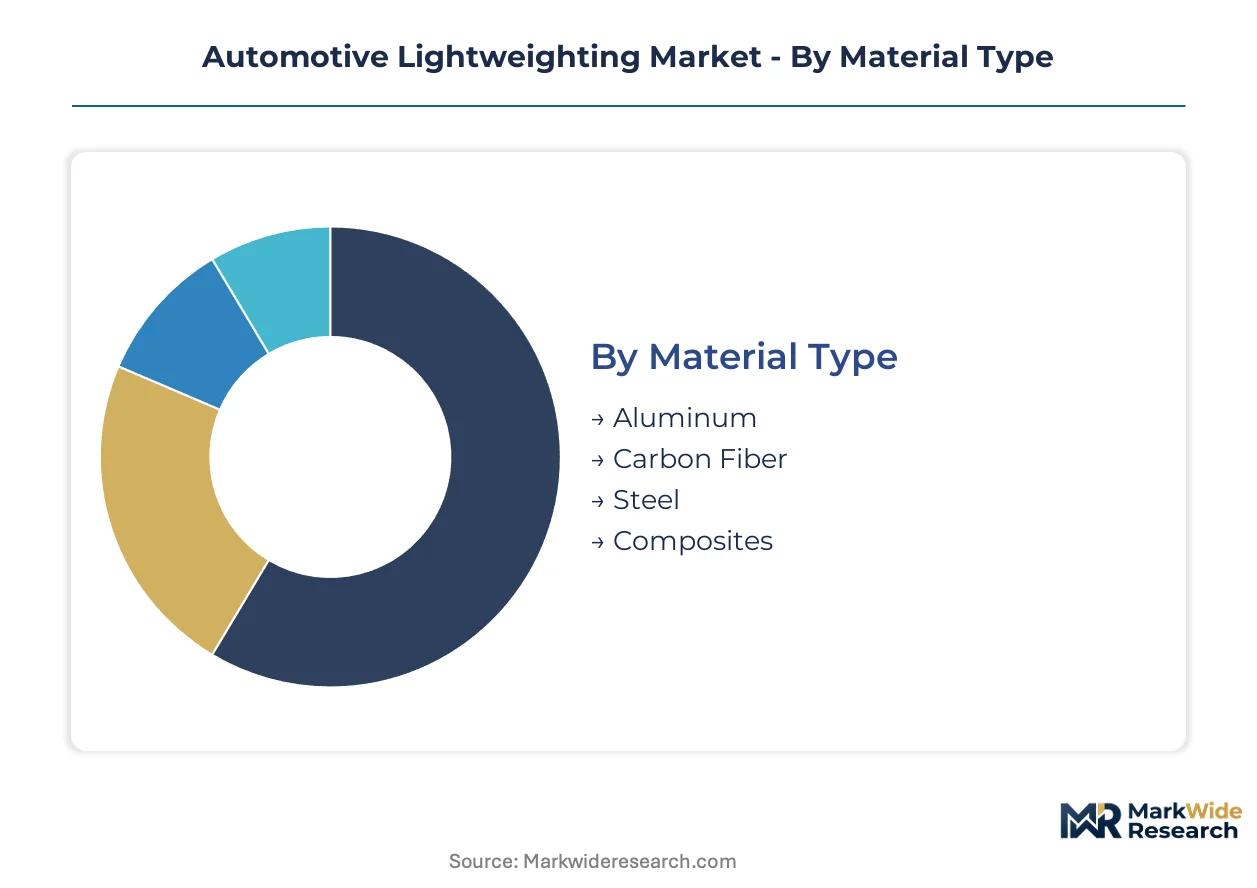
Material substitution pressure varies sharply across Automotive Lightweighting Market segments, with battery mass forcing divergent cost-performance trade-offs between aluminum platforms and composite-intensive architectures. Procurement teams segment supplier portfolios by joining complexity, recyclability thresholds, and crash certification velocity to match platform-specific mass reduction targets.
Material Type:
Substitution threat from carbon fiber and advanced composites intensifies most acutely against aluminum, where resin transfer molding cycle compression is eroding traditional cost barriers.
- Aluminum:High-strength 6000-series and 7000-series alloys dominate body-in-white stampings, with 5xxx and 6xxx grades specified for closure panels. Demand concentrates in Stuttgart and Munich engineering corridors where OEM-Tier-1 co-location accelerates multi-material prototype cycles. Established stamping infrastructure and closed-loop recycling systems sustain cost positioning between steel and carbon fiber alternatives.
- Carbon Fiber:PAN-based and pitch-based carbon fiber prepregs deliver 50-70% weight reduction versus steel in structural members and battery enclosures. Toray Industries and limited Japanese-Korean precursor manufacturers concentrate supply, creating single-source vulnerability for North American EV programs targeting extended range ratings.
- Steel:Hot-stamped ultra-high-strength grades above 1500 MPa retain B-pillar and roof rail applications where cabin integrity requirements resist full aluminum substitution.
- Composites:Glass-fiber-reinforced and natural-fiber-reinforced thermoplastics serve interior brackets and non-structural panels, though ECHA REACH additive restrictions force ongoing reformulation of flame-retardant compounds.
Aluminum anchors the volume base while carbon fiber gains share at the steepest rate.
Vehicle Type:
Platform architecture diverges by powertrain mass, with battery-heavy segments demanding compensatory lightweighting intensity that reshapes material specification hierarchies.
- SUVs:High curb weights and aerodynamic drag penalties drive aluminum-intensive body structures and composite hood assemblies. German OEMs specify mixed-material platforms for premium SUV architectures to preserve handling dynamics against 500-kilogram battery packs.
- Sedans:Lower mass baselines and streamlined aerodynamics permit selective aluminum door and closure programs rather than full body-in-white redesign. Detroit Three manufacturers accelerate aluminum hood and decklid introductions originally scheduled for later platform cycles.
- Trucks:Payload and towing requirements sustain steel frame rails and high-strength steel cab structures, with aluminum limited to hood, tailgate, and bed applications where mass reduction does not compromise structural load paths.
- Hybrids:Smaller battery packs relative to full-electric platforms reduce compensatory lightweighting pressure, permitting cost-optimized multi-material strategies blending aluminum closures with steel unibody construction.
Trucks maintain steel-dominant architectures while SUVs exhibit the most aggressive material substitution velocity.
Application:
Value per kilogram saved peaks where crashworthiness and stiffness requirements intersect with the largest surface areas and thickest gauge reductions.
- Body:Body-in-white applications concentrate the highest value per kilogram saved, with aluminum-intensive architectures and carbon fiber roof panels delivering 20-40% mass reduction. Hot-stamped steel retains strategic placements for cabin integrity.
- Chassis:Suspension components and subframes shift toward aluminum castings and carbon fiber control arms as EV battery mass increases unsprung weight sensitivity. Casting process expertise determines supplier qualification tiers.
- Interior:Structural seat frames, instrument panel carriers, and door modules adopt glass-filled nylon and long-fiber-reinforced thermoplastics. ECHA REACH restrictions on heavy-metal additives force reformulation timelines.
- Powertrain:Battery enclosures and electric motor housings emerge as high-growth applications, with aluminum extrusions and carbon fiber composite shields protecting thermal runaway containment zones.
Body applications command premium material specifications while powertrain gains share most rapidly.
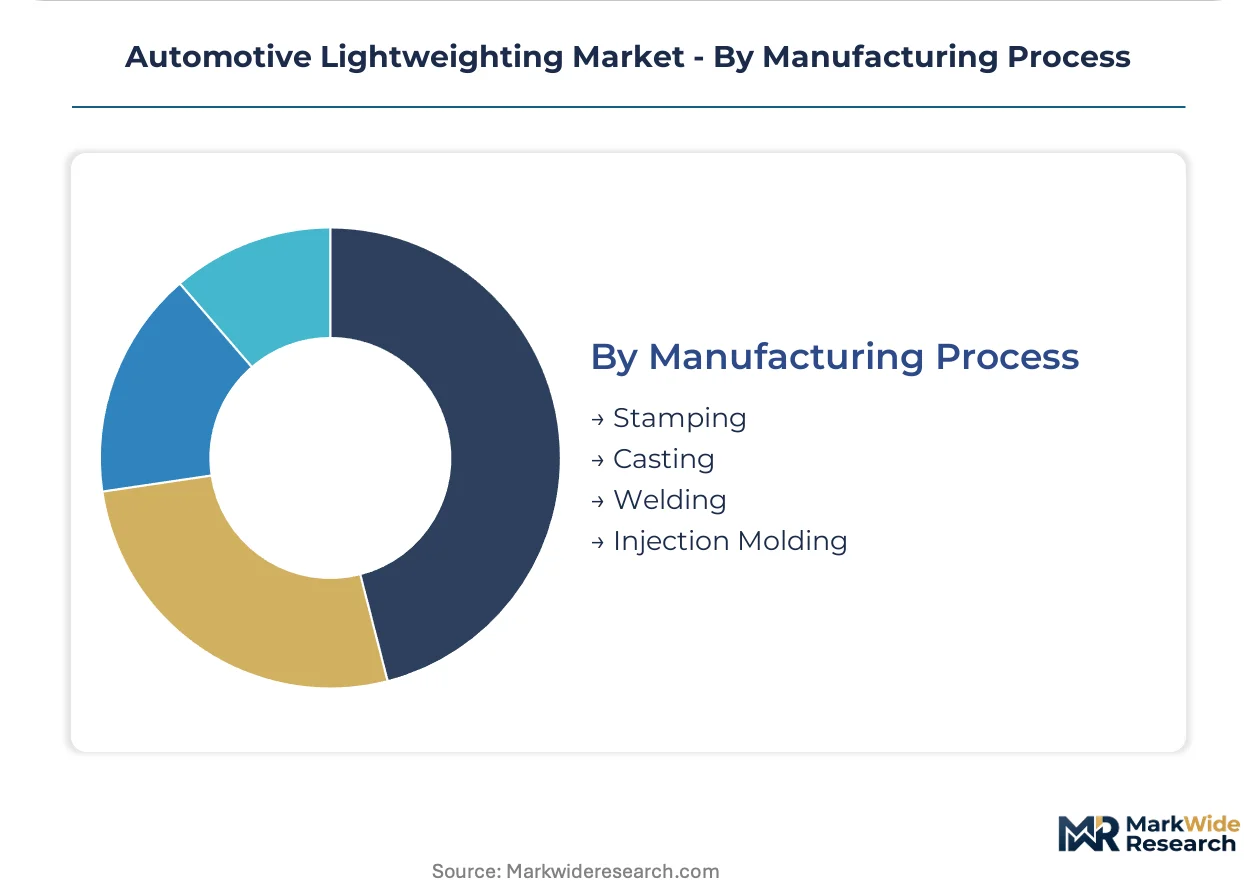
Manufacturing Process:
Process selection locks in capital deployment trajectories and supplier capability requirements across multi-decade platform lifecycles.
- Stamping:High-speed press lines with die-quenching capability process 6000-series aluminum at volumes exceeding 100,000 units annually. Tier-1 suppliers in Michigan and Ontario reorganize around platform-agnostic subassembly cells.
- Casting:High-pressure die casting and squeeze casting produce complex aluminum chassis nodes and battery enclosure structures with thin-wall geometries impossible in stamping. Vacuum-assisted processes reduce porosity for structural applications.
- Welding:Friction stir welding and laser welding join dissimilar materials in multi-material assemblies, though adhesive selection and galvanic corrosion management require specialized process engineering talent scarce in traditional operations.
- Injection Molding:Long-fiber-reinforced thermoplastic compounds serve interior brackets and non-structural panels, with sub-three-minute cycle times enabling carbon fiber fender applications previously reserved to aluminum.
Stamping retains the broadest installed base while casting captures the steepest capacity expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEM engineering centers concentrate procurement authority for aluminum-intensive architectures, while Chinese MIIT credit systems and US EPA enforcement create divergent compliance pathways for multi-material platform development.
Germany
The Stuttgart-Munich corridor anchors European lightweighting engineering, with BMW and Porsche specifying mixed-material platforms for premium EV architectures. KBA enforces EU Green Deal fleet standards that tighten through 2035, compelling full body-in-white redesigns. Supplier co-location around Ingolstadt and Wolfsburg compresses prototype-to-production cycles for aluminum-composite hybrid assemblies.
United States
Detroit Three manufacturers accelerate aluminum door and hood programs to offset NHTSA CAFE penalty escalation for overweight fleets. EPA enforcement trajectories compress supplier qualification windows, privileging material systems with existing automotive validation histories. Tier-1 stamping divisions in Michigan and Ontario reorganize around platform-agnostic subassembly cells to capture scale economics.
China
Domestic EV platforms drive the steepest composite adoption curves as MIIT new-energy vehicle credits reward range-extended designs with kilogram-efficient structures. SAMR oversees GB standards for battery enclosure safety that intersect with lightweighting requirements. Yangtze River Delta manufacturing clusters concentrate high-pressure aluminum die casting capacity for battery tray production.
Japan
Toray Industries and precursor manufacturers concentrate carbon fiber supply for structural composite programs serving both automotive and aerospace qualification pathways. METI supports dual carbon goals through material efficiency mandates that amplify lightweighting intensity. Nagoya-area engineering centers transfer aerospace prepreg expertise to automotive battery enclosure applications.
India
PLI scheme production-linked incentives for domestic EV component manufacturing open greenfield capacity for battery and lightweight structure fabrication. BIS certification requirements for aluminum alloy grades extend qualification timelines for imported material systems. Tamil Nadu and Gujarat automotive corridors attract Tier-1 suppliers establishing regional stamping and casting operations.
Automotive Lightweighting Market Vendor Landscape
Player mix skews toward integrated materials-science conglomerates with captive polymer, metal, and composite portfolios. BASF SE and Covestro AG anchor chemical-specialist positions, while ArcelorMittal and Thyssenkrupp AG represent steel-centric incumbents pivoting toward multi-material solutions. Three strategic archetypes dominate: closed-loop aluminum recyclers, carbon fiber precursor manufacturers, and high-pressure die casting specialists. Competitive moves concentrate on vertical integration into scrap-to-sheet systems and resin transfer molding cycle compression partnerships.
Within the chemical-specialist tier, BASF SE and Covestro AG occupy positions defined by polyurethane and polycarbonate portfolio breadth rather than single-material dominance. Novelis Inc. exemplifies the closed-loop recycler archetype, with geographic naming indicating North American operational concentration. Toray Industries, Inc. anchors the carbon fiber supply tier, its Japanese corporate structure reflecting precursor manufacturing concentration. These three represent distinct capability vectors—polymer formulation, metal recycling integration, and advanced fiber production—that structure supplier qualification tiers across OEM engineering centers.
| Leading Market Players |
|---|
| BASF SE |
| Toray Industries, Inc. |
| LyondellBasell Industries |
| Novelis Inc. |
| ArcelorMittal |
| Alcoa Corporation |
| Covestro AG |
| Constellium SE |
| Thyssenkrupp AG |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day aluminum coil inventory buffers at North American stamping plants tether pricing power to London Metal Exchange volatility, while OEM procurement teams leverage platform-agnostic subassembly contracts to compress supplier margins across the Automotive Lightweighting Market.
Pricing Analysis
Cost-plus contracts indexed to LME primary aluminum pricing dominate high-volume stamping agreements, with premium-mid-economy pricing differentiation separating aerospace-grade 7000-series alloys from standard 6000-series automotive grades. Price differentiation hinges on ISO 14001 environmental certification status and closed-loop scrap-recycling guarantees. Cost compression in standard-grade aluminum intensifies because Chinese smelter capacity expansions soften regional spot markets. Fleet procurement departments at volume OEMs exhibit highest price sensitivity, while premium German OEMs prioritize qualification velocity over unit cost.
Supply Chain Analysis
Forty-five-day carbon fiber prepreg lead times from Japanese precursor manufacturers expose North American EV programs to single-source vulnerability, while aluminum coil inventory draws from German, Chinese, and Canadian smelter networks. Raw material dependencies center on petroleum-based PAN precursor, bauxite ore grades, and high-purity magnesium alloying additions. Supply chain risk concentrates in tariff exposure for Chinese aluminum extrusions entering US battery enclosure fabrication. Distribution runs through Tier-1 stamping divisions in Michigan and Ontario, with just-in-time delivery to OEM body-in-white assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Closed-loop aluminum recycling services and scrap-to-sheet logistics contracts are expanding faster than virgin material sales, creating a service-attach layer that restructures supplier-OEM relationships toward long-term material stewardship agreements.
For Market Incumbents: Shield market position by deepening captive recycling infrastructure and securing ISO 14001 certification ahead of EU Green Deal supplier tier redraws. Prioritize backward integration into scrap collection networks to offset primary aluminum price volatility exposure. For New Entrants and Emerging Players: Differentiate on resin transfer molding cycle compression for carbon fiber fender applications, targeting Indian PLI scheme greenfield capacity where domestic battery enclosure demand outpaces established supplier footprints. Pursue joint qualification programs with Yangtze River Delta EV platforms to accelerate OEM validation timelines. For Investors and Strategic Acquirers: Long-term, this sits as a materials-circular-economy play because regulatory frameworks are embedding recyclability thresholds into OEM procurement mandates. Target high-pressure die casting specialists with vacuum-assisted porosity control capabilities. Watch for MIIT credit scheme revisions that alter composite adoption curves in domestic Chinese EV programs.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Recycling Infrastructure | Novelis-style scrap-to-sheet systems secure virgin-grade supply independent of LME volatility. |
| Resin Transfer Molding Partnership | Sub-three-minute cure chemistries enable carbon fiber applications previously reserved to aluminum. |
| Platform-Agnostic Subassembly Cells | Tier-1 stamping divisions in Michigan capture scale economics through reduced tooling changeover friction. |
| Multi-Material Joining Capability Investment | Friction stir welding expertise addresses adhesive selection and galvanic corrosion management gaps. |
| Battery Enclosure Certification Fast-Track | SAMR GB standards compliance accelerates qualification for Yangtze River Delta manufacturing clusters. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, SEC 10-K filings, and customs/trade records, combining structured interviews with Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and dealership operations managers. Bottom-up volume estimates triangulate against top-down market sizing across material type, vehicle class, and regional production cluster dimensions.
Segmentation dimensions modeled include propulsion architecture, content per vehicle, OEM tier, and regional production hub, with value projections derived from material substitution velocity curves and platform redesign cycle compression observed across the analysis window. Forecast inputs incorporate battery mass offset requirements and ECHA REACH reformulation timelines affecting glass-filled nylon qualification.
Material uncertainties — primary aluminum price swings, carbon fiber precursor supply disruptions, and NCAP protocol revisions — sit outside the modeled envelope, with outputs reflecting documented assumptions about regulatory enforcement trajectories and OEM platform standardization decisions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Germany Automotive Composites Market
Automotive Components
Automotive Part Cleaners and Degreasers Market
Automotive Components
United States Aftermarket Automotive Parts and Components Market
Automotive Components
Automobile Accessories Market
Automotive Components
Torque Vectoring Market
Automotive Components
Global Automotive Radiator Market
Automotive Components
Automotive Bushing Technologies Market
Automotive Components
Automotive Metal Timing Chain Market
Automotive Components
France Automotive Electric Actuators Market
Automotive Components
South Korea Automotive Pneumatic Actuators Market
Automotive Components
Global Cylinder Deactivation System Market
Automotive Components
Automobile Fluid Pipe Products Market
Automotive Components
Sheet Molding Compound (SMC) for Automotive Market
Automotive Components
Remote Automotive Exhaust Sensing Market
Automotive Components
Automotive Bearing Market
Automotive Components
Europe Automotive Electric Actuators Market