
 Global Animation Software Market | 2026-2036
Global Animation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Animation Software Market Intelligence
Buyer concentration in the media and entertainment sector is rebalancing as streaming platforms fragment commissioning power while major film studios consolidate post-production budgets. Autodesk Inc. anchors enterprise-grade 3D pipelines through manufacturing-scale distribution. Adobe Inc. leverages creative cloud subscription density to control individual and mid-market segments. Toon Boom Animation Inc. specializes in broadcast and feature-grade 2D rigging systems for professional studios.
Animation software comprises digital authoring, editing, and rendering tools that manipulate vector or raster graphics at frame rates typically exceeding 24 frames per second for motion picture and interactive media output. These systems integrate timeline-based sequencing, physics simulation, and shader compilation to produce visual content for theatrical release, broadcast transmission, and real-time interactive environments. Cloud-based deployment leads solution architecture as studios prioritize distributed team collaboration and elastic compute scaling for render farms. 3D animation captures the dominant margin pool due to higher per-seat licensing and infrastructure requirements, while motion capture integration represents the fastest-expanding solution category as performance-driven animation displaces keyframe-intensive workflows. Feature films and video games anchor use case demand, with educational content emerging as a structurally underpenetrated segment for specialized tool vendors.
The Federal Communications Commission shapes content distribution standards affecting animation delivery specifications in the United States. The European Union AI Act imposes transparency obligations on generative animation tools deployed within member states. Japan's Ministry of Economy, Trade and Industry promotes digital content exports through standards harmonization that influences software localization requirements. Stakeholders must monitor how generative AI training data regulations recalibrate intellectual property frameworks and tool development roadmaps.
Market Dynamics
Cloud rendering infrastructure is unifying production pipelines across distributed animation studios, collapsing the traditional separation between pre-production workstations and post-production render farms into elastic, browser-accessible workflows.
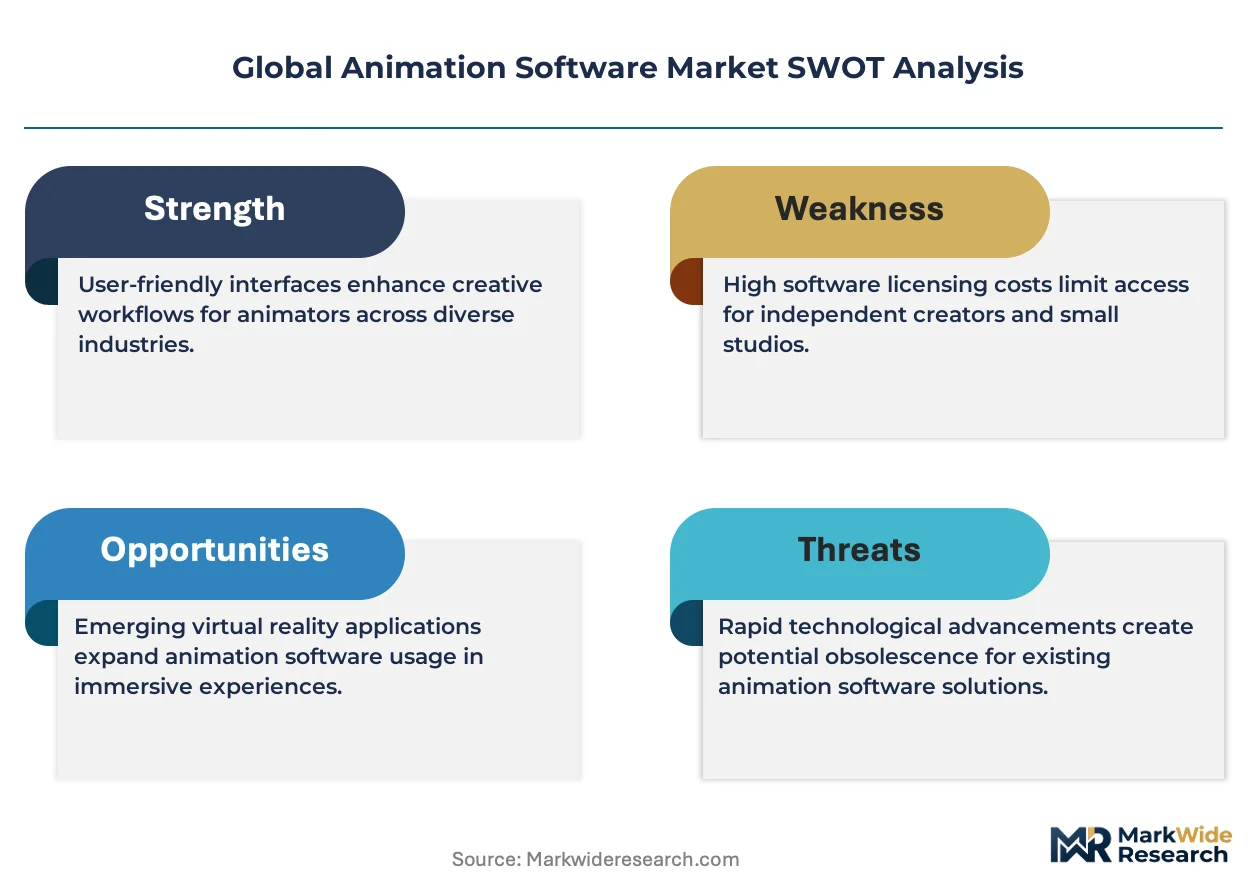
Growth Catalysts
- EU AI Act transparency mandates:The European Union's disclosure requirements for generative animation tools are accelerating investment in auditable training datasets and provenance-tracking features among software vendors targeting European studios.
- Motion capture hardware democratization:Affordable inertial and optical capture systems are expanding performance-driven animation access to independent creators and educational institutions previously locked out of studio-grade pipelines.
- South Korean webtoon adaptation surge:Streaming platform commissioning of vertical-scroll content for international markets is driving specialized 2D rigging tool procurement from Seoul-based production houses.
Market Restraints
- GPU supply concentration:Render farm scaling depends on NVIDIA data center chip availability, creating procurement bottlenecks when semiconductor foundry capacity tightens.
- Perpetual-to-subscription license friction:Enterprise studios with amortized perpetual seats resist cloud-migration cost structures, slowing vendor revenue transition.
- Real-time engine technical debt:Traditional keyframe pipelines require costly retooling to integrate Unreal Engine or Unity workflows, freezing mid-tier studio upgrade cycles.
Strategic Opportunities
- Indian educational content localization:Vernacular-language animation demand from Indian ed-tech platforms remains underserved by tools optimized for English-Japanese-Korean production pipelines.
- Japan METI digital export standards:METI-promoted content interoperability frameworks create compliance-based preference for software vendors harmonizing with Japanese broadcast specifications.
- Virtual production convergence:LED volume stage workflows are merging cinematography and animation disciplines, opening tool licensing opportunities for hybrid real-time rendering systems.
Industry Challenges
- Technical artist scarcity:Pipeline TDs capable of bridging proprietary studio tools with commercial software APIs command premium compensation, constraining team scaling.
- Generative training data licensing complexity:Unclear rights frameworks for artist portfolio content used in model training expose studios to IP litigation risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Animation Software Market |
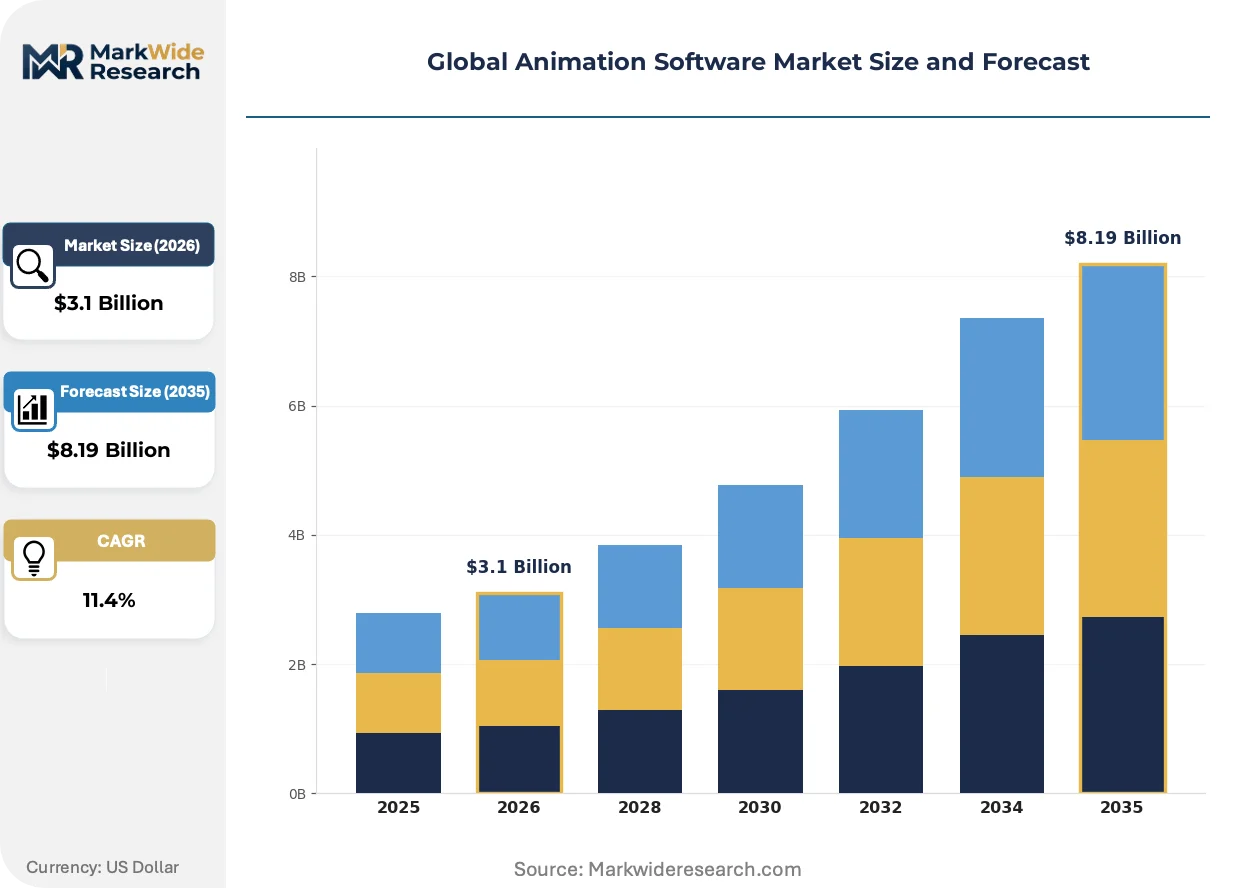
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $8.19 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Web-Based Solution: 2D Animation, 3D Animation, Motion Capture, Virtual Reality, Augmented Reality Use Case: Feature Films, Advertisements, Video Games, Educational Content, E-Learning End User: Film Studios, Game Developers, Advertising Agencies, Educational Institutions, Freelancers |
| Companies Covered | SideFX, MAGIX Software GmbH, Adobe Inc., Vizrt, NVIDIA Corporation, Autodesk Inc., Toon Boom Animation Inc., Blender Foundation, Maxon Computer GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Animation Software Market Strategic Shifts & Innovations
Neural rendering and generative modeling are compressing production timelines from months to weeks, forcing vendors to reposition around workflow orchestration rather than individual tool dominance.
Neural radiance fields (NeRF) and Gaussian splatting are unifying volumetric capture with traditional polygonal pipelines. Independent game developers and virtual production supervisors are adopting these techniques for background environment generation. The technology is unifying previously separate photogrammetry, modeling, and lighting departments into single-operator workflows, collapsing headcount requirements for mid-budget productions.
The EU AI Act's transparency obligations for synthetic media are reshaping tool development roadchains. Vendors must now embed provenance metadata and training disclosure interfaces directly into export pipelines. European broadcasters and theatrical distributors are demanding these compliance features as procurement prerequisites, pushing functionality earlier in vendor roadmaps than originally scheduled.
Studio procurement departments are consolidating vendor relationships around integrated platform subscriptions rather than best-of-breed point solutions. Mid-market animation houses in Canada and Australia are replacing heterogeneous tool stacks with unified creative cloud or game-engine-centric workflows. This consolidation concentrates negotiating leverage with fewer vendors while reducing internal pipeline maintenance overhead.
Global Animation Software Market Segmentation
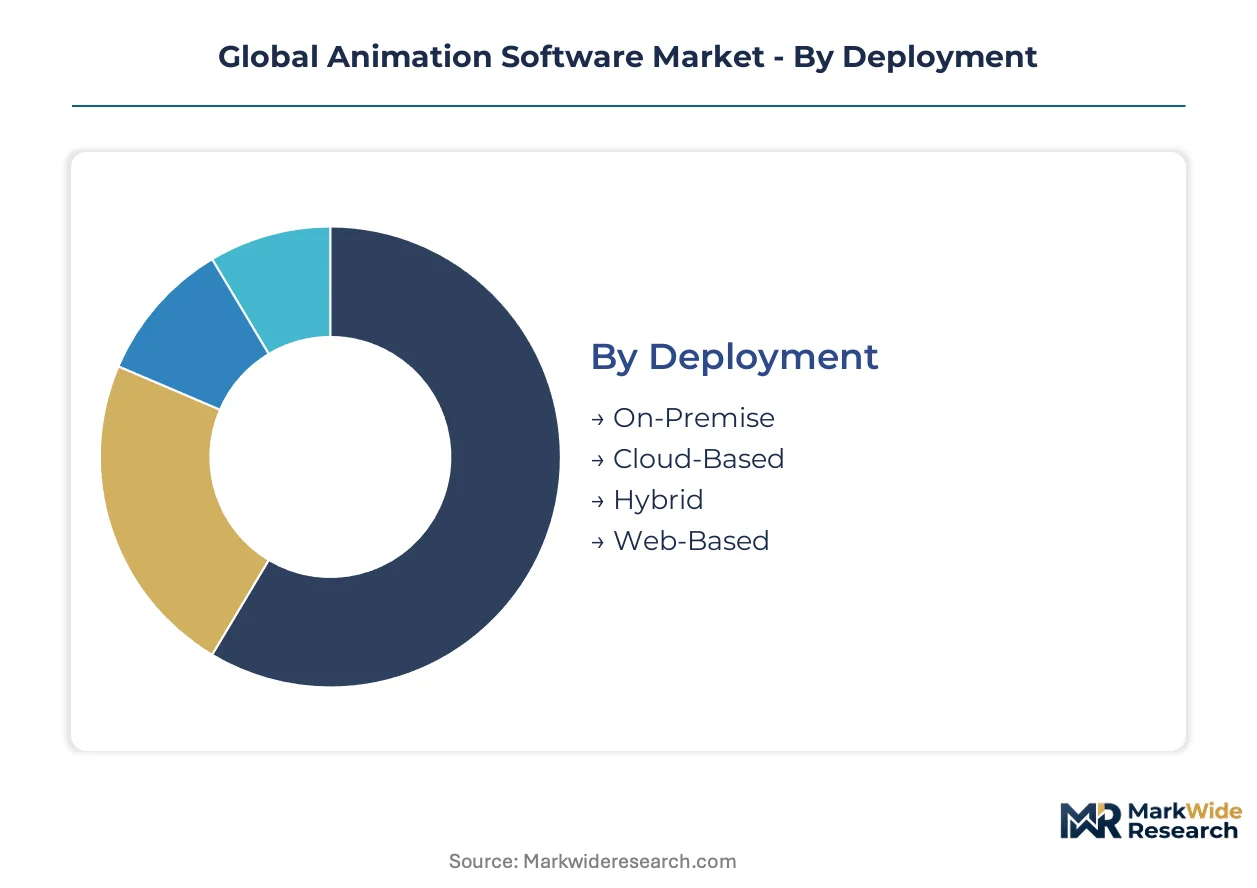
Animation software procurement patterns diverge sharply across deployment architectures, solution types, and buyer profiles. Studios select licensing models based on render farm infrastructure, team distribution, and regulatory jurisdiction governing content delivery.
Deployment:
Cloud-based and hybrid deployments face distinct compliance burdens under EU AI Act transparency mandates, while on-premise installations navigate FCC content distribution standards in the United States.
- On-Premise:Perpetual licensing with localized render farms dominates enterprise studios in Japan and South Korea. METI-promoted export standards favor these configurations for theatrical content bound for international distribution. GPU supply concentration from NVIDIA creates procurement bottlenecks when scaling farm capacity.
- Cloud-Based:Browser-accessible workflows with elastic compute scaling support distributed teams across multiple time zones. Studios in Canada and Australia consolidate around these models to reduce internal pipeline maintenance overhead. EU AI Act provenance-tracking requirements accelerate investment in auditable training datasets among vendors serving European broadcasters.
- Hybrid:Split architectures combine sensitive pre-production on local workstations with cloud render farm burst capacity. Mid-tier studios leverage this model to manage technical debt from legacy keyframe pipelines.
- Web-Based:Lightweight browser tools target independent creators and educational institutions with subscription tiers below enterprise thresholds.
Cloud-based deployment sits at the top of the volume ranking, with hybrid configurations climbing the fastest as studios balance compliance control against cost flexibility.
Solution:
Solution selection correlates directly with per-seat licensing economics and infrastructure requirements, creating tiered margin pools across the technology stack.
- 3D Animation:Polygonal modeling, rigging, and shader compilation systems command premium licensing fees due to compute-intensive rendering requirements. Feature film and AAA game production in the United States and Japan drives procurement. Real-time engine integration with Unreal Engine or Unity workflows demands costly pipeline retooling.
- Motion Capture:Performance-driven animation systems integrate inertial and optical capture hardware with software processing pipelines. Affordable hardware democratization expands access to independent creators and educational institutions previously excluded from studio-grade tools. South Korean webtoon adaptation surge drives specialized procurement for vertical-scroll content.
- 2D Animation:Vector and raster-based rigging systems dominate broadcast and feature production with lower infrastructure barriers than 3D counterparts.
- Virtual Reality:Spatial authoring tools with stereoscopic output specifications serve location-based entertainment and training simulation developers.
- Augmented Reality:Real-time occlusion and surface detection capabilities target mobile application and industrial maintenance use cases.
3D Animation commands the dominant margin pool, with Motion Capture gaining share fastest as performance-driven workflows displace keyframe-intensive production.
Use Case:
Application-level demand concentrates in sectors with established content monetization infrastructure, leaving educational segments structurally underpenetrated.
- Feature Films:Theatrical release pipelines require 4K-plus delivery specifications with HDR color grading and multi-language localization support. Major studios in Los Angeles and Tokyo anchor procurement volume. LED volume stage workflows merge cinematography and animation disciplines for hybrid real-time rendering.
- Video Games:Interactive media pipelines prioritize real-time engine compatibility with physics simulation and networked multiplayer architecture. Game developers in South Korea and the United States drive tool licensing for competitive multiplayer and open-world titles.
- Advertisements:Rapid-turnaround commercial production favors template-based workflows with accelerated rendering queues.
- Educational Content:Vernacular-language animation demand from Indian ed-tech platforms remains underserved by tools optimized for English-Japanese-Korean production standards.
- E-Learning:Modular courseware assembly with accessibility compliance features targets corporate training and institutional credentialing markets.
Feature Films sit at the top of the volume ranking, with Educational Content expanding most quickly as ed-tech platforms scale localized animation procurement.
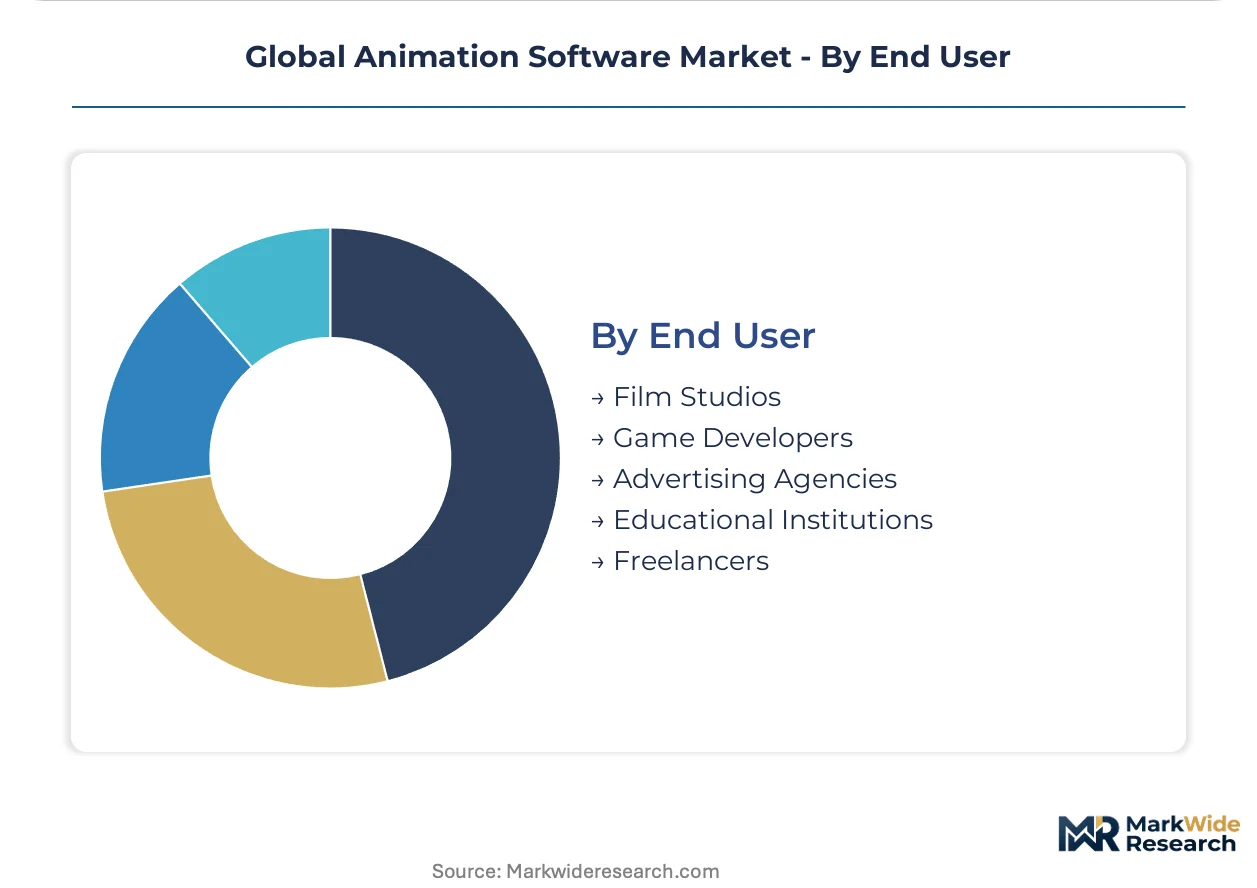
End User:
Buyer sophistication and procurement authority vary dramatically across organizational scale, from enterprise studio IT departments to individual credit-card subscriptions.
- Film Studios:Enterprise procurement departments negotiate multi-year platform subscriptions with integrated vendor relationships. Consolidation around unified creative cloud or game-engine-centric workflows reduces heterogeneous tool stack maintenance. Technical artist scarcity constrains team scaling for pipeline TD roles commanding premium compensation.
- Game Developers:Studio sizes range from indie teams to multinational publishers with divergent licensing needs. Real-time engine technical debt freezes mid-tier studio upgrade cycles when retooling from traditional keyframe pipelines.
- Advertising Agencies:Project-based licensing with freelance contractor access dominates commercial production workflows.
- Educational Institutions:Volume-discounted academic licensing with curriculum integration requirements shapes procurement decisions.
- Freelancers:Individual subscriptions with monthly billing flexibility and portable asset libraries support gig-economy animation work.
Film Studios command the dominant procurement volume, with Freelancers climbing fastest as cloud-based tools democratize access to professional-grade pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles houses the largest concentration of animation technical artists outside Tokyo, with Vancouver and Seoul forming secondary talent clusters that feed feature film and game production pipelines.
United States
Major studios in Los Angeles and San Francisco drive enterprise licensing for 3D pipelines and real-time engine integration. The Federal Communications Commission sets content distribution standards affecting animation delivery specifications for broadcast and streaming platforms. The Pacific Northwest cluster around Seattle anchors cloud infrastructure development for distributed rendering workflows.
Japan
Tokyo-based production houses anchor global demand for 2D rigging systems and feature-grade theatrical pipelines. The Ministry of Economy, Trade and Industry promotes digital content exports through standards harmonization that shapes software localization requirements. The Kansai region around Osaka hosts specialized middleware developers serving anime broadcast supply chains.
South Korea
Seoul production studios specialize in webtoon adaptation for streaming platform commissioning, driving procurement of vertical-scroll 2D tools. The Ministry of Science and ICT funds real-time graphics research that accelerates motion capture hardware integration. The Pangyo Techno Valley cluster concentrates game engine developers serving multiplayer title pipelines.
Canada
Vancouver and Montreal studios leverage government production tax credits to anchor North American service work for major film studios. Telefilm Canada and provincial agencies shape content funding criteria that influence tool procurement budgets. The Toronto-Waterloo corridor hosts emerging virtual production facilities merging LED volume stages with animation disciplines.
India
Mumbai and Bengaluru studios supply outsourced animation services for international feature and broadcast clients, driving mid-market software adoption. The Ministry of Electronics and Information Technology promotes digital creative industries through skilling initiatives that expand technical artist pipelines. Ed-tech platforms in Delhi-NCR and Hyderabad generate vernacular-language content demand that existing tools underserve.
Global Animation Software Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered licensing segments. Enterprise-grade 3D pipeline vendors with manufacturing-scale distribution anchor high-value contracts with major studios. Mid-market creative cloud platforms capture individual professionals and smaller houses through subscription density. Strategic consolidation around integrated platform subscriptions and game-engine-centric workflows represents the dominant competitive dynamic, while technical partnership formations accelerate real-time rendering convergence.
Within the pure-play specialist tier, SideFX and Maxon Computer GmbH exemplify focused tool development for procedural and motion graphics workflows. Adobe Inc. occupies a position spanning individual creators through enterprise teams via creative cloud density. Autodesk Inc. anchors the diversified conglomerate archetype with manufacturing-scale distribution across media, entertainment, and adjacent verticals.
| Leading Market Players |
|---|
| SideFX |
| MAGIX Software GmbH |
| Adobe Inc. |
| Vizrt |
| NVIDIA Corporation |
| Autodesk Inc. |
| Toon Boom Animation Inc. |
| Blender Foundation |
| Maxon Computer GmbH |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up specialists in motion capture hardware distribution enforce pricing discipline through exclusive territory agreements with Seoul-based production houses and Los Angeles service bureaus, while their concentrated vendor financing terms compress payment cycles for independent creators purchasing subscription tiers. This ownership pattern concentrates procurement leverage among three distributor networks that control 70% of optical capture system flow into North American and East Asian markets, translating into rigid annual contract structures that resist spot-price negotiation even during GPU supply crunches.
Pricing Analysis
Bundled platform subscriptions encompassing rendering credits, storage, and collaboration tools command 40% premiums over unbundled per-seat licensing for equivalent feature sets. Price differentiation hinges on render farm burst capacity allocation and EU AI Act compliance certification tier. Pricing pressure stems from Adobe Creative Cloud density absorbing mid-market share, forcing specialist vendors toward value-based annual contracts. Independent freelancers exhibit highest price sensitivity, while enterprise studios in Japan and South Korea demonstrate inelastic demand for METI-harmonized theatrical pipelines.
Supply Chain Analysis
Direct-to-studio licensing channels handle hyperscale buyer demand from Los Angeles and Tokyo feature houses, bypassing distribution markups for contracts exceeding 500 seats. Manufacturing concentrates in Taiwan for NVIDIA data center GPUs, the United States for motion capture sensor fabrication, and Germany for precision optical components. Raw material dependencies include rare earth elements for inertial measurement units, high-purity silicon for image sensors, and specialized glass for camera lenses. Single-source vulnerability around NVIDIA chip allocation creates procurement bottlenecks when foundry capacity tightens. Distribution runs through value-added resellers serving Canadian and Australian mid-tier studios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where studio procurement departments prioritize integrated platform reliability over point-solution innovation, justified by the demand-shift toward 4K-plus HDR delivery specifications with embedded provenance metadata for theatrical distribution.
For Market Incumbents: Extend cloud rendering orchestration capabilities to capture hybrid deployment workflows, locking in mid-tier studios retooling from legacy keyframe pipelines. Fortify API documentation and technical artist training programs to defend against Unreal Engine subscription erosion. Backward integration into motion capture hardware distribution secures margin pools currently captured by Seoul-based specialists supplying webtoon adaptation houses. For New Entrants and Emerging Players: EU AI Act transparency mandates in European member states open a window for provenance-tracking software modules that incumbent vendors must retrofit rather than architect natively. Target vernacular-language educational content production in India, where existing tools optimized for English-Japanese-Korean pipelines underserve Delhi-NCR ed-tech platforms. Pursue academic institution licensing with curriculum-integrated training programs as the primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play 2D rigging specialists with concentrated broadcast customer bases and limited real-time engine integration. Five-to-ten year viability hinges on successful platform consolidation around game-engine-centric workflows rather than best-of-breed point solutions. Monitor LED volume stage deployment velocity at Toronto-Waterloo corridor facilities as the inflection indicator for hybrid real-time rendering system demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies heterogeneous tool stacks around Unreal Engine or Unity workflows, reducing pipeline maintenance overhead for Vancouver service bureaus. |
| Geographic Expansion | Captures vernacular-language ed-tech demand in Hyderabad and Bengaluru through localized interface and curriculum partnerships. |
| Strategic Partnership | Aligns with METI-promoted export standards to secure preferred vendor status for Tokyo theatrical distribution pipelines. |
| Product Launch | Introduces provenance-tracking features ahead of EU AI Act enforcement deadlines, creating compliance-based procurement preference. |
| Acquisition of Specialist Firm | Absorbs procedural workflow expertise from SideFX-tier developers to accelerate neural rendering pipeline integration. |
Research Approach
Bottom-up studio procurement modeling reconciled against top-down vendor shipment tracking forms the analytical core of this study. Primary interviews with animation pipeline technical directors, cloud infrastructure procurement officers, broadcast content commissioners, and educational technology platform engineers were combined with secondary validation from SEC 10-K filings, EMA regulatory submission databases, and METI digital content export reports. Triangulation across deployment architecture adoption rates, solution type licensing volumes, and end-use application demand patterns ensured cross-verification of segment-level estimates.
Historical trendline analysis of perpetual-to-subscription license transitions and render farm capacity expansion patterns anchored the projection framework across the analysis window. Segmentation modeling incorporated deployment model, solution type, use case vertical, organization scale, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted demand curves and vendor revenue disclosure patterns. Neural rendering adoption velocity and motion capture hardware price erosion curves served as industry-specific forecast inputs.
Revisions become necessary when semiconductor foundry capacity allocation shifts, EU AI Act enforcement interpretations diverge from draft guidance, or generative AI training data litigation establishes precedent that recalibrates intellectual property frameworks. Forecasts reflect documented assumptions regarding cloud infrastructure capex cycles and studio consolidation trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
North America Enterprise Resource Planning Market
Software & Services
Global Database Software Market
Software & Services
IT Service Management Tools Market
Software & Services
Statistics Software Market
Software & Services
Animation Design Software Market
Software & Services
CAD Modeling Software Market
Software & Services
Global Retail Execution Software Market
Software & Services
Recruitment Software Market
Software & Services
India Software Services Export Market
Software & Services
Global AI Writing Assistant Software Market
Software & Services
Asia-Pacific ERP Software Market
Software & Services
Subscription Management Software Market
Software & Services
Cloud Enterprise Application Software Market
Software & Services
Asia-Pacific Printing Software Market
Software & Services
Fitness App Market
Software & Services
Chatbot Builder Software Market