
 Statistics Software Market | 2026-2036
Statistics Software Market Size, Share, and Industry Trends Forecast 2026-2036
Statistics Software Market Analysis
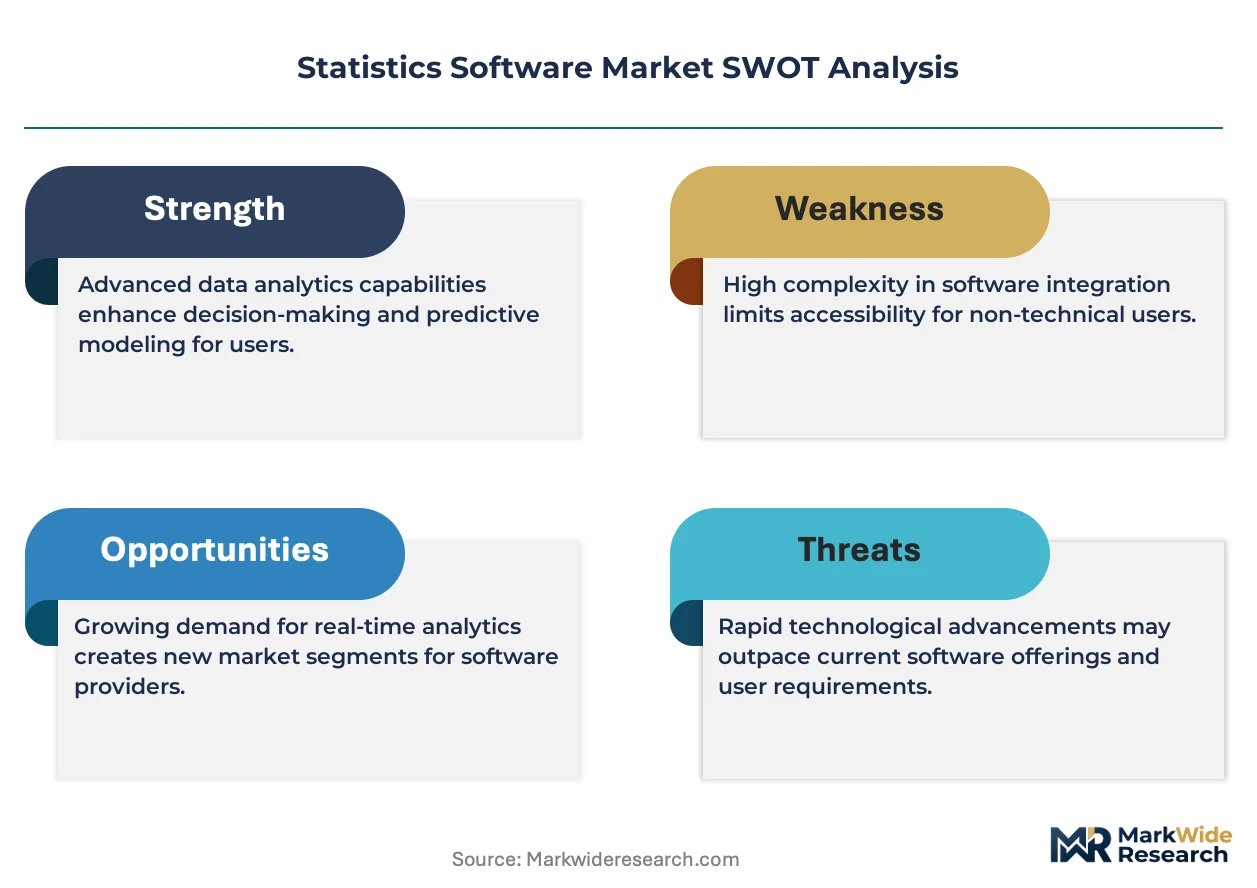
The EU AI Act is realigning procurement criteria for statistical platforms across regulated industries in Europe. SAS Institute leverages decades of specialized analytics expertise to sustain competitive positioning in government and healthcare verticals. IBM anchors its portfolio through hybrid cloud architectures that bridge on-premises statistical workloads with elastic compute environments. StataCorp specializes in academic and research-oriented statistical computing, occupying a defensible niche against broader enterprise suites.
Statistics software encompasses computational applications designed to perform quantitative data analysis, hypothesis testing, regression modeling, and multivariate analysis, typically supporting datasets ranging from thousands to billions of observations with integrated visualization engines. These tools serve primary commercial purposes across pharmaceutical trials, financial risk quantification, supply chain optimization, and policy evaluation. Cloud and SaaS deployment models represent the fastest-expanding segment as enterprises migrate from perpetual licenses to consumption-based analytics infrastructure. Web-based solutions are capturing share from traditional desktop installations among mid-market buyers prioritizing collaboration and reduced IT overhead. Machine learning applications within statistical platforms are drawing disproportionate R&D investment as vendors integrate automated model selection and neural network capabilities alongside classical inferential methods.
The FDA governs statistical validation requirements for clinical trial software through 21 CFR Part 11 electronic records standards, while the SEC mandates algorithmic transparency in quantitative trading systems under Regulation SCI and MiFID II influences for cross-border operations. ISO/IEC 27001 certification shapes vendor selection criteria for enterprises handling sensitive statistical datasets. EMA guidelines on statistical methodology in drug development create compliance-driven replacement cycles for pharmaceutical analytics tools. Stakeholders must evaluate whether their statistical infrastructure investments align with emerging algorithmic accountability frameworks and evolving data residency requirements across jurisdictions.
Market Dynamics
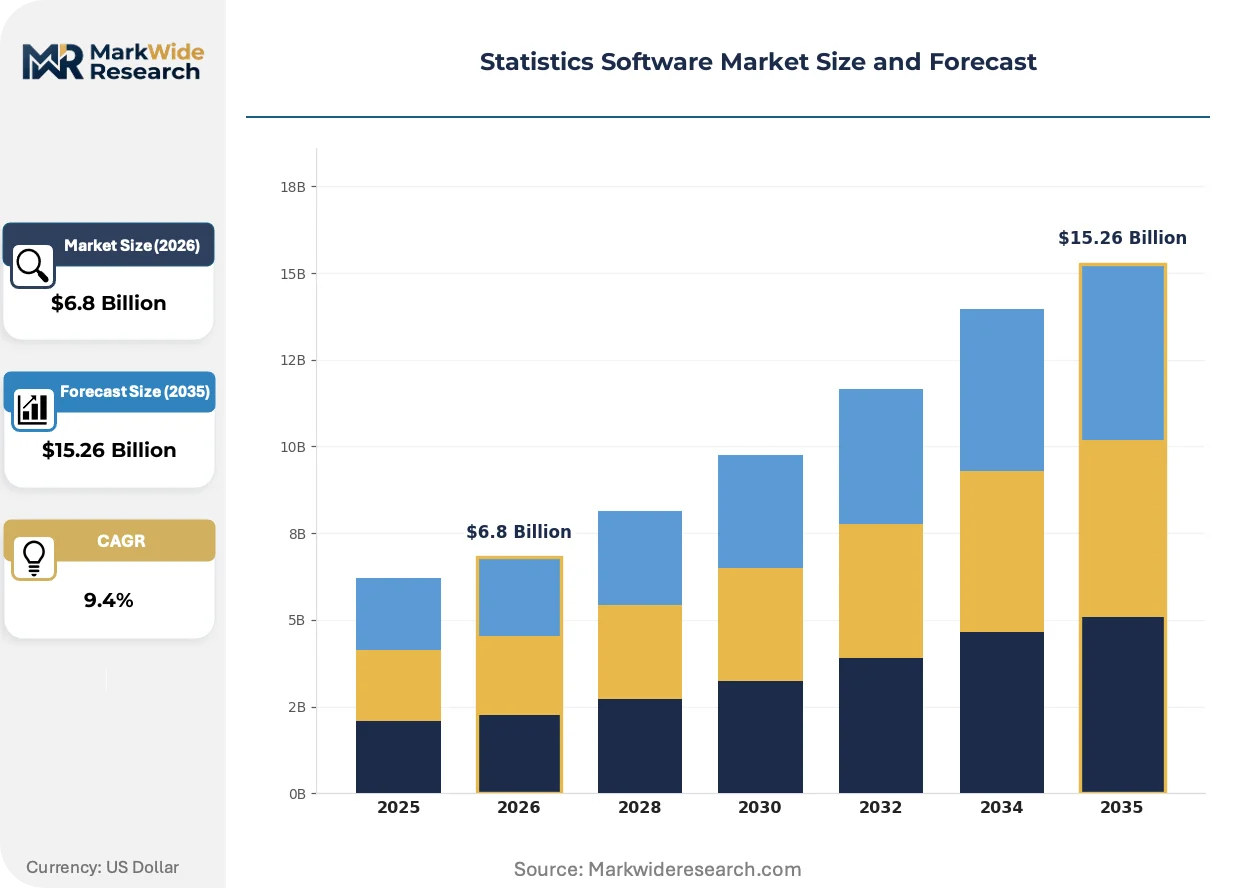
Cloud-native statistical infrastructure is displacing perpetual license models as enterprise buyers prioritize elastic compute consumption over fixed-capital software investments. This shift compresses vendor revenue recognition cycles while expanding addressable markets among mid-tier organizations previously priced out of on-premises deployments.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records standards for clinical trial software mandate validated statistical platforms, forcing pharmaceutical sponsors into compliance-driven procurement cycles that favor established vendors with pre-validated infrastructure.
- Healthcare predictive analytics:Hospital systems and payers deploy real-time risk stratification tools requiring integrated statistical engines capable of processing streaming patient data alongside historical cohorts.
- Machine learning convergence:Automated model selection and neural network capabilities embedded within classical statistical platforms expand user bases beyond trained statisticians to domain specialists.
Market Restraints
- Specialized talent scarcity:Shortage of professionals bridging classical inferential statistics with modern machine learning engineering constrains implementation velocity at enterprise scale.
- Data residency fragmentation:Divergent national requirements for statistical dataset localization force vendors into costly multi-region infrastructure replication.
- Open-source substitution:R and Python ecosystems with extensive package libraries erode pricing power for commercial platforms in academic and research segments.
Strategic Opportunities
- EU AI Act compliance services:Algorithmic accountability requirements for high-risk statistical decision systems create attach-rate opportunities for audit and validation modules.
- Edge statistical computing:Lightweight inference engines deployed on manufacturing equipment and medical devices enable real-time quality control without cloud latency.
- Consumption-based pricing:Metered analytics infrastructure lowers barriers for mid-market buyers in India and Southeast Asia previously excluded from enterprise licensing tiers.
Industry Challenges
- Legacy system integration:Mainframe-era statistical repositories in financial services resist API-based connectivity, requiring costly middleware development.
- ISO/IEC 27001 certification timelines:Six-to-twelve month security audit cycles delay vendor qualification for sensitive government and healthcare contracts.
- Interpretability standards:Regulatory demands for explainable model outputs conflict with black-box neural network architectures, forcing architectural compromises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Statistics Software Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Software, Web-based Solutions, Mobile Applications, Add-ons Deployment: Cloud, On-premises, Hybrid, SaaS End User: Academic Institutions, Research Organizations, Enterprises, Government Agencies Application: Data Analysis, Predictive Modeling, Statistical Reporting, Machine Learning |
| Companies Covered | SAS Institute, IBM, StataCorp, The MathWorks, Minitab, SAP, TIBCO Software, Qlik, JMP Statistical Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Statistics Software Market Emerging Trajectories
Computational architectures and compliance frameworks are converging to reshape how statistical capabilities are delivered, consumed, and governed across industries. Three developments dominate this transformation.
Containerized statistical workloads are modularizing deployment patterns across enterprise IT environments. Kubernetes-orchestrated analytics pods allow biostatistics teams to spin up validated environments for specific trial phases without provisioning permanent infrastructure. Pharmaceutical sponsors at mid-scale operations now adopt these patterns fastest, compressing traditional six-month procurement cycles into days while fragmenting vendor account control.
GDPR Article 22 provisions on automated decision-making are tightening documentation requirements for statistical scoring systems used in credit and insurance. EU national data protection authorities enforce algorithmic impact assessments that demand reproducible analytical pipelines with version-controlled parameters. Cross-border financial services firms respond by embedding audit trails directly into statistical workflow engines, treating compliance infrastructure as product feature rather than overhead.
Academic licensing models face pressure from browser-based collaboration platforms that eliminate local installation entirely. Research consortia in genomics and climate science now prioritize shared notebook environments with real-time co-editing over individual desktop packages. This behavioral shift concentrates procurement authority at institutional IT departments rather than departmental principal investigators, altering vendor sales motion from faculty relationships to enterprise contracting teams.
Statistics Software Market Segmentation
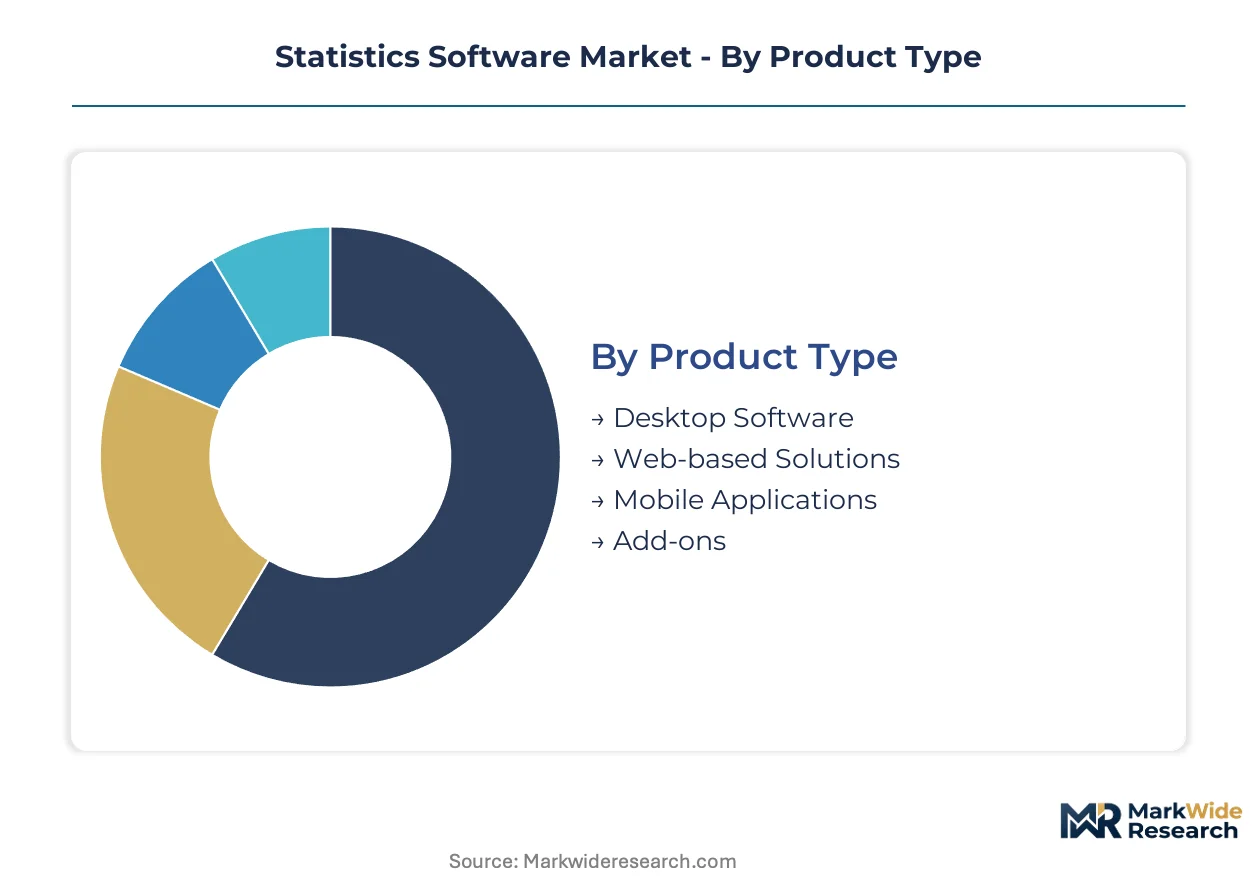
Segmentation in statistics software reveals how computational requirements, compliance constraints, and user sophistication fragment procurement patterns across buyer types. Vendors must architect distinct go-to-market motions for each axis, as cloud-native healthcare deployments share little operational DNA with academic desktop licenses.
Product Type:
Architectural modality determines infrastructure requirements, update cadence, and revenue recognition timing for platform vendors.
- Desktop Software:Local installation packages with perpetual licensing dominate regulated environments requiring air-gapped validation. Pharmaceutical sponsors at Merck KGaA and Boehringer Ingelheim maintain SAS and Stata deployments on isolated workstations to satisfy FDA 21 CFR Part 11 audit trails without cloud exposure.
- Web-based Solutions:Browser-accessible platforms with collaborative notebook environments are displacing individual licenses in multi-institutional research consortia. The European Molecular Biology Laboratory and CERN prioritize shared computational workspaces with version-controlled statistical pipelines over siloed desktop installations.
- Mobile Applications:Lightweight inference engines for field data collection and rapid dashboarding serve epidemiological surveillance teams and agricultural extension services requiring offline functionality.
- Add-ons:Modular extensions—custom R packages, Python libraries, and vendor-specific plugins—extend core platform capabilities for specialized methodologies like causal inference or spatial statistics.
Desktop software leads on scale; web-based solutions lead on momentum.
Deployment:
Delivery mechanism governs capital intensity, data residency compliance, and integration complexity for enterprise buyers.
- Cloud:Elastic compute environments with consumption-based pricing lower barriers for mid-market pharmaceutical and financial services firms. AWS GovCloud and Azure Government regions address public sector requirements while avoiding on-premises infrastructure overhead.
- On-premises:Perpetual license models with dedicated hardware persist in banking stress-testing operations and classified government analytics where external network connectivity is prohibited.
- Hybrid:Split architectures process sensitive patient or trading data locally while pushing anonymized aggregates to cloud environments for model training. German automotive suppliers and Swiss private banks favor this pattern to reconcile GDPR constraints with computational scalability.
- SaaS:Fully managed multi-tenant platforms with automatic updates capture share among small and mid-sized enterprises lacking dedicated IT analytics staff.
On-premises retains the largest installed base; cloud deployments are climbing the fastest.
End User:
Organizational context shapes pricing tolerance, feature requirements, and sales cycle duration.
- Academic Institutions:Site licenses with deep educational discounts sustain R and Python ecosystem dominance. MIT, ETH Zurich, and Tsinghua University negotiate multi-year enterprise agreements covering thousands of researchers while tolerating limited vendor support.
- Research Organizations:Grant-funded consortia prioritize reproducibility infrastructure and open-source interoperability over polished interfaces. The Broad Institute and Francis Crick Institute invest heavily in workflow orchestration layers atop statistical compute clusters.
- Enterprises:Revenue-generating analytics operations demand validated environments, SLA guarantees, and dedicated customer success resources. JPMorgan Chase and Novo Nordisk pay substantial premiums for vendor indemnification and regulatory pre-certification.
- Government Agencies:Procurement through federal supply schedules and framework contracts emphasizes security certification and domestic data residency. The US Census Bureau and UK Office for National Statistics mandate ISO/IEC 27001 and FedRAMP compliance as baseline qualifiers.
Enterprises generate the highest revenue per seat; academic institutions represent the steepest expansion trajectory for open-source alternatives.
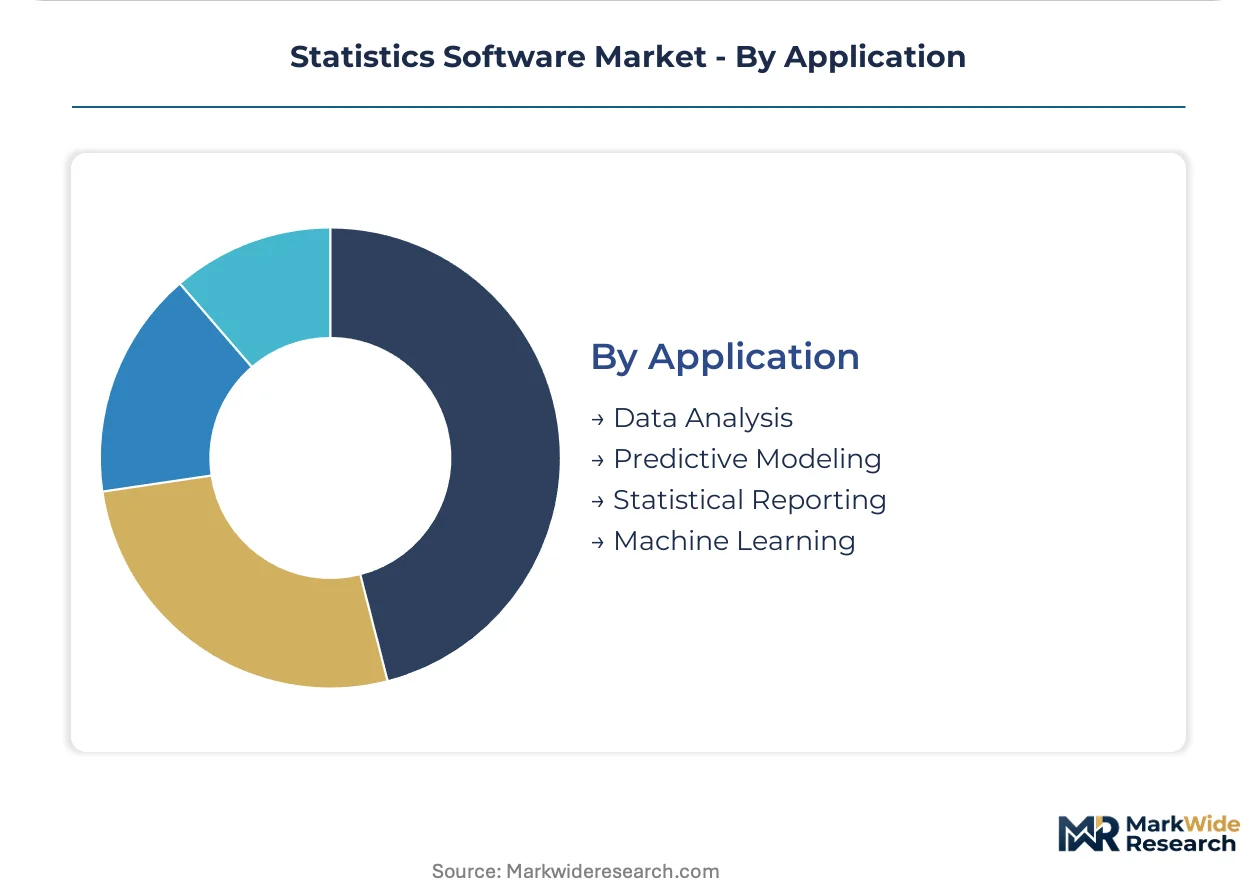
Application:
Functional use case determines algorithmic sophistication, visualization requirements, and interpretability standards.
- Data Analysis:Descriptive statistics and exploratory data visualization serve quality control and operational reporting across manufacturing and healthcare. FDA-regulated medical device manufacturers require validated summary statistics for batch release documentation.
- Predictive Modeling:Regression, time series forecasting, and risk scoring drive demand in insurance pricing and supply chain planning. EU AI Act compliance requirements are tightening documentation standards for high-risk predictive systems in credit and employment.
- Statistical Reporting:Automated generation of regulatory submissions, clinical study reports, and peer-reviewed manuscripts demands templated output formats and audit trails. EMA and FDA guidance on statistical methodology in drug development shapes feature roadmaps.
- Machine Learning:Neural network integration and automated model selection expand user bases beyond trained statisticians to domain specialists in radiology and materials science. Interpretability mandates from financial regulators conflict with black-box architectures, forcing explainable AI module development.
Data analysis commands the broadest user base; machine learning applications are gaining share fastest among vendor R&D investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Statistical computing originated in academic and government research centers across the United States during the 1960s, with early development concentrated at North Carolina State University and federal statistical agencies. This institutional foundation established patterns of public-sector procurement and university licensing that persist in contemporary market structure.
United States
Federal agencies and pharmaceutical sponsors in Maryland and New Jersey drive demand for validated statistical platforms. FDA 21 CFR Part 11 mandates electronic records standards that force compliance-driven procurement cycles among clinical trial sponsors. The Research Triangle Park cluster anchors biostatistics infrastructure development for contract research organizations.
Germany
Automotive suppliers and financial services firms in Munich and Frankfurt require hybrid statistical architectures reconciling GDPR constraints with computational scale. The national data protection authority enforces algorithmic impact assessments under GDPR Article 22 for credit scoring systems. Baden-Württemberg manufacturing consortia deploy edge statistical computing for real-time quality control.
United Kingdom
London-based quantitative trading operations and Cambridge genomics institutes sustain dual demand streams for statistical infrastructure. FCA and PRA guidelines on model risk management shape procurement criteria for banking stress-testing platforms. The Oxford-Cambridge-London triangle concentrates academic and commercial R&D investment in reproducible analytical pipelines.
India
IT services exporters in Bangalore and Hyderabad integrate statistical engines into client-facing analytics offerings. RBI guidelines on model governance for credit risk systems drive adoption of documented statistical workflows among scheduled commercial banks. The Pune-Ahmedabad corridor hosts captive centers for global pharmaceutical sponsors requiring offshore biostatistics capacity.
Japan
Automotive OEMs and electronics manufacturers in Nagoya and Osaka deploy statistical process control for precision manufacturing. METI initiatives on Society 5.0 promote AI-statistics convergence in industrial quality systems. The Kansai region maintains specialized statistical computing infrastructure for materials science and semiconductor yield optimization.
Statistics Software Market Vendor Landscape
Capital-heavy platform vendors compete with asset-light open-source ecosystems in a bifurcated structure. The market consolidates around established incumbents with decades of regulatory pre-certification while fragmenting among specialized academic tools and cloud-native entrants. Three archetypes dominate: legacy enterprise suites with government vertical expertise, research-oriented desktop packages, and consumption-based cloud analytics platforms. Competitive moves center on M&A for machine learning capabilities and strategic partnerships for multi-cloud deployment.
Among legacy enterprise vendors, SAS Institute and IBM exemplify the regulated-industry archetype with sustained positioning in government and healthcare procurement. StataCorp occupies a defensible niche representing the academic-specialist tier against broader enterprise suites. These three anchor points illustrate how vendor strategy diverges between compliance-driven account control and researcher-accessibility priorities.
| Leading Market Players |
|---|
| SAS Institute |
| IBM |
| StataCorp |
| The MathWorks |
| Minitab |
| SAP |
| TIBCO Software |
| Qlik |
| JMP Statistical Software |
| Others |
Supply Flow & Price Mechanics
Backward integration into cloud infrastructure anchors both supply position and pricing power for statistics software vendors. Vendors operating captive data center networks in the United States and Germany command premium positioning against pure-SaaS competitors dependent on third-party hyperscaler capacity.
Pricing Analysis
Consumption-based subscription tiers with metered compute credits dominate enterprise procurement, separating validated FDA 21 CFR Part 11-compliant environments from standard cloud offerings. Price differentiation rests on certification grade and geographic data residency, with EU sovereign cloud deployments commanding substantial premiums over standard AWS or Azure regions. Cost compression in mid-market SaaS tiers is intensifying because R and Python ecosystems erode pricing power for non-specialized statistical functions. Academic institutions exhibit the highest price sensitivity, while pharmaceutical sponsors under FDA mandate show the lowest.
Supply Chain Analysis
ISO/IEC 27001 and FedRAMP certification gating concentrates qualified vendor supply in the United States, Germany, and United Kingdom. Cloud-native statistical platforms draw from hyperscaler infrastructure, open-source package repositories, and specialized biostatistics consulting talent pools. Single-source vulnerability runs through hyperscaler concentration, with AWS GovCloud and Azure Government representing dominant distribution channels for regulated workloads.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Statistics software procurement functions as a geographic-arbitrage play. Vendors can capture margin expansion by locating R&D and support operations in India while pricing against US regulatory compliance premiums.
For Market Incumbents: Hedge against open-source substitution by embedding proprietary validation engines that satisfy FDA 21 CFR Part 11 and EU AI Act documentation requirements. SAS Institute and IBM should deepen backward integration into sovereign cloud infrastructure to defend government account control. Certification investment in ISO/IEC 27001 and FedRAMP represents the critical lever for excluding cloud-native entrants from healthcare and defense verticals. For New Entrants and Emerging Players: Mid-tier pharmaceutical sponsors in India and Southeast Asia represent the most penetrable buyer archetype. These organizations require validated statistical infrastructure but lack capital for perpetual SAS licenses. A consumption-based SaaS model with pre-configured FDA submission templates offers the strongest go-to-market angle against established incumbents. For Investors and Strategic Acquirers: Roll-up economics work for specialized biostatistics workflow tools because pharmaceutical sponsors demand integrated platforms spanning data management, statistical analysis, and regulatory submission. The target archetype comprises 50-200 employee firms with FDA-validated offerings and existing sponsor relationships. Watch for EU AI Act enforcement actions as the signal indicating accelerated replacement cycles for non-compliant legacy tools.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates fragmented biostatistics workflows into unified FDA submission pipelines. |
| Acquisition of Specialist Firm | Adds validated causal inference or spatial statistics capabilities to core enterprise suites. |
| Strategic Partnership | Secures hyperscaler capacity reservations for elastic clinical trial compute demands. |
| Geographic Expansion | Establishes ISO/IEC 27001-certified operations in EU sovereign cloud regions. |
| Product Launch | Introduces edge statistical engines for real-time manufacturing quality control. |
Methodological Framework
Coverage spans the United States, Germany, United Kingdom, India, and Japan, with primary inputs from each. Biostatistics directors at contract research organizations, FDA regulatory consultants, pharmaceutical IT procurement officers, and cloud platform engineering leads contributed structured interviews. Secondary validation drew from FDA 510(k) filings, EMA scientific advice letters, hyperscaler compliance documentation, and ISO/IEC 27001 certification registries. Bottom-up segment sizing triangulated against top-down market expenditure estimates.
Granularity-level modeling addressed deployment modality, end-user organization type, application function, and regional regulatory cluster throughout the forecast period. CAGRs were derived from segment-level growth rate analysis weighted by base-year revenue contribution. Forecast inputs incorporated pharmaceutical R&D pipeline density, EU AI Act implementation timelines, and cloud infrastructure capex trajectories from major hyperscalers.
Inputs from regulatory filing databases and vendor certification records were available through the study window; gaps in private SaaS company financial disclosures introduce uncertainty bands around mid-market segment estimates. Forecasts reflect assumptions regarding FDA enforcement continuity and EU AI Act delegated act finalization. A model refresh is warranted upon material change in pharmaceutical sponsor cloud migration velocity or sovereign data residency mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Reporting Software Market
Software & Services
Japan IT Services Market
Software & Services
Objectives & Key Results (OKR) Software Market
Software & Services
Optical Design Software Market
Software & Services
Collaboration Tools Market
Software & Services
Apparel Software Market
Software & Services
Commerce As a Service (Caas) Market
Software & Services
Sales Training Software Market
Software & Services
Software-Defined Machine Market
Software & Services
Data Conversion Services Market
Software & Services
Global App Store Optimization Software Market
Software & Services
Stone Analysis Software Market
Software & Services
Global Forestry Software Market
Software & Services
Global Sales Enablement Platform Market
Software & Services
Global Driving School Software Market
Software & Services
3D Animation Software Market