
 Portable Base Station (PBS) Market | 2026-2036
Portable Base Station (PBS) Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Base Station (PBS) Market Insights
The EU Green Deal's digital infrastructure resilience targets is shifting procurement criteria toward energy-efficient, rapidly deployable base stations. Nokia Corporation leverages its Open RAN portfolio to sustain leadership in interoperable compact systems. Ericsson anchors European defense contracts through ruggedized 5G NR platforms. Samsung competes aggressively in Asia-Pacific with modular designs optimized for temporary network deployment.
A portable base station is a self-contained, transportable cellular or microwave radio access node typically housed in a hardened enclosure weighing under 50 kilograms, designed to restore or extend wireless coverage without permanent infrastructure. These units integrate baseband processing, radio transceivers, and backhaul interfaces to serve emergency responders, military units, and event operators in locations where fixed towers are unavailable or compromised. Ruggedized PBS variants command premium positioning due to MIL-STD-810 certification requirements and extended temperature tolerances. 5G NR technology segments attract disproportionate R&D investment as defense forces and public safety agencies mandate low-latency, high-bandwidth field communications. Compact PBS formats dominate commercial volumes for telecommunication operators addressing temporary coverage gaps during infrastructure maintenance or surge events.
FCC Part 90 rules govern public safety spectrum allocation and equipment authorization in the United States, while the EU Radio Equipment Directive mandates CE marking and electromagnetic compatibility for PBS units sold across member states. South Korea's MSIT spectrum reforms have accelerated domestic 5G NR PBS adoption by defense and emergency agencies. Stakeholders must monitor evolving national security procurement restrictions that increasingly favor domestically sourced radio components over foreign-designed baseband chipsets.
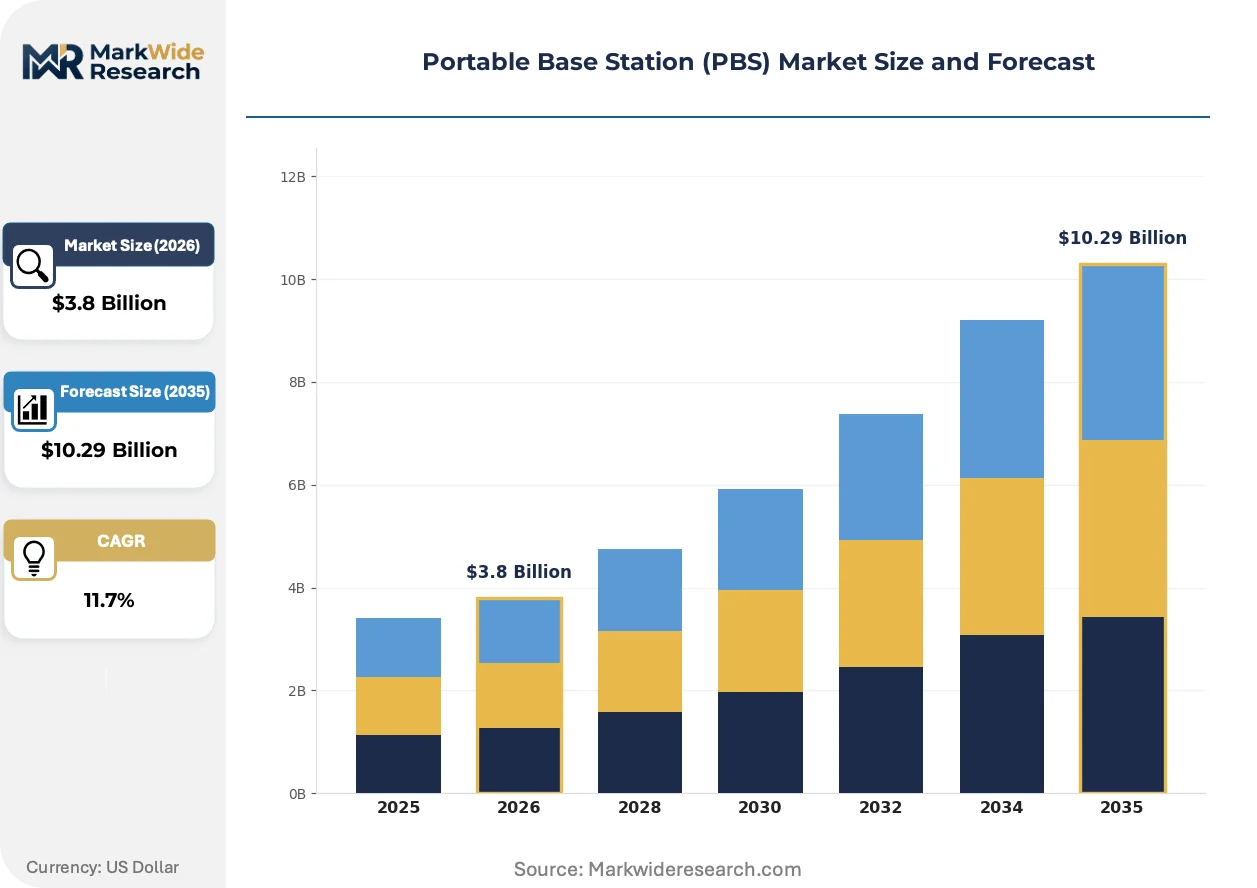
Market Dynamics
Defense modernization programs and emergency response mandates are compressing deployment timelines for rapidly deployable communications infrastructure, forcing suppliers to prioritize interoperability certifications and ruggedized form factors over pure cost optimization.
Growth Catalysts
- FCC Part 90 spectrum reforms:Public safety agencies across the United States are securing dedicated bandwidth for interoperable field communications, accelerating equipment replacement cycles for legacy narrowband systems.
- EU Cybersecurity Act certification tiers:European defense procurement now mandates Common Criteria evaluation for tactical radio equipment, creating structured demand for hardened baseband processors.
- 5G NR low-latency requirements:Military command-and-control applications specify sub-10 millisecond response times, driving investment in edge-computing-integrated radio heads.
Market Restraints
- Gallium nitride component supply:High-frequency power amplifiers depend on specialized semiconductor foundries concentrated in East Asia, exposing procurement to export control volatility.
- MIL-STD-810 certification costs:Environmental testing for temperature extremes, shock, and vibration adds substantial fixed cost per unit, compressing margins on sub-scale production runs.
- Optical fiber backhaul dependency:Remote deployment sites often lack terrestrial connectivity, forcing reliance on satellite links with bandwidth constraints and weather susceptibility.
Strategic Opportunities
- India's defense indigenization mandates:The country's phased manufacturing program for telecom equipment creates localized assembly requirements that favor joint ventures with domestic electronics manufacturers.
- Open RAN architecture convergence:Disaggregated baseband and radio units enable multi-vendor interoperability, lowering switching costs for procurement officers managing heterogeneous fleet deployments.
- Disaster response as-a-service models:Telecommunication operators are unbundling temporary coverage provision from capital ownership, creating recurring revenue streams for equipment lessors.
Industry Challenges
- Embedded systems security clearance:National procurement restrictions increasingly require domestically sourced baseband chipsets, forcing redesign cycles for products using foreign-designed silicon.
- Legacy analog integration:First responder agencies maintain substantial TETRA and P25 infrastructure, complicating migration paths to IP-based 5G NR architectures without dual-mode bridging equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Base Station (PBS) Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact PBS, Lightweight PBS, Modular PBS, Ruggedized PBS, Vehicle-Mounted PBS Technology: 4G LTE, 5G NR, Microwave, Satellite, Tetra Application: Disaster Recovery, Public Safety, Military Communications, Event Coverage, Temporary Networks End User Industry: Emergency Agencies, Defense Forces, Telecommunication Operators, Media & Entertainment, Construction Firms |
| Companies Covered | Huawei, Nokia Corporation, Ericsson, Samsung, ZTE Corporation, CommScope Holding Company, Inc., NEC Corporation, Qualcomm Incorporated, Cisco Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Base Station (PBS) Market Trends and Innovations
Software-defined radio architectures are displacing hardware-fixed platforms across tactical communications, enabling field-reconfigurable waveforms that adapt to spectrum availability without physical component swaps.
Software-defined baseband processing is integrating machine-learning-based spectrum sensing directly into field-deployable units. Defense forces in Germany and South Korea are piloting these cognitive radio capabilities for electronic warfare environments. The technology is integrating interference mitigation algorithms that previously required rack-mounted data centers into sub-50-kilogram enclosures.
EU Radio Equipment Directive harmonization is mandating unified electromagnetic compatibility testing across member states, eliminating redundant national certification procedures. Manufacturers serving European defense and public safety markets now submit single technical files for CE marking validity across 27 jurisdictions. This regulatory consolidation is compressing product launch timelines by eight to fourteen months for compliant suppliers.
Agency procurement officers are consolidating vendor relationships around full-lifecycle service agreements rather than discrete equipment purchases. United States emergency management departments now specify training, maintenance, and spectrum management as bundled contract elements. This behavioral shift is restructuring competitive dynamics toward integrated solution providers capable of field engineering support across multi-year deployment horizons.
Portable Base Station (PBS) Market Segmentation
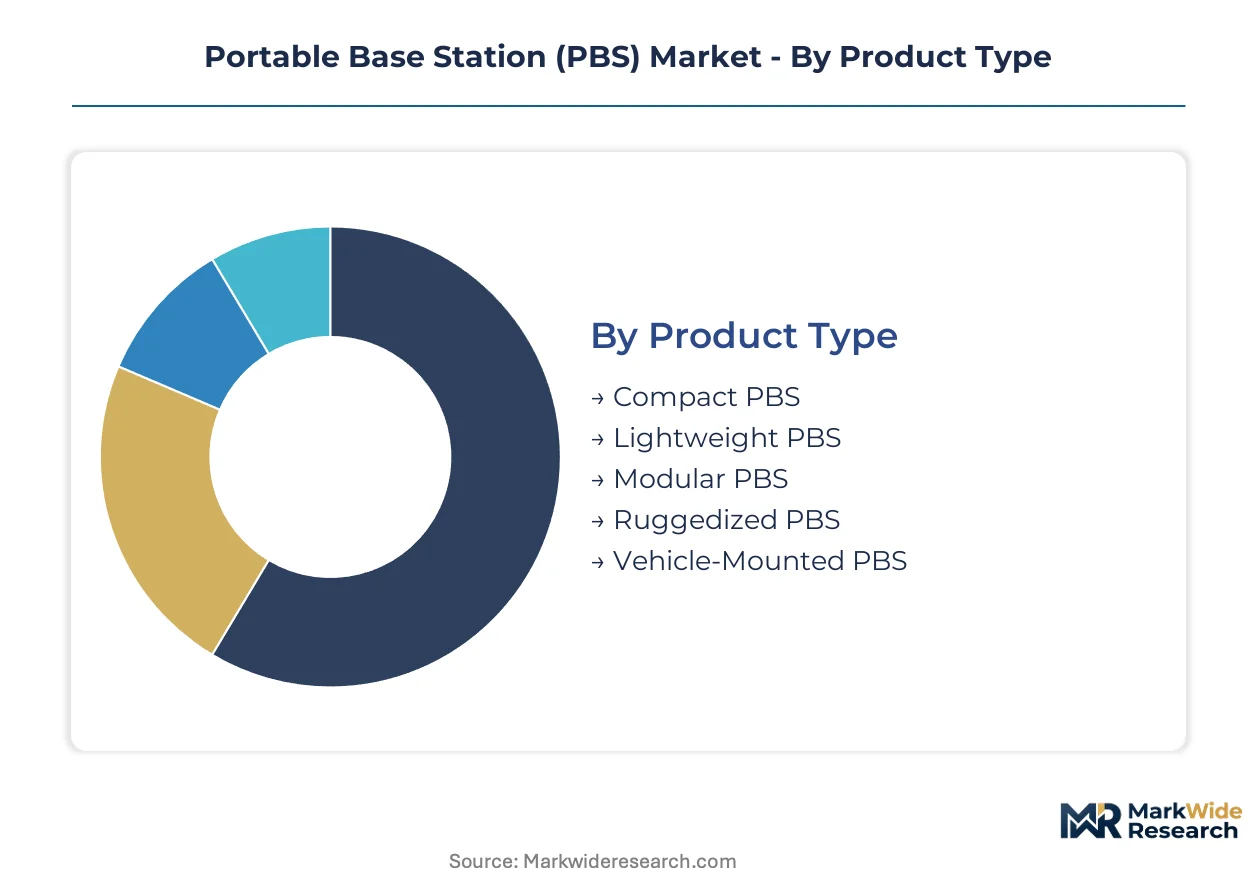
Portable base station procurement patterns diverge sharply between standalone rapid-deployment units and embedded systems integrated into vehicle or command platforms. Understanding these structural divisions reveals where margin pools concentrate and which technology transitions command capital allocation priority.
Product Type:
Integration depth separates self-contained backpack units from chassis-dependent systems requiring external power and backhaul infrastructure.
- Ruggedized PBS:MIL-STD-810G certified enclosures withstand temperature extremes from minus 40 to plus 70 degrees Celsius, shock loads, and particulate ingress. Defense forces in Germany and the United States specify these hardened variants for forward operating bases where environmental resilience overrides unit cost considerations.
- Compact PBS:Sub-20-kilogram enclosures integrate baseband processing, radio heads, and battery power in single carry-on cases. Emergency agencies across South Korea deploy these for urban disaster response where rapid personnel transport matters more than extended autonomous operation.
- Lightweight PBS:Stripped-down variants prioritize portability over feature completeness for short-duration event coverage.
- Modular PBS:Field-swappable radio and baseband cards enable multi-band reconfiguration without full unit replacement.
- Vehicle-Mounted PBS:Deep integration into military or emergency vehicle electrical and antenna systems sacrifices standalone flexibility for sustained power and elevated transmission range.
Volume placements concentrate in Compact PBS; the faster expansion belongs to Ruggedized PBS.
Technology:
Cost tier stratification separates established narrowband infrastructure from emerging 5G NR platforms commanding premium positioning.
- 5G NR:New radio interfaces deliver sub-10-millisecond latency and enhanced mobile broadband for command-and-control applications. South Korea's MSIT spectrum reforms and United States FCC Part 90 allocations are accelerating procurement of these high-throughput field units by defense and public safety agencies.
- 4G LTE:Mature ecosystem offers proven interoperability with existing carrier infrastructure and lower unit economics. Telecommunication operators in Germany favor these platforms for temporary coverage gaps during infrastructure maintenance where backward compatibility reduces deployment risk.
- Microwave:Point-to-point backhaul links for sites lacking fiber connectivity.
- Satellite:Essential for beyond-line-of-sight operation in remote or denied terrain.
- Tetra:Legacy narrowband standard persists in European public safety fleets requiring voice-centric mission-critical communications.
Revenue concentration sits with 4G LTE; steepest expansion trajectory belongs to 5G NR.
Application:
Customer maturity distinguishes institutional procurement with multi-year planning horizons from reactive event-driven purchasing.
- Military Communications:Integrated battlefield networks demand encrypted waveforms, anti-jam capabilities, and interoperability with allied force equipment. Defense modernization programs in the United States and Germany are compressing fielding timelines for these specialized platforms.
- Disaster Recovery:Post-event network restoration requires rapid deployment without pre-positioned infrastructure. Emergency management departments across South Korea and Germany maintain standing contracts for surge capacity activation within 24-hour response windows.
- Public Safety:First responder interoperability mandates drive equipment standardization around P25 and LTE standards.
- Event Coverage:Temporary capacity augmentation for sporting venues and festivals follows predictable seasonal patterns.
- Temporary Networks:Construction and remote resource extraction sites drive demand for medium-duration deployment.
Contract value concentrates in Military Communications; Disaster Recovery shows the most volatile demand spikes.
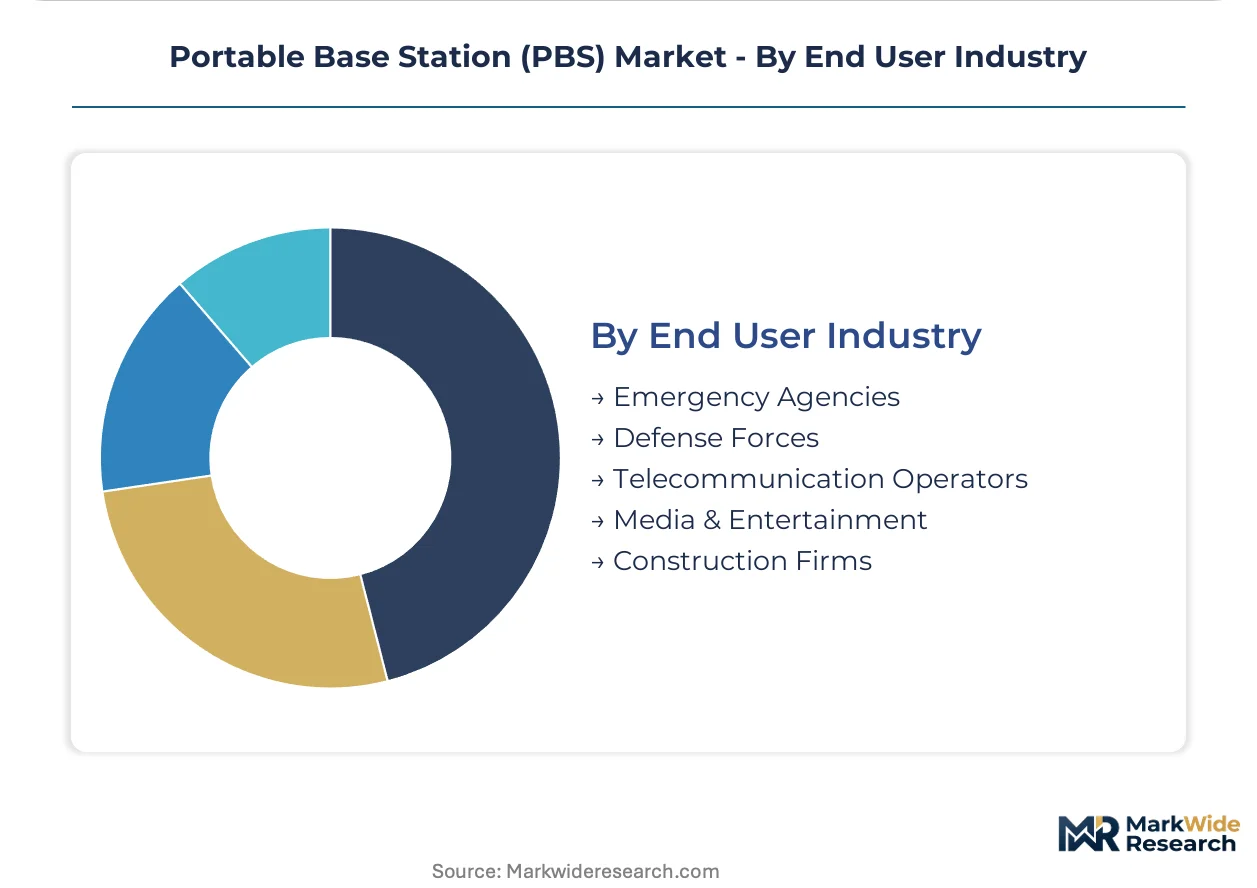
End User Industry:
Supply concentration aligns with defense and emergency procurement offices holding consolidated buying power versus fragmented commercial segments.
- Defense Forces:National security procurement restrictions increasingly require domestically sourced baseband chipsets and Common Criteria certification. United States and South Korean defense agencies are restructuring supplier relationships around full-lifecycle service agreements.
- Emergency Agencies:Federated purchasing across municipal, state, and federal levels creates complex certification requirements. FCC Part 90 rules and EU Radio Equipment Directive harmonization are streamlining equipment authorization for these public safety buyers.
- Telecommunication Operators:Commercial carriers prioritize cost optimization and rapid deployment for maintenance coverage gaps.
- Media & Entertainment:Broadcasters and event producers drive seasonal demand for temporary uplink capacity.
- Construction Firms:Remote site communications follow project-based procurement with limited standardization.
Order backlog concentrates in Defense Forces; Emergency Agencies demonstrate the fastest procurement cycle acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for portable base stations clusters in East Asian electronics hubs while procurement demand concentrates in North American and European defense markets. South Korea and China dominate component fabrication and final assembly. End-user deployment tilts toward United States, Germany, and South Korea where military and emergency agencies drive equipment acquisition.
United States
Defense modernization programs and FCC Part 90 spectrum reforms are accelerating procurement of interoperable field communications equipment. The Department of Homeland Security and state emergency management offices specify ruggedized units with P25 and LTE compatibility. Defense contractors in Northern Virginia and California's defense corridor are integrating these systems into tactical vehicle platforms.
Germany
Bundeswehr communications upgrades and EU Cybersecurity Act certification requirements are reshaping supplier qualification standards. The EU Radio Equipment Directive mandates CE marking and electromagnetic compatibility testing for tactical radio equipment. Industrial clusters in Bavaria and Baden-Württemberg host system integrators developing hardened baseband processors for European defense contracts.
South Korea
MSIT spectrum reforms have accelerated domestic 5G NR adoption by defense and emergency agencies seeking low-latency field networks. The country's phased manufacturing program for telecom equipment favors joint ventures with domestic electronics manufacturers. Seoul Capital Area and Busan-Ulsan regions concentrate final assembly operations for export-oriented ruggedized systems.
China
MIIT standards and GB certification frameworks govern domestic production of portable cellular infrastructure for emergency and industrial applications. Yangtze River Delta and Pearl River Delta manufacturing zones supply compact baseband modules and radio heads to regional markets. State-directed investment prioritizes indigenization of high-frequency power amplifier components.
India
Defense indigenization mandates under the phased manufacturing program are creating localized assembly requirements for tactical communications equipment. TRAI spectrum allocation rules and BIS certification standards apply to public safety network deployments. Industrial corridors in Maharashtra and Gujarat are emerging as assembly locations for joint venture production serving domestic defense procurement.
Portable Base Station (PBS) Market Competitive Landscape
The competitive structure tilts toward diversified telecommunications equipment manufacturers with established defense relationships. Market concentration remains moderate, with a tiered vendor base separating integrated platform providers from specialized radio component suppliers. Three archetypes dominate: diversified network infrastructure giants, defense-focused communications specialists, and modular radio component vendors. Capacity expansion and strategic partnerships represent the primary competitive vectors as vendors seek to anchor multi-year service agreements.
Within the diversified infrastructure tier, Nokia Corporation and Ericsson exemplify European-based manufacturers leveraging Open RAN portfolios and ruggedized 5G platforms to secure defense contracts. Samsung occupies a position among Asia-Pacific scale players optimizing modular designs for temporary network deployment. These three entities represent contrasting geographic anchoring strategies—European regulatory alignment, Nordic defense integration, and Asia-Pacific manufacturing scale—while converging on full-lifecycle service models.
| Leading Market Players |
|---|
| Huawei |
| Nokia Corporation |
| Ericsson |
| Samsung |
| ZTE Corporation |
| CommScope Holding Company, Inc. |
| NEC Corporation |
| Qualcomm Incorporated |
| Cisco Systems Inc. |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed defense contractors and private-equity-rolled-up radio component specialists anchor supply-side ownership patterns, concentrating pricing power among vendors with MIL-STD-810 certification capabilities while compressing margins for undifferentiated compact unit producers serving commercial telecommunication operators.
Pricing Analysis
Margin tightening in compact PBS tiers reflects volume competition from modular Asian manufacturers, while ruggedized variants sustain premium positioning through Common Criteria certification bundling. Three-tier pricing structure across MIL-certified, commercial-rugged, and economy compact levels segments buyers by mission-critical tolerance. Cost-down pressure on sub-20-kilogram units accelerates because South Korean and Chinese producers scale automated assembly. Emergency agencies demonstrate highest price sensitivity; defense procurement offices prioritize certification compliance over unit economics.
Supply Chain Analysis
Gallium nitride power amplifier supply rests on Taiwanese and South Korean specialty foundries, with Japanese substrate producers providing critical raw material inputs. Baseband processor fabrication concentrates in Taiwan, South Korea, and the United States. Single-source vulnerability in high-frequency semiconductor foundries exposes procurement to export control volatility. Distribution runs through defense prime contractors and telecommunication equipment lessors with field engineering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gallium nitride foundry capacity constraints prop pricing discipline across ruggedized PBS tiers, creating supply-constrained conditions favoring vendors with secured component allocations.
For Market Incumbents: Cement multi-year service agreements with United States and German defense procurement offices before Open RAN interoperability mandates commoditize baseband processing. Anchor supplier relationships with Taiwanese GaN foundries to defend against export control disruption. Prioritize Common Criteria certification investment over pure cost reduction in European markets. For New Entrants and Emerging Players: Direct-to-defense-agency digital channels bypass incumbent prime contractor gatekeeping for compact PBS units in India's phased manufacturing program. Target disaster-recovery-as-a-service models with telecommunication operators seeking unbundled temporary coverage. Penetrate South Korean emergency agency procurement through modular designs optimized for 24-hour deployment windows. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier ruggedized PBS specialists with stranded MIL-STD-810 certification assets in European industrial clusters. Long-term viability hinges on Open RAN software competency migration. Watch FCC Part 90 spectrum reallocation timing as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Architecture Certification | Enables multi-vendor interoperability for Bundeswehr and Pentagon procurement officers managing heterogeneous fleets. |
| GaN Power Amplifier Backward Integration | Captures margin pool concentrated in Taiwanese foundries while reducing export control exposure for defense contracts. |
| Disaster-Response-as-a-Service Launch | Creates recurring revenue streams from telecommunication operators unbundling temporary coverage from capital ownership. |
| Indian Joint Venture Formation | Satisfies phased manufacturing program mandates while accessing domestic defense procurement preference structures. |
| Cognitive Radio Capability Integration | Addresses German and South Korean electronic warfare requirements through machine-learning-based spectrum sensing. |
Research Methodology
Independent corroboration across defense procurement officers, emergency management directors, and telecommunication network engineers underwrites the qualitative findings. Primary fieldwork with system integrators in Bavaria and Northern Virginia defense corridors combined with secondary validation against FCC Part 90 equipment authorization databases, EU Radio Equipment Directive technical files, and South Korean MSIT spectrum allocation records. Bottom-up unit shipment estimates triangulated against top-down defense budget appropriation analysis.
Comparable-period anchoring to historical procurement cycles across military modernization programs and disaster response activation patterns structured the forecast window. Segmentation modeling spanned product integration depth, radio interface technology, end-use mission profile, and national security procurement restriction tiers. CAGRs derived from equipment replacement cycle compression and spectrum reform implementation timelines. Forecast inputs incorporated GaN component supply constraints and Open RAN standardization velocity.
The model holds under stable export control regimes and continued defense budget prioritization; deviation in semiconductor trade restrictions or spectrum allocation delays would shift equipment procurement timelines. Forecasts reflect documented assumptions regarding certification harmonization progress and foundry capacity expansion. FCC Part 90 rulemaking, EU Cybersecurity Act tier implementation, and Indian phased manufacturing program enforcement constitute the small set of triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global Ip Multimedia Subsystem (Ims) Market
Telecommunications
South Africa Telecom Market
Telecommunications
Global 5G Services Market
Telecommunications
5G Radio Access Network Market
Telecommunications
Satellite Broadband Communication in Public Safety Market
Telecommunications
Telecommunication Service Market
Telecommunications
Hong Kong Telecom Market
Telecommunications
Cloud PBX Market
Telecommunications
IP PBX Market
Telecommunications
Europe Telecom Expense Management Market
Telecommunications
South Africa Telecom Tower Market
Telecommunications
A2P Messaging Market
Telecommunications
Prepaid Communication Market
Telecommunications
Sri Lanka Telecom Tower Market
Telecommunications
Global SS7 Market
Telecommunications
Global Virtual PBX Market