
 North America Enterprise Resource Planning Market | 2026-2036
North America Enterprise Resource Planning Market Size, Share, and Industry Trends Forecast 2026-2036
North America Enterprise Resource Planning Market Outlook
Canada is narrowing its ERP vendor concentration as Toronto and Vancouver cloud corridors attract implementation partners. SAP SE leverages deep manufacturing module suites to anchor automotive and industrial equipment buyers across Ontario and Michigan. Oracle Corporation sustains database-to-ERP integration strength in energy and utilities verticals throughout Texas and Alberta. Microsoft Corporation competes through Dynamics 365 ecosystem bundling, capturing mid-market organizations migrating from legacy on-premise stacks.
Enterprise Resource Planning systems integrate core business processes through unified databases, workflow engines, and real-time analytics platforms operating across financial, operational, and human capital domains. These systems execute transaction processing, resource allocation, and regulatory reporting through configurable modules connected via APIs and middleware layers. Cloud-based deployment now leads new implementations as organizations prioritize subscription economics and remote accessibility over capital-intensive infrastructure ownership. Supply Chain Management modules represent the fastest-expanding solution category as manufacturers rebuild visibility after recent disruptions. Financial Management retains the deepest margin pools due to SOX-driven upgrade cycles and audit trail requirements.
NIST cybersecurity frameworks, SOX compliance mandates, and sector-specific HIPAA provisions shape product roadmaps and procurement criteria across the United States and Canada. The SEC's climate disclosure rules push ERP vendors to embed emissions tracking and ESG reporting capabilities directly into financial modules. Procurement teams must evaluate vendor cloud sovereignty commitments against cross-border data residency requirements.
Market Dynamics
Cloud migration among mid-market manufacturers is compressing implementation cycles and forcing incumbent vendors to reprice perpetual-license portfolios against subscription economics. This structural shift concentrates procurement decisions in finance and IT joint committees rather than traditional departmental buyers.
Growth Catalysts
- SOX compliance mandates:Audit trail requirements in financial modules drive replacement of legacy on-premise systems across publicly traded manufacturers in Michigan and Ontario.
- Supply chain visibility gaps:Post-disruption reconstruction efforts push discrete manufacturers toward integrated SCM modules with real-time inventory positioning.
- Texas energy-tech corridor:Capital-intensive project accounting needs in oilfield services and renewable infrastructure accelerate ERP adoption among mid-market energy contractors.
Market Restraints
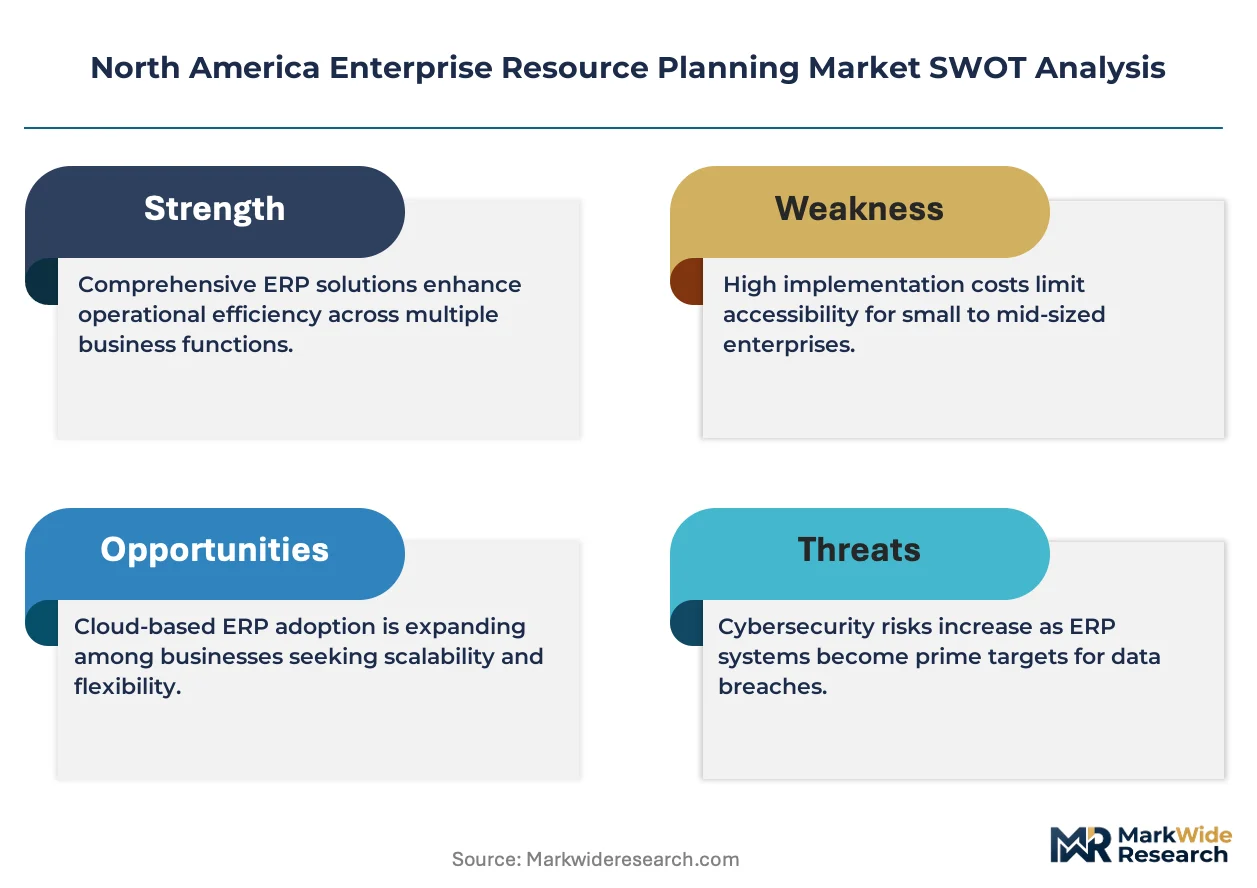
- Implementation cost overruns:Data migration complexity from legacy AS/400 and mainframe systems routinely exceeds budgeted professional services by 40-60% in automotive supplier networks.
- Cloud concentration risk:Three hyperscalers control 85% of North American ERP cloud infrastructure, creating vendor lock-in exposure for finance and HR modules.
- Skills scarcity:Shortage of certified implementation specialists in manufacturing module configuration extends deployment timelines by 8-14 months in the Great Lakes corridor.
Strategic Opportunities
- Canadian SME penetration:Underpenetrated mid-market manufacturers in Quebec and Atlantic provinces present whitespace for cloud-native ERP suites with preconfigured industry templates.
- SEC climate disclosure rules:Embedded emissions tracking in financial modules creates first-mover advantage for vendors integrating Scope 3 carbon accounting directly into general ledger workflows.
- AI-process convergence:Predictive maintenance algorithms fused with inventory optimization modules enable new pricing models based on supply chain uptime guarantees.
Industry Challenges
- Integration complexity:Shop-floor IoT sensor networks require custom API development to feed real-time production data into cloud ERP databases, straining IT bandwidth.
- Cross-border data residency:Canadian provincial privacy laws and US state-level requirements fragment cloud architecture decisions, complicating single-instance deployments for multinational manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Enterprise Resource Planning Market |
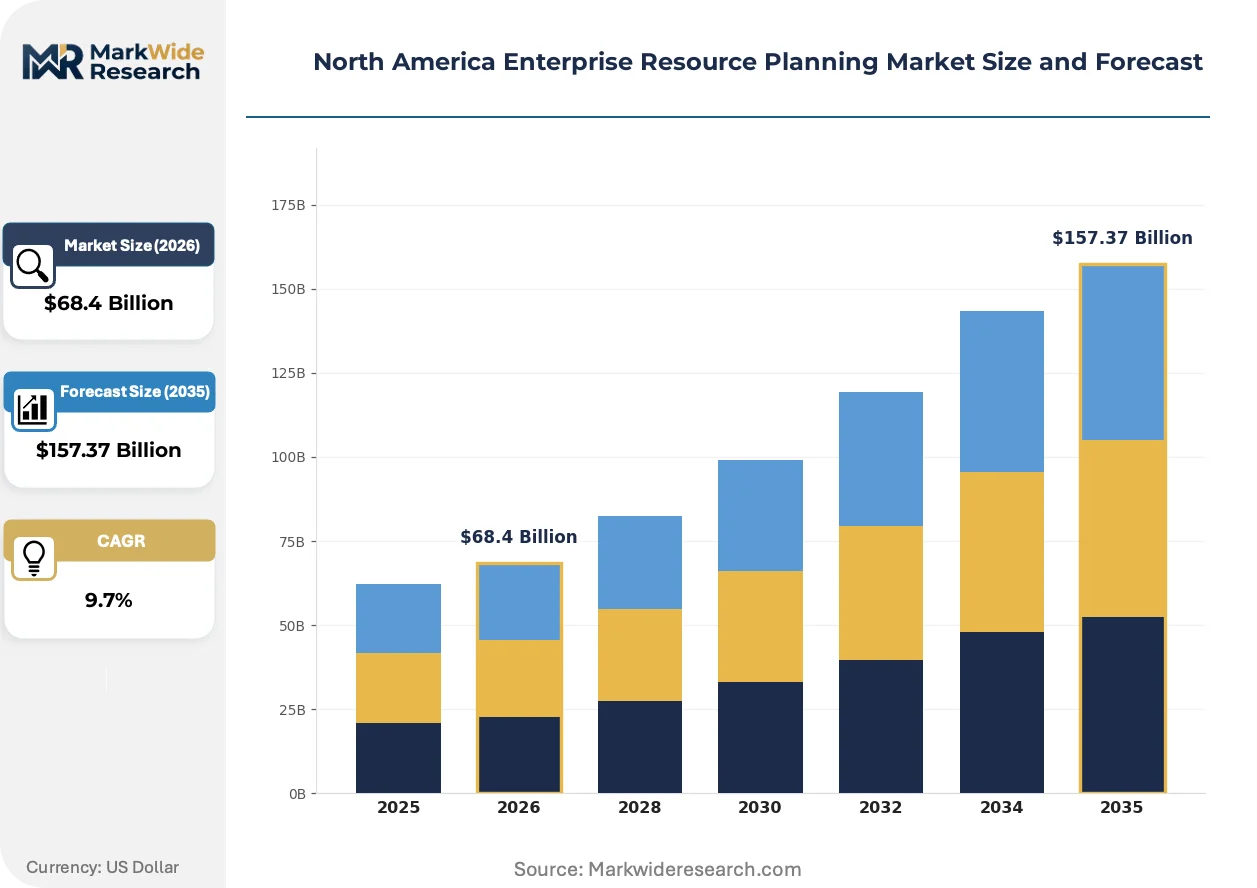
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $157.37 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS Solution Type: Financial Management, Supply Chain Management, Human Resource Management, CRM End User: Manufacturing, Retail, Healthcare, Education Company Size: Small Business, Medium Business, Large Enterprise, Multinational Corporation |
| Companies Covered | SAP SE, Oracle Corporation, Microsoft Corporation, Workday, Inc., Infor, Epicor Software Corporation, IBM Corporation, Sage Group, Acumatica, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Enterprise Resource Planning Market Strategic Shifts
Artificial intelligence and edge computing are rewriting module architecture, compressing the gap between transactional systems and predictive analytics. Vendors now compete on inference speed and model customization rather than database throughput alone.
Composable ERP architecture is hybridizing monolithic suites into interoperable microservices. Discrete manufacturers in automotive and industrial equipment adopt API-first financial modules that swap in best-of-breed tax engines or treasury tools without full-stack replacement. This modularity is compressing upgrade cycles from 7-year rip-and-replace events to continuous feature deployment.
SEC climate disclosure rules and NIST cybersecurity frameworks are mandating embedded compliance capabilities. Financial modules must now generate audit-ready emissions reports and encrypt data at rest and in transit by default. Energy and utilities verticals throughout Alberta and Texas face the steepest reconfiguration costs as they retrofit decade-old installations.
Subscription fatigue is altering vendor selection criteria. Mid-market buyers in the United States and Canada now prioritize consumption-based pricing over seat licenses, forcing implementation partners to restructure professional services around outcome milestones rather than hourly billing. This shift is most visible among private equity-backed manufacturers seeking to minimize cash conversion cycles.
North America Enterprise Resource Planning Market Segmentation
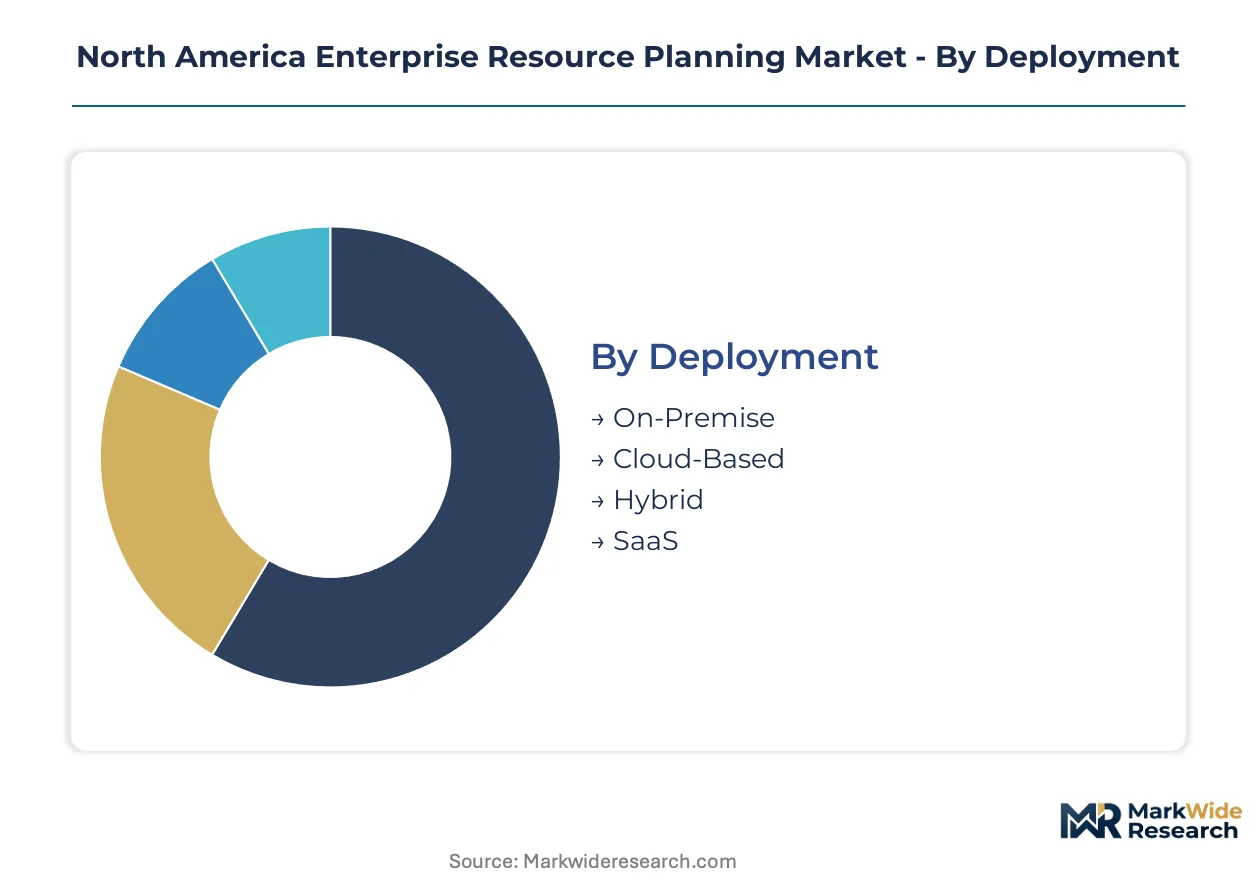
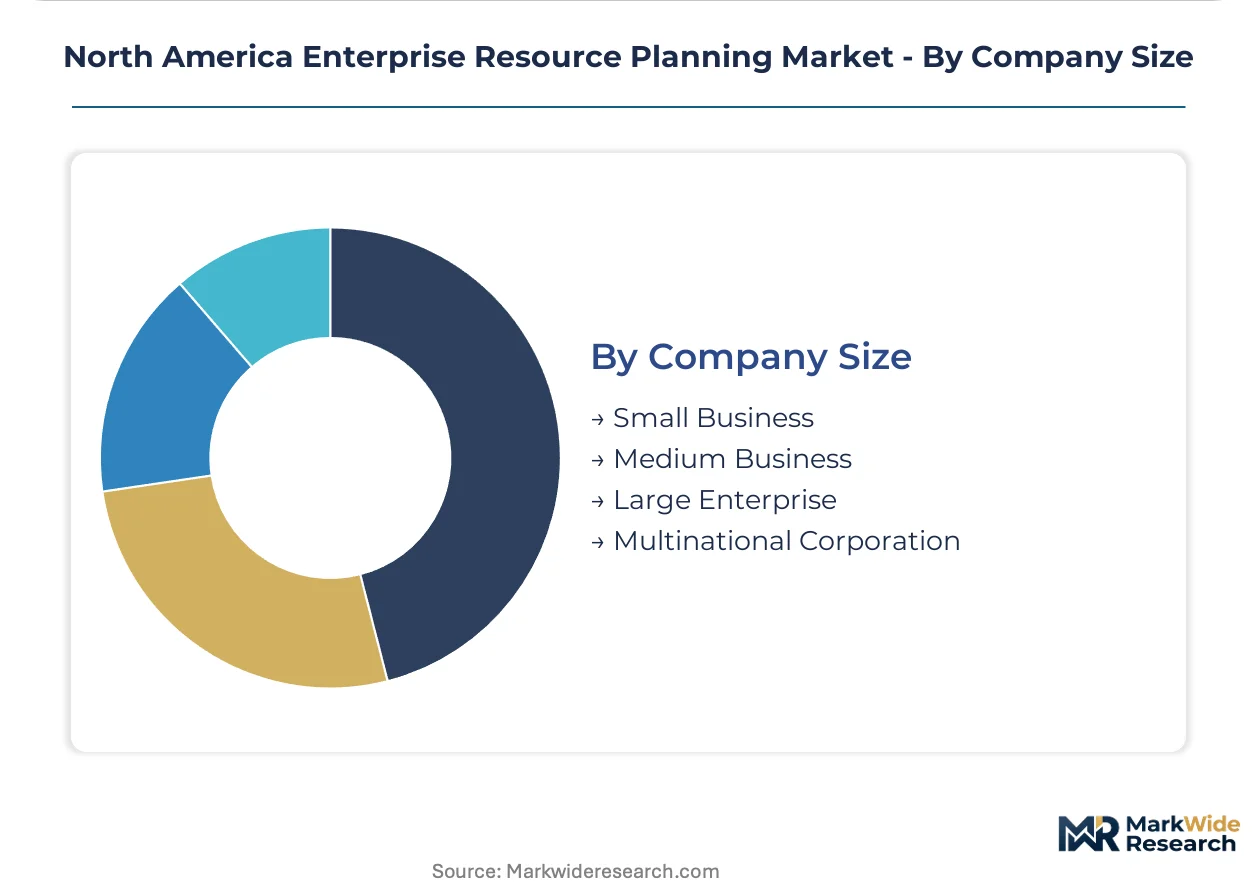
North American ERP procurement varies sharply by deployment architecture, functional module, and organizational scale. Buyers in Michigan automotive clusters and Texas energy corridors weight compliance integration and cloud sovereignty differently than mid-market manufacturers in Quebec. Understanding these segment boundaries clarifies where vendor specialization creates pricing power versus commodity competition.
Deployment:
Use-case spectrum spans capital-intensive on-premise installations for defense contractors to consumption-based SaaS for PE-backed manufacturers optimizing cash conversion cycles.
- On-Premise:Legacy installations persist where air-gapped security or millisecond-latency shop-floor integration is non-negotiable. Defense suppliers in Southern California and nuclear equipment fabricators across Ontario maintain perpetual-license stacks despite 40-60% higher total cost of ownership.
- Cloud-Based:Multi-tenant architectures dominate new procurement among mid-market discrete manufacturers rebuilding supply chain visibility post-disruption. NIST cybersecurity frameworks and SOX audit trail requirements reshape vendor selection criteria toward FedRAMP-authorized platforms.
- Hybrid:Split deployments isolate financial modules on-premise for SOX compliance while operational data flows to cloud analytics engines. Automotive tier-1 suppliers in Ohio and Michigan favor this architecture during multi-year migration windows.
- SaaS:Subscription economics compress implementation risk for private equity portfolio companies and venture-backed energy-tech firms in Austin and Calgary seeking minimal capital deployment.
The dominant share belongs to Cloud-Based deployments, while SaaS is closing the gap fastest among mid-market manufacturers exiting legacy AS/400 systems.
Solution Type:
Module selection tracks organizational maturity and regulatory exposure rather than industry vertical alone.
- Financial Management:General ledger, treasury, and tax engines generate the deepest margin pools due to SOX-driven replacement cycles and embedded audit trail requirements. Publicly traded manufacturers in Michigan and Ontario prioritize vendors with preconfigured GAAP/IFRS reconciliation workflows.
- Supply Chain Management:Inventory optimization, demand forecasting, and logistics coordination modules expand most quickly as manufacturers rebuild visibility after recent disruptions. Discrete manufacturers in the Great Lakes corridor drive adoption of real-time supplier collaboration portals.
- Human Resource Management:Payroll, benefits administration, and workforce analytics concentrate procurement decisions in joint finance-HR committees. HIPAA compliance requirements reshape evaluation criteria for healthcare systems across the United States and Canada.
- CRM:Customer data platforms and quote-to-cash workflows attract mid-market industrial equipment distributors seeking to unify field sales and inside sales operations without full-stack ERP replacement.
Financial Management retains the largest installed base, though Supply Chain Management is gaining share fastest among manufacturers prioritizing inventory velocity over accounting precision.
End User:
Vertical-specific compliance mandates and operational complexity create divergent vendor performance requirements.
- Manufacturing:Discrete and process manufacturers demand deep shop-floor integration, predictive maintenance algorithms, and ESG emissions tracking embedded in financial workflows. Automotive and industrial equipment producers across Ontario and Michigan anchor module development roadmaps.
- Retail:Omnichannel inventory visibility and real-time price optimization drive cloud-native procurement among regional chains and direct-to-consumer brands. Point-of-sale integration complexity favors vendors with prebuilt connectors to major payment processors.
- Healthcare:HIPAA audit trail requirements and clinical supply chain traceability reshape module selection for hospital networks and pharmaceutical distributors. Procurement prioritizes vendors with healthcare-specific compliance certifications.
- Education:Grant accounting, student information system integration, and endowment management create specialized requirements for universities and K-12 districts. Public institution procurement cycles extend deployment timelines compared to commercial buyers.
Manufacturing commands the dominant revenue concentration, while Healthcare is climbing fastest as hospital systems consolidate and modernize legacy financial platforms.
Company Size:
Organizational scale determines implementation approach, pricing model tolerance, and integration complexity thresholds.
- Small Business:Sub-100 employee manufacturers and professional services firms prioritize out-of-box configurations with minimal customization. QuickBooks-to-cloud-ERP migration paths dominate vendor selection in this tier.
- Medium Business:100-1,000 employee organizations represent the most contested segment as legacy on-premise systems reach end-of-life. Private equity ownership accelerates cloud migration timelines among mid-market manufacturers in Quebec and Atlantic Canada.
- Large Enterprise:Complex multi-entity consolidation, intercompany eliminations, and global tax engines drive seven-figure implementation budgets. These buyers sustain professional services margins for systems integrators.
- Multinational Corporation:Cross-border data residency requirements and multi-currency treasury operations fragment cloud architecture decisions. Canadian provincial privacy laws and US state-level requirements complicate single-instance deployments.
Large Enterprise maintains the dominant share of vendor revenue, though Medium Business is expanding most quickly as subscription economics democratize access to tier-one functionality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEC disclosure mandates and NIST cybersecurity frameworks anchor procurement priorities across the dominant United States market, while Canadian provincial privacy laws reshape cloud architecture decisions for cross-border manufacturers.
United States
SOX compliance mandates drive financial module replacements among publicly traded manufacturers in Michigan and Ohio. The SEC's climate disclosure rules push ERP vendors to embed emissions tracking directly into general ledger workflows. Automotive tier-1 suppliers in Detroit-Warren-Dearborn concentrate demand for hybrid deployments isolating financial modules on-premise while operational data flows to cloud analytics engines.
Canada
Toronto and Vancouver cloud corridors attract implementation partners narrowing vendor concentration in Ontario and British Columbia. Provincial privacy laws fragment single-instance deployments for multinational manufacturers operating across Quebec and Alberta borders. Mid-market manufacturers in Atlantic Canada present whitespace for cloud-native ERP suites with preconfigured industry templates.
Mexico
Maquiladora manufacturers near the US border accelerate cloud migration to synchronize supply chain visibility with parent company systems in Texas and California. The country's national data protection authority shapes cross-border data residency requirements for automotive and electronics exporters. Industrial clusters in Nuevo León and Baja California anchor demand for bilingual financial modules with NAFTA-compliant trade documentation.
North America Enterprise Resource Planning Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. The North American ERP market structures around three distinct vendor tiers: hyperscale suite providers with database-to-application integration, cloud-native specialists with consumption-based pricing, and vertical-focused implementers with preconfigured industry templates. Strategic moves concentrate on API-first composable architecture and outcome-based professional services restructuring.
Within the hyperscale tier, SAP SE and Oracle Corporation exemplify database-centric competitive positioning, while Microsoft Corporation occupies a position bridging ecosystem bundling with mid-market accessibility. These anchors represent divergent paths: deep manufacturing module suites versus subscription economics democratization.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| Microsoft Corporation |
| Workday, Inc. |
| Infor |
| Epicor Software Corporation |
| IBM Corporation |
| Sage Group |
| Acumatica |
| Others |
Value Chain & Pricing Dynamics
The I-35 corridor freight lanes connecting Texas energy-tech hubs to Great Lakes manufacturing centers transmit cost volatility directly into ERP module pricing, compressing margins for implementation partners while amplifying price differentiation between cloud-native suites and legacy migration projects.
Pricing Analysis
Geographic price spreads of 15-25% separate Ontario automotive clusters from Atlantic Canada mid-market buyers, reflecting implementation complexity premiums and certified specialist scarcity. Subscription SaaS tiers dominate new procurement, with differentiation driven by FedRAMP authorization levels and preconfigured industry template depth. Pricing pressure stems from hyperscaler concentration forcing repricing of professional services around outcome milestones rather than hourly billing. Private equity-backed manufacturers exhibit highest price sensitivity, while defense contractors with air-gapped security requirements show lowest elasticity.
Supply Chain Analysis
Export control regimes restricting semiconductor fabrication equipment flows to China concentrate ERP cloud infrastructure dependencies on three hyperscalers operating primarily from US and Canadian data centers. The supply chain draws from specialized labor pools in Toronto and Vancouver cloud corridors, with critical inputs including certified implementation specialists, API middleware layers, and FedRAMP-authorized platform licenses. Single-source vulnerability pervades cloud infrastructure provisioning. Distribution runs through systems integrator networks anchored by Big Four advisory practices and vertical-focused implementation boutiques.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America ERP market sits in a cyclical recovery phase as SOX-driven replacement cycles and SEC climate disclosure mandates force deferred upgrade commitments into active procurement pipelines.
For Market Incumbents: Build switching-cost moats through embedded compliance automation that locks financial modules into audit-ready workflows. Deepen API-first architecture investments to capture composable ERP demand from automotive tier-1 suppliers. Defend against cloud-native specialists by accelerating consumption-based pricing rollout before subscription fatigue hardens buyer preferences. For New Entrants and Emerging Players: Pursue whitespace in Quebec and Atlantic Canada mid-market manufacturers exiting legacy AS/400 systems without incumbent relationships. Target cloud-native ERP suites with preconfigured discrete manufacturing templates as the most penetrable segment. Lead with rapid-deployment guarantees backed by outcome-based professional services pricing to differentiate from established implementation timelines. For Investors and Strategic Acquirers: Cloud-native vertical specialists with healthcare or energy compliance certifications represent the highest-conviction acquisition archetype for portfolio construction. Long-term viability hinges on AI-process convergence capabilities that enable predictive maintenance and inventory optimization bundling. Watch for hyperscaler partnership announcements as inflection indicators signaling distribution access scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | FedRAMP-authorized cloud modules capture defense and healthcare procurement requirements. |
| Geographic Expansion | Toronto and Vancouver cloud corridors narrow vendor concentration in Ontario and British Columbia. |
| Strategic Partnership | Hyperscaler alliances resolve cloud concentration risk for finance and HR module buyers. |
| Product Launch | Embedded emissions tracking aligns financial modules with SEC climate disclosure mandates. |
| Acquisition of Specialist Firm | Manufacturing module boutiques accelerate shop-floor IoT integration capabilities. |
Study Parameters
A spread of perspectives from ERP implementation partners, cloud infrastructure architects, manufacturing CIOs, and procurement officers at publicly traded manufacturers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K disclosures, FedRAMP authorization databases, and hyperscaler capex reports. Bottom-up deployment modeling triangulated against top-down market sizing across cloud, on-premise, hybrid, and SaaS deployment architectures.
Demand-supply balance dynamics anchored the forecast framework, with segmentation modeling spanning deployment mode, solution type, end-user vertical, and organizational scale throughout the projection horizon. CAGRs derived from install-base replacement curves and greenfield adoption patterns across the Great Lakes manufacturing corridor and Texas energy-tech hubs. Industry-specific inputs included SOX compliance deadline clustering and NIST cybersecurity framework adoption velocity.
Sensitivities concentrate around cloud infrastructure pricing volatility and certified implementation specialist availability. Forecasts reflect assumptions on subscription economics penetration and hybrid deployment persistence. Material shifts in SEC disclosure rule implementation timelines or cross-border data residency regulatory fragmentation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Cloud-Based Call Center Software Market
Software & Services
Automotive Dealership Software Market
Software & Services
Job Description Management Software Market
Software & Services
Radio Propagation Software Market
Software & Services
OCR Scanning Software Market
Software & Services
North America IT Services Market
Software & Services
Acoustic Simulation Software Market
Software & Services
Home Design Software Market
Software & Services
Europe Digital Signage Software Market
Software & Services
Lifecycle Management Software Market
Software & Services
Estate Management Software Market
Software & Services
Global Disk Imaging Software Market
Software & Services
Global Church Management Software Market
Software & Services
Global Online Survey Software Market
Software & Services
Live Software Market
Software & Services
Asia-Pacific ERP Software Market