
 3D Animation Software Market | 2026-2036
3D Animation Software Market Size, Share, and Industry Trends Forecast 2026-2036
3D Animation Software Market Intelligence
Subscription-based access to software-defined rendering features is pivoting how vendors monetize creative tools. Autodesk sustains dual-platform dominance through Maya and 3ds Max, serving distinct studio workflows across film and architectural visualization. Epic Games leverages Unreal Engine's real-time pipeline to extend beyond gaming into virtual production environments. Maxon specializes in motion graphics through Cinema 4D, occupying a niche that broadcast and advertising studios depend upon.
3D animation software encompasses digital toolsets for modeling, rigging, animating, and rendering three-dimensional assets through polygonal mesh manipulation, shader-based material systems, and keyframe or procedural animation controllers. These platforms execute computationally intensive ray-tracing calculations and GPU-accelerated viewport previews to generate photorealistic or stylized imagery for entertainment, design visualization, and interactive media. Cloud-based deployment is expanding fastest as studios distribute rendering workloads across elastic compute clusters, while on-premises installations retain favor among enterprises handling sensitive pre-release content under strict data governance. Real-time rendering technology leads investment intensity as game engines and virtual production stages converge on a unified pipeline.
FCC content guidelines shape broadcast animation standards in the United States, while EMA and national regulators in Europe enforce age-rating frameworks that affect distribution-ready content workflows. ISO standards for digital asset interoperability increasingly determine how studios exchange rigged character data across software platforms. Stakeholders must monitor how AI-assisted animation tools trigger emerging copyright and labor classification disputes before committing to long-term licensing structures.
Market Dynamics
Real-time rendering pipelines are compressing production timelines across film, broadcast, and interactive media, forcing legacy tool vendors to rearchitect their compute architectures around GPU-native workflows or lose studio accounts to engine-based competitors.
Growth Catalysts
- Virtual Production Stages:LED volume stages in Los Angeles, London, and Auckland are standardizing real-time engine workflows for in-camera visual effects, pulling demand from traditional offline renderers.
- EMA Age-Rating Frameworks:European content classification requirements are accelerating investment in localization tools that automate lip-sync and facial animation for multi-territory releases.
- ISO Digital Asset Interoperability:Standardized rig and mesh exchange formats are reducing vendor lock-in, enabling studios to mix Maya, Blender, and Houdini in unified pipelines without rebuild costs.
Market Restraints
- GPU Supply Concentration:Foundry capacity for high-end graphics processors concentrates in Taiwan and South Korea, exposing studios to allocation delays during semiconductor demand surges.
- Perpetual-to-Subscription Cost Compression:Adobe and Autodesk licensing shifts have raised effective annual costs for mid-tier animation houses by 40-60% over five-year ownership cycles.
- Ray-Tracing Compute Intensity:Path-traced final renders require 10-50x more GPU-hours than rasterized previews, constraining independent creators without cloud render farm access.
Strategic Opportunities
- AI-Assisted Inbetweening:Machine learning interpolation tools are opening motion capture cleanup and secondary animation to boutique studios previously priced out of high-end production.
- India VFX Services Expansion:Mumbai, Hyderabad, and Bengaluru facilities are upgrading from roto-comp to full character animation, creating demand for localized training and software localization.
- Cloud-Native Collaboration:Browser-based viewport streaming and version control systems are enabling distributed teams across time zones to review assets without local workstation parity.
Industry Challenges
- Technical Artist Scarcity:The hybrid skill set bridging shader programming and traditional animation principles commands 40% salary premiums over generalist 3D artists, constraining team scaling.
- Legacy Pipeline Integration:Studios with 15+ years of proprietary Maya plugins and Python tooling face six-to-eighteen month migration timelines to real-time engine architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Animation Software Market |
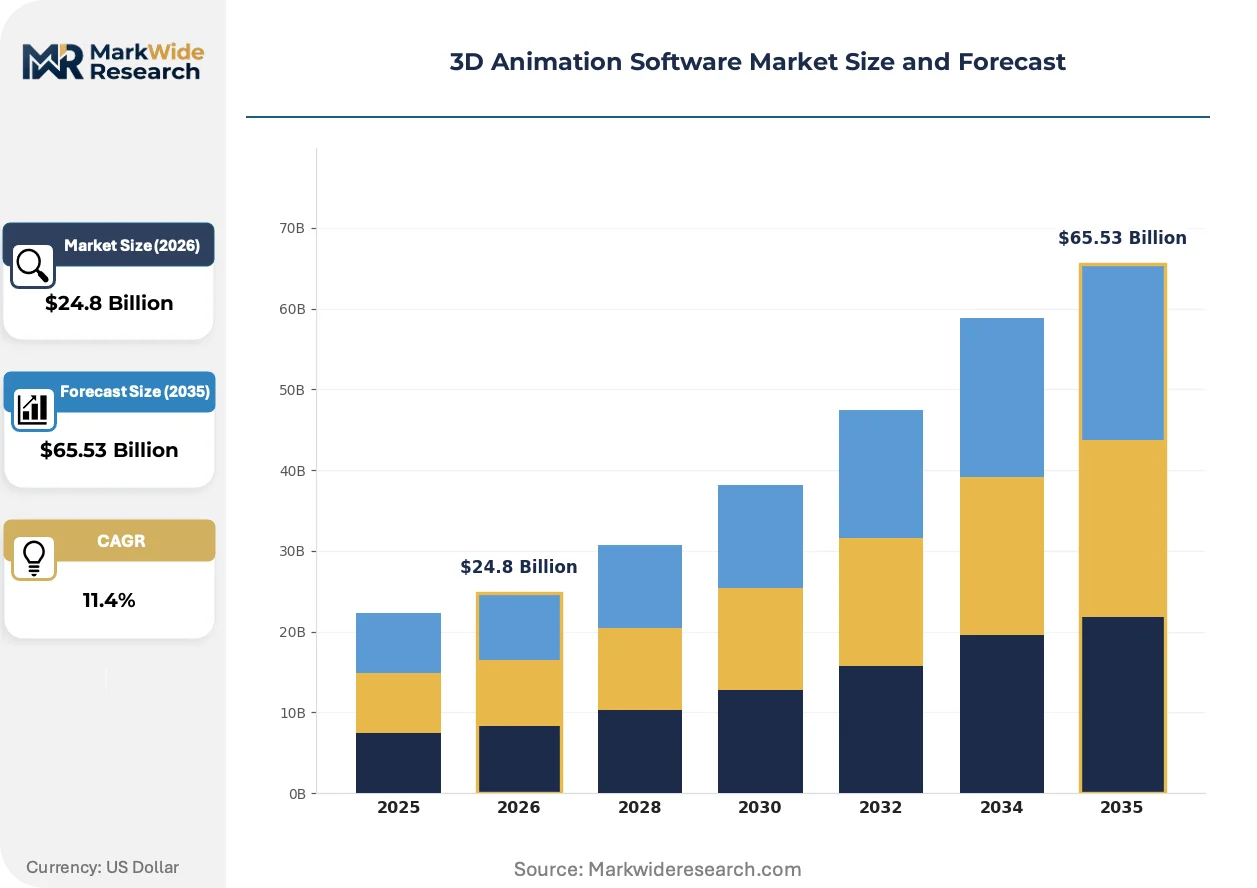
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $65.53 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
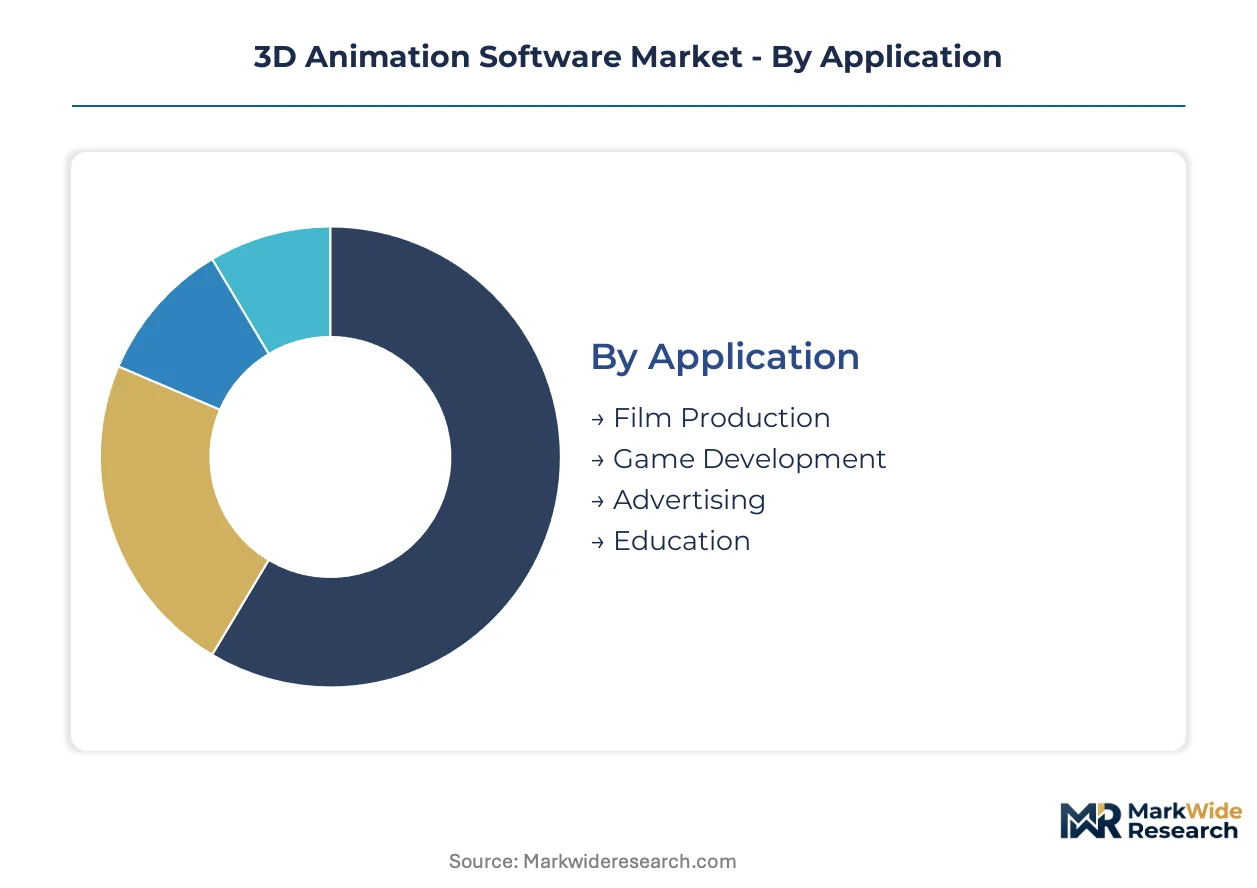
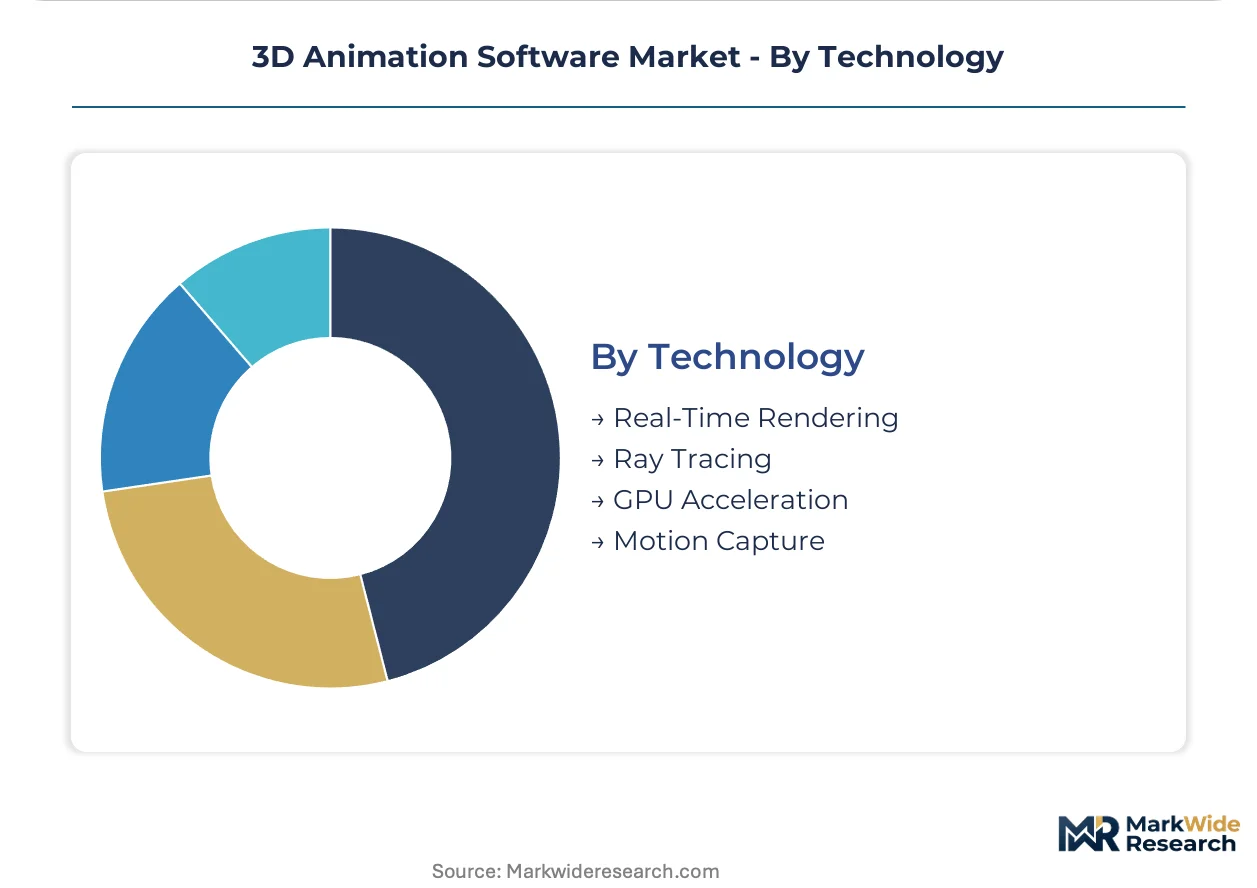
| Segmentation | Application: Film Production, Game Development, Advertising, Education Deployment: Cloud-Based, On-Premises, Hybrid, Mobile End User: Enterprises, Freelancers, Educational Institutions, Studios Technology: Real-Time Rendering, Ray Tracing, GPU Acceleration, Motion Capture |
| Companies Covered | Epic Games (Unreal Engine), Cascadeur, Autodesk (Maya), Chaos Group (V-Ray), Reallusion (iClone), Blender Foundation, Autodesk (3ds Max), Adobe (Substance 3D), Maxon (Cinema 4D), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Animation Software Market Strategic Shifts & Innovations
Neural rendering and generative texture synthesis are collapsing traditional asset preparation pipelines, while regulatory pressure on AI training data is forcing disclosure frameworks that reshape vendor competitive positioning.
Real-time path tracing is overtaking baked lighting workflows in architectural visualization and automotive configurators. D5 Render and Chaos Vantage are capturing mid-market studios from offline Corona and V-Ray seats. This compression of iteration cycles is reducing feedback loops from days to minutes, enabling same-day client approvals that previously required overnight farm renders.
The EU AI Act's transparency requirements for generative training data are imposing documentation burdens on vendors deploying AI-assisted animation tools. French CNIL and German state data protection authorities are already enforcing disclosure standards for motion capture datasets sourced from performer recordings. European broadcasters and VFX houses are now prioritizing vendors with auditable provenance chains over feature-rich but opaque alternatives.
Per-seat perpetual licenses are giving way to consumption-metered cloud rendering credits among freelance animators and small studios. Blender Cloud and Foundry's Flix are replacing traditional maintenance contracts with usage-tiered access. This shift is most visible in Latin American and Southeast Asian markets where upfront capital constraints previously excluded creators from professional toolchains.
3D Animation Software Market Segmentation
Studios select 3D animation software segments based on pipeline architecture, data sovereignty requirements, and rendering workload distribution. Each segmentation dimension carries distinct certification burdens and integration complexity that shapes procurement decisions across production environments.
Application:
Film production workflows face FCC broadcast compliance and MPAA rating system requirements, while game development must satisfy ESRB and PEGI classification standards across distribution territories.
- Film Production:Pipeline tools must support ACES color management and IMF delivery specifications for theatrical and streaming distribution. Demand concentrates in Los Angeles and London facilities where LED volume stages require real-time engine integration for in-camera VFX. Studios prioritize vendors with proven broadcast regulator approval documentation.
- Game Development:Real-time engine architectures dominate, with platforms requiring console manufacturer certification (Sony, Microsoft, Nintendo) for retail distribution. Japanese and Polish studios drive specialized demand for optimization tools targeting mobile and handheld performance tiers.
- Advertising:Rapid-turnaround motion graphics pipelines serve broadcast and digital campaign workflows. Compliance focuses on FTC disclosure requirements for sponsored content and regional advertising standards.
- Education:Site licensing and curriculum-aligned training resources shape procurement. Institutions prioritize Autodesk and Maxon programs with established certification pathways and academic pricing structures.
Leading the category by volume: Game Development. Growing fastest: Film Production.
Deployment:
Cost tier differentiation separates enterprise-grade infrastructure investments from accessible entry points for independent creators and small facilities.
- Cloud-Based:Elastic compute clusters enable distributed rendering without capital expenditure on local GPU farms. AWS, Azure, and Google Cloud host the majority of studio workloads, though data residency requirements in Germany and France drive regional cloud provider adoption.
- On-Premises:Air-gapped installations retain favor among major studios handling pre-release content under strict MPAA security protocols. High initial hardware investment and facility cooling requirements limit adoption to established production houses.
- Hybrid:Local viewport interaction combined with cloud burst rendering for final output. This architecture dominates mid-tier studio adoption in Vancouver and Sydney where project volume fluctuates seasonally.
- Mobile:Tablet and smartphone-based animation tools serve previsualization and client review workflows. iPad Pro deployments are expanding among directors and production designers for on-set blocking and camera planning.
Highest infrastructure investment: On-Premises. Expanding most quickly: Cloud-Based.
End User:
Customer type determines support tier requirements, training investment, and license aggregation patterns across the value chain.
- Enterprises:Media conglomerates and automotive manufacturers maintain dedicated pipeline engineering teams. Procurement emphasizes API extensibility, SSO integration, and enterprise SLA guarantees for mission-critical production schedules.
- Freelancers:Individual artists drive subscription-based revenue through monthly or annual seats. Blender's zero-cost entry point captures significant share, though commercial tool proficiency remains essential for studio employment.
- Educational Institutions:Universities and technical colleges require multi-year licensing with curriculum alignment and student certification programs. SCAD, CalArts, and Gobelins represent high-volume accounts with specialized training resource demands.
- Studios:Independent production companies balance project-based staffing with permanent technical infrastructure. These facilities prioritize render farm scalability and shot-based billing flexibility over perpetual license ownership.
Deepest technical integration requirements: Enterprises. Fastest subscription growth: Freelancers.
Technology:
Rendering methodology and capture technology maturity segments align with production quality tiers and hardware investment cycles.
- Real-Time Rendering:Game engine pipelines execute lighting, materials, and camera moves at interactive frame rates. Unreal Engine and Unity dominate virtual production stages in Auckland, London, and Los Angeles where same-day final pixel output eliminates traditional offline rendering delays.
- Ray Tracing:Path-traced global illumination generates photorealistic imagery for feature film VFX and automotive visualization. NVIDIA RTX hardware acceleration has reduced render times from hours to minutes for complex lighting scenarios.
- GPU Acceleration:Khronos Group Vulkan and OpenCL standards enable cross-platform viewport performance. AMD and NVIDIA architecture wars drive continuous software optimization requirements.
- Motion Capture:Optical and inertial systems record performer movement for character animation. Vicon and OptiTrack installations serve film and game studios in Los Angeles, while Xsens inertial suits expand access for independent creators without dedicated stage facilities.
Widest installed base: GPU Acceleration. Steepest expansion trajectory: Real-Time Rendering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors global 3D animation software demand through its concentration of LED volume stages and virtual production facilities. The city hosts the densest cluster of real-time engine deployments for in-camera visual effects. Regulatory frameworks and data sovereignty requirements are reshaping procurement patterns across major production hubs.
United States
FCC broadcast compliance and MPAA security protocols drive enterprise procurement decisions among Los Angeles and New York studios. The FTC enforces disclosure requirements for AI-assisted content creation tools entering commercial workflows. Texas and Georgia tax incentive programs are attracting secondary animation facilities away from California's cost base.
United Kingdom
London's Soho post-production district sustains demand for ACES color management and IMF delivery specifications. The UK Information Commissioner's Office applies GDPR-aligned data residency rules to cloud rendering contracts. Manchester and Edinburgh facilities are expanding real-time pipeline capacity for streaming content localization.
China
Beijing and Shanghai game studios are driving adoption of GPU-accelerated viewport technologies for mobile-first content. MIIT cybersecurity reviews constrain foreign software deployment in state-affiliated animation projects. Shenzhen hardware manufacturers are integrating rendering engines directly into consumer electronics pipelines.
Japan
Tokyo's anime production houses balance traditional 2D workflows with 3D asset integration for hybrid formats. METI subsidies support domestic software development to reduce reliance on imported toolchains. Osaka technical institutes are expanding motion capture curriculum to address technical artist shortages.
India
Mumbai, Hyderabad, and Bengaluru VFX facilities are upgrading from compositing to full character animation pipelines. The Ministry of Information and Broadcasting frames content localization requirements affecting multi-territory release workflows. Karnataka state incentives are concentrating render farm infrastructure around Bengaluru's technology corridor.
3D Animation Software Market Key Industry Players
Capital-heavy producers compete with asset-light designers across divergent infrastructure requirements. The market structures around three tiers: engine platforms with integrated real-time pipelines, specialized tool vendors serving vertical workflows, and open-source alternatives disrupting mid-market pricing. Consolidation pressures intensify as real-time rendering capabilities become table stakes. Strategic moves center on cloud rendering credit systems and AI-assisted feature integration.
Within the engine-platform tier, Epic Games and Autodesk occupy positions defined by divergent architectural philosophies. Epic Games exemplifies the real-time-native approach through its Unreal Engine ecosystem. Autodesk represents the legacy tool vendor adapting established film pipelines toward interactive formats. Blender Foundation anchors the open-source archetype, disrupting subscription economics through zero-cost entry points that capture independent creator segments.
| Leading Market Players |
|---|
| Epic Games (Unreal Engine) |
| Cascadeur |
| Autodesk (Maya) |
| Chaos Group (V-Ray) |
| Reallusion (iClone) |
| Blender Foundation |
| Autodesk (3ds Max) |
| Adobe (Substance 3D) |
| Maxon (Cinema 4D) |
| Others |
Cost & Logistics Intelligence
GPU foundry capacity costs cascade from Taiwan Semiconductor Manufacturing and Samsung Foundry through to rendering farm operators, ultimately stratifying software access across subscription tiers that separate enterprise studios from freelance creators.
Pricing Analysis
Render throughput per dollar anchors value-based pricing across cloud-native deployment tiers. Pricing stratifies across premium enterprise SLAs, standard studio subscriptions, and economy freelance seats, with differentiation driven by ISO-certified pipeline interoperability and dedicated technical account management. Cost compression in mid-tier subscriptions intensifies as Adobe and Autodesk shift perpetual licenses to recurring revenue models. Freelancers exhibit highest price sensitivity, while media conglomerates prioritize uptime guarantees over per-seat economics.
Supply Chain Analysis
Freight and logistics costs for specialized motion capture hardware concentrate supply chain vulnerabilities between Los Angeles, London, and Shenzhen distribution hubs. NVIDIA and AMD GPU architectures draw from Taiwan and South Korea foundry capacity, while optical tracking systems rest on German precision sensor components. Single-source vulnerability in high-end graphics processor allocation exposes studios to semiconductor demand surge delays. Distribution runs through authorized reseller networks and direct enterprise procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time rendering capability consolidation is eliminating pure-play offline render vendors, with GPU-native engine architectures forcing acquisition or obsolescence on legacy tool providers.
For Market Incumbents: Deepen cloud rendering credit systems to lock in studio dependency beyond software licensing. Acquire AI-assisted animation specialists before generative tooling commoditizes keyframe workflows. Autodesk and Epic Games must defend against open-source erosion by embedding proprietary format lock-in through optimized USD pipeline extensions. For New Entrants and Emerging Players: Browser-based viewport streaming offers a technology-first wedge against incumbent workstation-heavy deployment. Target Indian VFX services expansion in Mumbai and Hyderabad with localized training partnerships and rupee-denominated pricing. Pursue technical artist scarcity as a channel strategy by embedding certification programs that feed talent pipelines directly to adopting studios. For Investors and Strategic Acquirers: Major studio migration announcements to real-time LED volume stages are the leading indicator that rendering engine valuations will bifurcate between platform winners and offline rendering casualties. Five-to-ten year viability favors vendors with cloud-native architectures and auditable AI training provenance chains. Monitor EMA and CNIL enforcement actions against opaque generative tools as a signal for which vendors will retain European broadcast access.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unreal Engine's virtual production pipeline extension into broadcast workflows captures LED volume stage demand from traditional offline renderers. |
| Acquisition of Specialist Firm | Purchase of AI-assisted inbetweening tools addresses technical artist scarcity while accelerating boutique studio market penetration. |
| Strategic Partnership | AWS and Azure cloud rendering alliances enable elastic compute pricing that displaces on-premises render farm capital expenditure. |
| Geographic Expansion | Localized training infrastructure in Bengaluru and Hyderabad captures VFX services upgrading from roto-comp to character animation. |
| Product Launch | ISO-standardized rig exchange format support reduces vendor lock-in and enables mixed-toolchain procurement decisions. |
Research Approach
SEC 10-K filings, EMA regulatory submissions, and hyperscaler capex disclosures formed the secondary backbone, supplemented by customs records tracking GPU and motion capture hardware trade flows. Primary interviews with VFX pipeline supervisors, game engine technical directors, cloud procurement officers, and broadcast technology managers validated segmentation assumptions. Bottom-up studio license aggregation and top-down entertainment industry spend analysis were triangulated against Khronos Group standards adoption metrics.
Bottom-up modeling tracked individual software seat deployments across deployment tiers, while top-down analysis calibrated against aggregate media and entertainment technology expenditure surveys. Segmentation dimensions included application vertical, rendering methodology, organization scale, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves and GPU compute cost decline trajectories. Real-time engine penetration rates and cloud rendering credit consumption patterns served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen AI copyright litigation outcomes, semiconductor export control expansions, and pandemic-scale production disruption. Forecasts reflect assumptions about continued GPU architecture advancement and stable cloud pricing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Survey and Feedback Management Software Market
Software & Services
Global Application Platform Market
Software & Services
Executive Search (Headhunting) Software Market
Software & Services
Global Sales Enablement Platform Market
Software & Services
Integration Brokerage Software Market
Software & Services
Staffing Software Market
Software & Services
Global PEO Software Market
Software & Services
B2B Price Optimization and Management Software Market
Software & Services
Global Electronic Dictionary Market
Software & Services
Bank Reconciliation Software Market
Software & Services
Application Virtualization Market
Software & Services
Solar Rooftop Design Software Market
Software & Services
Data Integration Software/Tool Market
Software & Services
Bridge Analysis Software Market
Software & Services
Europe CMMS Software Market
Software & Services
Global Recipe Apps Market