
 Global Dance Studio Software Market | 2026-2036
Global Dance Studio Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dance Studio Software Market Foresight
Dance instructor availability is rotating toward hybrid teaching models, forcing studios to adopt software that coordinates in-person and virtual class logistics. WellnessLiving leverages cloud infrastructure to anchor its position among multi-location studios. Mindbody competes through extensive third-party integrations with fitness marketplaces. Glofox specializes in mobile-native experiences that sustain engagement among younger membership bases.
Dance studio software encompasses cloud-deployed management platforms that integrate class scheduling, payment processing, and customer relationship management through API-connected modules. These systems automate recurring billing, waitlist management, and instructor payroll while providing real-time occupancy analytics to studio operators. Cloud-Based deployment leads adoption due to lower upfront capital requirements and automatic feature updates, while Booking System functionality captures the fastest growth as studios prioritize frictionless reservation experiences. Subscription-Based pricing dominates revenue models, though Tiered Pricing structures are emerging to serve micro-studios alongside enterprise chains.
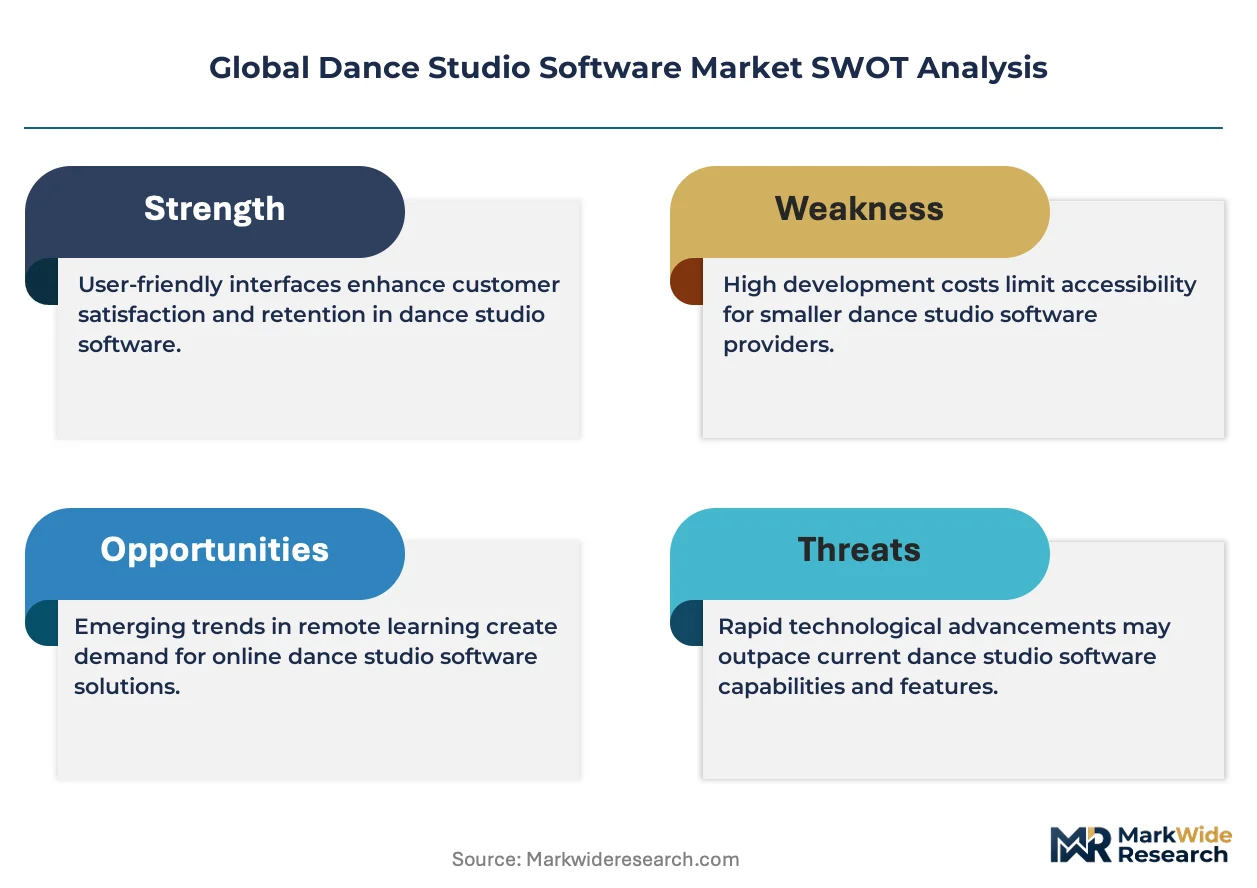
GDPR compliance requirements in Europe and state-level biometric privacy laws in Illinois and Texas shape how vendors store member photographs and payment credentials. The EU AI Act introduces forthcoming obligations for automated recommendation engines that suggest classes to users. Stakeholders must evaluate whether their current vendor roadmap addresses emerging algorithmic transparency mandates before renewal cycles commit them to multi-year contracts.
Market Dynamics
Hybrid instruction models are forcing studios to rebuild operational infrastructure around simultaneous in-person and virtual class coordination, compressing replacement cycles for legacy scheduling systems that cannot bridge physical and digital attendance tracking.
Growth Catalysts
- Cloud Migration:Lower upfront capital requirements and automatic feature updates accelerate adoption among independent studios and boutique fitness operators seeking operational flexibility.
- GDPR-Driven Data Infrastructure:European studios invest in compliant member photograph and payment credential storage, creating pull for vendors with certified cloud architectures.
- Mobile-First Engagement:Younger membership bases demand frictionless reservation experiences through native applications, elevating platforms with superior iOS and Android functionality.
Market Restraints
- Biometric Privacy Friction:Illinois Biometric Information Privacy Act and Texas Capture or Use of Biometric Identifier Act impose strict consent and retention rules on member photograph storage, increasing compliance costs for multi-state operators.
- API Integration Complexity:Legacy point-of-sale systems and accounting software require custom middleware development, extending deployment timelines and professional services expenditure.
- Subscription Fatigue:Small studios face cumulative SaaS costs across overlapping tools for scheduling, payments, and marketing, compressing willingness to upgrade to premium tiers.
Strategic Opportunities
- EU AI Act Compliance Services:Automated class recommendation engines face forthcoming algorithmic transparency mandates, creating white space for vendors offering explainable AI documentation and audit trails.
- Micro-Studio Tier Penetration:Solo instructors and pop-up dance collectives in Spain and Italy remain underserved by enterprise-focused pricing structures, opening volume opportunities at lower per-seat rates.
- Wearable Integration:Convergence between studio management platforms and fitness wearables enables real-time biometric sharing during virtual classes, differentiating vendors who secure hardware partnerships.
Industry Challenges
- Hybrid Instruction Coordination:Studios struggle to synchronize instructor availability across physical and virtual calendars, requiring manual workaround layers atop automated systems.
- Payment Processor Fragmentation:Regional preferences for country-specific gateways in Germany, France, and the Netherlands force vendors to maintain multiple processor integrations rather than unified stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dance Studio Software Market |
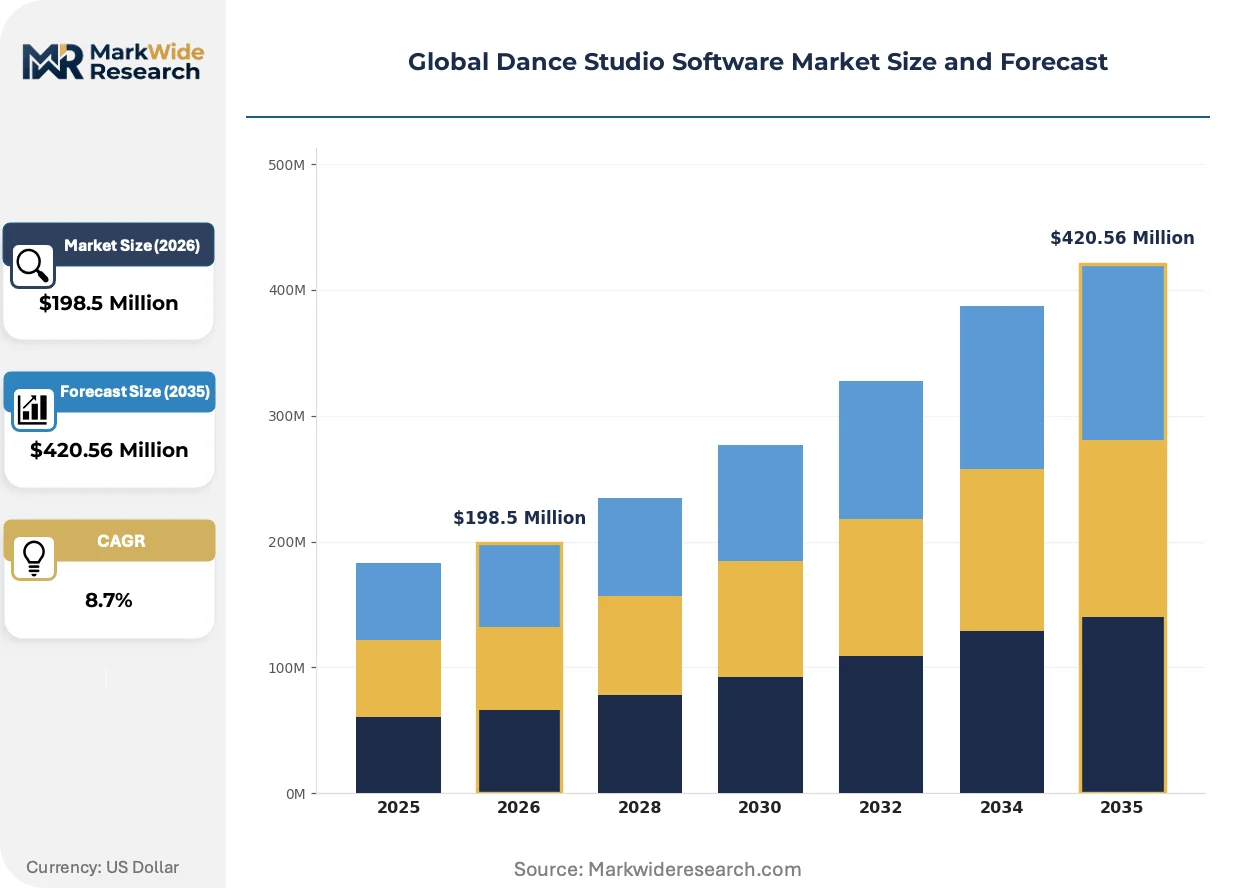
| Market Size in 2026 | $198.5 Million |
| Market Size in 2035 | $420.56 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Management Software, Booking System, Payment Processing, Marketing Tools Deployment: Cloud-Based, On-Premise, Hybrid, Mobile Application End User: Dance Studios, Schools, Community Centers, Freelancers Pricing Model: Subscription-Based, One-Time License, Freemium, Tiered Pricing |
| Companies Covered | WellnessLiving, Glofox, Mindbody, Vibefam, DanceStudio-Pro, Wellyx, JackRabbit Dance, Vagaro, Gymdesk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dance Studio Software Market Shifts & Advancements
Artificial intelligence is embedding into operational workflows at an accelerating pace, compressing the gap between data collection and automated decision-making while regulatory frameworks scramble to keep pace with algorithmic deployment.
Native mobile applications with integrated waitlist management and push-notification engagement are displacing browser-based portals among studios targeting demographics under 35. Boutique operators in urban United States markets adopt these platforms fastest, prioritizing retention metrics over pure scheduling efficiency. The shift is compressing vendor differentiation around user experience rather than feature breadth alone.
The EU AI Act introduces risk-based classification for automated recommendation systems that suggest classes to members based on attendance history. Vendors must now document training data provenance and decision logic for high-risk deployments, particularly those affecting pricing or access. Studios in France and Germany are demanding vendor roadmaps that address these transparency obligations before contract renewal.
Outcome-based membership models are replacing fixed monthly subscriptions in competitive urban markets. Studios in London and New York now tie software fees to member retention benchmarks rather than seat counts, transferring performance risk to platform providers. This restructures vendor incentives toward engagement optimization and churn prediction rather than pure operational automation.
Global Dance Studio Software Market Segmentation
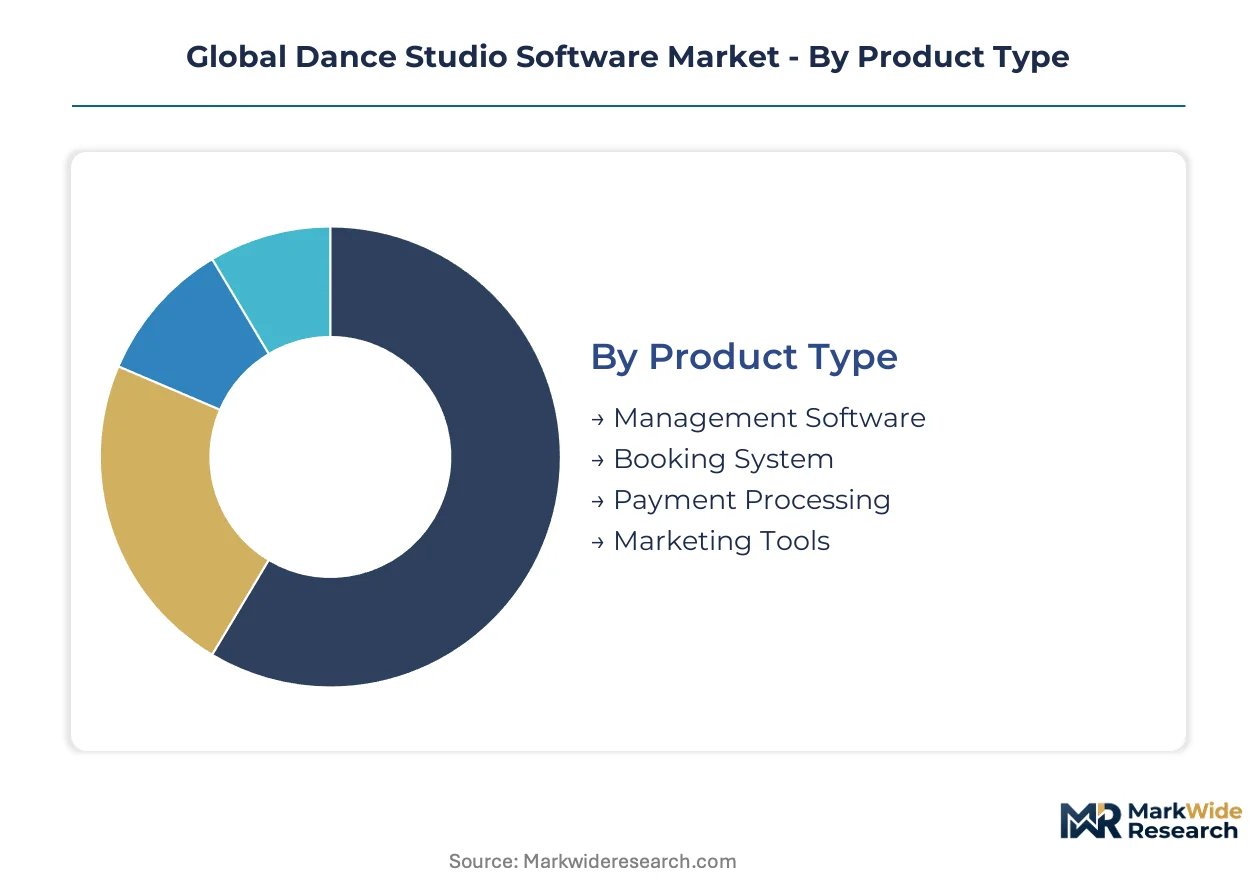
Dance studio software segments fragment across operational maturity and geographic concentration. Product architecture and deployment choices determine which vendors capture independent studios versus enterprise chains across North America, Western Europe, and Asia-Pacific.
Product Type:
Management Software anchors North American vendor portfolios while Booking System demand concentrates in European boutique markets. Payment Processing and Marketing Tools follow distinct geographic adoption curves.
- Management Software:Cloud-native platforms integrate class scheduling, instructor payroll, and member lifecycle tracking through unified dashboards. United States studios with five-plus locations prioritize these systems for multi-site visibility and consolidated reporting.
- Booking System:Frictionless reservation interfaces with real-time waitlist management and automated capacity optimization dominate German and French urban markets. Younger demographics in London and New York drive mobile-first implementations.
- Payment Processing:Recurring billing automation with split-payment flexibility for class packages.
- Marketing Tools:Email automation and social media integration modules for member acquisition campaigns.
Management Software commands the established base. The steepest expansion runs through Booking System.
Deployment:
Cloud-Based platforms minimize upfront capital barriers for Spanish and Italian micro-studios. On-Premise and Hybrid deployments persist where data sovereignty requirements or legacy infrastructure investments create switching friction.
- Cloud-Based:Browser-accessible platforms with automatic feature updates and API extensibility for third-party integrations. United Kingdom and Netherlands studios adopt fastest due to mature broadband infrastructure and digital payment penetration.
- On-Premise:Local server installations with custom security configurations for studios handling sensitive biometric data under Illinois BIPA or Texas biometric privacy statutes.
- Hybrid:Core scheduling in cloud with payment credential storage on local infrastructure for regulatory segmentation.
- Mobile Application:Native iOS and Android experiences with push-notification engagement and offline class browsing.
Cloud-Based deployment captures volume leadership. Mobile Application gains share fastest among demographics under 35.
End User:
Studio scale determines feature complexity requirements. Freelancers and community centers in Southern Europe seek stripped-down pricing while United States dance schools demand enterprise-grade compliance tools.
- Dance Studios:Dedicated facilities offering ballet, hip-hop, and contemporary instruction with recurring membership structures. Multi-location operators in California and Texas prioritize retention analytics and churn prediction.
- Schools:K-12 and university programs with semester-based scheduling, academic credit tracking, and parent portal requirements.
- Community Centers:Municipal and nonprofit venues with subsidized programming and grant reporting obligations.
- Freelancers:Solo instructors and pop-up collectives with variable class schedules and minimal administrative overhead.
Dance Studios anchor vendor revenue. Freelancers represent the most rapidly expanding addressable base as gig-economy instruction spreads.
Pricing Model:
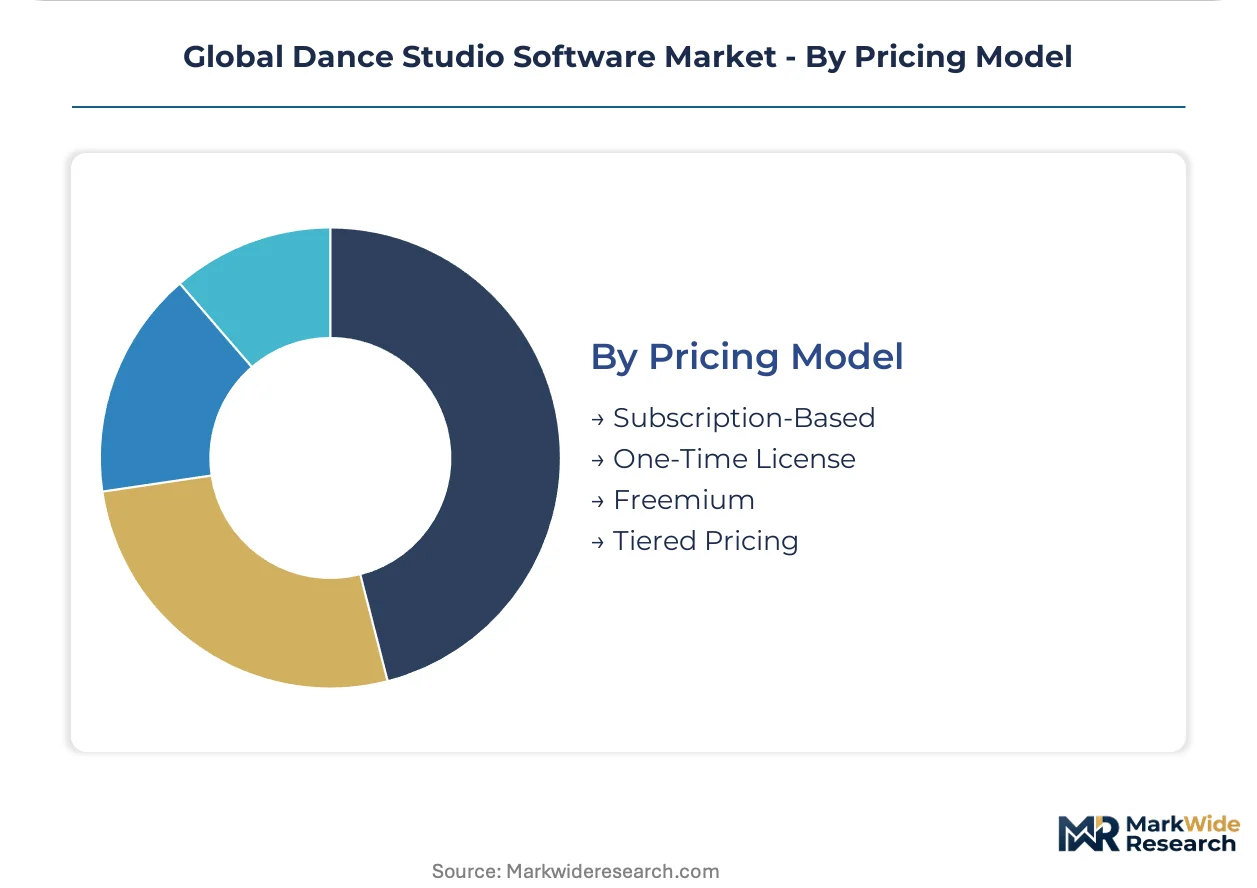
Subscription structures dominate United States and United Kingdom markets. Tiered and Freemium approaches unlock Southern European volume where micro-studio density exceeds enterprise chain presence.
- Subscription-Based:Monthly or annual recurring fees scaling with member count, location number, or feature tier. Standard across North American mid-market studios seeking predictable operational expenditure.
- One-Time License:Perpetual software purchase with maintenance contracts for studios with capital budget flexibility and long-term ownership preferences.
- Freemium:Core scheduling at no cost with premium unlocks for payment processing, marketing automation, or advanced analytics.
- Tiered Pricing:Three-level structures separating solo instructor, multi-instructor studio, and enterprise chain feature sets with corresponding support levels.
Subscription-Based pricing holds the incumbent position. Tiered Pricing climbs fastest as vendors penetrate underserved micro-studio segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States studios consume dance software primarily for multi-location coordination and retention analytics, while European operators prioritize GDPR-compliant data architectures and mobile-first booking interfaces. This consumption-mix differential shapes vendor feature roadmaps and pricing structures across geographies.
United States
California and Texas host dense clusters of multi-location dance studios driving demand for cloud-native retention analytics and churn prediction tools. Illinois Biometric Information Privacy Act and Texas Capture or Use of Biometric Identifier Act impose strict consent requirements on member photograph storage, elevating compliance-focused vendor selection. Los Angeles and Dallas-Fort Worth anchor the highest software adoption rates among boutique fitness operators.
Germany
Urban studios in Berlin and Munich prioritize frictionless reservation systems with real-time waitlist management for younger demographics. GDPR mandates certified cloud architectures for member payment credential storage, creating pull for vendors with EU-based data residency. The Rhine-Ruhr metropolitan region concentrates the fastest replacement cycles for legacy on-premise scheduling systems.
United Kingdom
London operators lead adoption of outcome-based pricing models tying software fees to member retention benchmarks rather than seat counts. Mature broadband infrastructure and digital payment penetration accelerate cloud-based platform migration. The Greater Manchester cluster follows with demand for hybrid instruction coordination across physical and virtual class calendars.
France
Parisian boutique studios drive mobile-native platform adoption with integrated push-notification engagement for demographics under 35. The EU AI Act's risk-based classification for automated class recommendation engines forces vendors to document training data provenance and decision logic. Studios in Lyon and Marseille increasingly demand algorithmic transparency roadmaps before contract renewal.
Spain
Barcelona and Madrid host expanding populations of solo instructors and pop-up dance collectives underserved by enterprise-focused pricing structures. Micro-studio density exceeds enterprise chain presence, creating volume opportunities for tiered pricing models at lower per-seat rates. Cloud migration accelerates among these operators seeking minimal upfront capital barriers.
Global Dance Studio Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding multi-location studio contracts through unified dashboards while specialists capture boutique operators with mobile-native experiences. The market structure reflects this vertical stratification rather than horizontal fragmentation. Three archetypes dominate: cloud infrastructure generalists, mobile-first engagement platforms, and compliance-focused European specialists. Competitive moves concentrate on API ecosystem expansion and tiered pricing penetration into underserved micro-studio segments.
Within the integrated leader tier, WellnessLiving anchors multi-location studio positioning through cloud infrastructure investments, while Mindbody exemplifies the API-connected marketplace approach. Glofox occupies the mobile-native specialist position targeting younger membership bases. These three represent distinct strategic vectors rather than overlapping competitive sets, with each anchoring a different consumption pattern across geography and studio scale.
| Leading Market Players |
|---|
| WellnessLiving |
| Glofox |
| Mindbody |
| Vibefam |
| DanceStudio-Pro |
| Wellyx |
| JackRabbit Dance |
| Vagaro |
| Gymdesk |
| Others |
Supply & Pricing Matrix
Subscription-based contracts with automatic renewal clauses lock in recurring revenue visibility for vendors while capping switching costs for studio operators across the United States and United Kingdom. These structures bundle cloud infrastructure access with tiered feature unlocks, creating price predictability that masks underlying cost compression in payment processing margins.
Pricing Analysis
Long-term subscription contracts dominate vendor revenue, with three-tier pricing structure across premium, standard, and economy levels scaling by location count and member volume. Price differentiation hinges on API integration depth and GDPR compliance certification tier, with European studios paying premiums for EU data residency. Cost compression in payment processing margins is intensifying because regional gateway fragmentation forces multi-processor maintenance. Freelancers and solo instructors in Spain and Italy exhibit highest price sensitivity, while California multi-location chains prioritize retention analytics over per-seat cost.
Supply Chain Analysis
The United States and Ireland anchor cloud infrastructure provisioning for dance studio software platforms, with Germany and the Netherlands hosting secondary data residency clusters for GDPR-bound deployments. Raw material dependencies center on hyperscaler compute capacity, payment processor API access, and mobile OS developer ecosystem licenses. Single-source vulnerability concentrates in AWS and Azure availability zones serving North American peak traffic. Distribution runs through direct vendor sales teams for enterprise chains and self-service onboarding portals for micro-studios under fifty members.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as hybrid instruction models force replacement waves through legacy scheduling systems unable to bridge physical and virtual attendance tracking. Cloud migration tailwinds sustain penetration gains among independent studios previously reliant on manual administration.
For Market Incumbents: Fortify API ecosystem breadth against emerging mobile-native specialists capturing younger demographics through superior iOS and Android experiences. Deepen vertical integration into payment processing to offset gateway fragmentation costs compressing margins in European markets. Prioritize EU AI Act compliance documentation as studios in France and Germany demand algorithmic transparency roadmaps before contract renewal. For New Entrants and Emerging Players: Micro-studio service gaps in Spain and Italy offer immediate white-space penetration where tiered pricing at sub-twenty-dollar monthly rates unlocks volume. Target freelance instructors and pop-up collectives through freemium onboarding with payment processing as the premium unlock. Pursue hardware partnerships with fitness wearable manufacturers to differentiate through real-time biometric sharing during virtual classes. For Investors and Strategic Acquirers: Mobile-first engagement platforms with proven retention metrics among under-thirty-five demographics represent the most compelling acquisition archetype for portfolio diversification. Long-term viability hinges on outcome-based pricing adoption transferring performance risk from studios to vendors. Watch for inflection signals in wearable integration partnership announcements as hardware convergence accelerates competitive differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Documentation | Algorithmic transparency mandates in France and Germany force vendor roadmap disclosures before renewal cycles. |
| Payment Processor Integration Expansion | Multi-gateway support for Germany, France, and Netherlands reduces friction for cross-border studio operators. |
| Wearable Hardware Partnership | Real-time biometric sharing during virtual classes differentiates platforms targeting demographics under thirty-five. |
| Tiered Pricing Penetration | Three-level structures unlock Spanish and Italian micro-studios previously priced out by enterprise-focused contracts. |
| Hybrid Instruction Coordination | Unified physical and virtual calendar management addresses operational pain points compressing replacement cycles. |
Research Methodology
Cross-validation between primary interviews with studio operators, software vendors, and payment processor integration specialists anchors the qualitative findings against secondary validation. Studio management executives, cloud infrastructure procurement officers, and regulatory compliance consultants provided operational perspectives. Bottom-up and top-down triangulation incorporated SEC filings from publicly listed fitness technology platforms, App Annie mobile engagement metrics, and GDPR certification databases maintained by EU supervisory authorities.
Sensitivity analysis across deployment model, studio scale, and regional adoption pattern dimensions stress-tested volume and value outputs. CAGRs were derived from installed base growth rates, replacement cycle compression, and pricing tier migration assumptions. Industry-specific inputs included biometric privacy law enforcement patterns in Illinois and Texas, plus EU AI Act implementation timelines affecting automated recommendation engine deployments.
Material uncertainties — regulatory enforcement intensity, hyperscaler pricing volatility, and wearable hardware partnership exclusivity — sit outside the modeled envelope. Forecasts reflect assumptions about cloud migration pace and hybrid instruction permanence that biometric privacy litigation or macroeconomic contraction could revise. Recalibration cycles align with material shifts in data protection enforcement and mobile OS ecosystem access policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Job Description Management Software Market
Software & Services
Programming Language Market
Software & Services
Global Recruiting Software Market
Software & Services
Global Chromatography Software Market
Software & Services
Global Content Management Software Market
Software & Services
Global License Management Market
Software & Services
United States Human Resource (HR) Technology Market
Software & Services
Enterprise Data Observability Software Market
Software & Services
Statistics Software Market
Software & Services
Courier Software Market
Software & Services
Global Electronic Design Automation Tools (EDA) Market
Software & Services
Global Food Traceability Software Market
Software & Services
B2B Gateway Software Market
Software & Services
Open Stack Service Market
Software & Services
Employee Referral Software Market
Software & Services
Global 360 Degree Feedback Software Market