
 Chatbot Builder Software Market | 2026-2036
Chatbot Builder Software Market Size, Share, and Industry Trends Forecast 2026-2036
Chatbot Builder Software Market Insights
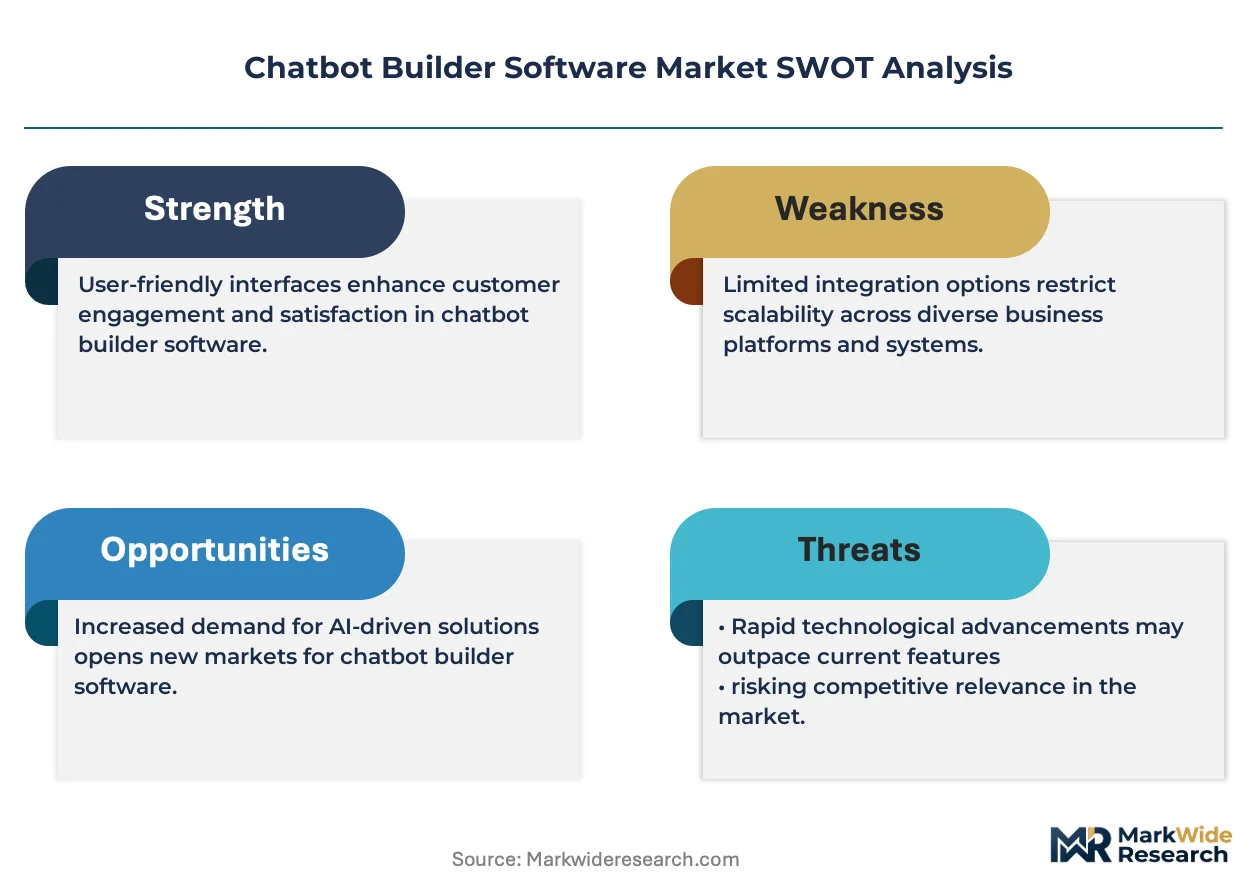
Subscription-based SaaS financing is narrowing the capital barrier for mid-market entrants competing against hyperscale cloud providers. Google leverages its vertically integrated AI stack to sustain pricing power across enterprise tiers. HubSpot anchors its position through tight CRM bundling that controls upgrade pathways for small-business users. Botpress differentiates via open-source distribution that extends developer adoption without proportional sales overhead.
Chatbot builder software encompasses platforms that enable non-technical users to design, train, and deploy conversational agents through visual workflow editors, natural language understanding engines, and pre-trained large language model integrations. These systems typically expose REST APIs and webhook architectures that connect agent outputs to enterprise databases, payment gateways, and ticketing systems for automated transaction completion. Cloud-based deployment dominates current revenue as enterprises prioritize elastic scaling over fixed infrastructure commitments, while hybrid configurations are gaining traction among healthcare and BFSI end users subject to data residency mandates. API-centric integration levels command premium positioning because they embed conversational capabilities directly into existing operational software rather than operating as siloed channels.
The EU AI Act imposes risk-classification requirements on chatbots handling financial and health-related queries, compelling vendors to document training data provenance and human-oversight protocols. The FDA and HIPAA constrain healthcare-specific deployments in the United States through validation standards for clinical decision-support functions and protected health information handling. Stakeholders must evaluate whether their conversational AI roadmaps align with emerging algorithmic transparency obligations before committing to platform architectures that lack audit-trail granularity.
Market Dynamics
Large language model integration is compressing development cycles from months to days, forcing incumbent vendors to rearchitect around transformer-based inference stacks or cede ground to API-native challengers. This technological discontinuity is redrawing competitive boundaries across enterprise, mid-market, and developer-tier segments simultaneously.
Growth Catalysts
- EU AI Act compliance mandates:Risk-classification requirements for financial and health-related conversational agents are compelling enterprise procurement of auditable platforms with documented training-data provenance and human-oversight protocols.
- BFSI call-center replacement:Legacy interactive voice response infrastructure in banking, financial services, and insurance is yielding to conversational AI capable of handling complex transaction workflows without human escalation.
- Cloud-native API architectures:REST API and webhook integration patterns are embedding chatbot capabilities directly into operational software, eliminating channel silos and expanding addressable use cases.
Market Restraints
- GPU compute cost volatility:Training and inference workloads for large language models depend on concentrated semiconductor supply from Taiwan and South Korea, exposing vendors to input cost swings.
- FDA validation timelines:Healthcare deployments with clinical decision-support functions face extended certification cycles that delay revenue recognition and inflate compliance overhead.
- Template-based chatbot substitution:Simple rule-based alternatives continue satisfying price-sensitive small-business segments, capping premium-platform penetration in the lowest tier.
Strategic Opportunities
- Hybrid deployment in Germany:Healthcare and financial institutions subject to data residency mandates are adopting on-premise inference with cloud-based model updates, creating demand for split-architecture vendors.
- Convergence of voice synthesis and NLU:Real-time text-to-speech quality improvements are opening multimodal customer-service applications previously requiring separate vendor stacks.
- India's BFSI digitization:Regional banks and non-banking financial companies are leapfrogging legacy infrastructure, creating greenfield demand for conversational AI without incumbent displacement costs.
Industry Challenges
- Prompt engineering talent scarcity:Vendors struggle to hire specialists capable of optimizing retrieval-augmented generation pipelines for domain-specific accuracy without hallucination.
- HIPAA audit-trail granularity:Healthcare deployments require conversation logging that satisfies protected health information handling standards, forcing architectural investments that slow product velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chatbot Builder Software Market |
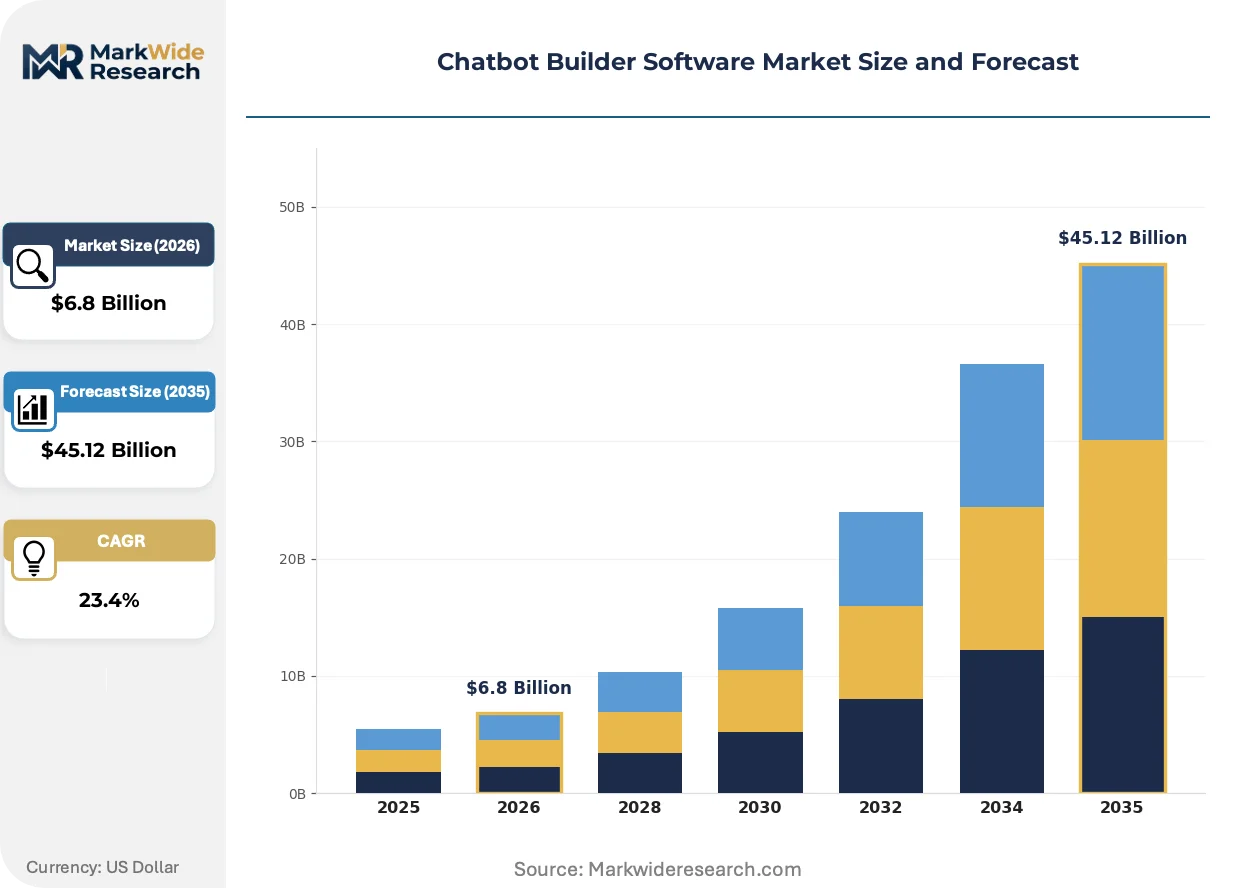
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $45.12 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Cloud-based, On-premises, Hybrid, SaaS End User: Retail, Healthcare, BFSI, Telecom Deployment Model: Web-based, Mobile, Desktop, API Integration Level: CRM, ERP, Social Media, Others |
| Companies Covered | Google, Microsoft, IBM, Baidu, OpenAI, Salesforce, HubSpot, Gupshup, Botpress, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chatbot Builder Software Market Trends and Innovations
Foundation-model commoditization is eroding proprietary natural language understanding as a differentiator, redirecting vendor investment toward orchestration layers, retrieval systems, and vertical-specific fine-tuning pipelines.
Retrieval-augmented generation architectures are rendering obsolete static knowledge bases that require manual content curation and frequent retraining cycles. Enterprise buyers in regulated industries are adopting these systems to ground LLM outputs in authoritative document repositories without exposing proprietary data to third-party training pipelines. The structural consequence is collapsing margins for vendors whose value proposition rests primarily on pre-built intent libraries rather than dynamic context injection.
The EU AI Act's risk-tier classification system is imposing documentation burdens on high-stakes conversational AI deployments. Vendors must now maintain technical files detailing training data sourcing, performance benchmarks, and human oversight mechanisms for systems handling credit scoring or medical triage. Financial services institutions across France, Germany, and the Netherlands are responding by consolidating procurement onto platforms with pre-built compliance modules rather than assembling audit artifacts ad hoc.
Buyer preference is gravitating toward consumption-based pricing tied to resolved conversation outcomes rather than seat licenses or message volumes. Mid-market SaaS procurement teams are displacing traditional annual contracts with monthly usage commitments that scale with automation success metrics. This shift is most visible in United States customer-service automation, where Fortune 500 technology procurement offices now mandate outcome-verification clauses before multi-year commitments.
Chatbot Builder Software Market Segmentation
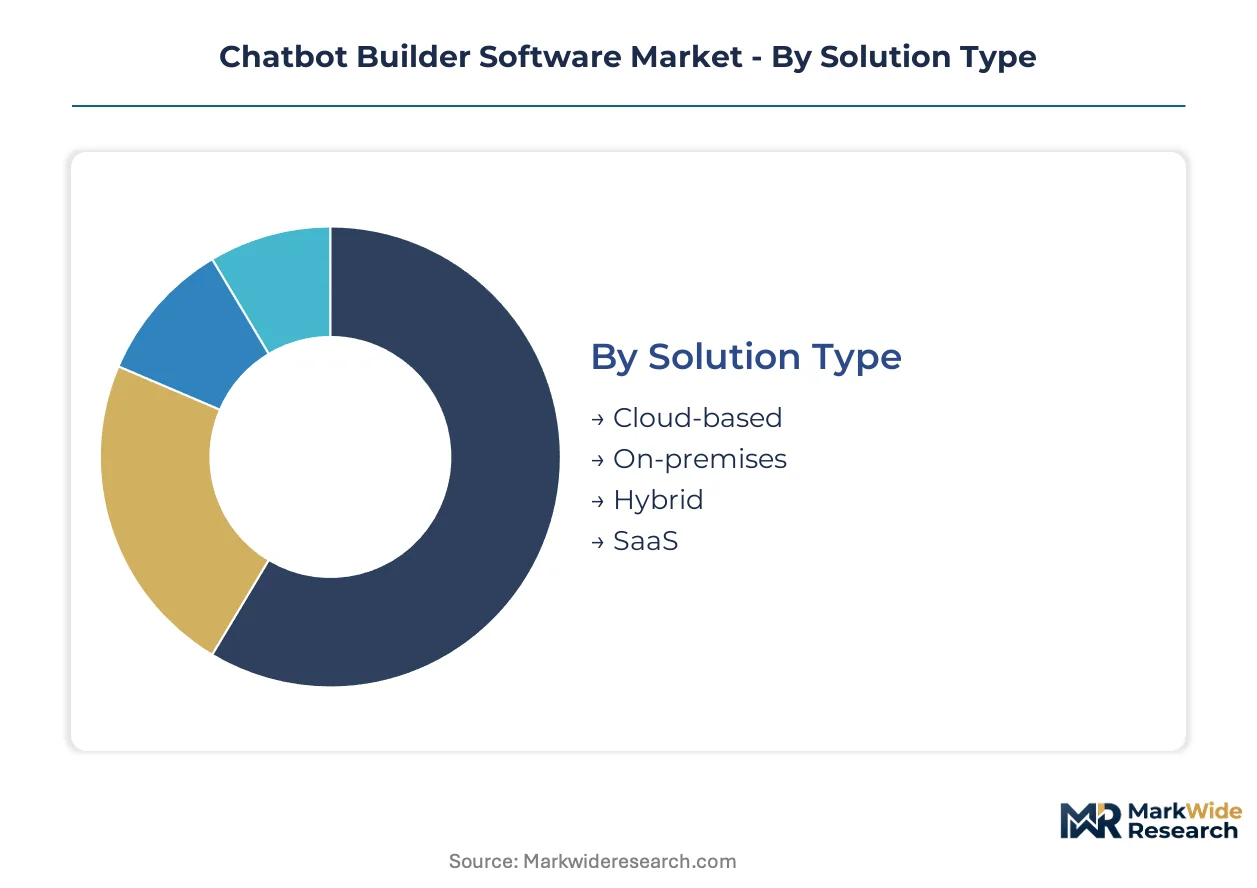
Chatbot builder software segments reflect divergent infrastructure requirements across enterprise maturity levels. Procurement patterns split between cloud-native entrants seeking elastic scaling and regulated incumbents demanding data sovereignty controls.
Solution Type:
Mature deployments favor established infrastructure models; emerging architectures prioritize AI-native elasticity without fixed commitments.
- Cloud-based:Multi-tenant architectures deliver transformer-based inference through managed API endpoints. Demand concentrates among United States mid-market SaaS vendors replacing legacy support tickets with automated resolution workflows.
- On-premises:Air-gapped installations run containerized NLU engines within enterprise data centers. German healthcare providers and French financial institutions deploy these configurations to satisfy EU AI Act documentation requirements for high-risk conversational systems.
- Hybrid:Split architectures process sensitive queries locally while routing model updates through cloud pipelines. This pattern gains traction among Japanese pharmaceutical distributors balancing HIPAA-equivalent data residency with rapid LLM iteration cycles.
- SaaS:Subscription pricing lowers capital barriers for developer-tier experimentation without infrastructure provisioning overhead.
Cloud-based configurations handle the majority of throughput; hybrid deployments are climbing the fastest as compliance mandates harden across European jurisdictions.
End User:
Application intensity varies sharply by sector-specific transaction complexity and regulatory exposure.
- Retail:Conversational commerce platforms integrate payment webhooks and inventory APIs for end-to-end purchase completion. United States direct-to-consumer brands deploy these systems to deflect high-volume seasonal support surges without proportional staffing.
- BFSI:Credit-scoring and claims-handling workflows demand auditable decision trails under EU AI Act risk-tier classifications. Dutch banking consortiums and Italian insurance networks prioritize procurement of platforms with pre-built compliance modules.
- Healthcare:Clinical triage and appointment scheduling require FDA validation timelines that extend revenue recognition cycles.
- Telecom:Technical support automation resolves network troubleshooting through device-agnostic conversational interfaces.
BFSI applications command premium pricing due to compliance overhead; retail implementations expand most quickly on volume.
Deployment Model:
Channel selection follows end-user device preferences and integration topology requirements.
- API:Headless architectures embed conversational capabilities directly into existing operational software through REST endpoints. Indian non-banking financial companies adopt these patterns to leapfrog legacy call-center infrastructure without channel displacement costs.
- Web-based:Browser-hosted widgets deploy through single-line JavaScript snippets for rapid time-to-value. South Korean e-commerce platforms favor this model for seamless checkout assistance without mobile app dependencies.
- Mobile:Native SDKs enable push-notification triggers and biometric authentication for secure transaction completion.
- Desktop:Thick-client installations persist in air-gapped enterprise environments with intermittent connectivity.
API deployments anchor enterprise procurement; web-based delivery gains share fastest among mid-market entrants.
Integration Level:
Connectivity depth determines whether conversational AI operates as siloed channel or embedded operational layer.
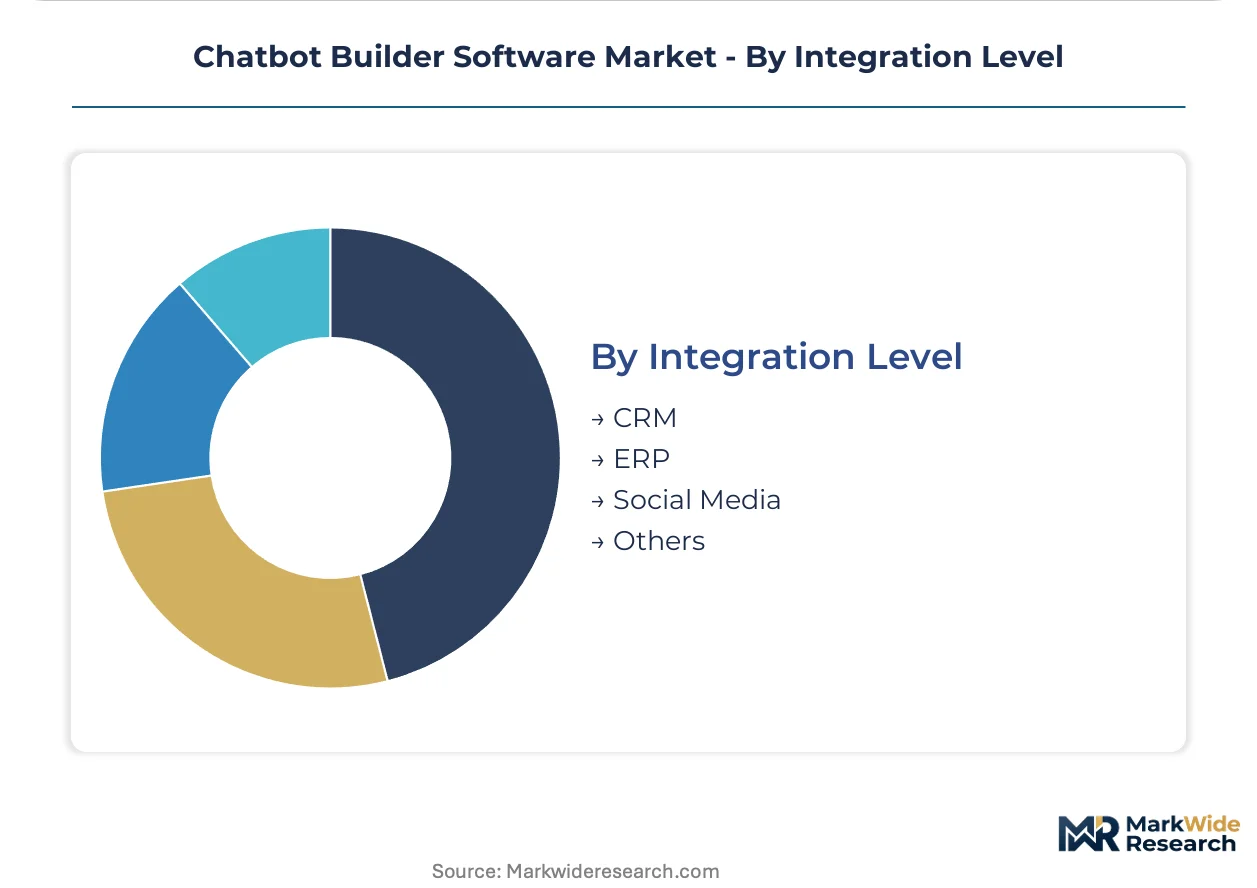
- CRM:Bidirectional synchronization maps conversation histories to customer lifetime value calculations and pipeline stage triggers. HubSpot and Salesforce-native chatbots dominate small-business upgrade pathways through tight bundling controls.
- ERP:Procurement and inventory modules expose conversational interfaces for purchase order status and supplier escalation workflows. German manufacturing mid-caps deploy these integrations to reduce procurement team headcount without process redesign.
- Social Media:Messenger and WhatsApp Business APIs transform public channels into transactional endpoints with built-in authentication.
- Others:Ticketing systems, payment gateways, and proprietary databases complete the integration spectrum through webhook architectures.
CRM integrations capture the largest deployment base; ERP connectivity shows steepest expansion trajectory as manufacturing automation deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act's risk-classification framework is accelerating procurement of auditable conversational AI platforms across jurisdictions with stringent algorithmic accountability mandates. National regulators in financial and healthcare sectors are extending documentation requirements beyond European borders, reshaping vendor qualification standards.
United States
Fortune 500 customer-service automation drives enterprise demand for API-centric deployment models. The FDA's validation timelines for clinical decision-support functions constrain healthcare rollout speeds. Silicon Valley technology procurement offices mandate outcome-verification clauses before multi-year platform commitments.
Germany
Healthcare providers and financial institutions adopt hybrid architectures to satisfy data residency mandates under national implementations of EU AI Act provisions. The Federal Financial Supervisory Authority enforces auditable decision trails for credit-scoring chatbots. Munich and Frankfurt banking consortiums consolidate procurement onto platforms with pre-built compliance modules.
India
Regional banks and non-banking financial companies deploy conversational AI to leapfrog legacy call-center infrastructure without displacement costs. The Reserve Bank of India's digital payment push creates greenfield demand for transaction-capable agents. Mumbai fintech clusters favor API-first architectures for rapid integration with existing core banking systems.
Japan
Pharmaceutical distributors balance HIPAA-equivalent data residency requirements with rapid LLM iteration cycles through split-deployment models. The Ministry of Economy, Trade and Industry promotes AI adoption in service sectors through regulatory sandboxes. Tokyo-based enterprise software buyers prioritize platforms with native Japanese language fine-tuning capabilities.
United Kingdom
Post-Brexit regulatory divergence creates procurement uncertainty for financial services chatbots previously harmonized under EU frameworks. The Financial Conduct Authority consults on algorithmic transparency standards for insurance triage applications. London insurance market participants evaluate platforms capable of dual EU-UK compliance documentation.
Chatbot Builder Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Hyperscale cloud providers leverage vertically integrated AI stacks to sustain pricing power across enterprise segments. Open-source distribution specialists extend developer adoption without proportional sales overhead. Incumbent CRM vendors anchor positions through tight bundling that controls upgrade pathways. Competitive moves concentrate on compliance module pre-certification and outcome-based pricing renegotiation.
Within the hyperscale tier, Google and Microsoft occupy positions defined by inference infrastructure ownership and enterprise distribution scale. HubSpot exemplifies the CRM-anchored archetype through bundled conversational capabilities targeting small-business upgrade pathways. Botpress represents the open-source specialist model, extending reach through developer-tier distribution without traditional sales force expansion. These three patterns illustrate how vendor investment priorities diverge across enterprise, mid-market, and developer segments.
| Leading Market Players |
|---|
| Microsoft |
| IBM |
| Baidu |
| OpenAI |
| Salesforce |
| HubSpot |
| Gupshup |
| Botpress |
| Others |
Pricing and Supply Chain Analysis
GPU fabrication concentration in Taiwan and South Korea funnels pricing power toward NVIDIA and TSMC, compressing margins for chatbot builder vendors downstream while amplifying returns for inference infrastructure owners. This upstream chokepoint forces software vendors to absorb cost volatility or pass through via consumption-based pricing models.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels anchors enterprise procurement, with EU AI Act-compliant platforms commanding substantial premiums over uncertified alternatives. Cost compression in the developer tier is intensifying because open-source distribution eliminates traditional sales overhead. Small-business buyers exhibit highest price sensitivity, while BFSI procurement teams prioritize audit-trail granularity over unit economics.
Supply Chain Analysis
High-bandwidth memory and advanced packaging feedstock from South Korea, Taiwan, and Japan anchors transformer inference capacity. Taiwan Semiconductor Manufacturing sources from Applied Materials and ASML for EUV lithography systems, while NVIDIA designs rest on SK Hynix HBM3 supply. Single-source vulnerability in CoWoS advanced packaging creates bottleneck risk for LLM training clusters. Distribution runs through hyperscaler marketplaces and direct enterprise sales with API-first provisioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around EU AI Act compliance documentation erects sustainable defensive moats for pre-certified vendors. Switching costs escalate as enterprises embed conversation histories into operational workflows.
For Market Incumbents: Insulate installed base by embedding retrieval-augmented generation pipelines deeper into client ERP systems, raising replacement friction. Pre-certify compliance modules for emerging algorithmic accountability frameworks before challengers achieve parity. API-native entrants threaten margin compression through consumption-based pricing; counter with outcome-guarantee contracts tied to automation success metrics. For New Entrants and Emerging Players: India's non-banking financial companies present the most penetrable white-space, with greenfield demand for conversational AI unencumbered by legacy displacement costs. Regional German healthcare providers seeking hybrid deployment architectures offer secondary entry points. Lead with API-first architectures enabling rapid core banking integration without channel friction. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed vertical specialists possessing pre-built BFSI compliance modules but limited geographic reach. Long-term viability hinges on orchestration layer ownership rather than foundation-model dependence. Watch for FDA validation timeline compression as inflection indicator for healthcare automation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Module Pre-Certification | EU AI Act documentation requirements favor vendors with pre-built audit artifacts over ad hoc assembly. |
| Hybrid Architecture Development | German healthcare providers demand split deployments balancing data residency with cloud model updates. |
| Outcome-Based Pricing Transition | Fortune 500 procurement offices now mandate resolved-conversation metrics before multi-year commitments. |
| Retrieval-Augmented Generation Integration | Dynamic context injection renders static knowledge-base vendors obsolete across regulated industries. |
| Voice Synthesis Convergence | Real-time text-to-speech quality improvements enable multimodal customer-service without separate vendor stacks. |
Research Methodology
Cross-validation between primary executive interviews and secondary regulatory filings anchors the qualitative findings. CTOs, IT procurement officers, platform engineers, and integration specialists at BFSI and healthcare enterprises provided deployment pattern intelligence. Secondary sources include EU AI Act implementation guidance, FDA validation pathway documentation, SEC hyperscaler capex disclosures, and hospital procurement database extracts. Bottom-up conversation volume estimates and top-down SaaS revenue triangulation constrain forecast variance.
Calibration against historical adoption curves in adjacent automation categories informs the projection framework. Segmentation dimensions span deployment model, organization size, vertical regulatory exposure, integration complexity, and regional compliance maturity. CAGRs derive from fitted diffusion models across the analysis window, with LLM inference cost trajectories and EU AI Act enforcement timelines as primary sensitivity inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by API-native challengers or hyperscaler bundling strategies would shift outcomes. Model risk concentrates in GPU supply disruption scenarios and regulatory timeline acceleration. Cross-checking against hyperscaler earnings call commentary on enterprise AI monetization is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Pet Tracking Software Market
Software & Services
Instant Messaging Software Market
Software & Services
Global Enterprise Architecture Tools Market
Software & Services
Global Disclosure Management Software Market
Software & Services
Independent Software Vendors (Isvs) Market
Software & Services
Global Intelligent Apps Market
Software & Services
Avionics Software Market
Software & Services
Global Client Portal Software Market
Software & Services
North America Telecom Expense Management Services Software Market
Software & Services
Asia Pacific Human Capital Management Software (HCM) Market
Software & Services
Middleware Market
Software & Services
Lending Software Market
Software & Services
Embedded Software Market
Software & Services
Performing Arts Software Market
Software & Services
Audio Editing Software Market
Software & Services
Supply Chain Visibility (SCV) Software Market