
 Cloud Enterprise Application Software Market | 2026-2036
Cloud Enterprise Application Software Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Enterprise Application Software Market Intelligence
Enterprise cloud architecture expertise is redrawing competitive boundaries across the sector. Oracle Corporation leverages decades of database infrastructure dominance to anchor large-scale ERP migrations. Microsoft sustains platform stickiness through deep integration between Azure and its productivity suite. Amazon Web Services competes on compute scale and specialized industry cloud offerings for regulated workloads.
Cloud enterprise application software encompasses modular, multi-tenant business systems delivered via internet protocols, typically built on containerized microservices with API-first integration layers and SLA-backed uptime guarantees. These platforms automate core operational workflows spanning finance, human capital, supply chain, and customer relationship management for organizations seeking to replace on-premises legacy stacks. ERP deployments within the product type category command the deepest integration budgets and longest implementation cycles, while CRM segments generate faster recurring revenue streams due to shorter sales cycles and lower switching costs. Hybrid cloud architectures are capturing disproportionate growth as regulated industries balance data sovereignty requirements with elastic capacity needs.
FDA 21 CFR Part 11 validation requirements shape healthcare sector procurement criteria for cloud ERP and HCM systems handling electronic records. EMA guidelines on pharmacovigilance data integrity, alongside EU GDPR territoriality rules, compel vendors to offer regional data residency options. ISO 27001 and SOC 2 Type II certifications have become baseline qualifiers rather than differentiators in enterprise RFP processes. Stakeholders must weigh sovereign cloud mandates against the interoperability limitations of geographically fragmented deployments.
Market Dynamics
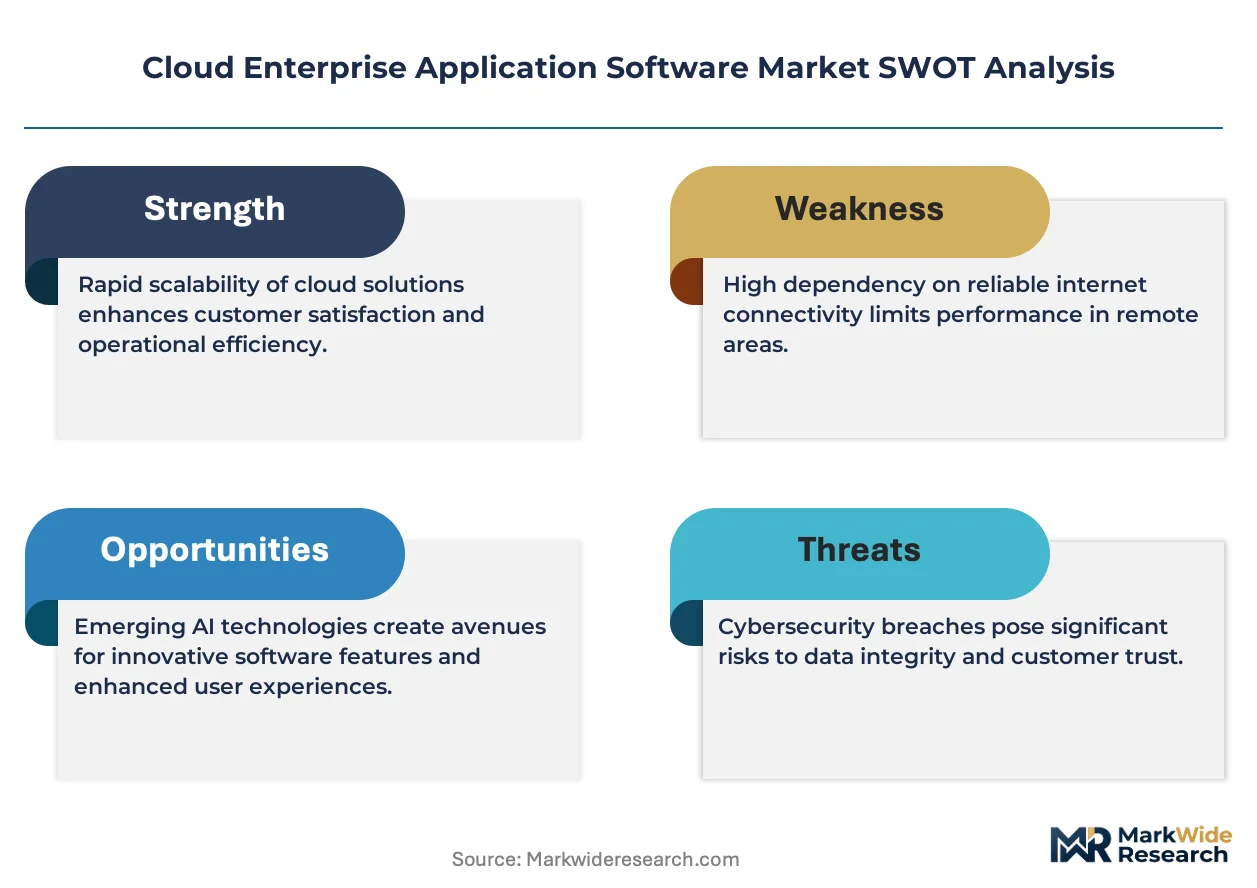
Hybrid cloud architectures are fragmenting procurement patterns across the Cloud Enterprise Application Software Market as regulated industries reconcile data sovereignty mandates with elastic infrastructure requirements. Sovereign cloud deployments in Europe, driven by GDPR territoriality rules and the EU AI Act, are forcing vendors to engineer region-locked instances that complicate global workload orchestration.
Growth Catalysts
- EU AI Act compliance deadlines:European enterprises are accelerating migrations to certified cloud ERP suites that embed algorithmic accountability controls and automated audit trails for high-risk AI applications.
- Healthcare digitization:Hospital systems and pharmaceutical manufacturers are replacing on-premises patient record infrastructure with cloud HCM and ERP platforms that satisfy FDA 21 CFR Part 11 validation protocols.
- Container orchestration maturation:Kubernetes-native microservices architectures are enabling modular ERP deployments that reduce integration timelines for mid-market manufacturers upgrading legacy SAP environments.
Market Restraints
- Data residency fragmentation:The EU GDPR, China's PIPL, and Saudi Arabia's PDPL create incompatible territorial storage requirements that inflate vendor engineering costs and limit cross-border analytics portability.
- Specialized talent scarcity:Cloud-native ERP architects with both legacy system knowledge and container orchestration expertise command premium compensation that concentrates within hyperscaler partner ecosystems.
- Hybrid integration complexity:Enterprises maintaining on-premises SAP or Oracle databases alongside cloud SaaS layers face persistent latency and synchronization failures that degrade real-time reporting reliability.
Strategic Opportunities
- India's PLI-linked manufacturing cloud:Production-linked incentive beneficiaries in automotive and electronics are adopting cloud MES and ERP bundles to satisfy BIS traceability mandates and export compliance documentation.
- Edge-cloud convergence for industrial IoT:German automotive suppliers are deploying distributed ERP nodes that process shop-floor telemetry locally while aggregating financial consolidation data in centralized cloud instances.
- Outcome-based licensing models:Vendors are piloting consumption-metered ERP contracts tied to actual transaction volumes rather than named user counts, lowering adoption barriers for seasonal businesses and project-based professional services firms.
Industry Challenges
- Multi-cloud credential sprawl:Security teams struggle to maintain consistent identity federation across AWS, Azure, and Google Cloud instances while satisfying ISO 27001 and SOC 2 Type II audit requirements.
- Legacy data migration integrity:Decades of on-premises financial and HR records require costly cleansing and field mapping before cloud ERP cutover, with German Mittelstand manufacturers reporting extended parallel-run periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Enterprise Application Software Market |
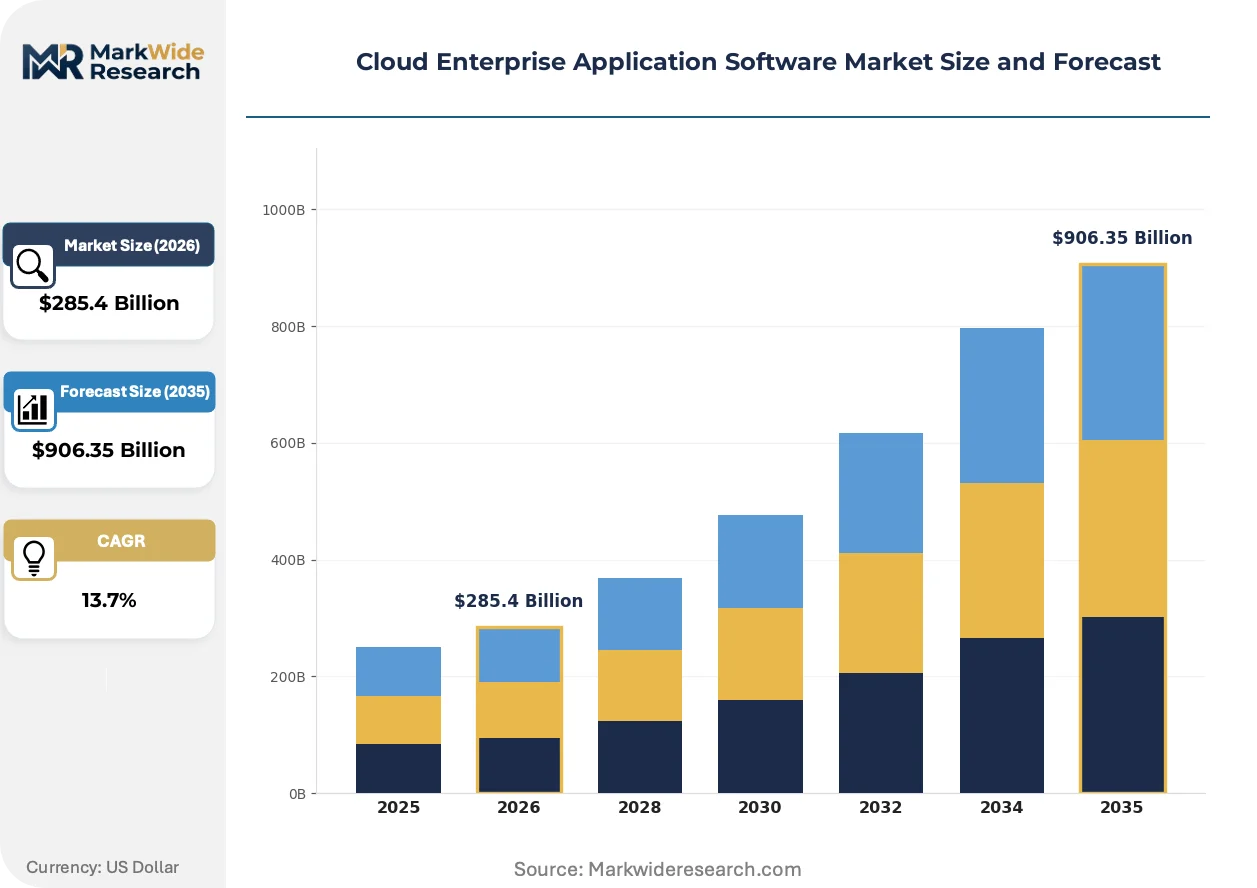
| Market Size in 2026 | $285.4 Billion |
| Market Size in 2035 | $906.35 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CRM, ERP, SCM, HCM Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: SMBs, Enterprises, Government, Non-Profit Industry Vertical: Healthcare, Finance, Retail, Education |
| Companies Covered | IBM, VMware, Accenture, Amazon Web Services, Atlassian, Oracle Corporation, Infor, Google Cloud, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Enterprise Application Software Market Strategic Shifts & Innovations
Artificial intelligence infusion is compressing implementation cycles and redefining user interfaces across enterprise cloud suites. Vendors are embedding generative capabilities that automate workflow configuration and natural language querying, displacing traditional menu-driven navigation.
Microservices-based ERP architecture is decomposing monolithic finance and supply chain modules into independently deployable functions. Industrial manufacturers in Germany and the United States are adopting these containerized components to isolate upgrade impacts and accelerate feature rollout. This decomposition is compressing vendor release cycles from annual to quarterly while fragmenting integration responsibility across internal DevOps teams.
The EU AI Act's risk classification framework is mandating algorithmic transparency documentation for cloud HCM and CRM systems deployed in European member states. Vendors must now maintain technical files detailing training data provenance and bias testing protocols for automated hiring and customer scoring tools. Healthcare and financial services procurement teams in France, Germany, and the Netherlands are prioritizing suppliers with pre-certified conformity assessments.
Subscription fatigue is prompting large enterprises to unbundle integrated suites and procure best-of-breed point solutions through cloud marketplaces. Procurement functions at North American and European manufacturers are negotiating direct contracts with specialized vendors for treasury management or carbon accounting modules, bypassing primary ERP vendor channels. This disintermediation is most pronounced among industrial conglomerates with heterogeneous geographic operations requiring localized compliance adaptations.
Cloud Enterprise Application Software Market Segmentation
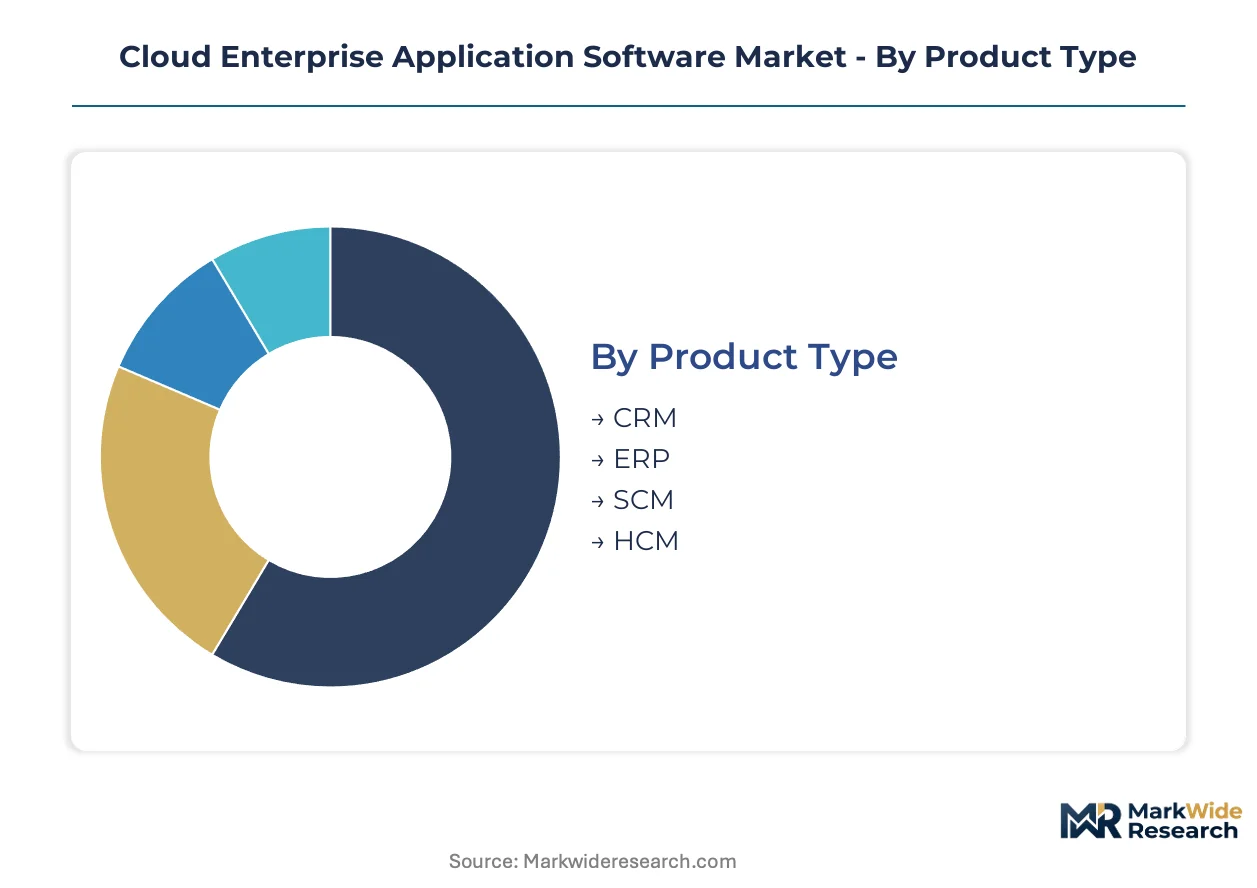
Cloud enterprise application software segments diverge sharply on compliance architecture and integration complexity. Procurement patterns cluster around deployment sovereignty requirements and end-user scale thresholds rather than feature parity alone.
Product Type:
FDA 21 CFR Part 11 and EU GDPR territoriality rules fragment validation requirements across functional modules. Healthcare and financial services procurement teams weight audit trail capabilities differently by segment.
- ERP:Monolithic finance and supply chain cores now decompose into Kubernetes-orchestrated microservices. German automotive suppliers and Mittelstand manufacturers drive demand as they migrate legacy SAP environments to containerized architectures with hybrid data residency.
- CRM:Generative AI infusion compresses sales cycle analytics and displaces menu-driven interfaces. Shorter implementation timelines and lower switching costs accelerate recurring revenue streams compared to ERP counterparts.
- SCM:Multi-tier supplier traceability modules address BIS documentation mandates for India's PLI scheme beneficiaries in automotive and electronics export channels.
- HCM:Cloud-native talent platforms embed algorithmic accountability controls for EU AI Act high-risk hiring automation compliance.
ERP handles the majority of throughput; CRM is the fastest mover on share.
Deployment:
Cost-to-performance ratios stratify sharply across infrastructure models. Sovereignty premiums and elastic capacity needs create divergent TCO profiles for regulated versus growth-stage adopters.
- Hybrid Cloud:Distributed architectures process shop-floor telemetry at German automotive supplier edge nodes while centralizing financial consolidation in cloud instances. This model captures disproportionate growth as manufacturers reconcile GDPR data residency with burst compute needs.
- Public Cloud:Multi-tenant SaaS delivery minimizes upfront capital deployment for mid-market professional services firms and seasonal businesses.
- Private Cloud:Single-tenant instances satisfy EMA pharmacovigilance data integrity requirements and FDA validation protocols for pharmaceutical manufacturers.
- On-Premises:Legacy SAP and Oracle database retention persists where latency-sensitive manufacturing execution systems require sub-millisecond response times.
Hybrid Cloud commands the steepest expansion trajectory; On-Premises retains entrenched positions in validated manufacturing environments.
End User:
Procurement sophistication and implementation risk tolerance scale with organizational complexity. Integration budget depth and compliance staff density determine segment attractiveness.
- Enterprises:Global workload orchestration demands drive multi-year ERP migrations with dedicated DevOps teams managing API-first integration layers.
- SMBs:Pre-configured industry templates and consumption-metered contracts lower adoption barriers for project-based firms without dedicated IT architecture functions.
- Government:FedRAMP and equivalent national certification requirements extend sales cycles while creating vendor lock-in through specialized compliance engineering.
- Non-Profit:Grant-funded implementations prioritize donor reporting transparency and restricted fund accounting modules over operational breadth.
Enterprises absorb the deepest integration investments; SMBs expand most quickly as cloud marketplaces democratize access.
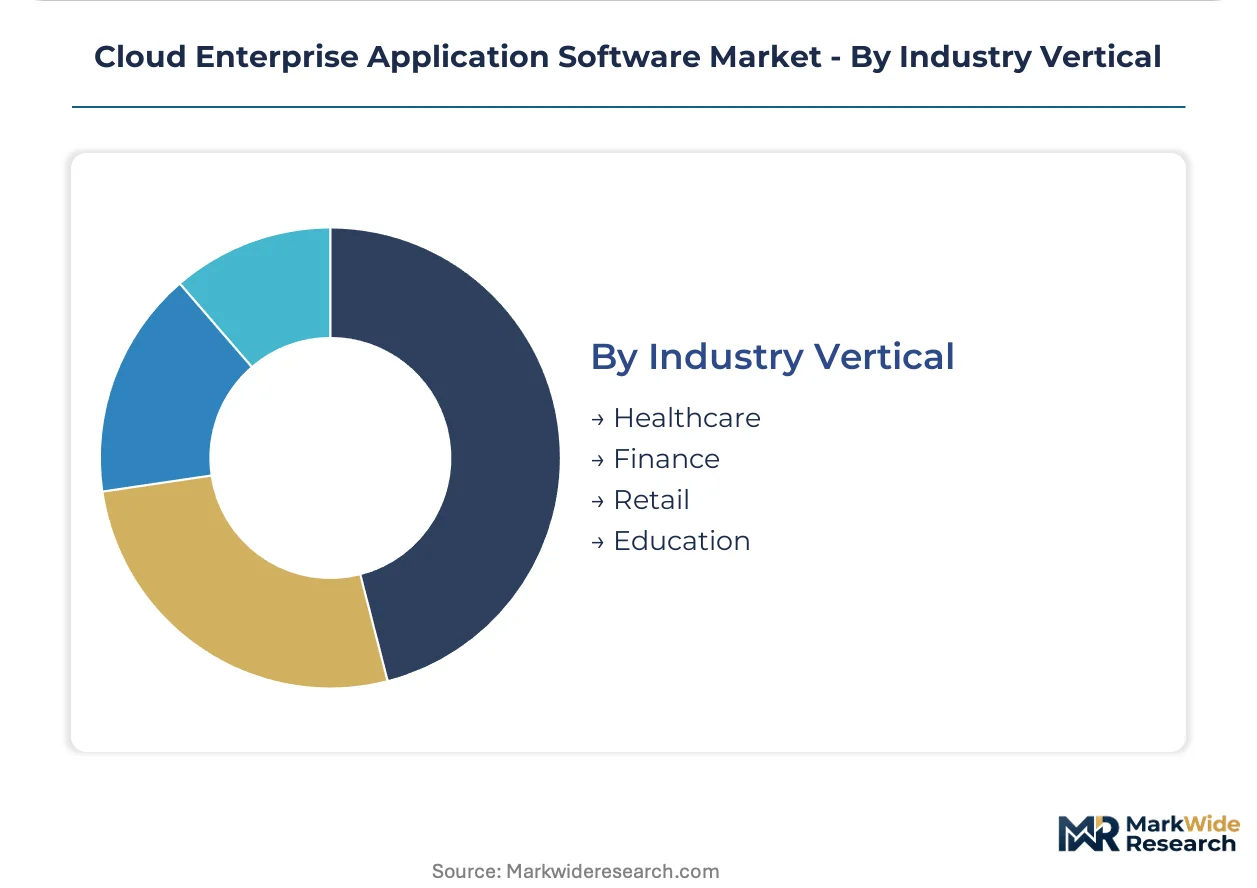
Industry Vertical:
Regulatory density and data sensitivity create vertical-specific procurement criteria. Validation protocols and territorial storage mandates reshape competitive positioning by sector.
- Healthcare:FDA 21 CFR Part 11 validation requirements and HIPAA security rule compliance dominate cloud ERP and HCM procurement criteria for hospital systems replacing on-premises patient record infrastructure.
- Finance:SOX audit trail mandates and SEC record-keeping rules drive demand for immutable ledger integration and automated compliance documentation.
- Retail:Seasonal volume volatility favors consumption-based licensing models with elastic capacity scaling for peak transaction periods.
- Education:FERPA student privacy protections and state-level procurement regulations fragment vendor selection across public university systems and private institutions.
Healthcare generates the most stringent certification requirements; Finance offers the highest contract values per seat.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GDPR territoriality rules and the EU AI Act are anchoring regulatory gravity in Europe, while healthcare digitization and sovereign cloud mandates create divergent procurement patterns across major economies.
United States
Hospital systems and pharmaceutical manufacturers are replacing legacy patient record infrastructure with cloud HCM and ERP platforms. FDA 21 CFR Part 11 validation protocols dominate procurement criteria for electronic records handling. The Boston-Cambridge biotech corridor and Research Triangle Park in North Carolina are driving concentrated demand for compliant cloud suites.
Germany
Industrial manufacturers in automotive and machinery sectors are migrating legacy SAP environments to hybrid cloud architectures. The EU AI Act's algorithmic accountability requirements and GDPR data residency rules compel regional instance deployment. Baden-Württemberg's automotive supplier cluster and Bavaria's Mittelstand manufacturing belt are leading containerized ERP adoption.
United Kingdom
Financial services firms are demanding immutable ledger integration for SOX-equivalent audit trail mandates under FCA guidelines. Cloud ERP procurement prioritizes automated compliance documentation for SEC record-keeping alignment. London's fintech concentration and Edinburgh's asset management hub are accelerating multi-tenant SaaS deployments.
India
Production-linked incentive beneficiaries in automotive and electronics are adopting cloud MES and ERP bundles. BIS traceability mandates and DGFT export compliance documentation requirements shape vendor selection. Tamil Nadu's electronics manufacturing cluster and Maharashtra's automotive belt are driving disproportionate growth in manufacturing cloud adoption.
Japan
Automotive OEMs and precision machinery manufacturers are deploying distributed ERP nodes for shop-floor telemetry processing. METI's data governance guidelines and JIS standards compliance create localization requirements. The Chubu region around Nagoya and Kanto's Tokyo-Yokohama manufacturing corridor are leading edge-cloud convergence for industrial IoT.
Cloud Enterprise Application Software Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the Cloud Enterprise Application Software Market. Database infrastructure specialists and hyperscale compute providers anchor distinct competitive tiers, while systems integrators occupy intermediary positions. Strategic consolidation centers on M&A activity targeting container orchestration capabilities and vertical-specific compliance engineering, alongside geographic expansion through sovereign cloud instance deployment.
Among database-centric providers, Oracle Corporation exemplifies the infrastructure-anchored archetype with decades of ERP integration dominance. Microsoft occupies a position bridging productivity suite stickiness with cloud platform scale. Amazon Web Services represents the hyperscale compute archetype competing on elastic capacity and specialized industry cloud offerings. These three players collectively illustrate the tripartite structure governing enterprise procurement decisions.
| Leading Market Players |
|---|
| IBM |
| VMware |
| Accenture |
| Amazon Web Services |
| Atlassian |
| Oracle Corporation |
| Infor |
| Google Cloud |
| Microsoft |
| Others |
Cost & Logistics Intelligence
Ninety-day implementation cycles for hybrid ERP deployments concentrate vendor capacity in Germany and the United States, compressing pricing power for mid-market buyers while extending lead-time premiums for sovereign cloud configurations in Europe. This supply-side bottleneck amplifies cost differentials between standardized public cloud SaaS and compliance-engineered private instances.
Pricing Analysis
Geographic price spreads of 40-60% separate North American public cloud SaaS from EU sovereign cloud instances governed by GDPR territoriality rules and EU AI Act certification requirements. Subscription-based tiered pricing dominates, with differentiation driven by compliance certification grade and customization depth for legacy SAP migration scenarios. Pricing pressure stems from hyperscaler competition in raw compute layers, though specialized healthcare and financial services tiers retain margin resilience. SMB procurement teams exhibit highest price sensitivity, while German automotive manufacturers absorb premium engineering costs for hybrid data residency.
Supply Chain Analysis
Just-in-time provisioning of Kubernetes-orchestrated microservices modules prevails among container-native vendors, contrasting with strategic stockpiling of legacy SAP integration specialists by systems integrators facing talent scarcity. Engineering talent concentrates in the United States, Germany, and India, with cloud-native architects commanding premium compensation that feeds into implementation pricing. Raw material dependencies span hyperscaler data center capacity, specialized compliance certification engineering, and legacy database migration tooling. Single-source vulnerability sits with Kubernetes orchestration expertise concentrated within hyperscaler partner ecosystems. Distribution runs through direct enterprise sales teams, cloud marketplace aggregators, and systems integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Cloud Enterprise Application Software Market represents high-growth disruption as containerized microservices architectures displace monolithic ERP deployments and EU AI Act compliance deadlines force accelerated procurement cycles.
For Market Incumbents: Consolidate container orchestration capabilities through targeted acquisition of Kubernetes-native specialists to defend against hyperscaler encroachment into ERP integration layers. Deepen compliance engineering investment for EU sovereign cloud instances to capture GDPR-mandated data residency premiums before certification bottlenecks concentrate pricing power with early movers.
For New Entrants and Emerging Players: Anchor in India's PLI-linked manufacturing cloud segment, where BIS traceability mandates and DGFT export documentation requirements create compliance-driven demand underserved by incumbent ERP vendors. Target automotive and electronics beneficiaries in Tamil Nadu and Maharashtra with pre-configured MES-ERP bundles and consumption-metered pricing that bypasses capital-intensive user-based licensing.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates divesting non-core software assets amid unbundling trends toward best-of-breed point solutions. Long-term viability favors vendors with sovereign cloud instance deployment capabilities and pre-certified EU AI Act conformity assessments. Monitor FDA 21 CFR Part 11 validation backlog clearance rates as inflection indicator for healthcare cloud ERP demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deepens Azure-Office 365 stickiness for Microsoft against Oracle database-anchored ERP migrations. |
| Acquisition of Specialist Firm | Captures Kubernetes-native talent scarce among legacy SAP integration partners in German Mittelstand belt. |
| Geographic Expansion | Deploys sovereign cloud instances in EU to satisfy GDPR territoriality and EU AI Act algorithmic accountability mandates. |
| Strategic Partnership | Links hyperscaler compute capacity with vertical-specific compliance engineering for FDA-validated healthcare workloads. |
| Product Launch | Introduces consumption-metered ERP contracts tied to transaction volumes rather than named user counts for seasonal businesses. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CIOs, cloud architects, ERP implementation leads, and procurement officers at healthcare systems and industrial manufacturers across the United States, Germany, and India. Secondary validation drew from SEC filings, hyperscaler capex disclosures, EMA pharmacovigilance guidance documents, and EU AI Act implementation tracking. Bottom-up deployment volume estimates triangulated against top-down addressable market sizing by vertical and organization scale.
Across the analysis window, the forecasting framework modeled deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster as primary segmentation dimensions. CAGRs were derived from trend extrapolation of migration velocity data and compliance deadline impacts. Forecast inputs incorporated Kubernetes adoption curves in legacy SAP environments and sovereign cloud instance deployment timelines driven by GDPR enforcement patterns.
Decision-makers should treat outputs as directional under assumptions of sustained EU AI Act implementation timelines and stable hyperscaler pricing for raw compute layers; material deviation would warrant model refresh. Specific risk factors include accelerated data residency fragmentation from China's PIPL or Saudi Arabia's PDPL expansion, and talent scarcity spikes disrupting implementation velocity. Revision becomes warranted when sovereign cloud certification backlog durations cross six-month thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Mobile Application Development Market
Software & Services
Bridge Analysis Software Market
Software & Services
Database Monitoring Software Market
Software & Services
Financial Corporate Performance Management (FCPM) Software Market
Software & Services
Global Application Development Software Market
Software & Services
E-Clinical Solution Software Market
Software & Services
3PL Software Market
Software & Services
Landscaping Engineering Software Market
Software & Services
Global Mobile Middleware Market
Software & Services
Global Invoice Automation Software Market
Software & Services
Content As a Service (Caas) Market
Software & Services
Video Editing Software Market
Software & Services
Lifecycle Management Software Market
Software & Services
Global Referral Software Market
Software & Services
Global UIUX Software Market
Software & Services
Tableau Services Market