
 Location-Based Marketing Software Market | 2026-2036
Location-Based Marketing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Location-Based Marketing Software Market Analysis
GDPR is broadening the cost-of-entry calculus for location-based marketing software vendors by mandating granular consent architectures and data-localization safeguards. Google sustains technology leadership in mapping infrastructure and geofencing APIs that underpin third-party campaign platforms. Foursquare differentiates through proprietary venue-recognition algorithms and first-party location intelligence. Esri dominates in geospatial analytics, extending its ArcGIS platform into retail and logistics use cases.
Location-based marketing software processes real-time geospatial signals from GPS, Wi-Fi, Bluetooth, and RFID to trigger personalized messaging, route optimization, or audience segmentation within defined geographic perimeters. The system ingests latitude-longitude coordinates, proximity radii, and dwell-time thresholds to execute programmatic campaigns or generate foot-traffic attribution reports. Cloud and SaaS deployment models lead the solution architecture due to elastic compute requirements for real-time signal processing and multi-tenant campaign orchestration. Retailers anchor end-user demand as brick-and-mortar operators deploy geofencing to recover in-store traffic and measure digital-to-physical conversion paths.
The Federal Trade Commission enforces truth-in-advertising standards for location claims, while the FCC governs wireless spectrum use for Bluetooth and Wi-Fi beacon transmissions that enable proximity marketing. The California Consumer Privacy Act imposes additional notice and opt-out obligations on businesses collecting precise geolocation data from state residents. Stakeholders must monitor evolving state-level privacy legislation and invest in consent-management infrastructure to preserve campaign reach without triggering enforcement exposure.
Market Dynamics
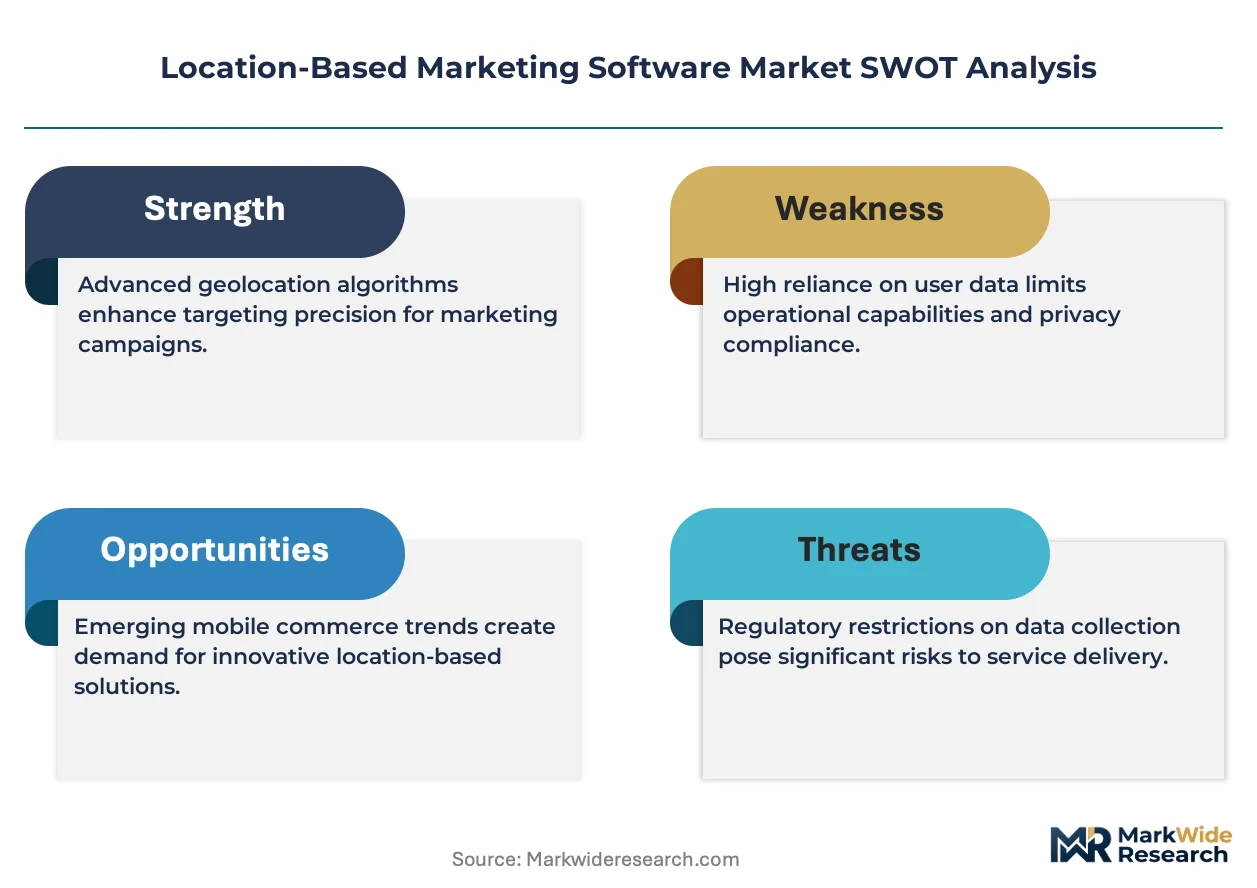
The Location-Based Marketing Software Market faces a structural inflection where privacy-first data architectures collide with real-time personalization demands. GDPR and the California Consumer Privacy Act force vendors to rebuild consent pipelines while retailers insist on granular foot-traffic attribution.
Growth Catalysts
- Geofencing API maturation:Cloud providers expose turnkey proximity-triggering infrastructure that slashes deployment timelines for retail chains bridging digital and physical customer journeys.
- EU GDPR consent frameworks:Regulatory pressure paradoxically advantages compliant first-party data aggregators who can demonstrate audit-ready geolocation governance.
- Smartphone penetration density:United States urban corridors sustain signal-rich environments where Bluetooth beacon and Wi-Fi fingerprinting accuracy supports sub-ten-meter campaign triggering.
Market Restraints
- Silicon supply concentration:Bluetooth Low Energy chip fabrication concentrates in Taiwan and South Korea, exposing beacon hardware costs to foundry capacity constraints.
- Battery chemistry volatility:Lithium-ion cell prices for portable beacon deployments fluctuate with raw material extraction bottlenecks in Chile and Australia.
- Signal interference limitations:Dense urban steel-and-glass architecture degrades GPS accuracy below ten meters, forcing redundant sensor fusion that inflates hardware BOMs.
Strategic Opportunities
- India retail modernization:Organized brick-and-mortar expansion in Mumbai and Bangalore creates first-mover terrain for proximity marketing platforms before privacy regulation crystallizes.
- AI-driven predictive geofencing:Machine learning models forecasting consumer trajectory before physical entry compress dwell-time thresholds and boost conversion precision.
- EU Green Deal procurement incentives:Public-sector retail and transit authorities in Germany and France prioritize carbon-footprint-minimized supply chains, advantaging SaaS-over-hardware beacon architectures.
Industry Challenges
- Consent-management engineering talent:Shortage of privacy-by-design architects who can build real-time opt-out pipelines without breaking campaign orchestration latency budgets.
- Legacy POS integration friction:Decades-old retail transaction systems lack API-native interfaces, forcing expensive middleware development to close digital-to-physical attribution loops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Location-Based Marketing Software Market |
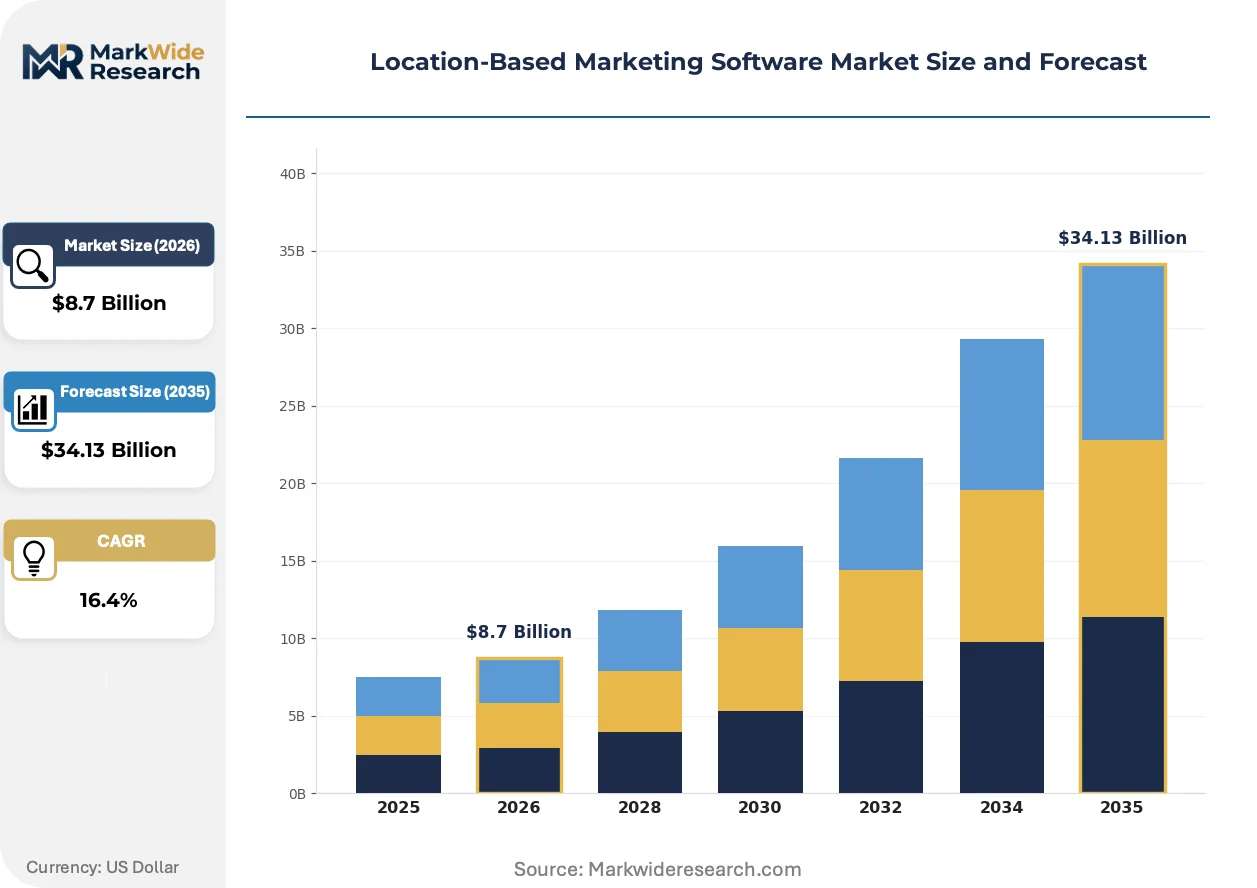
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud, On-Premise, Hybrid, SaaS End User: Retailers, Restaurants, E-commerce, Service Providers Technology: GPS, RFID, Wi-Fi, Bluetooth Solution: Analytics, Campaign Management, Customer Engagement, Audience Targeting |
| Companies Covered | CleverTap, Emarsys, GroundTruth, Foursquare, Google, Esri, InMarket, PlaceIQ, Cuebiq, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Location-Based Marketing Software Market Emerging Trajectories
Edge computing architectures are redistributing signal processing from centralized clouds to local nodes, compressing campaign latency while complicating data residency compliance. This shift demands new vendor capabilities spanning hardware, firmware, and distributed software layers.
Ultra-wideband (UWB) positioning chips are electrifying proximity accuracy standards in high-value retail environments. Luxury department stores in Tokyo and Dubai deploy UWB-enabled fitting rooms that trigger personalized recommendations within thirty centimeters. The technology is compressing competitive differentiation around sub-meter spatial resolution that Wi-Fi and Bluetooth cannot replicate.
The EU AI Act introduces risk-classification obligations for automated decision systems processing geolocation data. Campaign platforms using predictive audience segmentation now face conformity assessment requirements before deployment in European markets. Retail software vendors are responding by engineering explainability layers that expose scoring logic to audit trails.
Buyer procurement patterns in North American retail are pivoting toward outcome-based pricing tied to verified foot-traffic lift rather than impression volume. CMOs at mid-market apparel chains now demand attribution guarantees that legacy CPM contracts cannot satisfy. This compression is forcing platform vendors to absorb performance risk and invest in third-party measurement partnerships.
Location-Based Marketing Software Market Segmentation
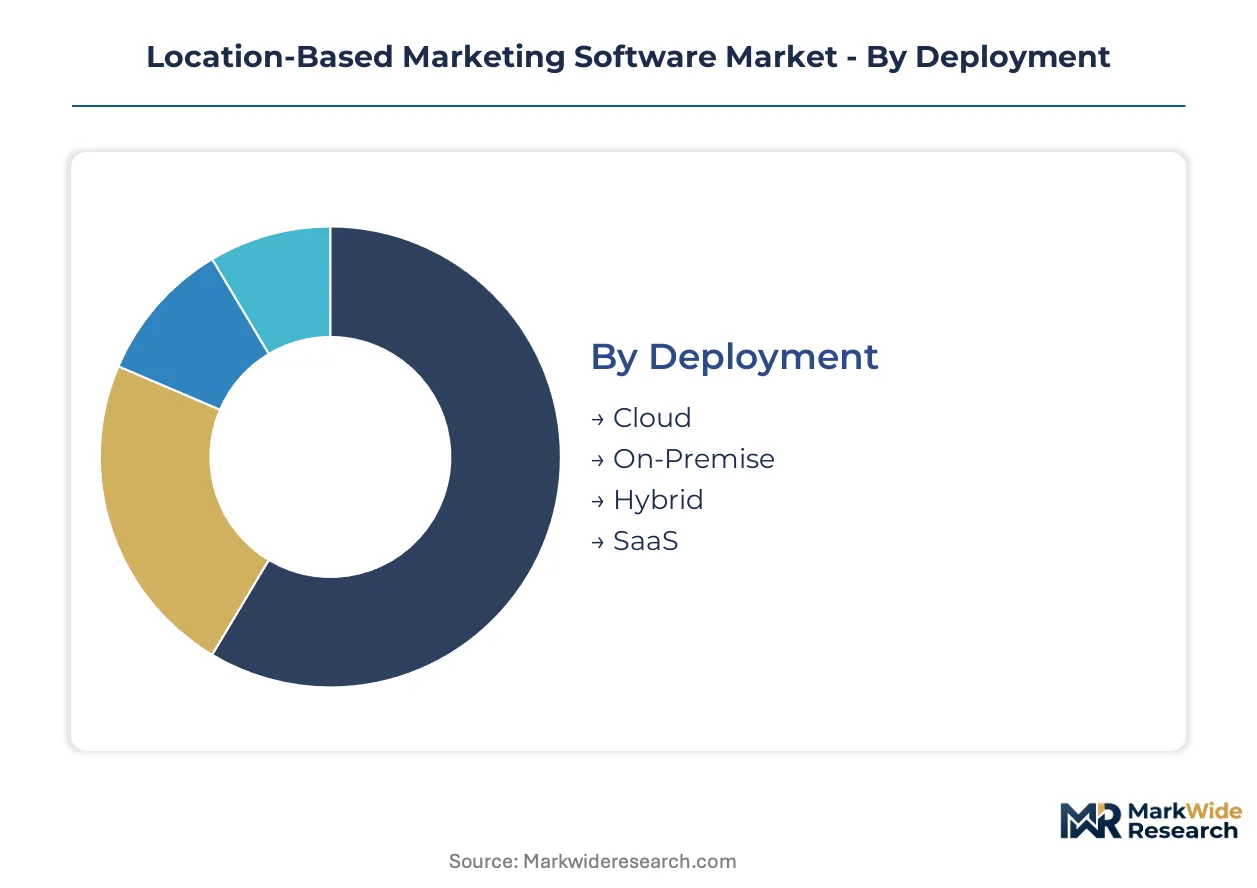
Deployment architecture determines data residency compliance and latency performance for location-based campaigns. End-user verticals impose distinct proximity-triggering requirements and attribution depth. Technology selection governs spatial accuracy and hardware cost structures across use cases.
Deployment:
Retail chains and transit authorities differentiate procurement decisions by sovereignty requirements and campaign velocity needs.
- Cloud:Elastic compute pools process real-time geofence breaches across millions of devices without capital infrastructure. United States urban retailers favor cloud architectures to compress campaign deployment from months to days, though GDPR forces EU data localization add-ons.
- SaaS:Multi-tenant platforms abstract beacon management and consent orchestration into subscription tiers. Mid-market apparel chains in Germany and France prioritize SaaS to avoid privacy-engineering headcount.
- On-Premise:Dedicated server installations satisfy banking and healthcare sector data sovereignty mandates. Airports in Dubai and Singapore deploy on-premise stacks to retain passenger movement analytics within national boundaries.
- Hybrid:Split architectures process raw signals locally while pushing aggregated insights to central clouds. Japanese convenience store operators use hybrid models to balance real-time promotion triggering with corporate BI consolidation.
Volume sits with Cloud; growth tilts toward SaaS as procurement shifts from capacity purchasing to outcome-based contracts.
End User:
Foot-traffic recovery urgency and digital attribution maturity separate buyers across verticals.
- Retailers:Brick-and-mortar operators deploy geofencing to recover in-store traffic and measure digital-to-physical conversion paths. United States department store chains anchor category demand with proximity-triggered promotion budgets.
- Restaurants:Quick-service operators use dwell-time thresholds to push mobile coupons during off-peak hours. Chains in India and Brazil expand beacon deployments ahead of privacy regulation crystallization.
- E-commerce:Pure-play digital retailers leverage location data for last-mile delivery optimization and hyperlocal inventory advertising. Same-day delivery platforms in the United Kingdom drive API consumption for route compression.
- Service Providers:Telecommunications and utility companies apply geospatial segmentation for field service dispatch and customer churn prediction. Australian energy retailers use location intelligence to target solar panel prospects by rooftop exposure mapping.
Revenue concentrates with Retailers; expansion accelerates most quickly in Restaurants as post-pandemic foot-traffic recovery programs multiply.
Technology:
Spatial accuracy requirements and infrastructure sunk costs drive technology selection divergence.
- GPS:Satellite-based positioning enables wide-area geofencing with ten-to-fifty-meter accuracy. United States logistics fleets rely on GPS for highway corridor triggering despite urban canyon degradation.
- Bluetooth:Low-energy beacon protocols achieve sub-ten-meter precision for in-store proximity campaigns. Luxury retailers in France and Italy deploy Bluetooth mesh networks for fitting room personalization.
- Wi-Fi:Fingerprinting techniques leverage existing access point infrastructure without dedicated hardware. Shopping malls in Singapore and Hong Kong repurpose Wi-Fi probe requests for anonymous foot-traffic mapping.
- RFID:Passive and active radio-frequency tags enable item-level tracking and interactive display triggering. Automotive showrooms in Germany use RFID for vehicle proximity demonstrations.
Bluetooth captures the largest installed base; ultra-wideband displacement is gaining share fastest in high-value retail environments.
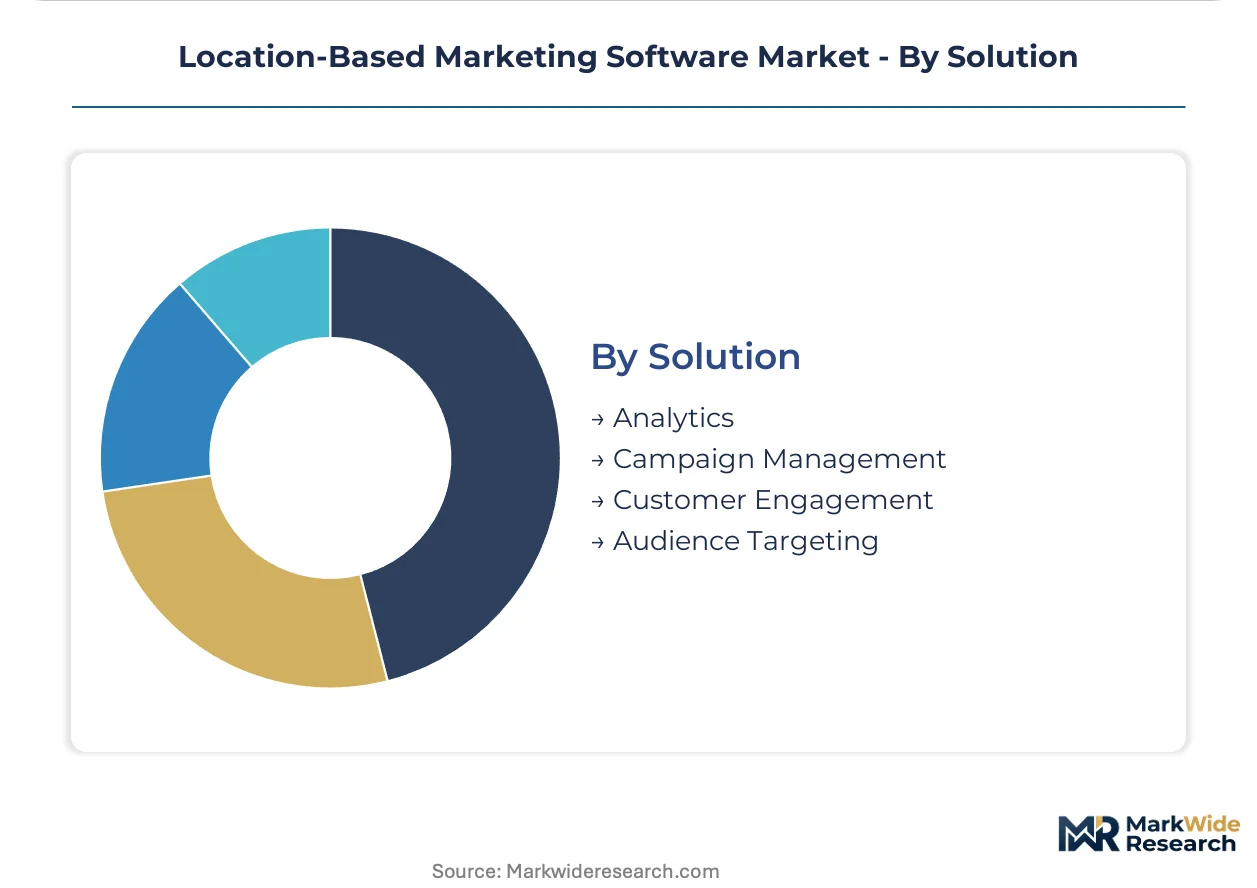
Solution:
Buyers prioritize either operational intelligence extraction or direct revenue activation from location data investments.
- Campaign Management:Platforms orchestrate geofence definition, creative rotation, and frequency capping across proximity-triggered channels. United States quick-service restaurant chains demand campaign management with same-day activation capabilities.
- Analytics:Foot-traffic attribution engines correlate mobile ad exposure with store visit verification. Retailers in the United Kingdom and Netherlands prioritize analytics modules with third-party measurement certification.
- Customer Engagement:Real-time messaging systems push notifications, SMS, or in-app content based on entry and dwell events. Fitness chains in Australia deploy engagement tools for class reminder automation.
- Audience Targeting:Segmentation engines build lookalike profiles from visitation patterns and demographic overlays. E-commerce platforms in India use targeting solutions to identify high-intent shoppers near competitor locations.
Campaign Management dominates current spending; Analytics is climbing the fastest as CMOs demand verified attribution guarantees over impression volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States urban corridors concentrate the heaviest deployment of proximity-triggered campaigns, while European privacy frameworks and Asian retail modernization programs create divergent growth trajectories across national markets.
United States
Department store chains and quick-service restaurant operators drive geofencing adoption to recover post-pandemic foot traffic and measure digital-to-physical attribution. The FTC enforces truth-in-advertising standards for location claims while the FCC governs wireless spectrum use for beacon transmissions. New York City and Los Angeles sustain dense signal environments where Bluetooth and Wi-Fi fingerprinting achieve sub-ten-meter campaign triggering accuracy.
Germany
Automotive showrooms and luxury retailers deploy RFID-enabled vehicle demonstrations and fitting room personalization systems. The EU GDPR mandates granular consent architectures and data-localization safeguards that advantage compliant first-party data aggregators. Frankfurt and Munich anchor industrial clusters where SaaS procurement prioritizes carbon-footprint-minimized supply chains under EU Green Deal incentives.
United Kingdom
Same-day delivery platforms and mid-market apparel chains consume API infrastructure for route compression and verified foot-traffic attribution. The Information Commissioner's Office enforces GDPR-aligned consent requirements for precise geolocation collection. London's West End retail district concentrates demand for third-party measurement certification and outcome-based pricing contracts.
India
Organized brick-and-mortar expansion in Mumbai and Bangalore creates first-mover terrain for proximity marketing platforms before privacy regulation crystallizes. TRAI governs telecommunications infrastructure supporting mobile-based location services. Quick-service restaurant chains accelerate beacon deployments ahead of anticipated national data protection legislation.
Japan
Convenience store operators and fitness chains deploy hybrid edge-cloud architectures for real-time promotion triggering and class reminder automation. METI promotes digital transformation standards affecting retail technology procurement. Tokyo's luxury department stores pioneer ultra-wideband-enabled fitting rooms with thirty-centimeter spatial resolution.
Location-Based Marketing Software Market Vendor Landscape
United States technology providers anchor the cloud infrastructure tier; European mapping specialists and Asian engagement platforms hold differentiated positions in analytics and campaign orchestration. The vendor base splits between consolidated platform operators with full-stack capabilities and focused specialists in venue recognition or geospatial analytics. Three archetypes dominate: mapping infrastructure providers, first-party location intelligence aggregators, and geospatial analytics platform vendors. Competitive moves concentrate on strategic partnerships with retail chains and portfolio diversification into predictive audience segmentation.
Within the mapping infrastructure tier, Google and Esri occupy positions representing cloud-native proximity API provision and enterprise geospatial platform extension respectively. Foursquare exemplifies the first-party data archetype through proprietary venue-recognition algorithms. These three companies illustrate how technology leadership fragments across infrastructure, analytics, and intelligence specializations rather than consolidating under single vendors.
| Leading Market Players |
|---|
| CleverTap |
| Emarsys |
| GroundTruth |
| Foursquare |
| Esri |
| InMarket |
| PlaceIQ |
| Cuebiq |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up SaaS specialists anchor the vendor landscape, concentrating pricing discipline through recurring-revenue contract structures while compressing hardware procurement cycles for beacon-dependent deployments.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with United States retailers paying subscription uplifts for same-day geofence activation versus standard thirty-day implementation windows. Pricing stratifies across premium, standard, and economy tiers tied to consent-management sophistication and third-party measurement certification. Cost compression in the mid-market tier is intensifying because German and French buyers bundle carbon-footprint disclosures into procurement scoring. Quick-service restaurant chains exhibit highest price sensitivity, while luxury department stores in Tokyo and Dubai absorb premiums for ultra-wideband precision.
Supply Chain Analysis
Dual-sourcing mandates from United States retail chains force qualification of alternative beacon hardware vendors beyond primary Taiwan and South Korea fabricators. Bluetooth Low Energy chip fabrication concentrates in Taiwan and South Korea, while lithium-ion cell production for portable beacon deployments draws from China and Japan. Single-source vulnerability persists at the foundry level, where TSMC and Samsung capacity allocation dictates hardware lead times. Distribution runs through hyperscaler marketplaces and direct OEM relationships, with cloud API provisioning displacing traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consent-management engineering talent scarcity props pricing power for vendors with audit-ready privacy architectures, creating supply-constrained conditions across the European procurement pipeline.
For Market Incumbents: Extend first-party data aggregation capabilities through proprietary venue-recognition algorithm investments, countering threat from emerging privacy-preserving federated learning platforms. Build backward integration into edge computing hardware to reduce dependency on Taiwan foundry capacity and compress campaign latency budgets. For New Entrants and Emerging Players: Ultra-wideband positioning modules offer technology-first wedge into high-value retail environments where sub-meter spatial resolution commands premium pricing. Target Indian quick-service restaurant chains before national data protection legislation crystallizes, deploying outcome-based pricing tied to verified foot-traffic lift. For Investors and Strategic Acquirers: Distressed-cycle entries favor SaaS-native campaign orchestration platforms with GDPR-compliant consent pipelines in Germany and France. Long-term viability hinges on predictive geofencing AI capabilities. Watch for inflection when United States mid-market retailers shift procurement from impression-volume to verified attribution guarantees.| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-by-Design Certification Investment | GDPR and EU AI Act compliance accelerates procurement eligibility in Frankfurt and Munich industrial clusters. |
| Ultra-Wideband Hardware Partnership | Thirty-centimeter positioning precision unlocks luxury retail deployments in Tokyo department stores. |
| Outcome-Based Pricing Transition | Foot-traffic attribution guarantees align vendor incentives with United States CMO performance metrics. |
| Edge Computing Architecture Deployment | Local signal processing satisfies Japanese convenience store operators' real-time promotion requirements. |
| India Market Entry Acceleration | First-mover positioning in Mumbai and Bangalore precedes anticipated TRAI data localization mandates. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with platform engineering directors, retail CMOs, privacy compliance officers, and beacon hardware procurement leads. SEC 10-K disclosures from cloud infrastructure providers, GDPR enforcement actions from European data protection authorities, and FCC spectrum allocation records provided validation layers. Bottom-up deployment counts triangulated against top-down SaaS revenue estimates.
Granularity-level modeling captured deployment architecture at the country-city tier, end-user vertical at the sub-sector level, and technology selection at the protocol-specification tier across the analysis window. CAGRs derived from elasticity-adjusted adoption curves incorporating smartphone penetration density and retail foot-traffic recovery trajectories. Forecast inputs included Bluetooth beacon shipment volumes and cloud API consumption metrics from hyperscaler disclosures.
Several conditions sit outside the modeled scope, including speculative national data protection legislation in India and Brazil, and breakthrough battery chemistry displacing lithium-ion in portable beacon form factors. Forecasts assume continued FCC spectrum stability for Bluetooth and Wi-Fi transmissions. Deviation in EU AI Act enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Saudi Arabia Location-Based Services Market
Geographic Information Systems (GIS)
Sales Mapping System Market
Geographic Information Systems (GIS)
China Location-Based Services Market
Geographic Information Systems (GIS)
China Geospatial Analytics Market
Geographic Information Systems (GIS)
Europe Mobile Mapping Market
Geographic Information Systems (GIS)
South Korea Geospatial Analytics Market
Geographic Information Systems (GIS)
Business Mapping Software Market
Geographic Information Systems (GIS)
Japan Location-Based Services Market
Geographic Information Systems (GIS)
Cloud GIS Market
Geographic Information Systems (GIS)
Mobile Map Market
Geographic Information Systems (GIS)
Digital Map Software Market
Geographic Information Systems (GIS)
France Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
Asia Pacific Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
IP Geo-Location Services Market
Geographic Information Systems (GIS)
Satellite Image Data Services Market
Geographic Information Systems (GIS)
Mobile Mapping Market