
 India Software Services Export Market | 2026-2036
India Software Services Export Market Size, Share, and Industry Trends Forecast 2026-2036
India Software Services Export Market Insights
Artificial intelligence is realigning the talent economics of software delivery, as traditional coding workflows yield to machine-augmented development. Tata Consultancy Services Limited leverages its global delivery network to anchor large-scale transformation programs for Fortune 500 clients. Infosys Limited differentiates through its in-house AI platforms that automate testing and maintenance workflows. Wipro Limited competes on cloud-native engineering capabilities, sustaining margins in a commoditizing application services landscape.
India Software Services Export encompasses the cross-border provision of information technology and business process services by Indian vendors, spanning consulting, system integration, application development, IT support, and managed infrastructure operations delivered through onshore, offshore, and hybrid engagement models. The primary commercial purpose is to reduce client cost structures while accelerating digital transformation timelines for enterprises, governments, and technology firms across buyer geographies. Application development and cloud computing segments command the deepest margin pools, as clients prioritize modernization over maintenance spend. Offshore delivery retains volume leadership, though hybrid models are capturing the fastest expansion as data residency requirements fragment execution geography.
India's Ministry of Electronics and Information Technology (MeitY), the Reserve Bank of India (RBI), and SEBI collectively shape export demand through data localization guidelines, cross-border payment frameworks, and fintech outsourcing norms that determine where Indian vendors can host and process client information. The Digital Personal Data Protection Act and forthcoming sector-specific regulations are tightening compliance obligations, filtering vendor eligibility by certification grade and audit transparency. Stakeholders must monitor how evolving data sovereignty rules in client jurisdictions reshape delivery model economics and contract structuring.
Market Dynamics
Machine-augmented development workflows are compressing delivery timelines and flattening talent hierarchies across Indian software export operations. Generative coding tools now handle routine module construction, forcing vendors to restructure engagement economics around architecture and integration expertise rather than headcount scale.
Growth Catalysts
- Digital India Initiative:MeitY's infrastructure investments expand domestic cloud capacity, reducing latency for hybrid delivery models serving North American BFSI clients.
- Cloud Migration Surge:European enterprises accelerate legacy modernization, creating sustained demand for Indian vendors with platform-specific engineering certifications.
- PLI Scheme for IT Hardware:Domestic server and component manufacturing incentives strengthen end-to-end solution bundling capabilities for export contracts.
Market Restraints
- Data Localization Mandates:RBI's cross-border payment processing rules and SEBI's fintech outsourcing norms fragment execution geography, raising compliance overhead.
- Talent Cost Inflation:AI-augmented development skills command premium compensation, squeezing margin structures in commoditized application maintenance segments.
- Geopolitical Fragmentation:Divergent data sovereignty regimes across client jurisdictions force redundant infrastructure investments.
Strategic Opportunities
- GCC Expansion in Tier-2 Cities:Underpenetrated delivery centers in Kochi, Indore, and Bhubaneswar offer cost arbitrage beneath saturated Bengaluru and Hyderabad markets.
- AI Platform Monetization:Proprietary automation frameworks for testing and maintenance workflows create recurring revenue streams distinct from time-and-material contracts.
- Digital Personal Data Protection Act:Compliance certification requirements filter vendor eligibility, creating competitive moats for audit-transparent operators.
Industry Challenges
- Prompt Engineering Talent Gap:Shortage of professionals capable of architecting effective human-AI collaboration workflows in production environments.
- Legacy System Integration Complexity:Mainframe and on-premise ERP environments resist cloud-native refactoring, extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Software Services Export Market |
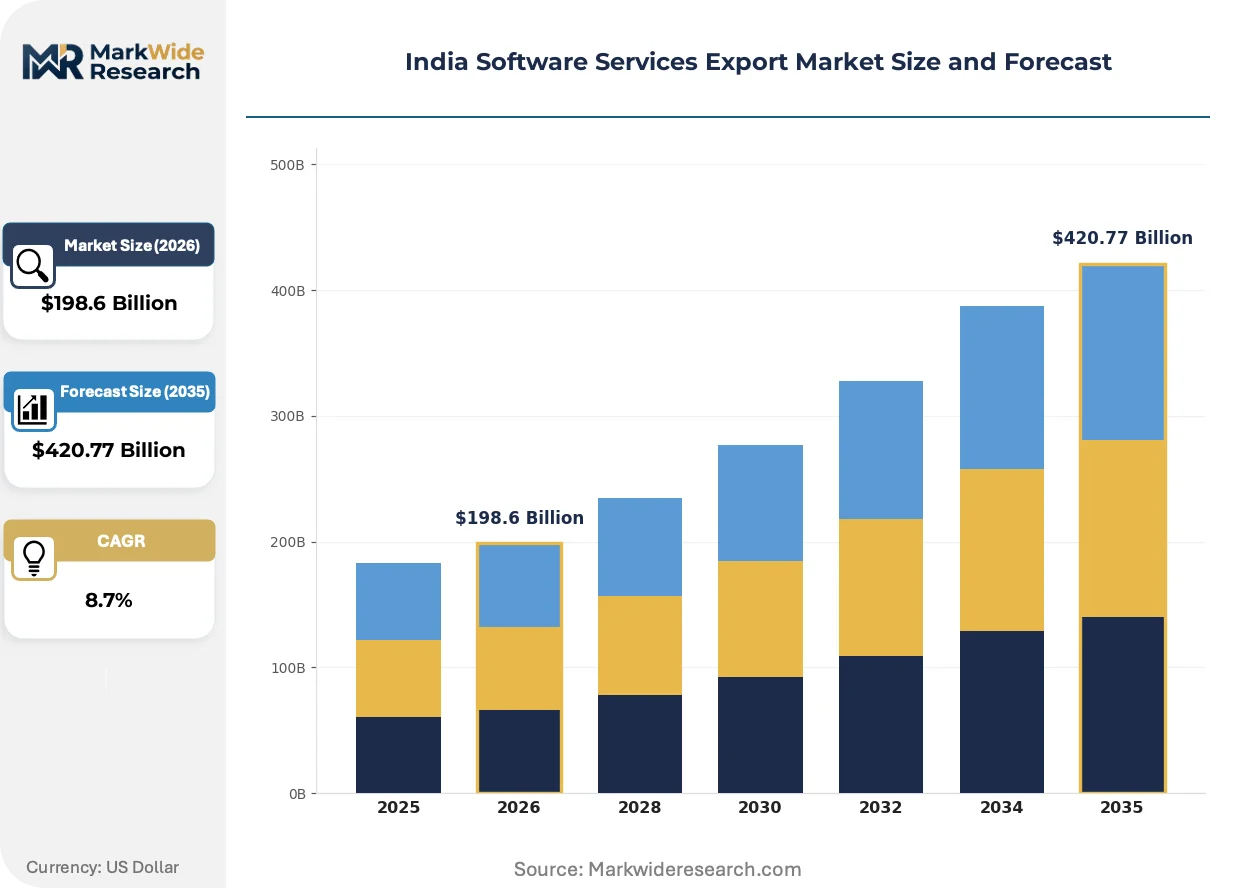
| Market Size in 2026 | $198.6 Billion |
| Market Size in 2035 | $420.77 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, System Integration, Application Development, IT Support Client Type: Small Enterprises, Medium Enterprises, Large Enterprises, Government Delivery Model: Onshore, Offshore, Hybrid, Managed Services Technology: Cloud Computing, Artificial Intelligence, Data Analytics, Cybersecurity |
| Companies Covered | Tata Consultancy Services Limited, Infosys Limited, Wipro Limited, HCL Technologies, Tech Mahindra Ltd, LTIMindtree, Cognizant Technology Solutions, Mphasis, Persistent Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Software Services Export Market Trends and Innovations
Generative AI is restructuring how Indian vendors package and price intellectual labor, separating routine execution from high-margin architecture services. Delivery models are fragmenting as data residency requirements multiply.
Agentic AI systems capable of autonomous debugging and code generation are electrifying traditional software delivery economics. Mid-market BFSI clients in North America deploy these tools for rapid prototype development. This compression of initial build phases is forcing Indian vendors to front-load consulting revenue and reduce dependency on maintenance retainers.
India's Digital Personal Data Protection Act imposes consent-layer obligations on cross-border data flows. Processing agreements now require explicit audit trails for client information handling. Export-oriented vendors are restructuring contracts to accommodate these compliance checkpoints, particularly affecting healthcare and financial services verticals.
Enterprise buyers are unbundling transformation programs into discrete outcome milestones rather than monolithic multi-year engagements. Fixed-scope sprints with defined deliverables replace traditional time-and-material arrangements. This pattern is most pronounced among Fortune 500 manufacturing clients restructuring supply chain software portfolios.
India Software Services Export Market Segmentation
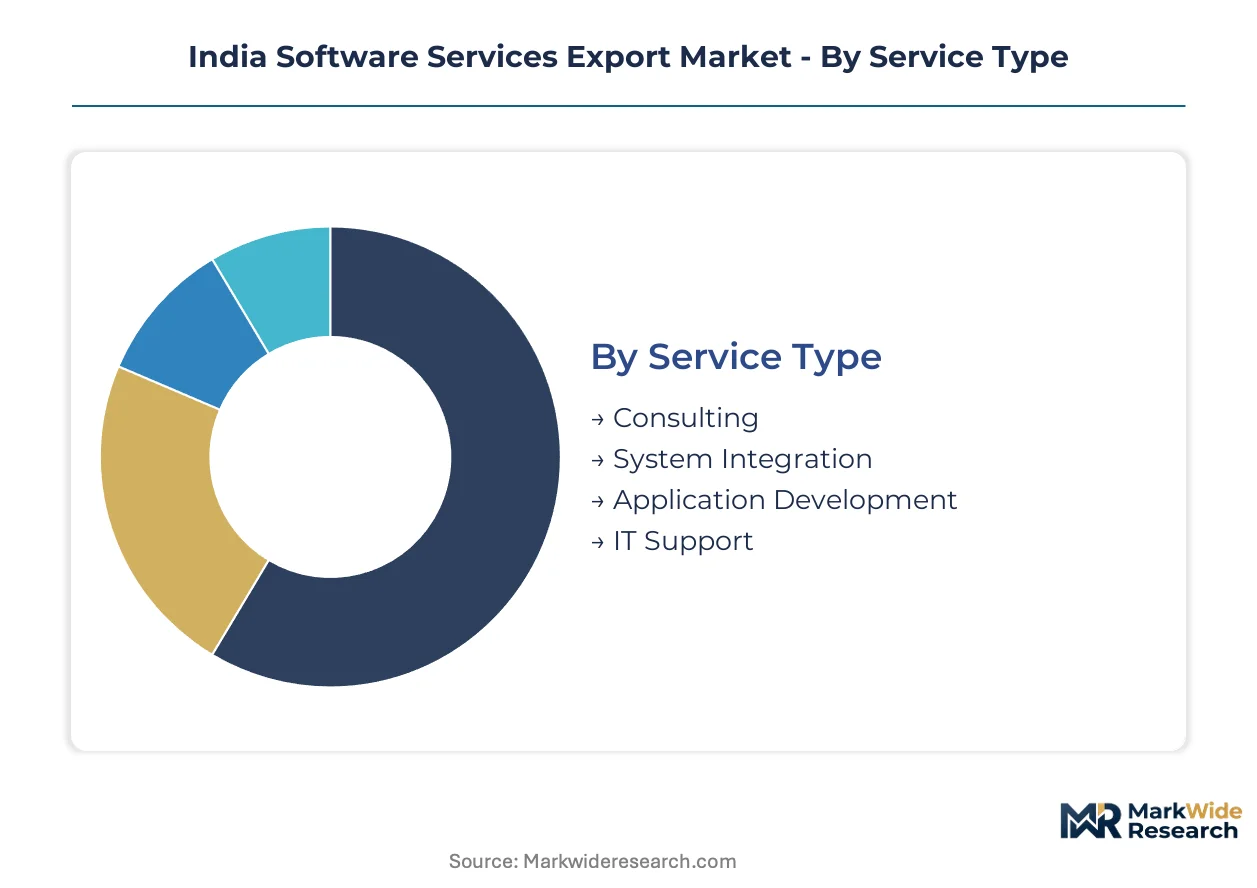
Segmentation reveals how Indian vendors structure pricing and resource allocation across divergent client requirements. Service complexity, delivery geography, and technology intensity fragment contract economics into distinct margin tiers.
Service Type:
Client budget authority and transformation maturity determine which service layers capture procurement spend.
- Application Development:Custom software engineering spans legacy modernization and greenfield builds. North American BFSI enterprises concentrate procurement here, prioritizing cloud-native architectures over maintenance-heavy engagements.
- System Integration:Enterprise application stitching demands certified platform expertise. European manufacturing clients drive demand for SAP and Salesforce integration as they consolidate fragmented ERP estates.
- Consulting:Advisory services around digital strategy and process reengineering. Large enterprises commission these engagements to define scope before execution contracts.
- IT Support:Maintenance and helpdesk operations for deployed infrastructure. Government contracts favor this segment for cost containment.
Volume sits with Application Development; growth tilts toward System Integration.
Client Type:
Contract scale and sales cycle duration segment vendor economics across buyer organizational profiles.
- Large Enterprises:Fortune 500 and multinational corporations with multi-year transformation mandates. These clients concentrate spend in hybrid delivery models requiring data residency compliance.
- Medium Enterprises:Mid-market firms accelerating digital adoption without captive IT capacity. Cloud migration and AI-augmented development services expand most quickly here.
- Government:Public sector entities with procurement transparency requirements and domestic delivery preferences. Indian state governments and central ministries anchor this demand.
- Small Enterprises:Startups and growth-stage companies purchasing discrete project scopes. Price sensitivity limits engagement duration and technology depth.
Revenue concentrates with Large Enterprises; expansion tilts toward Medium Enterprises.
Delivery Model:
Data sovereignty obligations and collaboration intensity reshape where execution occurs.
- Offshore:India-based delivery centers handling majority of development and support workloads. Cost arbitrage sustains this model for non-regulated workloads.
- Hybrid:Split execution between Indian centers and client geography for compliance-sensitive operations. RBI data localization guidelines and EU GDPR requirements accelerate this configuration.
- Onshore:Client-country delivery teams for real-time collaboration and regulated data handling. Premium pricing reflects talent cost differentials.
- Managed Services:Outcome-based contracts with vendor assumption of operational risk. Long-term engagements with defined SLAs dominate this structure.
Volume sits with Offshore; growth tilts toward Hybrid.
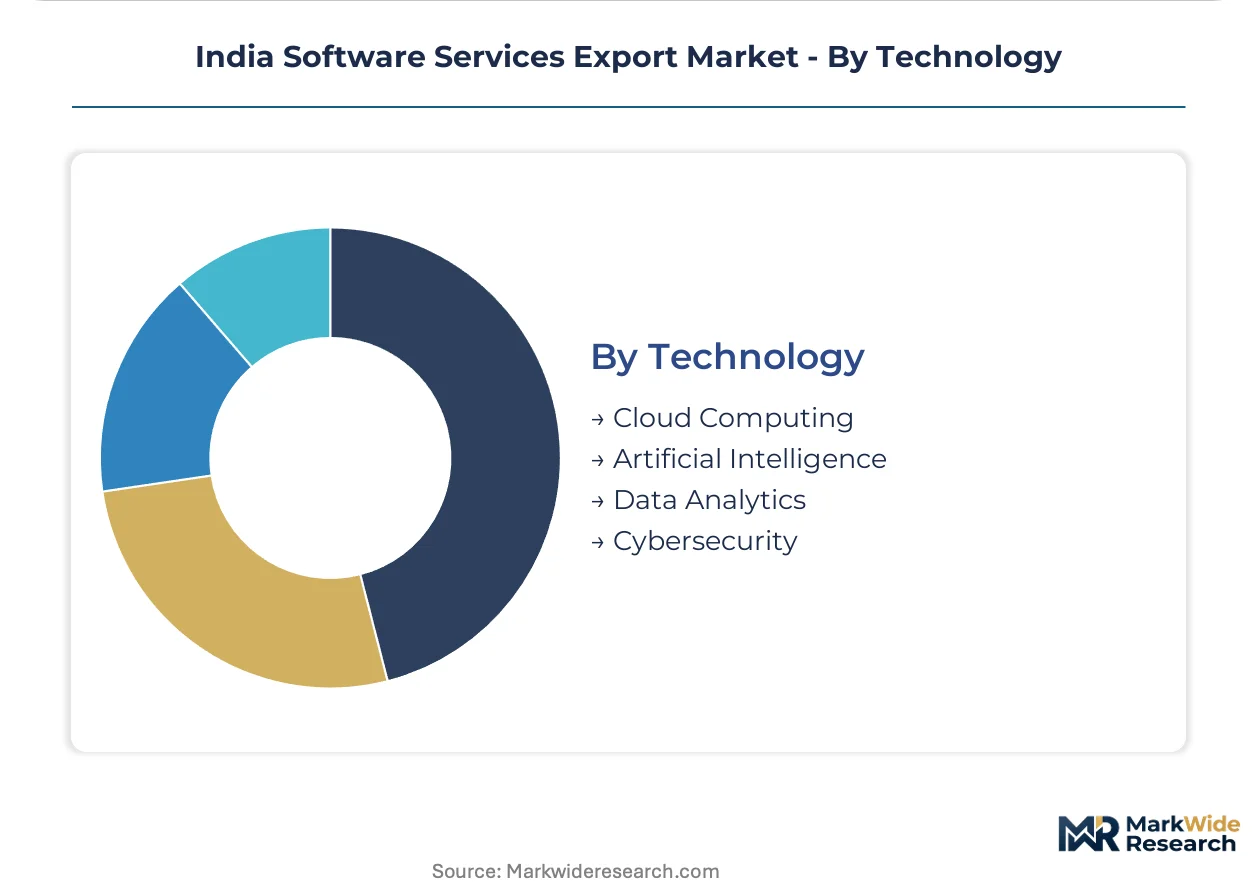
Technology:
Platform certification requirements and talent scarcity stratify vendor capabilities.
- Cloud Computing:Migration, modernization, and native development across AWS, Azure, and GCP. European enterprise demand concentrates here as legacy infrastructure reaches end-of-life.
- Artificial Intelligence:Machine learning operations, generative AI integration, and agentic system deployment. North American BFSI clients commission rapid prototype development in this layer.
- Cybersecurity:Security operations, compliance auditing, and threat management services. Digital Personal Data Protection Act obligations expand this segment for cross-border contracts.
- Data Analytics:Business intelligence, predictive modeling, and visualization implementations. Manufacturing supply chain optimization drives specific demand.
Revenue concentrates with Cloud Computing; expansion tilts toward Artificial Intelligence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Karnataka and Telangana concentrate software export operations through tax holidays and infrastructure subsidies. These zones anchor delivery centers serving North American and European clients.
United States
Fortune 500 BFSI enterprises commission large-scale transformation programs from Indian vendors. SEC disclosure requirements and state-level data privacy laws like CCPA fragment contract structuring. Delivery partnerships concentrate in New Jersey and Texas corridors where client proximity enables hybrid execution.
United Kingdom
Financial services firms in London accelerate cloud migration post-Brexit regulatory recalibration. FCA outsourcing guidelines and GDPR alignment requirements shape vendor selection criteria. Indian delivery centers in Manchester and Edinburgh expand to meet data residency preferences.
Germany
Industrial manufacturing clients drive demand for SAP integration and IoT platform development. BSI cybersecurity certification and EU AI Act compliance obligations filter vendor eligibility. Frankfurt's fintech cluster sources specialized engineering talent from Indian partners.
France
Luxury goods conglomerates and aerospace suppliers pursue digital supply chain modernization. ANSSI cybersecurity frameworks and CNIL data protection enforcement raise compliance thresholds. Paris-based procurement teams favor vendors with French-speaking delivery capabilities.
Singapore
Southeast Asian headquarters of multinational corporations route regional IT spend through Indian vendors. MAS fintech regulations and cross-border data flow agreements facilitate hub-and-spoke delivery models. Marina Bay financial district anchors client decision-making for regional contracts.
India Software Services Export Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-service IT vendors capturing transformation budgets while niche players secure platform-specific maintenance. The vendor base organizes into three tiers: global scale operators with multi-industry delivery networks, mid-cap specialists with vertical certifications, and emerging firms competing on cost. Strategic moves concentrate on AI platform development and GCC expansion into Tier-2 Indian cities.
Within the scale-driven tier, Tata Consultancy Services Limited, Infosys Limited, and Wipro Limited occupy positions defined by global delivery network breadth. These entities exemplify the transition from headcount-based pricing to outcome-oriented engagement models. Their market presence reflects decades of Fortune 500 relationship depth and platform certification accumulation.
| Leading Market Players |
|---|
| Tata Consultancy Services Limited |
| Infosys Limited |
| Wipro Limited |
| HCL Technologies |
| Tech Mahindra Ltd |
| LTIMindtree |
| Cognizant Technology Solutions |
| Mphasis |
| Persistent Systems |
| Others |
Pricing and Supply Chain Analysis
Captive delivery center networks in Karnataka and Telangana anchor both supply positioning and pricing power for Indian software exporters, concentrating high-certification talent pools that command premium rates in BFSI contracts. This geographic clustering enables tiered rate cards based on engineer seniority and platform specialization, while RBI data localization mandates fragment execution economics across hybrid delivery models.
Pricing Analysis
Volume concentrates in time-and-material application maintenance contracts with thinning margins, while margin pools shift toward fixed-scope transformation sprints and AI-augmented architecture engagements. Pricing stratifies across premium, standard, and economy tiers based on certification grade and data residency compliance level. Cost compression in commoditized maintenance tiers is intensifying because generative coding tools displace junior headcount. Small enterprises exhibit acute price sensitivity, whereas Fortune 500 BFSI clients prioritize audit transparency over rate negotiation.
Supply Chain Analysis
Workforce availability in Bengaluru, Hyderabad, and Pune feeds from tier-1 engineering institutes and specialized upskilling programs, with secondary pipelines emerging from Indore and Kochi. Talent supply draws from computer science graduates, platform-certified professionals, and prompt engineering specialists. Single-source vulnerability concentrates in cloud infrastructure dependencies on AWS, Azure, and GCP hyperscaler regions. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and GCC captive arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India Software Services Export Market operates as a supply-constrained environment where prompt engineering talent scarcity props pricing for AI-augmented delivery tiers.
For Market Incumbents: Anticipate margin compression in commoditized maintenance segments by accelerating proprietary AI platform monetization and securing audit-transparent certifications under the Digital Personal Data Protection Act. Capacity addition in underpenetrated Tier-2 cities defends cost position against emerging specialists.
For New Entrants and Emerging Players: Cloud-native consulting channels offer the most penetrable entry vector for mid-market European manufacturing clients seeking SAP integration without incumbent relationship overhead. Fixed-scope outcome contracts with defined deliverables bypass time-and-material scale disadvantages.
For Investors and Strategic Acquirers: Exit pathways concentrate in vertical AI platform specialists with recurring revenue streams distinct from headcount-dependent engagements. Acquisition targets with MeitY compliance certifications and GCC footprints in Tier-2 cities offer long-term viability. The signal to watch is RBI data localization rule expansion forcing hybrid delivery infrastructure investments.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Platform Monetization | Proprietary automation frameworks create recurring revenue distinct from time-and-material contracts. |
| GCC Expansion in Tier-2 Cities | Underpenetrated delivery centers in Kochi and Indore offer cost arbitrage beneath saturated Bengaluru markets. |
| Compliance Certification Investment | Digital Personal Data Protection Act audit transparency filters vendor eligibility, creating competitive moats. |
| Hybrid Delivery Infrastructure | RBI data localization guidelines fragment execution geography, requiring redundant capacity investments. |
| Strategic Partnership with Hyperscalers | AWS, Azure, and GCP platform certifications anchor cloud migration procurement decisions. |
Research Methodology
SEC filings, MeitY policy circulars, and RBI regulatory notifications formed the secondary backbone, supplemented by hyperscaler capex disclosures and trade association export statistics. Primary interviews with CTOs at North American BFSI enterprises, IT procurement officers at European manufacturers, platform engineers at Indian delivery centers, and channel partners in Singapore informed demand-side validation. Bottom-up and top-down triangulation reconciled contract value estimates with aggregate export revenue flows.
Bottom-up modeling segmented the market across service type, client organization size, delivery model configuration, and technology intensity, while top-down analysis anchored aggregate projections to official export statistics. CAGRs were derived from trend extrapolation of segment-specific growth rates across the analysis window, incorporating AI adoption curves and cloud migration timelines as software-specific forecast inputs.
The model holds under stable regulatory enforcement of data localization guidelines; deviation in RBI cross-border payment rules or EU AI Act compliance timelines would shift delivery model economics. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Full Screen Website Screenshot Software Market
Software & Services
Application Platform As a Service Market
Software & Services
Global Screen and Script Writing Software Market
Software & Services
Global Healthcare Contract Management Software Market
Software & Services
Global Gym Software Market
Software & Services
Mind Mapping Software Market
Software & Services
Global Reporting Software Market
Software & Services
Construction Estimating Software Market
Software & Services
Deck Design Software Market
Software & Services
Digital Sculpture Software Market
Software & Services
Europe Digital Signage Software Market
Software & Services
Saas-Based Expense Management Market
Software & Services
Europe Drone Software Market
Software & Services
RIP Color Management Software Market
Software & Services
Decision Support System (DSS) Software Market
Software & Services
Global Online Form Builder Software Market