
 Global Metadata Management Tools Market | 2026-2036
Global Metadata Management Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metadata Management Tools Market Foresight
Multi-source procurement of metadata platforms is hardening as enterprises diversify vendor relationships to reduce lock-in risk. IBM leverages its hybrid cloud footprint to anchor large financial services contracts. Oracle competes through deep database integration that sustains renewal rates in existing accounts. Collibra specializes in business-friendly data cataloging interfaces that differentiate its offering from technically oriented rivals.
Metadata management tools govern the discovery, classification, lineage tracking, and quality monitoring of data assets across distributed systems through automated harvesting engines and semantic layer construction. These platforms parse schema definitions, business glossaries, and transformation logic to create searchable inventories that accelerate analytics pipeline development and regulatory audit response. Cloud-based deployment leads solution type adoption as organizations retire fixed-capacity data centers, while subscription-based pricing captures the fastest-growing revenue pool by aligning vendor incentives with customer consumption patterns. Data governance and data lineage modules concentrate margin contribution due to their direct mapping onto mandatory compliance workflows in regulated industries.
FDA 21 CFR Part 11 requirements for electronic records integrity shape validation protocols that metadata tools must satisfy in pharmaceutical manufacturing environments. EBA guidelines on data aggregation and risk reporting, alongside GDPR Article 30 records of processing obligations, compel European banks and insurers to invest in automated lineage documentation. ISO 8000 data quality standards and IEC 27001 security frameworks further constrain product architecture decisions for vendors seeking cross-border certification. Stakeholders must weigh interoperability commitments against the accelerating fragmentation of cloud provider-native metadata services.
Market Dynamics
Cloud-native metadata architectures are compressing deployment cycles from months to weeks, forcing incumbent vendors to rearchitect legacy platforms or cede enterprise contracts to agile competitors. This structural acceleration is tightening the link between data governance investment and regulatory audit readiness across financial services and life sciences.
Growth Catalysts
- BCBS 239 lineage mandates:Basel Committee standards compel global banks to maintain end-to-end data provenance documentation, driving automated metadata harvesting adoption in London, Frankfurt, and New York trading hubs.
- AI-ready data infrastructure:Enterprise machine learning pipelines require semantic layer consistency that only governed metadata repositories can provide, accelerating procurement in pharmaceutical and insurance sectors.
- Germany:Bundesbank supervisory expectations on risk data aggregation are forcing domestic lenders to replace spreadsheet-based lineage tracking with enterprise-grade platforms.
Market Restraints
- Specialized engineering talent scarcity:Shortage of professionals combining data engineering expertise with regulatory domain knowledge inflates implementation costs and extends deployment timelines.
- Cloud provider service bundling:AWS Glue Data Catalog, Azure Purview, and Google Cloud Data Catalog create native ecosystem lock-in that constrains independent software vendor pricing power.
- Schema standardization fragmentation:Competing industry-specific metadata models (HL7 FHIR in healthcare, FIX in trading, ISO 20022 in payments) multiply integration complexity and maintenance overhead.
Strategic Opportunities
- India:RBI data localization guidelines and SEBI reporting modernization are creating first-mover advantage for vendors establishing compliant cloud regions in Mumbai and Hyderabad.
- Real-time lineage streaming:Apache Kafka and change-data-capture integration enables continuous metadata refresh, opening subscription revenue streams distinct from batch-oriented legacy pricing.
- EU AI Act documentation requirements:High-risk AI system operators must maintain training data provenance records, expanding addressable market beyond traditional regulated industries into manufacturing and logistics.
Industry Challenges
- Mainframe metadata extraction:COBOL copybooks and IMS hierarchies in core banking systems resist automated parsing, requiring costly manual remediation or risky abstraction-layer investments.
- Cross-functional alignment friction:Metadata initiatives stall when IT engineering teams and business data stewards disagree on glossary authority and quality rule ownership.
- Version control at enterprise scale:Thousands of concurrent schema changes across distributed microservices overwhelm traditional governance workflows, demanding new operational models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metadata Management Tools Market |
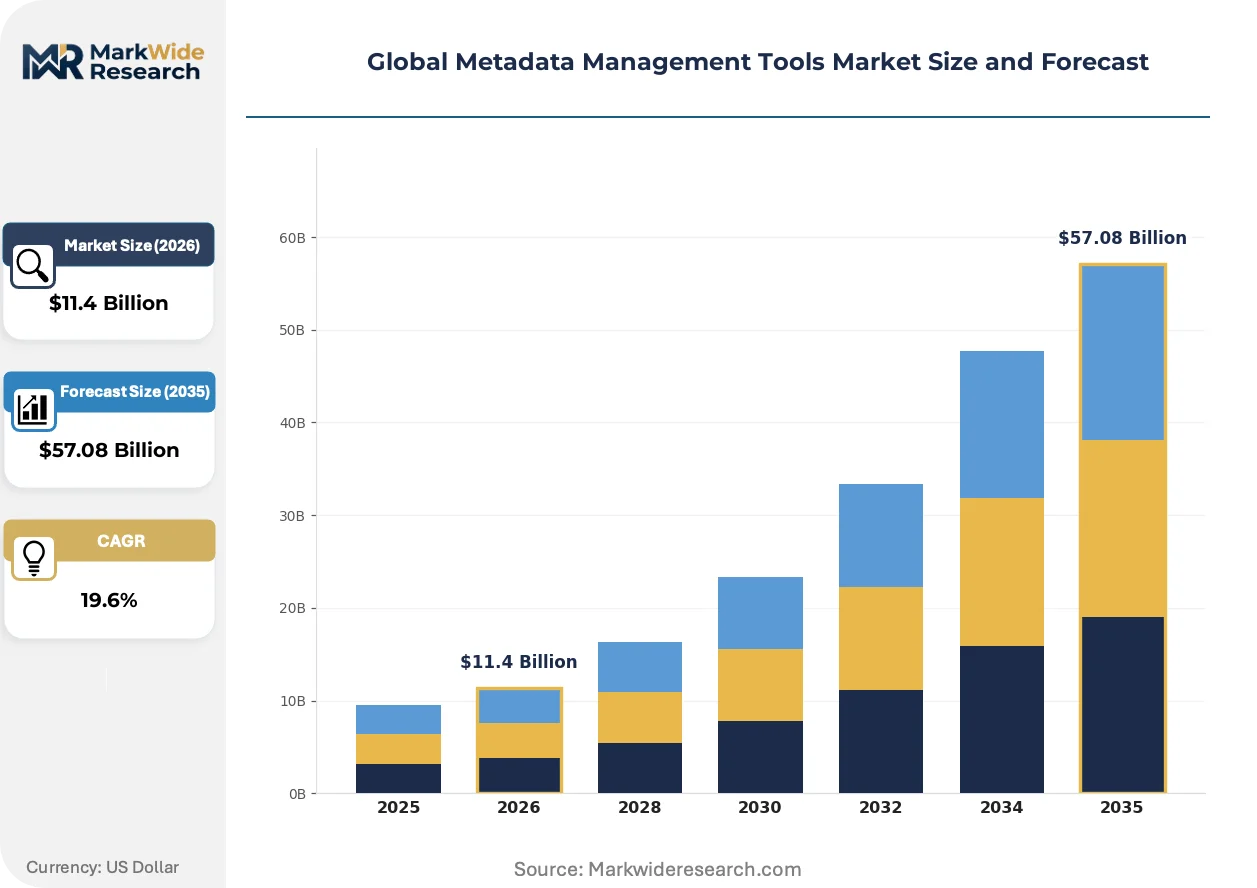
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $57.08 Billion |
| CAGR (2026 – 2036) | 19.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Cloud Solution Type: Data Governance, Data Integration, Data Cataloging, Data Quality, Data Lineage End User Industry: Information Technology, Telecommunications, Banking, Transportation, Media & Entertainment Pricing Model: Subscription-Based, Perpetual License, Usage-Based, Freemium |
| Companies Covered | IBM, Oracle, Microsoft, SAP, Collibra, Informatica, ASG Technologies, Adaptive, Alation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metadata Management Tools Market Shifts & Advancements
Active metadata—systems that not only catalog but automatically recommend, classify, and remediate—is displacing passive repository models. This shift redefines vendor differentiation around intelligence depth rather than ingestion breadth.
Knowledge graph technology is integrating entity-relationship inference engines with traditional metadata stores. Financial services firms in Switzerland and Singapore are deploying these hybrid architectures to uncover hidden data dependencies for stress testing. The technology is compressing time-to-insight for lineage queries from hours to seconds, reshaping competitive benchmarks for platform responsiveness.
GDPR Article 30 records-of-processing obligations are hardening documentation requirements for automated decision systems. European insurers and French healthcare providers must now maintain machine-readable processing inventories that regulators can query directly. This policy shift is forcing vendors to embed compliance-as-code features that generate audit artifacts without manual curation.
Consumption-based pricing models are replacing perpetual license structures in enterprise procurement. Buyers in United Kingdom banking and United States pharmaceutical sectors now prefer metered lineage tracking costs aligned to actual data asset volumes. This behavioral pivot is compressing vendor cash conversion cycles while aligning product roadmaps to customer expansion metrics rather than upfront deal size.
Global Metadata Management Tools Market Segmentation
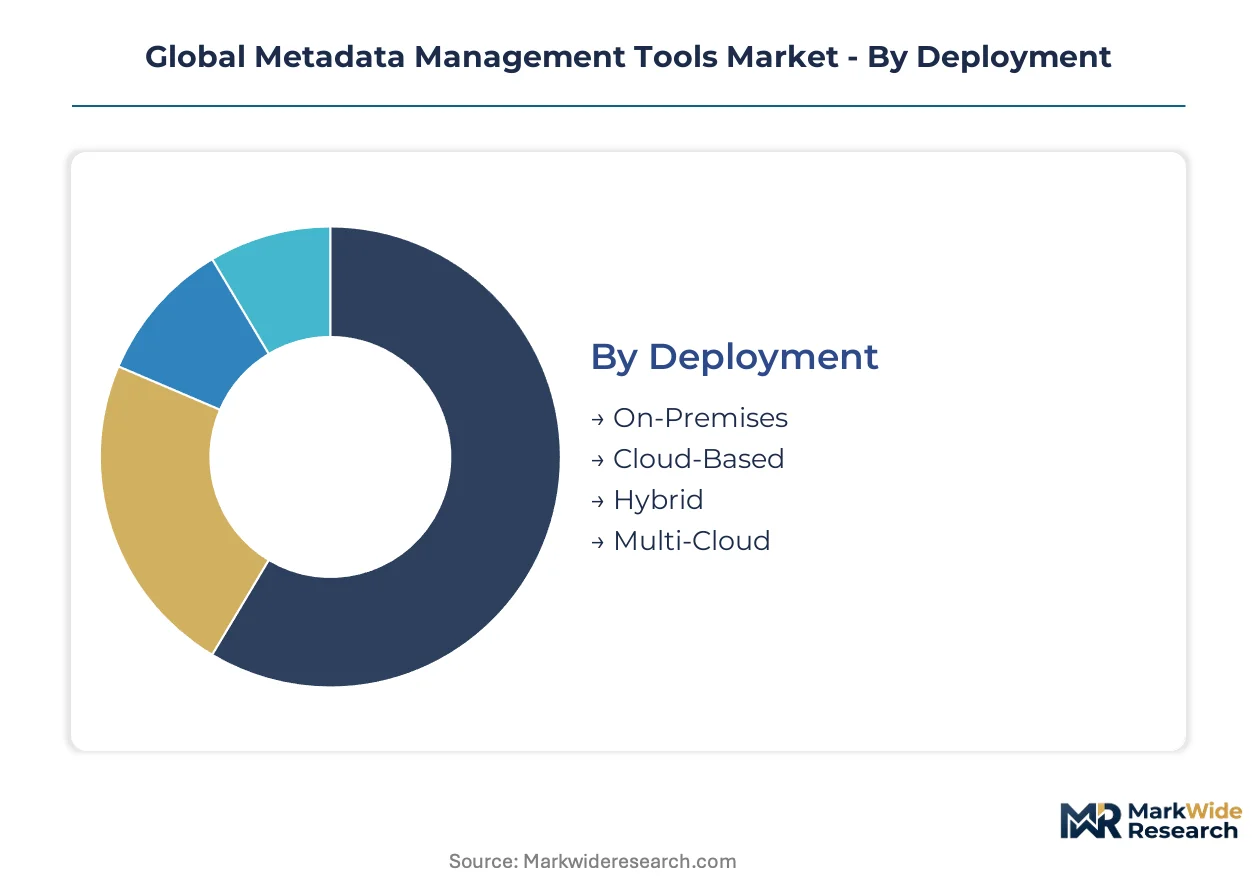
Metadata management tools segment across deployment architecture, functional capability, industry vertical, and commercial terms. Procurement teams weight these dimensions differently based on regulatory exposure, cloud maturity, and data estate complexity.
Deployment:
Architecture choice hinges on data residency mandates and legacy system entanglement.
- Cloud-Based:Fully managed SaaS platforms eliminate infrastructure overhead and compress provisioning from quarters to days. Demand clusters in United States fintech and United Kingdom neobanks where BCBS 239 audits favor elastic lineage scaling without capital commitment.
- Hybrid:Split architectures keep sensitive metadata on-premises while federating catalog access to cloud analytics. German automotive suppliers and Swiss private banks deploy this model to satisfy GDPR Article 30 localization while enabling cross-border collaboration.
- On-Premises:Air-gapped installations persist in defense contractors and classified government facilities with zero-trust cloud policies.
- Multi-Cloud:Abstraction layers prevent AWS Glue, Azure Purview, and Google Cloud Data Catalog lock-in by normalizing metadata across hyperscaler boundaries.
Volume sits with Cloud-Based; growth tilts toward Multi-Cloud as vendor diversification hardens.
Solution Type:
Functional module selection tracks compliance workflow integration depth.
- Data Lineage:Automated provenance mapping traces transformations from ingestion through consumption, generating audit artifacts for FDA 21 CFR Part 11 and EBA risk data aggregation guidelines. Financial services in New York and London trading floors prioritize this capability above all others.
- Data Governance:Policy enforcement engines embed business glossaries, quality rules, and access controls into metadata layers. European insurers under GDPR Article 30 and EU AI Act documentation mandates drive procurement here.
- Data Cataloging:Searchable inventories accelerate analytics discovery for data science teams in pharmaceutical R&D.
- Data Quality:Profiling and remediation modules monitor schema drift and anomaly patterns in real-time streaming pipelines.
- Data Integration:Metadata-driven ETL orchestration harmonizes siloed sources for enterprise data mesh architectures.
Revenue concentrates in Data Lineage; expansion is steepest in Data Governance as AI documentation obligations proliferate.
End User Industry:
Vertical specialization determines schema complexity and regulatory density.
- Banking:Basel Committee BCBS 239 mandates force end-to-end data provenance documentation across trading, risk, and reporting systems. Frankfurt and Singapore hubs lead replacement of spreadsheet lineage with enterprise platforms.
- Information Technology:SaaS providers and cloud-native enterprises deploy metadata to govern microservice data contracts and API versioning at scale.
- Telecommunications:Subscriber data portability regulations and 5G network slicing drive metadata investments in spectrum management and customer journey analytics.
- Transportation:Logistics operators track shipment provenance and carbon footprint data for supply chain transparency mandates.
- Media & Entertainment:Content rights management and personalization engine governance shape metadata requirements for streaming platforms.
Banking dominates current spend; Information Technology is climbing fastest as platform engineering matures.
Pricing Model:
Commercial structure alignment shapes vendor cash flow and customer commitment horizons.
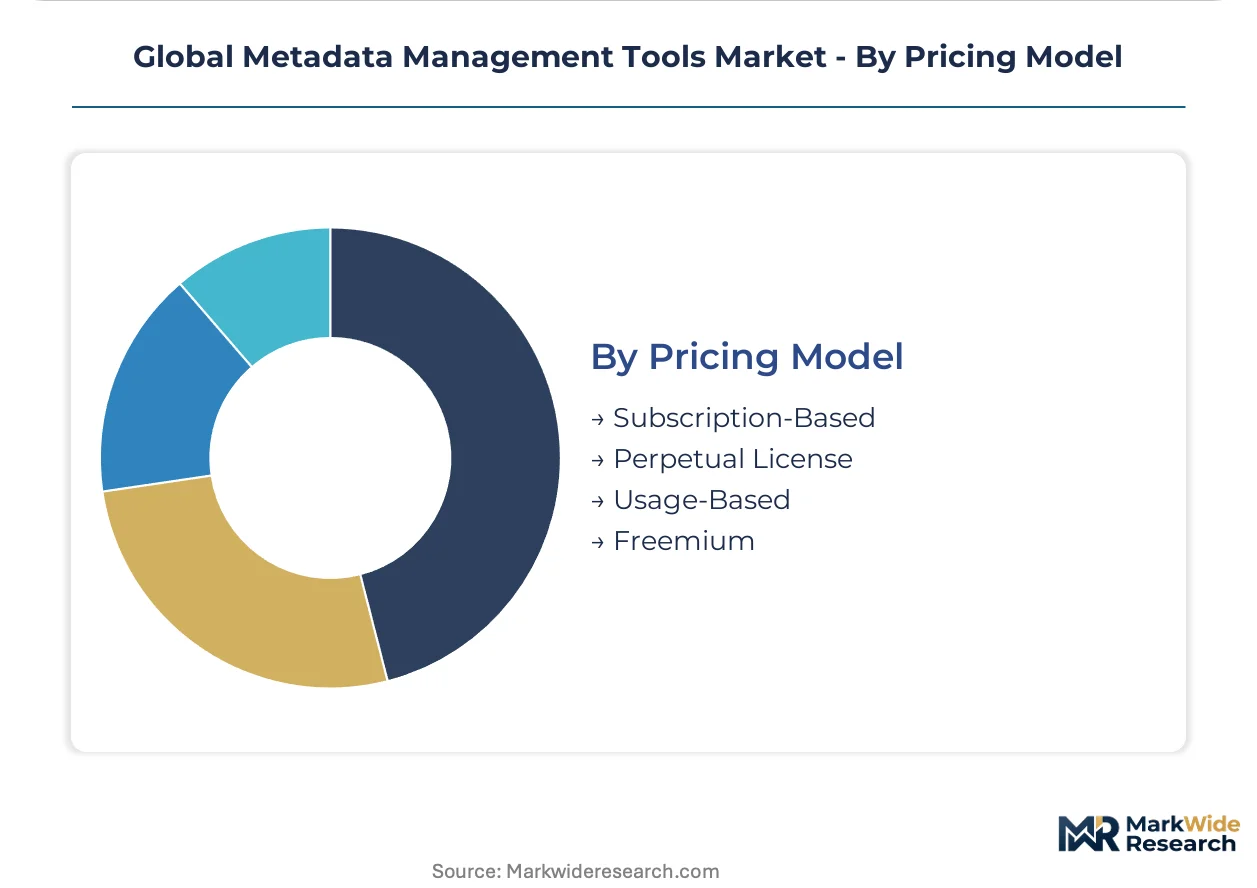
- Subscription-Based:Annual or multi-year recurring contracts align vendor incentives with customer expansion metrics. United States pharmaceutical and United Kingdom banking procurement teams prefer this predictability for budget planning.
- Usage-Based:Metered lineage tracking costs scale with actual data asset volumes and query intensity. Cloud-native adopters in India and Brazil favor this operational expenditure model.
- Perpetual License:One-time capital purchases with maintenance streams persist in regulated industries with lengthy procurement cycles and depreciation schedules.
- Freemium:Limited-feature entry tiers enable pilot deployments and developer community building before enterprise conversion.
Subscription-Based captures the largest revenue pool; Usage-Based is gaining share fastest as consumption economics displace upfront licensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial services firms in the United States, Germany, and the United Kingdom currently concentrate procurement of metadata management platforms due to intensifying regulatory scrutiny on data provenance documentation.
United States
BCBS 239 lineage mandates from the Basel Committee drive automated metadata harvesting adoption across New York trading floors. FDA 21 CFR Part 11 requirements for electronic records integrity shape validation protocols in pharmaceutical manufacturing environments. Boston and San Francisco fintech clusters favor cloud-native deployment models that compress provisioning timelines from quarters to days.
Germany
Bundesbank supervisory expectations on risk data aggregation compel domestic lenders to replace spreadsheet-based lineage tracking with enterprise-grade platforms. EBA guidelines on data aggregation and risk reporting enforce automated lineage documentation across Frankfurt banking hubs. Bavarian automotive suppliers deploy hybrid architectures to satisfy GDPR Article 30 localization while enabling cross-border collaboration.
United Kingdom
London trading floors prioritize data lineage capabilities above all other functional modules for regulatory audit readiness. GDPR Article 30 records-of-processing obligations harden documentation requirements for automated decision systems in insurance sectors. Edinburgh and Manchester neobanks prefer subscription-based pricing aligned to actual data asset volumes.
India
RBI data localization guidelines and SEBI reporting modernization create first-mover advantage for vendors establishing compliant cloud regions. BIS standards constrain product architecture decisions for cross-border certification seekers. Mumbai and Hyderabad financial centers favor usage-based operational expenditure models over upfront capital commitments.
Switzerland
Swiss private banks deploy hybrid metadata architectures to satisfy data residency mandates while federating catalog access. FINMA supervisory requirements on risk data aggregation parallel EBA guidelines in stringency. Zurich and Geneva financial services firms integrate knowledge graph technology to uncover hidden data dependencies for stress testing.
Global Metadata Management Tools Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbent vendors rearchitect legacy platforms to counter agile cloud-native competitors. The vendor base stratifies across three tiers: hyperscaler-integrated suites, specialized data governance platforms, and emerging AI-native entrants. Strategic archetypes include hybrid cloud anchors competing through infrastructure footprint, catalog specialists differentiating via business-friendly interfaces, and compliance-focused vendors embedding regulatory automation. M&A activity and cloud region expansion represent the dominant competitive moves reshaping market structure.
Within the hybrid cloud anchor tier, IBM leverages infrastructure breadth to secure large financial services contracts, while Oracle sustains renewal rates through deep database integration. Collibra occupies a distinct position exemplifying the catalog specialist archetype with business-oriented data governance interfaces. These three companies represent contrasting strategic postures: infrastructure leverage, database ecosystem lock-in, and user experience differentiation.
| Leading Market Players |
|---|
| IBM |
| Oracle |
| Microsoft |
| SAP |
| Collibra |
| Informatica |
| ASG Technologies |
| Adaptive |
| Alation |
| Others |
Supply & Pricing Matrix
BCBS 239 audit-ready procurement mandates from United States and European banking sectors are compressing vendor sales cycles and forcing platform providers to absorb implementation risk through outcome-based contracting. This demand-side pressure is reshaping how metadata management tools are priced and delivered, with subscription elasticity now tethered to proven lineage accuracy rather than seat counts.
Pricing Analysis
Volume concentrates in subscription-based SaaS tiers while margin contribution shifts toward usage-based lineage metering. Three-tier pricing structure across enterprise, mid-market, and developer entry levels differentiates by integration depth and governance module breadth. Cost compression in mid-market tiers is intensifying because cloud-native entrants are undercutting incumbent maintenance-heavy offerings. Neobanks and fintechs in London and Mumbai exhibit highest price sensitivity; Basel-regulated global banks in Frankfurt and New York prioritize audit reliability over per-seat economics.
Supply Chain Analysis
Single-source vulnerability sits with hyperscaler-native catalog services from AWS, Microsoft Azure, and Google Cloud Platform that dominate downstream distribution. Engineering talent for semantic layer construction draws from India, Poland, and the United States, creating geographic concentration in implementation capacity. Supply chain risk centers on regulatory restriction: data localization mandates in India and Switzerland fragment cloud region availability and inflate compliance overhead. Distribution runs through direct enterprise sales teams and systems integrator partnerships with Accenture, Deloitte, and boutique data governance consultancies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized engineering talent scarcity—particularly professionals bridging data engineering and regulatory domain expertise—props pricing power for vendors with proven implementation track records. This supply constraint insulates premium tiers from commoditization pressure.
For Market Incumbents: Anticipate displacement by AI-native metadata platforms through accelerated investment in automated classification and recommendation engines. Defensive consolidation should prioritize acquisition of knowledge graph specialists in Switzerland and Singapore to anchor financial services stress-testing workflows. Certification investment in ISO 8000 and IEC 27001 frameworks preserves cross-border contract eligibility. For New Entrants and Emerging Players: Launch via usage-based pricing models targeting Indian financial centers where RBI localization guidelines have delayed hyperscaler dominance. White-space concentration exists in real-time lineage streaming for Apache Kafka environments and EU AI Act documentation automation for manufacturing sector AI operators. Go-to-market should emphasize consumption economics aligned to actual data asset volumes rather than upfront enterprise licensing. For Investors and Strategic Acquirers: The window for entry favors catalog specialists with business-friendly interfaces over infrastructure-heavy hybrid cloud anchors. Long-term viability hinges on embedding compliance-as-code features that generate audit artifacts without manual curation. The inflection signal to watch is contraction in perpetual license revenue share as subscription and usage-based models displace capital expenditure procurement patterns.| Strategic Initiative | Industry Significance |
|---|---|
| Knowledge Graph Integration | Swiss and Singaporean banks deploy hybrid architectures to compress lineage query response from hours to seconds. |
| Compliance-as-Code Embedding | GDPR Article 30 and EU AI Act mandates force automated audit artifact generation without manual curation. |
| Multi-Cloud Abstraction Layer | Prevention of AWS Glue, Azure Purview, and Google Cloud Data Catalog lock-in preserves vendor pricing power. |
| Real-Time Lineage Streaming | Apache Kafka and change-data-capture integration enables continuous metadata refresh distinct from batch pricing. |
| Cloud Region Expansion | Mumbai and Hyderabad compliant infrastructure addresses RBI data localization and SEBI reporting modernization. |
Research Methodology
Independent corroboration across primary interviews with chief data officers, enterprise architects, regulatory compliance leads, and systems integration specialists underwrites the qualitative findings. Secondary validation draws from SEC 10-K filings, hyperscaler capex disclosures, EBA guideline documentation, and FDA 21 CFR Part 11 validation protocols. Bottom-up sizing of deployment models and solution types triangulates against top-down regulatory mandate coverage estimates across banking, pharmaceutical, and insurance verticals.
Comparable-period anchoring to historical cloud migration cycles and BCBS 239 implementation timelines structures the projection horizon. The analytical framework models deployment architecture, functional capability, end-user industry, and pricing model dimensions alongside regional adoption pattern intensity. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion constraints. Forecast inputs include cloud-native platform penetration curves and regulatory deadline clustering effects in European and Indian financial centers.
Regulatory deadline delays, hyperscaler service bundling intensification, and schema standardization fragmentation are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about procurement team preference shifts and vendor competitive response timing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Data Enrichment Solutions Market
Digital Solutions
Global User Experience (UX) Market
Digital Solutions
Enterprise Asset Management (EAM) Market
Digital Solutions
Data Analytics in the Smart Home Market
Digital Solutions
Service Orchestration Market
Digital Solutions
Europe Warranty Management System Market
Digital Solutions
Marketing Automation Market
Digital Solutions
On-Demand Warehousing Platforms Market
Digital Solutions
Service Virtualization Market
Digital Solutions
Global Photo Management Software Market
Digital Solutions
Customer-To-Customer (C2C) Community Market
Digital Solutions
North America Online Dating Services Market
Digital Solutions
Mobile Engagement Market
Digital Solutions
Warranty Management System Market
Digital Solutions
Ticketing Solution Market
Digital Solutions
Public Relations (PR) Tools Market