
 Global AI Writing Assistant Software Market | 2026-2036
Global AI Writing Assistant Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global AI Writing Assistant Software Market Foresight
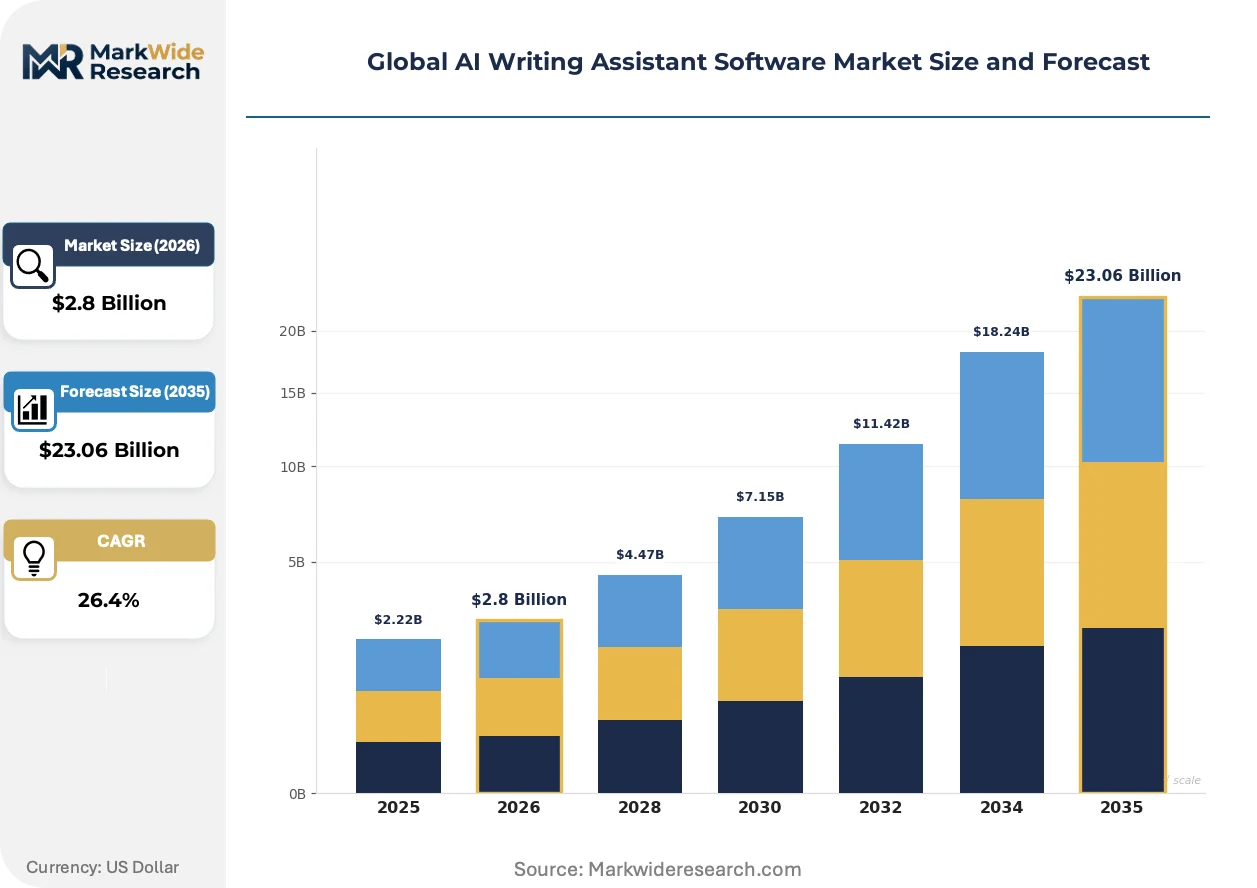
Enterprise marketing teams are rebalancing their software procurement toward cloud-based content generation suites. Grammarly sustains brand strength in real-time grammar correction for corporate communications. Jasper leverages vertical integration into proprietary large language model training for marketing copy.
AI writing assistant software deploys natural language processing models, transformer architectures, and reinforcement learning from human feedback to generate, edit, or refine text across commercial and educational contexts. Cloud-based deployment dominates current infrastructure choices due to elastic scaling and lower upfront capital requirements, while content generation solutions capture expanding margin pools as enterprises automate blog posts, ad copy, and technical documentation. Grammar checking remains the most mature solution offering with established pricing power.
The EU AI Act imposes transparency obligations on providers of general-purpose AI systems that generate text, reshaping product roadmaps for vendors serving European marketing agencies and publishing houses. The United States lacks comprehensive federal AI legislation, though the FTC applies existing consumer protection statutes to deceptive automated content practices. Stakeholders must monitor diverging regulatory trajectories across jurisdictions when allocating compliance resources and localization investments.
Market Dynamics
Transformer-based large language models are compressing content production cycles across enterprise marketing functions, forcing vendors to rearchitect pricing and deployment models around inference costs rather than seat-based subscriptions.
Growth Catalysts
- EU AI Act transparency mandates:Automated text disclosure requirements are accelerating procurement of auditable AI writing platforms among European publishing houses and advertising agencies seeking compliance-ready tooling.
- Cloud infrastructure elasticity:GPU-as-a-service provisioning from hyperscalers is lowering capital barriers for mid-market SaaS vendors to train and deploy proprietary models without captive data center investments.
- Technical documentation automation:DevOps teams at software companies are integrating API-first writing assistants into CI/CD pipelines to auto-generate release notes and SDK documentation at deployment velocity.
Market Restraints
- Inference cost volatility:Spot pricing fluctuations for NVIDIA H100 clusters are squeezing gross margins for vendors without long-term cloud compute commitments or in-house training infrastructure.
- Training data licensing friction:Copyright disputes over web-scraped corpora are creating legal exposure for model providers in jurisdictions with strong fair use limitations, particularly Germany and France.
- Human-in-the-loop persistence:Enterprise legal and compliance departments mandate editorial review workflows that prevent full automation, capping efficiency gains and elongating sales cycles.
Strategic Opportunities
- Japan's aging workforce:Knowledge management automation demand from Japanese insurers and banks is outpacing domestic NLP vendor capacity, creating entry points for multilingual model providers.
- Healthcare regulatory writing:FDA eCTD submission requirements are driving pharmaceutical sponsors toward AI-assisted clinical study report generation with embedded audit trails.
- Multimodal convergence:Text-to-image and text-to-video orchestration is opening creative production suites where writing assistants anchor cross-format campaign workflows.
Industry Challenges
- Prompt engineering talent scarcity:Vendors compete for practitioners capable of optimizing few-shot learning performance across domain-specific fine-tuning pipelines.
- Legacy CMS integration complexity:Enterprise content management stacks from Adobe and Oracle require custom middleware development, inflating implementation timelines and professional services dependency.
- Output hallucination liability:Factual errors in generated financial or medical content expose enterprise customers to regulatory enforcement and reputational damage, demanding costly guardrail investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global AI Writing Assistant Software Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $23.06 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Solution Offering: Grammar Checking, Content Generation, Style Improvement, Plagiarism Detection, Summarization, Translation Use Case: Content Marketing, Academic Writing, Legal Drafting, Technical Documentation, Social Media Management, Customer Support End User: Publishing Houses, Freelancers, Educational Institutions, Legal Firms, Corporate Communications, Marketing Agencies |
| Companies Covered | Copy.ai, Anyword, Jasper, Claude, QuillBot, Grammarly, Writesonic, Surfer, ChatGPT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global AI Writing Assistant Software Market Shifts & Advancements
Reinforcement learning from human feedback is rewriting how writing assistants align outputs with brand voice and factual accuracy, compressing the gap between generic model behavior and enterprise-grade reliability requirements.
Retrieval-augmented generation architectures are automating factual grounding by querying proprietary knowledge bases before text synthesis. Enterprise legal departments at US financial institutions are piloting these systems for contract drafting. The technology is automating the reduction of hallucination rates in high-stakes documentation without requiring full model retraining on sensitive corpora.
The EU AI Act's risk-based classification system is forcing providers of general-purpose text generators to implement systemic transparency measures. Vendors must document training data provenance and enable downstream users to identify AI-generated content. European marketing agencies are demanding these capabilities as procurement prerequisites, reshaping product roadmaps for US and Asian software firms.
Subscription fatigue among mid-market content teams is accelerating experimentation with consumption-based pricing tied to output volume rather than user seats. Marketing departments at German automotive suppliers and Japanese electronics manufacturers are negotiating tiered usage contracts. This shift is most visible in North America and Western Europe where procurement functions scrutinize per-seat SaaS proliferation.
Global AI Writing Assistant Software Market Segmentation
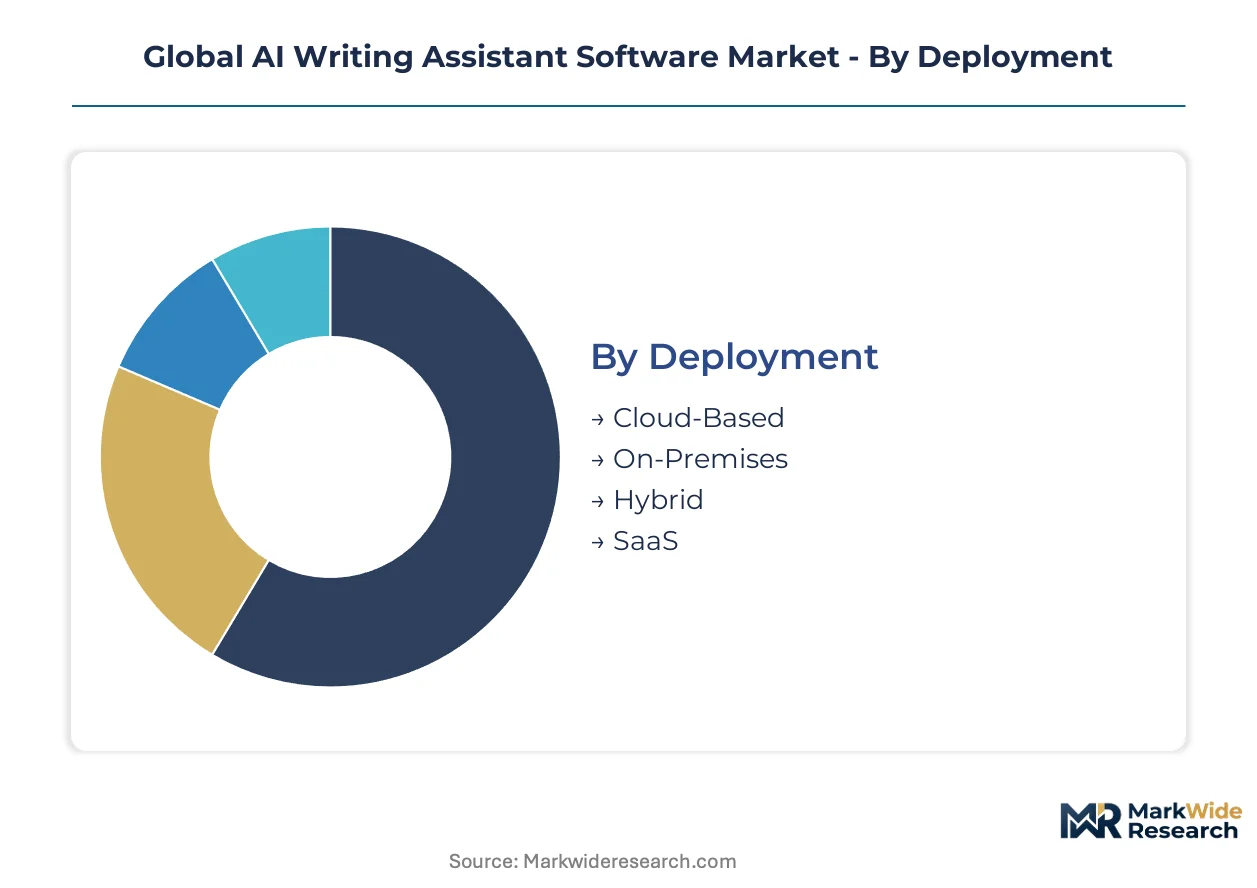
Segmentation reveals how capital intensity and regulatory exposure vary across deployment architectures, solution types, and customer workflows. Vendors must align infrastructure investments with the specific compliance and performance requirements of each slice.
Deployment:
Capital requirements diverge sharply across deployment modes, with self-managed infrastructure demanding the heaviest upfront investment.
- Cloud-Based:Elastic GPU provisioning from hyperscalers eliminates captive data center spend. German automotive suppliers and Japanese electronics manufacturers are consolidating procurement here to satisfy EU AI Act auditability requirements without infrastructure ownership.
- SaaS:Multi-tenant architectures amortize model training costs across thousands of seats. This mode captures the bulk of mid-market marketing agency subscriptions due to minimal IT integration friction.
- Hybrid:Sensitive drafting workflows stay on-premises while model inference taps cloud APIs. Financial institutions in the United States favor this split for HIPAA and SEC compliance boundaries.
- On-Premises:Air-gapped deployments serve defense contractors and classified government facilities with zero external data transmission.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Hybrid configurations as regulated industries seek architectural compromise.
Solution Offering:
Margin profiles separate mature, commoditized functions from emerging capabilities still commanding pricing power.
- Content Generation:Transformer-based synthesis of long-form marketing copy, technical documentation, and campaign creative. Pharmaceutical sponsors in the United States are embedding this into FDA eCTD submission workflows, driving demand for audit-trailed outputs.
- Grammar Checking:Real-time syntactic and semantic correction with established enterprise pricing. Corporate communications teams treat this as table stakes, constraining vendor differentiation.
- Style Improvement:Brand voice alignment and readability optimization for editorial consistency. Publishing houses in France deploy this to enforce in-house style guides across distributed contributor networks.
- Plagiarism Detection:Cross-referencing against proprietary and web corpora for originality verification. Educational institutions mandate this for admissions and assessment integrity.
- Summarization:Abstractive and extractive compression of long documents for executive consumption. Legal firms in Germany apply this to due diligence and contract review pipelines.
- Translation:Neural machine translation with domain-specific fine-tuning for localized content production. Japanese insurers use this to automate policy document localization for Southeast Asian markets.
Grammar Checking retains the largest seat count. Content Generation is climbing the fastest as enterprises automate production workflows.
Use Case:
Workflow integration complexity determines sales cycle length and professional services attachment rates.
- Content Marketing:End-to-end campaign creation from brief to publishable copy. Marketing agencies in the United States negotiate usage-based contracts tied to output volume rather than seat licenses.
- Technical Documentation:API-first generation of SDK references, release notes, and user manuals. DevOps teams at software companies embed this into CI/CD pipelines for deployment-velocity documentation.
- Legal Drafting:Contract generation, clause extraction, and risk flagging with embedded audit trails. US financial institutions pilot retrieval-augmented generation for regulatory compliance documentation.
- Academic Writing:Research assistance, citation formatting, and integrity checking for scholarly publication. Educational institutions impose this as a procurement standard for student-facing tools.
- Social Media Management:Short-form copy generation and scheduling optimization for brand channels. Freelancers and boutique agencies dominate this segment due to low contract values.
- Customer Support:Ticket response drafting and knowledge base article generation. Corporate communications teams integrate this with CRM platforms for response consistency.
Content Marketing carries the heaviest contract values. Technical Documentation is expanding most quickly as software vendors automate developer relations output.
End User:
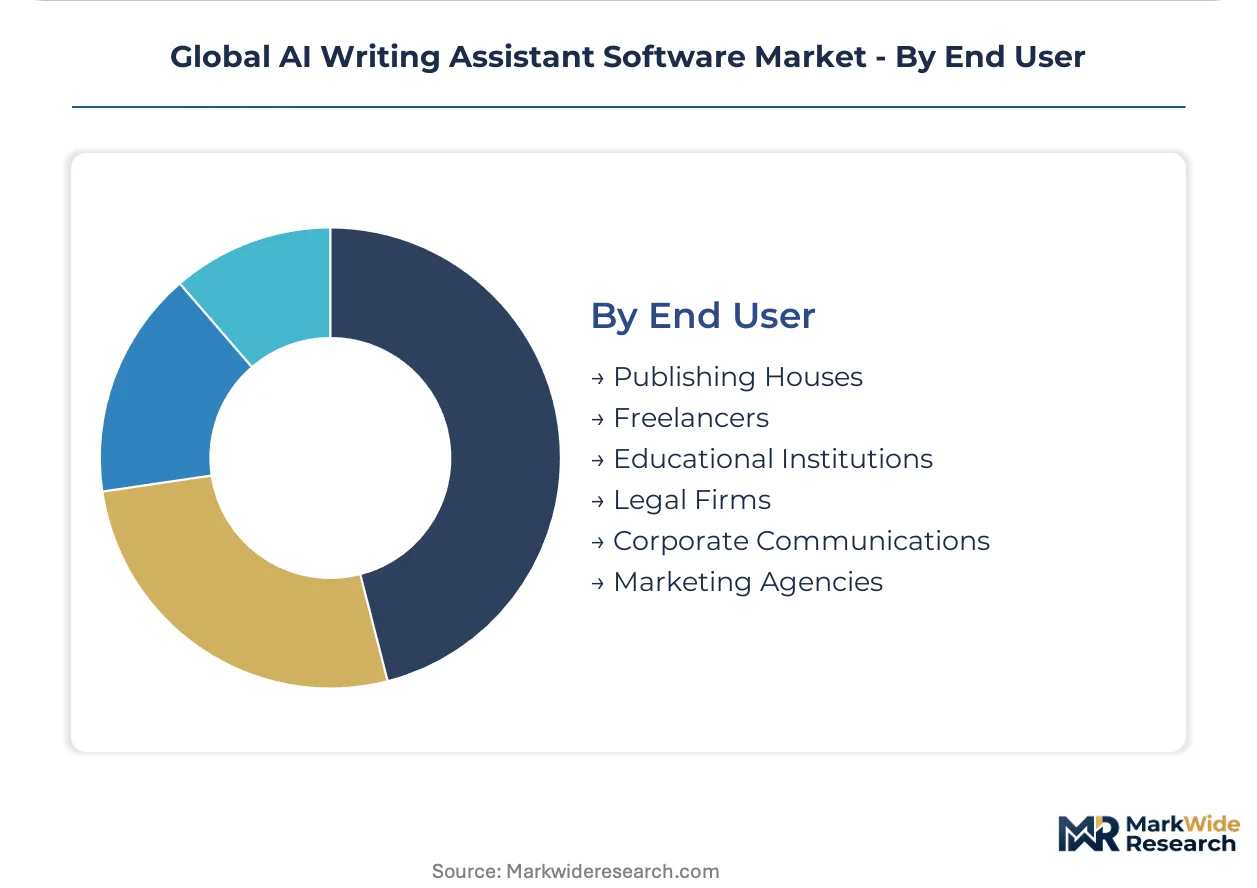
Buyer sophistication and procurement rigor segment the customer base into enterprise, institutional, and individual tiers.
- Marketing Agencies:Multi-client workflow management with brand voice isolation per account. European agencies are demanding EU AI Act transparency features as procurement prerequisites.
- Corporate Communications:Internal and external messaging governance across distributed teams. US-headquartered multinationals drive standardization to ensure regulatory compliance across jurisdictions.
- Publishing Houses:Editorial pipeline automation with contributor management and rights tracking. French and German publishers are consolidating vendor relationships to satisfy emerging copyright disclosure mandates.
- Educational Institutions:Student-facing writing support with academic integrity enforcement. Admissions offices and writing centers deploy this for scalable feedback.
- Legal Firms:Contract drafting, discovery summarization, and regulatory filing preparation. German law practices emphasize GDPR-compliant data handling in vendor selection.
- Freelancers:Individual productivity enhancement with minimal integration requirements. Price sensitivity here constrains vendor margin.
Marketing Agencies represent the deepest contract penetration. Corporate Communications is gaining share fastest as enterprises centralize content governance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software vendors are relocating engineering resources to jurisdictions with lighter AI disclosure burdens, widening the compliance-cost gap between the United States and European Union. The EU AI Act's systemic transparency mandates are accelerating procurement of auditable platforms among European publishing houses and advertising agencies. Demand concentration spans the United States, Germany, and Japan.
United States
Enterprise marketing teams at Fortune 500 companies are consolidating procurement around cloud-based content generation suites with API-first architectures. The FTC applies existing consumer protection statutes to deceptive automated content practices rather than issuing AI-specific rules. Silicon Valley vendors dominate technical documentation automation for DevOps pipelines.
Germany
Automotive suppliers and industrial conglomerates are demanding grammar checking and style improvement tools with embedded GDPR compliance boundaries. The EU AI Act imposes automated text disclosure requirements that reshape product roadmaps for vendors serving Frankfurt and Munich advertising clusters. Publishing houses in Hamburg are consolidating vendor relationships to satisfy emerging copyright disclosure mandates.
Japan
Knowledge management automation demand from Tokyo-based insurers and Osaka banks is outpacing domestic NLP vendor capacity. METI guidelines on AI utilization in financial services are creating procurement specifications for audit-trailed outputs. Multilingual model providers are establishing partnerships with Nagoya manufacturing exporters for localized technical documentation.
United Kingdom
London marketing agencies are negotiating usage-based contracts tied to output volume rather than seat licenses. The UK lacks comprehensive AI legislation post-Brexit, though the Information Commissioner's Office applies data protection frameworks to automated text systems. Legal firms in the City are piloting retrieval-augmented generation for contract drafting workflows.
France
Publishing houses in Paris are enforcing in-house style guides across distributed contributor networks using style improvement solutions. CNIL guidance on automated decision-making extends to text generation transparency requirements. Lyon-based pharmaceutical sponsors are embedding AI-assisted clinical study report generation into FDA eCTD submission workflows.
Global AI Writing Assistant Software Market Competitive Landscape
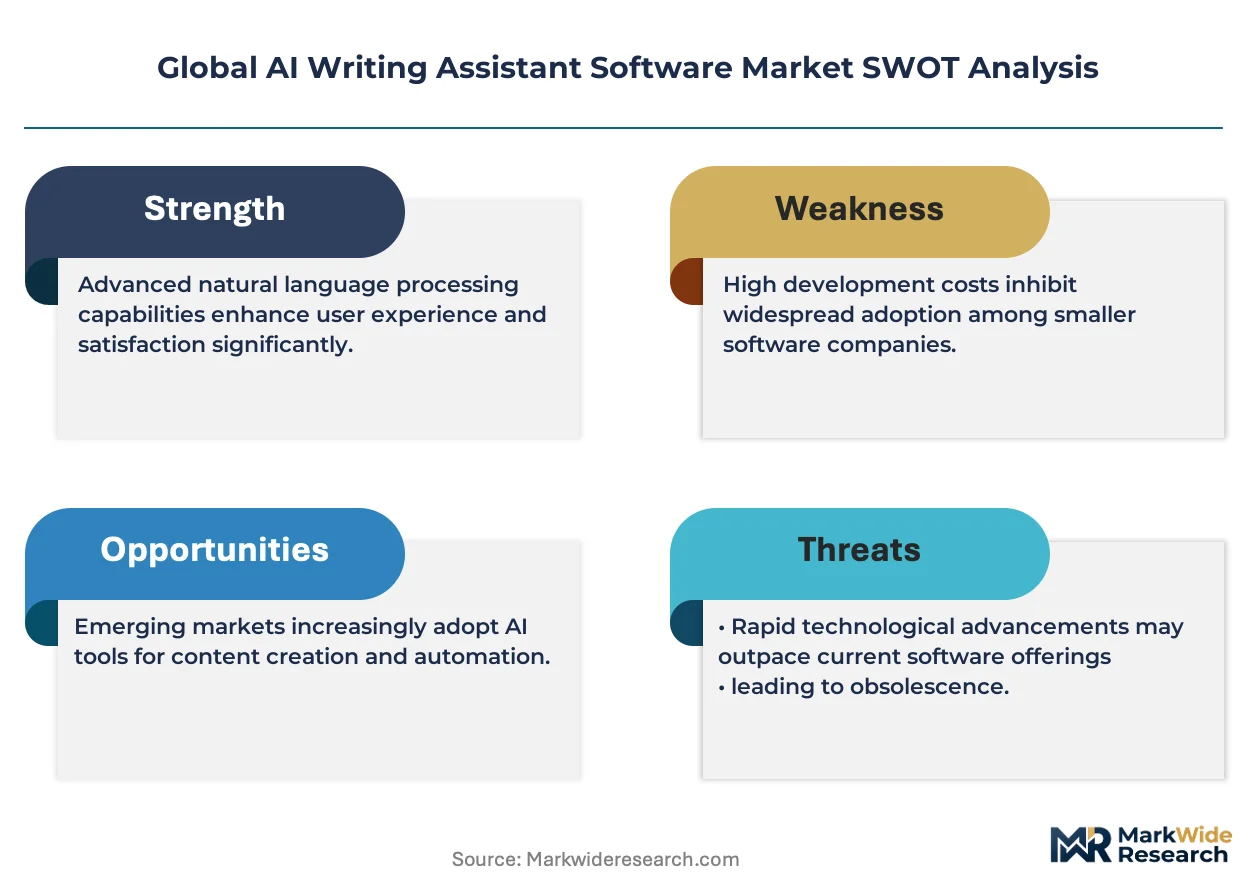
Branded specialists and contract manufacturers split share differently across segments, with consolidated positions in real-time grammar correction and fragmented competition in vertical-specific content generation. Grammar checking retains pricing power from enterprise communications teams treating the capability as table stakes. Three archetypes dominate: horizontal platform vendors with proprietary model training, point-solution specialists in grammar or plagiarism detection, and hyperscaler-backed generalists integrating text generation into productivity suites. Competitive moves center on backward integration into captive GPU clusters and consumption-based pricing pivots away from seat-based subscriptions.
Within the horizontal platform tier, Grammarly and Jasper exemplify divergent infrastructure strategies. Grammarly sustains brand strength in corporate communications through real-time syntactic and semantic correction. Jasper leverages in-house production of proprietary large language model training for marketing copy synthesis. Claude occupies a position among general-purpose conversational interfaces that anchor cross-format creative workflows. These three entities represent the spectrum from specialized correction engines to full-stack generation platforms.
| Leading Market Players |
|---|
| Copy.ai |
| Anyword |
| Jasper |
| Claude |
| QuillBot |
| Grammarly |
| Writesonic |
| Surfer |
| ChatGPT |
| Others |
Supply & Pricing Matrix
Enterprise procurement teams in Germany and Japan are consolidating vendor relationships around EU AI Act-compliant platforms, forcing suppliers to absorb compliance tooling costs and restructure contract terms toward consumption-based models. This demand compression is reshaping how cloud inference providers negotiate GPU-as-a-service commitments and how SaaS vendors tier their feature bundles.
Pricing Analysis
Distributor margins in the enterprise SaaS channel are compressing as hyperscaler marketplaces displace traditional resale relationships. Pricing stratifies across premium, standard, and economy tiers based on audit trail depth and model training transparency. Cost compression in the mid-market tier is intensifying because seat-based subscriptions face procurement scrutiny. Freelancers and boutique agencies exhibit the highest price sensitivity, while pharmaceutical sponsors and financial institutions tolerate premium pricing for embedded compliance documentation.
Supply Chain Analysis
ISO 27001 and SOC 2 Type II certifications gate access to enterprise procurement pipelines, particularly for vendors serving US financial institutions and German automotive suppliers. GPU cluster provisioning concentrates in the United States, Taiwan, and Ireland. Model training draws from NVIDIA H100 silicon, proprietary fine-tuning datasets, and reinforcement learning from human feedback infrastructure. Single-source vulnerability runs through NVIDIA's foundry relationships for advanced AI accelerators. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global AI Writing Assistant Software Market represents a late-cycle quality story as enterprise buyers prioritize audit-trailed outputs over generic generation capabilities. Procurement specifications from Frankfurt advertising clusters and Tokyo financial institutions now mandate embedded transparency tooling as a baseline requirement.
For Market Incumbents: Extend platform stickiness through backward integration into captive GPU clusters for inference cost control. Incumbents should deepen API-first architectures to capture DevOps workflow integration, defending against emerging API-native challengers. Certification investment in EU AI Act readiness represents the critical lever for European revenue retention. For New Entrants and Emerging Players: Retrieval-augmented generation architectures offer a technology-first wedge into legal drafting and healthcare regulatory writing segments where hallucination liability has stalled incumbent penetration. White-space opportunity concentrates in Japanese knowledge management automation and FDA eCTD submission tooling for mid-cap pharmaceutical sponsors. A channel partnership strategy with systems integrators serving regulated industries accelerates enterprise trust formation. For Investors and Strategic Acquirers: Asymmetric upside sits with vertical specialists possessing proprietary fine-tuning pipelines for healthcare and financial services. Long-term viability hinges on differentiation durability against hyperscaler generalist bundling. The signal to watch is procurement mandate expansion from EU AI Act transparency requirements into US federal contracting specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding writing assistants into Salesforce and Adobe CMS stacks captures enterprise workflow lock-in. |
| Strategic Partnership | Hyperscaler alliances with AWS and Azure provide GPU provisioning leverage for mid-market vendors. |
| Acquisition of Specialist Firm | Buying retrieval-augmented generation startups accelerates factual grounding capabilities for legal and medical use cases. |
| Geographic Expansion | Establishing Tokyo engineering centers addresses Japanese insurer demand outpacing domestic NLP capacity. |
| Product Launch | Introducing multimodal orchestration suites anchors text generation within cross-format campaign workflows. |
Research Methodology
Bottom-up enterprise procurement modeling reconciled against top-down cloud infrastructure spend tracking forms the analytical core of this study. Primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners were validated against secondary sources including SEC filings, hyperscaler capex disclosures, and EU regulatory filings. Triangulation across deployment architecture data and solution offering revenue splits ensures segment-level accuracy.
Historical trendline analysis of seat-based versus consumption-based contract transitions informed the projection framework. Segmentation modeling spans deployment mode, solution offering, use case workflow, and end-user sophistication tier across the analysis window. CAGRs were derived from elasticity-adjusted adoption curves and inference cost trajectory assumptions. Forecast inputs include GPU spot pricing volatility and EU AI Act implementation timelines.
The model holds under steady regulatory enforcement intensity; deviation in FTC rulemaking or EU AI Act penalty structures would shift enterprise procurement velocity. Forecasts reflect documented assumptions regarding cloud infrastructure elasticity and mid-market subscription fatigue persistence. A model refresh is warranted upon material change in hyperscaler GPU provisioning economics or federal AI legislation introduction in the United States.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Application Platform Market
Software & Services
US Content Services Platform Market
Software & Services
Media Planning Software Market
Software & Services
Voice to Text on Mobile Devices Market
Software & Services
Global Data Quality Software Market
Software & Services
Hydraulic Modeling Software Market
Software & Services
Subscription Management Software Market
Software & Services
Global SEO Software Market
Software & Services
User Interface Software Market
Software & Services
Video Converter Software Market
Software & Services
Car-Hailing Software Market
Software & Services
Inventory Management Software Market
Software & Services
Graphical User Interface (GUI) Design Software Market
Software & Services
Asia-Pacific Text to Speech (TTS) Software Market
Software & Services
Global Sweepstakes Software Market
Software & Services
Global Gamification Software Market