
 Asia-Pacific ERP Software Market | 2026-2036
Asia-Pacific ERP Software Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific ERP Software Market Analytics
Modular subscription bundling is expanding across the Asia-Pacific ERP landscape as vendors unbundle monolithic suites into composable microservices. SAP leverages deep vertical specialization in process manufacturing to sustain premium positioning across ASEAN chemical and food processing plants. Oracle anchors cloud ERP growth through aggressive data center expansion in Singapore and Tokyo, competing directly with Microsoft's Dynamics platform which extends through channel partnerships with local system integrators in Australia and South Korea.
Enterprise resource planning software integrates core business processes through centralized databases with real-time transaction processing, typically deployed via multi-tenant cloud architectures with API-first connectivity to third-party logistics and payroll systems. Cloud-based deployment now leads new installations as SMEs abandon legacy client-server maintenance burdens, while on-premise solutions retain dominance in Japanese financial institutions bound by strict data residency protocols. Supply chain management modules represent the fastest-growing solution segment as manufacturers rebuild buffers after recent disruptions, though financial management still captures the largest margin pool due to embedded banking and treasury integrations.
India's Ministry of Electronics and Information Technology enforces data localization through the Digital Personal Data Protection Act, compelling foreign ERP vendors to store citizen and business records on domestic servers. China's Cybersecurity Administration mandates security reviews for critical information infrastructure operators using foreign software, creating compliance complexity for multinational deployments. Stakeholders must monitor evolving cross-border data flow restrictions as these regulations reshape hosting architecture decisions and partner selection criteria across the region.
Market Dynamics
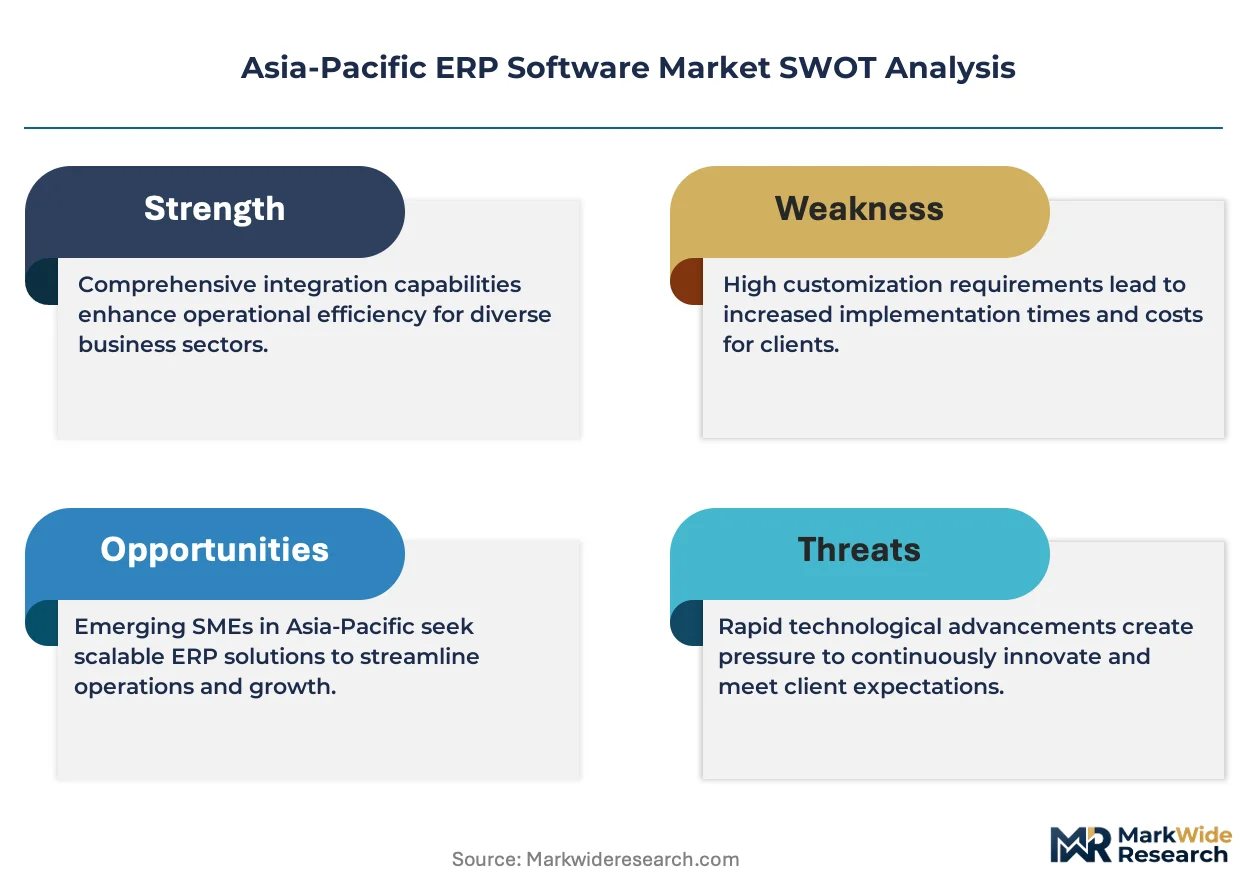
Modular unbundling of monolithic ERP suites into API-first microservices is restructuring vendor economics across Asia-Pacific, forcing incumbents to rebuild pricing architectures around consumption-based metering while mid-market manufacturers demand composable deployment.
Growth Catalysts
- India's PLI scheme for electronics and IT hardware:The incentive framework accelerates domestic cloud infrastructure buildout, compelling ERP vendors to localize data centers and edge nodes to serve manufacturing clusters in Bangalore and Hyderabad.
- Supply chain reconstruction post-disruption:Southeast Asian manufacturers are prioritizing real-time inventory visibility and multi-tier supplier coordination, driving replacement of legacy MRP systems with cloud-native planning modules.
- API-first connectivity standards:Open banking protocols and logistics platform integrations enable ERP vendors to embed treasury and freight management without custom development, shortening implementation cycles for mid-market buyers.
Market Restraints
- Data localization mandates:India's Digital Personal Data Protection Act and China's Cybersecurity Administration security review requirements force foreign vendors to replicate hosting infrastructure across multiple sovereign jurisdictions, inflating operational overhead.
- Legacy technical debt in Japanese financial institutions:Decades-old mainframe integrations and strict data residency protocols bind major banks to on-premise deployments, capping cloud migration velocity in a high-margin vertical.
- Skills scarcity in ASEAN implementation markets:Shortages of certified solution architects and change management specialists in Vietnam, Indonesia, and the Philippines extend project timelines and elevate deployment failure rates.
Strategic Opportunities
- Indonesia's manufacturing digitization push:Government incentives for Industry 4.0 adoption in Batam and Jababeka industrial zones create first-mover advantage for vendors offering localized Bahasa interfaces and Sharia-compliant financial modules.
- Convergence of ERP and ESG reporting:Integration of carbon accounting and Scope 3 emissions tracking into core financial workflows addresses emerging CSRD-aligned disclosure requirements for export-oriented manufacturers.
- Embedded finance partnerships:Direct API linkages between ERP treasury modules and neobank lending platforms enable working capital financing at point-of-invoice, unlocking new recurring revenue streams for software providers.
Industry Challenges
- Multi-tenant security certification complexity:Achieving ISO 27001, SOC 2 Type II, and jurisdiction-specific attestations across Singapore, Australia, and South Korea data centers consumes 12-18 month compliance cycles that delay regional launches.
- Hybrid integration architecture management:Maintaining real-time synchronization between cloud ERP cores and persistent on-premise manufacturing execution systems in Japanese and Korean automotive plants demands specialized middleware expertise that vendors struggle to staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific ERP Software Market |
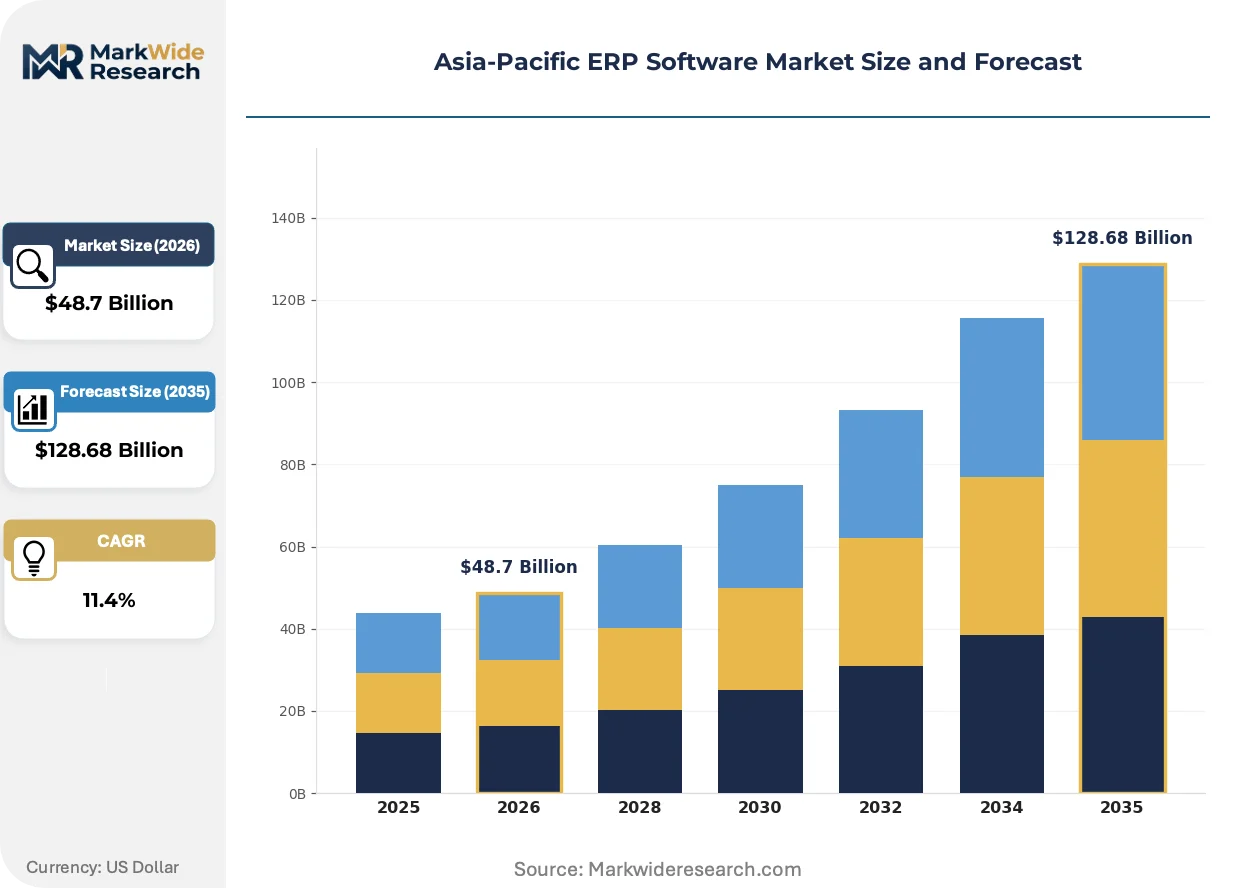
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Managed End User: Manufacturing, Retail, Healthcare, Education Solution: Financial Management, Supply Chain Management, Human Resources, CRM Size: Large Enterprises, SMEs, Startups, Corporations |
| Companies Covered | IFS, Acumatica, Oracle, Deskera, HashMicro, SAP, Infor, 3i Infotech, Microsoft, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific ERP Software Market Evolving Landscape
Artificial intelligence infusion is redefining core ERP workflows across Asia-Pacific, shifting competitive advantage from functional breadth toward predictive automation and autonomous decisioning capabilities in financial and supply chain operations.
Generative AI copilots are absorbing routine transactional coding and exception-handling workflows previously executed by shared service center staff. Mid-market manufacturers in Thailand and Malaysia are piloting natural language interfaces for procurement requisitioning and vendor inquiry resolution, compressing the headcount economics that previously justified ERP investments. The technology is absorbing first-line support volumes and accelerating user onboarding without proportional training investment.
China's Cybersecurity Administration mandates security reviews for critical information infrastructure operators deploying foreign software, creating compliance architecture requirements that reshape product roadmaps. Multinational vendors must now maintain technically equivalent domestic codebases and audit trails to satisfy MIIT inspection protocols. Japanese automotive and semiconductor manufacturers with dual China-ASEAN supply chains face the most complex certification burden, driving preference for vendors with established Beijing-Shanghai data center presence.
Subscription fatigue among CFOs is triggering unbundling of ERP contracts into separately negotiable modules with annual true-up provisions. Australian and South Korean mid-market buyers are rejecting all-inclusive per-user pricing in favor of consumption-based metering tied to transaction volumes and API call rates. This behavioral shift is most visible in SaaS corridors where local system integrators now structure gain-share arrangements linking implementation fees to realized efficiency metrics rather than license values.
Asia-Pacific ERP Software Market Segmentation
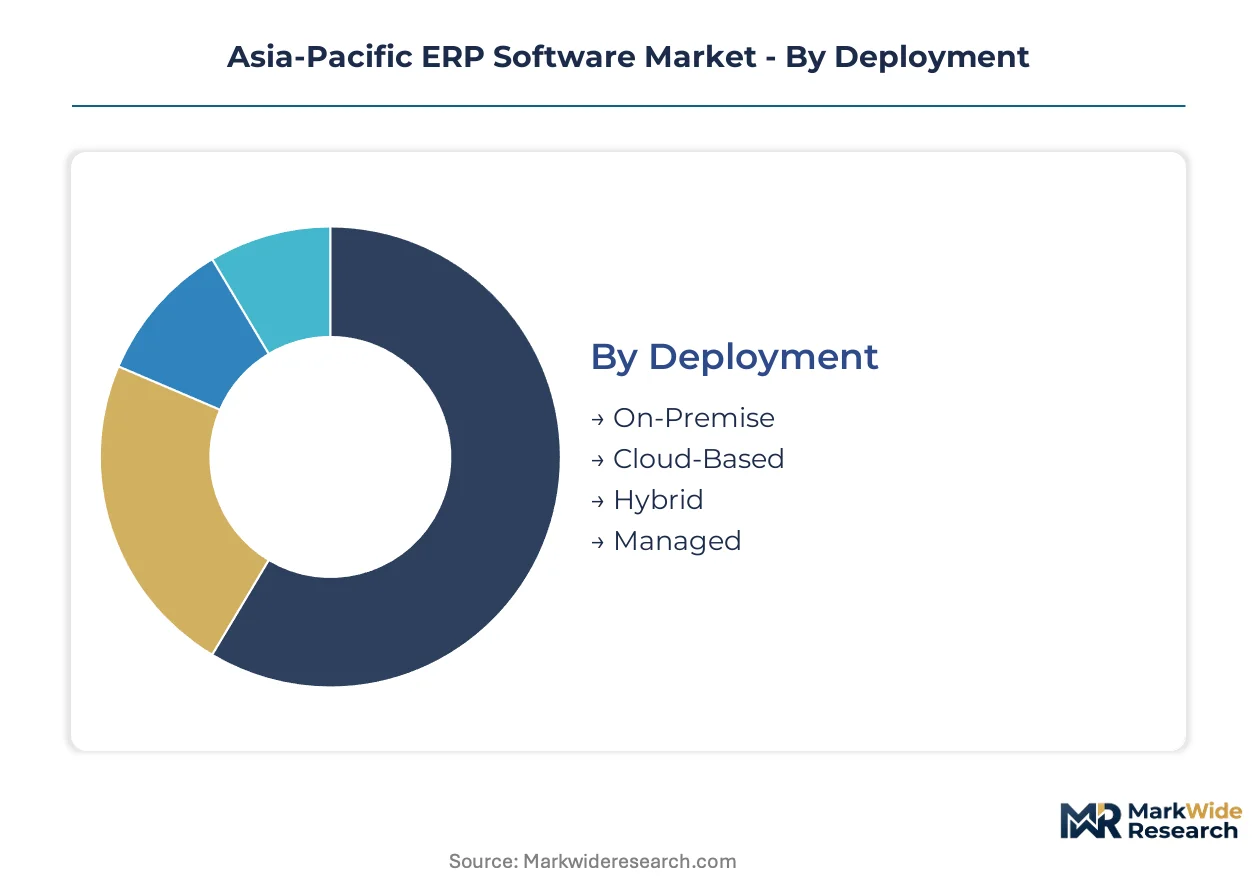
ERP procurement patterns across Asia-Pacific diverge sharply by deployment maturity, end-user digital readiness, and regulatory data sovereignty requirements. Vendors must align module pricing and implementation architecture to these structural fault lines to capture replacement cycles and greenfield installations.
Deployment:
Volume deployments concentrate in standardized cloud configurations, while premium pricing attaches to customized hybrid and managed service arrangements.
- Cloud-Based:Multi-tenant SaaS architectures with API-first connectivity dominate new installations among mid-market manufacturers in India's Bangalore-Hyderabad corridor. Subscription metering tied to transaction volumes and user seats displaces perpetual licensing as CFOs reject bundled suite pricing.
- On-Premise:Legacy client-server installations persist in Japanese financial institutions bound by METI data residency protocols and decades-old mainframe integrations. These deployments command premium maintenance revenue but face sunset pressure from cloud-native competitors.
- Hybrid:Split architectures synchronize cloud ERP cores with persistent on-premise manufacturing execution systems in Korean and Japanese automotive plants.
- Managed:Third-party hosted private clouds serve Australian mining operators and Singaporean logistics firms requiring dedicated infrastructure without operational burden.
Mature deployment sits with On-Premise. Newer deployment is concentrated in Cloud-Based.
End User:
Application complexity and integration depth separate high-margin verticals from standardized horizontal deployments.
- Manufacturing:Process and discrete manufacturers across Southeast Asia drive module demand for supply chain planning, shop floor integration, and multi-tier supplier coordination. Chemical and food processing plants in Thailand and Vietnam prioritize lot traceability and regulatory batch reporting.
- Retail:Omnichannel inventory unification and POS-ERP synchronization dominate requirements among Australian and South Korean mid-market chains. Real-time stock visibility across warehouse, storefront, and marketplace channels determines vendor selection.
- Healthcare:Hospital networks in Singapore and Australia require patient billing integration with clinical systems and compliance with jurisdiction-specific privacy frameworks.
- Education:Universities and vocational institutes across Indonesia and the Philippines adopt lightweight financial and HR modules for grant management and payroll processing.
Manufacturing commands the deepest module penetration. Education shows the steepest expansion trajectory as public digitization budgets flow to institutional modernization.
Solution:
Margin pools concentrate where embedded banking, regulatory reporting, and third-party platform integrations create switching costs.
- Financial Management:General ledger, treasury, and compliance modules anchor ERP value propositions through embedded banking APIs and automated tax reporting. Indian mid-market manufacturers prioritize GST-compliant invoicing and TDS automation.
- Supply Chain Management:Demand planning, inventory optimization, and logistics coordination modules expand fastest as manufacturers rebuild buffers after recent disruptions. Real-time supplier visibility commands premium pricing in ASEAN electronics clusters.
- Human Resources:Payroll, attendance, and talent management modules serve distributed workforces across Australia's mining sites and India's IT services corridors.
- CRM:Customer data platforms and sales force automation integrate with core ERP transaction records for retail and B2B manufacturing verticals.
Financial Management retains the largest installed base. Supply Chain Management is gaining share fastest as procurement volatility drives replacement investment.
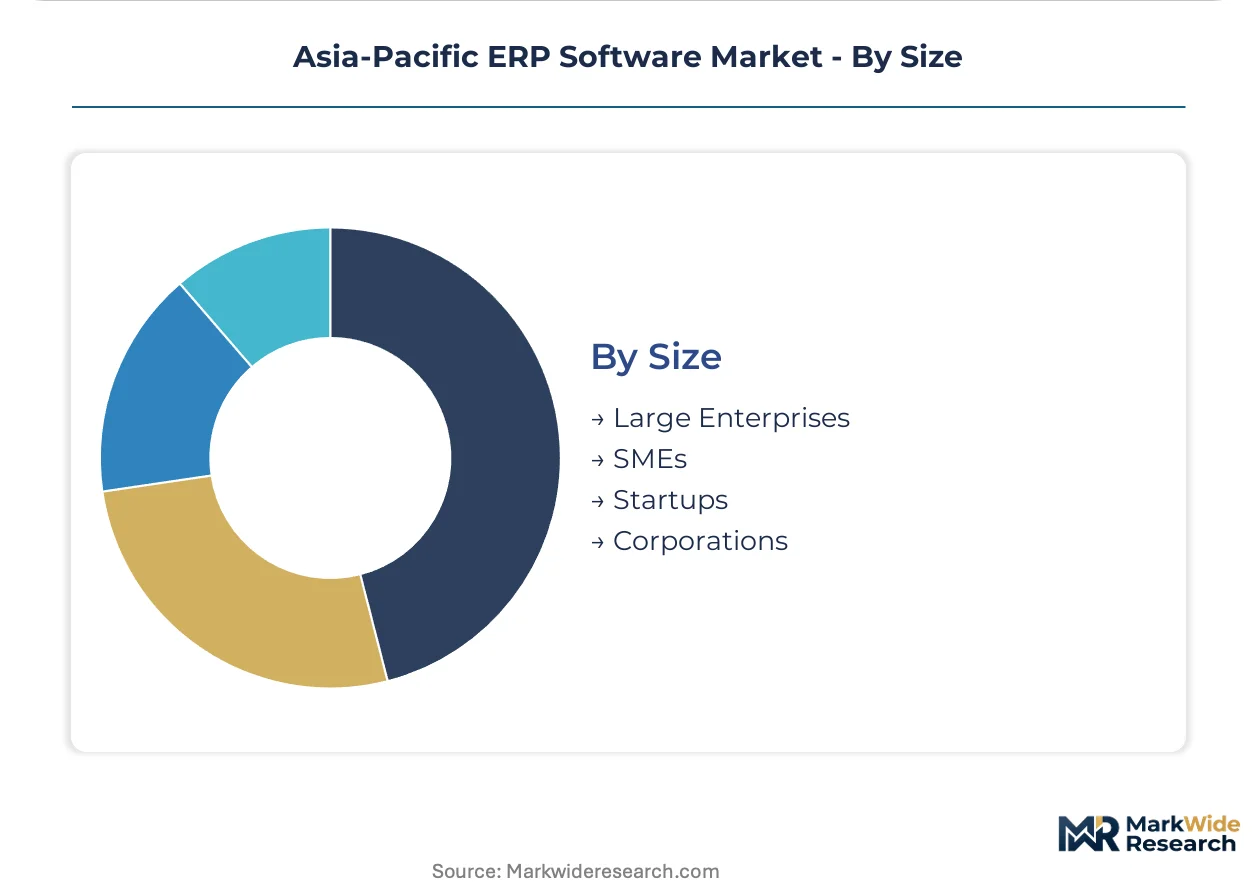
Size:
Customer scale determines implementation methodology, with self-service onboarding for smaller entities and dedicated transformation programs for complex enterprises.
- SMEs:Mid-market manufacturers and services firms across Malaysia, Thailand, and Vietnam adopt composable microservices with rapid deployment templates. These buyers reject monolithic suites in favor of subscription-based financial and supply chain modules.
- Large Enterprises:Conglomerates and multinational subsidiaries require multi-entity consolidation, intercompany eliminations, and jurisdiction-specific regulatory reporting across India, China, and ASEAN operations.
- Startups:Venture-backed technology firms in Singapore and Bangalore select lightweight cloud-native platforms with minimal customization and pay-as-you-grow scaling.
- Corporations:Established regional headquarters in Tokyo, Sydney, and Mumbai mandate standardized ERP templates across subsidiary networks with centralized governance.
Corporations anchor professional services revenue. Startups represent the fastest-climbing adoption curve as venture capital flows to operational infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in India's software corridors while consumption spreads across Southeast Asian manufacturing belts. Cloud infrastructure buildout lags demand in Indonesia and Vietnam, forcing vendors to route traffic through Singapore hubs. Regulatory fragmentation across data sovereignty regimes complicates unified service delivery.
India
Mid-market manufacturers in Bangalore and Hyderabad drive subscription demand for financial and supply chain modules. The Ministry of Electronics and Information Technology enforces data localization through the Digital Personal Data Protection Act, compelling domestic server deployment. Vendors cluster in the SaaS corridor spanning Karnataka and Telangana to serve electronics manufacturers qualifying under the PLI scheme.
China
State-owned manufacturers and private conglomerates sustain demand for on-premise and hybrid deployments amid security review requirements. The Cybersecurity Administration mandates MIIT inspections for critical information infrastructure operators using foreign software. Multinational vendors maintain technically equivalent codebases in Beijing and Shanghai data centers to serve automotive and semiconductor supply chains.
Japan
Financial institutions bound by METI data residency protocols perpetuate legacy client-server installations despite cloud pressure. The central bank and financial regulators enforce strict operational continuity standards that privilege proven on-premise architectures. Tokyo anchors professional services revenue while Osaka-Nagoya manufacturing clusters pilot hybrid ERP-MES synchronization for automotive production.
South Korea
Chaebol subsidiaries and mid-market manufacturers adopt cloud-native platforms with API-first connectivity to logistics and banking systems. The MFDS and financial regulators maintain sector-specific data handling guidelines that shape vendor certification requirements. Seoul Capital Area concentrates deployment activity while Busan-Ulsan industrial zones demand supply chain modules for shipbuilding and petrochemical operations.
Australia
Mining operators and logistics firms favor managed private cloud arrangements requiring dedicated infrastructure without operational burden. The TGA and APRA enforce compliance frameworks that elevate security certification requirements for healthcare and financial deployments. Sydney and Melbourne anchor enterprise adoption while Perth serves resource extraction companies with specialized asset management modules.
Asia-Pacific ERP Software Market Competitive Landscape
The competitive structure tilts toward integrated suite providers with deep vertical specialization. Incumbent vendors defend position through data center expansion and channel partnerships with local system integrators. Three archetypes dominate: global platform owners with regional localization teams, regional specialists offering Bahasa and Hindi language interfaces, and cloud-native challengers targeting mid-market manufacturers with consumption-based pricing. M&A activity concentrates on acquiring implementation capabilities and sector-specific module developers, while geographic expansion through Singapore and Tokyo data centers represents the primary capacity move.
Among global platform owners, SAP and Oracle exemplify the integrated suite archetype with established ASEAN chemical and food processing specialization. Microsoft occupies a channel-dependent position leveraging local system integrator networks in Australia and South Korea. Regional challengers include Deskera and HashMicro, which represent the localization-focused tier targeting SME manufacturers with rapid-deployment templates and vernacular interfaces.
| Leading Market Players |
|---|
| IFS |
| Acumatica |
| Oracle |
| Deskera |
| HashMicro |
| SAP |
| Infor |
| 3i Infotech |
| Microsoft |
| Others |
Value Network & Pricing Analysis
India's Digital Personal Data Protection Act gates qualified supply access and premium-tier pricing power by mandating domestic server deployment for citizen and business records, forcing foreign ERP vendors to absorb data center buildout costs before competing for mid-market manufacturing contracts in Bangalore and Hyderabad.
Pricing Analysis
Margin tightening in cloud-native tiers reflects subscription fatigue among CFOs rejecting bundled per-user pricing in favor of consumption-based metering tied to transaction volumes and API call rates. Three-tier pricing structure across premium, standard, and economy levels separates SAP and Oracle's vertical-specialized suites from regional challengers offering rapid-deployment templates. Price differentiation hinges on ISO 27001 certification status and embedded banking integration depth. Australian and South Korean mid-market buyers exhibit highest price sensitivity, while Japanese financial institutions bound by METI data residency protocols show lowest elasticity due to switching cost lock-in.
Supply Chain Analysis
Cloud infrastructure supply rests on data center buildouts in Singapore, Tokyo, and Sydney serving as regional hubs for traffic routing into Indonesia and Vietnam where local capacity lags demand. Software development inputs draw from certified solution architects concentrated in India's SaaS corridor, with implementation partners and API middleware providers as critical dependencies. Single-source vulnerability concentrates in Singapore hub routing for Southeast Asian deployments. Distribution runs through channel partnerships with local system integrators in Australia and South Korea, direct enterprise sales for large conglomerates, and self-service platforms for venture-backed startups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native microservices architectures are displacing monolithic client-server suites across Asia-Pacific manufacturing and financial verticals, compressing implementation timelines from 18-month transformation programs to 90-day modular deployments.
For Market Incumbents: Acquire certified implementation specialists in Vietnam, Indonesia, and the Philippines to close skills scarcity gaps that extend project timelines and elevate deployment failure rates. Anchor defensive position through data center expansion in Singapore and Tokyo to satisfy multi-tenant security certification complexity consuming 12-18 month compliance cycles. Prioritize ISO 27001 and SOC 2 Type II investments ahead of regional challengers.
For New Entrants and Emerging Players: API-first marketplace routes offer lowest-friction customer acquisition for mid-market manufacturers in Thailand and Malaysia piloting natural language procurement interfaces. Target Indonesia's Batam and Jababeka industrial zones where government Industry 4.0 incentives create first-mover advantage for vendors with localized Bahasa interfaces and Sharia-compliant financial modules. Structure gain-share arrangements linking implementation fees to realized efficiency metrics rather than license values.
For Investors and Strategic Acquirers: PLI scheme qualification announcements for electronics and IT hardware manufacturers are the leading indicator that domestic cloud infrastructure buildout will accelerate ERP localization requirements. Long-term viability favors vendors with established Beijing-Shanghai data center presence serving dual China-ASEAN supply chains. Acquisition target archetype: regional specialists offering vernacular interfaces and rapid-deployment templates. Watch for embedded finance partnership announcements between ERP treasury modules and neobank lending platforms as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Data Center Localization | Domestic server deployment satisfies India's Digital Personal Data Protection Act mandates and unlocks mid-market manufacturing contracts. |
| Vertical Module Acquisition | Specialized chemical and food processing capabilities defend premium positioning against composable microservice challengers. |
| API-First Partnership Ecosystem | Open banking and logistics platform integrations shorten implementation cycles for consumption-metered buyers. |
| ESG Reporting Integration | Carbon accounting and Scope 3 emissions tracking address CSRD-aligned disclosure requirements for export-oriented manufacturers. |
| Channel Partner Certification | Certified solution architect networks in ASEAN implementation markets reduce deployment failure rates and extend geographic reach. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Asia-Pacific ERP software market assessment. Primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners combined with secondary validation from SEC filings, hyperscaler capex disclosures, and CDSCO software registration databases. Bottom-up and top-down triangulation cross-checked vendor revenue disclosures against end-user deployment surveys.
Segmentation-level modeling tracked deployment model, organization size, vertical specialization, integration complexity, and regional adoption pattern across the projection horizon. CAGRs derived from fitted growth curves applied to base-year sizing, with cloud infrastructure buildout rates and PLI scheme qualification timelines as industry-specific forecast inputs.
The model holds under stable data localization enforcement and continued manufacturing digitization incentives; deviation in cross-border data flow restrictions or sudden subsidy withdrawal would shift trajectory. A small set of named triggers—MIIT security review protocol changes, METI data residency relaxations, and ASEAN skills certification program expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
North America Saas-Based Expense Management Market
Software & Services
Digital Painting Software Market
Software & Services
Sales Coaching Software Market
Software & Services
Collaborative Authoring Tools Market
Software & Services
Embedded Operating Systems Market
Software & Services
Salesforce Services Market
Software & Services
Canada HR Payroll Software Market
Software & Services
Global Script Writing Software Market
Software & Services
Global Headless CMS Software Market
Software & Services
Airline Route Profitability Software Market
Software & Services
Nonconformance Management Software Market
Software & Services
Emotion Recognition and Sentiment Analysis Software Market
Software & Services
Global Call Center Software Market
Software & Services
Global Absence and Leave Management Software Market
Software & Services
Global Time Series Analysis Software Market
Software & Services
VFX Software Market