
 IT Service Management Tools Market | 2026-2036
IT Service Management Tools Market Size, Share, and Industry Trends Forecast 2026-2036
IT Service Management Tools Market Outlook
AI-powered automation is consolidating around legacy rule-based ticketing as the dominant operational substrate in IT service management tools. ServiceNow leverages its workflow engine dominance across enterprise accounts. BMC Software anchors mainframe-era relationships through deep systems management integration. Atlassian competes on developer-centric collaboration interfaces that bridge IT operations with software engineering teams.
IT Service Management Tools constitute software platforms that orchestrate service request fulfillment, incident resolution, and change control through configurable workflow engines, CMDB integration, and SLA monitoring dashboards. These systems automate the ITIL service lifecycle to minimize downtime and align technology delivery with business objectives. Cloud-based deployment leads segment momentum as organizations retire on-premises data center commitments, while incident management remains the most mature service type with established pricing benchmarks. Asset management registers the fastest expansion as hybrid infrastructure complexity drives discovery and lifecycle tracking requirements across distributed endpoints.
FDA oversight applies where ITSM tools manage regulated healthcare systems, while the EU AI Act imposes algorithmic transparency requirements on automated ticket routing and predictive maintenance modules. ISO 20000 certification shapes procurement eligibility for enterprise buyers and government agencies evaluating vendor compliance. Procurement officers must weigh cloud data residency against AI feature depth when selecting platforms for regulated environments.
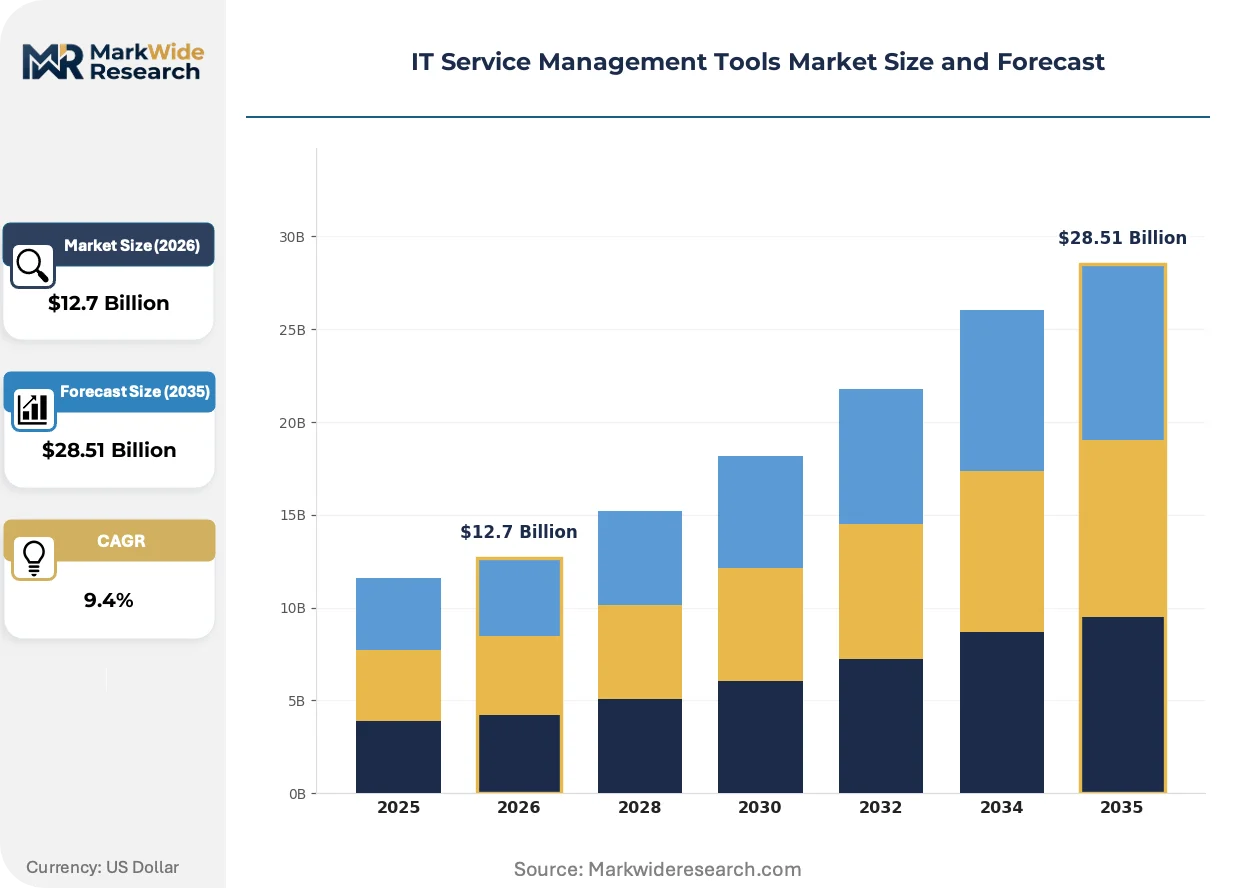
Market Dynamics
Cloud migration mandates under the EU AI Act and comparable data sovereignty frameworks are compressing procurement cycles and forcing platform consolidation decisions across enterprise IT departments.
Growth Catalysts
- EU AI Act compliance deadlines:Automated ticket routing and predictive maintenance modules require algorithmic transparency documentation, accelerating replacement of legacy systems in regulated European industries.
- Hybrid infrastructure complexity:Distributed endpoint proliferation across manufacturing and financial services is expanding asset discovery and lifecycle tracking requirements.
- ISO 20000 procurement eligibility:Government agencies and enterprise buyers in Germany and India are mandating certified platforms for vendor shortlisting.
Market Restraints
- Cloud data residency requirements:The EU AI Act and national implementations in France and Germany fragment platform architectures and inflate compliance engineering costs.
- Mainframe integration technical debt:Deep systems management integration with BMC Software and similar legacy anchors creates switching friction for large enterprises.
- Specialized AI/ML talent scarcity:Automated workflow engine development requires scarce machine learning operations expertise concentrated in US and Indian technology hubs.
Strategic Opportunities
- India digital infrastructure scaling:Central and state government cloud-first policies are creating procurement windows for ITSM platforms with localized data center presence.
- Developer-centric collaboration convergence:Bridging IT operations interfaces with software engineering team workflows represents underpenetrated whitespace outside traditional enterprise accounts.
- FDA-regulated healthcare systems:ITSM tools managing medical device networks and clinical systems face specialized compliance requirements that premium platforms can capture.
Industry Challenges
- ITIL process standardization gaps:Organizations struggle to align configurable workflow engines with established service lifecycle methodologies across distributed teams.
- CMDB data quality maintenance:Configuration management database integration requires continuous discovery accuracy that degrades rapidly in dynamic cloud environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IT Service Management Tools Market |
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $28.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Private Cloud Service Type: Incident Management, Change Management, Asset Management, Problem Management End User: IT Departments, Service Providers, Enterprises, Government Agencies Offering: Software, Consulting, Training, Support |
| Companies Covered | ServiceNow, Atlassian, BMC Software, Broadcom, Ivanti Software, IBM, Microsoft, Freshworks, GoTo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IT Service Management Tools Market Strategic Shifts
Artificial intelligence is compressing traditional service desk staffing models while regulatory pressure on algorithmic decision-making is reshaping platform architecture requirements.
Generative AI assistance for incident resolution and knowledge base management is consolidating around established workflow engines rather than displacing them entirely. Mid-market enterprises in the United States are piloting these capabilities fastest, with IT departments accepting co-pilot interfaces that preserve existing CMDB investments. The structural consequence is that AI feature depth is consolidating as a secondary evaluation criterion behind data residency compliance.
The EU AI Act imposes documentation and human oversight requirements on automated ticket classification and routing systems used by European financial institutions and healthcare providers. Industrial consequence includes mandatory risk assessments for high-risk AI applications and audit trail preservation for algorithmic decisions. Incident management modules with predictive capabilities face the steepest compliance engineering burden, with vendors responding through segregated EU-specific feature branches.
Enterprise buying committees are compressing evaluation cycles for cloud-native platforms while extending diligence periods for on-premises retention scenarios. Traditional reseller channels serving mid-market accounts face disintermediation as direct vendor marketplaces and self-service procurement portals capture simpler workloads. This pattern is most visible in Germany, where Mittelstand manufacturers are bypassing systems integrators for standardized SaaS ITSM subscriptions.
IT Service Management Tools Market Segmentation
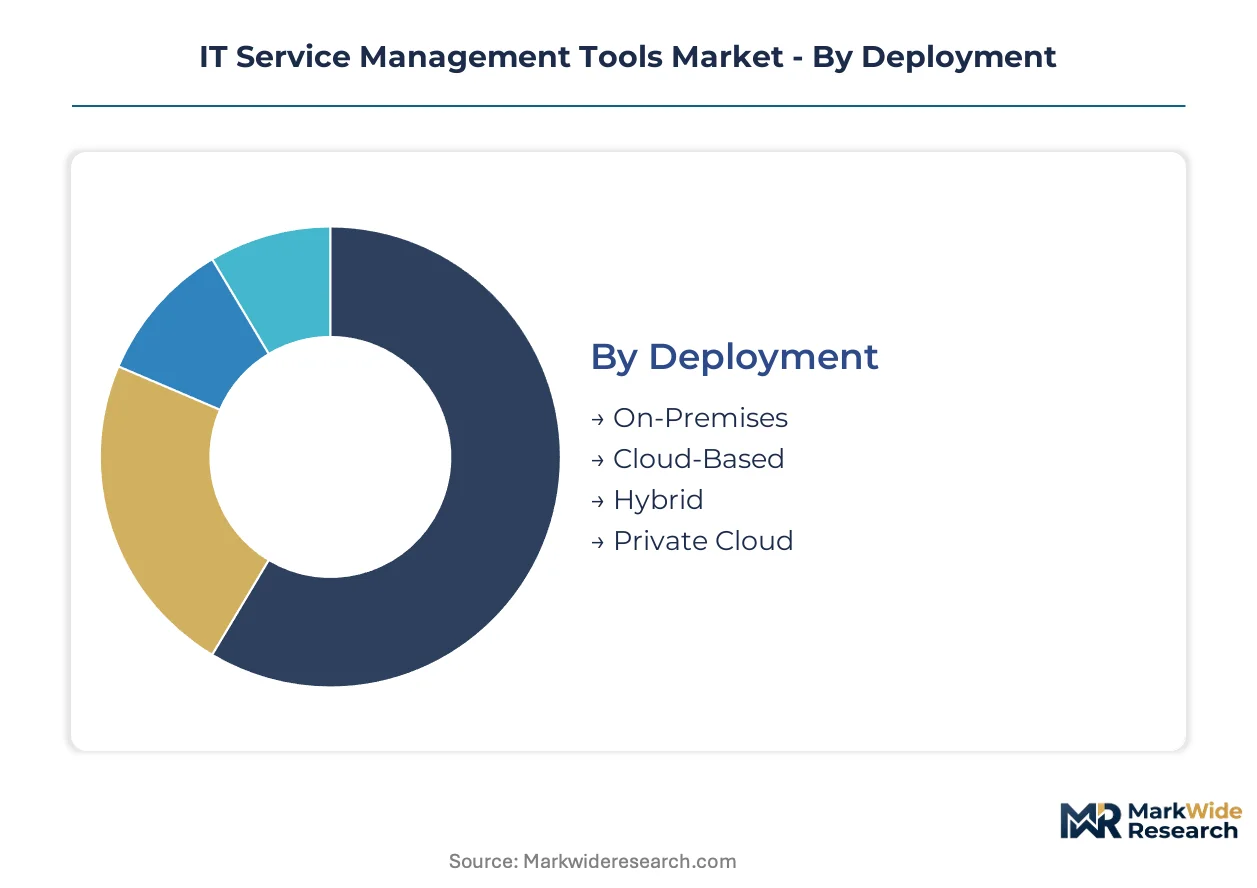
IT Service Management Tools segmentation reveals divergent compliance engineering costs across deployment architectures and service modules. Procurement committees evaluate segments against ISO 20000 certification requirements and jurisdiction-specific data residency mandates.
Deployment:
Cloud-based deployments face EU AI Act algorithmic transparency documentation burdens, while on-premises retention triggers FDA audit trail requirements in regulated healthcare environments.
- Cloud-Based:Multi-tenant SaaS architectures with automated scaling and API-first integration patterns. Demand concentrates in United States mid-market enterprises seeking rapid procurement without capital expenditure cycles. EU AI Act compliance deadlines accelerate replacement of legacy systems in German and French financial services.
- On-Premises:Single-tenant installations with full infrastructure control and custom security perimeter configuration. Healthcare systems in the United States favor this model for FDA-regulated medical device network management. Capital intensity and extended procurement cycles constrain expansion outside regulated industries.
- Hybrid:Orchestrated workloads spanning private data centers and public cloud resources with unified policy enforcement. Manufacturing enterprises in Germany adopt this architecture to preserve operational technology isolation while enabling cloud analytics.
- Private Cloud:Dedicated cloud infrastructure with tenant-isolated compute and storage resources. Indian government agencies mandate this deployment model under data localization directives for citizen service platforms.
Leading the category by volume: Cloud-Based. Growing fastest: Hybrid.
Service Type:
Incident management commands established pricing benchmarks, while asset management segments absorb premium margins from hybrid infrastructure complexity.
- Asset Management:Automated discovery and lifecycle tracking across distributed endpoints with CMDB synchronization. Financial services in the United States and manufacturing in Germany drive demand as IoT device proliferation complicates inventory accuracy. ISO 20000 certification requirements elevate procurement eligibility thresholds.
- Incident Management:Ticket routing, escalation protocols, and SLA monitoring with predictive maintenance modules. Mature pricing benchmarks exist across all deployment models. EU AI Act imposes steepest compliance burden here through mandatory risk assessments for automated classification systems.
- Change Management:Controlled release orchestration with impact analysis and rollback capabilities. IT departments in India prioritize this service type for digital infrastructure scaling initiatives.
- Problem Management:Root cause analysis and known error database maintenance with trend correlation. Service providers embed this capability into managed service offerings for enterprise accounts.
Asset management captures premium pricing. Incident management retains volume leadership.
End User:
Government procurement eligibility hinges on ISO 20000 certification, while service providers demand API extensibility for multi-tenant operations.
- Enterprises:Multi-divisional deployments with federated service desk architectures and centralized governance. United States and German manufacturers dominate procurement volume. Complex CMDB integration requirements favor established workflow engine vendors.
- Government Agencies:Sovereign data residency mandates with public procurement transparency requirements. India and Germany exhibit strongest procurement momentum through cloud-first policy implementation.
- IT Departments:Internal service delivery organizations with business-aligned SLA frameworks. Mid-market adoption accelerates in United States healthcare and financial services.
- Service Providers:Multi-tenant platform operations with customer-segregated data and white-label interfaces. Managed service expansion in Germany and India creates procurement windows.
Enterprises dominate segment revenue. Government agencies expand most quickly.
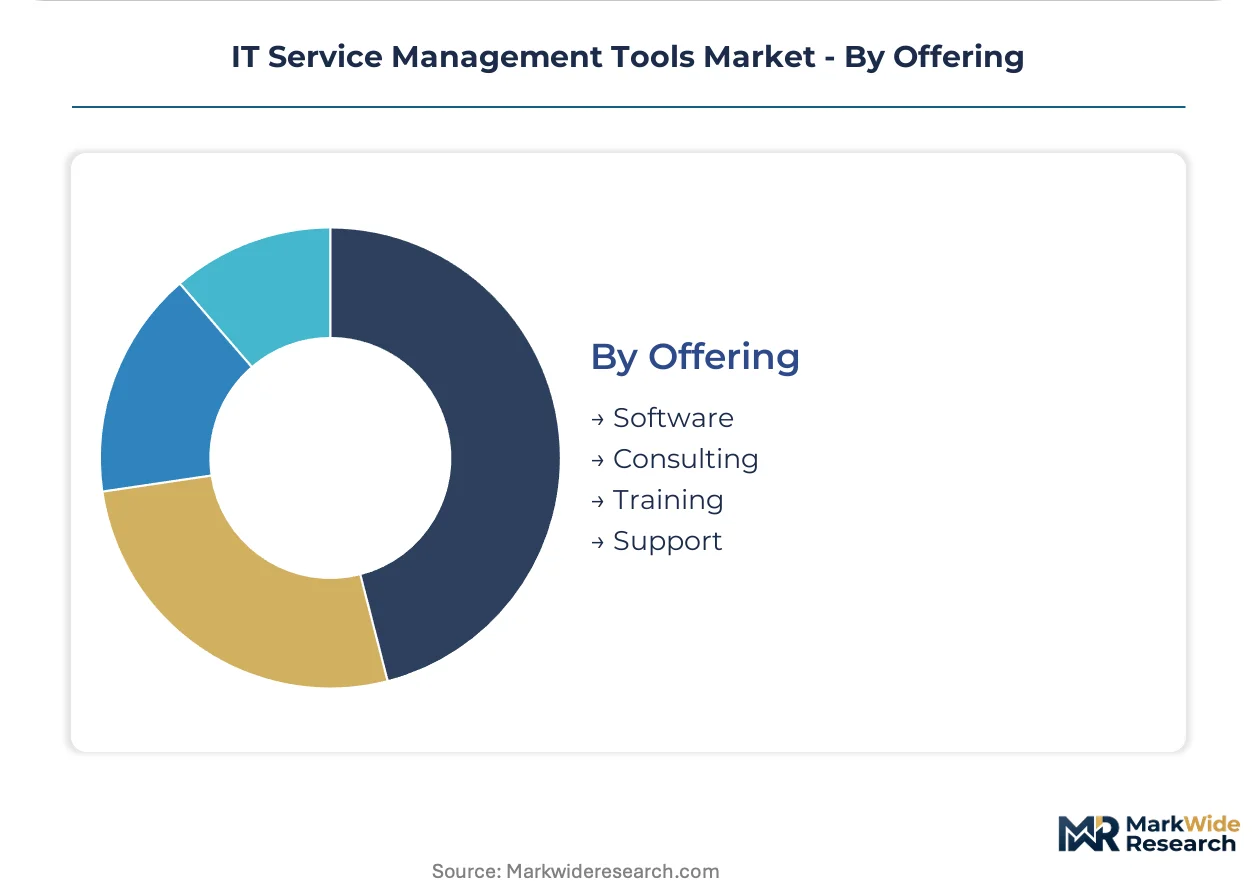
Offering:
Software licensing generates recurring revenue concentration, while consulting engagements concentrate around ITIL process standardization gaps.
- Software:Subscription or perpetual licensing for workflow engines, CMDB platforms, and analytics modules. Cloud-native deployments in United States and Germany drive subscription revenue conversion. EU AI Act compliance features command pricing premiums.
- Consulting:ITIL process design, CMDB data quality remediation, and migration planning services. German Mittelstand manufacturers purchase implementation support for ISO 20000 alignment.
- Support:Technical assistance, version maintenance, and security patch delivery. Government agencies in India mandate domestic support presence for critical infrastructure.
- Training:Administrator certification and end-user adoption programs with ITIL foundation integration. Service providers invest heavily for multi-tenant operational readiness.
Software commands revenue concentration. Consulting climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Hyderabad and Bangalore concentrate Indian ITSM procurement through data localization mandates and cloud-first government policies.
United States
FDA-regulated healthcare systems and financial services in New York and Boston drive demand for on-premises retention with audit trail capabilities. HIPAA compliance requirements shape procurement specifications for medical device network management. The Pacific Northwest hosts cloud-native platform development clusters serving mid-market enterprises.
Germany
Mittelstand manufacturers in Baden-Württemberg and Bavaria bypass systems integrators for standardized SaaS subscriptions under ISO 20000 procurement rules. The EU AI Act imposes algorithmic transparency documentation on automated ticket routing systems. Frankfurt's financial services sector faces compressed compliance deadlines for legacy system replacement.
India
Central and state government cloud-first policies create procurement windows for platforms with localized data center presence in Mumbai and Bangalore. RBI data localization directives and BIS certification requirements elevate vendor eligibility thresholds. Telangana's Hyderabad IT corridor anchors domestic support presence mandates for critical infrastructure.
United Kingdom
Financial services in London's Square Mile demand CMDB integration with legacy mainframe systems. GDPR and emerging UK AI governance frameworks impose documentation requirements on predictive maintenance modules. The Thames Valley technology cluster concentrates managed service provider operations for multi-tenant deployments.
Japan
Manufacturing enterprises in the Chubu region around Nagoya adopt hybrid architectures to preserve operational technology isolation. METI digital transformation incentives accelerate ITIL process standardization initiatives. Tokyo-based IT departments prioritize change management capabilities for digital infrastructure scaling.
IT Service Management Tools Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with workflow engine vendors commanding enterprise accounts and developer-centric platforms capturing mid-market expansion. The vendor base concentrates around three strategic tiers: legacy mainframe integrators, cloud-native SaaS providers, and collaboration-suite extenders. Consolidation pressure intensifies through platform bundling and API ecosystem expansion. M&A activity targets CMDB data quality capabilities and EU-specific compliance engineering.
Among North American platform vendors, ServiceNow, BMC Software, and Atlassian occupy distinct archetype positions. ServiceNow exemplifies workflow engine dominance across multi-divisional enterprise deployments. BMC Software represents deep systems management integration anchored in mainframe-era relationships. Atlassian sits within the developer-centric collaboration convergence, bridging IT operations interfaces with software engineering workflows. Each anchors procurement evaluation criteria for different buyer committees.
| Leading Market Players |
|---|
| ServiceNow |
| Atlassian |
| BMC Software |
| Broadcom |
| Ivanti Software |
| IBM |
| Microsoft |
| Freshworks |
| GoTo |
| Others |
Value Chain & Pricing Dynamics
Enterprise IT procurement committees in Germany and India concentrate purchasing power through ISO 20000 certification requirements, anchoring subscription-based SaaS pricing as the dominant commercial model across cloud-native deployments.
Pricing Analysis
Short lead-time premiums apply to EU AI Act compliance-ready modules, while extended procurement cycles for on-premises retention command spot discounts. Three-tier pricing structure across premium, standard, and economy levels segments by certification depth and data residency configuration. Price differentiation hinges on algorithmic transparency documentation and CMDB integration complexity. Mid-market buyers in the United States exhibit highest price sensitivity, whereas FDA-regulated healthcare systems accept premium tiers for audit trail capabilities. Cost compression in standard-tier SaaS subscriptions is intensifying because vendor consolidation reduces competitive differentiation.
Supply Chain Analysis
Refurbishment flows for legacy mainframe integration components extend hardware lifecycles in United States and German enterprise accounts, creating secondary parts markets that compete with new cloud-native platform provisioning. Software development concentrates in the United States, India, and Ireland, with implementation services drawing from Eastern European and Latin American delivery centers. Cloud infrastructure dependencies rest on hyperscaler data center presence in Frankfurt, Mumbai, and Virginia. Single-source vulnerability exists for specialized AI/ML operations talent concentrated in Bangalore and Seattle. Distribution runs through direct vendor marketplaces and certified systems integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IT Service Management Tools market functions as a cost-of-compliance story where EU AI Act documentation requirements create a barrier-to-entry moat for vendors with established algorithmic transparency engineering.
For Market Incumbents: Deploy certification investment as the primary lever to deepen ISO 20000 and EU AI Act compliance moats against cloud-native challengers. Capture mid-market expansion through API ecosystem partnerships that preserve CMDB infrastructure lock-in. Consolidate position by acquiring CMDB data quality specialists before platform bundling accelerates. For New Entrants and Emerging Players: Self-service procurement portals represent the most penetrable channel for bypassing traditional systems integrator relationships in German Mittelstand manufacturing. Target developer-centric collaboration whitespace outside established enterprise accounts by bridging IT operations interfaces with software engineering workflows. Pursue white-label platform partnerships with managed service providers seeking multi-tenant operational readiness. For Investors and Strategic Acquirers: The window for entry favors EU-specific compliance engineering specialists with algorithmic transparency documentation capabilities. Long-term viability hinges on platforms that can absorb escalating sovereignty-driven architecture fragmentation. Monitor RBI data localization directive enforcement in India as an inflection indicator for government procurement eligibility shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Engineering | Algorithmic transparency documentation creates pricing power in Frankfurt and Paris financial services procurement. |
| CMDB Data Quality Acquisition | Configuration management accuracy underpins renewal rates for ServiceNow and BMC Software enterprise accounts. |
| India Data Center Localization | Hyderabad and Mumbai infrastructure presence satisfies RBI mandates for government and banking sector eligibility. |
| Developer Workflow Integration | Atlassian-style collaboration interfaces capture mid-market expansion outside traditional ITIL-governed enterprises. |
| Hybrid Architecture Orchestration | German manufacturing demand for operational technology isolation drives premium pricing for unified policy enforcement. |
Study Parameters
Document review covered SEC filings from publicly traded platform vendors, EU regulatory guidance documents on algorithmic transparency, and ISO 20000 certification registries, complemented by interviews with IT procurement officers, CMDB implementation specialists, and managed service provider operations directors. Secondary validation drew from hyperscaler data center expansion announcements, government cloud-first policy directives, and trade data on software services exports. Bottom-up segment sizing triangulated against top-down IT spending benchmarks across the analysis window.
Cross-referencing historical adoption curves with panel input from vendor sales leadership and systems integrator delivery heads shaped the analytical framework. Deployment model, organization size, vertical industry, and regional regulatory cluster segmentation dimensions were modeled throughout the forecast period. CAGRs were derived from elasticity-adjusted replacement cycle projections and compliance-driven procurement acceleration patterns. Cloud migration velocity under EU AI Act deadlines and India digital infrastructure scaling initiatives served as primary forecast inputs.
The model holds under stable regulatory enforcement timelines; deviation in EU AI Act implementation rigor or RBI data localization waiver policies would shift replacement cycle assumptions. Forecasts reflect documented assumptions on certification penetration rates and hyperscaler geographic expansion commitments. Practitioners should monitor BIS certification requirement announcements and state-level India data center tender awards for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Sweepstakes Software Market
Software & Services
Global Subscription Billing Software Market
Software & Services
Data Integration Software/Tool Market
Software & Services
Family Law Software Market
Software & Services
Business Spend Management (BSM) Software Market
Software & Services
Family Office Software Solutions Market
Software & Services
Global Customer Communications Management (CCM) Software Market
Software & Services
Collaborative Authoring Tools Market
Software & Services
Medical Equipment Repair Software Market
Software & Services
Fitness App Market
Software & Services
Machine Translation Software Market
Software & Services
Global Kiosk Software Market
Software & Services
Backend-As-A-Service Market
Software & Services
Global Permit Management Software Market
Software & Services
Information Technology Service Management (ITSM) Market
Software & Services
Content Moderation Software Market