
 Animation Design Software Market | 2026-2036
Animation Design Software Market Size, Share, and Industry Trends Forecast 2026-2036
Animation Design Software Market Analysis
Real-time rendering and AI-assisted keyframe interpolation is narrowing the gap between pre-visualization and final output in animation pipelines. Autodesk Inc. leverages its dominance in architectural visualization tools to cross-sell motion design suites into adjacent industrial markets. Adobe Inc. sustains channel control through Creative Cloud bundling that locks in monthly recurring revenue from independent creators and mid-size studios. Maxon Computer GmbH specializes in motion graphics through Cinema 4D, occupying the premium tier where broadcast designers and commercial production houses concentrate spending.
Animation design software comprises digital toolsets for creating, editing, and compositing moving imagery through vector-based drawing, polygonal modeling, rigging systems, and shader-based rendering engines operating at 24 to 60 frames per second for broadcast and theatrical delivery. The primary commercial purpose spans entertainment content production, advertising, architectural visualization, and interactive media where temporal motion communicates narrative or functional information. Cloud-based deployment is capturing share fastest as studios distribute rendering workloads across elastic compute clusters, while 3D animation retains the deepest margin pools due to complexity premiums in feature film and AAA gaming pipelines. Character animation functionality commands sustained investment because rigging and performance capture tools determine production efficiency in high-volume series work.
FCC content guidelines in the United States, EMA media directives in Europe, and METI digital content promotion frameworks in Japan collectively shape product safety standards, intellectual property enforcement, and subsidy eligibility for animation software vendors. GDPR compliance requirements in Europe and emerging state-level privacy statutes in the United States add data governance layers to cloud-based collaboration features. Stakeholders must monitor how generative AI training data disputes and evolving copyright frameworks reshape licensing models and creator tool preferences.
Market Dynamics
Real-time rendering engines and AI-assisted interpolation are compressing production timelines from months to weeks, forcing incumbent vendors to rearchitect licensing models around per-minute cloud compute rather than perpetual seat sales.
Growth Catalysts
- Streaming Content Arms Race:Netflix, Disney+, and Amazon Prime Video are expanding original animated series slates, driving seat demand for 3D character animation suites among mid-tier production houses in Los Angeles and Seoul.
- METI Digital Content Promotion:Japan's Ministry of Economy, Trade and Industry subsidizes software procurement for domestic studios, lowering adoption barriers for cloud-native pipeline tools in Tokyo's animation cluster.
- Generative In-Betweening:Machine learning models trained on motion capture databases now automate tween frame generation, cutting labor hours for Korean webtoon adaptation studios by half on volume series.
Market Restraints
- GPU Supply Concentration:Cloud rendering workloads depend on NVIDIA datacenter silicon, creating input cost volatility when Taiwanese foundry capacity tightens during semiconductor cycle peaks.
- GDPR Data Residency:European studios face structural friction storing rendered assets on cross-border servers, forcing redundant infrastructure investment or compliance-delayed project launches.
- Open-Source Substitution:Blender's 3.0+ releases displace entry-level commercial seats among independent creators, capping pricing power at the hobbyist and freelance tier.
Strategic Opportunities
- India's Untapped VFX Pipeline:Mumbai and Bangalore post-production houses are upgrading from rotoscoping to full 3D character work, creating white space for rigging tool vendors with localized training programs.
- Virtual Production Convergence:Game engines and LED wall systems are merging with traditional animation pipelines, enabling real-time previz for automotive commercial shoots in Stuttgart and Detroit.
- FCC Children's Content Mandates:US broadcast quota requirements sustain demand for educational animation software modules that simplify compliance tagging and accessibility overlay generation.
Industry Challenges
- Technical Artist Scarcity:Pipeline TDs who bridge Python scripting and shader optimization command premium wages, constraining studio scaling in Vancouver and London.
- Legacy Tool Integration:Proprietary formats from 1990s-era systems persist in Japanese feature studios, complicating cloud migration and AI-assisted workflow adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animation Design Software Market |
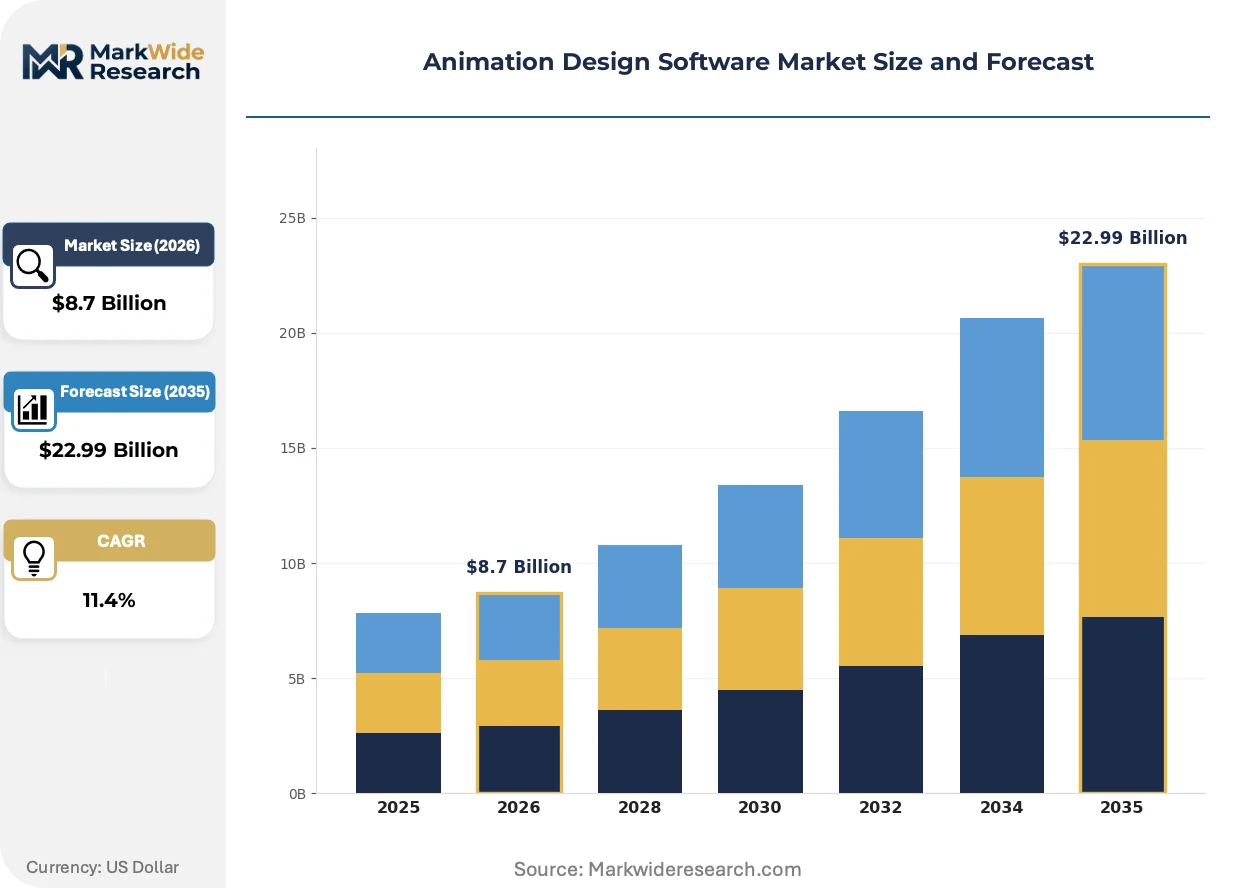
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Animation, 3D Animation, Stop Motion, Motion Graphics Deployment: On-Premise, Cloud-Based, Hybrid, Web-Based End User: Media & Entertainment, Education, Marketing, Gaming Functionality: Character Animation, Visual Effects, Storyboarding, Rendering |
| Companies Covered | Adobe Inc., Autodesk Inc., Maxon Computer GmbH, Side Effects Software Inc., Pixar, Blender Foundation, NVIDIA Corporation, Toon Boom Animation Inc., The Foundry Visionmongers Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animation Design Software Market Emerging Trajectories
Cloud-native architecture and generative AI are rewriting how animation assets move through production, collapsing the distance between concept art and final pixel.
Neural radiance fields (NeRF) are virtualizing volumetric scene capture from 2D reference plates. Automotive and architectural visualization houses in Munich and Detroit now deploy NeRF-based environments for camera-aware previz, eliminating physical set construction for one-third of commercial spots. The technology is virtualizing location scouting budgets into software licensing spend.
The EU AI Act's transparency requirements for generative tools are mandating training data disclosure in animation software shipped to European studios. Vendors must now document source datasets for style transfer and motion synthesis features, adding compliance engineering headcount. French and German public broadcasters are prioritizing procurement from suppliers with certified ethical AI pipelines.
Subscription fatigue among freelance animators is fragmenting buyer concentration, with solo creators cycling between month-to-month seats rather than annual commitments. Tool vendors respond with modular micro-licensing for specific functions like fluid simulation or cloth dynamics. This behavioral shift is most visible in Brazil's growing independent animation sector, where creators assemble bespoke pipelines from competing cloud services.
Animation Design Software Market Segmentation
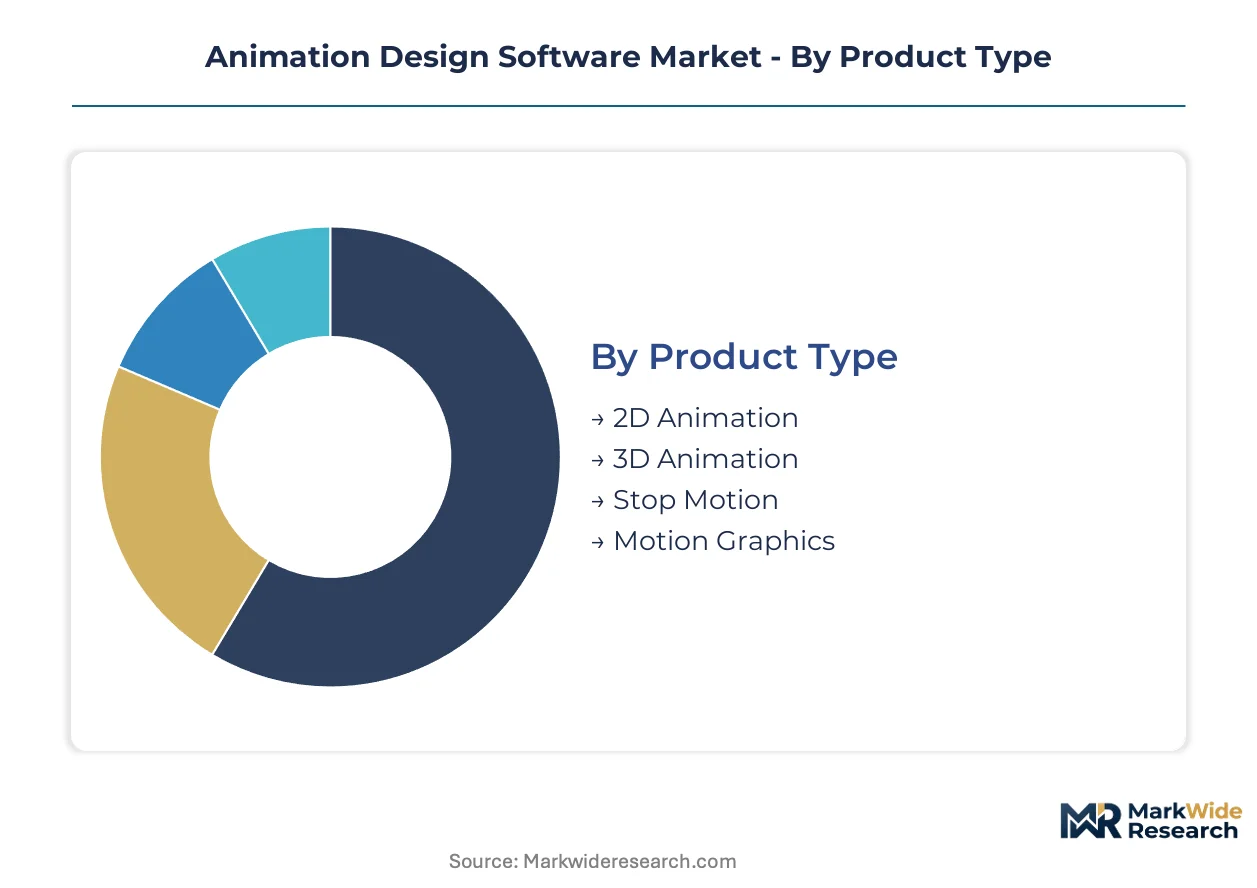
Animation design software segments reflect divergent technical requirements across production pipelines. Cloud-native tools and AI-assisted functionality are redistributing spending patterns as studios rearchitect workflows around elastic compute and automated in-betweening.
Product Type:
Cost tier separates hobbyist-accessible tools from enterprise-grade suites commanding complexity premiums.
- 2D Animation:Vector-based drawing systems with frame-by-frame or rigged puppet workflows dominate webtoon adaptation studios in Seoul. Korean production houses deploy these tools for volume series where automated tweening compresses delivery schedules.
- 3D Animation:Polygonal modeling, rigging systems, and shader-based rendering engines operate at 24 to 60 frames per second for theatrical and AAA gaming delivery. Feature film pipelines in Los Angeles and Tokyo concentrate spending here due to per-minute complexity premiums.
- Stop Motion:Frame capture and onion-skinning utilities serve boutique commercial houses and independent filmmakers.
- Motion Graphics:Broadcast designers in New York and London leverage these tools for title sequences and brand identity systems.
3D Animation holds installed capacity. Motion Graphics is rotating up the share rankings.
Deployment:
Application context determines whether studios prioritize data sovereignty or elastic scalability.
- Cloud-Based:Elastic compute clusters distribute rendering workloads across geographically dispersed nodes. Mid-tier production houses in Vancouver and Mumbai adopt these pipelines to avoid capital-intensive server farms.
- Hybrid:Local workstations handle sensitive pre-production assets while burst rendering shifts to cloud instances. Japanese feature studios favor this architecture to satisfy METI subsidy compliance while accessing scalable compute.
- On-Premise:Legacy installations persist in facilities with proprietary format dependencies.
- Web-Based:Browser-native tools capture freelance creators and educational institutions.
Cloud-Based deployment is climbing the fastest. Hybrid configurations retain defensive positions in regulated markets.
End User:
Customer type dictates feature prioritization and pricing sensitivity across the buyer base.
- Media & Entertainment:Streaming platforms expanding original animated slates drive seat demand for character animation suites. Netflix, Disney+, and Amazon Prime Video procurement decisions cascade through Los Angeles and Seoul production houses.
- Gaming:Real-time engines and performance capture tools dominate AAA pipeline investment. Studios in Tokyo and Montreal prioritize rigging efficiency for high-volume character output.
- Education:Institutional licensing concentrates in design schools and vocational programs.
- Marketing:Commercial production houses and in-house brand teams deploy motion graphics for campaign delivery.
Media & Entertainment holds installed capacity. Gaming is gaining share fastest.
Functionality:
Volume intensity in series production elevates specific workflow modules above others.
- Character Animation:Rigging systems and performance capture tools determine production efficiency in high-volume series work. Korean webtoon studios invest heavily here as machine learning models automate tween frame generation.
- Rendering:Shader-based engines and cloud-distributed compute clusters finalize pixel output. GPU supply concentration from NVIDIA datacenter silicon creates input cost volatility for this module.
- Visual Effects:Simulation tools for fluid, cloth, and particle dynamics serve feature film and commercial pipelines.
- Storyboarding:Pre-visualization utilities bridge concept art and animated sequence planning.
Character Animation holds installed capacity. Rendering is expanding most quickly as cloud pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean animation studios export webtoon adaptation services to Japanese broadcasters and global streaming platforms, establishing Seoul as the primary trade-flow corridor for volume series production in Asia-Pacific.
United States
Netflix, Disney+, and Amazon Prime Video procurement decisions cascade through Los Angeles production houses, expanding seat demand for 3D character animation suites. FCC children's content mandates sustain demand for educational animation software modules. Burbank and Glendale clusters concentrate feature film pipeline investment where real-time rendering engines compress pre-visualization timelines.
Japan
METI digital content promotion frameworks subsidize software procurement for domestic studios, lowering adoption barriers for cloud-native pipeline tools. The country's national media regulator enforces broadcast standards that shape product safety requirements for animation software vendors. Tokyo's animation cluster retains proprietary format dependencies from 1990s-era systems, complicating cloud migration for established feature studios.
South Korea
Webtoon adaptation studios deploy automated tweening systems to cut labor hours by half on volume series, driving investment in machine learning-enabled character animation tools. The country's national broadcasting regulator oversees content guidelines that influence software feature requirements. Seoul's production houses concentrate spending on 2D vector-based systems for streaming platform delivery schedules.
India
Mumbai and Bangalore post-production houses upgrade from rotoscoping to full 3D character work, creating white space for rigging tool vendors with localized training programs. The country's national media and technology regulator shapes digital content standards affecting software procurement decisions. Maharashtra and Karnataka clusters attract foreign studio partnerships as labor cost arbitrage destinations for mid-tier animation services.
Germany
Automotive and architectural visualization houses in Munich deploy NeRF-based environments for camera-aware previz, eliminating physical set construction for commercial spots. GDPR data residency requirements force redundant infrastructure investment or compliance-delayed project launches for studios storing rendered assets on cross-border servers. Stuttgart's commercial production sector merges game engines with LED wall systems for real-time automotive shoots.
Animation Design Software Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidated control at the top contrasts with fragmentation among independent creators and mid-tier studios. Three archetypes dominate: ecosystem bundlers with subscription platforms, motion graphics specialists with broadcast design focus, and open-source disruptors with zero-cost entry points. Competitive moves concentrate on cloud licensing rearchitecture and generative AI feature integration.
Within the ecosystem bundler tier, Adobe Inc. and Autodesk Inc. occupy positions defined by Creative Cloud and architectural visualization cross-selling respectively. Maxon Computer GmbH represents the product-specialist archetype with Cinema 4D concentration. Side Effects Software Inc. anchors the technical premium segment where simulation-heavy pipelines command complexity premiums. Blender Foundation exemplifies open-source substitution pressure at the freelance and educational entry tier.
| Leading Market Players |
|---|
| Adobe Inc. |
| Autodesk Inc. |
| Maxon Computer GmbH |
| Side Effects Software Inc. |
| Pixar |
| Blender Foundation |
| NVIDIA Corporation |
| Toon Boom Animation Inc. |
| The Foundry Visionmongers Ltd. |
| Others |
Supply Flow & Price Mechanics
NVIDIA datacenter silicon concentration creates input cost volatility that compresses margin spreads between cloud-native subscription tiers and on-premise perpetual licenses while forcing studios toward hybrid deployment architectures. GPU supply tightness during Taiwanese foundry cycle peaks directly determines whether mid-tier production houses in Vancouver and Mumbai absorb cost spikes or defer pipeline upgrades.
Pricing Analysis
Current-generation cloud-per-minute compute commands premium positioning against prior-generation perpetual seat licenses and emerging next-generation AI-assisted bundles. Three-tier pricing structure across premium, standard, and economy levels separates enterprise feature film pipelines from mid-tier series producers and freelance creators. Cost compression in the standard tier intensifies because Blender's zero-cost entry displaces commercial seats among independent animators. Freelance creators in Brazil's independent sector exhibit highest price sensitivity, while Los Angeles feature studios demonstrate lowest sensitivity due to complexity premiums in theatrical delivery.
Supply Chain Analysis
Extended payment terms from cloud hyperscalers now finance rendering workload distribution for studios lacking capital-intensive server farm investment. Hardware supply concentrates in Taiwan, South Korea, and the United States where NVIDIA datacenter silicon, Samsung HBM memory, and Intel processor architectures originate. Software licensing draws from proprietary engine development in the United States, open-source community contribution in Europe, and specialized plugin ecosystems from Japan. Single-source vulnerability around Taiwanese foundry capacity creates structural risk for GPU-dependent rendering pipelines. Distribution runs through direct vendor cloud portals and regional value-added resellers serving studio clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Animation design software constitutes a defensive-moat market where Creative Cloud subscription bundling generates network effects that lock in creator workflows and raise switching costs for established studios.
For Market Incumbents: Pre-empt open-source substitution by embedding generative AI in-betweening as default workflow infrastructure rather than premium add-on modules. Acquire specialized rigging tool vendors in Seoul and Mumbai to capture webtoon adaptation and VFX pipeline growth before regional champions consolidate. Channel control through integrated asset marketplaces represents the critical lever against modular micro-licensing fragmentation. For New Entrants and Emerging Players: Pursue India's untapped VFX pipeline where Mumbai and Bangalore post-production houses upgrade from rotoscoping to full 3D character work without incumbent format lock-in. Target educational institutions in São Paulo and Mexico City where institutional licensing concentrates before vendor relationships solidify. Freemium cloud-native deployment with localized training programs offers the most penetrable go-to-market angle against perpetual license inertia. For Investors and Strategic Acquirers: Technical premium specialists with simulation-heavy pipeline concentration anchor acquisition target archetypes where complexity premiums sustain margin structures. Cloud-native pipeline tool vendors with METI subsidy eligibility or GDPR-compliant European infrastructure command defensive positioning in regulated markets. Watch generative AI training data disclosure requirements under the EU AI Act as inflection indicator for compliance engineering cost structures and ethical AI procurement preferences among French and German public broadcasters.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Creative Cloud bundling locks monthly recurring revenue from independent creators and mid-size studios. |
| Acquisition of Specialist Firm | Rigging tool vendors in Seoul capture Korean webtoon adaptation studio spending. |
| Strategic Partnership | Cloud hyperscaler alliances distribute rendering workloads across elastic compute clusters. |
| Product Launch | AI-assisted in-betweening modules compress production timelines for volume series. |
| Geographic Expansion | Localized training programs in Mumbai penetrate India's VFX pipeline upgrade cycle. |
Methodological Framework
The analysis maps 2D vector-based systems, 3D polygonal pipelines, motion graphics suites, and cloud-native deployment architectures, each validated through animation studio technical directors, streaming platform procurement officers, software vendor product managers, and educational institution licensing administrators. Primary interviews with pipeline TDs in Vancouver and London, cloud infrastructure leads at Los Angeles production houses, and METI subsidy program officials in Tokyo combined with secondary validation from SEC filings, EMA media directive documentation, and EU AI Act transparency requirement filings. Bottom-up seat deployment estimates and top-down content production budget analysis triangulate market sizing.
Assumption sets held streaming platform original content budgets and GPU supply cycle conditions fixed while varying generative AI adoption rates and open-source substitution velocity across the projection horizon. Segmentation dimensions modeled include product type, deployment architecture, end-user vertical, and functionality module with regional adoption patterns. CAGRs derive from elasticity-adjusted seat demand curves and complexity-premium pricing trajectories. Forecast inputs incorporate cloud rendering workload growth and AI-assisted workflow penetration assumptions.
Sensitivities concentrate around generative AI training data disputes, evolving copyright frameworks, and Taiwanese foundry capacity cycles. Forecasts reflect documented assumptions regarding streaming content arms race sustainability and regulatory compliance cost trajectories. Macroeconomic contraction in entertainment advertising, semiconductor supply disruption, or generative AI capability breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Digital Onboarding Platform Market
Software & Services
Equipment Management Software Market
Software & Services
Lawn Care Software Market
Software & Services
Payroll and HR Software Market
Software & Services
Attendance Management Software Market
Software & Services
CAD Modeling Software Market
Software & Services
North America Enterprise Resource Planning Market
Software & Services
Global Employee Engagement Software Market
Software & Services
Eclinical Solutions and Software Market
Software & Services
Enterprise Capture Software Market
Software & Services
Cloud-Based Payroll Software Market
Software & Services
General Ledger Accounting Software Market
Software & Services
Global Distribution Software Market
Software & Services
Global App Design Software Market
Software & Services
Asia-Pacific Digital Signage Software Market
Software & Services
Global Offshore Software Development Market