
 Fitness App Market | 2026-2036
Fitness App Market Size, Share, and Industry Trends Forecast 2026-2036
Fitness App Market Intelligence
The fusion of on-device machine learning with cloud-based AI models is reconfiguring how fitness applications deliver personalized user experiences. Nike leverages its vast user data to refine workout recommendations within its ecosystem. Google integrates its fitness platforms deeply with the Android operating system and its Wear OS. Strava, Inc. differentiates through its focus on social features and competitive community-building for cyclists and runners.
Fitness apps are software programs designed for mobile or wearable devices that track, record, and analyze a user's physical activity, nutrition, and other health-related metrics. They often utilize device sensors like accelerometers and GPS to gather raw data for metrics such as steps taken, distance covered, and calories burned. Mobile application deployments dominate the market, while comprehensive workout planner and nutrition tracker functionalities represent core value propositions. Feature sets built around wearable integration and progress tracking are critical for engaging and retaining fitness enthusiasts, the primary end-user segment.
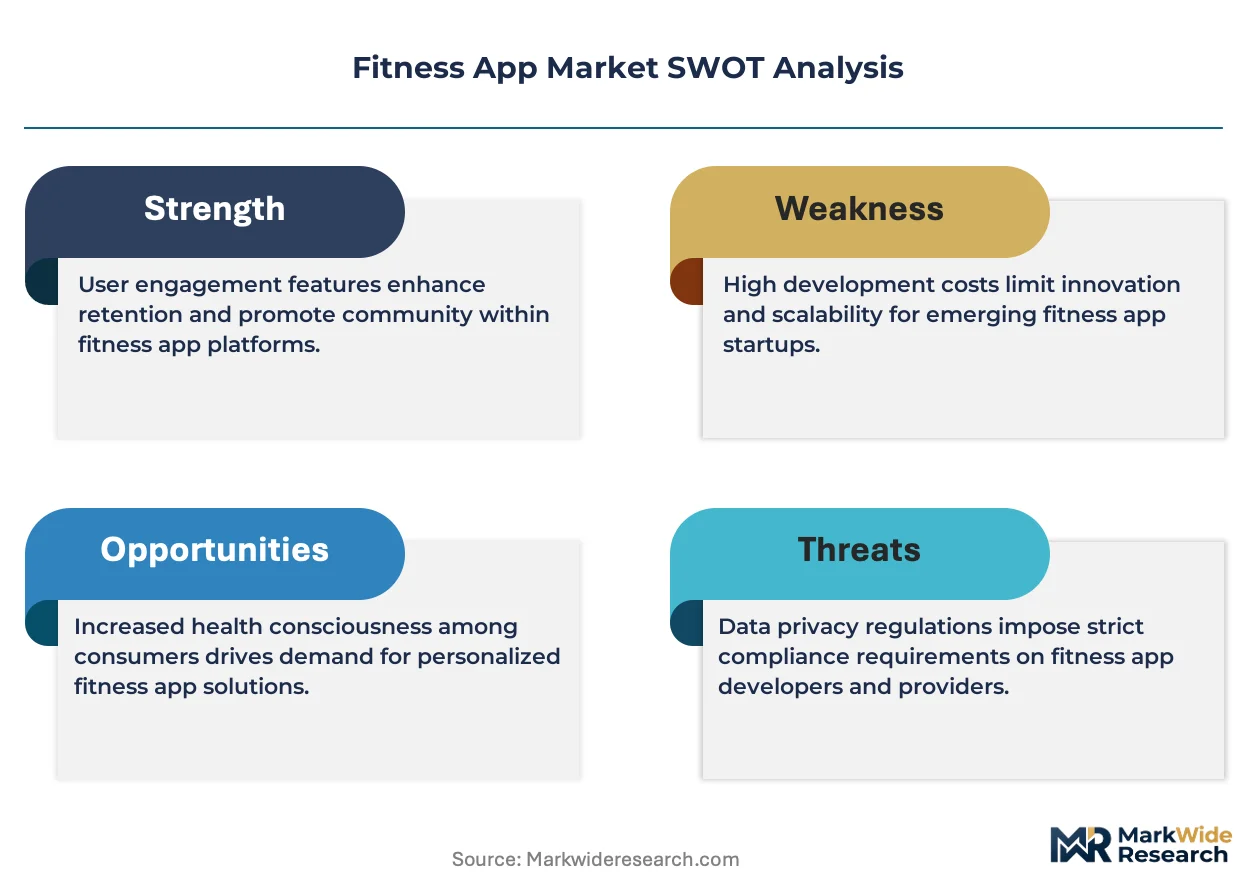
Data privacy regulations, including Europe's GDPR and aspects of the US HIPAA where health data is involved, impose strict requirements on user consent and data handling. In China, regulations from the MIIT and standards from the SAMR govern app distribution and data localization, shaping market access for non-Chinese companies. App developers must navigate this complex regulatory patchwork while deciding where to invest in AI-driven personalization versus community-based social features to drive user engagement.
Market Dynamics
The central tension shaping the fitness app market is the conflict between delivering hyper-personalized user experiences via AI and navigating an increasingly stringent global data privacy landscape, including regulations like GDPR.
Growth Catalysts
- AI Personalization:The use of artificial intelligence to generate customized fitness and nutrition plans enhances user engagement, driving adoption.
- Wearable Device Proliferation:High penetration of smartwatches in markets like the United States and Germany provides constant sensor data for app functions.
- Corporate Wellness Initiatives:Businesses increasingly offer fitness app subscriptions as part of employee wellness programs to promote preventative health.
Market Restraints
- Regulatory Complexity:Navigating a patchwork of data privacy laws like Europe’s GDPR creates significant compliance overhead for developers.
- High User Churn:The high rate of user abandonment after initial download remains a structural challenge due to failures in habit formation.
- Platform Dependency:Developer monetization and feature deployment are constrained by the policies and commissions of dominant app stores.
Strategic Opportunities
- Geriatric Population Focus:Developing apps for older adults, focusing on low-impact exercise and mobility, addresses an underserved demographic.
- B2B2C Channels:Partnering with insurance companies to offer apps as preventative care tools creates a new distribution and revenue channel.
- Enhanced Gamification:Integrating competitive leaderboards and team challenges can improve long-term user retention and build community effects.
Industry Challenges
- Cross-Platform Interoperability:Ensuring seamless data synchronization across fragmented iOS, Android, and wearable operating systems requires continuous, costly development effort.
- Data Accuracy Validation:Maintaining the accuracy of sensor-derived metrics like calorie burn is a technical challenge that can undermine user trust.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fitness App Market |
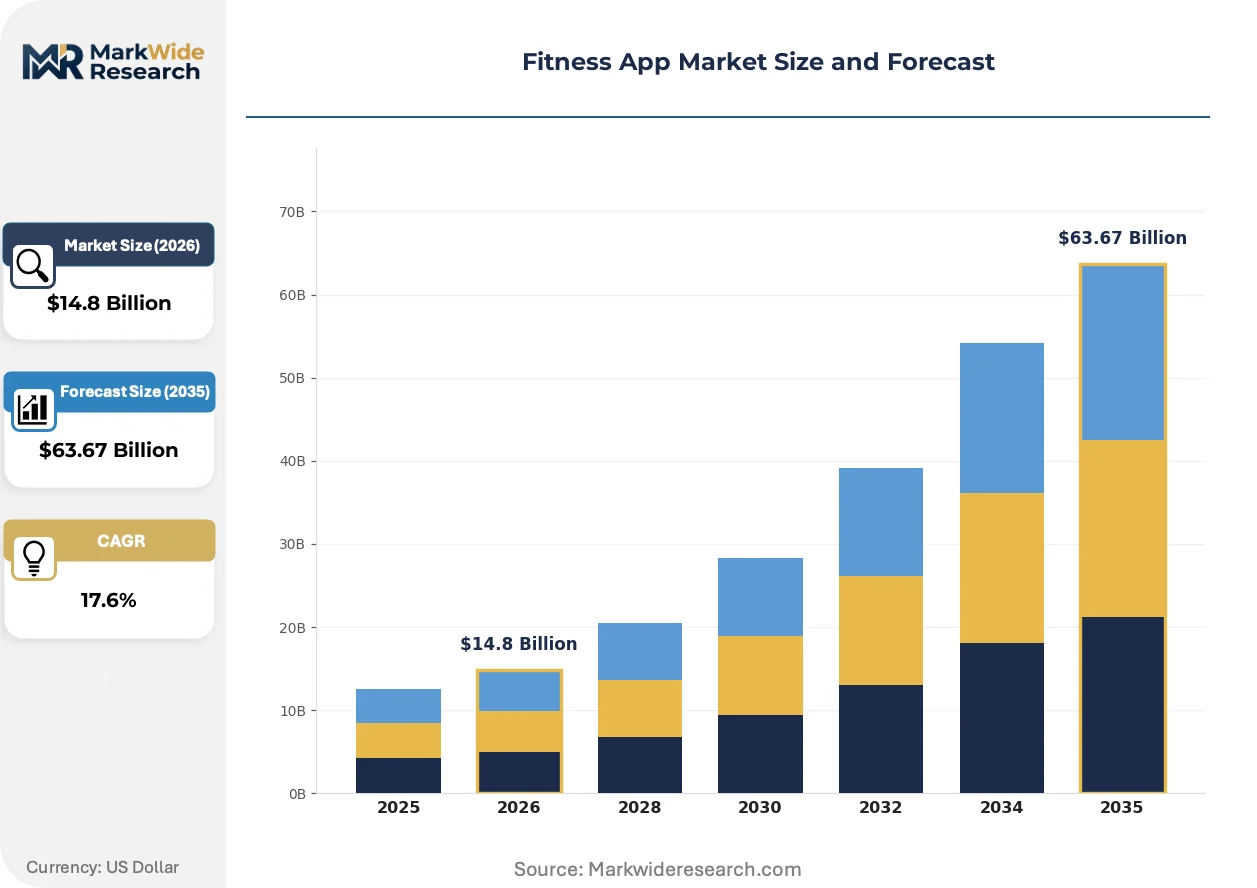
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $63.67 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
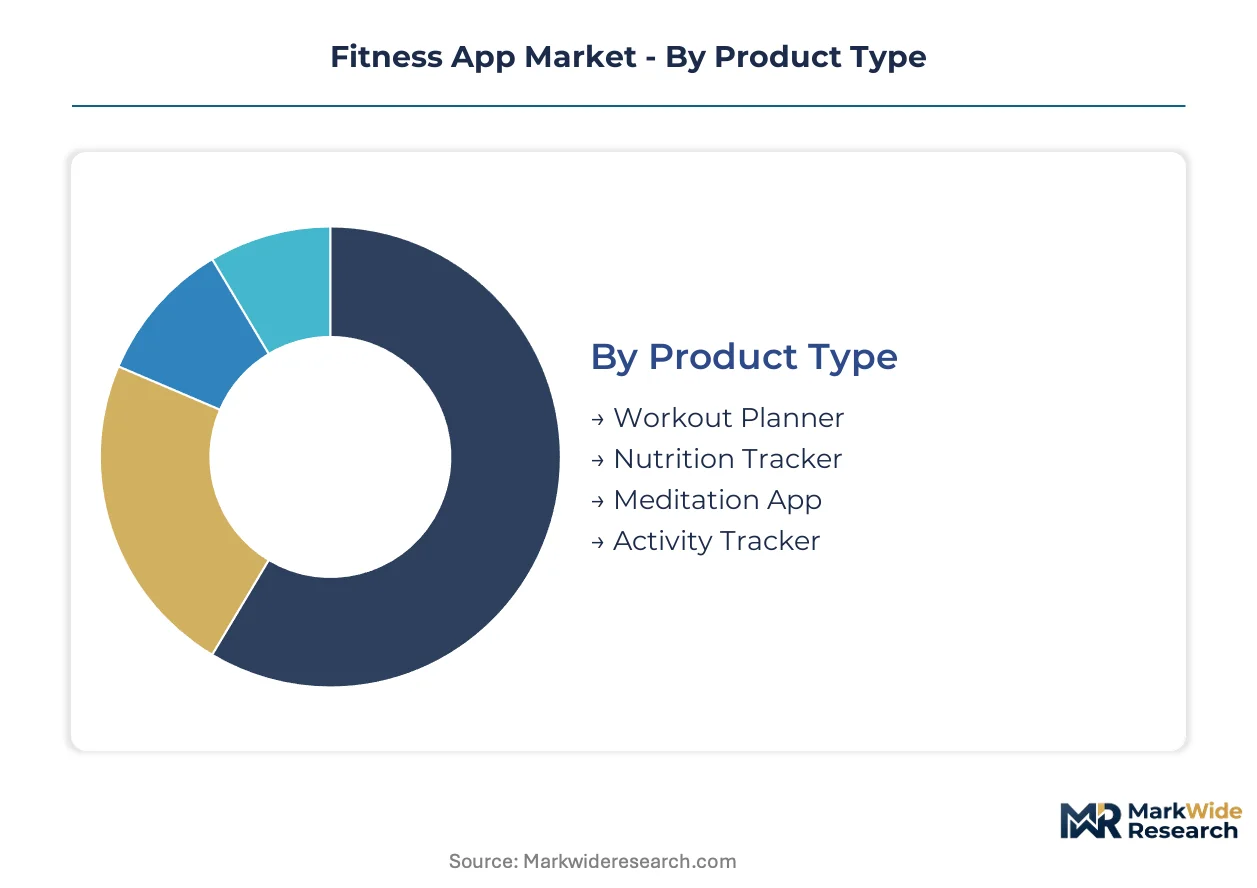
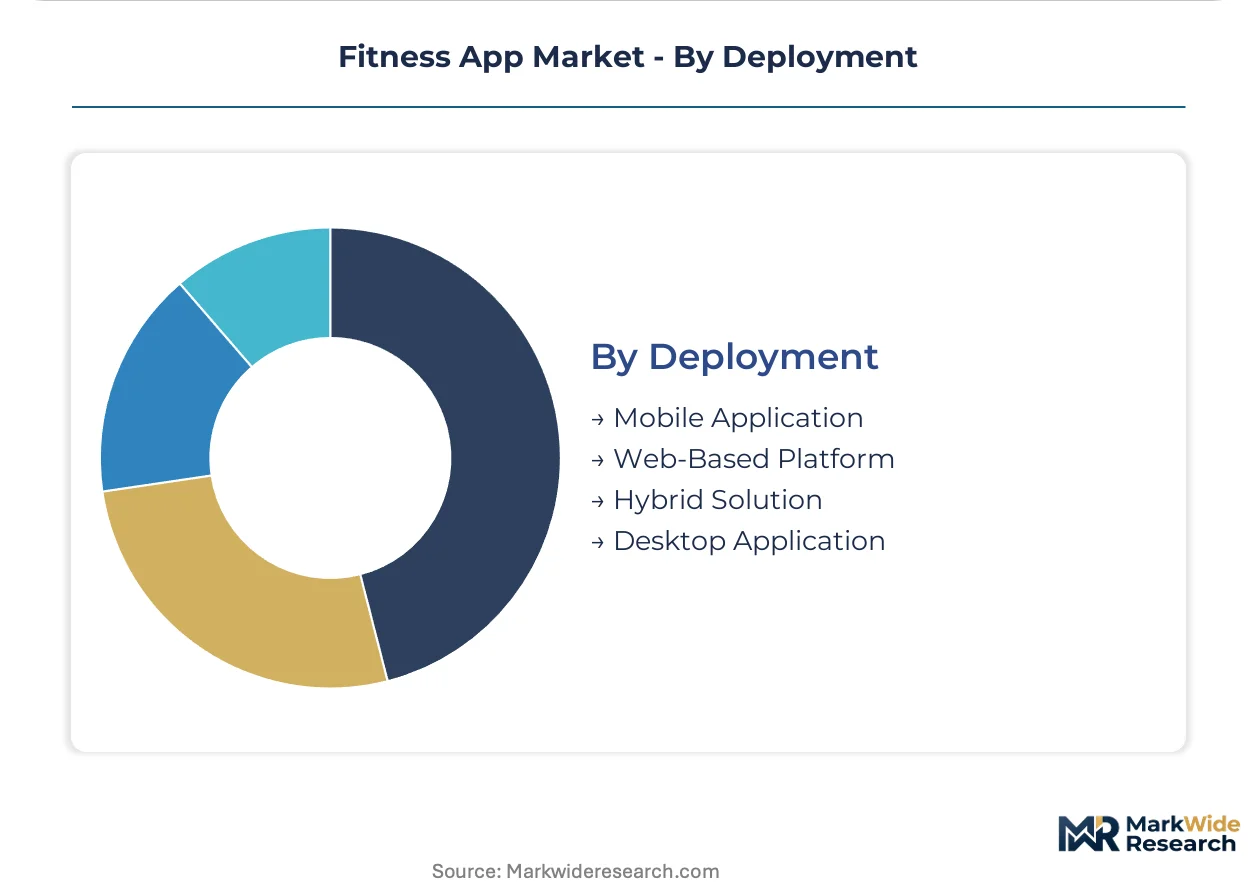
| Segmentation | Product Type: Workout Planner, Nutrition Tracker, Meditation App, Activity Tracker End User: Fitness Enthusiasts, Casual Users, Personal Trainers, Health Coaches Feature: Wearable Integration, Social Sharing, Custom Challenges, Progress Tracking Deployment: Mobile Application, Web-Based Platform, Hybrid Solution, Desktop Application |
| Companies Covered | Under Armour, Inc., Samsung Electronics Co., Ltd., MyFitnessPal, Inc., Strava, Inc., Peloton Interactive, Inc., Google (Alphabet Inc.), Adidas AG, Noom, Inc., Nike, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fitness App Market Strategic Shifts & Innovations
The market's evolution is defined by a shift from passive data logging to proactive, intelligent health management. This is powered by synthesizing real-time biometric data from wearables with sophisticated analytical models to guide user behavior.
On-device machine learning processes biometric data directly on a user's smartphone or wearable, bypassing cloud latency. Fitness enthusiasts are adopting this for instant, actionable insights. This local processing is virtualizing the feedback loop of a personal coach, offering real-time form correction and intensity adjustments during a workout.
Europe's AI Act establishes a risk-based classification for artificial intelligence, impacting how apps generate health recommendations. The regulation mandates transparency for AI systems, including personalized fitness and nutrition planners. Developers targeting the EU are now auditing their algorithms and data governance practices to ensure compliance and avoid market restrictions.
Consumer preference is moving toward service bundling, where fitness apps are included within broader subscription packages. This model challenges the standalone freemium app, favoring platforms integrated into ecosystems offered by technology companies. The shift is most pronounced in North America, where users seek to consolidate digital spending.
Fitness App Market Segmentation
Understanding the distinct segments within the fitness app market is critical for developers to tailor product offerings and marketing strategies effectively. This segmentation highlights varying user needs, technological preferences, and engagement models that shape competitive positioning.
Product Type:
The product type segmentation reveals varying development cycles and user engagement patterns within the fitness app ecosystem.
- Workout Planner:Workout Planner applications provide structured exercise routines, often with video demonstrations and progress tracking capabilities. Demand for these tools concentrates in developed markets like the United States, driven by fitness enthusiasts seeking guided training programs.
- Activity Tracker:Activity Tracker apps utilize device sensors to monitor physical movement, including steps, distance, and calories burned. Their widespread adoption is fueled by the proliferation of wearable devices across Germany and other European nations.
- Nutrition Tracker:Nutrition Tracker platforms enable users to log food intake and monitor macronutrient consumption, supporting dietary goals.
- Meditation App:Meditation App offerings focus on mental wellness and stress reduction, providing guided sessions for mindfulness and relaxation.
Activity Tracker anchors the volume base while Nutrition Tracker gains share at the steepest rate.
End User:
The end-user classification highlights distinct engagement levels and monetization strategies across different consumer groups.
- Fitness Enthusiasts:Fitness Enthusiasts represent individuals highly committed to physical activity, seeking advanced features like personalized plans and detailed performance analytics. This segment drives premium subscription uptake and sustained app usage.
- Personal Trainers:Personal Trainers leverage fitness apps to manage client workouts, track progress, and deliver remote coaching services. Their adoption is expanding as digital tools enhance their service delivery and client reach.
- Casual Users:Casual Users engage with fitness apps for general health awareness and basic activity monitoring, often preferring free or freemium models.
- Health Coaches:Health Coaches utilize these platforms for broader wellness guidance, integrating exercise and nutrition advice for their clientele.
Fitness Enthusiasts consistently represent the primary revenue stream, though Health Coaches are expanding their platform usage.
Feature:
Feature-based segmentation demonstrates the core utility and value propositions driving user adoption within fitness applications.
- Wearable Integration:Wearable Integration enables seamless data synchronization between fitness apps and smart devices, providing real-time biometric feedback. This feature is critical for users in high-penetration markets like the US and Germany.
- Progress Tracking:Progress Tracking functionalities allow users to monitor their performance over time, visualizing improvements in strength, endurance, or weight management. This sustains long-term engagement for dedicated users.
- Social Sharing:Social Sharing features facilitate user interaction, allowing individuals to share achievements and engage with friends or community groups.
- Custom Challenges:Custom Challenges provide personalized fitness goals and competitive elements, motivating users through tailored objectives.
Wearable Integration remains a foundational requirement, with Social Sharing features increasingly influencing user stickiness.
Deployment:
Deployment options outline the technical infrastructure and market penetration of fitness app solutions across various platforms.
- Mobile Application:Mobile Application deployment involves native apps designed for iOS and Android smartphones, offering optimal performance and sensor integration. This remains the dominant access point for the majority of fitness app users globally.
- Hybrid Solution:Hybrid Solution deployments combine web technologies with native app wrappers, enabling cross-platform compatibility and faster development cycles. These solutions balance broad reach with device-specific capabilities.
- Web-Based Platform:Web-Based Platforms provide browser-accessible fitness services, often used for supplementary content or administrative functions.
- Desktop Application:Desktop Application deployments are less common but serve niche use cases requiring extensive data processing or professional-grade tools.
Mobile Application deployment commands the largest user base, while Hybrid Solutions offer increasing flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The flow of digital health innovation from developed markets like the United States influences adoption patterns across the global fitness app ecosystem. These regions often set trends in personalized AI and wearable integration, which subsequently diffuse into other advanced economies and emerging markets. Regulatory frameworks also vary significantly, impacting market access and operational strategies for app developers.
United States
Demand for fitness applications in the United States is driven by high wearable device penetration and consumer preference for personalized health management. The country's HIPAA regulations impose strict requirements on health data handling, influencing app design and data privacy policies. Silicon Valley and other tech hubs continue to innovate in AI-driven personalization and real-time biometric feedback.
Germany
Germany exhibits strong demand for activity trackers and workout planners, supported by a health-conscious population and robust digital infrastructure. Europe's GDPR and the EU AI Act significantly impact how German developers manage user data and deploy AI for health recommendations. Munich and Berlin serve as key centers for health tech startups, fostering innovation in data-secure fitness solutions.
China
China's fitness app market is expanding rapidly, fueled by increasing smartphone adoption and government initiatives promoting public health. Regulations from the MIIT and standards from the SAMR govern app distribution and data localization, creating unique market entry challenges. Major tech cities like Beijing and Shenzhen are at the forefront of integrating fitness apps with broader digital ecosystems.
United Kingdom
The United Kingdom shows strong user engagement with fitness apps, particularly for progress tracking and social sharing features. UK data protection laws, post-Brexit, largely align with GDPR principles, demanding careful data governance from app providers. London's vibrant tech scene supports the development of innovative fitness platforms, often focusing on community building and gamification.
Japan
Japan's fitness app adoption is growing, particularly among younger demographics, with a focus on mental wellness and low-impact exercise. The country's personal information protection laws guide how fitness apps collect and process user data, emphasizing consent and transparency. Tokyo remains a central hub for technology development, including advancements in sensor-based health monitoring.
Fitness App Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, with large technology conglomerates coexisting with specialized fitness platforms. This market structure reflects varying business models, from comprehensive health ecosystems to niche activity tracking solutions. Strategic archetypes include ecosystem integrators, specialized performance trackers, and wellness-focused providers. Dominant competitive moves involve strategic partnerships with wearable manufacturers and continuous feature diversification to enhance user retention.
Ecosystem integrators often leverage their broad user bases and hardware integration capabilities; Google, for example, deeply embeds its fitness platforms within the Android operating system and Wear OS. Specialized performance trackers, such as Strava, Inc., differentiate through community features and competitive elements tailored for specific athletic pursuits like cycling and running. Meanwhile, Nike, Inc. exemplifies a brand-driven approach, refining workout recommendations within its extensive user ecosystem and leveraging its strong brand identity to attract and retain fitness enthusiasts.
| Leading Market Players |
|---|
| Under Armour, Inc. |
| Samsung Electronics Co., Ltd. |
| MyFitnessPal, Inc. |
| Strava, Inc. |
| Peloton Interactive, Inc. |
| Google (Alphabet Inc.) |
| Adidas AG |
| Noom, Inc. |
| Nike, Inc. |
| Others |
Cost & Logistics Intelligence
Overcapacity in freemium fitness app models drives aggressive user acquisition strategies, impacting premium subscription pricing. This utilization signal shapes both developer behavior and consumer willingness to pay for advanced features.
Pricing Analysis
The pricing gap between current-generation fitness apps offering basic tracking and next-generation AI-driven platforms influences consumer choice. Subscription-based models dominate, often employing freemium tiers to attract users. Price differentiation stems from the depth of personalized plans and seamless wearable integration. Pricing pressure stems from abundant free alternatives, yet advanced AI features command higher value. Casual Users exhibit the highest price sensitivity, while Fitness Enthusiasts readily invest in premium subscriptions.
Supply Chain Analysis
Regulatory complexity across Europe's GDPR and China's MIIT standards presents a significant supply chain risk for fitness app developers seeking global reach. Geographic concentration for core development talent exists in technology hubs within the United States and Germany, alongside emerging centers in China. Raw material dependencies include advanced AI models and access to robust cloud infrastructure. Distribution runs primarily through dominant mobile application stores, which exert considerable influence over market access and monetization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fitness app market represents a high-growth disruption, driven by the continuous integration of AI for hyper-personalized user experiences. This technological inflection reshapes how individuals engage with health and wellness platforms.
For Market Incumbents: Insulate core user bases by deepening ecosystem integration, particularly with dominant operating systems like Android and Wear OS. Invest heavily in AI R&D to maintain a lead in personalized plan generation, mitigating the threat of user churn from less sophisticated offerings. Strategic partnerships with wearable manufacturers secure critical sensor data access. Continuous compliance with global data privacy regulations like GDPR also protects market position.
For New Entrants and Emerging Players: Establish a beachhead in underserved demographics, such as the geriatric population, focusing on low-impact exercise and mobility. Target corporate wellness initiatives through B2B2C channels, offering fitness app subscriptions as preventative health tools. Enhanced gamification features and team challenges provide a compelling go-to-market angle, fostering community effects and user retention in niche segments like cycling or running.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-driven personalization platforms, signaling increased R&D investment. Long-term viability rests on platforms demonstrating sustained user engagement and robust data monetization strategies over the next decade. Acquisition targets should include specialized performance trackers with strong community features or companies possessing advanced AI algorithms. The adoption rate of service bundling within broader tech ecosystems provides a key signal to watch for market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-driven Personalization | This enhances user engagement by delivering customized fitness and nutrition plans. |
| Wearable Ecosystem Partnerships | These secure real-time biometric data, critical for advanced app functions. |
| B2B2C Distribution Channels | This expands market reach by integrating apps into corporate wellness programs. |
| Gamification and Community Features | These improve user stickiness and foster competitive social interaction among users. |
| Data Privacy Compliance Audits | These mitigate regulatory risks from GDPR and MIIT, ensuring market access. |
Research Approach
The analysis maps fitness app product types, end-user segments, and feature sets, each validated through extensive primary interviews with app developers, health coaches, and personal trainers. Secondary validation sources included app store analytics, government health reports, and technology company financial filings. This approach triangulated insights using both bottom-up market sizing and top-down validation, ensuring comprehensive data coverage.
Assumptions regarding global smartphone penetration and cloud infrastructure availability were held fixed, while AI integration rates and wearable device adoption varied across the analysis window. The analytical framework modeled market growth across product type, end user, feature, and deployment segments. Compound annual growth rates were derived from historical data and projected technological advancements. Regional adoption patterns also served as a key forecast input.
Stress conditions across regulatory shifts and unforeseen technological breakthroughs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding market dynamics and competitive responses. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Archiving Software Market
Software & Services
Association Management Software Market
Software & Services
Adaptive Learning Software Market
Software & Services
Employee Engagement Solutions Market
Software & Services
Cloud Communication Platform Software Market
Software & Services
Global Rapid Application Development Market
Software & Services
Client Virtualization Software Market
Software & Services
Global Political Campaign Software Market
Software & Services
Microsoft Office 365 Integration Services Market
Software & Services
Germany HR Payroll Software Market
Software & Services
Financial Corporate Performance Management (FCPM) Software Market
Software & Services
Global Thermal Analysis Software Market
Software & Services
Relational Database Management System Market
Software & Services
UK Point of Sale Software Market
Software & Services
Global Server Management Software Market
Software & Services
Global Online Proofing Software Market