
 Recruitment Software Market | 2026-2036
Recruitment Software Market Size, Share, and Industry Trends Forecast 2026-2036
Recruitment Software Market Intelligence
The capability gap between developing proprietary AI matching algorithms and providing broad human capital management integration is redrawing the competitive landscape. Large-scale providers like Oracle Corporation leverage their extensive ERP footprint to bundle recruitment modules. In contrast, specialists such as iCIMS, Inc. and Bullhorn, Inc. differentiate through dedicated applicant tracking functionalities. Workday, Inc. sustains its market position by offering a unified data model for finance, HR, and planning.
Recruitment software comprises a suite of tools designed to automate the entire hiring lifecycle, from candidate sourcing to final onboarding. These platforms function by integrating with corporate career pages, external job boards, and internal HRIS through APIs. Cloud-based SaaS models represent the dominant deployment method due to superior scalability and lower upfront capital expenditure. Within solution types, applicant tracking systems form the core functionality, while talent analytics modules for predicting candidate success represent the fastest-growing segment.
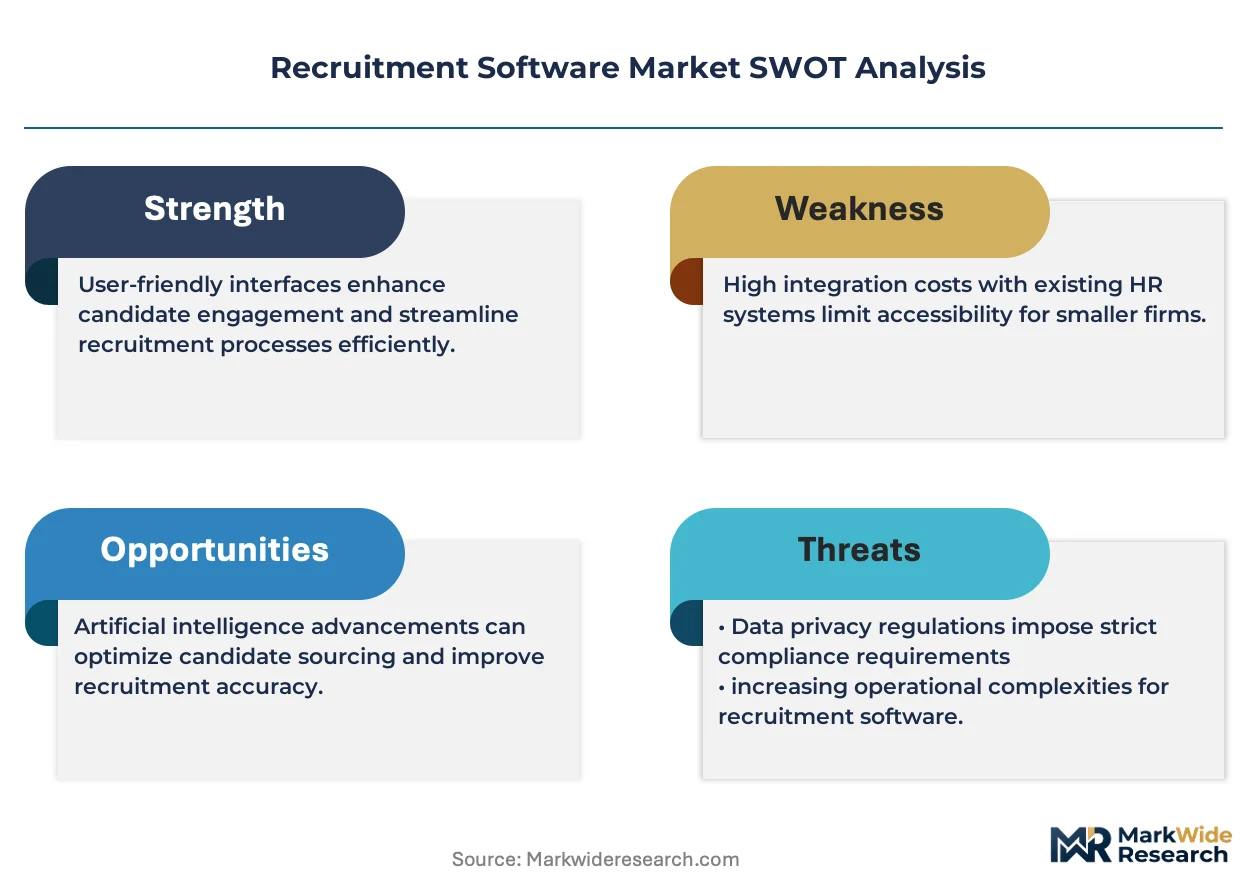
Data privacy regulations, including Europe's GDPR and China's PIPL, mandate strict controls on how candidate data is collected, stored, and processed. In the United States, EEOC guidelines and new laws in cities like New York City influence software design to ensure fair hiring practices. Vendors and HR departments must now balance the drive for AI-powered efficiency with evolving ethical standards and cross-border compliance obligations.
Market Dynamics
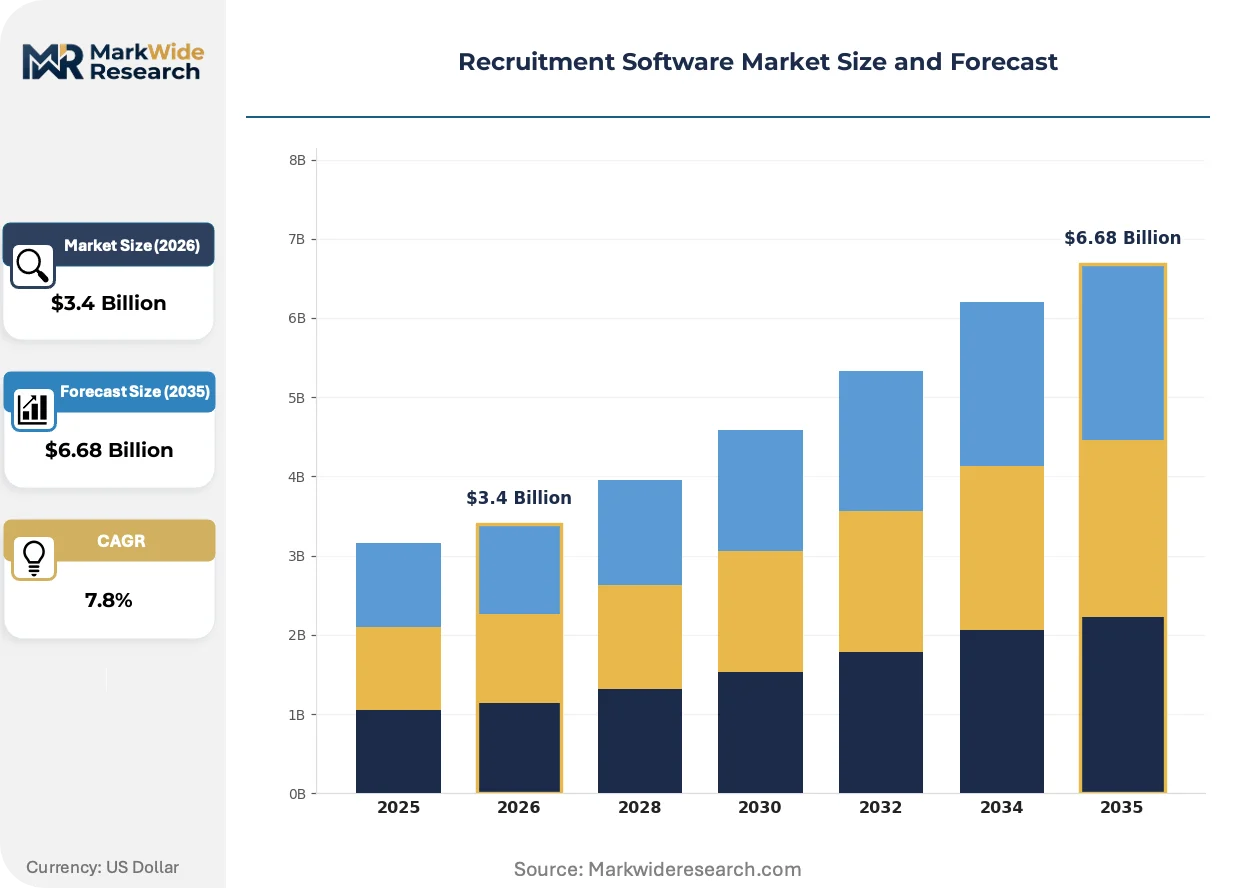
The market's central tension lies in balancing the efficiency gains from AI-driven automation against the escalating complexity of global data privacy and fair hiring regulations, such as GDPR and evolving EEOC guidelines.
Growth Catalysts
- AI-Powered Analytics:The integration of predictive analytics for candidate matching and success forecasting accelerates time-to-hire for corporate HR departments seeking to improve talent acquisition quality.
- Sector-Specific Demand:High-volume hiring in India's IT services and business process outsourcing sectors fuels adoption of automated platforms to manage large candidate pools efficiently.
- SaaS Deployment:Cloud-based subscription models reduce upfront capital expenditure, making advanced recruitment tools accessible to a wider range of small and medium-sized enterprises.
Market Restraints
- Regulatory Compliance Burden:Navigating divergent data privacy laws like Europe's GDPR and China's PIPL imposes significant development and operational costs on software vendors.
- Integration Complexity:The technical challenges and expense of integrating new recruitment platforms with legacy Human Resource Information Systems (HRIS) can deter or delay adoption.
- Algorithmic Bias Risk:The potential for AI models to inadvertently perpetuate historical biases in hiring creates legal risks under frameworks like the U.S. EEOC guidelines and similar anti-discrimination laws.
Strategic Opportunities
- Internal Mobility Platforms:Expanding software capabilities to facilitate internal talent marketplaces addresses corporate needs for employee retention and systematic career pathing within large organizations.
- Niche Industry Modules:Developing specialized solutions for regulated industries, such as automated credential verification for healthcare or security clearance tracking for defense, creates new revenue streams.
- SME Market Penetration:Targeting under-digitized small and medium-sized enterprises in emerging economies across Southeast Asia and Latin America represents a key growth vector.
Industry Challenges
- Specialized Talent Scarcity:A shortage of data scientists with expertise in both machine learning and human resources principles constrains the development of more sophisticated and ethically sound AI features.
- Ethical AI Implementation:Balancing the drive for automated decision-making with the need for human oversight to comply with regulations like New York City's AI hiring law is a major operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recruitment Software Market |
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.68 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted, SaaS, Private Solution Type: Applicant Tracking, Candidate Sourcing, Interview Scheduling, Onboarding, Talent Analytics, Background Verification End User: Corporate HR Departments, Recruitment Agencies, Staffing Firms, Freelance Recruiters, Educational Institutions, Nonprofit Organizations Pricing Model: Subscription-Based, Pay-Per-Hire, One-Time License, Freemium, Usage-Based, Tiered Pricing |
| Companies Covered | SAP SE, Workday, Inc., Oracle Corporation, ADP LLC, International Business Machines Corporation, iCIMS, Inc., Bullhorn, Inc., SmartRecruiters, Inc., Cornerstone OnDemand, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recruitment Software Market Strategic Shifts & Innovations
Software platforms are evolving from administrative record-keeping systems into strategic talent intelligence engines. This transformation is driven by the convergence of advanced AI and a new focus on provably fair and skills-oriented hiring practices.
Generative AI automates the creation of job descriptions, candidate outreach, and interview summaries. Technology and media companies are leading adoption to enhance recruiter productivity. This technology is bifurcating the market between platforms offering basic templating and those with sophisticated, context-aware content generation capabilities.
New rules like the EU AI Act classify hiring systems as high-risk, demanding greater transparency and human oversight. This forces vendors to build in features for algorithmic explainability and bias auditing. The impact is most significant for software providers selling into the European Union, requiring substantial redesign to meet conformity requirements.
Skills-based hiring models are gaining traction, shifting focus from resumes to verifiable competencies. This change disrupts traditional applicant tracking in favor of platforms that integrate with skills assessment and credentialing services. The shift is most visible within the North American cybersecurity and software engineering sectors where specific abilities are critical.
Recruitment Software Market Segmentation
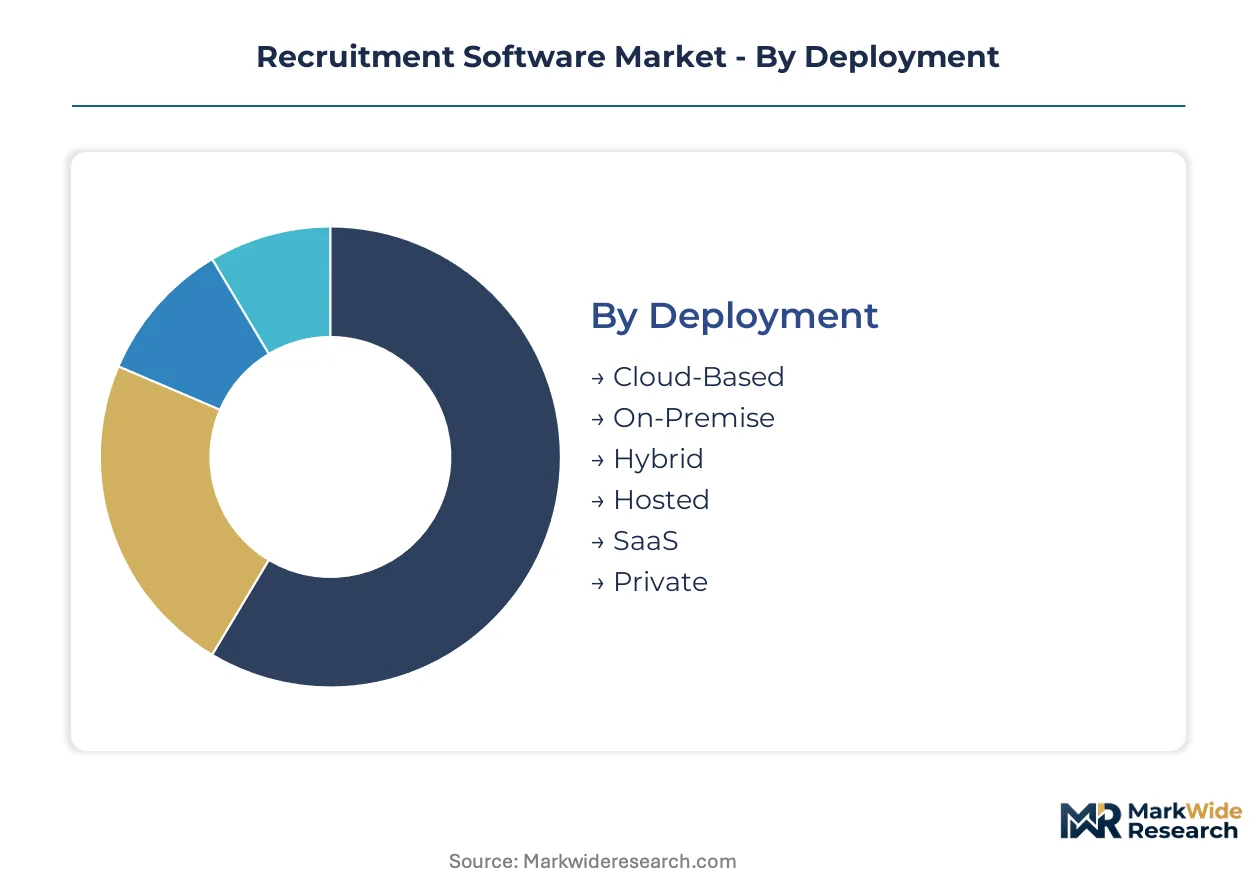
Segmentation provides granular insight into the diverse requirements and operational structures within the recruitment software market. Understanding these distinct segments helps vendors tailor solutions to specific user needs, deployment preferences, and regulatory environments, optimizing market penetration and product development.
Deployment:
Deployment models for recruitment software face distinct regulatory demands, particularly concerning data residency and access controls.
- Cloud-Based:Cloud-based solutions host data on vendor servers, offering remote accessibility and scalability for global teams. Europe's GDPR and China's PIPL heavily influence data storage location and compliance requirements for these platforms.
- SaaS:Software-as-a-Service (SaaS) provides subscription-based access to cloud-hosted applications, minimizing upfront investment for users. This model facilitates rapid deployment and continuous updates, appealing to small and medium-sized enterprises seeking agile talent acquisition tools.
- On-Premise:On-premise solutions reside on client servers, offering maximum data control but requiring significant IT infrastructure investment.
- Hybrid:Hybrid models combine on-premise components with cloud services, balancing security needs with flexible scalability.
- Hosted:Hosted solutions are managed by a third-party provider, distinct from multi-tenant SaaS, offering dedicated resources.
- Private:Private cloud deployments provide exclusive infrastructure for a single organization, often for enhanced security or specific compliance needs.
Cloud-Based deployments handle the majority of throughput; SaaS is the fastest mover on share.
Solution Type:
Solution types within recruitment software delineate the specific hiring functions they automate, from initial candidate engagement to post-offer processes.
- Applicant Tracking:Applicant Tracking Systems (ATS) manage the entire candidate workflow, from application submission through to hiring decisions. Corporate HR departments rely on robust ATS platforms for efficient candidate management and compliance with fair hiring practices.
- Talent Analytics:Talent analytics modules leverage data to predict candidate success, identify skill gaps, and optimize recruitment strategies. Demand for these AI-driven tools is accelerating among large enterprises seeking to improve hiring quality and reduce turnover rates.
- Candidate Sourcing:Candidate sourcing tools identify and engage potential applicants across various online channels and databases.
- Interview Scheduling:Interview scheduling solutions automate the coordination of interviews, reducing administrative burden for recruiters.
- Onboarding:Onboarding modules streamline the new hire process, integrating with HRIS for a smooth transition.
- Background Verification:Background verification tools automate checks on candidate credentials, ensuring compliance and mitigating hiring risks.
Applicant Tracking remains the foundational capability; Talent Analytics is expanding most quickly.
End User:
End-user segmentation highlights the diverse organizational needs driving demand for specialized recruitment software functionalities.
- Corporate HR Departments:Corporate HR departments utilize recruitment software for internal talent acquisition across various business units and geographies. Their demand focuses on integrated platforms that offer scalability, compliance features, and robust reporting capabilities for large candidate pools.
- Recruitment Agencies:Recruitment agencies employ specialized software to manage client relationships, candidate pipelines, and placement processes efficiently. These firms prioritize speed, database search capabilities, and tools for client communication to secure top talent rapidly.
- Staffing Firms:Staffing firms use platforms tailored for temporary placements and contract roles, requiring rapid matching and deployment features.
- Freelance Recruiters:Freelance recruiters often opt for cost-effective, flexible tools to manage individual client projects and candidate outreach.
- Educational Institutions:Educational institutions use recruitment software to manage faculty and staff hiring, often with specific academic credentialing requirements.
- Nonprofit Organizations:Nonprofit organizations seek affordable and user-friendly recruitment solutions to manage volunteer and staff recruitment within budget constraints.
Corporate HR Departments represent the largest user base; Recruitment Agencies show consistent expansion in platform utilization.
Pricing Model:
Pricing models dictate how recruitment software is monetized, reflecting varying value propositions and customer budgetary considerations.
- Subscription-Based:Subscription-based models offer recurring access to software features for a fixed period, typically monthly or annually. This provides predictable costs for users and stable revenue streams for vendors, making it the dominant model for cloud-based offerings.
- Tiered Pricing:Tiered pricing structures provide different feature sets or usage limits at escalating price points, catering to diverse organizational sizes and needs. This allows small businesses to access basic functionality while large enterprises can opt for comprehensive, enterprise-grade solutions.
- Pay-Per-Hire:Pay-per-hire models charge based on successful placements, aligning vendor costs with recruitment outcomes.
- One-Time License:One-time license purchases grant perpetual software usage, typically for on-premise deployments, with separate maintenance fees.
- Freemium:Freemium models offer basic features for free, with advanced functionalities available through paid upgrades, attracting smaller users.
- Usage-Based:Usage-based pricing scales costs according to specific metrics, such as candidate volume or data storage, ensuring flexibility.
Subscription-Based models capture the majority of market revenue; Tiered Pricing is gaining traction across diverse customer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global recruitment software adoption exhibits varied consumption patterns across geographies. Corporate HR departments in established economies prioritize advanced talent analytics and compliance features. Emerging markets like India focus on high-volume candidate management and cost-effective SaaS solutions.
India
India's IT services and business process outsourcing sectors drive significant demand for automated recruitment platforms. The country's data protection framework, including the IT Act, influences local software design. Bengaluru and Hyderabad technology hubs see extensive platform utilization for scaling workforce needs.
United States
United States corporate HR departments seek advanced AI-powered analytics for precise talent acquisition. EEOC guidelines and New York City's AI hiring law mandate fair and transparent algorithmic processes. Silicon Valley and New York City technology firms pioneer ethical AI integration within their recruitment strategies.
Germany
German enterprises prioritize recruitment software integration with existing ERP systems for seamless human capital management. The EU AI Act and GDPR impose strict transparency and data privacy requirements on vendors. Munich and Berlin tech ecosystems develop compliant, unified recruitment platforms for European markets.
China
China's vast labor market and high-volume recruitment needs fuel demand for scalable software solutions. The Personal Information Protection Law (PIPL) mandates stringent data handling and cross-border transfer controls. Shanghai and Shenzhen technology companies develop localized platforms adhering to national data residency rules.
United Kingdom
United Kingdom organizations increasingly adopt cloud-based SaaS models for recruitment flexibility and reduced capital expenditure. The UK GDPR and Data Protection Act shape software requirements for candidate data privacy. London's financial services and tech sectors leverage talent analytics for strategic workforce planning.
Recruitment Software Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the recruitment software market. This structure reflects a bifurcation between comprehensive human capital management suites and dedicated applicant tracking functionalities. Archetypes include large enterprise resource planning providers, pure-play recruitment software specialists, and emerging AI-centric solution developers. Strategic partnerships and targeted acquisitions represent dominant competitive moves among these diverse players.
At the enterprise scale, Oracle Corporation and Workday, Inc. exemplify providers leveraging extensive ERP footprints for bundled recruitment modules. Oracle Corporation, a global technology conglomerate, integrates recruitment functionalities across its broad software portfolio. Workday, Inc. sustains its market position by offering a unified data model for finance and human resources, targeting large organizational needs. Specialists like iCIMS, Inc. differentiate through dedicated applicant tracking functionalities, focusing on core recruitment process optimization for diverse client bases.
| Leading Market Players |
|---|
| SAP SE |
| Workday, Inc. |
| Oracle Corporation |
| ADP LLC |
| International Business Machines Corporation |
| iCIMS, Inc. |
| Bullhorn, Inc. |
| SmartRecruiters, Inc. |
| Cornerstone OnDemand, Inc. |
| Others |
Cost & Logistics Intelligence
Average implementation lead times for recruitment software, ranging from weeks to months, directly influence vendor pricing flexibility and the overall supply chain's responsiveness to market demands.
Pricing Analysis
Subscription-based models dominate recruitment software pricing, offering predictable costs for corporate HR departments. Tiered pricing structures differentiate functionality based on enterprise size and feature requirements, providing solutions from basic applicant tracking to advanced talent analytics. Pricing pressure stems from the high development costs of ethical AI features and the need for continuous regulatory compliance updates. Small and medium-sized enterprises exhibit the highest price sensitivity, often opting for freemium or lower-tier subscription plans.
Supply Chain Analysis
Typical software development lead times, often spanning several months for new features, shape the supply chain for recruitment software. Geographic supply concentration for core development talent resides in technology hubs across the United States, India, and the European Union. Key dependencies include cloud infrastructure services from providers like Amazon Web Services and Microsoft Azure, alongside specialized AI/ML talent. Regulatory fragmentation, particularly concerning data residency and cross-border data transfer, represents a significant supply chain risk. Distribution primarily runs through direct sales teams and strategic partnerships with HR technology consultants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The recruitment software market is experiencing a shift in buyer power, driven by the increasing consolidation among large enterprise clients seeking integrated human capital management solutions.
For Market Incumbents: Secure existing enterprise client bases by aggressively expanding platform integration capabilities with legacy HRIS. Develop robust ethical AI frameworks to mitigate the growing threat of algorithmic bias litigation under evolving regulations like the EU AI Act. Invest in global compliance teams to navigate divergent data privacy laws, ensuring product adherence across all operating regions.
For New Entrants and Emerging Players: Certification fast-tracks for AI ethics compliance offer a strategic entry point for new recruitment software providers. Target under-digitized small and medium-sized enterprises in emerging economies with cost-effective, cloud-based solutions. Focus on niche industry modules, such as automated credential verification for healthcare, to establish a specialized go-to-market angle.
For Investors and Strategic Acquirers: Carve-out targets emerge from larger ERP vendors seeking to divest non-core human capital management assets. Long-term viability depends on acquiring specialized AI firms with proven ethical AI capabilities or deep compliance expertise. A key signal to watch is the volume of M&A activity in talent analytics and ethical AI auditing solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate Generative AI for Content Creation | This initiative enhances recruiter productivity by automating job descriptions and candidate outreach. |
| Develop Niche Industry Compliance Modules | Specialized modules address unique regulatory requirements for healthcare or defense sectors. |
| Expand Cloud-Based SaaS Offerings | SaaS models provide scalability and lower upfront costs for small and medium-sized enterprises. |
| Acquire Ethical AI Auditing Startups | Acquisitions strengthen compliance features for new regulations like the EU AI Act. |
| Form Partnerships with HRIS Providers | Partnerships improve data flow and system interoperability for corporate HR departments. |
Research Approach
The analysis maps recruitment software sub-sectors, each validated through extensive interviews with HR directors, recruitment tech vendors, and compliance officers. This approach combines primary insights from industry stakeholders with secondary data from SEC filings, regulatory guidelines, and academic publications. Both bottom-up and top-down triangulation methods were applied to ensure data accuracy.
Consistency checks against external industry benchmarks and regulatory filings validated the forecast framework. The analytical approach modeled segmentation dimensions including deployment, solution type, end-user, pricing model, and regional adoption patterns across the analysis window. Compound annual growth rates were derived from historical data analysis and projected market drivers, with AI integration rates and regulatory compliance spending serving as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside unforeseen regulatory shifts or rapid AI advancements would require recalibration. Forecasts reflect assumptions regarding market evolution and technological progression. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Europe Feedback Management Software Market
Software & Services
Asia-Pacific Printing Software Market
Software & Services
Email Optimization Software Market
Software & Services
Global Headless CMS Software Market
Software & Services
Global Childcare Management Software Market
Software & Services
Medical Equipment Repair Software Market
Software & Services
Low Code Development Platform Market
Software & Services
Global Continuous Testing Market
Software & Services
Global Reporting Software Market
Software & Services
CGI Software Market
Software & Services
Global Screen and Script Writing Software Market
Software & Services
Europe Business Software Market
Software & Services
ITSM Market
Software & Services
North America Telecom Expense Management Services Software Market
Software & Services
Global Product Lifecycle Management Software Market
Software & Services
North America Saas-Based Expense Management Market