
 CAD Modeling Software Market | 2026-2036
CAD Modeling Software Market Size, Share, and Industry Trends Forecast 2026-2036
CAD Modeling Software Market Analysis
Subscription-based licensing is consolidating the revenue architecture of CAD modeling software, shifting perpetual purchases toward recurring revenue pools. Autodesk Inc. leverages its Fusion 360 cloud platform to anchor small-to-mid enterprise workflows across dispersed engineering teams. Siemens Digital Industries Software sustains deep integration between its NX platform and factory automation hardware, competing on closed-loop digital thread capabilities. Dassault Systèmes differentiates through its 3DEXPERIENCE cloud-native environment, positioning design collaboration as a standalone service layer rather than a software feature.
CAD modeling software encompasses computer-aided design applications that generate, modify, analyze, and optimize precision digital representations of two-dimensional or three-dimensional objects, typically operating through parametric feature-based modeling kernels with constraint resolution engines and NURBS surface mathematics. Its primary industrial purpose is to compress product development cycles by enabling virtual prototyping, simulation-driven validation, and associative geometry updates before physical manufacturing commitment. Cloud-based CAD deployment captures the fastest expansion trajectory as engineering teams distribute across hybrid work arrangements, while on-premises installations retain dominance in defense and regulated infrastructure sectors where data sovereignty requirements constrain SaaS adoption. The aerospace vertical concentrates margin pools due to certification-grade geometry traceability demands and long-term maintenance contract structures.
FDA 21 CFR Part 820 quality system regulations shape medical device design documentation requirements, mandating CAD revision control and audit trails that favor enterprise-tier platforms with embedded compliance modules. The EU AI Act's risk classification framework for automated design optimization tools is forcing vendors to embed explainability features into generative CAD workflows sold into European markets. ISO 10303 STEP standards govern interoperability between competing CAD kernels, reducing customer switching costs and intensifying platform stickiness investments. Stakeholders must monitor how NIST cybersecurity framework updates for critical manufacturing software reshape cloud deployment risk assessments and insurance underwriting models.
Market Dynamics
Cloud-native parametric modeling kernels are compressing deployment timelines for engineering teams while regulatory mandates from the EU AI Act force explainability layers into automated design workflows.
Growth Catalysts
- EU AI Act compliance mandates:Automated design optimization tools sold into European markets must embed explainability features, accelerating replacement cycles for legacy CAD installations.
- Electric vehicle chassis development:Automotive OEMs are expanding parametric design adoption for EV platform engineering, pulling advanced surfacing and simulation modules into core R&D budgets.
- Germany's Mittelstand manufacturing corridor:Mid-market industrial firms in Baden-Württemberg and Bavaria are driving license growth through digital twin investments tied to factory automation upgrades.
Market Restraints
- Data sovereignty requirements:Defense contractors and critical infrastructure operators in regulated sectors face contractual and national security barriers to SaaS CAD adoption.
- NURBS kernel licensing costs:Foundational geometry engines from specialized mathematics vendors impose royalty structures that inflate per-seat pricing for independent software vendors.
- ISO 10303 STEP interoperability:Standardized file exchange protocols reduce customer switching costs, intensifying platform stickiness investments and compressing margin pools.
Strategic Opportunities
- Generative design convergence:Machine learning topology optimization is integrating with constraint resolution engines to automate first-pass geometry generation for aerospace structural components.
- Medical device compliance modules:FDA 21 CFR Part 820 quality system regulations favor enterprise-tier platforms with embedded revision control and audit trail capabilities.
- Hybrid work distribution:Engineering teams across dispersed locations are pulling browser-native modeling environments into standard procurement specifications.
Industry Challenges
- Simulation-to-manufacturing skill gaps:Talent scarcity in computational fluid dynamics and finite element analysis is extending project timelines for automotive and aerospace contractors.
- Legacy PLM integration friction:Associative geometry updates between new cloud-native CAD instances and on-premises product lifecycle management databases require costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CAD Modeling Software Market |
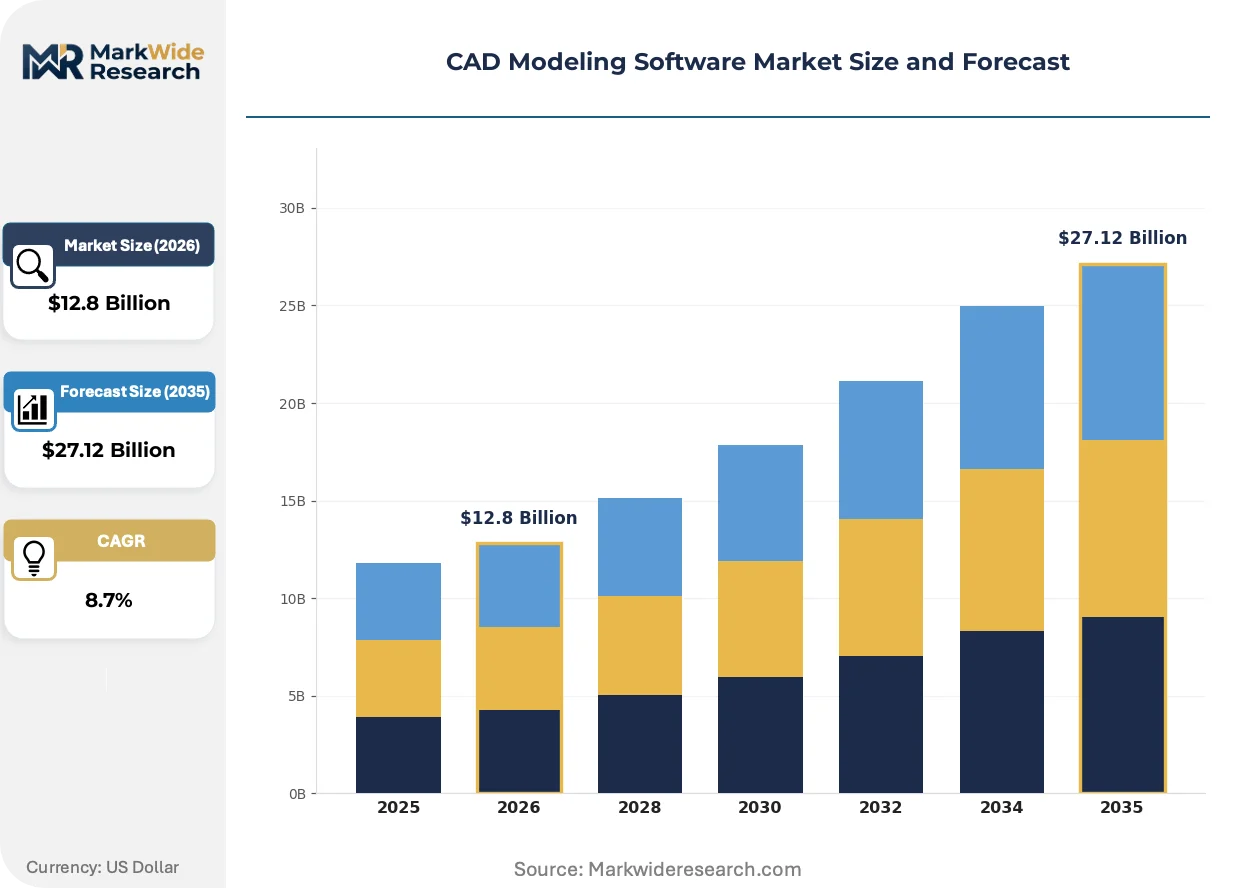
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D CAD, 3D CAD, Cloud-based CAD, Open-source CAD Industry Vertical: Aerospace, Automotive, Construction, Manufacturing Deployment: On-premises, Cloud, Hybrid, SaaS End User: Engineers, Designers, Architects, Hobbyists |
| Companies Covered | Autodesk Inc., Dassault Systèmes, Siemens Digital Industries Software, PTC Inc., Hexagon AB, Bentley Systems, Trimble Inc., Nemetschek Group, ZWSOFT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CAD Modeling Software Market Emerging Trajectories
Real-time collaborative editing environments are displacing file-based check-in workflows as the default mode for distributed engineering teams. Three developments are compressing traditional development cycles.
Generative adversarial networks trained on manufacturing constraint libraries are integrating topology optimization directly into parametric feature trees. Automotive seating and bracket suppliers are deploying these tools to collapse first-pass design iterations from weeks to hours. The structural consequence is a compression of supplier quoting timelines and an elevation of simulation validation as the primary value-creation layer.
The EU AI Act's risk classification framework for automated design tools is mandating algorithmic transparency in generative CAD workflows sold into European markets. Engineering software vendors must now embed decision-logging capabilities that trace how optimization algorithms arrived at specific geometry solutions. Aerospace certification authorities in Germany and France are incorporating these audit capabilities into their design approval processes.
Subscription-based access models are displacing perpetual license purchases across mid-market engineering firms. Value-added resellers are pivoting from transaction-based margins to recurring service fees for deployment support and custom training. This shift is most visible in Germany's industrial manufacturing corridor, where Mittelstand firms are consolidating vendor relationships around platforms with embedded cloud collaboration layers.
CAD Modeling Software Market Segmentation
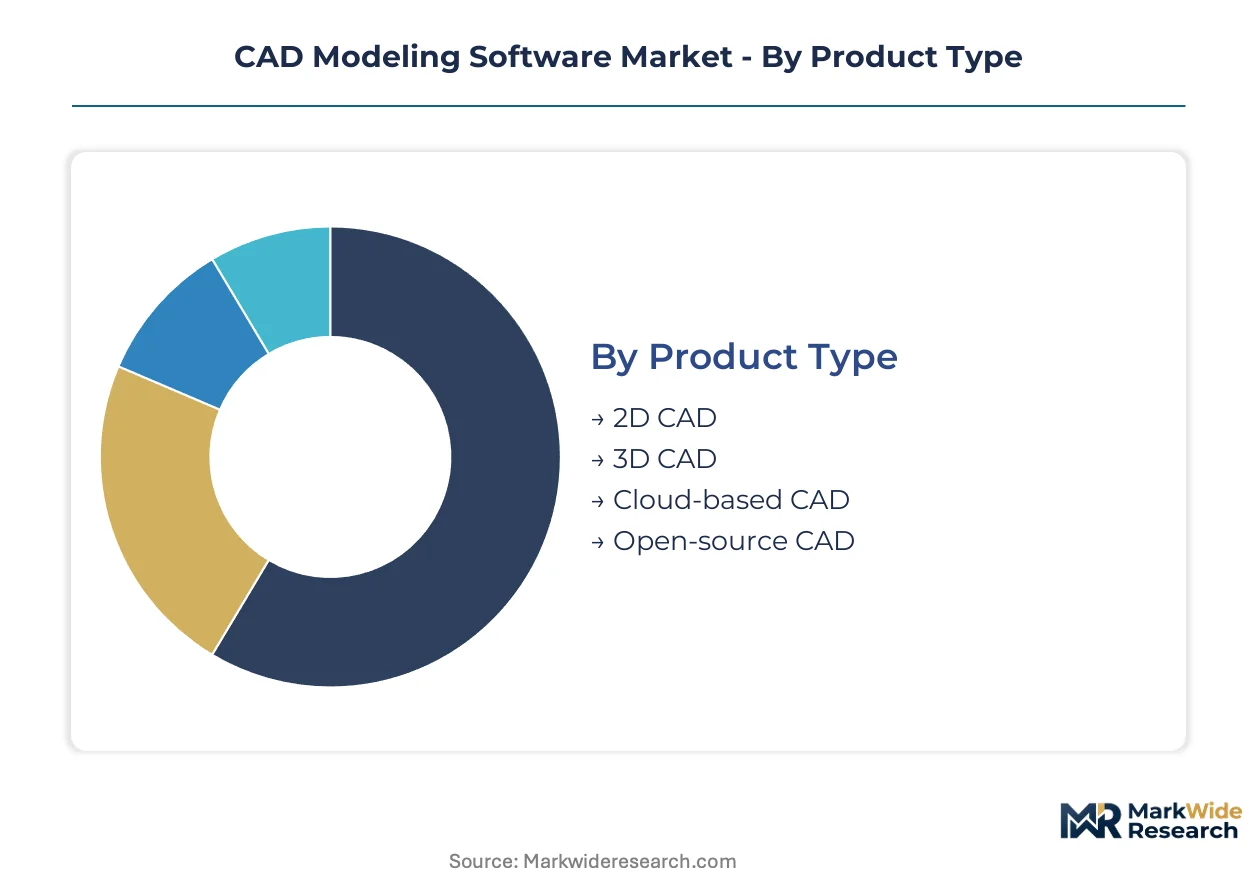
CAD modeling software segments fracture along capability depth and infrastructure requirements. Procurement patterns diverge sharply between mission-critical engineering workflows and discretionary design tools. Understanding these fault lines exposes where pricing power concentrates and where commodification pressures mount.
Product Type:
Supply concentration in core geometry kernels funnels licensing revenue toward vendors controlling NURBS and constraint-resolution engines. Independent developers face royalty structures that compress their margin flexibility.
- 3D CAD:Parametric feature-based modeling environments with associative geometry updates and simulation-ready solid bodies. Aerospace contractors in Germany and France anchor demand through certification-grade surfacing requirements tied to EASA airworthiness protocols. Autodesk and Siemens capture recurring revenue through integrated PLM connectivity.
- Cloud-based CAD:Browser-native parametric kernels with real-time collaborative editing and distributed version control. Engineering teams across Germany's Mittelstand manufacturing corridor are pulling these platforms into procurement specifications as hybrid work arrangements solidify. EU AI Act explainability mandates accelerate replacement of legacy desktop installations.
- 2D CAD:Drafting and documentation tools for schematic and planar geometry generation, retaining dominance in construction documentation and legacy manufacturing workflows.
- Open-source CAD:Community-developed modeling kernels with extensible scripting interfaces, concentrated among academic researchers and startup hardware ventures with constrained licensing budgets.
Today's leader: 3D CAD. Tomorrow's challenger: Cloud-based CAD.
Industry Vertical:
Application-specific compliance burdens create tiered pricing structures across certification-grade and general-purpose deployments. Margin pools deepen where audit trails and revision control carry regulatory weight.
- Aerospace:Certification-grade geometry traceability with long-term maintenance contract structures and EASA/FAA design approval documentation. German and French aerospace clusters in Hamburg and Toulouse concentrate demand for platforms with embedded STEP interoperability and generative design audit capabilities.
- Automotive:Parametric chassis development and electric vehicle platform engineering with simulation-driven validation cycles. OEMs in Stuttgart and Munich are expanding advanced surfacing module adoption for EV battery enclosure design.
- Manufacturing:Factory automation integration and digital twin connectivity for production equipment design.
- Construction:Building information modeling coordination and structural documentation for commercial and infrastructure projects.
Aerospace commands premium pricing through compliance depth. Automotive offers the steepest expansion trajectory through EV platform investments.
Deployment:
Infrastructure decisions hinge on data sovereignty requirements and cross-border collaboration intensity. Customer switching costs vary dramatically across these models.
- SaaS:Fully managed cloud subscriptions with automatic kernel updates and usage-based scaling. European engineering firms are consolidating procurement around these platforms as EU AI Act cloud mandates take effect.
- On-premises:Locally installed kernels with air-gapped operation for defense contractors and critical infrastructure operators facing national security barriers to external data residency.
- Cloud:Vendor-hosted environments with customer-controlled encryption and regional data center selection.
- Hybrid:Split architectures with sensitive geometry processed locally and collaborative workflows synchronized to cloud instances.
SaaS is displacing perpetual licensing fastest. Hybrid architectures retain strategic importance for regulated verticals.
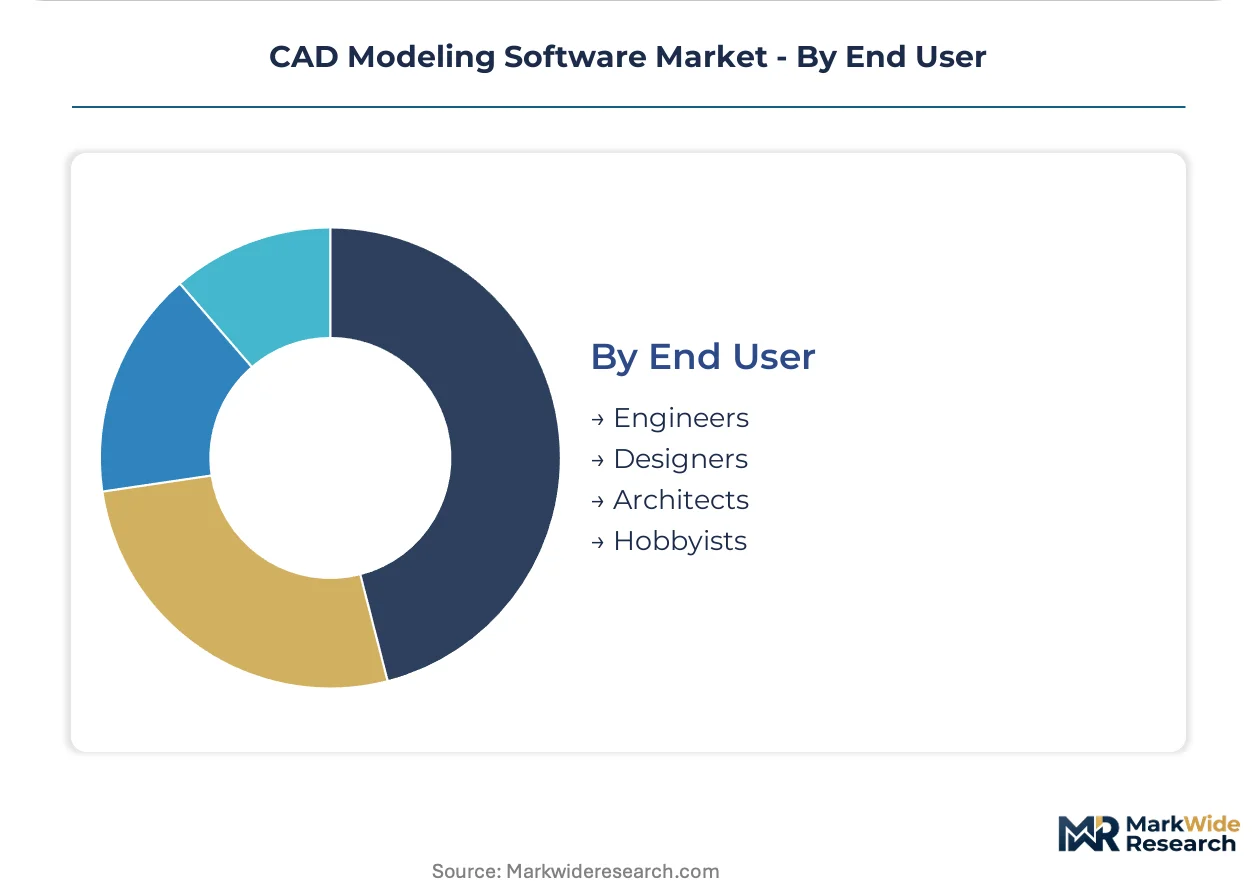
End User:
Skill specialization and workflow integration requirements segment pricing tolerance across professional and enthusiast cohorts.
- Engineers:Simulation-driven design validation with computational fluid dynamics and finite element analysis integration. Talent scarcity in these domains extends project timelines for automotive and aerospace contractors.
- Designers:Industrial styling and ergonomic form development with real-time rendering and virtual reality visualization.
- Architects:Building geometry coordination with structural and MEP system integration.
- Hobbyists:Entry-level parametric modeling for personal fabrication and maker community projects.
Engineers drive enterprise licensing volume. Hobbyists represent the entry-point funnel for future professional conversions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage around data sovereignty and AI explainability mandates is fragmenting procurement patterns. Engineering firms migrate licenses toward jurisdictions with lighter compliance burdens or stronger industrial subsidies, compressing vendor pricing power in high-cost regulatory environments.
United States
Defense contractors and aerospace primes anchor demand through FAA certification workflows and ITAR-controlled development environments. FDA 21 CFR Part 820 documentation requirements drive medical device manufacturers toward platforms with embedded audit trails. The Greater Boston biotech corridor and Seattle aerospace cluster concentrate procurement for compliance-grade installations.
Germany
Mittelstand manufacturers in Baden-Württemberg and Bavaria are consolidating vendor relationships around cloud-native platforms with EU AI Act explainability features. KBA automotive regulations and EASA design approval protocols shape platform selection for Stuttgart OEMs. The Hamburg aerospace cluster demands STEP interoperability for supplier coordination.
China
Domestic EV platform engineering and MIIT smart manufacturing mandates accelerate local CAD kernel development. SAMR data localization requirements constrain SaaS adoption, favoring on-premises deployments with state-controlled encryption. The Yangtze River Delta manufacturing belt concentrates demand for factory automation integration.
Japan
METI digital transformation subsidies and JIS standardization frameworks guide procurement for precision machinery and automotive suppliers. Talent scarcity in computational engineering extends project timelines for Nagoya-based industrial equipment manufacturers. The Kanto region anchors demand for hybrid cloud architectures balancing collaboration with IP protection.
France
ANSM medical device regulations and CNIL data governance requirements shape platform selection for Paris-region healthcare technology firms. The Toulouse aerospace cluster incorporates EU AI Act audit capabilities into EASA design approval processes. Auvergne-Rhône-Alpes machinery manufacturers drive mid-market license growth through digital twin investments.
CAD Modeling Software Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-stack platform vendors capturing enterprise recurring revenue while point-solution developers serve niche compliance workflows. The vendor base organizes into three tiers: cloud-native challengers with browser-based kernels, legacy incumbents with deep PLM integration, and open-source alternatives with academic and startup adoption. Consolidation pressures favor M&A activity around simulation-ready geometry engines and vertical-specific compliance modules.
Within the cloud-native tier, Autodesk Inc. and Dassault Systèmes occupy positions anchored by real-time collaboration layers and design-as-a-service positioning. Siemens Digital Industries Software exemplifies the integrated-systems archetype, with NX platform connectivity to factory automation hardware representing the closed-loop digital thread model. These three vendors collectively illustrate how subscription architecture and regulatory compliance features are compressing competitive differentiation around deployment speed and audit transparency rather than raw geometry performance.
| Leading Market Players |
|---|
| Autodesk Inc. |
| Dassault Systèmes |
| Siemens Digital Industries Software |
| PTC Inc. |
| Hexagon AB |
| Bentley Systems |
| Trimble Inc. |
| Nemetschek Group |
| ZWSOFT |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialists in cloud-native CAD kernels have consolidated NURBS geometry engine licensing, compressing margin flexibility for independent software vendors while enforcing disciplined SaaS-tiered pricing across European engineering procurement.
Pricing Analysis
Capacity additions in Germany's Mittelstand manufacturing corridor are reshaping price floors for mid-market cloud CAD subscriptions. Three-tier pricing structure across premium, standard, and economy levels segments buyers by compliance module depth and PLM integration scope. Price differentiation rests on EU AI Act explainability certification and EASA-grade audit trail capabilities. Pricing pressure stems from open-source kernel alternatives in academic and startup segments. Hobbyists and independent contractors exhibit highest price sensitivity; aerospace primes with long-term maintenance contracts show lowest.
Supply Chain Analysis
EASA and FDA certification requirements gate geometry kernel sourcing to vendors with embedded compliance documentation and revision control modules. Supply concentrates in Germany, France, and the United States for certification-grade platforms. Raw material dependencies include NURBS mathematics libraries from specialized vendors, cloud infrastructure from hyperscalers, and simulation mesh engines from CAE specialists. Single-source vulnerability runs through foundational geometry kernel licensors. Distribution feeds from direct enterprise sales teams and value-added resellers pivoting to recurring service fees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in CAD modeling software hinges on SaaS conversion compressing customer acquisition costs and generative design modules commanding premium tier placement.
For Market Incumbents: Cement platform stickiness through embedded EU AI Act explainability features and STEP interoperability investments that raise switching costs. Deepen backward integration into constraint-resolution engines to escape NURBS royalty structures. Open-source kernel proliferation and browser-native challengers represent primary substitution threats. For New Entrants and Emerging Players: Capture white-space in medical device compliance modules where FDA 21 CFR Part 820 documentation requirements favor specialized audit-trail platforms. Target Germany's Mittelstand corridor through browser-native collaboration tools with factory automation connectivity. Lead with usage-based pricing to displace perpetual-license incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among vertical-specific compliance module developers with embedded regulatory workflows. Long-term viability favors platforms with generative design convergence and closed-loop digital thread capabilities. Watch for MIIT localization mandates in China as signal for regional kernel development acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Integration | Embedded explainability features accelerate replacement cycles for legacy desktop installations in European markets. |
| Generative Design Convergence | Machine learning topology optimization compresses first-pass aerospace component design from weeks to hours. |
| Cloud-Native Kernel Development | Browser-native parametric modeling enables real-time collaboration for dispersed hybrid engineering teams. |
| Medical Device Compliance Modules | FDA 21 CFR Part 820 audit trail capabilities capture premium pricing from device manufacturers. |
| Digital Thread Integration | Closed-loop connectivity between CAD and factory automation hardware deepens enterprise platform stickiness. |
Methodological Framework
Multiple input streams — primary interviews with CTOs and IT procurement officers, platform engineer consultations, and channel partner discussions — were reconciled against secondary validation from SEC filings, hyperscaler capex disclosures, and EASA certification databases. Bottom-up license deployment estimates across deployment models and verticals were triangulated with top-down vendor revenue analysis.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size tier, industry vertical, integration complexity with PLM systems, and regional regulatory adoption patterns. CAGRs were derived from license growth trajectories and SaaS conversion velocity. Generative design module attach rates and EU AI Act compliance timelines served as industry-specific forecast inputs.
Regulatory enforcement delays, NURBS kernel licensing renegotiations, and defense sector data sovereignty reversals are the dominant revision risks to modeled assumptions. A model refresh is warranted upon material change in EASA or FAA certification protocol updates affecting geometry traceability requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Policy Management Software Market
Software & Services
Europe Business Software Market
Software & Services
Home Fitness App Market
Software & Services
Engineering Software Market
Software & Services
Global Audit Software Market
Software & Services
Data Integration Software Market
Software & Services
Sales Performance Management (SPM) Software Market
Software & Services
Global Gamification Software Market
Software & Services
Global Time Series Analysis Software Market
Software & Services
Entity Management Software Market
Software & Services
Lead Management Software Market
Software & Services
Global Cloud Based Collaboration Software Market
Software & Services
Electronic Design Automation Software Market
Software & Services
Stock Control Software Market
Software & Services
Global User Interface Service Market
Software & Services
POS Software Market