
 Virtual Router Market | 2026-2036
Virtual Router Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Router Market Intelligence
Software-based forwarding planes are realigning cost structures away from dedicated ASIC-dependent hardware. Cisco Systems leverages extensive enterprise channel relationships to sustain installed-base migration toward virtualized platforms. Juniper Networks anchors service provider credibility through Contrail routing software optimized for Kubernetes-orchestrated workloads. Huawei Technologies competes on price-performance metrics in emerging markets where national infrastructure buildouts prioritize programmable networks over legacy chassis investments.
A virtual router implements IP forwarding, BGP/OSPF routing protocols, and ACL policy enforcement through software executing on standard x86 or ARM compute substrates rather than purpose-built silicon, enabling deployment across hypervisors, containers, and bare-metal cloud instances. Its commercial purpose centers on decoupling network control from physical topology to accelerate provisioning and reduce hardware lifecycle lock-in. Cloud-based deployment captures the dominant margin pool as hyperscaler co-location and multi-tenant SaaS delivery normalize operational expenditure models. Software-defined networking as a solution type leads technology adoption where centralized controllers program distributed virtual router instances across heterogeneous transport. Edge computing use cases represent the fastest structural expansion as latency-sensitive applications compel routing intelligence toward last-mile aggregation points.
FCC net-neutrality rulings and NIST cybersecurity frameworks in the United States shape product certification requirements for virtual routers handling federal traffic. ETSI NFV standards and GDPR data-localization mandates in Europe compel vendors to architect geo-fenced routing instances with auditable packet-path documentation. Stakeholders must evaluate whether their vendor roadmaps commit to cloud-native control plane disaggregation or perpetuate hybrid dependence on legacy physical chassis for critical forwarding paths.
Market Dynamics
Telecom operators are dismantling proprietary hardware dependencies as cloud-native control planes disaggregate routing intelligence from physical chassis, forcing vendors to rearchitect around Kubernetes-orchestrated software stacks.
Growth Catalysts
- Edge Computing Deployment:Latency-sensitive applications in autonomous vehicles and industrial IoT are pulling routing intelligence toward last-mile aggregation points in Germany, Japan, and the United States.
- FCC Net-Neutrality Framework:Federal traffic handling requirements in the United States are accelerating certification-driven procurement of software-defined routing platforms for service provider networks.
- ETSI NFV Standards:European mandates for geo-fenced routing instances with auditable packet-path documentation are compelling infrastructure modernization across telecom operators.
Market Restraints
- Silicon Supply Concentration:Dependence on advanced x86 and ARM processor fabrication in Taiwan and South Korea creates vulnerability in compute substrate availability for virtual router deployments.
- Legacy Chassis Sunk Costs:Existing investments in purpose-built routing hardware by tier-one carriers in the United States and Japan delay full software-defined transitions.
- Skill Scarcity in Cloud-Native Networking:Shortage of engineers proficient in Kubernetes networking and BGP control plane virtualization constrains deployment velocity.
Strategic Opportunities
- 5G Standalone Core Buildouts:Service providers in India and Brazil are greenfielding user plane function virtualization without legacy hardware migration burdens.
- GDPR-Compliant Edge Routing:Data-localization mandates across Europe are creating demand for sovereign cloud routing instances with jurisdictional packet containment.
- AI-Driven Traffic Engineering:Convergence of machine learning inference with real-time routing decisions is opening new value pools in predictive congestion management.
Industry Challenges
- Multi-Vendor Integration Complexity:Service providers struggle to harmonize Contrail, Cisco IOS-XE, and open-source FRRouting control planes within unified orchestration layers.
- Certification Timeline Compression:NIST cybersecurity framework compliance for federal virtual router deployments demands extended validation cycles that conflict with agile DevOps release cadences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Router Market |
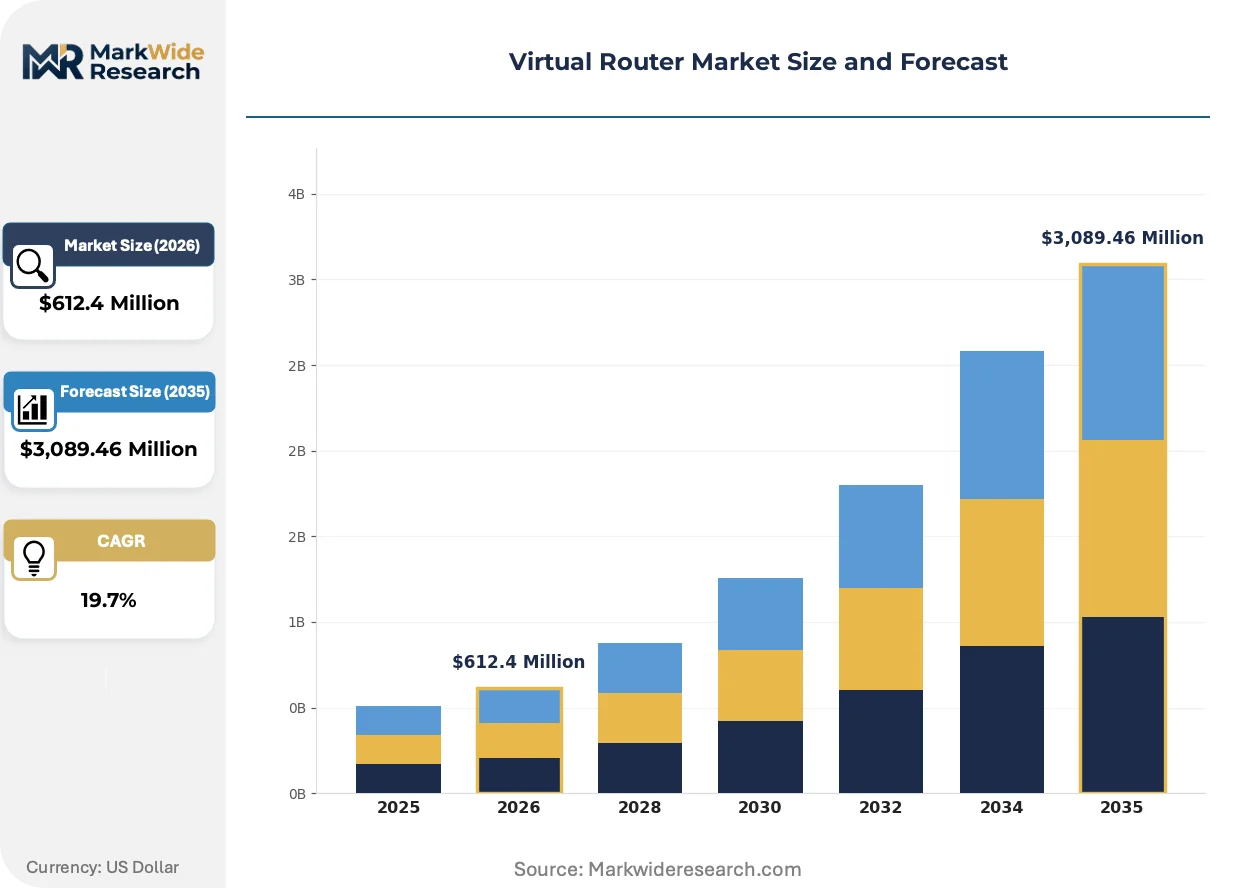
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $3,089.46 Million |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted Solution Type: Network Function Virtualization, Software-Defined Networking, Routing Optimization, Security Integration, Traffic Management Use Case: Data Center Management, Enterprise Connectivity, Service Provider Networks, Telecommunication Backbone, Edge Computing End User: Telecom Operators, Managed Service Providers, Government Agencies, Financial Institutions, Educational Institutes |
| Companies Covered | Cisco Systems, Juniper Networks, Huawei Technologies, Nokia Corporation, Ericsson, Hewlett Packard Enterprise, IBM, Arista Networks, Palo Alto Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Router Market Strategic Shifts & Innovations
Intent-based networking is rewriting how routing policies are authored, tested, and enforced across distributed infrastructure, compressing provisioning cycles from weeks to minutes.
eBPF-based data plane acceleration is automating kernel-bypass packet processing for virtual router instances running on commodity x86 servers. Hyperscale cloud operators in the United States are deploying this technology at production scale. The shift is automating performance parity between software and hardware forwarding while collapsing cost structures for high-throughput edge locations.
ETSI NFV Release 4 specifications are mandating cloud-native network function packaging standards across European telecom infrastructure. Vendors must now deliver routing software as containerized microservices rather than monolithic virtual machines. German and French operators are piloting these specifications in 5G standalone core deployments ahead of broader continental rollout.
Subscription-based routing software licensing is displacing perpetual license models among enterprise buyers in the United States and Japan. Channel partners are restructuring compensation around recurring revenue recognition. This behavioral pivot is most visible in mid-market financial services verticals seeking operational expenditure alignment with cloud migration timelines.
Virtual Router Market Segmentation
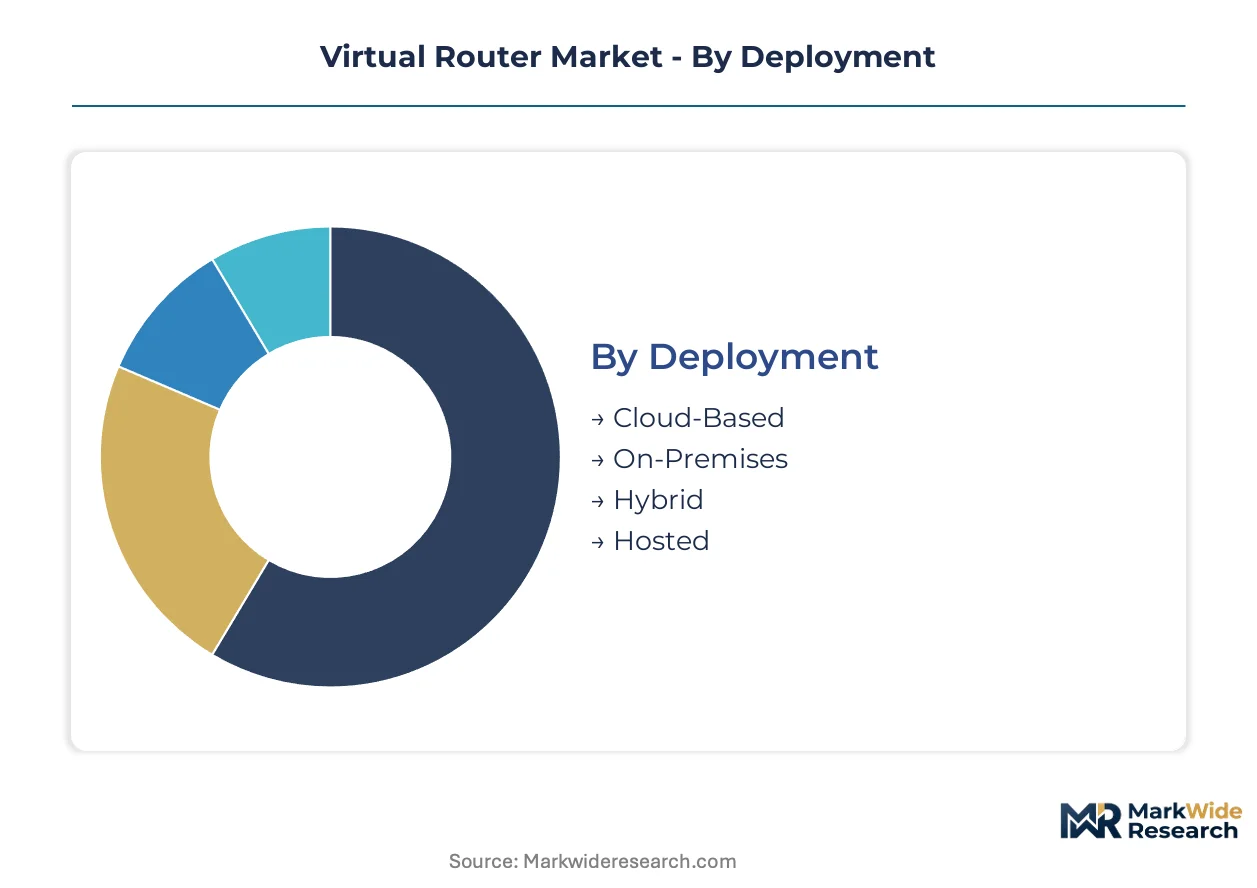
Virtual router procurement patterns diverge sharply across deployment models and buyer sophistication, with legacy hardware replacement cycles determining where software-based alternatives gain initial traction. Understanding segment-specific upgrade timelines reveals which customer categories will dominate capacity expansion versus those locked into extended depreciation schedules.
Deployment:
Replacement-cycle timing varies dramatically by deployment architecture, with cloud-native environments offering the shortest path from hardware retirement to software instantiation.
- Cloud-Based:Fully managed routing instances running on hyperscaler infrastructure eliminate capital depreciation entirely. Telecom operators in Germany and Japan are prioritizing this model for 5G standalone core buildouts where legacy chassis carry minimal sunk cost.
- Hybrid:Split control and user plane architectures allow gradual migration of specific forwarding functions while preserving existing BGP session state on physical hardware. Financial institutions in the United States favor this intermediate posture for regulatory audit continuity during transition periods.
- On-Premises:Bare-metal software deployments on customer-owned x86 servers retain operational control for classified traffic handling. Government agencies with NIST compliance mandates specify this architecture for federal network segments.
- Hosted:Single-tenant routing appliances at carrier-neutral colocation facilities bridge operational expenditure preferences with jurisdictional data residency requirements. GDPR-bound European enterprises deploy this model for sovereign cloud adjacency.
Volume placements concentrate in Cloud-Based; the faster expansion belongs to Hybrid.
Solution Type:
Margin capture potential separates centralized controller architectures from embedded routing functions, with orchestration-layer premiums commanding disproportionate vendor investment.
- Software-Defined Networking:Centralized control planes program distributed forwarding elements through southbound APIs, collapsing provisioning intervals from weeks to minutes. Service provider networks in the United States and Japan are standardizing on this architecture for multi-vendor interoperability.
- Network Function Virtualization:Virtualized routing software packaged as containerized microservices per ETSI Release 4 specifications enables elastic scaling independent of hardware lifecycle. German and French operators pilot this packaging in production 5G cores.
- Security Integration:Converged routing and firewall functions reduce east-west traffic inspection latency in zero-trust architectures. Managed service providers bundle this capability for mid-market enterprise clients lacking dedicated security operations.
- Traffic Management:Policy-based path selection across multiple transport underlays optimizes cost-per-bit for international bandwidth. Submarine cable operators deploy these functions for dynamic route steering around congestion events.
- Routing Optimization:Machine learning-enhanced path computation engines predict congestion and preemptively reroute flows. Hyperscale cloud operators integrate these algorithms with real-time telemetry feeds from backbone infrastructure.
Revenue concentration sits with Software-Defined Networking; steepest expansion trajectory belongs to Network Function Virtualization.
Use Case:
Latency requirements and traffic predictability determine whether virtual routers displace hardware or merely augment existing infrastructure.
- Edge Computing:Distributed routing intelligence at last-mile aggregation points supports autonomous vehicle and industrial IoT workloads with sub-10 millisecond round-trip constraints. Deployment velocity in Germany, Japan, and the United States outpaces all other use cases.
- Service Provider Networks:Core and aggregation layer virtualization enables traffic engineering at continental scale without chassis upgrade cycles. National infrastructure buildouts in India and Brazil adopt this architecture greenfield without legacy migration burdens.
- Data Center Management:East-west traffic routing between tenant workloads demands high-throughput, low-latency forwarding on commodity servers. Hyperscale facilities in the United States deploy eBPF-accelerated data planes for performance parity with hardware switches.
- Telecommunication Backbone:Long-haul optical transport interconnection requires proven carrier-grade reliability that virtual platforms are only now achieving certification parity. Tier-one operators maintain hybrid deployments pending software maturity milestones.
- Enterprise Connectivity:Branch office aggregation and SD-WAN headend functions represent mature virtualization with established procurement patterns. Mid-market financial services verticals in the United States and Japan drive subscription licensing transitions here.
Deployment scale favors Service Provider Networks; the segment climbing fastest is Edge Computing.
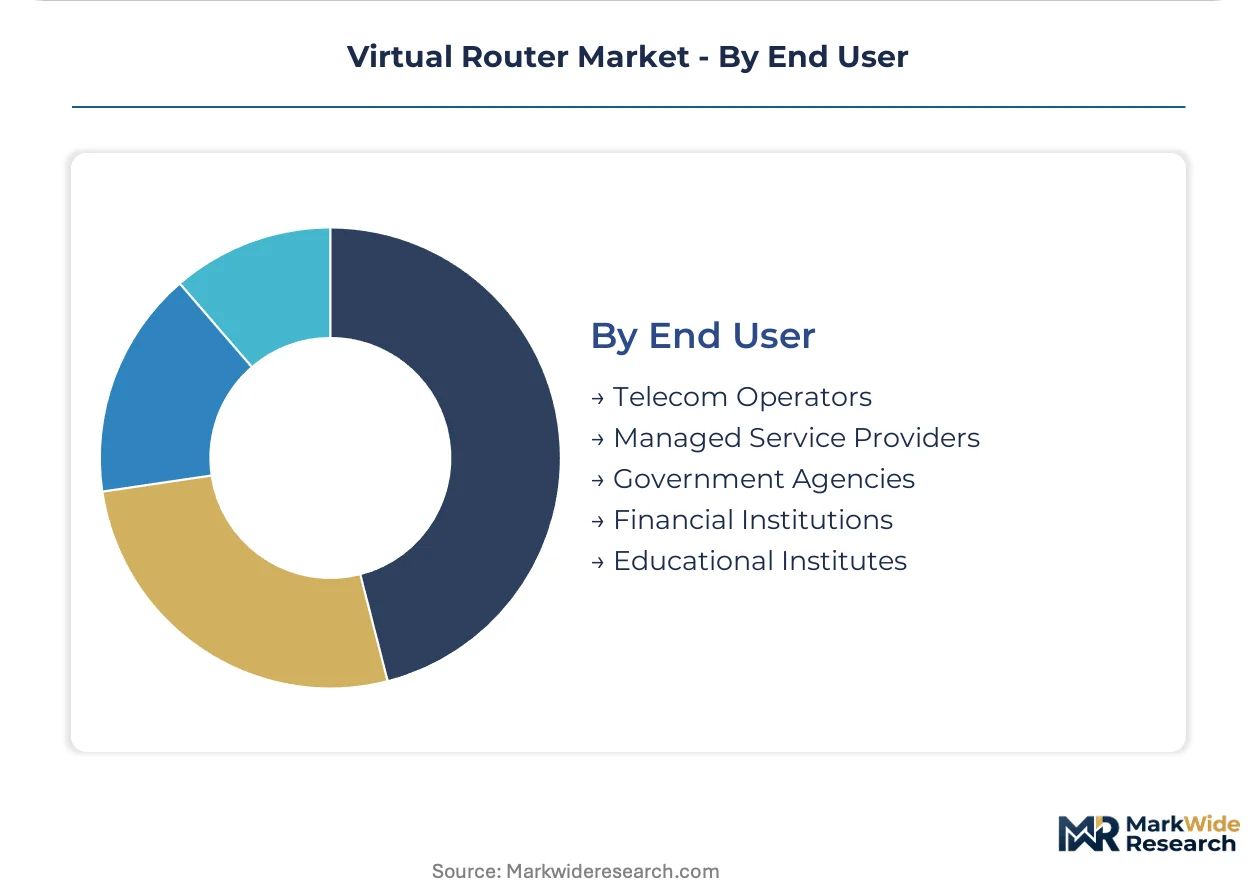
End User:
Procurement authority and technical staffing depth create distinct buying behaviors across institutional categories.
- Telecom Operators:Capital-intensive network builders with dedicated engineering organizations capable of multi-vendor integration and custom orchestration layer development. These buyers negotiate enterprise licensing frameworks directly with Cisco, Juniper, and Huawei.
- Managed Service Providers:Intermediary buyers aggregating demand from hundreds of mid-market clients, requiring standardized, low-touch deployment tooling. Subscription routing software licensing aligns their cost structures with recurring revenue recognition.
- Financial Institutions:Regulated entities with stringent audit requirements and conservative technology adoption curves, often mandating hybrid architectures during extended transition periods. NIST cybersecurity framework compliance drives extended validation cycles.
- Government Agencies:Sovereign buyers with classified traffic handling mandates and domestic vendor preferences, particularly in defense and intelligence applications. FCC net-neutrality rulings shape certification requirements for federal traffic.
- Educational Institutes:Budget-constrained research networks pioneering open-source routing stacks like FRRouting for campus backbone and research exchange point interconnection. These deployments inform commercial platform roadmaps through production feedback.
Contract value concentrates with Telecom Operators; the category gaining share fastest is Managed Service Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for cloud infrastructure development in Singapore, Germany, and the United States are concentrating hyperscaler investment and virtual router procurement authority. These zones accelerate depreciation schedules and reduce jurisdictional friction for multi-tenant routing deployments.
United States
Hyperscale cloud operators in Northern Virginia and Oregon data center clusters are deploying eBPF-accelerated virtual routers at production scale. FCC net-neutrality rulings shape certification requirements for federal traffic handling, compelling vendors through NIST cybersecurity framework validation cycles. The Dallas-Fort Worth metro anchors telecom operator edge computing buildouts for autonomous vehicle networks.
Germany
ETSI NFV Release 4 specifications are mandating containerized microservice packaging for 5G standalone core deployments across Deutsche Telekom and Vodafone infrastructure. GDPR data-localization requirements enforce geo-fenced routing instances with auditable packet-path documentation. The Frankfurt Rhine-Main cluster concentrates sovereign cloud routing deployments for financial services compliance.
Japan
METI industrial digitization programs are subsidizing edge computing infrastructure for factory automation and autonomous logistics networks in Aichi and Kanagawa prefectures. Conservative procurement cycles at NTT and KDDI delay full cloud-native transitions while hybrid architectures preserve existing BGP session state. The Tokyo-Osaka corridor hosts the densest concentration of latency-sensitive industrial IoT routing deployments.
India
Department of Telecommunications spectrum allocation and PLI scheme incentives are enabling greenfield 5G standalone core buildouts without legacy hardware migration burdens. TRAI net-neutrality consultations are shaping domestic routing software procurement frameworks for Reliance Jio and Bharti Airtel. The Bengaluru-Hyderabad corridor concentrates cloud-native network function development for export to Middle Eastern and African operators.
Brazil
ANATEL infrastructure modernization mandates are accelerating virtual router adoption for regional backbone consolidation by Vivo and Claro. National data center localization requirements under the Marco Civil da Internet compel jurisdictional packet containment for financial traffic. The São Paulo metro anchors Latin America's largest concentration of multi-tenant colocation routing deployments.
Virtual Router Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with enterprise channel relationships sustaining incumbent positions while cloud-native entrants capture greenfield service provider deployments. The vendor base organizes around three archetypes: legacy networking incumbents with extensive installed bases, cloud infrastructure specialists with Kubernetes-native orchestration capabilities, and telecommunications equipment providers with carrier-grade reliability certifications. Dominant competitive moves include strategic partnerships between routing software vendors and hyperscale cloud platforms, plus portfolio diversification into converged security-routing functions.
Within the legacy incumbent tier, Cisco Systems and Juniper Networks exemplify vendors leveraging extensive enterprise channel relationships to sustain installed-base migration toward virtualized platforms. Among telecommunications equipment providers, Nokia Corporation and Ericsson occupy positions anchored in carrier-grade reliability credentials for 5G core deployments. Huawei Technologies represents price-performance competition in emerging markets where national infrastructure buildouts prioritize programmable networks over legacy chassis investments.
| Leading Market Players |
|---|
| Cisco Systems |
| Juniper Networks |
| Huawei Technologies |
| Nokia Corporation |
| Ericsson |
| Hewlett Packard Enterprise |
| IBM |
| Arista Networks |
| Palo Alto Networks |
| Others |
Cost & Logistics Intelligence
Subscription licensing mandates from mid-market financial services buyers in the United States and Japan are forcing vendors to restructure perpetual license portfolios into recurring revenue frameworks, compressing upfront cash flows while expanding customer lifetime value capture.
Pricing Analysis
Short lead-time premiums dominate pricing negotiations for virtual router deployments targeting 5G standalone core buildouts in India and Brazil. Three-tier pricing structure across premium, standard, and economy levels separates carrier-grade certified instances from development sandboxes and bare-metal open-source alternatives. Cost compression in the economy tier is intensifying because hyperscaler co-location providers are internalizing routing functions into managed infrastructure bundles. Managed service providers exhibit the highest price sensitivity due to thin margin aggregation models, while government agencies with NIST compliance mandates accept premium pricing for validated supply chains.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced x86 and ARM processor fabrication feeding virtual router compute substrates. Software licensing draws from proprietary routing stacks developed in the United States, Germany, and Japan alongside open-source FRRouting contributions from global developer communities. Tariff exposure on semiconductor imports into Brazil and India threatens deployment cost structures for greenfield telecom infrastructure. Distribution runs through direct enterprise licensing by Cisco and Juniper, hyperscaler marketplace listings, and carrier-neutral colocation channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The virtual router market operates as a cost-of-compliance story where NIST cybersecurity framework validation creates a barrier-to-entry moat that rewards vendors with extended federal certification timelines.
For Market Incumbents: Cement carrier-grade reliability credentials through ETSI NFV Release 4 certification investments before open-source FRRouting contributors achieve feature parity. Defend against Kubernetes-native entrants by deepening backward integration into eBPF-accelerated data plane silicon partnerships. Channel control over enterprise migration from physical chassis to virtualized platforms remains the critical retention lever. For New Entrants and Emerging Players: Mid-market managed service providers in Brazil and India represent an underserved buyer archetype hungry for standardized, low-touch deployment tooling without legacy hardware migration burdens. White-space targets include GDPR-compliant edge routing for European sovereign cloud deployments and AI-driven traffic engineering modules for hyperscale cloud operators. A containerized microservices packaging strategy aligned with ETSI standards offers the most penetrable go-to-market angle against monolithic incumbent offerings. For Investors and Strategic Acquirers: The window for entry favors cloud-native networking specialists with Kubernetes-orchestrated control plane expertise over legacy hardware-dependent vendors. Long-term viability hinges on software-defined networking convergence with zero-trust security functions across the analysis window. Acquisition targets should demonstrate production eBPF deployments at hyperscale. The signal to watch is federal procurement contract awards shifting from hybrid to cloud-native-only architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Control Plane Disaggregation | Separates routing intelligence from physical chassis, enabling Kubernetes-orchestrated deployments at Deutsche Telekom and Vodafone. |
| eBPF Data Plane Acceleration Partnership | Automates kernel-bypass packet processing for hyperscale operators in Northern Virginia and Oregon data center clusters. |
| ETSI NFV Release 4 Certification Investment | Mandates containerized microservice packaging for 5G standalone core pilots across German and French operators. |
| Zero-Trust Security Convergence | Integrates routing and firewall functions for managed service providers serving mid-market financial services clients. |
| Edge Computing Routing Deployment | Positions virtual router instances at last-mile aggregation points for autonomous vehicle networks in Dallas-Fort Worth metro. |
Research Approach
Document review covered ETSI NFV specifications, FCC net-neutrality rulings, NIST cybersecurity framework documentation, and hyperscaler capex disclosures, complemented by interviews with network architects at tier-one telecom operators, cloud infrastructure procurement officers, channel partners distributing routing software, and regulatory compliance leads at financial institutions. Secondary validation drew from SEC filings, TRAI consultation papers, and customs data on semiconductor imports. Bottom-up deployment forecasts triangulated against top-down infrastructure spending projections.
Segment-level outputs across the projection horizon reflect modeled dimensions including deployment architecture, solution type, end-user category, and regional regulatory cluster. CAGRs were derived from replacement-cycle timing analysis and greenfield buildout velocity assessments. Industry-specific inputs incorporated 5G standalone core rollout schedules, edge computing infrastructure subsidies under METI programs, and GDPR data-localization compliance timelines.
Revisions become necessary when semiconductor supply disruptions, net-neutrality regulatory reversals, or open-source routing stack maturity milestones materialize differently than assumed. Forecasts reflect documented assumptions about carrier migration timelines and hyperscaler internalization trends. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global 5G Smart Antenna Market
Network Technology
Network Emulator Market
Network Technology
Protocol Analyzer Market
Network Technology
US Private 5G Network Market
Network Technology
Global Network Probe Market
Network Technology
Application Delivery Controller (ADC) Market
Network Technology
GPON WIFI6 Home Gateway Market
Network Technology
Mobile Accelerator Market
Network Technology
Converged Cable Access Platform (CCAP) Market
Network Technology
Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Global Gigabit Wi-Fi Access Points Market
Network Technology
Europe Self-Healing Networks Market
Network Technology
Network Management Systems (NMS) Market
Network Technology
Passive Optical Network Market
Network Technology
Structured Cabling Market
Network Technology
Germany Residential Gateway Market