
 Global Retail Execution Software Market | 2026-2036
Global Retail Execution Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Retail Execution Software Market Outlook
The capability gap between cloud-native and legacy on-premise vendors is rotating competitive capital allocation toward platform consolidation. Salesforce Consumer Goods Cloud leverages its CRM data backbone to anchor enterprise accounts across beverage and packaged goods verticals. Pepperi specializes in B2B order-taking workflows for wholesale-distributor channels. Reflexis by Zebra dominates workforce scheduling integration with its hardware ecosystem, sustaining defensible positioning in big-box retail.
Retail execution software encompasses mobile-first field force automation platforms that synchronize store-level audits, merchandising compliance, inventory checks, and sales order capture through offline-capable applications with GPS tagging and image-recognition shelf analytics. Cloud-based Solutions lead deployment preference due to lower infrastructure overhead and faster rollout cycles, while Mobile Applications capture the fastest growth trajectory as frontline worker smartphone penetration deepens. Analytics Tools sit at the margin pool center, commanding premium pricing for AI-driven shelf-condition scoring and competitive intelligence dashboards.
GDPR enforcement by European data protection authorities restricts cross-border customer data flows, compelling vendors to architect EU-sovereign cloud instances. The US patchwork of state privacy laws, including CCPA and emerging biometrics regulations, fragments compliance engineering requirements for SaaS providers. FDA oversight of promotional materials in regulated consumer health categories adds a secondary compliance layer for pharmaceutical-adjacent retail segments. Stakeholders must monitor how AI Act risk-classification rules reshape algorithmic shelf-scoring features before committing to platform roadmaps.
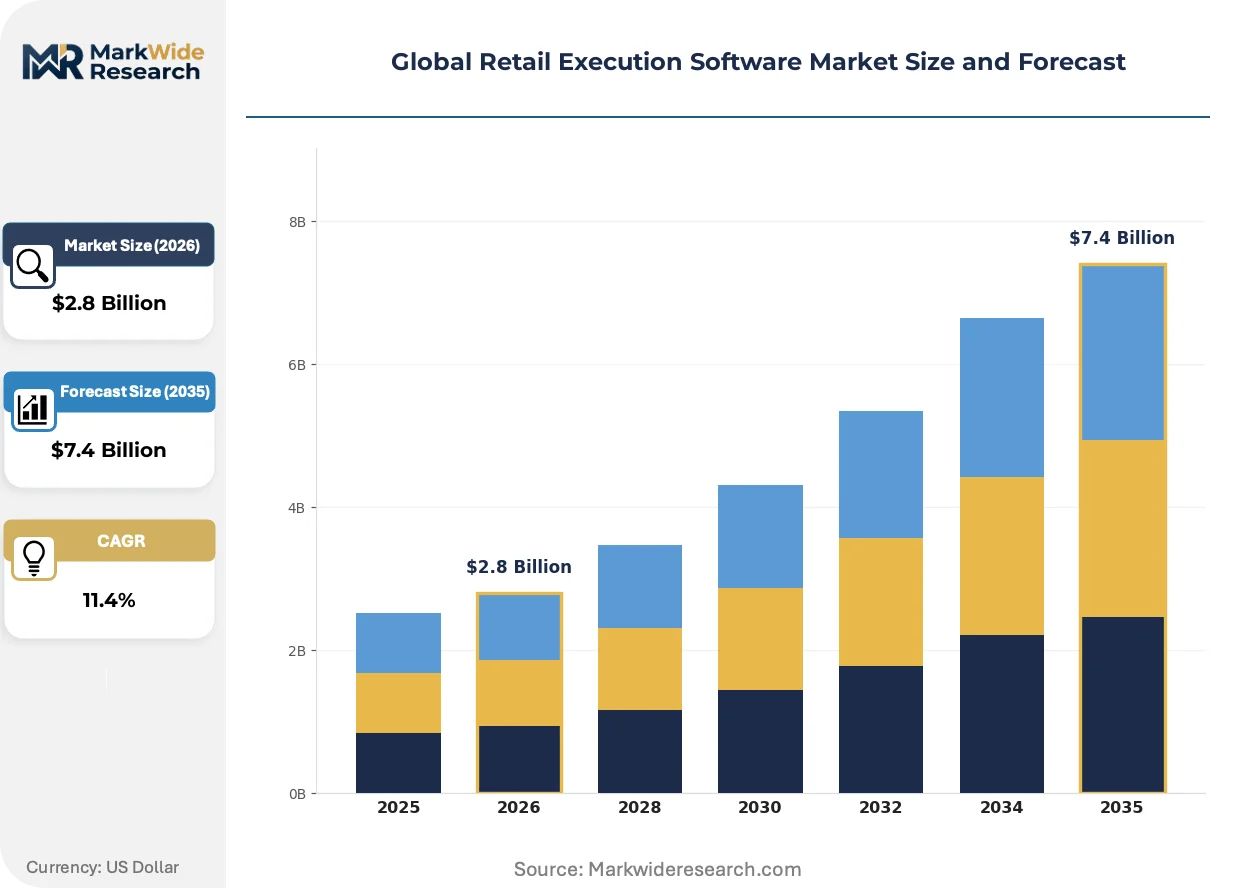
Market Dynamics
The migration from on-premise field force systems to cloud-native architectures is compressing vendor margins while expanding addressable use cases across beverage, packaged goods, and pharmaceutical retail channels.
Growth Catalysts
- GDPR Article 44 cross-border transfer rules:European data protection authorities mandate EU-sovereign cloud instances, forcing vendors to localize infrastructure and creating replacement demand for non-compliant legacy deployments.
- Smartphone penetration among frontline merchandising teams:Android and iOS device ubiquity in developing markets eliminates hardware procurement barriers that previously slowed mobile-first platform adoption.
- AI-driven shelf analytics:Image recognition algorithms scoring out-of-stock conditions and planogram compliance automate audit workflows previously requiring manual labor.
Market Restraints
- State-level privacy fragmentation in the United States:CCPA, CPRA, and emerging biometrics laws in Illinois and Texas multiply compliance engineering costs for SaaS providers serving multi-state retail chains.
- Legacy ERP integration complexity:SAP and Oracle back-end synchronization consumes 40-60% of implementation timelines, delaying time-to-value for enterprise accounts.
- Offline capability requirements:Rural store locations with intermittent cellular coverage demand sophisticated local data caching architectures that inflate development overhead.
Strategic Opportunities
- India's retail digitalization push:Reliance JioMart and Tata Neu platform investments create greenfield demand for field force automation among domestic FMCG brands expanding modern trade coverage.
- EU AI Act risk classification:Algorithmic shelf-scoring features face pending high-risk system designations, creating first-mover advantage for vendors pre-certifying compliance documentation.
- Independent pharmacy chains:Regulated consumer health categories underserved by beverage-focused incumbents present white space for FDA promotional-materials-compliant workflow modules.
Industry Challenges
- Embedded systems engineering talent scarcity:Developers capable of optimizing offline-first SQLite architectures with GPS tagging and camera pipeline integration command premium compensation.
- Multi-tenant data isolation certification:SOC 2 Type II and ISO 27001 audit cycles extend 6-9 months, blocking enterprise procurement approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Retail Execution Software Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Applications, Cloud-based Solutions, On-premise Software, Analytics Tools Customer Type: Retail Chains, E-commerce Platforms, Wholesalers, Independent Stores Deployment: Hybrid, SaaS, On-premises, Public Cloud Service Type: Implementation Services, Support Services, Maintenance Services, Consulting Services |
| Companies Covered | Repsly, Movista, CT Mobile / CT REx (Customertimes), Reflexis by Zebra, Yoobic, Salesforce Consumer Goods Cloud, Axonify, Pepperi, Aforza, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Retail Execution Software Market Strategic Shifts
Edge computing architectures and federated learning models are redistributing computational load from centralized clouds to field devices, altering vendor cost structures and data governance frameworks.
Computer vision inference at the device level is fragmenting competitive positioning in shelf analytics. Edge-deployed TensorFlow Lite models enable real-time planogram verification without cellular backhaul. Beverage manufacturers in Mexico and Southeast Asia pilot these capabilities to reduce audit labor costs. The technology is fragmenting margin pools between camera-enabled hardware suppliers and pure-play software vendors.
GDPR enforcement actions by CNIL in France and ICO in the United Kingdom impose seven-figure penalties for inadequate data retention policies. SaaS providers must architect automated deletion workflows and granular consent management. Pharmaceutical-adjacent retail segments face compounded obligations from FDA 21 CFR Part 11 promotional materials oversight, driving consolidation toward compliance-heavy platform vendors.
Subscription pricing for analytics modules is displacing perpetual licensing in enterprise procurement. Consumer goods manufacturers in Germany and the United States negotiate outcome-based contracts tied to measured shelf-condition improvements. Procurement teams favor vendors offering usage-based tiers over fixed seat licenses. This shift concentrates contract value in quarterly business review cycles rather than upfront implementation fees.
Global Retail Execution Software Market Segmentation
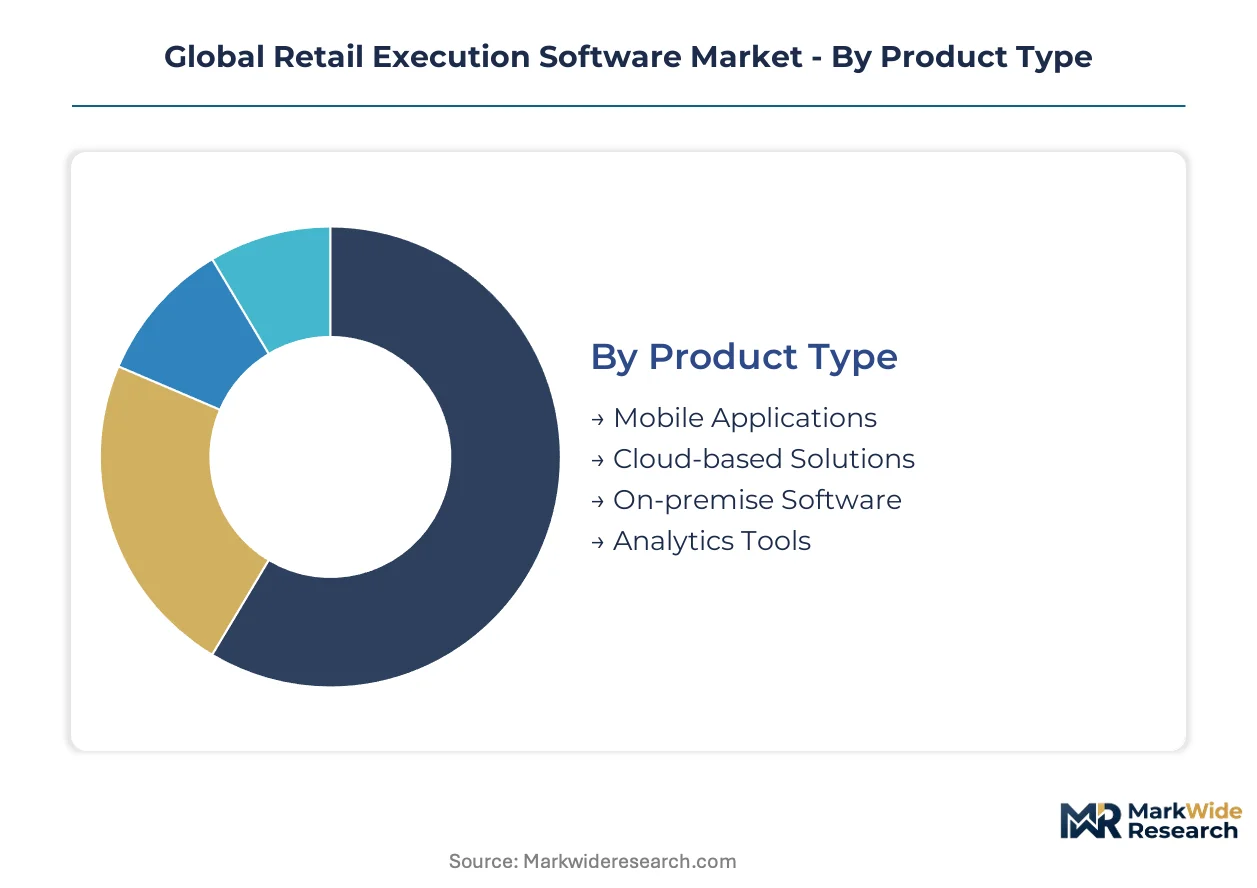
Retail execution software segments diverge sharply in compliance architecture and infrastructure economics. GDPR Article 44 mandates reshape cloud deployment patterns across European accounts, while mobile-first architectures unlock frontier market penetration where cellular coverage remains intermittent.
Product Type:
GDPR Article 44 cross-border transfer rules and FDA 21 CFR Part 11 oversight create divergent certification burdens across software architectures.
- Cloud-based Solutions:Multi-tenant architectures with automated EU-sovereign instance provisioning satisfy CNIL and ICO enforcement actions. German beverage manufacturers anchor enterprise demand here, prioritizing SOC 2 Type II certification for SAP ERP synchronization. Established volume favors Cloud-based Solutions; emerging adoption favors Mobile Applications.
- Mobile Applications:Offline-capable SQLite architectures with TensorFlow Lite inference at the device level eliminate cellular dependency for rural store audits. Indian FMCG brands expanding modern trade coverage through Reliance JioMart partnerships drive fastest expansion. GPS tagging and camera pipeline integration command premium embedded systems talent.
- Analytics Tools:AI-driven shelf-condition scoring modules face pending EU AI Act high-risk system designations.
- On-premise Software:Legacy SAP and Oracle back-end synchronization consumes 40-60% of implementation timelines.
Margin concentration follows compliance intensity: cloud-native platforms capture outcome-based contract value, while on-premise deployments stagnate.
Customer Type:
Procurement scale and integration complexity separate multinational mandates from regional deployment patterns.
- Retail Chains:Multi-state operators in the United States navigate CCPA, CPRA, and Illinois biometrics law fragmentation. Big-box retailers demand Reflexis-style workforce scheduling integration with Zebra hardware ecosystems. Volume concentrates among beverage and packaged goods verticals.
- Wholesalers:B2B order-taking workflows for wholesale-distributor channels require Pepperi-specialized merchandising compliance modules. German distributors negotiate usage-based tiers over fixed seat licenses.
- E-commerce Platforms:Tata Neu and Reliance JioMart investments in India create greenfield field force automation demand.
- Independent Stores:Rural locations with intermittent cellular coverage demand sophisticated local data caching architectures.
Enterprise procurement favors Retail Chains; platform consolidation targets Independent Stores.
Deployment:
Data residency requirements and latency sensitivity determine architectural selection across regulatory jurisdictions.
- SaaS:Subscription pricing displaces perpetual licensing in enterprise procurement. Automated deletion workflows and granular consent management satisfy GDPR enforcement by French CNIL and UK ICO. German and United States consumer goods manufacturers anchor outcome-based contract negotiation.
- Hybrid:Federated learning models redistribute computational load between centralized clouds and field devices. Edge computing architectures alter vendor cost structures for beverage manufacturers piloting real-time planogram verification in Mexico and Southeast Asia.
- Public Cloud:Lower infrastructure overhead and faster rollout cycles attract mid-market accounts without EU data sovereignty obligations.
- On-premises:FDA promotional materials oversight in pharmaceutical-adjacent retail segments sustains residual demand.
SaaS captures procurement preference; Hybrid gains share fastest where AI inference shifts to device level.
Service Type:
Implementation risk and ongoing compliance burden separate one-time project revenue from recurring support economics.
- Implementation Services:ERP integration complexity consumes 40-60% of deployment timelines. ISO 27001 and SOC 2 Type II audit cycles extend 6-9 months, blocking enterprise procurement approvals.
- Support Services:Quarterly business review cycles concentrate contract value as subscription pricing displaces upfront implementation fees.
- Consulting Services:AI Act risk-classification pre-certification documentation creates first-mover advantage for vendors.
- Maintenance Services:Automated deletion workflow architecture for GDPR compliance sustains recurring revenue.
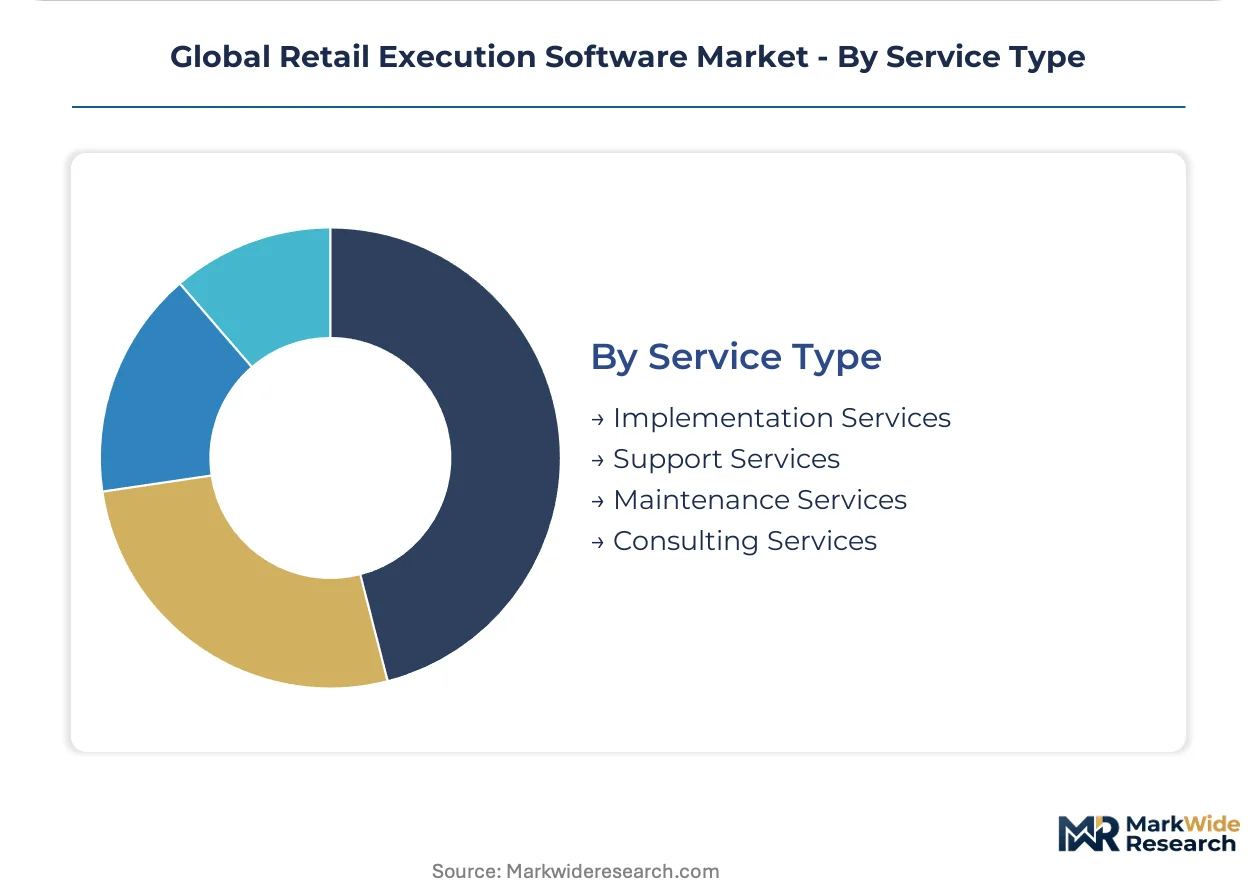
Implementation Services dominate initial contract value; Support Services expand lifetime revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and the United States where enterprise beverage manufacturers negotiate outcome-based contracts, while Indian vendors compete on volume throughput for JioMart-integrated deployments.
United States
Beverage and packaged goods manufacturers anchor enterprise procurement through Salesforce Consumer Goods Cloud deployments. CCPA, CPRA, and Illinois biometrics laws fragment compliance engineering costs for SaaS providers serving multi-state retail chains. Chicago and Dallas clusters concentrate big-box retail workforce scheduling integration with Zebra hardware ecosystems.
Germany
German beverage manufacturers prioritize SOC 2 Type II certification for SAP ERP synchronization in cloud-native platform selection. GDPR Article 44 mandates EU-sovereign cloud instances, compelling vendors to localize infrastructure and creating replacement demand for non-compliant legacy systems. Munich and Hamburg industrial corridors drive subscription pricing negotiation for analytics modules tied to measured shelf-condition improvements.
India
Domestic FMCG brands expanding modern trade coverage through Reliance JioMart and Tata Neu partnerships generate greenfield demand for mobile-first field force automation. BIS standards and RBI data localization guidance shape vendor architecture decisions for payment-integrated retail workflows. Mumbai and Bangalore tech corridors concentrate embedded systems talent for offline-capable SQLite architectures with GPS tagging.
France
CNIL enforcement actions impose seven-figure penalties for inadequate data retention policies, driving automated deletion workflow architecture among SaaS providers. French beverage distributors negotiate usage-based tiers over fixed seat licenses for B2B order-taking modules. Paris and Lyon clusters concentrate AI-driven shelf analytics development facing pending EU AI Act high-risk system designations.
United Kingdom
ICO enforcement on cross-border data flows restricts customer data architecture for vendors serving UK-based retail chains. Independent pharmacy chains present white space for FDA promotional-materials-compliant workflow modules in regulated consumer health categories. London and Manchester corridors concentrate quarterly business review cycles as subscription pricing displaces upfront implementation fees.
Global Retail Execution Software Market Competitive Environment
Concentration sits with CRM-anchored enterprise platforms and specialized field force automation vendors serving distinct vertical workflows. The vendor base separates into three strategic archetypes: cloud-native platforms with ERP integration depth, mobile-first specialists for wholesale-distributor channels, and hardware-ecosystem-integrated workforce schedulers. M&A activity targets offline-capable architecture talent, while geographic expansion focuses on EU-sovereign instance provisioning for GDPR compliance.
Among CRM-anchored platforms, Salesforce Consumer Goods Cloud exemplifies enterprise beverage and packaged goods vertical penetration. Pepperi occupies a position within B2B order-taking workflow specialization for wholesale-distributor channels. Reflexis by Zebra represents hardware-ecosystem integration dominance in big-box retail workforce scheduling. These three anchors illustrate how competitive capital allocation rotates toward platform consolidation as the capability gap between cloud-native and legacy on-premise vendors widens.
| Leading Market Players |
|---|
| Repsly |
| Movista |
| CT Mobile / CT REx (Customertimes) |
| Reflexis by Zebra |
| Yoobic |
| Salesforce Consumer Goods Cloud |
| Axonify |
| Pepperi |
| Aforza |
| Others |
Value Chain & Pricing Dynamics
Outcome-based subscription contracts lock in multi-year platform access while anchoring price visibility to measured shelf-condition improvements rather than seat-based metrics. German beverage manufacturers and United States packaged goods producers negotiate these structures to align vendor compensation with audit labor reduction and planogram compliance gains.
Pricing Analysis
The customization-premium spread separates standard SaaS tiers from configured-to-order deployments with SAP ERP synchronization and EU-sovereign instance provisioning. Subscription pricing for analytics modules displaces perpetual licensing as procurement teams favor usage-based tiers over fixed seat licenses. Price differentiation hinges on SOC 2 Type II certification status and AI-driven shelf-scoring feature depth. Cost compression in mid-market segments intensifies as Android and iOS ubiquity eliminates hardware procurement barriers. Independent pharmacy chains exhibit highest price sensitivity due to constrained IT budgets, while enterprise beverage manufacturers demonstrate lowest sensitivity given outcome-based contract structures.
Supply Chain Analysis
Inventory and lead-time dynamics for embedded systems talent extend implementation cycles as developers capable of optimizing offline-first SQLite architectures with GPS tagging command premium compensation. Supply concentrates in the United States, Germany, and India as retail digitalization investments intensify. Platform development draws from cloud infrastructure providers, specialized computer vision hardware suppliers, and compliance documentation consultancies. Single-source vulnerability sits with TensorFlow Lite inference model providers for edge-deployed shelf analytics. Distribution runs through direct enterprise sales teams for cloud-native platforms and channel partners for mobile-first specialists serving wholesale-distributor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from vertically integrated ERP vendors embedding field force modules as loss-leader extensions, compressing standalone platform pricing power.
For Market Incumbents: Fortify defensible positioning through EU-sovereign cloud instance provisioning to capture GDPR-driven replacement demand and deepen TensorFlow Lite optimization capabilities for edge inference workloads. Acquire embedded systems engineering talent scarce across Mumbai and Bangalore tech corridors. Prioritize AI Act pre-certification documentation for algorithmic shelf-scoring features before high-risk system designations formalize. For New Entrants and Emerging Players: Regulatory compliance consulting layers represent an underserved service gap where incumbents under-serve mid-market accounts navigating CCPA, CPRA, and Illinois biometrics law fragmentation. Target independent pharmacy chains in the United Kingdom with FDA 21 CFR Part 11 promotional-materials-compliant workflow modules. Pursue white-label platform partnerships with Reliance JioMart and Tata Neu to penetrate India's greenfield modern trade expansion. For Investors and Strategic Acquirers: Offline-capable architecture specialists with proven SQLite caching and GPS pipeline integration command acquisition premiums as capability scarcity intensifies. Frame long-term viability around platform consolidation winners capturing outcome-based contract value concentration. Monitor EU AI Act risk-classification finalization as inflection indicator for algorithmic shelf-scoring feature compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| EU-Sovereign Cloud Instance Provisioning | CNIL and ICO enforcement actions mandate localized infrastructure for European accounts. |
| Edge Computing Architecture Development | TensorFlow Lite inference at device level eliminates cellular dependency for rural audits. |
| AI Act Pre-Certification Documentation | Algorithmic shelf-scoring features face pending high-risk system designations in France. |
| Offline-First SQLite Optimization | Reliance JioMart partnerships in India demand intermittent connectivity resilience. |
| SAP ERP Synchronization Deepening | German beverage manufacturers prioritize SOC 2 Type II certified integration layers. |
Study Parameters
Initial hypotheses were tested against primary input from CTOs at beverage manufacturers, IT procurement officers at packaged goods enterprises, platform engineers specializing in offline architectures, and channel partners serving wholesale-distributor segments and refined through secondary validation against SEC filings, hyperscaler capex disclosures, App Annie mobile deployment data, and EU regulatory enforcement databases. Bottom-up sizing of cloud-native and mobile-first deployments triangulated against top-down market aggregation.
Variance decomposition across deployment model, organization size, vertical integration complexity, and regional adoption pattern shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation with macroeconomic retail digitalization indicators. Industry-specific forecast inputs included frontline worker smartphone penetration curves and GDPR Article 44 compliance cost estimates.
Forecasts assume regulatory continuity in GDPR enforcement by CNIL and ICO, FDA 21 CFR Part 11 oversight, and emerging EU AI Act classifications; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
E-Invoicing Software Market
Software & Services
Global Audit Software Market
Software & Services
UI Design Software Market
Software & Services
North America IT Services Market
Software & Services
Employee Advocacy Software Market
Software & Services
Europe Digital Signage Software Market
Software & Services
Stone Analysis Software Market
Software & Services
Staffing Software Market
Software & Services
Asia-Pacific Accounting Software Market
Software & Services
Global Forestry Software Market
Software & Services
Computational Medicine and Drug Discovery Software Market
Software & Services
PCB Layout Software Market
Software & Services
Global User Interface Service Market
Software & Services
Global Email Software Market
Software & Services
Global Virtual Desktop Market
Software & Services
Instant Messaging Software Market