
 Asia-Pacific Printing Software Market | 2026-2036
Asia-Pacific Printing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Printing Software Market Analytics
Packaging converters is rebalancing toward cloud-native print management as brand owners demand shorter run lengths and versioned SKUs. HP Inc. anchors North Asian enterprise accounts with integrated print-to-cut workflows. Canon Inc. competes through specialized large-format RIP engines for signage producers. PaperCut Software International dominates mid-market print cost recovery across Australian education networks.
Asia-Pacific printing software encompasses raster image processors, color management engines, job ticketing systems, and output management platforms that translate digital files into machine-ready instructions for inkjet, offset, and toner-based devices. These systems manage ICC profile embedding, halftone screening algorithms, and substrate-specific ink laydown curves to ensure color accuracy across heterogeneous equipment fleets. Cloud-based platforms are capturing the fastest expansion as distributed workforces require browser-based job submission and proofing without VPN dependency. On-premises deployments retain structural importance in Japanese financial institutions where data residency requirements block public cloud adoption. Desktop software persists as a margin pool among legacy newspaper prepress rooms reluctant to retrain operators.
India's BIS labeling standards, Australia's Privacy Act data-handling obligations for printed patient records, and Japan's METI cybersecurity guidelines for connected industrial printers collectively shape product roadmaps and certification requirements. Compliance costs favor vendors offering multi-tenant platforms with regional data sovereignty controls. Stakeholders must weigh hybrid cloud architectures against pure SaaS models as ASEAN member states diverge on cross-border data flow enforcement.
Market Dynamics
Cloud-native print management platforms are compressing deployment cycles across Asia-Pacific packaging corridors as pharmaceutical converters race against India's BIS traceability deadlines. This structural acceleration favors vendors with multi-tenant architectures capable of rapid regulatory reconfiguration.
Growth Catalysts
- India's BIS labeling mandates:Pharmaceutical contract packers in Mumbai-Pune corridor are replacing legacy prepress systems to embed serialized traceability codes. This regulatory pressure is pulling through integrated RIP-to-output workflows.
- Cloud browser-based proofing:Distributed brand owner teams across Southeast Asia now demand VPN-independent job submission. Software vendors with zero-install client interfaces capture upgrade budgets from converter IT departments.
- Short-run SKU versioning:Consumer goods producers in Thailand and Vietnam require rapid job changeover capabilities. Print automation software with dynamic imposition engines reduces makeready waste for folding carton applications.
Market Restraints
- Data residency compliance costs:Japan's METI cybersecurity guidelines for connected industrial printers block public cloud adoption at financial institutions. Vendors must maintain parallel on-premises codebases, fragmenting R&D resources.
- Legacy operator skill lock-in:Newspaper prepress rooms across Australia and New Zealand retain desktop-based RIP installations. Retraining-resistant workforces delay subscription revenue conversion for SaaS-native vendors.
- Substrate-ink calibration complexity:Southeast Asian converters source films and boards from fragmented regional suppliers. Each substrate variation demands custom ICC profile development, inflating implementation timelines.
Strategic Opportunities
- Indonesian archipelago penetration:Islands beyond Java remain underserved by integrated print management. Local packaging cooperatives present channel partners with white-label platform distribution potential.
- Australian education sector consolidation:University print cost recovery systems face replacement cycles. Vendors offering pull-print authentication with student billing integration capture multi-campus procurement.
- AI-driven color prediction:Machine learning models trained on historical press runs enable first-pull accuracy without manual densitometer iteration. Early deployments in Japanese commercial print houses demonstrate proof-of-concept.
Industry Challenges
- Prepress technician scarcity:Vietnam and Philippines packaging clusters lack trained color management specialists. Vocational pipeline gaps force converters to rely on vendor field engineers for routine profile maintenance.
- Hybrid cloud integration complexity:ASEAN member states diverge on cross-border data flow enforcement. Vendors architecting single-tenant edge nodes for each national jurisdiction face escalating DevOps overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Printing Software Market |
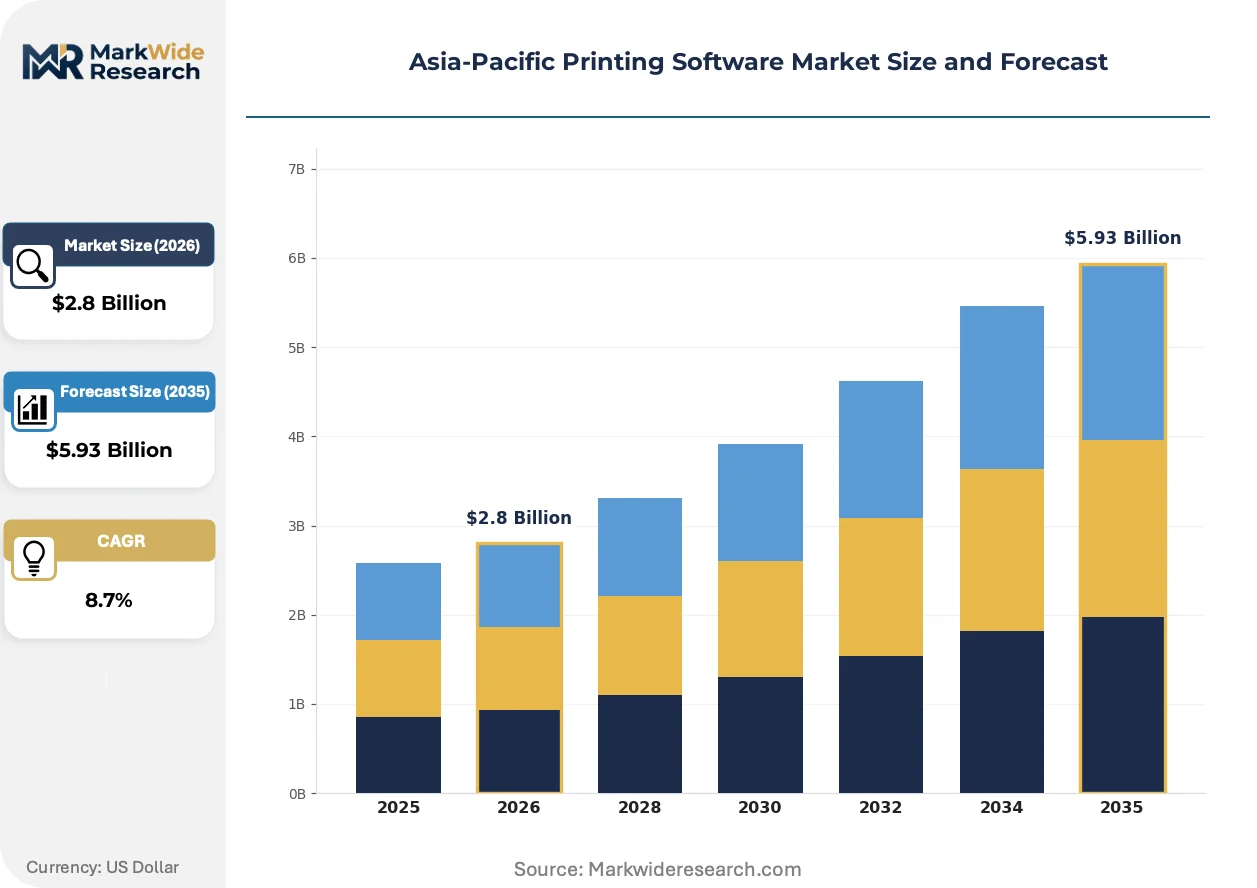
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Software, Mobile Applications, Web-based Solutions, Cloud-based Platforms Industry Vertical: Education, Healthcare, Retail, Manufacturing Deployment: On-Premises, Private Cloud, Public Cloud, Hybrid Cloud Customer Type: Small Businesses, Enterprises, Government Agencies, Non-profits |
| Companies Covered | Canon Inc., HP Inc., Xerox Corporation, Seiko Epson Corporation, Ricoh Company Ltd., Konica Minolta Inc., Dai Nippon Printing Co. Ltd., Toppan Printing Co. Ltd., PaperCut Software International, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Printing Software Market Evolving Landscape
Electrification of software-defined color pipelines is compressing the gap between design intent and press output across heterogeneous Asia-Pacific equipment fleets. Three convergent developments are restructuring competitive positioning.
AI-powered spectral prediction is electrifying prepress workflows by replacing iterative press-side color matching with neural network inference. Japanese commercial printers with aging Heidelberg and Komori fleets adopt these tools to extend asset life without capital replacement. The technology is compressing makeready times from hours to minutes on complex spot-color cosmetic packaging.
Australia's Privacy Act data-handling obligations for printed patient records are mandating audit-trail functionality in healthcare output management. Software vendors must embed immutable job logging with 7-year retention to serve hospital network procurement. New South Wales and Victoria health districts now exclude uncertified platforms from tender consideration.
Brand owners in South Korea's cosmetics and electronics sectors are unbundling print specification from converter selection. Direct cloud-to-press job submission portals let packaging designers bypass traditional prepress intermediaries. This disintermediation concentrates margin pressure on mid-tier converters while rewarding software vendors with direct enterprise relationships.
Asia-Pacific Printing Software Market Segmentation
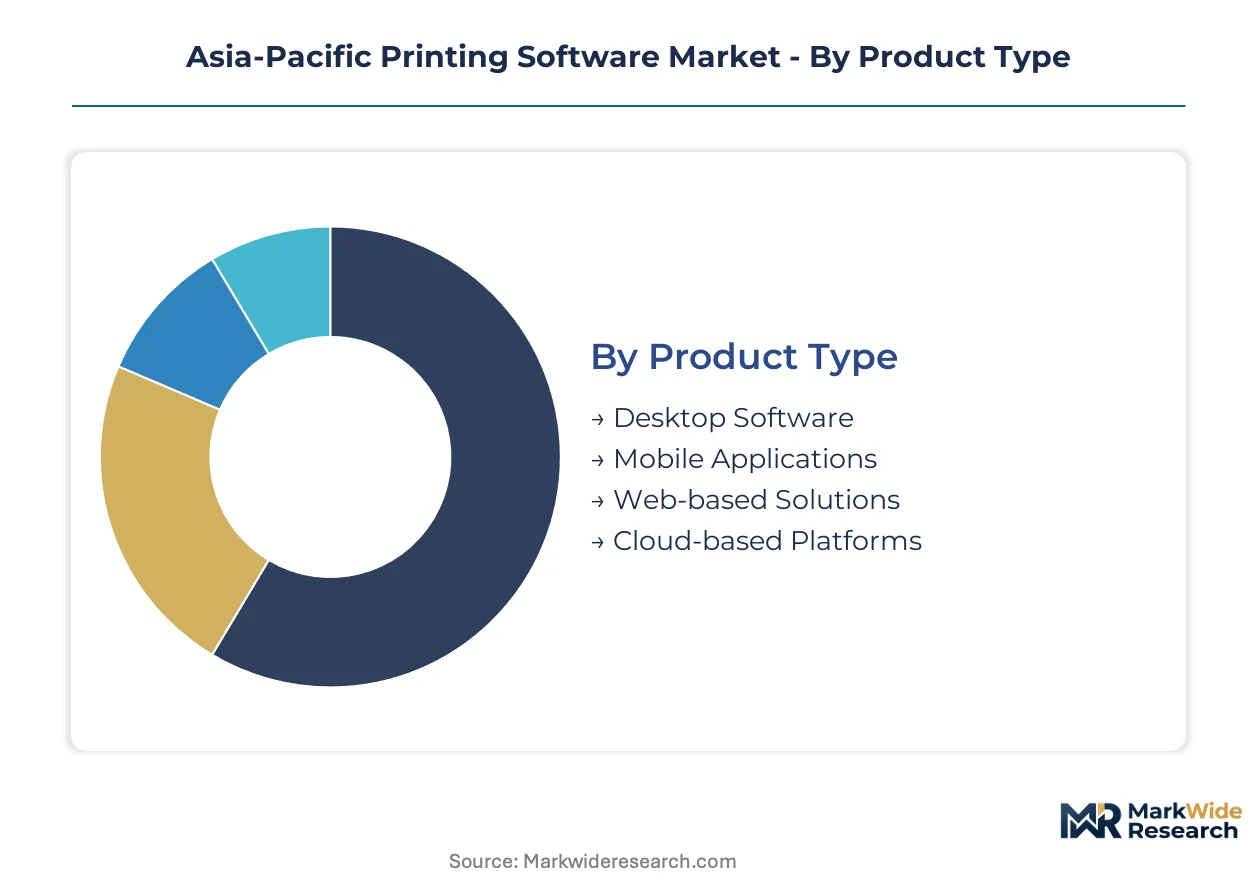
Software-defined print workflows fragment across deployment architectures, customer scale tiers, and vertical compliance regimes. Segmentation reveals where certification burdens concentrate and which product configurations capture upgrade budgets from regulated industries.
Product Type:
Cloud-based Platforms and Web-based Solutions carry Australia's Privacy Act data-handling obligations for printed patient records, while Desktop Software operates outside these audit-trail mandates. Mobile Applications face lighter regulatory scrutiny but limited enterprise procurement.
- Cloud-based Platforms:Multi-tenant architectures with browser-based job submission and proofing eliminate VPN dependency for distributed Southeast Asian brand owner teams. Pharmaceutical contract packers in India's Mumbai-Pune corridor deploy these to meet BIS traceability deadlines for serialized labeling.
- Web-based Solutions:Zero-install client interfaces reduce IT deployment overhead across Australian university networks. Education sector procurement favors these for student billing integration and pull-print authentication across multi-campus environments.
- Desktop Software:Legacy RIP installations persist in newspaper prepress rooms across Australia and New Zealand where retraining-resistant workforces delay SaaS conversion.
- Mobile Applications:Limited to ad-hoc job monitoring and approval workflows rather than production-critical prepress functions.
Cloud-based Platforms sit at the top of the volume ranking, with Web-based Solutions climbing the fastest.
Industry Vertical:
Healthcare and Education concentrate compliance-driven procurement, while Retail and Manufacturing chase operational efficiency gains from shorter run lengths.
- Healthcare:Australia's Privacy Act mandates immutable job logging with 7-year retention for printed patient records. New South Wales and Victoria health districts exclude uncertified output management platforms from tender consideration.
- Education:University print cost recovery systems across Australia face replacement cycles. Student billing integration and multi-campus authentication drive software selection criteria.
- Retail:Consumer goods producers in Thailand and Vietnam demand rapid job changeover for versioned SKUs. Dynamic imposition engines reduce makeready waste in folding carton applications.
- Manufacturing:Packaging converters integrate print automation with ERP systems for substrate inventory synchronization.
Healthcare commands the steepest pricing tier due to certification overhead, while Retail expands most quickly on SKU proliferation.
Deployment:
Public Cloud deployments confront Japan's METI cybersecurity guidelines for connected industrial printers, fragmenting vendor R&D across parallel codebases.
- Public Cloud:Blocked at Japanese financial institutions by data residency requirements. Favors pharmaceutical converters in Southeast Asia with distributed brand owner teams requiring VPN-independent access.
- Hybrid Cloud:Architected for ASEAN cross-border data flow divergence. Single-tenant edge nodes per national jurisdiction escalate DevOps overhead for vendors.
- Private Cloud:Preferred by Australia's healthcare networks for patient record audit-trail isolation.
- On-Premises:Structural importance in Japanese financial institutions where regulatory compliance blocks public cloud adoption entirely.
Hybrid Cloud dominates new procurement conversations, with Public Cloud gaining share fastest where regulatory barriers permit.
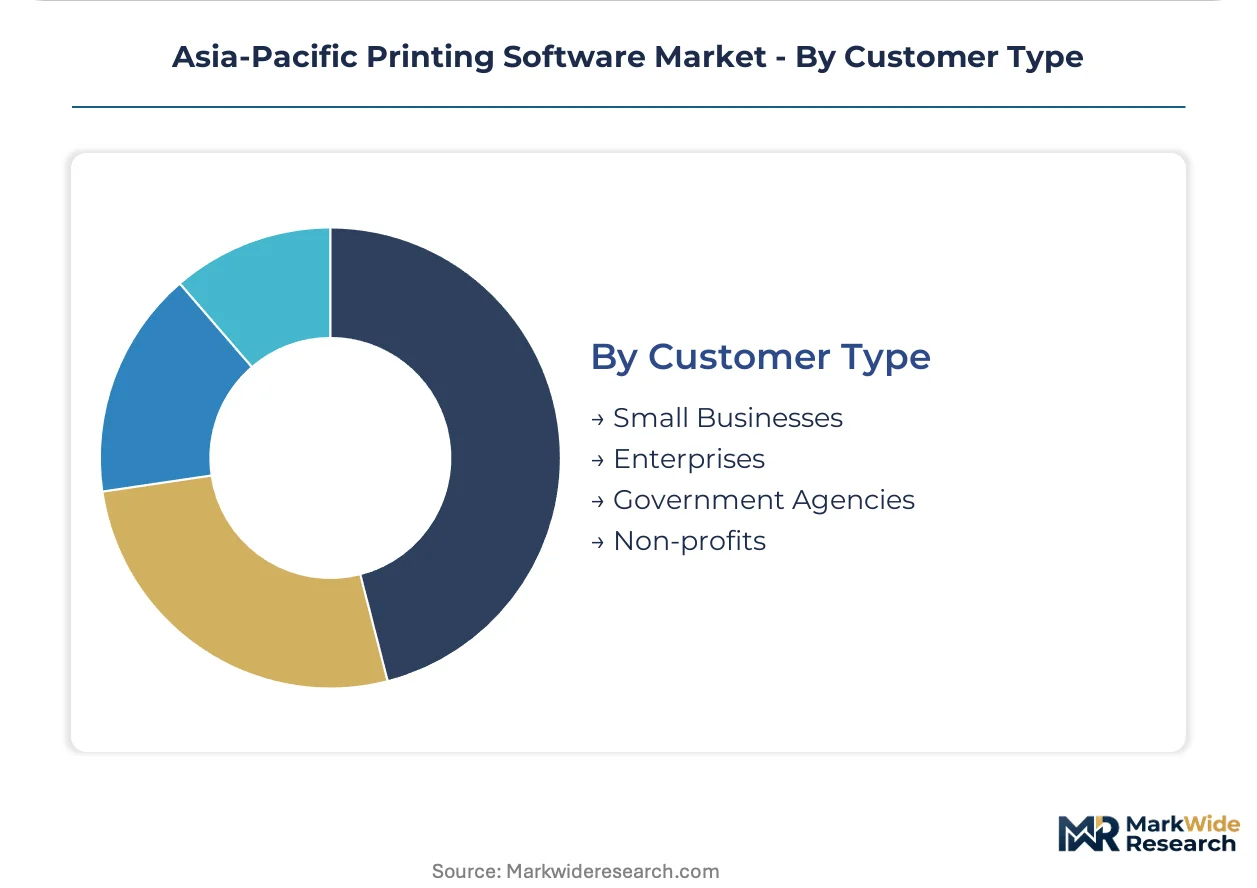
Customer Type:
Enterprises and Government Agencies impose certification requirements that Small Businesses circumvent through lighter configurations.
- Enterprises:South Korean cosmetics and electronics brand owners deploy direct cloud-to-press job submission portals. Disintermediation of traditional prepress intermediaries concentrates margin pressure on mid-tier converters.
- Government Agencies:India's BIS labeling mandates pull through integrated RIP-to-output workflows at pharmaceutical contract packers. Procurement requires demonstrable traceability code embedding capabilities.
- Small Businesses:Packaging cooperatives across Indonesian islands beyond Java present white-label platform distribution potential for channel partners.
- Non-profits:Cost recovery functionality takes priority over advanced color management or regulatory compliance features.
Enterprises anchor revenue concentration, with Government Agencies expanding most quickly on regulatory deadline pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing print software procurement across the Asia-Pacific as pharmaceutical converters migrate toward jurisdictions with clearer compliance roadmaps and subsidized digital infrastructure. Cost-of-compliance gaps between mature and emerging markets are accelerating vendor localization strategies.
India
Pharmaceutical contract packers in the Mumbai-Pune industrial corridor are replacing legacy prepress systems to embed BIS-mandated serialized traceability codes. The Bureau of Indian Standards labeling deadlines are pulling through integrated RIP-to-output workflows. Western Maharashtra packaging clusters now concentrate upgrade budgets for cloud-native print management platforms.
Japan
Commercial print houses with aging Heidelberg and Komori fleets are adopting AI-powered spectral prediction tools to extend asset life without capital replacement. METI cybersecurity guidelines for connected industrial printers block public cloud adoption at financial institutions. Kanto and Kansai regions maintain structural demand for on-premises deployment architectures.
Australia
University print cost recovery systems across New South Wales and Victoria face synchronized replacement cycles. The Privacy Act mandates immutable job logging with 7-year retention for printed patient records, excluding uncertified platforms from hospital network procurement. Education and healthcare verticals drive browser-based job submission demand.
South Korea
Cosmetics and electronics brand owners are unbundling print specification from converter selection through direct cloud-to-press job submission portals. This disintermediation concentrates margin pressure on mid-tier converters while rewarding vendors with direct enterprise relationships. Seoul Capital Area packaging designers bypass traditional prepress intermediaries.
Indonesia
Packaging cooperatives across islands beyond Java remain underserved by integrated print management platforms. Local converters present channel partners with white-label platform distribution potential. The archipelago's fragmented substrate supply chains demand custom ICC profile development, inflating implementation timelines for standardized software deployments.
Asia-Pacific Printing Software Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors architect hybrid cloud solutions for ASEAN's divergent cross-border data flow enforcement. The vendor base clusters around three archetypes: diversified hardware-software conglomerates with integrated print-to-cut workflows, specialized RIP engine developers for large-format applications, and SaaS-native platforms targeting mid-market cost recovery. M&A activity and technology licensing agreements represent the primary competitive vectors as incumbents acquire AI-driven color prediction capabilities.
Within the diversified hardware-software tier, Canon Inc. and HP Inc. anchor competitive positioning through enterprise account penetration across North Asian markets. PaperCut Software International exemplifies the SaaS-native archetype with concentrated presence in Australian education networks. These three entities represent distinct strategic postures: equipment-integrated workflow bundling, specialized large-format engine development, and vertical-specific subscription platforms.
| Leading Market Players |
|---|
| Canon Inc. |
| HP Inc. |
| Xerox Corporation |
| Seiko Epson Corporation |
| Ricoh Company Ltd. |
| Konica Minolta Inc. |
| Dai Nippon Printing Co. Ltd. |
| Toppan Printing Co. Ltd. |
| PaperCut Software International |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up SaaS specialists in Australian education networks and Japanese financial services are compressing channel margins while extending payment terms to substrate calibration engineers, tightening pricing discipline across cloud-native print management deployments.
Pricing Analysis
Distributor margins in Southeast Asian pharmaceutical packaging corridors absorb the steepest compression as BIS-mandated traceability upgrades pull through integrated RIP-to-output workflows. Three-tier pricing structure across enterprise, mid-market, and cooperative tiers reflects certification grade and volume scale. Pricing pressure stems from cloud-native vendors undercutting on-premises legacy support contracts. Mid-market converters in Thailand and Vietnam exhibit highest price sensitivity; Japanese financial institutions show lowest sensitivity due to METI compliance lock-in.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from South Korean cosmetics brand owners deploying cloud-to-press job submission portals. Software development concentrates in Australia, Japan, and India; specialized ICC profile engineering clusters in Singapore and Hong Kong. Raw material dependencies include hyperscaler compute capacity, spectral measurement hardware, and substrate-specific color databases. Single-source vulnerability sits with cloud infrastructure providers serving ASEAN cross-border data flows. Distribution runs through systems integrators anchored in Mumbai-Pune and Sydney-Melbourne corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with India's BIS labeling mandates for pharmaceutical traceability generating irreversible upgrade cycles across packaging converters.
For Market Incumbents: Lock in multi-tenant architecture advantages by accelerating edge-node deployment for ASEAN data sovereignty requirements. Acquire AI-driven spectral prediction capabilities before Japanese commercial print houses complete vendor consolidation. Channel control through certified systems integrators in the Mumbai-Pune corridor remains the critical defensive lever against SaaS-native challengers. For New Entrants and Emerging Players: Begin with white-label platform distribution to Indonesian packaging cooperatives beyond Java, where integrated print management penetration remains minimal. Target Australian university replacement cycles with student billing integration as the anchor feature. Direct sales to South Korean brand owner design teams bypasses entrenched converter relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized RIP engine developers serving large-format signage producers. Long-term viability hinges on regulatory certification moats widening across healthcare and pharmaceutical verticals. Watch for AI-powered color prediction proof-of-concept deployments in Japanese commercial houses as inflection signal for technology acquisition windows.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Multi-tenant architectures capture BIS traceability upgrade budgets across Indian pharmaceutical corridors. |
| Acquisition of Specialist Firm | AI-driven spectral prediction capabilities extend asset life for aging Heidelberg and Komori fleets in Japan. |
| Geographic Expansion | Edge-node deployment addresses ASEAN cross-border data flow divergence and METI cybersecurity guidelines. |
| Strategic Partnership | Systems integrator alliances in Mumbai-Pune and Sydney-Melbourne corridors lock out direct-sales competitors. |
| Product Launch | Zero-install client interfaces with student billing integration capture Australian education replacement cycles. |
Research Methodology
Coverage spans India, Japan, Australia, South Korea, and Southeast Asia, with primary inputs from each. The analysis combines structured interviews with print automation directors, packaging converter IT managers, pharmaceutical contract packer operations heads, and university procurement officers with secondary validation. Sources include BIS regulatory filings, METI cybersecurity guidelines, Australian Privacy Act compliance documentation, SEC 10-K software segment disclosures, and hyperscaler regional capex reports. Bottom-up demand modeling and top-down market sizing triangulate volume estimates.
Granularity-level framing segments the market by deployment architecture, customer scale tier, vertical compliance regime, and regional regulatory cluster. Modeled dimensions include cloud versus on-premises adoption patterns, pharmaceutical versus education versus retail verticals, and enterprise versus government versus small business procurement. CAGRs derive from regression analysis of historical upgrade cycle timing and regulatory deadline impacts. Forecast inputs incorporate BIS labeling mandate enforcement timelines and Australian hospital network tender schedules.
Several conditions sit outside the modeled scope, including potential relaxation of Japan's METI cybersecurity guidelines, accelerated SaaS conversion in Australian newspaper prepress rooms, and breakthrough substrate-agnostic color prediction algorithms. Forecasts reflect assumptions about regulatory deadline adherence and cloud infrastructure cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Service Resource Planning (SRP) Saas Solutions Market
Software & Services
Global Digital Signage Software Market
Software & Services
Global Rapid Application Development Market
Software & Services
VFX Software Market
Software & Services
Integration Brokerage Software Market
Software & Services
Global Server Management Software Market
Software & Services
Truck Dispatch Software Market
Software & Services
Background Removal Software Market
Software & Services
Configuration Management (CM) Tools Market
Software & Services
Global Data Recovery Software Market
Software & Services
Software Defined Broadcasting Market
Software & Services
Europe Saas-Based SCM Market
Software & Services
Dynamic Slotting and Storage Optimization Software Market
Software & Services
Vertical Software Market
Software & Services
Compositing Software Market
Software & Services
Global Online Survey Software Market