
 Global Database Software Market | 2026-2036
Global Database Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Database Software Market Analysis
ISO/IEC 27001 certification is unwinding competitive access for database vendors serving regulated European and North American clients. Oracle Corporation leverages its embedded position in legacy enterprise stacks to sustain renewal revenue. MongoDB, Inc. specializes in document-oriented architectures that anchor developer-led adoption cycles.
Database software comprises structured data storage, retrieval, and management systems built on SQL or alternative query languages with ACID or BASE consistency models, serving transactional and analytical workloads across enterprises. Relational Database systems still occupy the largest installed base, though margin pools are shifting toward Cloud-Based deployment models where consumption pricing captures variable workloads. NoSQL Database architectures lead in real-time analytics and unstructured data pipelines, while Data Security functionality commands premium pricing as breach liability escalates.
FDA 21 CFR Part 11, HIPAA, and GDPR collectively shape product requirements for audit trails, encryption standards, and cross-border data residency in healthcare and financial applications. The EU AI Act adds algorithmic accountability layers that database vendors must embed at the infrastructure level. Stakeholders should monitor how sovereign cloud mandates in Germany, France, and India fragment deployment architecture decisions.
Market Dynamics
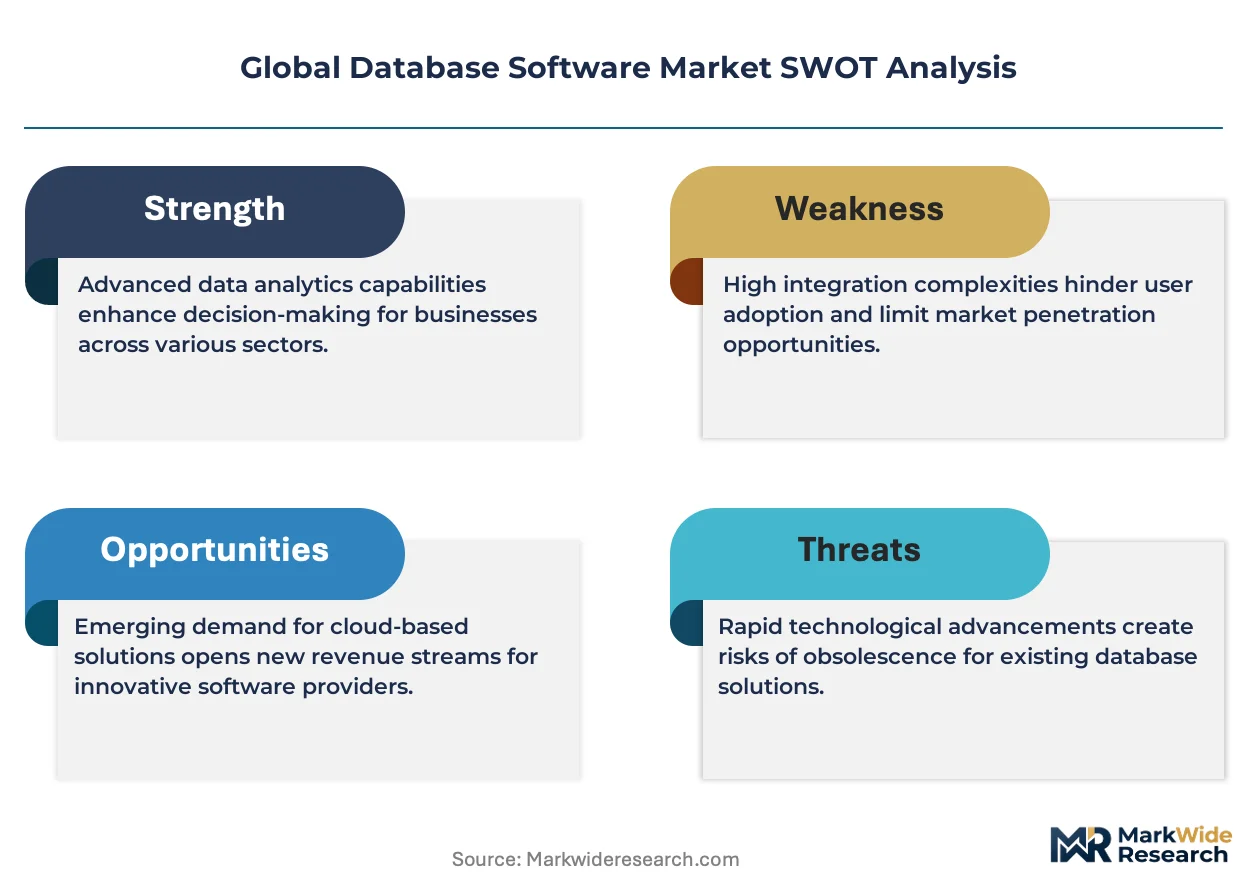
Cloud consumption pricing is fragmenting traditional perpetual-license revenue pools as hyperscalers embed database services within broader infrastructure bundles. This shift compresses standalone vendor margins while expanding addressable workload volumes.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements are forcing enterprises to upgrade data infrastructure for auditability and lineage tracking across AI pipelines.
- Real-time analytics workloads:IoT sensor networks and streaming data pipelines in manufacturing and logistics are driving NoSQL and time-series database adoption.
- BFSI cloud migration:Financial institutions in the United States and United Kingdom are accelerating displacement of on-premise Oracle and SQL Server estates to managed cloud services.
Market Restraints
- Skilled DBA scarcity:Shortage of certified database administrators conversant in distributed systems architecture limits enterprise migration velocity.
- Data sovereignty mandates:Germany, France, and India are imposing residency requirements that fragment cloud deployment architectures and inflate compliance costs.
- Legacy integration friction:Decades of COBOL and mainframe-bound data structures in insurance and government sectors resist API-based modernization.
Strategic Opportunities
- Edge computing data infrastructure:Latency-sensitive applications in autonomous vehicles and industrial automation require localized database nodes outside centralized cloud regions.
- Healthcare interoperability mandates:HIPAA and FDA 21 CFR Part 11 compliance frameworks are creating specialized demand for immutable audit trails and encryption-at-rest.
- Vector database architectures:Retrieval-augmented generation pipelines for large language models are converging with traditional transactional stores.
Industry Challenges
- Multi-cloud skill fragmentation:Database engineering teams must maintain operational proficiency across AWS Aurora, Azure Cosmos DB, and Google Cloud Spanner simultaneously.
- ISO/IEC 27001 certification timelines:Security certification cycles spanning 12-18 months delay vendor eligibility for regulated procurement pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Database Software Market |
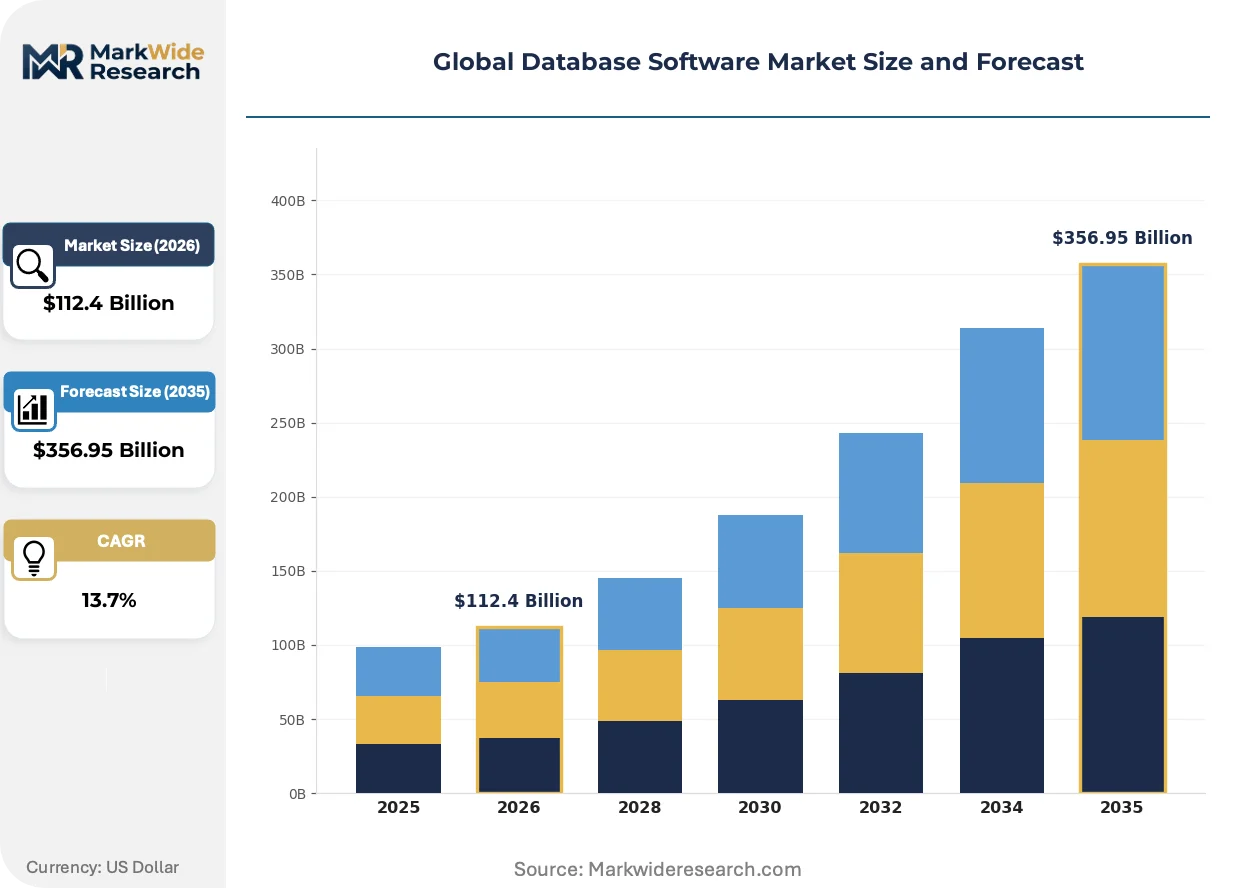
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $356.95 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Relational Database, NoSQL Database, NewSQL Database, In-Memory Database Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed Service End User: IT & Telecommunication, BFSI, Retail, Healthcare Functionality: Data Management, Analytics, Data Integration, Data Security |
| Companies Covered | Oracle Corporation, Microsoft Corporation, IBM Corporation, Amazon Web Services, Google LLC, Snowflake Inc., MongoDB, Inc., Databricks, Inc., SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Database Software Market Emerging Trajectories
Serverless database provisioning is compressing the traditional boundary between infrastructure and application layers. This architectural shift enables consumption-aligned pricing while demanding new operational disciplines from platform teams.
Vector search extensions to PostgreSQL and dedicated vector databases like Pinecone and Weaviate are fragmenting the analytics layer. AI application developers are adopting these stores for semantic retrieval at scale. The structural consequence is a bifurcation between transactional systems of record and embedding-powered inference caches.
GDPR and the EU AI Act are mandating explainability infrastructure at the data layer. Database vendors must now embed lineage tracking, automated tagging, and policy enforcement engines. Healthcare and financial services deployments in Germany and France are prioritizing vendors with native compliance tooling over performance-optimized alternatives.
Consumption-based pricing is displacing capacity planning in enterprise procurement. Database buyers are shifting from three-year reserved instances to on-demand autoscaling commitments. This pattern is most visible among SaaS providers in the United States, where workload volatility makes traditional provisioning economically untenable.
Global Database Software Market Segmentation
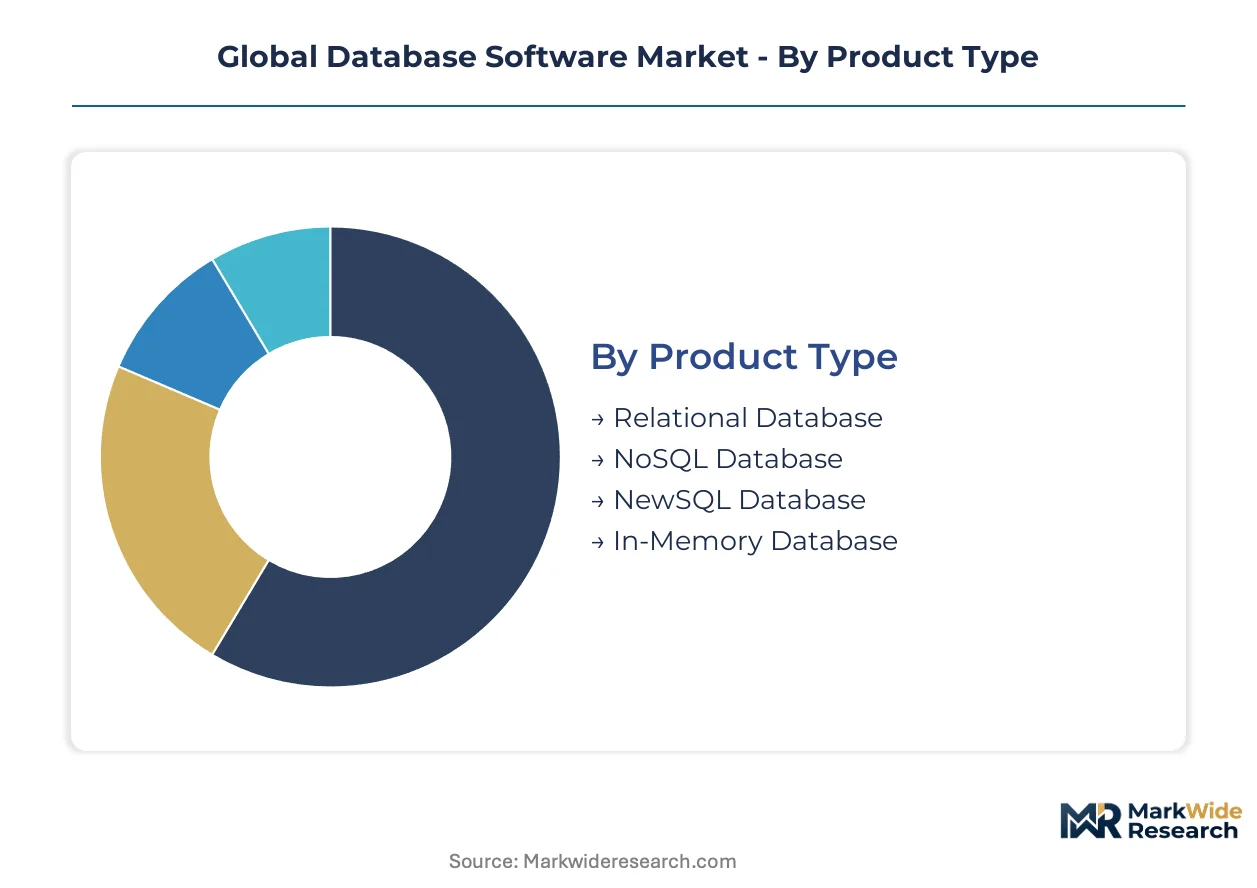
Database software segmentation reveals how margin pools migrate across architectural paradigms and delivery models. Vendors capture premium pricing where compliance complexity intersects with mission-critical workloads.
Product Type:
Relational engines still command the largest revenue share, though margin compression intensifies as cloud-native alternatives erode pricing power.
- Relational Database:ACID-compliant engines built on SQL standards dominate transactional systems of record in financial services and government. Oracle and SQL Server estates in US and UK banking sectors sustain renewal revenue despite cloud displacement pressure.
- NoSQL Database:Document, key-value, and wide-column stores handle unstructured data pipelines with BASE consistency models. IoT sensor networks in German manufacturing and real-time analytics in Indian e-commerce drive MongoDB and Cassandra deployments.
- NewSQL Database:Distributed SQL architectures combine horizontal scalability with transactional guarantees.
- In-Memory Database:DRAM-resident engines accelerate latency-sensitive applications.
The dominant share belongs to Relational Database, while NoSQL Database is closing the gap fastest.
Deployment Model:
Cloud consumption pricing is fragmenting traditional license revenue pools and reshaping procurement patterns across enterprise segments.
- Cloud-Based:Hyperscaler-managed services with autoscaling and consumption billing. SaaS providers in the United States favor AWS Aurora and Azure Cosmos DB for variable workload economics.
- Managed Service:Third-party operational outsourcing of database administration and infrastructure. GDPR and EU AI Act compliance requirements in France and Germany accelerate procurement of sovereign-managed PostgreSQL and MySQL.
- On-Premise:Self-hosted infrastructure with perpetual or subscription licensing.
- Hybrid:Split architectures spanning private data centers and public cloud regions.
Cloud-Based deployments hold the revenue lead, with Managed Service climbing most steeply.
End User:
Regulatory intensity varies sharply across verticals, with healthcare and financial services commanding premium pricing for audit and encryption capabilities.
- BFSI:Banking, insurance, and capital markets require sub-millisecond latency for trading systems and immutable audit trails for regulatory reporting. HIPAA and FDA 21 CFR Part 11 adjacent requirements in US health insurance drive specialized procurement.
- Healthcare:Electronic health records, clinical trial data management, and medical device telemetry demand encryption-at-rest and cross-border residency controls. German university hospitals and French public health systems prioritize EU AI Act-compliant lineage tracking.
- IT & Telecommunication:Network function virtualization and subscriber data management.
- Retail:Real-time inventory and personalization engines.
BFSI maintains the largest installed base, though Healthcare is expanding most quickly.
Functionality:
Security and analytics modules capture disproportionate margin as breach liability and AI pipeline complexity escalate.
- Data Security:Encryption, access control, masking, and threat detection layered across storage and transit. ISO/IEC 27001 certification requirements in European and North American procurement disqualify uncertified vendors from regulated contracts.
- Analytics:Query optimization, columnar storage, and vector search extensions for business intelligence and machine learning. Retrieval-augmented generation pipelines in US technology firms drive PostgreSQL vector extensions and dedicated stores like Pinecone.
- Data Management:Storage, retrieval, and lifecycle governance.
- Data Integration:ETL, streaming ingestion, and cross-system synchronization.
Data Security commands premium pricing, while Analytics is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers cluster in jurisdictions with stringent data residency frameworks and hyperscaler infrastructure density. Financial institutions and healthcare providers drive procurement in markets with enforceable algorithmic accountability standards.
United States
Hyperscaler headquarters in Seattle and San Francisco anchor cloud-native database adoption among SaaS providers. HIPAA and FDA 21 CFR Part 11 shape healthcare procurement requirements for immutable audit trails. New York financial services firms accelerate displacement of on-premise estates to managed services.
Germany
Automotive and industrial machinery sectors generate demand for edge-computing data nodes in latency-sensitive applications. The EU AI Act and GDPR impose algorithmic transparency mandates that vendors must embed at infrastructure level. Bavarian university hospitals prioritize sovereign-managed PostgreSQL with native compliance tooling.
United Kingdom
BFSI cloud migration accelerates displacement of legacy SQL Server estates in London and Edinburgh banking corridors. Financial Conduct Authority guidelines intersect with GDPR residency requirements. Manchester and Birmingham technology clusters drive managed service procurement for variable workload economics.
India
E-commerce and logistics platforms in Bangalore and Hyderabad drive NoSQL adoption for real-time analytics pipelines. RBI data localization directives and impending digital personal data protection frameworks reshape deployment architectures. Mumbai financial institutions balance cloud migration against sovereign cloud mandates.
France
Public health systems and pharmaceutical research institutions in Paris and Lyon demand EU AI Act-compliant lineage tracking. ANSM and CNIL enforcement actions elevate native compliance tooling above performance-optimized alternatives. Toulouse aerospace clusters require specialized encryption-at-rest for defense-adjacent workloads.
Global Database Software Market Vendor Landscape
Player mix skews toward hyperscale cloud providers with embedded database services and independent specialists in document-oriented or analytical architectures. Consolidation pressure intensifies as consumption pricing fragments traditional perpetual-license revenue pools. Strategic archetypes include legacy stack incumbents with renewal-dependent models, cloud-native challengers with developer-led adoption cycles, and vertical specialists in compliance-intensive segments. Dominant competitive moves encompass strategic partnerships with systems integrators and portfolio diversification into vector search and AI pipeline infrastructure.
Within the legacy incumbent tier, Oracle Corporation and IBM Corporation exemplify embedded-position vendors sustaining renewal revenue through decades of enterprise stack penetration. Among cloud-native challengers, MongoDB, Inc. occupies a position representing document-oriented specialists that anchor developer-led procurement decisions. Snowflake Inc. sits within the analytical workload archetype, exemplifying consumption-priced alternatives eroding traditional data warehouse margins.
| Leading Market Players |
|---|
| Oracle Corporation |
| Microsoft Corporation |
| IBM Corporation |
| Amazon Web Services |
| Google LLC |
| Snowflake Inc. |
| MongoDB, Inc. |
| Databricks, Inc. |
| SAP SE |
| Others |
Supply Flow & Price Mechanics
Ninety-day certification cycles for ISO/IEC 27001 compliance compress vendor eligibility windows and amplify pricing power for pre-certified incumbents in regulated procurement pipelines. Cloud consumption models fragment traditional perpetual-license revenue pools while hyperscaler bundling reshapes how database infrastructure is sourced and priced.
Pricing Analysis
Consumption-based contracts indexed to monthly active workload volumes dominate enterprise procurement, displacing three-year reserved instance commitments. Price differentiation hinges on compliance certification tier and geographic data residency requirements, with EU AI Act-aligned deployments commanding substantial premiums over standard cloud tiers. Pricing pressure intensifies in the relational database segment as managed open-source alternatives erode proprietary vendor margins. SaaS providers exhibit highest price sensitivity due to workload volatility, while BFSI institutions prioritize audit capabilities over cost optimization.
Supply Chain Analysis
Just-in-time provisioning preferences dominate cloud-native deployments, though sovereign cloud mandates in Germany, France, and India force strategic stockpiling of compliance-certified infrastructure capacity. Supply concentration centers on the United States for hyperscaler headquarters and managed service innovation, Germany for automotive edge-computing nodes, and India for NoSQL engineering talent pipelines. Raw material dependencies include specialized semiconductor fabrication for in-memory engines, rare earth elements for data center hardware, and cryptographic module supply chains. Single-source vulnerability concentrates in hyperscaler-controlled API ecosystems. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Database incumbents face substitution pressure from vector-native architectures and retrieval-augmented generation pipelines that bypass traditional transactional stores. Defense requires repositioning core infrastructure as lineage-enabled compliance platforms rather than commodity storage layers.
For Market Incumbents: Compound embedded positions in legacy enterprise stacks by embedding EU AI Act-compliant lineage tracking and automated policy enforcement engines directly at the infrastructure level. Prioritize ISO/IEC 27001 certification maintenance to sustain procurement eligibility in European and North American regulated verticals. Counter open-source displacement by integrating vector search extensions into core relational engines.
For New Entrants and Emerging Players: Sovereign-managed PostgreSQL gaps in German and French public health systems represent immediate white-space opportunities where incumbent hyperscalers under-serve compliance complexity. Target healthcare interoperability mandates requiring immutable audit trails and encryption-at-rest as the most penetrable application layer. Pursue channel partnerships with regional systems integrators possessing existing procurement relationships in Bavarian university hospitals and Paris pharmaceutical research clusters.
For Investors and Strategic Acquirers: Carve-out targets emerge from legacy enterprise software parents seeking to divest non-core database assets amid cloud transition pressures. Long-term viability favors specialists with native compliance tooling over performance-optimized alternatives as regulatory intensity escalates. Monitor EU AI Act enforcement actions by ANSM and CNIL as inflection indicators for vendor consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding vector search into PostgreSQL captures RAG pipeline demand from US technology firms. |
| Strategic Partnership | Systems integrator alliances accelerate sovereign cloud procurement in German automotive clusters. |
| Acquisition of Specialist Firm | Time-series database targets address IoT sensor network requirements in Indian logistics platforms. |
| Geographic Expansion | Mumbai and Hyderabad edge nodes satisfy RBI data localization directives for financial workloads. |
| Product Launch | Serverless provisioning aligns with SaaS provider demand for consumption-aligned pricing in US markets. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners across BFSI, healthcare, and SaaS verticals. Secondary validation drew from SEC filings, hyperscaler capex disclosures, App Annie enterprise software adoption data, and EU regulatory guidance documents. Bottom-up segment sizing triangulated against top-down market envelope estimates derived from vendor revenue disclosures and cloud infrastructure spending patterns.
Across the analysis window, forecasts modeled deployment model transitions, vertical regulatory intensity gradients, and geographic adoption pattern divergence. Segmentation dimensions included architectural paradigm, consumption pricing tier, compliance certification status, and workload type. CAGRs were derived from slope-intercept modeling of historical vendor growth rates adjusted for cloud displacement elasticity. Industry-specific inputs incorporated DBA talent pipeline constraints and sovereign cloud mandate implementation timelines.
Underlying assumptions cover sustained cloud migration velocity in US and UK BFSI sectors, with deviation risk concentrated in data sovereignty enforcement intensity and skilled administrator scarcity. Revision becomes warranted when EU AI Act audit requirement granularity crosses implementation thresholds that fundamentally alter infrastructure procurement criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Technical Illustration Software Market
Software & Services
Global Retail Sourcing and Procurement Software Market
Software & Services
Global Diagram Software Market
Software & Services
Data Visualization Software Market
Software & Services
Configure Price and Quote (CPQ) Market
Software & Services
Canada HR Payroll Software Market
Software & Services
Hypervisor Market
Software & Services
United Arab Emirates (UAE) Cloud Accounting Software Market
Software & Services
Lending Software Market
Software & Services
Automotive Design Software Market
Software & Services
Global Cloud Testing Market
Software & Services
Casino Management Systems Market
Software & Services
Talent Management Software Market
Software & Services
Landscaping Engineering Software Market
Software & Services
G Suite Technology Services Market
Software & Services
Global Data Recovery Software Market