
 Global Aluminum Cladding Panels Market | 2026-2036
Global Aluminum Cladding Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aluminum Cladding Panels Market Intelligence
Heightened fire safety standards for building envelopes, such as those updated in the United Kingdom and Australia following high-profile incidents, is repositioning the cost-of-entry calculus for panel manufacturers. Arconic Corporation leverages its extensive R&D in fire-retardant (FR) core technologies to meet these stringent codes. Schweiter Technologies AG, through its 3A Composites division, specializes in high-performance composite panels for large-scale architectural projects. Mulk Holdings International competes on manufacturing scale and a broad product portfolio.
Aluminum cladding panels are multi-layered architectural materials consisting of two aluminum sheets bonded to a core material. These panels provide a lightweight, durable, and weather-resistant exterior finish for building facades, often featuring a Polyvinylidene Fluoride (PVDF) coating for color retention and UV resistance. Composite aluminum panels continue to dominate due to their balance of cost and performance, while solid aluminum panels are specified for premium projects requiring maximum fire resistance. Application in commercial complexes and high-rise building facades constitutes the largest share of consumption.
Compliance with fire performance standards, including Europe’s EN 13501-1, the ASTM E84 test in the United States, and China's GB 8624, is mandatory for market access. Regulations like the EU's REACH also govern the chemical composition of panel cores and coatings, restricting hazardous substances. Navigating this complex web of regional fire codes and material sustainability rules remains the central strategic challenge for manufacturers and architectural firms.
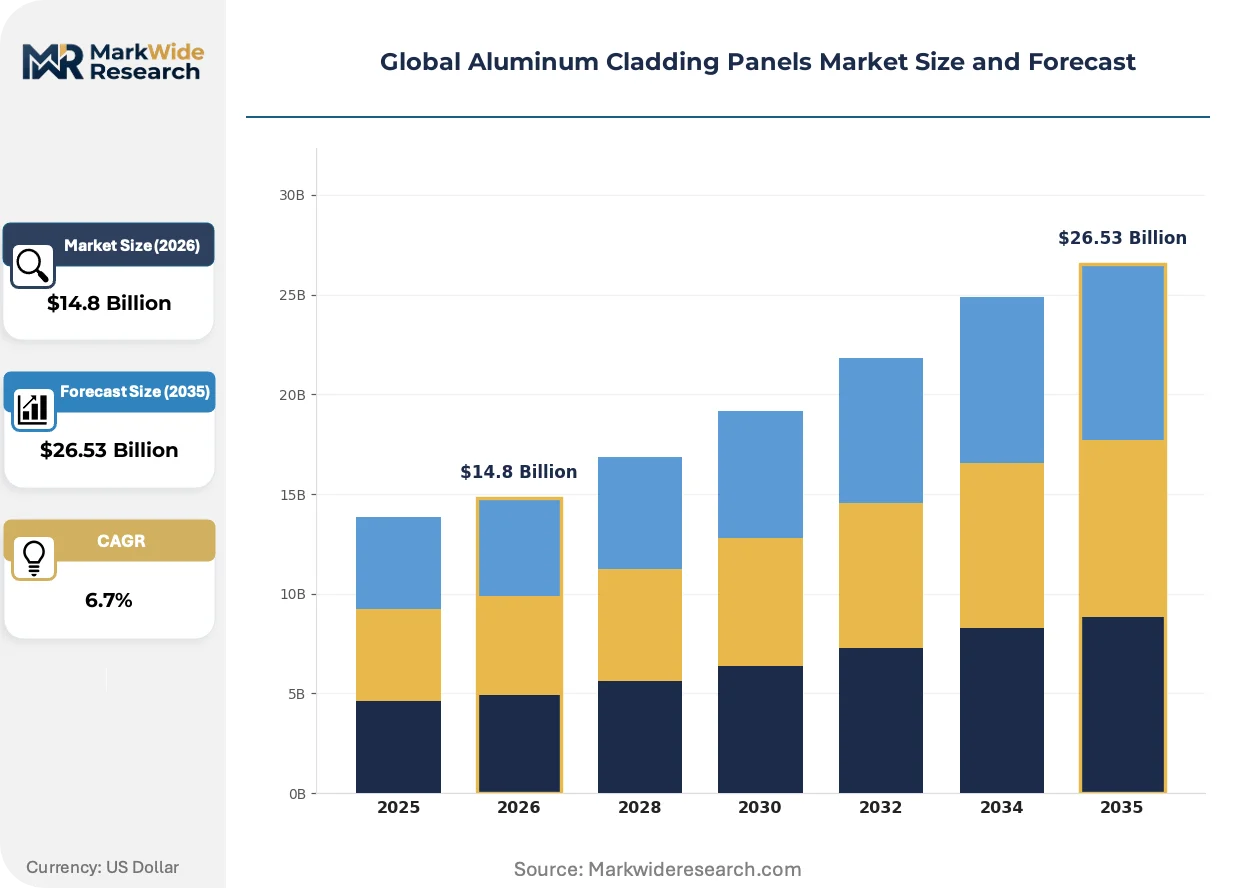
Market Dynamics
The market's central dynamic is the mandatory pivot toward non-combustible materials, driven by post-incident regulatory reforms in multiple countries. This shift elevates the importance of material science in core composition, directly influencing manufacturing costs and competitive positioning.
Growth Catalysts
- Urbanization and Construction:Continued urbanization, particularly in China and India, fuels demand for cladding in new commercial complexes and high-rise residential towers, which represent a major consumption segment.
- Advanced Core Materials:The development of fire-retardant (FR) mineral wool and non-combustible core technologies provides a direct solution to heightened fire safety standards, enabling market access.
- Architectural Versatility:Aluminum panels offer a lightweight, durable, and aesthetically flexible facade solution, meeting architectural demand for modern building envelopes with superior weather resistance and color retention.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of raw materials, especially primary aluminum and the resins used in PVDF coatings, can compress manufacturer margins and create price instability for end-users.
- Substitution from Alternatives:In certain low-rise and mid-rise applications, aluminum panels face competition from materials like high-pressure laminates (HPL), fiber cement, and brick veneers that offer different cost-performance profiles.
- Fragmented Regulatory Landscape:Navigating disparate regional fire safety codes, such as Europe’s EN 13501-1 and the ASTM E84 test in the United States, adds significant compliance costs and complexity.
Strategic Opportunities
- Building Retrofit Programs:Government-backed initiatives in Europe focused on energy efficiency and fire safety upgrades for existing building stock create a substantial market for recladding projects.
- Smart and Sustainable Panels:Integrating functionalities like photovoltaic cells for energy generation or photocatalytic coatings for self-cleaning properties opens new premium product categories for green buildings.
- Emerging Market Penetration:Expanding sales and distribution networks into high-growth construction markets in Southeast Asia and Latin America offers a path to capture new project volume.
Industry Challenges
- Certification and Compliance Burden:The time and expense required to test and certify products against a growing web of fire performance and chemical regulations, including the EU's REACH, is a major operational hurdle.
- Skilled Labor Shortage:A deficit of properly trained installers capable of executing complex facade system installations correctly is a key bottleneck that can impact project timelines and final build quality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aluminum Cladding Panels Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Aluminum Panels, Composite Aluminum Panels, Perforated Aluminum Panels, Aluminum Foam Panels Application: High-Rise Building Facades, Commercial Complexes, Institutional Buildings, Sports Arenas, Cultural Centers End User: Construction Contractors, Architectural Firms, Infrastructure Developers, Real Estate Management, Property Maintenance Installation Type: Ventilated Facade Systems, Rainscreen Cladding, Stick System, Unitized System, Mechanically Fastened Systems |
| Companies Covered | Arconic Corporation, Schweiter Technologies AG (3A Composites), Mulk Holdings International (Alubond U.S.A.), Mitsubishi Chemical Holdings Corporation, Jyi Shyang Industrial Co., Ltd. (Alucomat), Alucoil, CSP Architectural, Aluminium Specialties Group Pty Ltd., Alcoa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aluminum Cladding Panels Market Strategic Shifts & Innovations
Product development is increasingly centered on enhancing fire resistance and environmental performance. This focus responds directly to stricter building codes and a demand-side shift where lifecycle value and safety certification are prioritized over initial acquisition cost.
Advanced core materials utilizing mineral wool and proprietary fire-retardant formulations provide superior non-combustibility. Architects and developers are specifying these materials for high-rise facades and public infrastructure projects at an accelerated rate. This technology is overtaking traditional polyethylene (PE) core panels, which are now restricted or banned for many applications in regulated markets like the UK and Australia.
Europe’s EN 13501-1 standard, with its rigorous "reaction to fire" classifications, is a primary regulatory driver. The standard effectively mandates the use of A2 or B-rated panels for high-risk buildings, impacting material selection profoundly. Panel manufacturers targeting the EU market must reformulate their products or exit specific building segments, particularly those involving high-rise residential and commercial structures.
Architectural specification criteria are evolving from a cost-centric model to one based on verified system performance and material transparency. This change disrupts procurement channels that previously favored the lowest-cost panel, forcing suppliers to provide extensive documentation on fire testing and chemical composition. The shift is most visible in markets like Australia and the United Kingdom, where liability for non-compliant building materials has increased significantly.
Global Aluminum Cladding Panels Market Segmentation
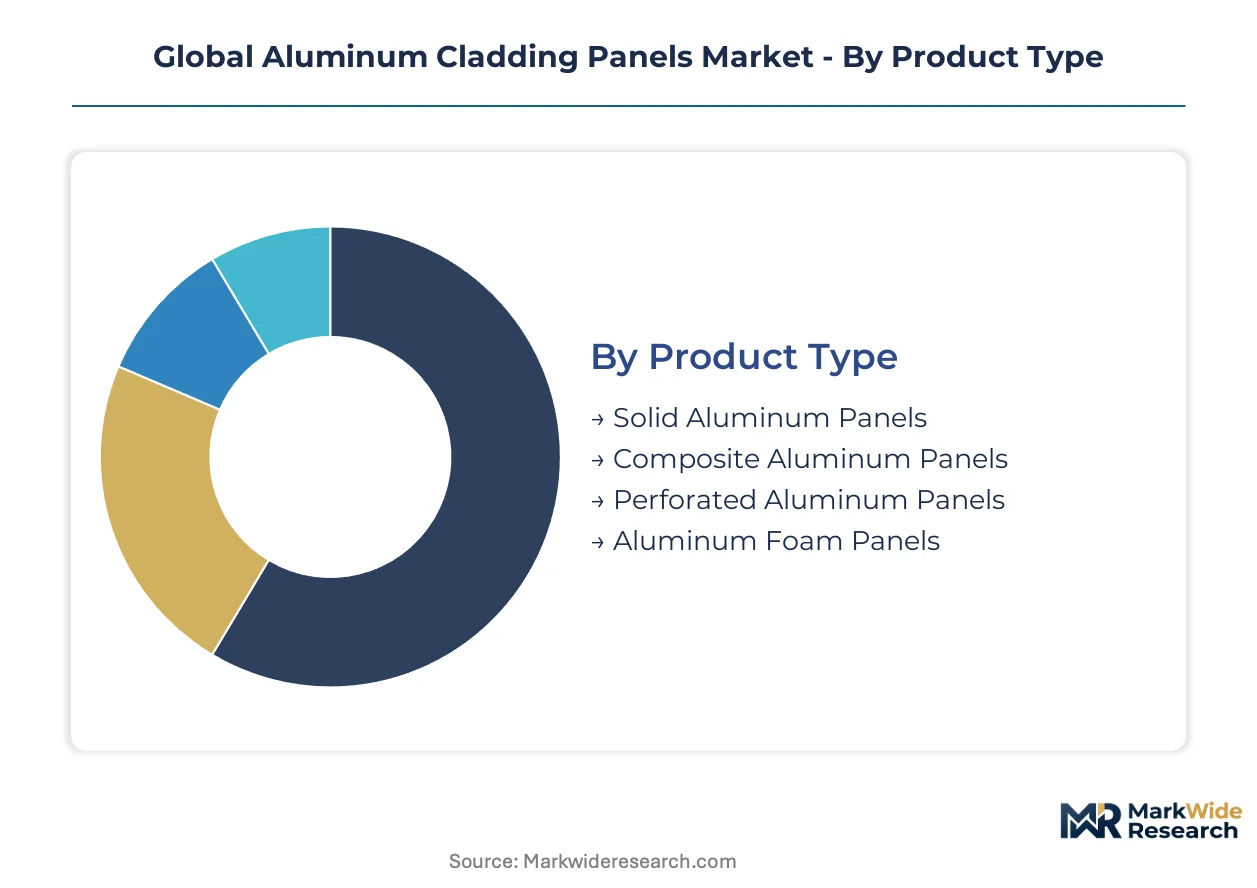
Understanding the distinct segments within the global aluminum cladding panels market is crucial for identifying specific demand drivers and regulatory compliance challenges. Each segment reflects unique material requirements, application environments, and end-user preferences. This detailed breakdown illuminates strategic opportunities for manufacturers and architectural specifiers.
Product Type:
Buyers in this category differentiate based on the core material composition and desired performance characteristics of the panels.
- Composite Aluminum Panels:These panels feature two aluminum sheets bonded to a non-aluminum core, balancing cost-effectiveness with performance. Demand concentrates in commercial complexes and mid-rise buildings, driven by their versatility and aesthetic flexibility.
- Solid Aluminum Panels:Composed entirely of aluminum, these panels offer maximum fire resistance and structural integrity for premium projects. Specification for high-risk building envelopes and luxury architectural designs is increasing due to stringent fire safety codes.
- Perforated Aluminum Panels:These panels incorporate patterns of holes, primarily for aesthetic design, light diffusion, or acoustic management in specific architectural applications.
- Aluminum Foam Panels:Lightweight and offering enhanced sound and thermal insulation, these advanced panels target niche applications requiring specific acoustic or energy performance.
Volume sits with Composite Aluminum Panels; growth tilts toward Solid Aluminum Panels.
Application:
The application segment illustrates where aluminum cladding panels are physically integrated into building structures, reflecting varying performance needs and design priorities.
- High-Rise Building Facades:These applications demand panels with superior fire resistance, durability, and weather protection due to extreme environmental exposure and safety regulations. Demand for these panels is expanding across major urban centers like London and Shanghai, driven by continuous urbanization.
- Commercial Complexes:This segment represents a significant consumption share, utilizing panels for aesthetic appeal, energy efficiency, and branding across retail, office, and mixed-use developments. Construction activity in China and other Asian markets heavily influences demand in this area.
- Institutional Buildings:Panels for schools, hospitals, and government facilities prioritize durability, low maintenance, and compliance with public safety standards.
- Sports Arenas:These large-scale projects use panels for their aesthetic impact, weather resistance, and ability to accommodate complex architectural forms.
- Cultural Centers:Panels contribute to unique architectural expressions and environmental control for museums, theaters, and performance venues.
High-Rise Building Facades exhibit the steepest expansion trajectory, while Commercial Complexes maintain the largest overall consumption volume.
End User:
This segmentation highlights the primary stakeholders responsible for specifying, purchasing, and installing aluminum cladding panels across various construction projects.
- Construction Contractors:These entities directly procure and install cladding panels, focusing on cost-effectiveness, material availability, and ease of installation to meet project timelines. Their purchasing decisions are often influenced by the project's overall budget and regulatory compliance requirements in markets like Germany.
- Architectural Firms:Architects specify cladding panel types based on design aesthetics, performance criteria, and compliance with building codes such as Europe’s EN 13501-1. Their influence shapes material selection for premium and complex projects globally.
- Infrastructure Developers:These developers utilize panels for large-scale public works and transportation hubs, prioritizing durability and long-term structural integrity.
- Real Estate Management:Property managers select panels for renovation and maintenance, considering lifecycle costs, aesthetic upkeep, and energy performance.
- Property Maintenance:This segment focuses on repair and replacement of existing cladding, often requiring panels that match previous installations or meet new safety standards.
Architectural Firms drive specification trends, while Construction Contractors account for the majority of direct procurement.
Installation Type:
The method of panel attachment to a building's structure dictates specific performance characteristics, including thermal efficiency, water management, and aesthetic finish.
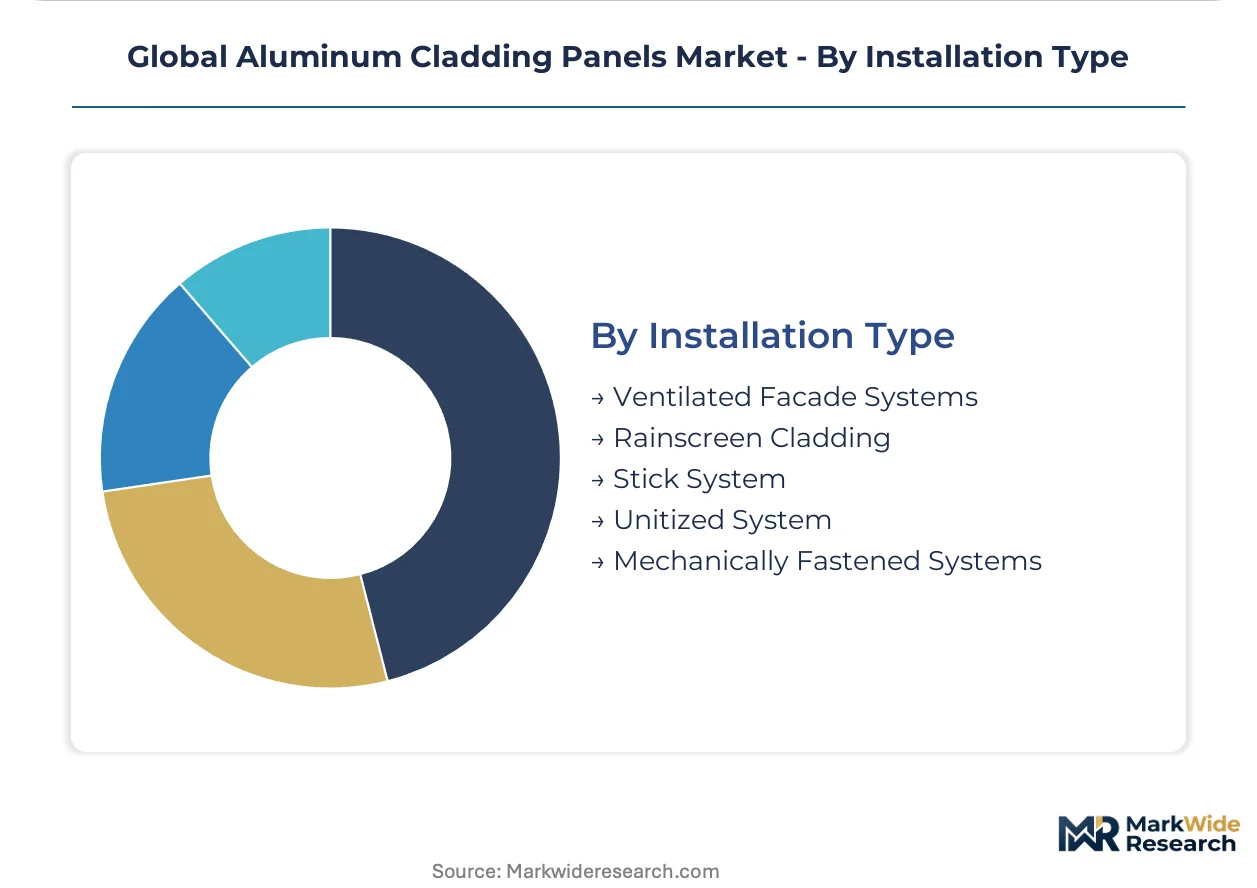
- Ventilated Facade Systems:These systems incorporate an air gap behind the cladding, improving thermal performance and moisture management for energy-efficient buildings. European Green Deal initiatives are accelerating their adoption for new construction and retrofit projects.
- Rainscreen Cladding:Designed to protect the building structure from weather, this system manages water drainage and air circulation effectively. It is a common choice for commercial and residential buildings seeking durable exterior protection in regions with high rainfall.
- Stick System:This traditional method involves assembling the facade on-site, piece by piece, offering flexibility for complex designs.
- Unitized System:Factory-assembled units are delivered to the site for quicker installation, suitable for large-scale, repetitive facade designs.
- Mechanically Fastened Systems:Panels are directly attached to the substrate using visible or concealed fasteners, offering a straightforward installation approach.
Ventilated Facade Systems demonstrate the most rapid expansion due to sustainability mandates, while Mechanically Fastened Systems remain widely used for their installation simplicity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta Economic Zone in China drives significant demand for aluminum cladding panels, concentrating manufacturing and high-rise construction activity. This region, alongside other global urban centers, exemplifies the market's reliance on specific development hubs for project volume and material innovation.
China
Continued urbanization fuels substantial demand for cladding in new commercial complexes and high-rise residential towers. China's GB 8624 standard mandates stringent fire performance for these facade materials. Construction activity in major cities like Shanghai and Shenzhen utilizes advanced panel systems for large-scale developments.
United Kingdom
Post-incident regulatory reforms, such as the Building Safety Act, elevate fire safety standards for building envelopes. The UK government mandates stricter material compliance for high-rise structures. London's extensive urban development projects require A2 or B-rated panels, influencing procurement decisions.
United States
Urbanization drives demand for cladding in new commercial and high-rise residential projects across major metropolitan areas. The ASTM E84 test is a critical standard for panel market access and material specification. Major construction hubs like New York City and Chicago consistently specify durable facade solutions for their skylines.
Germany
Government-backed initiatives focusing on energy efficiency and fire safety upgrades for existing building stock create a substantial recladding market. Europe’s EN 13501-1 standard profoundly influences material selection for new builds and retrofits. Commercial and institutional projects in Berlin and Munich prioritize compliant, high-performance panels.
Australia
Heightened fire safety standards for building envelopes, following high-profile incidents, significantly impact material choices. The National Construction Code sets stringent requirements for facade materials, particularly for multi-story buildings. Melbourne and Sydney's high-rise developments now mandate non-combustible cladding, shifting market demand.
Global Aluminum Cladding Panels Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a tiered market structure. Large material science companies often leverage extensive research and development capabilities to meet evolving standards. Competitive moves center on portfolio diversification and strategic partnerships to address complex regulatory demands.
On the premium-tier vector, Arconic Corporation exemplifies advanced fire-retardant core technologies, positioning itself for high-specification projects. Schweiter Technologies AG, through its 3A Composites division, anchors the market for high-performance composite panels, particularly for large-scale architectural endeavors. Mulk Holdings International sits within the scale-driven end, offering a broad product portfolio for various construction needs globally.
| Leading Market Players |
|---|
| Arconic Corporation |
| Schweiter Technologies AG (3A Composites) |
| Mulk Holdings International (Alubond U.S.A.) |
| Mitsubishi Chemical Holdings Corporation |
| Jyi Shyang Industrial Co., Ltd. (Alucomat) |
| Alucoil |
| CSP Architectural |
| Aluminium Specialties Group Pty Ltd. |
| Alcoa Corporation |
| Others |
Cost & Logistics Intelligence
Vertical integration into aluminum smelting anchors manufacturer supply positions, allowing greater control over primary aluminum input costs and influencing final panel pricing power. This strategic depth provides a buffer against raw material volatility for key market players.
Pricing Analysis
Premium pricing for short lead times reflects the high demand for compliant, fire-rated panels in urgent retrofit projects. Project-based pricing models dominate the market, with significant differentiation based on certification level, such as A2 or B-rated panels, and geographic delivery costs for specialized systems. Cost compression in standard composite panels stems from raw material volatility, particularly primary aluminum and PVDF resins. Construction contractors exhibit high price sensitivity for commodity-grade panels, while architectural firms prioritize verified performance and safety compliance for premium designs.
Supply Chain Analysis
Direct-to-project distribution channels handle large-scale facade system procurement for high-rise developments and commercial complexes. Geographic supply concentration centers in China, Germany, and the United States, reflecting major manufacturing hubs. The industry relies heavily on primary aluminum, PVDF resins, and specialized core materials like mineral wool. Commodity price volatility for aluminum represents a structural supply chain risk. Specialized distributors and direct manufacturer sales teams form the dominant downstream distribution model for complex facade systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market for aluminum cladding panels is a supply-constrained story, with specialized fire-retardant core material production capacity limiting immediate output and propping pricing for compliant products.
For Market Incumbents: Deploy advanced R&D in non-combustible core materials to counter the threat of alternative facade systems and maintain market leadership. Invest in expanding certified manufacturing capacity for A2-rated panels, particularly in high-demand urban centers like London and Shanghai. Acquire smaller specialist firms with proprietary fire-retardant technologies to deepen material science expertise and secure intellectual property against emerging competitors.
For New Entrants and Emerging Players: Capture market share by focusing on modular, unitized panel systems for mid-rise commercial projects in Southeast Asia, leveraging streamlined installation and cost-effectiveness. Target applications requiring specific acoustic or thermal insulation properties, such as Aluminum Foam Panels, offering a differentiated value proposition. Develop robust certification pathways for local building codes to ensure market access and build trust with regional construction contractors.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized material science firms developing proprietary non-combustible core technologies, offering long-term value appreciation over a five-to-ten-year horizon. Acquire companies with strong intellectual property in mineral wool or advanced FR formulations to capitalize on the mandatory pivot towards safer building materials. The signal to watch is an increase in regulatory enforcement actions against non-compliant materials, driving demand for certified solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for A2-Rated Panels | Addresses growing demand for fire-compliant panels in major urban centers like London and Shanghai. |
| Backward Integration into Core Material Production | Secures consistent supply of specialized fire-retardant materials, stabilizing input costs. |
| Investment in Digital Design and Fabrication | Enhances architectural versatility and reduces lead times for complex facade projects. |
| Strategic Partnerships with Installation Firms | Mitigates the skilled labor shortage bottleneck, improving project timelines and quality. |
| Green Manufacturing Transition and Product Development | Aligns with EU Green Deal initiatives, appealing to architects specifying sustainable building envelopes. |
Research Approach
Independent corroboration across architectural specifications, construction contractor procurement records, and material science journals underwrites the qualitative findings. This approach combines primary interviews with architectural firms, construction contractors, material scientists, and regulatory compliance officers. Secondary validation draws from building codes like EN 13501-1, ASTM E84, and China's GB 8624, alongside government construction reports and corporate financial statements, ensuring bottom-up and top-down triangulation.
Rate-of-change decomposition across product types, application segments, and regional construction activity forms the quantitative framework for this analysis. The study models segmentation dimensions including composite versus solid panels, high-rise versus commercial applications, and ventilated versus mechanically fastened installation types, factoring in regional regulatory stringency. Compound annual growth rates are derived from historical trends, projected urbanization rates, and anticipated regulatory impacts. Urbanization rates in China and fire safety regulation updates in the United Kingdom serve as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to shifts in global commodity prices and evolving fire safety legislation. The projections reflect underlying assumptions regarding construction activity and material science advancements. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Advanced Building Materials Market
Building & Construction Materials
Global Fire-Rated Medium Density Fiberboard Market
Building & Construction Materials
I-Joist Market
Building & Construction Materials
Mexican Insulated Panels Market
Building & Construction Materials
Spray Foam Insulation Market
Building & Construction Materials
Decorative Tiles Market
Building & Construction Materials
Bollard Market
Building & Construction Materials
Acoustical Ceiling Market
Building & Construction Materials
Lightweight Composite External Access Panels and Doors Market
Building & Construction Materials
Asia-Pacific Gypsum Board Market
Building & Construction Materials
Fire Rated Glass Market
Building & Construction Materials
Construction Sealants Market
Building & Construction Materials
Insulating Glass Window Market
Building & Construction Materials
Europe Building Materials Market
Building & Construction Materials
Insulated Concrete Form (ICF) Market
Building & Construction Materials
Fiber Cement Rainscreen Panels Market